
 South Africa Data Center Storage Market | 2026-2036
South Africa Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Data Center Storage Market Insights
Data center engineering talent scarcity is redrawing competitive dynamics across South Africa. Dell Technologies leverages its direct sales force and local service infrastructure to sustain enterprise relationships. Huawei Technologies competes aggressively on price-performance metrics for flash storage arrays. Teraco anchors the colocation layer, controlling access to carrier-neutral interconnection in Johannesburg and Cape Town.
South Africa data center storage encompasses solid-state, magnetic, and tape-based media systems engineered for enterprise-grade durability, with flash arrays typically rated for millions of write cycles and HDDs optimized for sequential throughput in petabyte-scale deployments. The primary purpose is to ensure data persistence, availability, and recoverability for mission-critical workloads across cloud and on-premises environments. Flash storage leads product type revenue due to performance requirements in financial trading and telecommunications, while software defined storage is displacing traditional SAN architectures among large enterprises seeking programmatic control. Hybrid cloud deployment captures growing interest as organizations balance latency-sensitive local processing with elastic cloud burst capacity.
POPIA compliance obligations enforced by South Africa's Information Regulator mandate encryption, access logging, and geographic data residency, directly shaping procurement specifications and vendor qualification criteria. BIS standards for electrical safety and electromagnetic compatibility govern equipment importation and installation certification. ICASA regulations on cross-border data flows intersect with storage architecture decisions for multinational operators. Stakeholders must weigh the trade-off between capex-heavy on-premises expansion and opex-based colocation contracts as power reliability and renewable energy commitments reshape total cost of ownership calculations.
Market Dynamics
POPIA-mandated encryption and geographic data residency requirements are forcing storage architecture redesigns across South African enterprises, compressing procurement cycles and elevating compliance to a primary vendor selection criterion ahead of raw performance metrics.
Growth Catalysts
- Financial services transaction volume:Real-time payment platforms and digital banking expansion in Johannesburg and Cape Town are driving petabyte-scale storage deployments with sub-millisecond latency requirements.
- POPIA enforcement:South Africa's Information Regulator audits are compelling organizations to replace legacy unencrypted systems with compliant infrastructure, creating replacement demand across healthcare and government sectors.
- Teraco interconnection density:Carrier-neutral facility expansion in Isando and Bredell is attracting hyperscale cloud providers, generating colocated storage demand from multinational enterprises seeking local presence.
Market Restraints
- Import tariff structure:BIS electrical safety certification delays and customs processing for flash storage components extend equipment lead times by eight to twelve weeks, constraining rapid deployment.
- Eskom grid instability:Chronic load-shedding forces storage operators to oversize UPS and generator capacity, adding capex overhead that disadvantages smaller domestic providers against global vendors with integrated power resilience portfolios.
- Technical skill scarcity:Certified storage architects and data protection specialists concentrate in Gauteng, limiting enterprise-grade deployment velocity in KwaZulu-Natal and Western Cape secondary markets.
Strategic Opportunities
- Western Cape renewable energy corridor:Cape Town's municipal power reliability and green energy commitments are attracting carbon-conscious multinational headquarters, creating demand for sustainable storage infrastructure with documented renewable sourcing.
- Software-defined storage convergence:Programmable storage fabrics combining NVMe-over-Fabrics with container orchestration are opening mid-market penetration paths for vendors previously excluded by traditional SAN cost barriers.
- Cross-border African data hub positioning:South Africa's submarine cable landing density positions Johannesburg as a regional aggregation point for Angolan, Namibian, and Mozambican enterprise data requiring POPIA-equivalent protection standards.
Industry Challenges
- Legacy SAN integration complexity:Financial institutions with fifteen-plus years of Fibre Channel investment face forklift-upgrade resistance when migrating to software-defined architectures, prolonging sales cycles and requiring extensive professional services bundling.
- Certification timeline compression:BIS electromagnetic compatibility testing queue lengths and ICASA equipment type approval backlogs delay product launches, forcing vendors to pre-position inventory ahead of confirmed demand.
- Specialized engineering attrition:Storage-specific technical talent migrates to cloud architecture roles or emigrates to European markets, forcing vendors to absorb training costs and accept longer deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Data Center Storage Market |
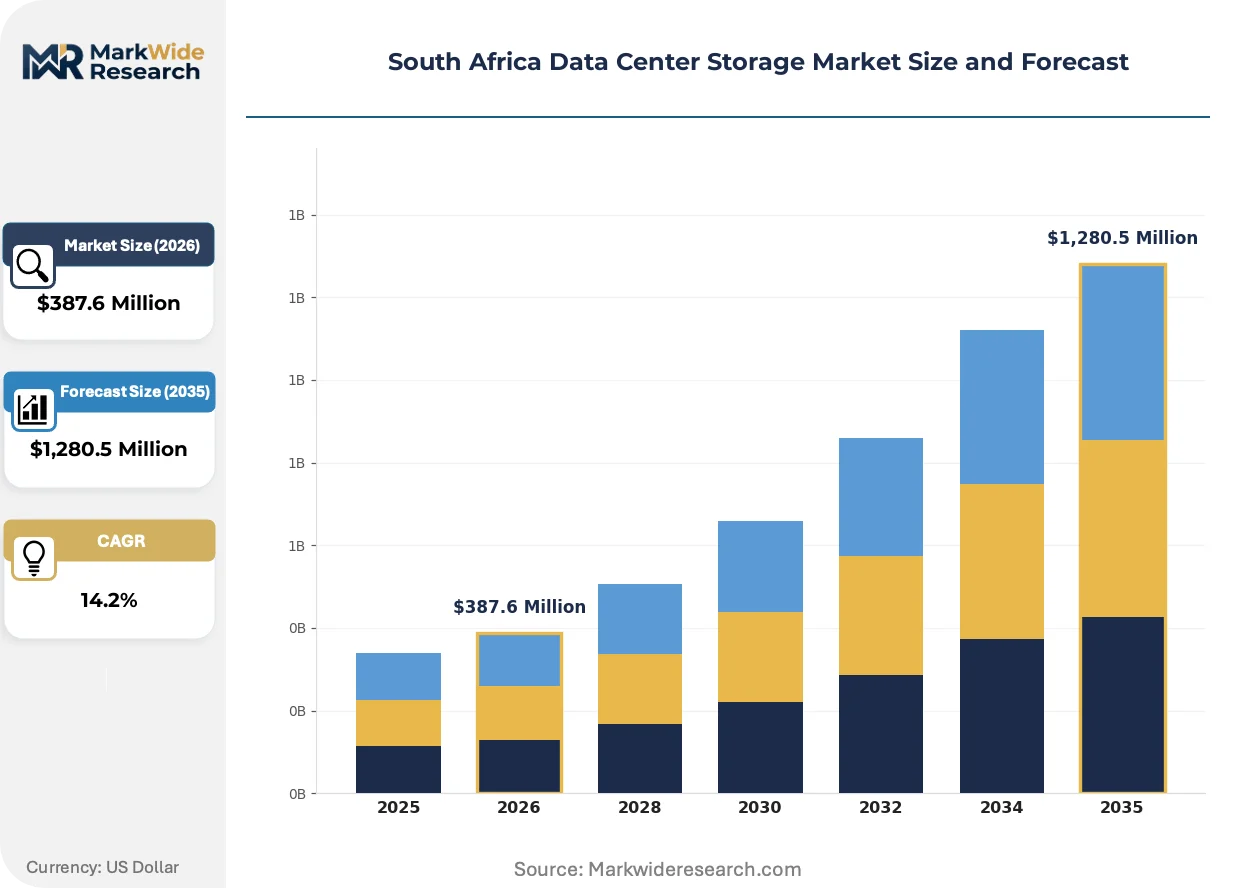
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flash Storage, Hard Disk Drives, Hybrid Storage, Tape Storage Technology: Software Defined Storage, Cloud Storage, Edge Computing, Object Storage End User: Telecommunications, Financial Services, Government, Healthcare Deployment: On-Premises, Colocation, Hybrid Cloud, Public Cloud |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise, NetApp, Pure Storage, IBM, Hitachi Vantara, Huawei Technologies, Teraco, Africa Data Centres, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Data Center Storage Market Trends and Innovations
Storage architecture decisions in South Africa are converging around three vectors: media technology transition, regulatory compliance automation, and procurement model restructuring. Each trend carries distinct implications for vendor positioning and customer retention.
NVMe-based all-flash arrays are supplanting hybrid SSD-HDD configurations in Johannesburg financial trading floors and telecommunications switching centers. Tier-one banks and mobile network operators are completing this transition within eighteen-month refresh windows. The shift is compressing acceptable latency thresholds from milliseconds to microseconds, disqualifying vendors without end-to-end NVMe fabric expertise.
South Africa's Information Regulator is escalating POPIA enforcement through sector-specific audit programs targeting healthcare and insurance. Organizations must now demonstrate encryption-at-rest, access logging, and geographic data residency in procurement documentation. Enterprise buyers are responding by mandating vendor-provided compliance attestation as a contractual precondition, elevating legal and audit functions in technology selection.
Consumption-based capacity contracts are displacing traditional capital-acquisition models among mid-market enterprises in Pretoria and Durban. Managed service providers and colocation operators are capturing storage demand through opex-aligned offerings that bundle hardware, maintenance, and compliance management. This pattern is most visible in healthcare and professional services verticals where IT capital budgets face sustained pressure.
South Africa Data Center Storage Market Segmentation
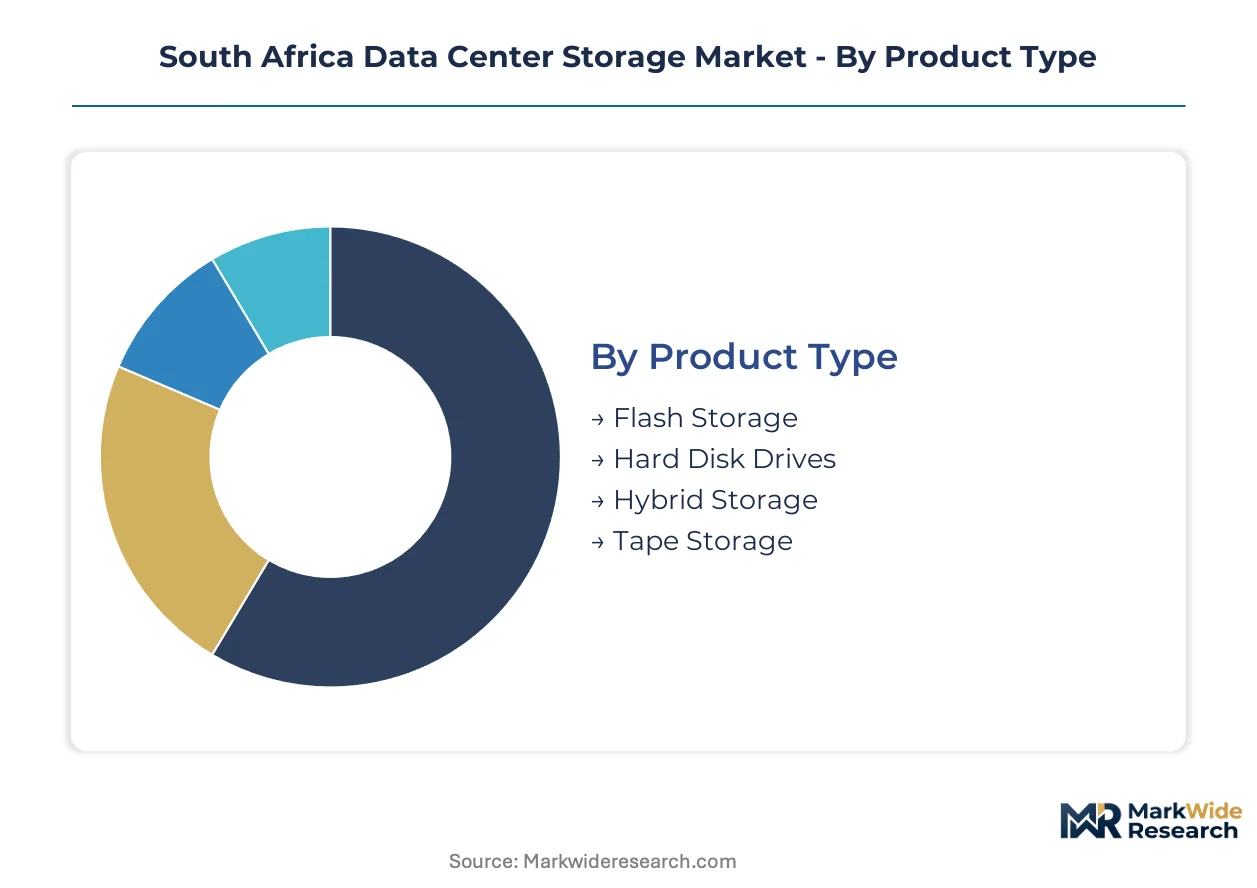
Storage procurement in South Africa splits across four dimensions that reshape vendor access and margin capture. Product type determines hardware refresh cycles, while deployment model governs whether Dell or Teraco captures the customer relationship.
Product Type:
Channel mix varies sharply by media technology, with direct sales forces dominating high-performance flash while distribution partners handle tape and legacy HDD volumes.
- Flash Storage:NVMe-based solid-state arrays deliver sub-millisecond latency for real-time transaction processing. Johannesburg financial trading floors and mobile network switching centers concentrate demand as POPIA-compliant encryption requirements accelerate replacement of unencrypted legacy systems.
- Hard Disk Drives:Sealed magnetic media optimized for sequential throughput in petabyte-scale archival deployments. Cape Town municipal data centers and KwaZulu-Natal logistics operators favor HDD economics for video surveillance and document retention where access frequency remains low.
- Hybrid Storage:Tiered SSD-HDD configurations balancing cost and performance for mid-market enterprises.
- Tape Storage:Linear magnetic media for air-gapped backup and long-term compliance archiving in government and healthcare sectors.
HDD dominates installed base across provincial government facilities. Flash storage is where expansion concentrates as banks compress refresh windows.
Technology:
Cost tier stratification separates programmable software-defined fabrics from capital-intensive hardware-centric alternatives.
- Software Defined Storage:Decoupled control planes enabling programmatic capacity orchestration via APIs. Large Pretoria-based mining houses and professional services firms displace traditional SAN architectures to gain container-native provisioning and automated tiering.
- Cloud Storage:Elastic capacity provisioned via hyperscale provider APIs with opex-based metering. Durban healthcare networks and Cape Town fintech startups leverage cloud burst capacity for unpredictable analytics workloads without local generator oversizing.
- Edge Computing:Distributed processing nodes with co-located persistence for latency-sensitive industrial IoT.
- Object Storage:Flat namespace architectures for unstructured data lakes and media archives.
Cloud storage dominates new contract value in services verticals. Software-defined storage is climbing the fastest among enterprises with internal platform engineering teams.
End User:
Application-criticality determines whether procurement centers on performance specifications or compliance attestation.
- Financial Services:Tier-one banks and insurance groups in Johannesburg and Cape Town mandate microsecond latency for algorithmic trading and real-time fraud detection. POPIA audit exposure compels encryption-at-rest and geographic residency guarantees in every RFP.
- Telecommunications:Mobile network operators and fixed-line carriers operating national switching infrastructure. Vodacom and MTN data centers in Gauteng drive all-flash demand for subscriber databases and billing systems with five-nines availability requirements.
- Government:National and provincial departments subject to State Information Technology Agency procurement frameworks.
- Healthcare:Hospital groups and medical insurers managing patient records under Information Regulator enforcement.
Telecommunications holds the largest committed capacity under long-term refresh cycles. Financial services is gaining share fastest as digital banking platforms scale transaction volumes.
Deployment:
Customer type separates capital-budget enterprises from opex-preferring organizations with constrained IT headcount.
- On-Premises:Dedicated facilities with captive power, cooling, and physical security operated by the owning organization. South African Reserve Bank and major retail banks maintain on-premises primary storage to satisfy data sovereignty interpretations of POPIA geographic residency clauses.
- Colocation:Leased space in carrier-neutral facilities with shared power and interconnection infrastructure. Multinational enterprises establishing Johannesburg presence for Angolan and Mozambican operations favor Teraco's Isando and Bredell campuses for submarine cable access and cross-connect density.
- Hybrid Cloud:Workload-split architectures combining local performance tiers with elastic cloud burst capacity.
- Public Cloud:Fully outsourced infrastructure with no local hardware footprint.
On-premises retains dominance in regulated sectors with conservative risk committees. Colocation is expanding most quickly among enterprises exiting self-managed facilities due to Eskom reliability concerns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's Information Regulator anchors the southern African data protection framework through escalating POPIA enforcement, creating geographic data residency requirements that concentrate storage infrastructure investment in Gauteng and Western Cape provinces.
Gauteng Province
Johannesburg and Pretoria host the majority of carrier-neutral facilities including Teraco's Isando and Bredell campuses. Financial services institutions drive petabyte-scale flash storage deployments for real-time transaction processing with sub-millisecond latency requirements. The province faces acute engineering talent scarcity as certified storage architects concentrate in this economic hub.
Western Cape
Cape Town's municipal power reliability and renewable energy commitments attract carbon-conscious multinational headquarters seeking sustainable storage infrastructure. Cape Town data centers favor HDD economics for video surveillance and document retention workloads where access frequency remains low. The city's submarine cable landing density positions it as a secondary aggregation point for regional enterprise data.
KwaZulu-Natal
Durban healthcare networks and logistics operators represent emerging demand centers constrained by limited local engineering capacity. Provincial government facilities maintain significant HDD installed base for archival deployments. Certification timeline compression from BIS electromagnetic compatibility testing backlogs delays equipment deployment relative to Gauteng.
Eastern Cape
Port Elizabeth and surrounding industrial zones generate edge computing demand for latency-sensitive manufacturing IoT applications. Secondary market status limits enterprise-grade deployment velocity due to technical skill scarcity. Eastern Cape organizations increasingly leverage colocation in Gauteng facilities to bypass local infrastructure constraints.
South Africa Data Center Storage Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with global technology conglomerates competing against regional colocation operators and niche flash storage vendors. The market structure reflects dual procurement patterns: direct enterprise sales for high-performance workloads and channel-mediated distribution for mid-market archival deployments. Three archetypes dominate—integrated infrastructure providers, carrier-neutral facility operators, and software-defined storage specialists. Competitive moves center on compliance bundling and renewable energy certification rather than raw price competition.
Among integrated infrastructure providers, Dell Technologies and Hewlett Packard Enterprise occupy positions anchored by direct sales forces and local service infrastructure. Huawei Technologies exemplifies price-performance competition in flash storage arrays. Teraco represents the carrier-neutral facility archetype, controlling interconnection density in Johannesburg and Cape Town. NetApp and Pure Storage sit within the software-defined tier, targeting enterprises displacing traditional SAN architectures.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise |
| NetApp |
| Pure Storage |
| IBM |
| Hitachi Vantara |
| Huawei Technologies |
| Teraco |
| Africa Data Centres |
| Others |
Pricing and Supply Chain Analysis
BIS electrical safety certification gates both vendor qualification and price differentiation in South Africa's data center storage procurement, compressing margins for uncertified entrants while rewarding pre-approved suppliers with pricing power in POPIA-mandated replacement cycles.
Pricing Analysis
Long-term colocation contracts dominate enterprise procurement, with consumption-based capacity agreements displacing capital-acquisition models among mid-market buyers. Price differentiation rests on POPIA compliance bundling and local service infrastructure depth rather than raw hardware specifications. Pricing pressure stems from Huawei's aggressive price-performance positioning in flash arrays. Mid-market healthcare networks exhibit highest price sensitivity, while Johannesburg tier-one banks prioritize latency guarantees over cost.
Supply Chain Analysis
Inventory lead times stretch eight to twelve weeks due to BIS electromagnetic compatibility testing queues and customs processing for NVMe controller components. Supply concentrates in China, South Korea, and Taiwan for flash memory fabrication. Component dependencies include NAND wafers, enterprise SSD controllers, and specialized power supply units. Single-source vulnerability runs through Taiwan-based controller foundries. Distribution runs through Teraco's carrier-neutral facilities for multinational enterprises, with direct vendor relationships dominating financial services procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
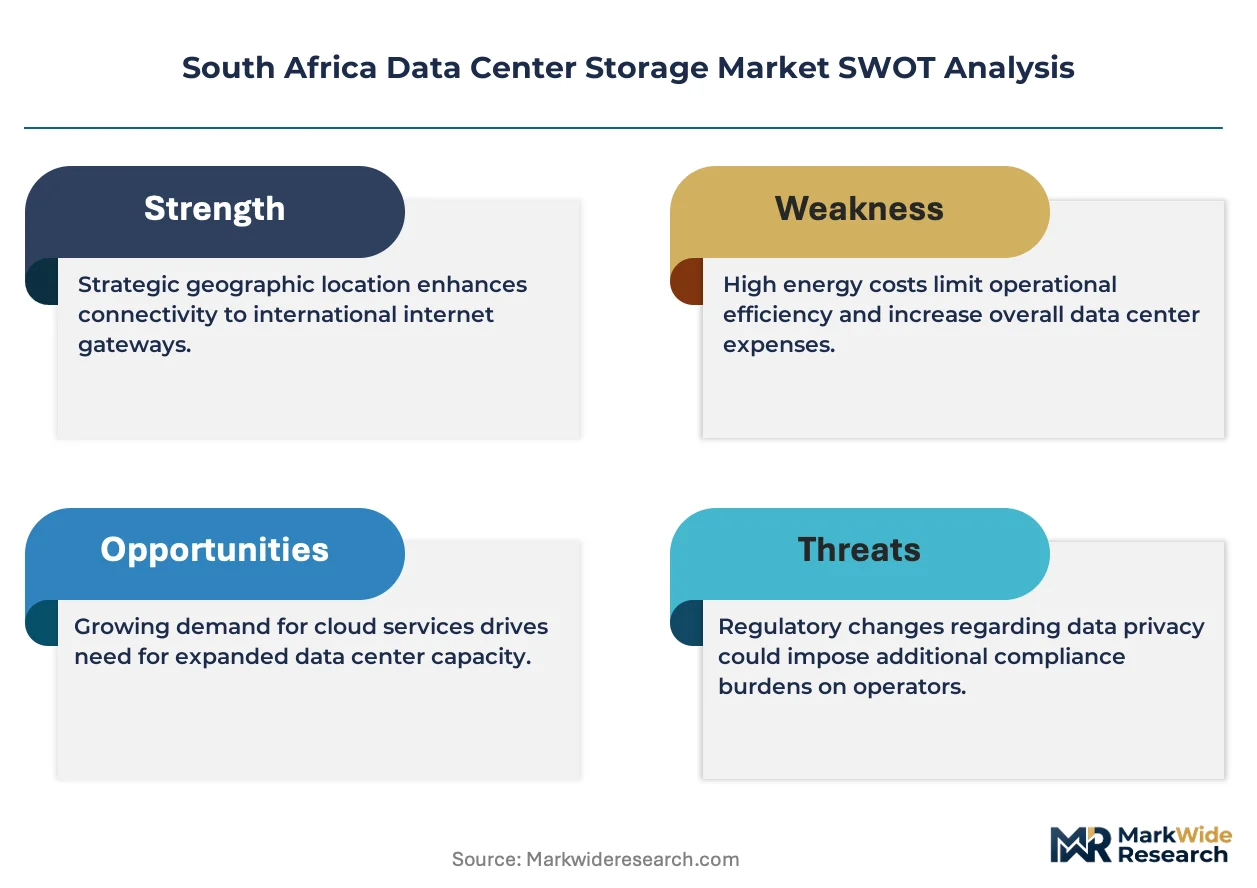
Managed compliance services represent the fastest-expanding recurring-revenue layer, outpacing hardware growth as POPIA audit enforcement compels outsourcing of encryption management and geographic residency verification.
For Market Incumbents: Shield enterprise relationships by embedding POPIA compliance attestation into standard maintenance contracts, neutralizing Huawei's price aggression through audit-risk mitigation. Deepen captive supply of certified power infrastructure to offset Eskom-driven generator oversizing costs. Control Teraco cross-connect density to constrain new entrant interconnection access. For New Entrants and Emerging Players: Anchor in Western Cape renewable energy corridor positioning, where carbon-conscious multinationals prioritize documented green sourcing over incumbent brand recognition. Target Durban healthcare networks constrained by Gauteng engineering talent scarcity. Lead with software-defined storage converged offerings that bypass traditional SAN professional services requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-defined storage sub-segments as programmable fabrics displace hardware-centric architectures. Five-to-ten year viability favors vendors with container-native orchestration capabilities and POPIA compliance automation. Monitor BIS certification timeline compression as inflection signal—backlog reduction would accelerate hardware refresh velocity and expand addressable market.| Strategic Initiative | Industry Significance |
|---|---|
| POPIA Compliance Automation Platform | Reduces audit preparation burden for Johannesburg financial institutions facing Information Regulator enforcement. |
| Renewable Energy Certification Program | Documents green power sourcing for Cape Town multinational headquarters with carbon disclosure requirements. |
| NVMe-over-Fabrics Integration | Enables microsecond latency for algorithmic trading floors compressing refresh windows below eighteen months. |
| Managed Colocation Service Expansion | Bundles generator-backed power resilience with encryption management for Eskom-affected enterprises. |
| Cross-Border African Data Hub Partnership | Leverages submarine cable density to capture Angolan and Mozambican enterprise data requiring POPIA-equivalent protection. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, incorporating data center engineering directors, storage procurement officers at tier-one banks, Teraco facility managers, and BIS certification specialists. Secondary validation drew from ICASA equipment type approval databases, Eskom grid reliability reports, Information Regulator audit disclosures, and hyperscaler capex filings. Bottom-up deployment tracking and top-down infrastructure investment analysis were triangulated to reconcile vendor shipment data with facility expansion announcements.
Across the projection horizon, the analytical framework modeled product type transitions, deployment model shifts, and end-user vertical concentration. Segmentation dimensions included media technology, control plane architecture, organizational scale, and provincial regulatory enforcement intensity. CAGRs were derived from fitted growth curves anchored to disclosed capacity expansions and replacement cycle compression observed in financial services. Forecast inputs incorporated POPIA audit schedule acceleration and renewable energy procurement commitments from multinational headquarters.
Decision-makers should treat outputs as directional under assumptions of sustained Eskom load-shedding and Information Regulator enforcement continuity; material deviation in grid stability or audit intensity would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Switzerland Data Center Storage Market
Storage Solutions
Poland Data Center Storage Market
Storage Solutions
Denmark Data Center Storage Market
Storage Solutions
Nigeria Data Center Storage Market
Storage Solutions
Cloud Storage Gateways Market
Storage Solutions
Spain Data Center Storage Market
Storage Solutions
Network File System Market
Storage Solutions
Netherlands Data Center Storage Market
Storage Solutions
Global Virtual Data Storage Market
Storage Solutions
Indonesia Data Center Storage Market
Storage Solutions
Storage Software Market
Storage Solutions
Cloud Object Storage Solutions Market
Storage Solutions
Copy Data Management Software Market
Storage Solutions
Public Cloud Storage Services Market
Storage Solutions
United Arab Emirates Data Center Storage Market
Storage Solutions
Vietnam Data Center Storage Market