
 Global Enterprise File Sharing and Synchronization (EFSS) Market | 2026-2036
Global Enterprise File Sharing and Synchronization (EFSS) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Enterprise File Sharing and Synchronization (EFSS) Market Foresight
ISO/IEC 27001 certification is collapsing the vendor landscape into a smaller set of qualified providers. Microsoft leverages its Azure stack to anchor hybrid deployment contracts across regulated industries. Dropbox specializes in user-centric design that sustains premium positioning among creative and professional services segments.
Enterprise File Sharing and Synchronization denotes a software infrastructure category enabling secure storage, distribution, and real-time consistency of digital assets across distributed endpoints, typically incorporating AES-256 encryption, granular access controls, and API-driven policy enforcement to support collaborative workflows. Cloud-based deployment leads volume adoption among mid-market buyers seeking operational flexibility, while hybrid configurations capture margin concentration from healthcare and government agencies navigating data sovereignty mandates. File Synchronization and Endpoint Security within the Solution Type dimension are outpacing legacy backup tools as organizations prioritize continuous data consistency over periodic recovery.
The EU GDPR, the U.S. SEC cybersecurity disclosure rules, and Japan's METI data governance guidelines collectively reshape product roadmaps toward jurisdictional data residency and audit-ready access logs. China's Personal Information Protection Law and GB/T 35273 standards further fragment architecture requirements for multinational deployments. Stakeholders must evaluate whether their infrastructure investments accommodate divergent national encryption and localization mandates before committing to single-region cloud strategies.
Market Dynamics
Data sovereignty mandates are fragmenting cloud-first architectures into hybrid and on-premises configurations across financial services and manufacturing verticals. ISO/IEC 27001 certification requirements are collapsing the qualified vendor pool while elevating procurement scrutiny on encryption standards and jurisdictional data residency controls.
Growth Catalysts
- EU AI Act Compliance:Article 50 transparency obligations and high-risk system classifications are forcing financial institutions to deploy sovereign EFSS infrastructure with immutable audit trails and EU-based data processing.
- Japan METI Guidelines:Cross-border data governance frameworks for industrial data are accelerating hybrid synchronization deployments among automotive and electronics manufacturers with multi-site R&D operations.
- AES-256 Encryption:End-to-end encryption at rest and in transit is becoming a non-negotiable procurement criterion for healthcare providers exchanging patient imaging and diagnostic records.
Market Restraints
- Compute Cost Volatility:GPU-intensive AI-powered content classification features are exposing buyers to unpredictable cloud consumption pricing, compressing margin visibility on multi-year enterprise contracts.
- Vendor Concentration Risk:ISO/IEC 27001 certification requirements have reduced the qualified provider pool to fewer than a dozen vendors capable of serving regulated industries, creating single-source dependency.
- Legacy Integration Friction:On-premises ERP and document management systems built on proprietary protocols require expensive middleware development for real-time bidirectional synchronization.
Strategic Opportunities
- India Manufacturing Corridors:PLI scheme beneficiaries in electronics and pharmaceuticals are establishing captive EFSS infrastructure for IP protection and supplier collaboration platforms.
- Zero Trust Architecture Convergence:Integration of continuous verification protocols with file synchronization endpoints is opening new contract value in defense and critical infrastructure sectors.
- API-First Distribution:Embedded finance and vertical SaaS platforms are white-labeling EFSS capabilities through OEM partnerships, bypassing traditional enterprise sales cycles.
Industry Challenges
- Cybersecurity Talent Scarcity:Shortages of cloud security architects with cross-border compliance expertise are extending implementation timelines for multinational hybrid deployments.
- Certification Timeline Compression:ISO/IEC 27001 and SOC 2 Type II audit cycles are stretching 12-18 months, delaying product launches in competitive procurement windows.
- Multi-Jurisdictional Encryption:Divergent national cryptographic standards between the US, EU, and China are forcing architectural complexity and redundant infrastructure investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Enterprise File Sharing and Synchronization (EFSS) Market |
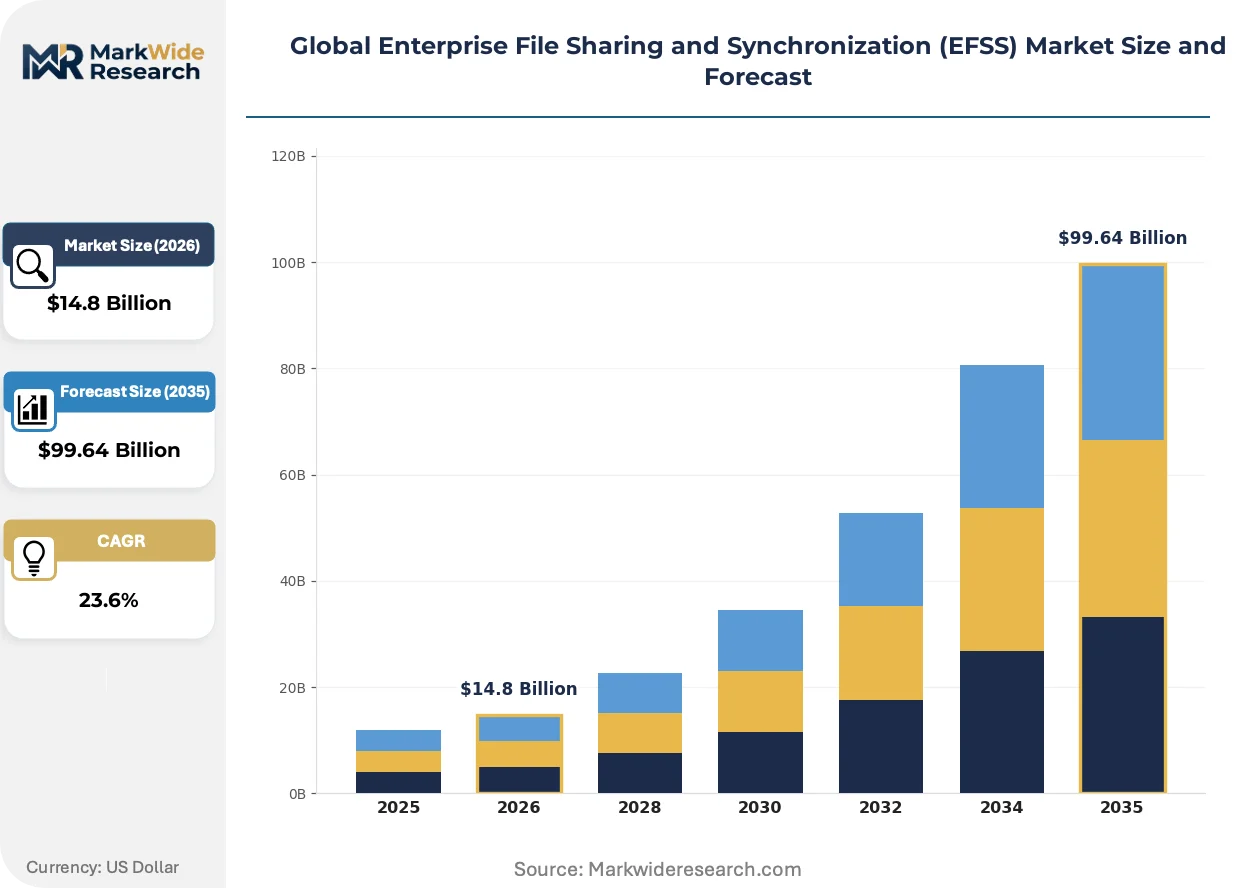
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $99.64 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Cloud-based, On-premises, Hybrid, Community Cloud Solution Type: File Sharing, File Synchronization, Backup & Recovery, Collaboration Tools, Endpoint Security Use Case: Remote Work Enablement, Compliance Management, Content Management, Workflow Automation, Data Archiving End User Industry: Information Technology, Telecommunications, Legal Services, Education, Government Agencies |
| Companies Covered | Microsoft, Google, Dropbox, Box, IBM, Citrix Systems, VMware, Egnyte, OpenText, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Enterprise File Sharing and Synchronization (EFSS) Market Shifts & Advancements
Edge-native synchronization protocols are displacing centralized cloud hubs as latency-sensitive workloads expand into manufacturing floors and clinical settings. Regulatory fragmentation is accelerating investment in jurisdictional data residency controls.
Confidential computing using hardware-based trusted execution environments is fragmenting the security architecture landscape for EFSS deployments. Healthcare systems managing genomic data and financial institutions processing algorithmic trading signals are adopting Intel SGX and AMD SEV-based enclaves for computation on encrypted data without decryption exposure. This technology is fragmenting vendor roadmaps between hardware-attested security models and traditional software-only encryption approaches.
The EU AI Act's high-risk system classification is forcing EFSS vendors to implement explainable access logging and automated decision documentation for AI-powered content classification features. Financial services firms deploying automated document routing must now maintain human-in-the-loop override capabilities and algorithmic impact assessments. German automotive manufacturers are extending these requirements into supplier qualification processes, creating a compliance cascade through tiered supply chains.
Consumption-based pricing models are displacing per-seat licensing in mid-market procurement. Channel partners and MSPs are bundling EFSS with adjacent security and collaboration tools into outcome-aligned service tiers, compressing direct vendor relationships. This shift is most visible in the US professional services sector, where accounting and legal firms are consolidating vendor relationships through platform-centric procurement strategies rather than point-solution acquisitions.
Global Enterprise File Sharing and Synchronization (EFSS) Market Segmentation
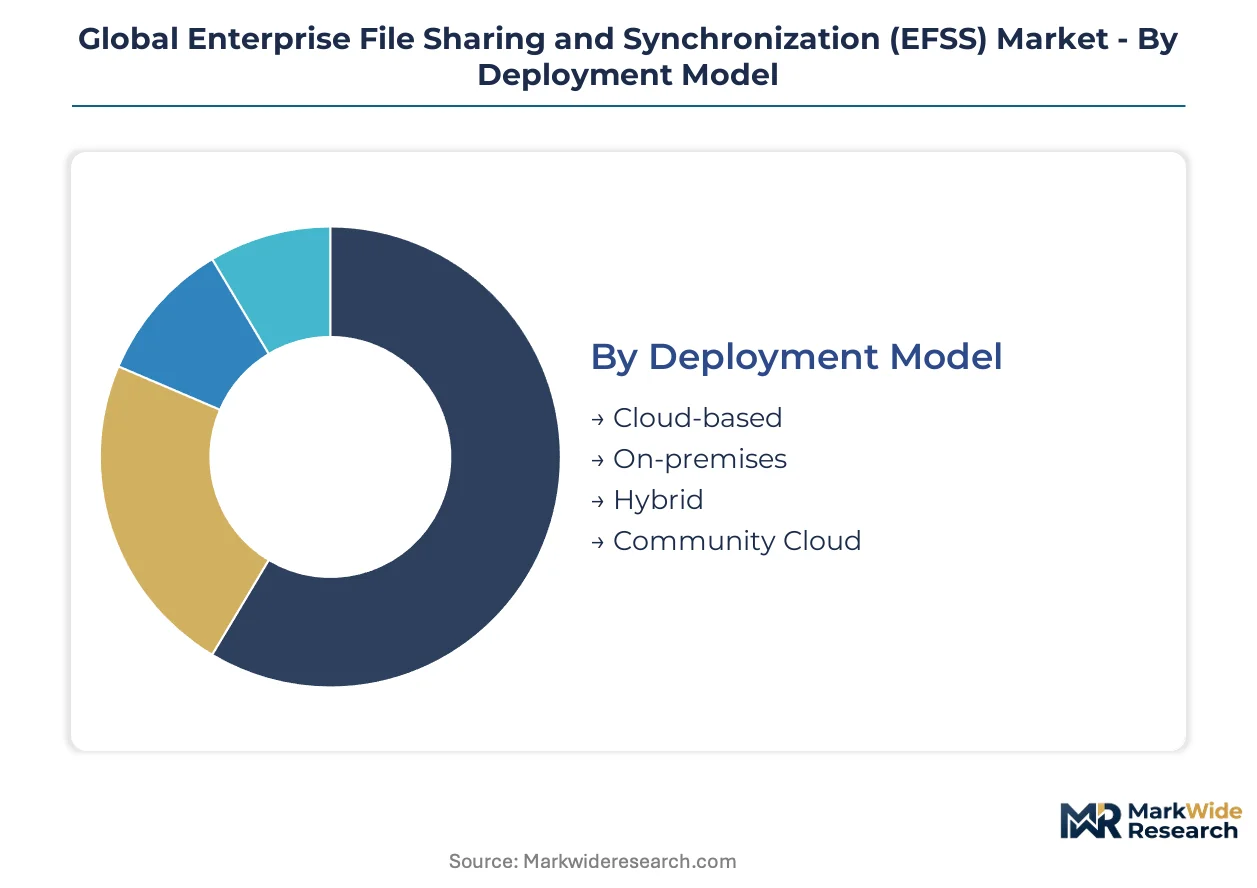
EFSS procurement patterns diverge sharply across deployment models and use cases, with regulated industries demanding sovereign infrastructure while creative sectors prioritize collaborative velocity. Channel economics favor hybrid configurations that bundle professional services margin with recurring software revenue.
Deployment Model:
Channel mix varies dramatically by deployment topology, with cloud-native solutions flowing through hyperscaler marketplaces and on-premises deployments requiring systems integrator intermediation.
- Cloud-based:Multi-tenant architectures with elastic compute provisioning dominate mid-market procurement through AWS Marketplace and Azure commercial channels. Financial services firms in Singapore and professional services clusters in London are consolidating vendor relationships through platform-centric procurement rather than point-solution acquisitions.
- Hybrid:Split-stack configurations with jurisdictional data residency controls capture premium pricing from German automotive manufacturers and Japanese electronics suppliers navigating cross-border R&D collaboration. METI guidelines and EU AI Act compliance requirements are accelerating these deployments.
- On-premises:Air-gapped infrastructure with hardware security modules serves defense contractors and critical infrastructure operators in the US and Israel.
- Community Cloud:Sector-specific instances shared among non-competing peers address cost pooling for US healthcare systems and Canadian provincial government agencies.
By volume, Cloud-based leads. By growth pace, Hybrid is climbing the fastest.
Solution Type:
Cost tier stratification separates commodity backup tools from high-margin endpoint security suites with confidential computing attestation.
- File Sharing:Browser-based distribution with granular access controls and watermarking capabilities anchors procurement in legal services and investment banking. New York and London law firms are mandating client-side encryption for matter-specific document exchange.
- File Synchronization:Continuous delta-sync protocols with conflict resolution algorithms command premium positioning among distributed engineering teams. German Mittelstand manufacturers require on-premises synchronization nodes for CAD file protection across supplier networks.
- Backup & Recovery:Immutable snapshot retention with ransomware-resistant air-gapping addresses healthcare and municipal government requirements in the US and Australia.
- Collaboration Tools:Real-time co-editing with version branching targets creative agencies and architectural practices in Copenhagen and Melbourne.
- Endpoint Security:Hardware-attested enclaves using Intel SGX and AMD SEV are fragmenting vendor roadmaps for genomic data and algorithmic trading workloads.
By margin concentration, Endpoint Security outperforms. By adoption velocity, File Synchronization is gaining share fastest.
Use Case:
Application maturity separates established content management deployments from emerging workflow automation integrations with vertical SaaS platforms.
- Remote Work Enablement:Zero-trust access with device posture verification became baseline infrastructure following distributed workforce normalization. Australian professional services firms and Dutch technology consultancies are consolidating endpoint security with file synchronization into unified procurement.
- Compliance Management:Immutable audit trails with automated retention policy enforcement address SEC cybersecurity disclosure rules and Japan's METI data governance frameworks. Swiss private banks and Singapore wealth managers are deploying sovereign EFSS infrastructure with EU-based data processing.
- Content Management:Metadata-driven classification with automated lifecycle policies serves media archives and pharmaceutical documentation in the US and Ireland.
- Workflow Automation:API-driven routing with human-in-the-loop override capabilities is expanding fastest among German automotive manufacturers extending EU AI Act requirements through tiered supply chains.
- Data Archiving:WORM-compliant cold storage with jurisdictional residency controls addresses long-term retention mandates for US federal agencies and French nuclear operators.
By installed base, Remote Work Enablement dominates. By expansion trajectory, Workflow Automation shows the steepest climb.
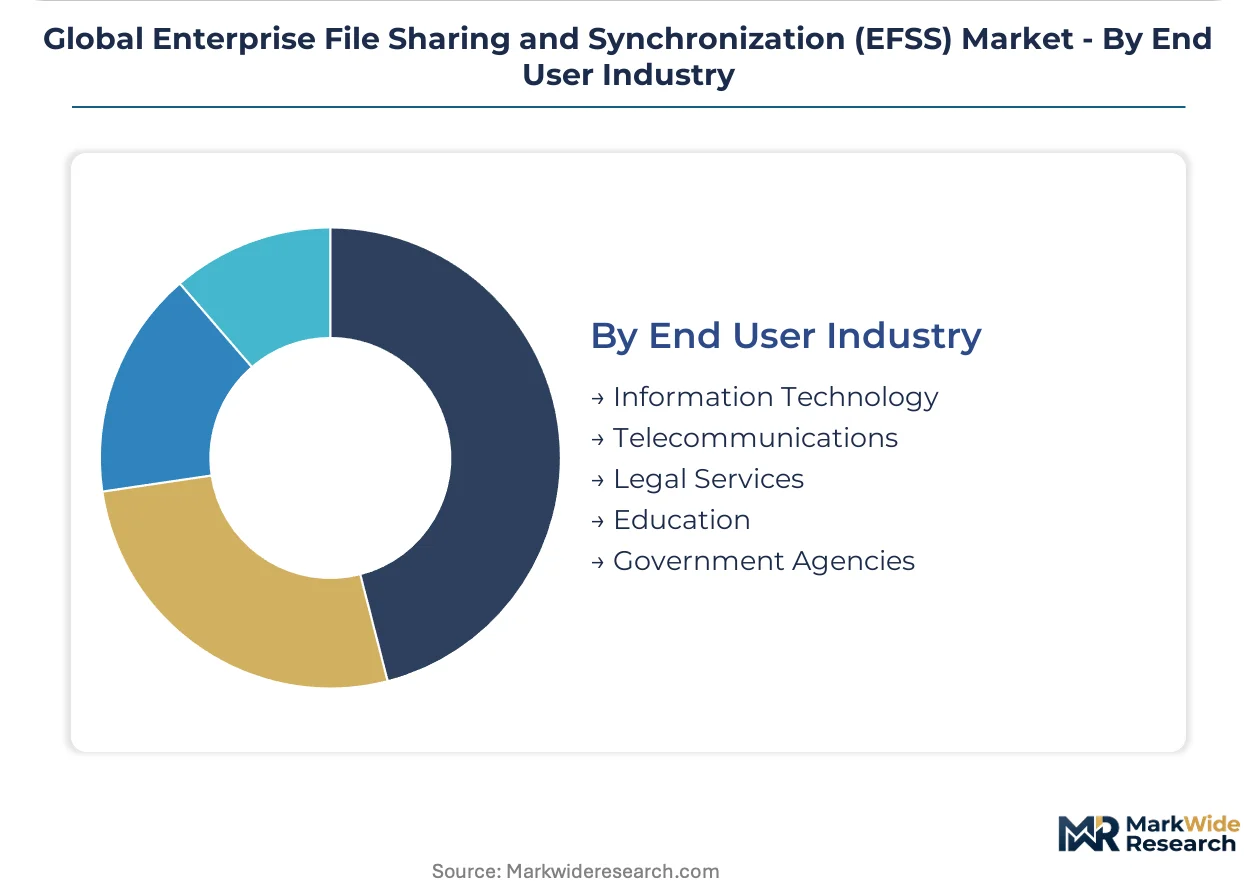
End User Industry:
Customer type determines pricing architecture, with government agencies demanding fixed-fee enterprise licenses and telecommunications carriers preferring consumption-based metering.
- Information Technology:DevOps-integrated pipelines with infrastructure-as-code deployment support software vendors and cloud service providers in Israel and Estonia. These buyers are white-labeling EFSS capabilities through OEM partnerships, bypassing traditional enterprise sales cycles.
- Telecommunications:Edge-native synchronization with 5G core integration addresses latency requirements for network function virtualization and subscriber data management. South Korean and Finnish carriers are deploying confidential computing for encrypted data processing without decryption exposure.
- Legal Services:Matter-centric isolation with ethical wall enforcement and client-specific encryption key escrow dominates UK and US law firm procurement.
- Education:Federated identity integration with learning management systems serves research universities in Canada and Australia managing multi-institutional collaboration.
- Government Agencies:FedRAMP and ISO/IEC 27001 certification requirements are collapsing the qualified vendor pool for US federal and German state-level deployments.
By contract value, Information Technology leads. By procurement momentum, Telecommunications is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GDPR enforcement and the EU AI Act are redirecting procurement toward sovereign data residency controls. Japanese METI guidelines and India's PLI scheme are accelerating parallel investments in hybrid synchronization infrastructure across manufacturing verticals.
United States
SEC cybersecurity disclosure rules and FedRAMP certification requirements are compressing the vendor pool for federal agencies. Healthcare systems in Boston and financial services clusters in New York are mandating AES-256 encryption with immutable audit trails for patient and client document exchange.
Germany
Mittelstand manufacturers require on-premises synchronization nodes for CAD file protection across supplier networks. The EU AI Act's high-risk system classification is forcing automotive OEMs in Bavaria and Baden-Württemberg to deploy explainable access logging through tiered supply chains.
Japan
METI cross-border data governance frameworks are accelerating hybrid deployments among automotive and electronics manufacturers. R&D operations in Nagoya and Osaka are establishing jurisdictional data residency controls for multi-site collaboration on proprietary designs.
India
PLI scheme beneficiaries in electronics and pharmaceuticals are establishing captive EFSS infrastructure for IP protection. Manufacturing corridors in Maharashtra and Karnataka are deploying supplier collaboration platforms with sovereign data processing capabilities.
Singapore
Wealth managers and private banks are consolidating vendor relationships through platform-centric procurement strategies. Financial services firms are deploying sovereign infrastructure with EU-based data processing to satisfy cross-border compliance requirements for high-net-worth client documentation.
Global Enterprise File Sharing and Synchronization (EFSS) Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and deployment flexibility. ISO/IEC 27001 requirements have collapsed the qualified vendor pool to fewer than a dozen providers capable of serving regulated industries. Three archetypes dominate: hyperscale cloud platforms with hybrid anchoring strategies, user-centric design specialists commanding premium positioning, and legacy enterprise software vendors pivoting toward API-first distribution. Competitive moves concentrate on strategic partnerships with systems integrators and portfolio diversification into confidential computing attestation.
Within the hyperscale tier, Microsoft leverages its Azure stack to anchor hybrid deployment contracts across regulated industries. Dropbox occupies a position exemplifying user-centric design that sustains premium positioning among creative and professional services segments. Box represents the specialist archetype focused on enterprise-grade compliance and granular access controls for legal and financial services verticals.
| Leading Market Players |
|---|
| Microsoft |
| Dropbox |
| Box |
| IBM |
| Citrix Systems |
| VMware |
| Egnyte |
| OpenText |
| Others |
Supply & Pricing Matrix
ISO/IEC 27001 certification gates both vendor qualification and price tiering simultaneously, compressing the qualified supplier pool to under a dozen providers while stratifying contract values across FedRAMP, GDPR, and SOC 2 Type II compliance tiers. German automotive OEMs and US healthcare systems pay premiums for sovereign data residency controls, while mid-market buyers face compressed margins as consumption-based pricing displaces per-seat licensing.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ISO/IEC 27001 and FedRAMP-attested solutions commanding three-to-five-fold premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects deployment complexity, with hybrid configurations capturing highest margins from regulated verticals. Cost compression in cloud-native tiers intensifies as hyperscaler marketplaces commoditize base storage and sync functionality. Healthcare and financial services buyers show lowest price sensitivity due to non-negotiable compliance mandates, while professional services firms drive hardest bargains through consolidated platform procurement.
Supply Chain Analysis
Container availability fluctuations on Asia-Pacific trade lanes and port congestion at Rotterdam and Long Beach inject unpredictability into hardware appliance delivery timelines for on-premises deployments. Component sourcing concentrates in Taiwan for confidential computing enclaves, Ireland for EU data residency infrastructure, and Israel for endpoint security modules. Supply chains rest on specialized cryptographic hardware from Intel and AMD, sovereign cloud infrastructure from regional hyperscalers, and systems integrator labor pools in Germany and Japan. Single-source vulnerability in qualified certification auditors stretches implementation timelines. Distribution runs through hyperscaler marketplaces for cloud-native solutions and systems integrator channels for hybrid configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EFSS market sits in early-cycle expansion as sovereign data residency mandates penetrate beyond financial services into manufacturing supply chains. Regulatory fragmentation across the EU AI Act, METI guidelines, and India's PLI scheme creates sustained tailwinds for hybrid infrastructure investment.
For Market Incumbents: Consolidate certification depth as the primary defensive moat, accelerating ISO/IEC 27001 and FedRAMP renewals ahead of procurement windows. Acquire confidential computing capabilities through specialist partnerships to counter hardware-attested security entrants. Anchor hybrid deployment contracts with German automotive and Japanese electronics manufacturers before compliance cascades harden vendor selection.
For New Entrants and Emerging Players: Lead with vertical-specific workflow automation for EU AI Act compliance, targeting tier-two automotive suppliers and pharmaceutical contract manufacturers. India's PLI scheme beneficiaries in electronics and pharmaceuticals represent the most penetrable geography, with captive infrastructure requirements bypassing hyperscaler incumbency. White-label through vertical SaaS platforms to bypass direct enterprise sales cycles.
For Investors and Strategic Acquirers: EU AI Act enforcement reshapes the acquisition landscape toward vendors with explainable AI logging and human-in-the-loop override architectures. Long-term viability favors specialists with jurisdictional data residency controls over pure-play cloud storage. Watch for ISO/IEC 27001 certification timeline compression as the inflection signal for vendor pool scarcity premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Confidential Computing Integration | Intel SGX and AMD SEV enclaves enable genomic data processing for healthcare systems without decryption exposure. |
| API-First Distribution Partnership | Embedded finance platforms white-label EFSS capabilities, bypassing traditional enterprise sales cycles through OEM channels. |
| Jurisdictional Data Residency Expansion | EU-based processing nodes satisfy GDPR and AI Act requirements for Swiss private banks and Singapore wealth managers. |
| Zero Trust Architecture Convergence | Continuous verification protocols with file synchronization endpoints open defense and critical infrastructure contract value. |
| PLI Scheme Infrastructure Capture | Captive EFSS deployment in Maharashtra and Karnataka manufacturing corridors addresses IP protection for electronics and pharmaceuticals. |
Research Methodology
Desk research of regulatory filings, hyperscaler capex disclosures, and certification audit records preceded structured interviews with CISOs at financial services firms, IT procurement officers in German manufacturing, cloud architects at systems integrators, and compliance leads at healthcare systems. Secondary validation drew from SEC cybersecurity disclosures, EU AI Act implementation guidance, METI cross-border data governance frameworks, and ISO/IEC 27001 certification databases. Bottom-up deployment modeling triangulated against top-down market sizing across cloud, hybrid, and on-premises configurations.
Variance decomposition across deployment model, solution type, end-user industry, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from penetration rate trajectories in regulated verticals, substitution effects from legacy backup tools, and pricing elasticity by buyer segment. Forecast inputs incorporated confidential computing hardware shipment pipelines, certification audit cycle durations, and PLI scheme beneficiary infrastructure commitments.
Forecasts assume regulatory continuity in EU AI Act enforcement, METI guideline implementation, and FedRAMP certification requirements; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Network File System Market
Storage Solutions
Storage and Backup Software Market
Storage Solutions
Automated Storage and Retrieval Systems in Laboratories Market
Storage Solutions
Cloud Native Storage Market
Storage Solutions
Global Personal Cloud Storage Market
Storage Solutions
Storage in Big Data Market
Storage Solutions
Network Attached Storage (NAS) Market
Storage Solutions
Storage Software Market
Storage Solutions
Global in-Memory Database Market
Storage Solutions
United Arab Emirates Data Center Storage Market
Storage Solutions
Global Cloud Storage Software Market
Storage Solutions
Data Backup and Recovery Market
Storage Solutions
Hong Kong Data Center Storage Market
Storage Solutions
5D Data Storage Market
Storage Solutions
Denmark Data Center Storage Market
Storage Solutions
Belgium Data Center Storage Market