
 Vietnam Data Center Storage Market | 2026-2036
Vietnam Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Data Center Storage Market Insights
The Vietnam data center storage market is consolidating around a widening gap between hyperscale-grade flash arrays and legacy disk infrastructure serving cost-sensitive local enterprises. Viettel IDC leverages its military-affiliated fiber backbone to dominate sovereign and defense-adjacent contracts. FPT Telecom International competes through vertical integration into cloud service layers, while Dell Technologies anchors premium enterprise sales with direct-to-datacenter logistics networks.
Vietnam data center storage encompasses electromechanical and solid-state systems engineered for persistent digital retention, with flash arrays achieving sub-millisecond latency and disk platforms optimizing cost per terabyte for archival workloads. Flash storage commands the fastest expansion trajectory as hyperscale deployments in Ho Chi Minh City prioritize NVMe-over-Fabric performance. Software-defined storage is displacing traditional SAN architectures among service providers seeking vendor-agnostic orchestration, while tape storage sustains long-horizon compliance retention for government archives with minimal energy overhead.
Vietnam's Ministry of Information and Communications enforces data localization through Decree 53, compelling foreign platforms to contract domestic storage capacity, while BIS-aligned standards govern equipment import certification. The national cybersecurity law mandates cross-border data flow review, tightening procurement criteria for foreign-origin storage hardware. Stakeholders must weigh sovereign infrastructure requirements against total cost of ownership as localization rules harden and domestic vendors deepen firmware customization capabilities.
Market Dynamics
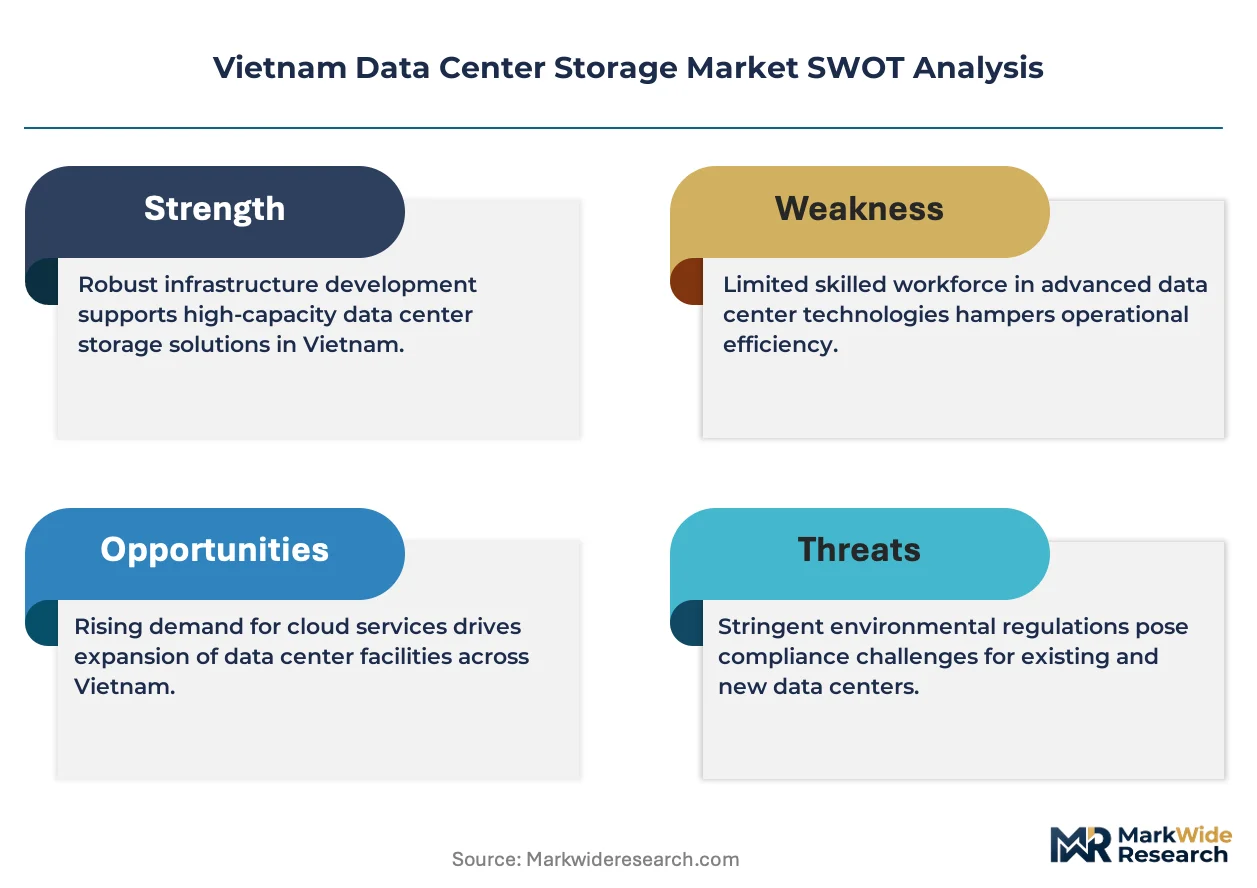
NVMe-over-Fabric flash arrays are compressing latency benchmarks across Ho Chi Minh City hyperscale facilities, forcing legacy SAN architectures into accelerated obsolescence cycles as sovereign data localization mandates harden procurement criteria.
Growth Catalysts
- Decree 53 Localization Mandate:Vietnam's Ministry of Information and Communications compels foreign cloud platforms to contract domestic storage capacity, creating guaranteed demand for local facility expansion.
- Hyperscale NVMe Deployment:Sub-millisecond flash arrays in Ho Chi Minh City and Hanoi are pulling infrastructure investment away from disk-based archival systems.
- Central Bank Compliance Retention:Vietnamese financial services firms are expanding storage capacity to meet State Bank of Vietnam data retention mandates for transaction records and audit trails.
Market Restraints
- Import Certification Friction:BIS-aligned equipment certification creates procurement delays for foreign-origin storage hardware entering Vietnamese facilities.
- Flash Cost Premium:Solid-state arrays maintain 3-4x cost per terabyte disadvantage against disk platforms for archival workloads, constraining adoption outside performance-critical tiers.
- Firmware Customization Gap:Domestic Vietnamese vendors lag in sovereign firmware customization capabilities, limiting their capture of defense-adjacent contracts.
Strategic Opportunities
- Software-Defined Orchestration:Vendor-agnostic storage virtualization is capturing service provider procurement as alternatives to proprietary SAN architectures.
- Tape Archive Energy Arbitrage:Government archives in Hanoi are deploying tape libraries for long-horizon compliance retention with minimal energy overhead versus spinning disk.
- Cross-Border Flow Review:Vietnam's national cybersecurity law tightens hardware procurement criteria for foreign vendors, creating white space for domestic-integrated systems.
Industry Challenges
- Legacy SAN Integration Complexity:Financial institutions in Ho Chi Minh City face operational friction migrating transaction processing workloads from traditional Fibre Channel architectures to NVMe fabrics.
- Specialized Firmware Engineering Talent:Defense-adjacent storage contracts require cleared personnel with both semiconductor firmware and sovereign security clearance, a scarce combination in Vietnam's labor pool.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Data Center Storage Market |
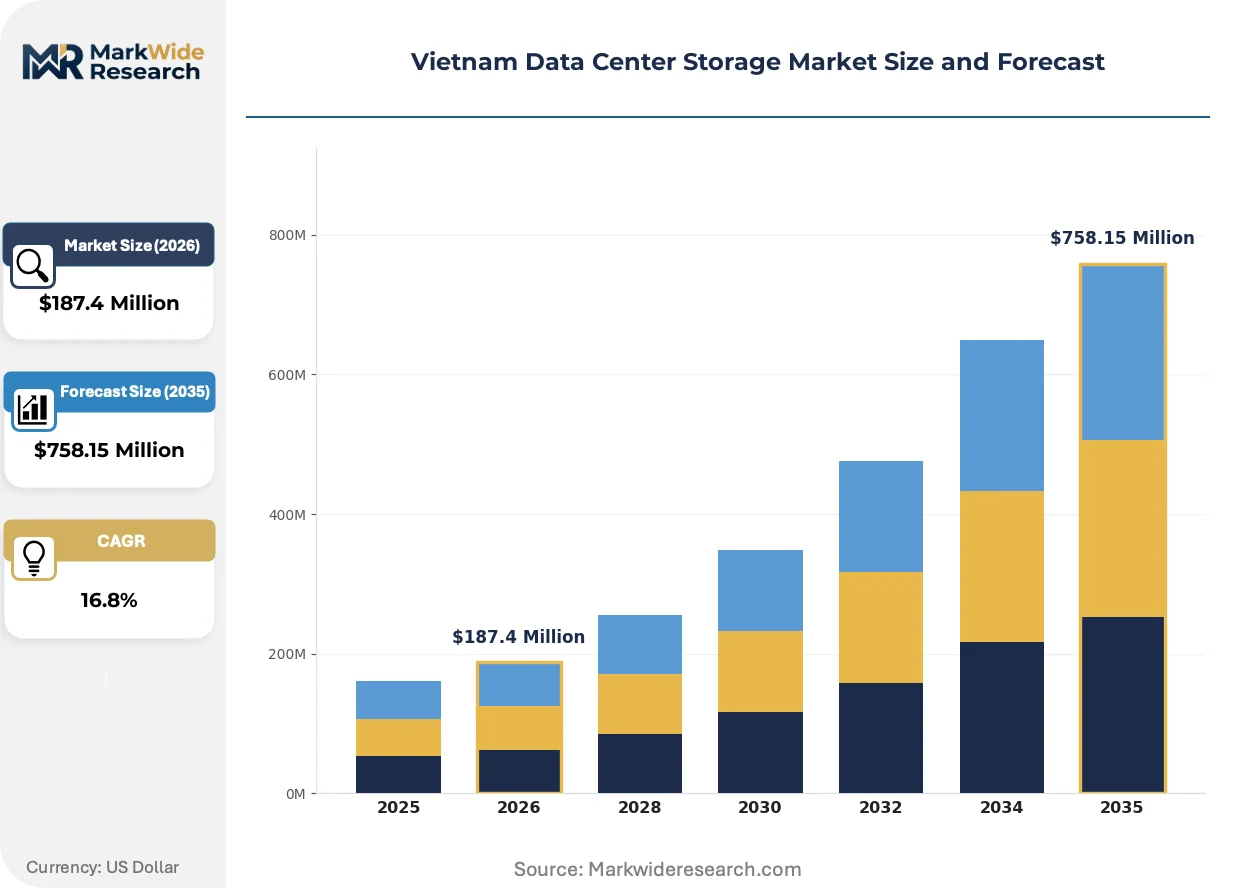
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $758.15 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disk Storage, Tape Storage, Flash Storage, Optical Storage End User: Enterprises, Small Businesses, Government, Service Providers Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Technology: SAN, NAS, Object Storage, Software-Defined Storage |
| Companies Covered | Viettel IDC, VNPT VinaData, FPT Telecom International, CMC Telecom, Dell Technologies, Seagate Technology, NetApp, Oracle Corporation, NTT Global Data Centers Vietnam, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Data Center Storage Market Trends and Innovations
Storage-class memory hierarchies are flattening latency profiles across Vietnamese hyperscale deployments while regulatory firmware requirements are fragmenting vendor qualification pathways.
NVMe-over-Fabric architectures are expanding into transaction processing tiers previously reserved for Fibre Channel SANs. State Bank of Vietnam-regulated financial institutions in Ho Chi Minh City are piloting these fabrics for real-time payment clearing. The technology is expanding into mission-critical workloads by collapsing storage network latency from milliseconds to microseconds, compressing competitive differentiation around raw performance rather than feature breadth.
Decree 53 enforcement is hardening data localization requirements for foreign platform operators. The regulation mandates domestic storage contracting and cross-border data flow review, compelling hyperscale cloud providers to establish certified Vietnamese facilities. Foreign-origin hardware faces extended BIS-aligned import certification timelines, advantaging domestic-integrated storage systems in sovereign-sensitive procurement.
Consumption-based capacity contracts are displacing traditional capital-intensive storage procurement among mid-tier Vietnamese enterprises. FPT Telecom International and domestic service providers are unbundling hardware ownership from operational management, shifting buyer preference toward utility-modeled storage subscriptions. This pattern is most visible among SaaS-enabled logistics firms in Hanoi seeking to convert fixed infrastructure costs to variable operating expenditure.
Vietnam Data Center Storage Market Segmentation
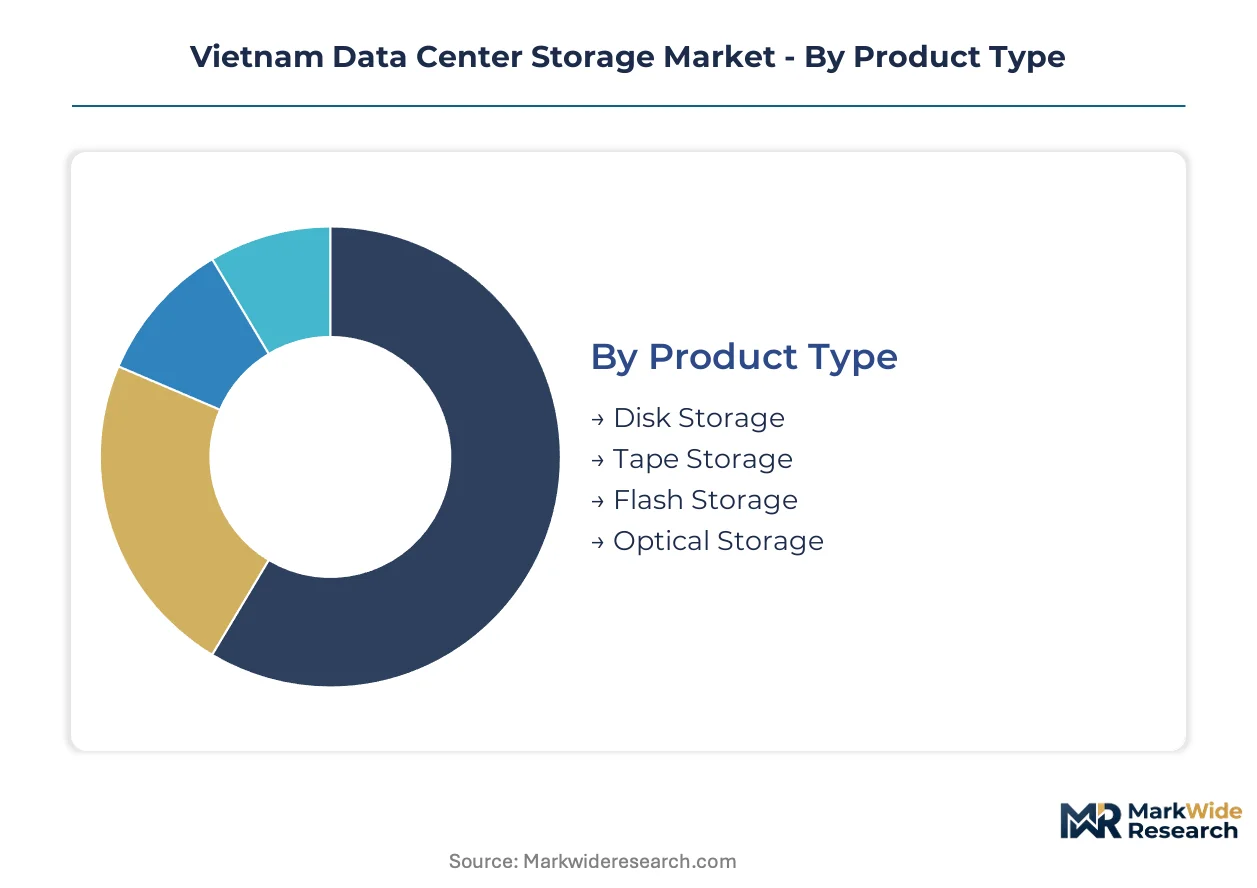
Storage procurement in Vietnam fragments across performance tiers, regulatory exposure, and operational control requirements. Buyers calibrate infrastructure choices against Decree 53 localization mandates, State Bank of Vietnam retention rules, and hyperscale latency benchmarks.
Product Type:
Standardized commodity platforms anchor volume procurement while sovereign-customized firmware commands premium positioning in defense-adjacent deployments.
- Flash Storage:NVMe-over-Fabric arrays deliver sub-millisecond latency for real-time payment clearing in Ho Chi Minh City financial institutions. State Bank of Vietnam compliance mandates for transaction record retention are pulling investment toward performance-tier flash despite 3-4x cost premiums over disk alternatives.
- Disk Storage:Electromechanical HDD platforms optimize cost per terabyte for archival and backup workloads. Mid-tier enterprises in Hanoi favor disk tiers for non-critical data lakes where retrieval latency tolerance exceeds 10 milliseconds.
- Tape Storage:Linear Tape-Open libraries serve government archives with minimal energy overhead for multi-decade compliance retention.
- Optical Storage:Blu-ray archival systems address immutable audit requirements in provincial tax authority facilities.
Leading the category by volume: Disk Storage. Growing fastest: Flash Storage.
End User:
Procurement sophistication scales with regulatory scrutiny intensity and cross-border data exposure.
- Enterprises:Large Vietnamese conglomerates deploy hybrid flash-disk hierarchies with software-defined orchestration layers. Manufacturing exporters in Binh Duong prioritize NVMe fabrics for ERP transaction processing.
- Service Providers:Domestic cloud operators contract hyperscale flash capacity to satisfy Decree 53 localization requirements for foreign platform subcontractors. FPT Telecom International and Viettel IDC dominate this procurement tier with vertically integrated facility ownership.
- Government:Military-affiliated agencies mandate sovereign firmware customization, limiting vendor qualification to domestic-integrated systems.
- Small Businesses:Consumption-based storage subscriptions displace capital expenditure among SaaS-enabled logistics firms converting fixed costs to variable operating expenditure.
Dominating procurement value: Enterprises. Expanding most quickly: Service Providers.
Deployment Model:
Control retention preferences diverge sharply between regulated financial institutions and cost-optimizing mid-market buyers.
- On-Premises:Dedicated facility ownership persists among defense contractors and central bank-regulated entities requiring air-gapped transaction processing infrastructure.
- Hybrid:Tiered data placement across owned flash and contracted cloud archive is capturing financial services procurement as retention rules harden.
- Cloud-Based:Foreign hyperscale providers establish certified Vietnamese facilities under Decree 53, contracting domestic storage capacity for platform localization.
- Managed:Third-party operational control appeals to enterprises lacking specialized storage engineering talent in Vietnam's constrained labor pool.
Commanding current investment: On-Premises. Gaining share fastest: Hybrid.
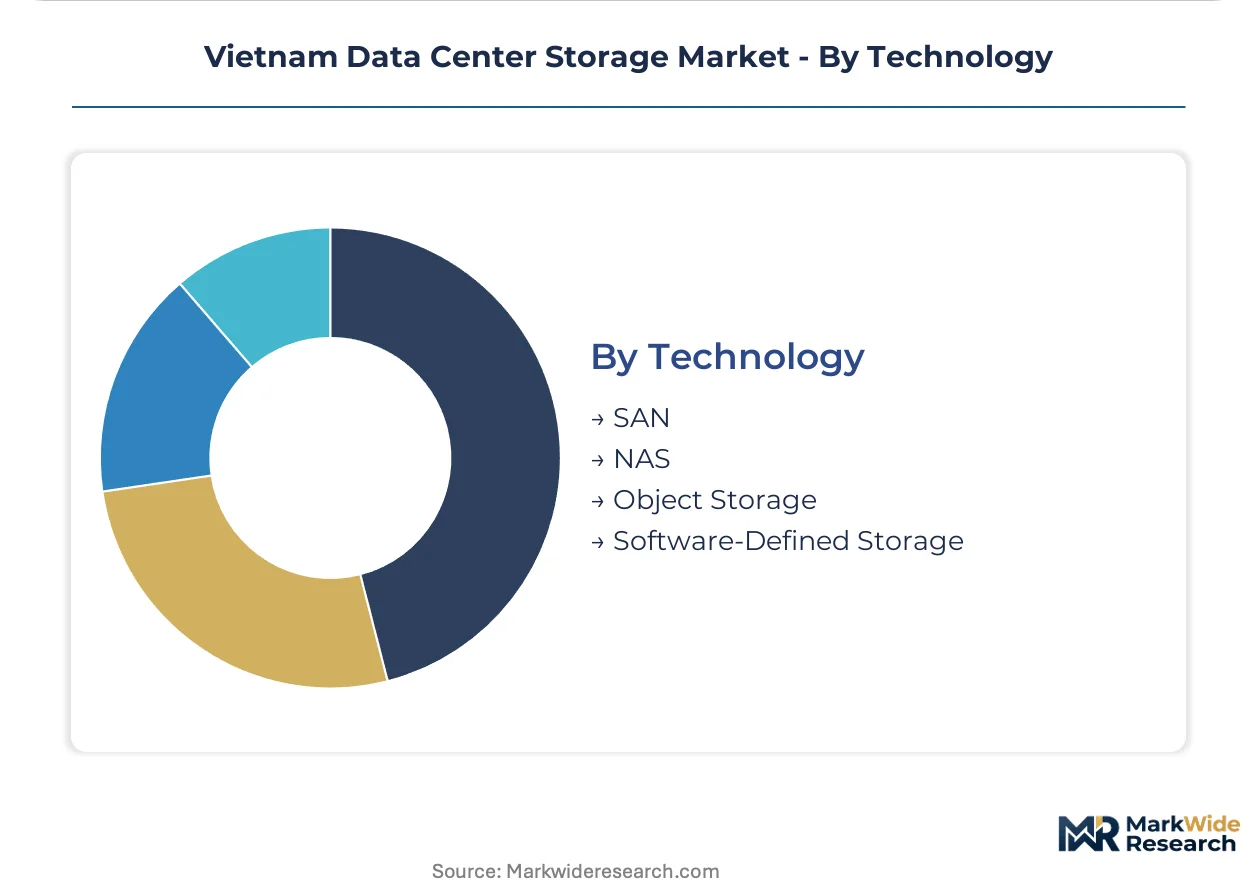
Technology:
Proprietary architectures face displacement pressure from vendor-agnostic alternatives as service providers seek procurement flexibility.
- Software-Defined Storage:Abstraction layers decouple hardware procurement from data management software, enabling multi-vendor flash deployments. Domestic operators favor SDS for defense-adjacent contracts requiring firmware customization without single-vendor lock-in.
- SAN:Fibre Channel fabrics retain installed base in legacy transaction processing environments. Ho Chi Minh City banks face operational friction migrating critical workloads to NVMe alternatives.
- NAS:File-level access protocols serve unstructured data growth in media and content distribution networks.
- Object Storage:S3-compatible APIs support cloud-native application development among Vietnamese SaaS providers.
Capturing replacement demand: Software-Defined Storage. Facing steepest erosion: SAN.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ho Chi Minh City anchors Vietnam's data center storage expansion through hyperscale facility construction serving financial services compliance mandates.
Ho Chi Minh City
NVMe-over-Fabric flash arrays dominate transaction processing infrastructure as State Bank of Vietnam retention rules harden. Decree 53 localization compels foreign cloud platforms to contract domestic capacity. District 7 and Thu Duc City host concentrated hyperscale deployments from Viettel IDC and FPT Telecom International.
Hanoi
Government archives drive tape storage procurement for multi-decade compliance retention with minimal energy overhead. The Ministry of Information and Communications enforces BIS-aligned equipment certification for foreign-origin hardware. Cau Giay and Nam Tu Liem districts concentrate military-affiliated data facilities requiring sovereign firmware customization.
Da Nang
Central region enterprises favor hybrid cloud deployments balancing on-premises flash with contracted archive tiers. The national cybersecurity law mandates cross-border data flow review for facilities serving logistics exporters. Hoa Vang district emerging as secondary data hub connecting north-south fiber routes.
Binh Duong
Manufacturing conglomerates deploy NVMe fabrics for ERP transaction processing supporting export operations. Provincial industrial zones attract managed storage subscriptions from SaaS-enabled supply chain operators. Di An and Thuan An cities concentrate foreign-invested electronics manufacturers with localized retention requirements.
Hai Phong
Port logistics and shipping operators drive object storage demand for unstructured cargo documentation. Northern coastal positioning offers submarine cable landing advantages for international connectivity. Cat Hai district facilities serve customs and maritime regulatory data localization mandates.
Vietnam Data Center Storage Market Competitive Landscape
Capital-heavy facility operators compete with asset-light technology integrators across Vietnam's storage procurement tiers. Market structure consolidates around military-affiliated domestic champions, vertically integrated telecom providers, and foreign-origin equipment vendors navigating certification friction. Three archetypes dominate: sovereign-integrated domestic operators, regional cloud platform integrators, and premium enterprise technology suppliers. Competitive intensity centers on facility ownership consolidation and firmware customization capabilities for defense-adjacent contracts.
Within the sovereign-integrated tier, Viettel IDC anchors military and government procurement through fiber backbone control. FPT Telecom International exemplifies vertical integration into cloud service layers, while Dell Technologies occupies the premium enterprise position with direct-to-datacenter logistics networks. These three represent distinct competitive vectors—sovereign infrastructure, platform services, and high-performance hardware—each capturing procurement flows from divergent buyer risk tolerances and compliance exposure levels.
| Leading Market Players |
|---|
| Viettel IDC |
| VNPT VinaData |
| FPT Telecom International |
| CMC Telecom |
| Dell Technologies |
| Seagate Technology |
| NetApp |
| Oracle Corporation |
| NTT Global Data Centers Vietnam |
| Others |
Pricing and Supply Chain Analysis
NAND flash memory spot price indices cascade through Vietnamese data center procurement tiers, compressing margins on hyperscale NVMe deployments while amplifying cost advantages for tape-based government archives. Buyers calibrate tier placement against Decree 53 localization mandates and BIS-aligned import certification timelines.
Pricing Analysis
Throughput-guaranteed uptime contracts anchor enterprise flash pricing in Ho Chi Minh City financial institutions. Pricing stratifies across sovereign-customized firmware tiers, certified import grades, and consumption-based subscription models. Cost compression in standard disk tiers intensifies as mid-tier enterprises migrate toward managed service bundles. Small logistics operators in Hanoi exhibit highest price sensitivity, while defense-adjacent agencies accept premium positioning for cleared personnel requirements.
Supply Chain Analysis
Direct-to-datacenter channels handle hyperscale buyer demand from Viettel IDC and FPT Telecom International, bypassing distributor markups for volume flash procurement. Component supply concentrates in South Korea, Taiwan, and China for NAND fabrication and controller silicon. Vietnam's storage infrastructure draws from imported HDD mechanisms, LTO tape media, and domestic rack integration. Single-source vulnerability in NVMe controller ASICs creates procurement risk for defense-adjacent contracts requiring sovereign firmware customization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's data center storage market is consolidating around localization mandates that favor facility owners with military fiber access and certified domestic integration capabilities. Weaker foreign equipment vendors face displacement as BIS-aligned certification timelines harden procurement criteria.
For Market Incumbents: Extend sovereign firmware customization capabilities to capture defense-adjacent contracts from military-affiliated agencies. Deepen backward integration into cloud service layers to match FPT Telecom International's vertical control. Secure cleared personnel pipelines ahead of competitors as specialized engineering talent scarcity intensifies.
For New Entrants and Emerging Players: Begin with managed storage subscriptions targeting mid-tier logistics operators in Da Nang and Hai Phong seeking variable operating expenditure conversion. Penetrate the tape archive energy arbitrage opportunity in Hanoi government facilities where minimal energy overhead commands procurement preference. Position through utility-modeled capacity contracts rather than capital-intensive hardware sales.
For Investors and Strategic Acquirers: Distressed-cycle entries favor domestic-integrated operators with Decree 53 certification and existing fiber backbone control in secondary cities. Long-term viability hinges on positioning ahead of cross-border data flow review enforcement tightening hardware procurement criteria. Watch State Bank of Vietnam retention rule expansion as the inflection signal for compliance-driven capacity demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Firmware Customization | Captures defense-adjacent contracts requiring military security clearance integration. |
| NVMe-over-Fabric Deployment | Collapses latency for State Bank of Vietnam-regulated real-time payment clearing. |
| Consumption-Based Subscription Launch | Converts fixed infrastructure costs to variable OPEX for SaaS-enabled logistics firms. |
| Tape Archive Energy Arbitrage | Addresses Hanoi government demand for multi-decade compliance with minimal power overhead. |
| Decree 53 Certification Investment | Secures guaranteed demand from foreign cloud platforms mandating domestic capacity contracting. |
Research Methodology
Regulatory filings from Vietnam's Ministry of Information and Communications, State Bank of Vietnam circulars, and BIS equipment certification databases formed the secondary backbone. Primary interviews with data center facility operators, storage procurement officers at financial institutions, and defense contractor IT directors validated demand assumptions. Hyperscaler capex disclosures and customs import records provided triangulation anchors against bottom-up facility construction tracking.
Bottom-up modeling aggregated individual facility capacity announcements across Ho Chi Minh City, Hanoi, Da Nang, and Binh Duong, while top-down analysis calibrated against national data localization mandate compliance requirements. Segmentation dimensions spanned product type, end user regulatory exposure, deployment control preferences, and technology abstraction layers. CAGRs derived from facility pipeline visibility and sovereign contract award trajectories across the projection horizon.
Underlying measurement precision varies by segment; government and defense-adjacent procurement carries tighter precision than mid-tier enterprise subscriptions. Forecasts reflect assumptions on Decree 53 enforcement intensity and cross-border data flow review implementation timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Europe Data Center Storage Market
Storage Solutions
Stand Alone Cloud Storage Market
Storage Solutions
Cloud Block Storage Market
Storage Solutions
Enterprise File Sync and Share Platform Market
Storage Solutions
Belgium Data Center Storage Market
Storage Solutions
India Data Center Storage Market
Storage Solutions
Storage and Backup Software Market
Storage Solutions
Automated Storage and Retrieval System (AS & RS) Market
Storage Solutions
Copy Data Management Software Market
Storage Solutions
Global Cloud Storage Software Market
Storage Solutions
Multi Cloud Storage Market
Storage Solutions
Virtual Machine Backup and Recovery Market
Storage Solutions
Public Cloud Storage Services Market
Storage Solutions
New Zealand Data Center Storage Market
Storage Solutions
Mexico Data Center Storage Market
Storage Solutions
Network File System Market