
 Distributed Performance and Availability Management Software Market | 2026-2036
Distributed Performance and Availability Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Distributed Performance and Availability Management Software Market Outlook
Microservices architecture is fragmenting the traditional monolithic monitoring stack into specialized, API-driven observability layers. Dynatrace leverages its Davis AI engine to automate root-cause analysis across containerized environments. Splunk competes through its data-to-everything platform that unifies logs, metrics, and traces. New Relic differentiates with consumption-based pricing that lowers barriers for mid-market cloud migrations.
Distributed performance and availability management software comprises agent-based and agentless instrumentation that collects telemetry from servers, containers, networks, and applications to measure latency, throughput, error rates, and uptime against service-level objectives. Cloud-based deployment now captures the dominant margin pool as enterprises abandon capital-intensive data center instrumentation. Real-time monitoring functionality leads in attach rates because operational teams require sub-second alerting to prevent cascading failures in distributed architectures. Financial services and telecommunications verticals generate the steepest growth curves due to regulatory uptime mandates and 5G network complexity.
FDA 21 CFR Part 11 and HIPAA shape healthcare buyer requirements for audit trails and data integrity in availability management tools. The EU AI Act and GDPR impose algorithmic transparency obligations on automated anomaly detection systems, forcing vendors to document decision logic. NIST cybersecurity frameworks in the United States further harden procurement criteria for federal agencies. Stakeholders must weigh sovereign cloud requirements against multi-cloud interoperability when selecting platforms for the next infrastructure refresh cycle.
Market Dynamics
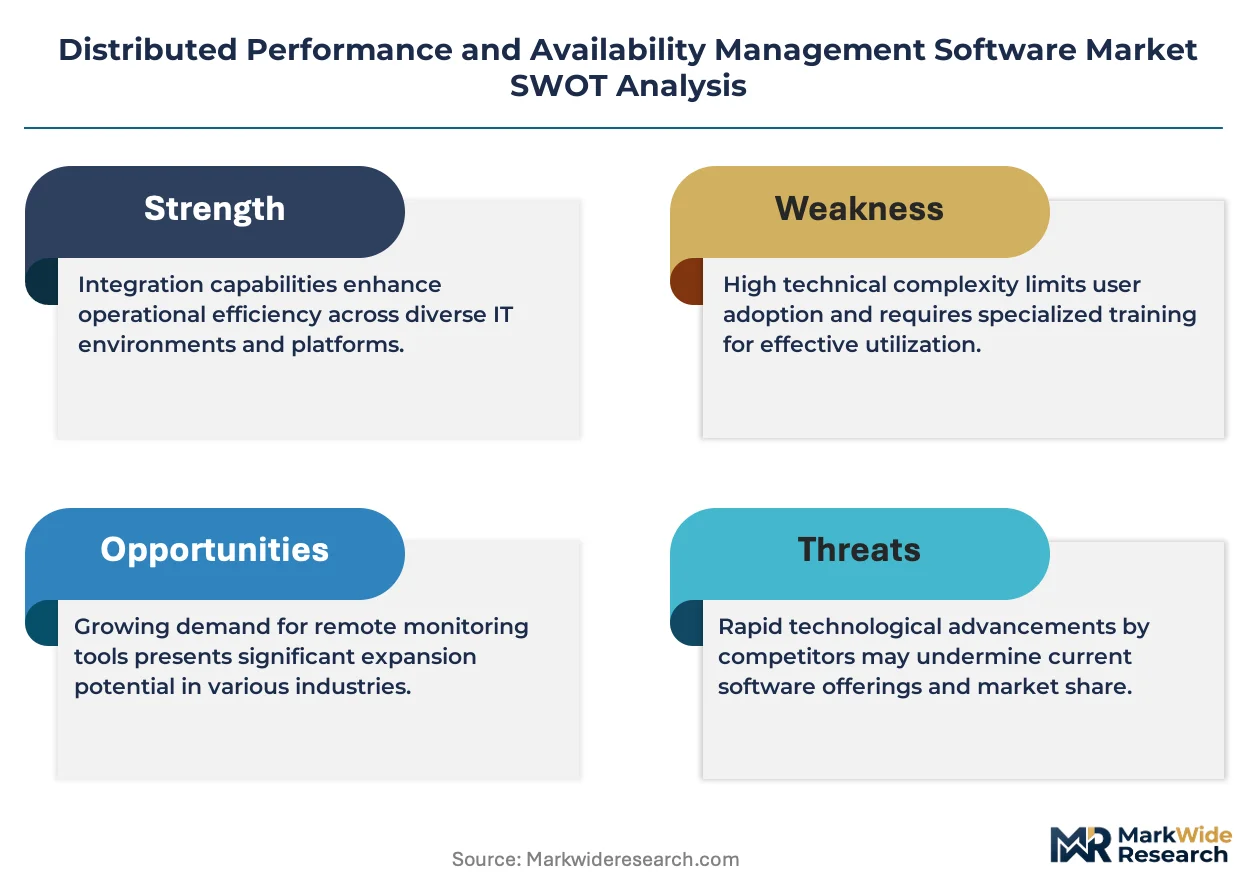
Cloud-native observability stacks are fragmenting procurement patterns as financial services institutions dismantle monolithic monitoring infrastructure in favor of API-driven, containerized instrumentation layers.
Growth Catalysts
- EU AI Act mandates:Algorithmic transparency requirements for automated anomaly detection systems are forcing enterprises to upgrade legacy monitoring tools, creating replacement demand across European banking and insurance sectors.
- 5G network complexity:Telecommunications operators require sub-second alerting capabilities to manage distributed radio access networks and edge computing nodes, driving attach rates for real-time monitoring functionality.
- Microservices architecture:Containerized application deployments generate telemetry volumes that overwhelm traditional agent-based instrumentation, accelerating adoption of agentless and eBPF-based collection methods.
Market Restraints
- Specialized talent scarcity:Site reliability engineering expertise concentrated in technology hubs limits enterprise ability to operationalize advanced observability platforms without managed service intermediation.
- Data sovereignty compliance:GDPR cross-border transfer restrictions and EU AI Act documentation obligations impose architectural constraints that increase total cost of ownership for multi-cloud deployments.
- Legacy system entrenchment:Capital-intensive data center instrumentation with depreciated hardware creates switching friction that delays cloud migration timelines in industrial and healthcare verticals.
Strategic Opportunities
- German industrial digitization:Manufacturing conglomerates implementing Industry 4.0 frameworks require resilient distributed systems for predictive maintenance, opening mid-market entry points for consumption-based pricing models.
- Healthcare audit trail mandates:FDA 21 CFR Part 11 and HIPAA data integrity requirements create specialized product configurations for availability management tools in pharmaceutical manufacturing and clinical trial infrastructure.
- Unified telemetry convergence:Integration of logs, metrics, and traces into single-pane observability platforms enables cross-functional workflow consolidation that reduces mean-time-to-resolution for operational teams.
Industry Challenges
- eBPF instrumentation expertise:Kernel-level telemetry collection requires Linux systems programming capabilities that outpace current supply of platform engineers in enterprise IT organizations.
- NIST framework procurement hardening:Federal agency cybersecurity requirements extend vendor qualification timelines and demand specialized compliance documentation that smaller observability providers struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distributed Performance and Availability Management Software Market |
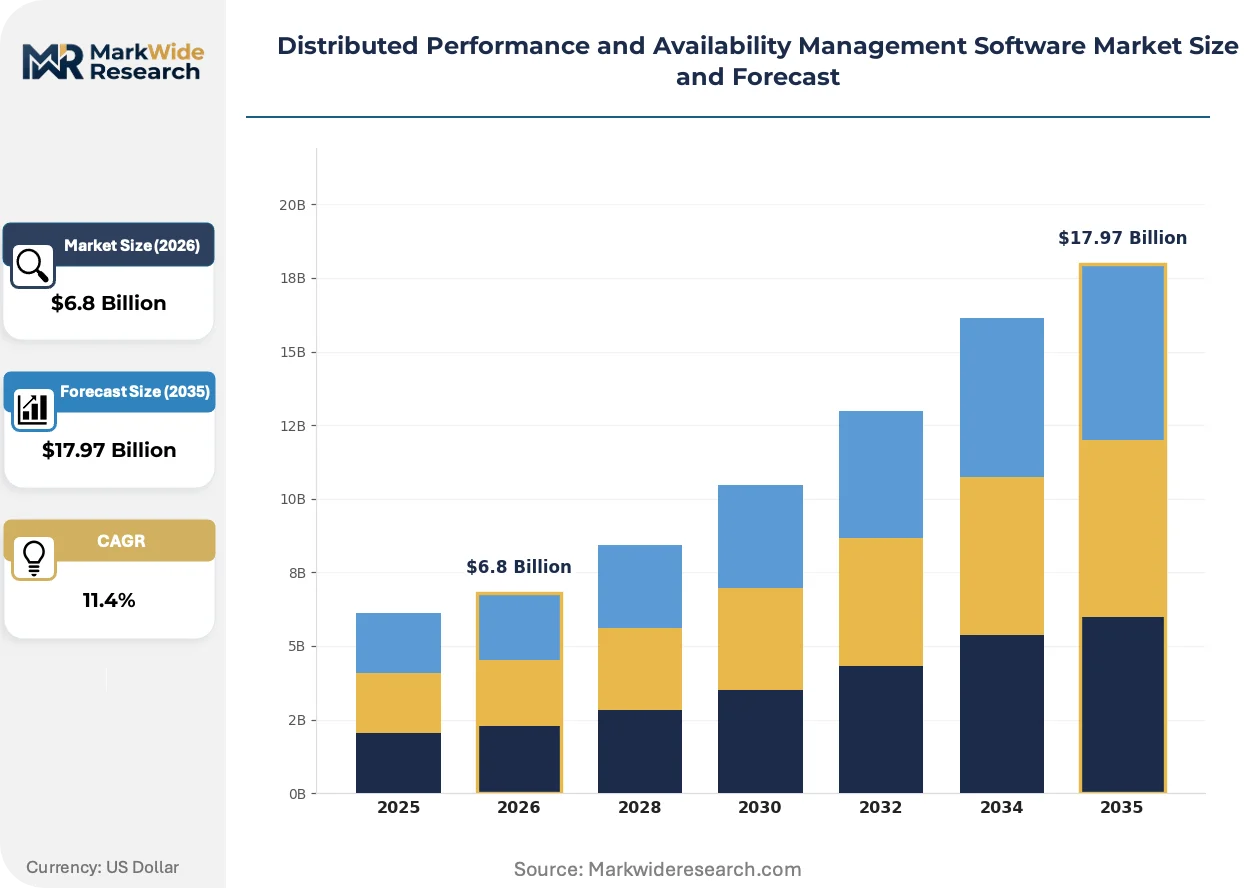
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, Multi-Cloud End User: Enterprise, SMEs, Managed Service Providers, Government Agencies Functionality: Real-Time Monitoring, Reporting, Alerting, Analytics Industry Vertical: Healthcare, Financial Services, Retail, Telecommunications |
| Companies Covered | Dynatrace, New Relic, Broadcom, BMC Software, IBM Corporation, Microsoft Corporation, Cisco Systems, SolarWinds, Splunk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distributed Performance and Availability Management Software Market Strategic Shifts
Artificial intelligence is compressing root-cause analysis timelines from hours to seconds, restructuring competitive advantage around automated correlation engines rather than dashboard visualization depth.
OpenTelemetry is collapsing proprietary agent architectures by standardizing telemetry collection formats across cloud providers and on-premises infrastructure. Financial services institutions are adopting this instrumentation framework to avoid vendor lock-in during multi-cloud migrations. The standardization is collapsing differentiation among incumbent monitoring platforms and commoditizing data ingestion layers.
The EU AI Act imposes documentation obligations on automated anomaly detection systems that process personal data or influence critical infrastructure decisions. Vendors must now maintain decision logic audit trails and explainability interfaces that increase engineering overhead. Healthcare and telecommunications verticals in Germany, France, and the Netherlands are front-loading compliance investments to preempt enforcement actions.
Site reliability engineering teams are consolidating vendor relationships around platforms that unify observability data with incident response workflows. This procurement compression displaces point solutions for log management, synthetic monitoring, and error tracking. The pattern is most visible among mid-market technology companies in the United States and United Kingdom that prioritize operational headcount efficiency over best-of-breed feature depth.
Distributed Performance and Availability Management Software Market Segmentation
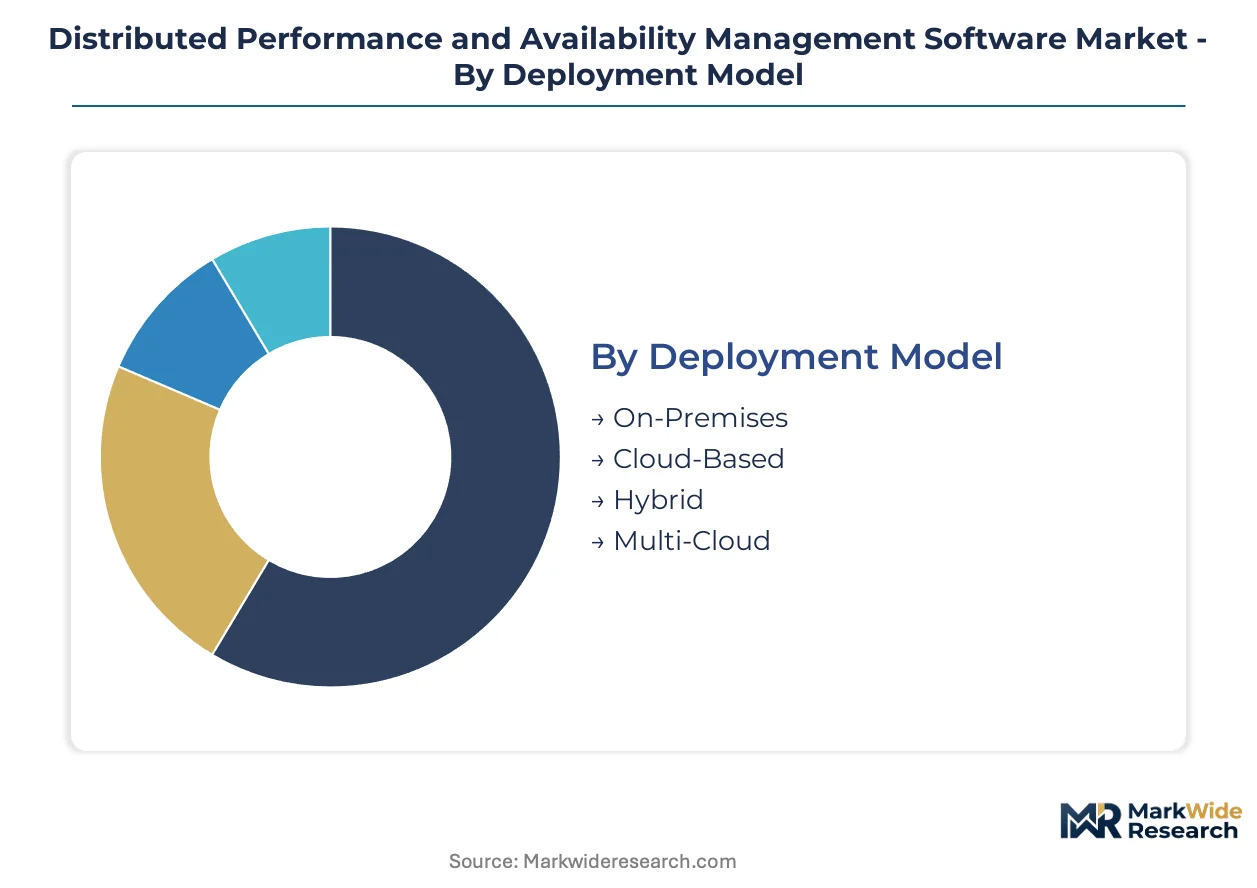
Fragmented telemetry architectures demand precise segmentation to align procurement cycles with operational maturity. Buyers match deployment models to infrastructure refresh timelines and select functionality tiers based on incident response automation requirements.
Deployment Model:
Cloud-based deployments turn over fastest as enterprises abandon depreciated data center assets; on-premises contracts extend longest due to capital recovery schedules.
- Cloud-Based:Fully managed SaaS delivery eliminates hardware procurement cycles and enables elastic scaling for containerized workloads. Financial services institutions in Germany and the Netherlands front-load migrations to satisfy EU AI Act documentation requirements for automated anomaly detection systems.
- Hybrid:Split instrumentation across sovereign on-premises nodes and burst-capable cloud tiers addresses GDPR cross-border transfer restrictions. Healthcare providers in France deploy this architecture to maintain patient data locality while leveraging cloud analytics for operational dashboards.
- On-Premises:Capital-intensive perpetual licensing with depreciated server infrastructure creates switching friction in industrial verticals.
- Multi-Cloud:Abstraction layers normalize telemetry collection across AWS, Azure, and GCP environments to prevent vendor lock-in.
On-premises dominates installed base. Cloud-based is where expansion concentrates.
End User:
Enterprise procurement runs on 3-5 year framework agreements; SME adoption accelerates through consumption-based pricing that eliminates upfront commitments.
- Enterprise:Centralized observability teams mandate unified telemetry platforms spanning hybrid infrastructure. Telecommunications operators in Spain require sub-second alerting capabilities across distributed radio access networks and edge computing nodes.
- SMEs:Limited site reliability engineering headcount drives preference for managed observability with automated correlation. Mid-market technology companies in the United Kingdom prioritize operational headcount efficiency over best-of-breed feature depth.
- Managed Service Providers:Multi-tenant architectures demand granular data isolation and white-label dashboard capabilities.
- Government Agencies:NIST cybersecurity frameworks extend vendor qualification timelines and demand specialized compliance documentation.
Enterprise captures the dominant revenue pool. SMEs are climbing the fastest as cloud-native pricing lowers entry barriers.
Functionality:
Real-time monitoring attaches at highest rates due to operational necessity; analytics modules face longer sales cycles requiring data science team validation.
- Real-Time Monitoring:Sub-second telemetry ingestion with automated threshold alerting prevents cascading failures in microservices architectures. 5G network complexity in Italy drives attach rates for distributed radio access network visibility.
- Analytics:Predictive capacity planning and anomaly pattern recognition require historical data lakes and machine learning pipeline integration. Banking regulators in Belgium mandate algorithmic transparency documentation for automated decision systems.
- Alerting:Multi-channel notification routing with escalation policies integrates directly with incident response workflows.
- Reporting:Compliance-ready audit trails satisfy FDA 21 CFR Part 11 and HIPAA data integrity requirements for pharmaceutical manufacturing.
Real-time monitoring dominates attach rates. Analytics is where vendor differentiation intensifies.
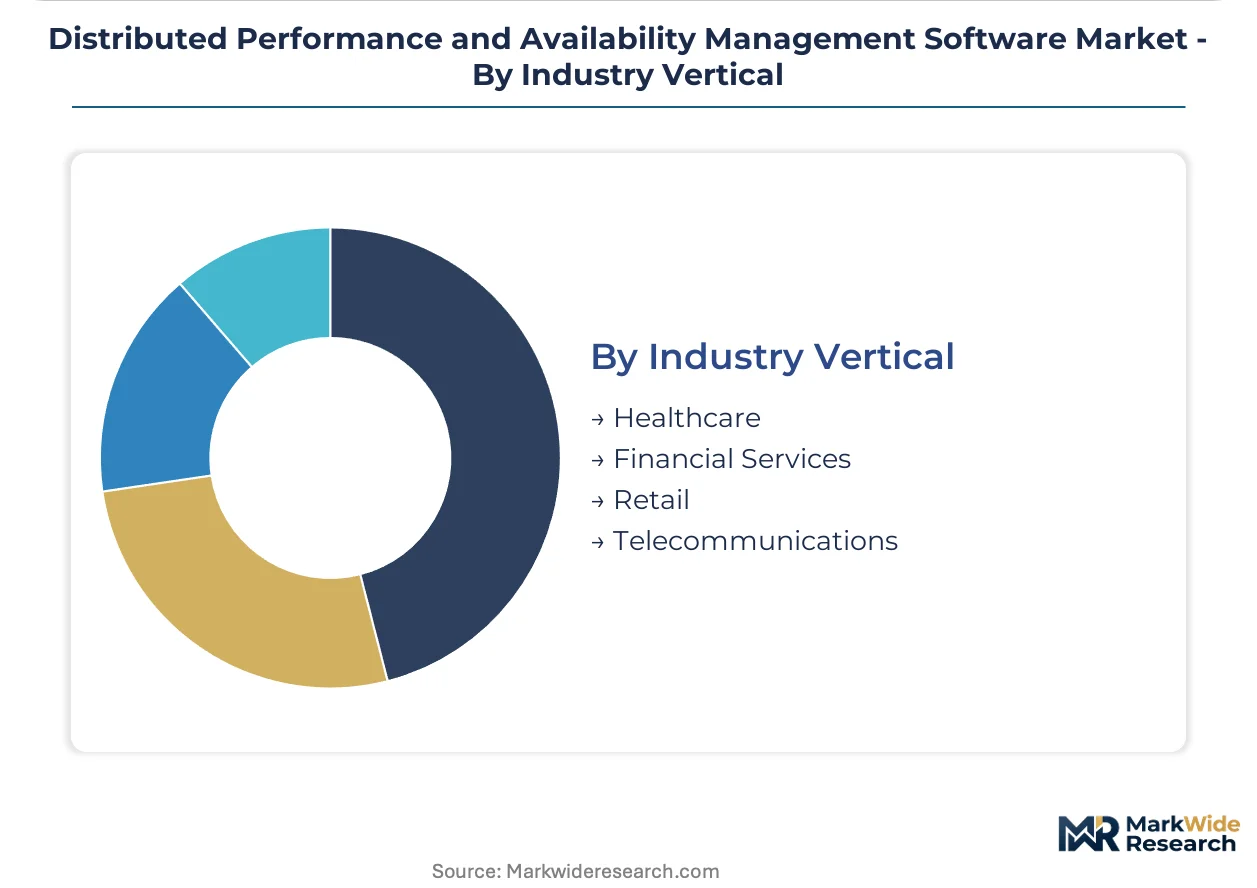
Industry Vertical:
Financial services refresh cycles align with regulatory examination schedules; healthcare procurement extends due to validation requirements for clinical infrastructure.
- Financial Services:Regulatory uptime mandates and algorithmic trading latency requirements drive investment in resilient distributed systems. EU AI Act compliance obligations in Germany force upgrades to legacy monitoring tools with explainable decision logic.
- Telecommunications:5G standalone core deployments and edge computing node proliferation generate telemetry volumes that overwhelm traditional instrumentation. Operators in Poland require kernel-level eBPF collection for network function virtualization visibility.
- Healthcare:FDA 21 CFR Part 11 and HIPAA audit trail mandates create specialized configurations for availability management in clinical trial infrastructure.
- Retail:Seasonal demand spikes and omnichannel transaction monitoring prioritize elastic cloud observability over fixed infrastructure.
Financial services dominates compliance-driven replacement demand. Telecommunications is gaining share fastest from 5G infrastructure buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial services institutions in Germany and telecommunications operators across Southern Europe drive the steepest procurement curves for cloud-native observability platforms.
United States
Enterprise technology companies and federal agencies anchor demand for unified telemetry platforms. NIST cybersecurity frameworks extend vendor qualification timelines for observability providers seeking government contracts. Silicon Valley site reliability engineering teams consolidate vendor relationships around incident response workflow integration.
Germany
Industrial conglomerates implementing Industry 4.0 frameworks require resilient distributed systems for predictive maintenance and manufacturing uptime. EU AI Act algorithmic transparency mandates force banking and insurance sectors to upgrade legacy monitoring tools with explainable decision logic. Munich and Frankfurt financial services clusters front-load compliance investments to preempt enforcement actions.
United Kingdom
Mid-market technology companies prioritize operational headcount efficiency over best-of-breed feature depth in observability procurement. GDPR cross-border transfer restrictions shape hybrid deployment architectures for healthcare providers maintaining patient data locality. London fintech clusters drive consumption-based pricing adoption for containerized workload monitoring.
France
Healthcare providers deploy hybrid instrumentation architectures to satisfy CNIL data sovereignty requirements while leveraging cloud analytics capabilities. ANSM audit trail mandates for pharmaceutical manufacturing create specialized configurations for availability management tools. Paris-based telecommunications operators require sub-second alerting for 5G standalone core deployments.
Japan
Telecommunications operators managing distributed radio access networks and edge computing nodes generate telemetry volumes overwhelming traditional agent-based instrumentation. METI industrial digitization programs accelerate manufacturing sector investment in predictive maintenance systems. Tokyo and Osaka technology clusters concentrate site reliability engineering expertise for enterprise observability operationalization.
Distributed Performance and Availability Management Software Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement patterns in the distributed performance and availability management software market. Consolidation pressures intensify as site reliability engineering teams compress vendor relationships around unified telemetry platforms. Three archetypes dominate: cloud-native specialists with consumption-based pricing, legacy infrastructure incumbents with hybrid deployment capabilities, and data platform aggregators unifying logs, metrics, and traces. Competitive moves concentrate on strategic partnerships for OpenTelemetry standardization and portfolio diversification into automated incident response workflows.
Within the cloud-native specialist tier, Dynatrace and New Relic exemplify platform approaches that lower barriers for mid-market cloud migrations through consumption-based pricing models. Splunk occupies a position representing data platform aggregation archetypes that unify telemetry streams across hybrid infrastructure. These three companies anchor competitive positioning around automated correlation engines rather than dashboard visualization depth.
| Leading Market Players |
|---|
| Dynatrace |
| New Relic |
| Broadcom |
| BMC Software |
| IBM Corporation |
| Microsoft Corporation |
| Cisco Systems |
| SolarWinds |
| Splunk |
| Others |
Value Chain & Pricing Dynamics
Kernel-level telemetry engineering talent concentrates in Germany, Japan, and the United States, concentrating margin pools with vendors who maintain captive eBPF instrumentation expertise rather than outsourced development partnerships.
Pricing Analysis
Annual subscription contracts with CPI indexation dominate enterprise procurement, though consumption-based metering gains traction among mid-market cloud migrations. Price differentiation rests on AI-driven correlation depth and EU AI Act compliance documentation tiers. Pricing pressure intensifies from OpenTelemetry standardization commoditizing data ingestion layers. SMEs exhibit highest price sensitivity; financial services institutions in Germany prioritize algorithmic transparency over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China disrupts semiconductor supply for telemetry processing hardware embedded in on-premises appliances. Software supply chains draw from India for backend development, Ireland for EU data residency infrastructure, and Singapore for Asia-Pacific cloud orchestration. Single-source vulnerability concentrates in proprietary AI training data repositories. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OpenTelemetry instrumentation standardization is collapsing vendor lock-in economics, creating platform-economics inflection where interoperability investments determine long-term competitive viability.
For Market Incumbents: Harden defensive moats by deepening in-house eBPF kernel engineering capabilities and acquiring automated incident response workflow specialists. Consolidate channel relationships before OpenTelemetry commoditization erodes proprietary agent differentiation. Prioritize EU AI Act documentation tooling investments to preempt compliance-driven displacement in European banking. For New Entrants and Emerging Players: Pursue white-space expansion in German manufacturing mid-market segments underserved by consumption-based pricing models. Target healthcare providers in France requiring hybrid deployment architectures for CNIL data sovereignty compliance. Lead with managed observability services that eliminate site reliability engineering headcount requirements. For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native specialists with demonstrated OpenTelemetry integration roadmaps and established hyperscaler marketplace distribution. Long-term viability hinges on automated correlation engine differentiation rather than dashboard visualization depth. Watch for inflection signals in federal agency NIST framework certification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies logs, metrics, and traces into single-pane observability for financial services SRE teams. |
| Strategic Partnership | Hyperscaler marketplace placement accelerates consumption-based pricing adoption among mid-market technology companies. |
| Acquisition of Specialist Firm | eBPF instrumentation expertise addresses kernel-level telemetry collection capability scarcity in enterprise IT organizations. |
| Geographic Expansion | Munich and Frankfurt financial services clusters front-load EU AI Act compliance investments ahead of enforcement. |
| Product Launch | Explainable decision logic interfaces satisfy algorithmic transparency mandates for automated anomaly detection systems. |
Study Parameters
A standing panel of site reliability engineering directors, IT procurement officers, platform engineers, and channel integration specialists provided ongoing calibration across the primary research phase. Secondary validation drew from hyperscaler capex disclosures, SEC filings, EU regulatory documentation databases, and telecommunications infrastructure deployment records. Bottom-up telemetry volume modeling and top-down enterprise spending surveys were triangulated against vendor-reported contract values.
Scenario-bracketing around OpenTelemetry adoption velocity and EU AI Act enforcement timelines framed the analytical approach across the projection horizon. Segmentation dimensions modeled include deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted replacement demand curves and greenfield cloud-native workload projections. Forecast inputs incorporated 5G standalone core deployment schedules and Industry 4.0 predictive maintenance system adoption curves.
Sensitivities concentrate around OpenTelemetry standardization pace, EU AI Act documentation obligation enforcement intensity, and site reliability engineering talent availability in enterprise IT organizations. Forecasts reflect assumptions regarding multi-cloud interoperability requirements and sovereign cloud procurement criteria. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Virtual Client Computing Market
Digital Solutions
Express Digitizer Market
Digital Solutions
Load Balancer Market
Digital Solutions
Global Hybrid Integration Platform Market
Digital Solutions
Stylus Pen for Education Market
Digital Solutions
Global Computer Aided Dispatch Market
Digital Solutions
In-App Purchase Market
Digital Solutions
Europe Electronic Contract Manufacturing and Design Services Market
Digital Solutions
Work From Home Setup Market
Digital Solutions
Transport Management System Market
Digital Solutions
Global Domain and Hosting Market
Digital Solutions
Global Mesh App and Service Architecture Market
Digital Solutions
Crop Management Software Market
Digital Solutions
Global Digital Business Card Market
Digital Solutions
EHS Software Market
Digital Solutions
Utility Bill Management System Market