
 Asia Pacific Automated Storage and Retrieval System Market | 2026-2036
Asia Pacific Automated Storage and Retrieval System Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Automated Storage and Retrieval System Market Outlook
Japan's Top Runner program for industrial energy efficiency is expanding compliance obligations for large-scale distribution centers, compelling operators to evaluate automated alternatives. Daifuku Co., Ltd. leverages its vertical integration into stacker crane manufacturing to sustain margin control across turnkey installations. Murata Machinery, Ltd. anchors its regional position through deep specialization in cleanroom-compatible mini-load systems for semiconductor and pharmaceutical clients.
An automated storage and retrieval system comprises computer-controlled machines that automatically deposit and retrieve loads from defined storage locations, typically operating on rail-guided stacker cranes with positioning accuracy within plus or minus one millimeter to maximize cubic space utilization. The primary industrial purpose centers on eliminating forklift traffic and human picking errors while compressing warehouse footprints by sixty to seventy percent versus conventional pallet racking. Unit-load systems dominate capital expenditure volumes due to their entrenched role in palletized manufacturing and distribution, while shuttle technology segments are attracting disproportionate engineering investment as multi-deep buffer configurations displace traditional crane-based throughput in high-velocity e-commerce operations. Vertical lift modules concentrate margin pools in pharmaceutical and electronics end users where cleanroom certification and lot-level traceability justify premium pricing.
China's SAMR enforces GB standards for automated equipment safety interlocks and electromagnetic compatibility, while South Korea's MFDS mandates validation protocols for pharmaceutical warehouse automation that directly shape system design requirements. Japan's METI coordinates with JIS standards committees to harmonize energy consumption metrics across material handling equipment categories, creating compliance-driven replacement cycles. Stakeholders must monitor divergence between Chinese GB standards and emerging ASEAN technical regulations as regional supply chain reconfiguration accelerates cross-border equipment procurement decisions.
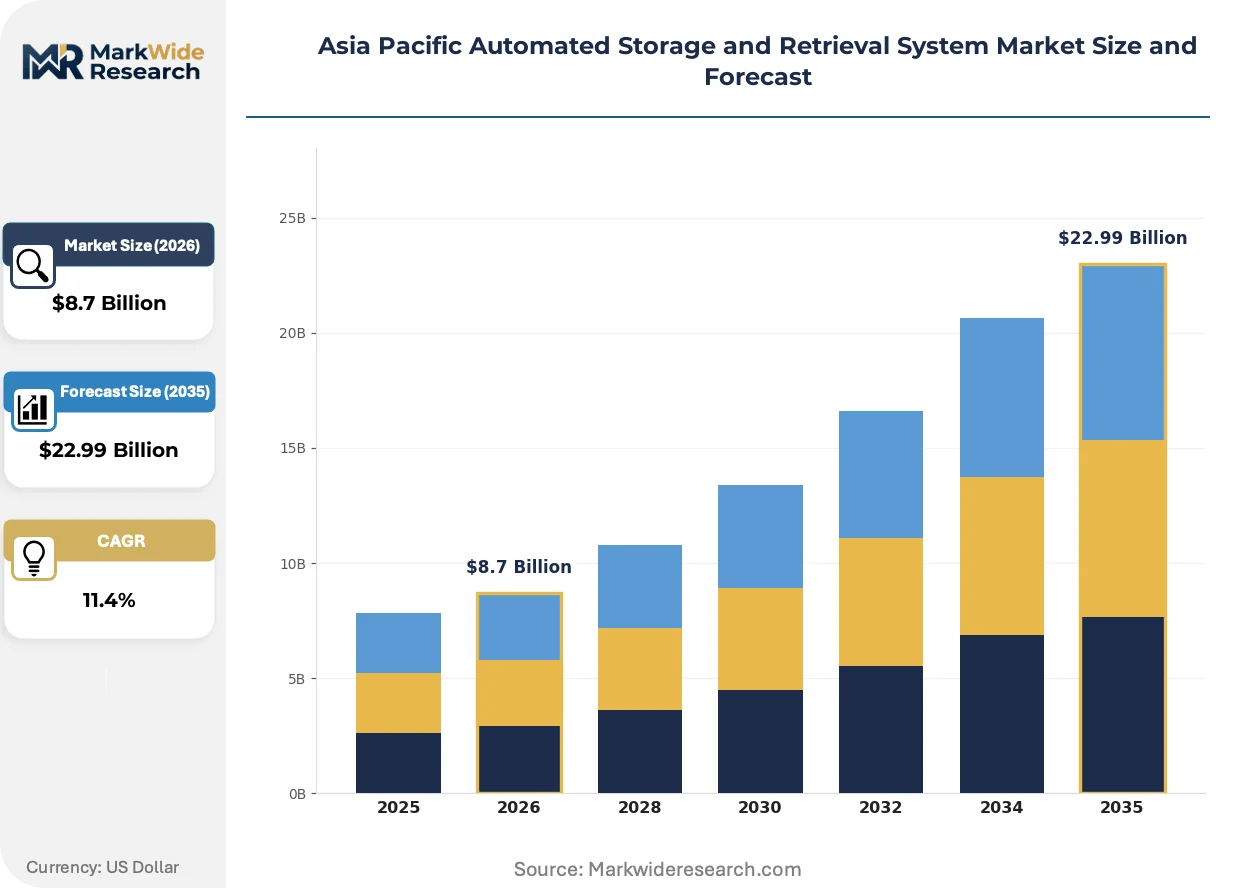
Market Dynamics
Japan's METI energy-efficiency mandates for logistics facilities are compelling warehouse operators across the Asia Pacific to replace conventional racking with automated alternatives, compressing replacement cycles and reshaping capital allocation priorities.
Growth Catalysts
- E-commerce fulfillment velocity:Southeast Asian online retail platforms are accelerating deployment of shuttle-based systems to manage same-day delivery SLIs.
- China's dual carbon goals:The country's MEE carbon intensity targets for industrial facilities are forcing manufacturing clusters toward electrified material handling.
- GB standards enforcement:SAMR-mandated safety interlocks and electromagnetic compatibility rules are standardizing procurement specifications across Chinese contract electronics manufacturers.
Market Restraints
- Steel input cost volatility:Fluctuations in high-grade structural steel prices directly impact stacker crane fabrication economics and project quoting stability.
- Korean system integrator concentration:Regional project execution depends heavily on a narrow base of Seoul-based automation engineering firms.
- Cleanroom certification timelines:MFDS validation protocols for pharmaceutical warehouse automation extend deployment schedules by eight to fourteen months.
Strategic Opportunities
- Vietnam manufacturing corridor penetration:Electronics contract manufacturers in Bac Ninh and Hai Phong industrial zones remain undersupplied with unit-load AS/RS infrastructure.
- 5G-enabled predictive maintenance convergence:Integration of private cellular networks with crane-mounted vibration sensors is opening remote service revenue streams.
- India's PLI scheme for logistics:Production-linked incentives for automated warehousing equipment are attracting component localization investments.
Industry Challenges
- Mechatronics talent scarcity:Shortages of technicians certified in rail-guided crane alignment and PLC programming are constraining installation capacity.
- Legacy WMS integration friction:Retrofitting AS/RS controls into existing warehouse management architectures requires costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Automated Storage and Retrieval System Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unit-Load, Mini-Load, Vertical Lift Module, AS/RS for Parts Technology: Automated Guided Vehicles, Robotics, Shuttle Systems, Conveyor Systems End User: Retail, Warehousing, Manufacturing, Pharmaceuticals Installation: New, Retrofit, Temporary, Permanent |
| Companies Covered | Daifuku Co., Ltd., Murata Machinery, Ltd., Toyota Industries Corporation, SSI Schaefer, Hanwha Group, Kardex Holding AG, KNAPP AG, Siasun Robot & Automation Co., Ltd., Addverb Technologies Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Automated Storage and Retrieval System Market Strategic Shifts
Shuttle-based buffer systems are actively displacing traditional crane-based throughput models in high-velocity operations, while regulatory pressure on energy consumption is accelerating hardware refresh cycles across established manufacturing corridors.
Multi-deep shuttle technology is expanding into electronics contract manufacturing facilities across China's Yangtze River Delta. Foxconn and Luxshare Precision are deploying these systems to compress floor space requirements by sixty percent while maintaining lot-level traceability. The technology is expanding into semiconductor backend operations where cleanroom compatibility and positioning accuracy within one millimeter justify capital intensity.
Japan's METI Top Runner program for industrial energy efficiency is expanding compliance obligations for large-scale distribution centers. Warehouse operators must now meet escalating efficiency benchmarks or face operational restrictions. Cold chain logistics facilities in Osaka and Nagoya industrial zones are responding by accelerating crane replacement schedules ahead of regulatory deadlines.
Electronics manufacturers are consolidating automation procurement under single-source turnkey contracts rather than fragmented equipment-vendor relationships. This consolidation is displacing traditional multi-vendor integration models. The shift is most visible in South Korea's Gyeonggi-do semiconductor cluster, where Samsung and SK Hynix suppliers now demand unified responsibility for crane, shuttle, and control system performance.
Asia Pacific Automated Storage and Retrieval System Market Segmentation
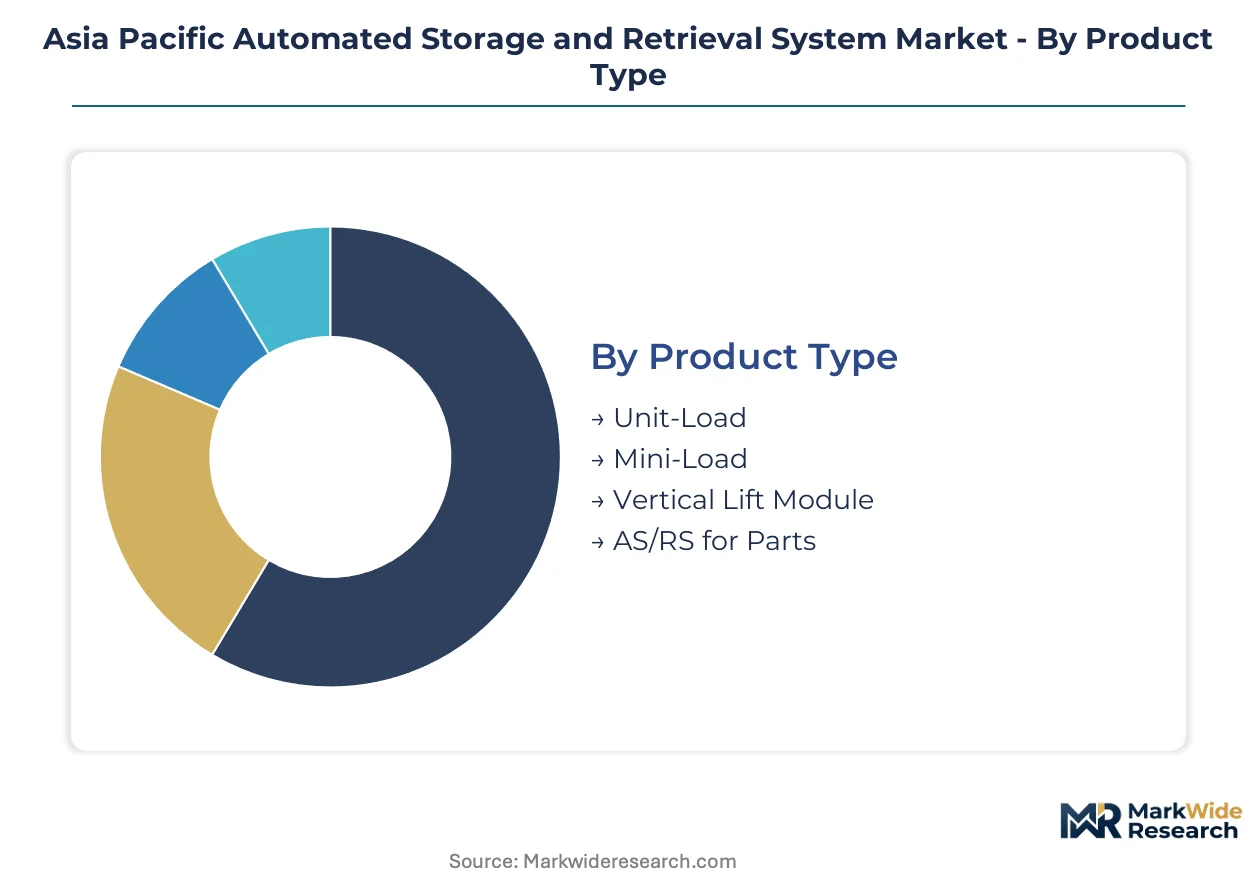
AS/RS procurement patterns diverge sharply across product scale, automation modality, and facility lifecycle stage. Understanding these fault lines clarifies where capital concentrates and which specifications command premium positioning.
Product Type:
Physical load characteristics and cubic density requirements define the technical specification axis across installations.
- Unit-Load:Rail-guided stacker cranes handle single or double-deep pallet configurations with positioning accuracy within one millimeter. Demand concentrates in China's Yangtze River Delta manufacturing corridor, where contract electronics manufacturers retrofit existing facilities to compress floor space and labor costs under MEE carbon intensity enforcement.
- Mini-Load:Crane-based systems manage totes and cartons in high-density configurations optimized for piece-pick operations. Japan's semiconductor and pharmaceutical clusters in Osaka and Nagoya drive specification requirements for cleanroom compatibility and lot-level traceability.
- Vertical Lift Module:Enclosed column systems with automated extractors deliver SKUs to ergonomic pickup windows. Pharmaceutical distributors in South Korea's Gyeonggi-do cluster specify these for MFDS-mandated validation protocols.
- AS/RS for Parts:Compact systems targeting small-component storage with sub-second retrieval cycles. Electronics subcontractors in Vietnam's Bac Ninh industrial zone deploy these for surface-mount device kitting operations.
Mature deployment sits with Unit-Load systems in heavy manufacturing. Newer deployment is concentrated in Mini-Load configurations for e-commerce fulfillment velocity.
Technology:
Automation modality selection hinges on throughput velocity, SKU proliferation, and facility footprint constraints.
- Shuttle Systems:Battery-powered carriers traverse multi-deep racking lanes independent of crane rails, enabling parallel access to all storage positions. Southeast Asian online retail platforms in Jakarta and Bangkok accelerate deployment to manage same-day delivery SLIs against warehouse labor scarcity.
- Robotics:Articulated arms and gantry systems handle irregular loads and mixed-case palletizing. India's PLI scheme for logistics automation is attracting component localization investments for robotic integration modules.
- Automated Guided Vehicles:Laser- or vision-guided mobile platforms transport pallets between storage and shipping without fixed infrastructure. Japanese cold chain operators in Nagoya evaluate these for METI Top Runner compliance flexibility.
- Conveyor Systems:Fixed-path belt and roller networks link receiving, storage, and dispatch zones. China's SAMR GB standards for electromagnetic compatibility shape procurement specifications for electronics manufacturers.
Established throughput relies on Conveyor Systems in traditional distribution. Emerging deployment favors Shuttle Systems for buffer flexibility in high-velocity operations.
End User:
Operational requirements and regulatory exposure create distinct specification tiers across verticals.
- Manufacturing:Unit-load and mini-load systems integrate with production lines for just-in-sequence material delivery. China's dual carbon goals are forcing industrial clusters toward electrified material handling with energy recovery on crane descent.
- Warehousing:High-bay configurations maximize cubic utilization for third-party logistics operators. South Korean system integrator concentration in Seoul constrains project execution capacity for regional expansion.
- Retail:Shuttle-based buffer systems enable rapid order consolidation for omnichannel fulfillment. Vietnam's electronics manufacturing corridor in Hai Phong remains undersupplied with automated infrastructure.
- Pharmaceuticals:Cleanroom-certified systems with batch tracking and environmental monitoring. MFDS validation protocols extend deployment schedules by eight to fourteen months, compressing ROI timelines.
Regulatory intensity peaks with Pharmaceuticals. Volume scaling concentrates in Manufacturing and Warehousing verticals.
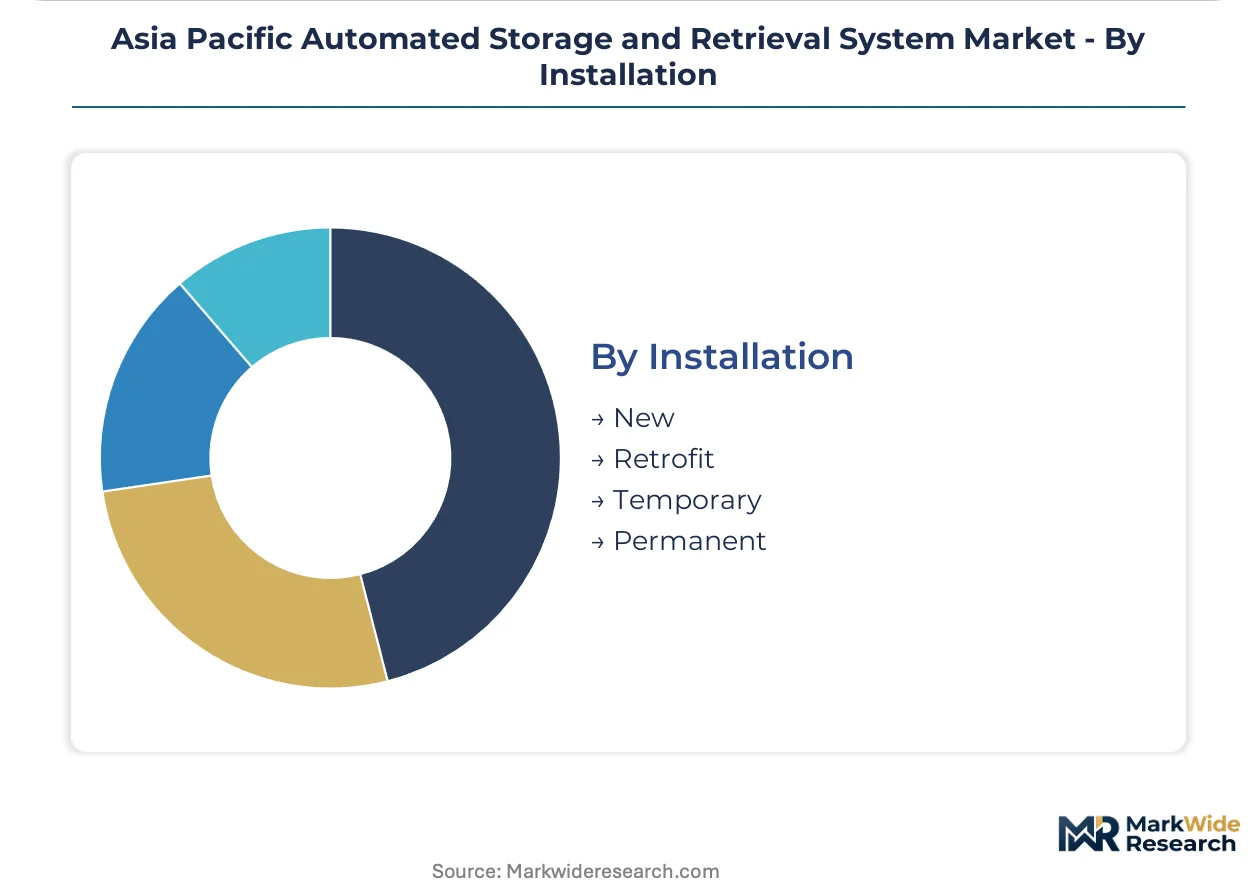
Installation:
Facility lifecycle stage determines integration complexity and capital recovery horizons.
- Retrofit:AS/RS integration into existing warehouse management architectures requires costly middleware development. Legacy WMS integration friction constrains installation capacity across the region.
- New:Greenfield installations allow unified control architecture design from foundation. Electronics manufacturers consolidate procurement under single-source turnkey contracts rather than fragmented equipment-vendor relationships.
- Permanent:Fixed infrastructure with twenty-year depreciation schedules anchors capital commitment. Steel input cost volatility directly impacts stacker crane fabrication economics and project quoting stability.
- Temporary:Modular configurations for seasonal demand peaks or facility transition periods. Limited adoption outside contract logistics providers serving consumer electronics launch cycles.
Capital allocation favors Permanent installations in core manufacturing assets. Flexibility demands drive Temporary configurations in seasonal retail fulfillment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta manufacturing corridor anchors regional demand as contract electronics manufacturers retrofit existing facilities with unit-load AS/RS to compress floor space and labor costs under tightening environmental enforcement.
China
Contract electronics manufacturers in Suzhou and Kunshan drive unit-load system procurement to meet MEE carbon intensity targets for industrial facilities. SAMR enforces GB standards for safety interlocks and electromagnetic compatibility that standardize procurement specifications. The Yangtze River Delta corridor concentrates retrofit activity as manufacturers seek sixty to seventy percent footprint compression versus conventional pallet racking.
Japan
Cold chain logistics operators in Osaka and Nagoya accelerate crane replacement schedules ahead of regulatory deadlines. METI's Top Runner program expands compliance obligations for large-scale distribution centers with escalating efficiency benchmarks. Kansai industrial zones respond with automated alternatives that eliminate forklift traffic and human picking errors.
South Korea
Semiconductor and pharmaceutical clusters in Gyeonggi-do specify cleanroom-compatible mini-load systems with lot-level traceability. MFDS validation protocols for pharmaceutical warehouse automation extend deployment schedules by eight to fourteen months. Seoul-based system integrators concentrate regional project execution capacity, constraining expansion timelines.
Vietnam
Electronics contract manufacturers in Bac Ninh and Hai Phong industrial zones remain undersupplied with automated infrastructure. The country's national industrial development frameworks prioritize manufacturing corridor expansion. Surface-mount device kitting operations in northern provinces deploy compact AS/RS for sub-second retrieval cycles.
India
Production-linked incentives for automated warehousing equipment attract component localization investments. Third-party logistics operators evaluate shuttle-based buffer systems for omnichannel fulfillment velocity. Maharashtra and Karnataka industrial zones emerge as early deployment centers for electrified material handling infrastructure.
Asia Pacific Automated Storage and Retrieval System Market Competitive Environment
Premium-margin players sit above commodity-margin players across technology specialization and cleanroom certification tiers. The vendor base organizes around three strategic archetypes: vertically integrated Japanese fabricators with captive crane production, European system integrators with modular shuttle platforms, and emerging Asian specialists targeting cost-sensitive retrofit segments. Consolidation pressures favor turnkey contracting over fragmented multi-vendor relationships. Geographic expansion and single-source performance guarantees represent the dominant competitive moves reshaping procurement patterns.
Within the integrated fabrication tier, Daifuku Co., Ltd. and Murata Machinery, Ltd. exemplify Japanese specialists leveraging domestic supply chain control. Daifuku anchors premium positioning through in-house stacker crane manufacturing, while Murata occupies a cleanroom-focused niche serving semiconductor and pharmaceutical validation requirements. Among diversified industrial conglomerates, Toyota Industries Corporation represents scale-driven manufacturing depth with cross-sector automation portfolio breadth.
| Leading Market Players |
|---|
| Daifuku Co., Ltd. |
| Murata Machinery, Ltd. |
| Toyota Industries Corporation |
| SSI Schaefer |
| Hanwha Group |
| Kardex Holding AG |
| KNAPP AG |
| Siasun Robot & Automation Co., Ltd. |
| Addverb Technologies Limited |
| Others |
Value Chain & Pricing Dynamics
High-grade structural steel price indices cascade through Asia Pacific AS/RS supply chains, compressing margins for crane fabricators in Japan and South Korea while forcing procurement managers toward modular shuttle configurations that reduce steel intensity per storage position.
Pricing Analysis
Throughput-guarantee contracts anchor value-based pricing for turnkey installations, with premium tiers commanding positioning accuracy within one millimeter and cleanroom certification. Price differentiation hinges on METI energy-efficiency compliance tier and after-sales remote monitoring bundling. Cost compression in standard unit-load configurations is intensifying because Chinese contract electronics manufacturers consolidate procurement under single-source contracts. Third-party logistics operators in Southeast Asia exhibit highest price sensitivity, while semiconductor fabs in Gyeonggi-do accept premium positioning for lot-level traceability.
Supply Chain Analysis
Dual-sourcing mandates from Samsung and SK Hynix suppliers require crane motor and controller qualification across at least two Japanese or German vendors, fragmenting procurement leverage. Manufacturing concentrates in Japan, South Korea, and China, with high-tensile steel beams and precision rail systems drawing from specialized mills in Osaka and Pohang. Single-source vulnerability sits with Seoul-based system integrators controlling regional project execution. Distribution runs through turnkey contracting channels that displace fragmented multi-vendor integration models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific AS/RS competitive dynamics favor consolidation as METI efficiency mandates and single-source procurement trends squeeze margin capacity from fragmented equipment vendors.
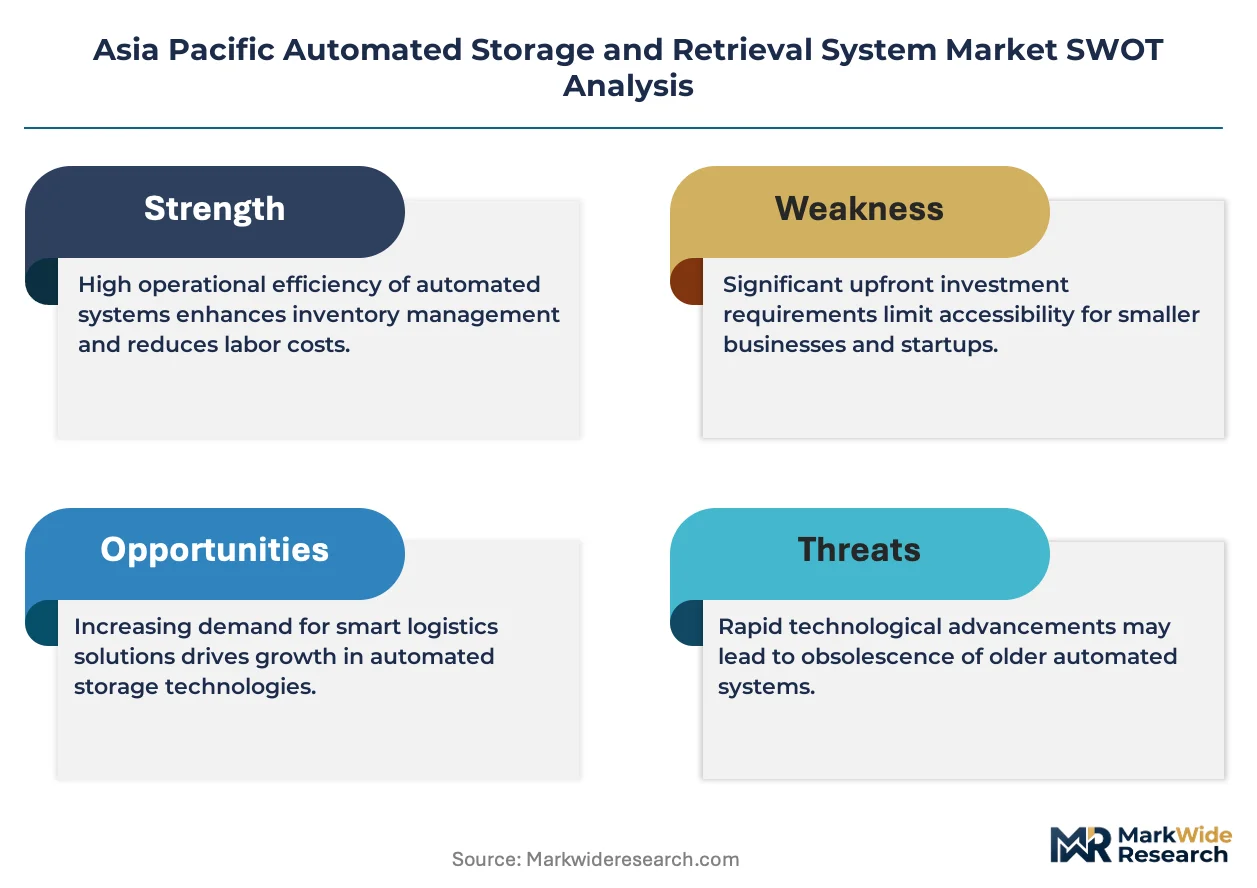
For Market Incumbents: Hedge against Korean system integrator concentration risk by qualifying alternative project execution partners in Taiwan or Singapore. Anchor backward integration into vibration sensor and 5G module supply to capture predictive maintenance revenue streams that emerging shuttle specialists cannot replicate. For New Entrants and Emerging Players: System integrators in Vietnam's Bac Ninh corridor offer channel access to electronics contract manufacturers deploying compact AS/RS for surface-mount device kitting. Target India's PLI scheme beneficiaries for component localization partnerships, positioning for aftermarket service contracts rather than capital equipment sales. For Investors and Strategic Acquirers: Distressed-cycle entries favor cleanroom-certified mini-load specialists in Japan's Kansai industrial zone facing working capital pressure from extended MFDS validation timelines. Watch for inflection when China's MEE accelerates carbon intensity enforcement across the Yangtze River Delta, triggering retrofit demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Turnkey Contracting Consolidation | Single-source performance guarantees displace fragmented multi-vendor relationships across Samsung and SK Hynix supplier networks. |
| Cleanroom Certification Investment | Murata Machinery and Daifuku deepen pharmaceutical and semiconductor validation capabilities to sustain premium positioning. |
| 5G-Enabled Predictive Maintenance | Private cellular integration with crane-mounted sensors opens recurring revenue streams for Japanese cold chain operators. |
| Vietnam Manufacturing Corridor Penetration | Bac Ninh and Hai Phong electronics clusters remain undersupplied with unit-load infrastructure for contract manufacturers. |
| India PLI Scheme Localization | Component manufacturing investments qualify for production-linked incentives while building aftermarket service density. |
Study Parameters
Multi-period observation of METI efficiency benchmark trajectories and MEE carbon intensity enforcement patterns anchored the trend analysis, supplemented by interviews with warehouse operations directors at third-party logistics providers, automation procurement leads at electronics contract manufacturers, and project managers at Seoul-based system integrators. Secondary validation drew from SAMR GB standards filings, JIS committee documentation, customs data on stacker crane imports, and SEC disclosures from listed material handling equipment vendors. Bottom-up installation tracking across China's Yangtze River Delta and top-down market sizing triangulated volume estimates.
Input-output matrices mapped crane fabrication capacity, shuttle technology adoption curves, and regulatory compliance cost structures across the projection horizon. Segmentation dimensions modeled include product type, automation modality, end-use vertical, and facility lifecycle stage. CAGRs derived from fitted growth curves incorporating steel price volatility, cleanroom certification timeline distributions, and 5G infrastructure deployment schedules in target industrial zones.
Caveats apply where MFDS validation protocol revisions or ASEAN technical regulation divergence could materially shift the outlook. Deviation in China's dual carbon goal enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Brazil Data Center Storage Market
Storage Solutions
Network File System Market
Storage Solutions
Scale-Out NAS Market
Storage Solutions
Virtual Machine Backup and Recovery Market
Storage Solutions
Cloud Storage Market
Storage Solutions
Enterprise File Sync and Share Platform Market
Storage Solutions
Hard Disk Market
Storage Solutions
Philippines Data Center Storage Market
Storage Solutions
United Arab Emirates Data Center Storage Market
Storage Solutions
Data Backup and Recovery Market
Storage Solutions
Disk Based Data Fabric Market
Storage Solutions
Vietnam Data Center Storage Market
Storage Solutions
Automated Storage and Retrieval System (AS & RS) Market
Storage Solutions
Thailand Data Center Storage Market
Storage Solutions
Sweden Data Center Storage Market
Storage Solutions
Global in Memory Data Grid Market