
 Hong Kong Data Center Storage Market | 2026-2036
Hong Kong Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Hong Kong Data Center Storage Market Insights
Data center engineering talent is rotating toward cloud-native and AI-optimized storage architectures, tightening labor supply for legacy infrastructure roles. Dell Inc. leverages its direct sales force and local service partnerships to dominate enterprise refresh cycles. Huawei Technologies Co. Ltd. anchors its position through integrated compute-storage-network bundles tailored to mainland Chinese enterprises operating in Hong Kong. IBM sustains relevance with mainframe-attached storage for financial institutions maintaining hybrid estates.
Hong Kong Data Center Storage encompasses disk arrays, solid-state systems, and software-defined platforms engineered to retain, protect, and serve structured and unstructured data within geographically contained facilities. Systems typically operate at latency thresholds below five milliseconds for transactional workloads while scaling to petabyte-class capacity for archival and analytics repositories. Storage Area Network deployments lead in finance and telecommunications due to deterministic performance requirements, while Object Storage expands fastest among video streaming and AI training data lakes. Flash Storage and SSD technology segments command premium pricing where sub-millisecond response governs customer-facing applications, whereas Hybrid Storage configurations capture mid-tier margin pools from enterprises balancing cost against performance.
The Office of the Privacy Commissioner for Personal Data enforces the Personal Data (Privacy) Ordinance, mandating explicit consent frameworks and cross-border transfer safeguards that elevate encrypted and access-controlled storage specifications. BSI Hong Kong promotes ISO 27001 certification as a procurement threshold, filtering vendors without audited information security management systems. Stakeholders must weigh colocation expansion against on-premise retention as regulatory scrutiny of data sovereignty intensifies and energy costs reshape total cost of ownership calculations.
Market Dynamics
The Hong Kong Data Center Storage market faces acute pressure from the Personal Data (Privacy) Ordinance amendments, which mandate stricter data residency and encryption standards while financial institutions simultaneously expand petabyte-scale transactional storage estates.
Growth Catalysts
- Financial Services Data Expansion:Banks and securities firms in Central and Admiralty districts are scaling storage arrays to capture real-time trading telemetry and compliance audit trails. Transaction volumes from cross-border wealth management products are forcing capacity upgrades at existing facilities.
- Amendments to the Personal Data (Privacy) Ordinance:The Office of the Privacy Commissioner for Personal Data now requires explicit consent frameworks and cross-border transfer safeguards. This regulatory tightening elevates demand for encrypted, access-controlled storage systems with localized data sovereignty features.
- Tseung Kwan O Cluster Concentration:Hyperscale operators are consolidating in this industrial estate, creating network effects that attract secondary data center developments and specialized storage engineering talent pools.
Market Restraints
- Land Scarcity and Premium Real Estate Costs:Hong Kong's constrained geography limits greenfield data center development, forcing operators into expensive brownfield retrofits or offshore secondary sites with higher latency penalties.
- Electricity Tariff Volatility:Storage infrastructure power consumption faces upward pressure from CLP Power and HK Electric tariff adjustments, compressing operating margins for high-density flash deployments.
- Mainland Chinese Equipment Dependencies:Integrated compute-storage-network bundles from Shenzhen and Dongguan suppliers create supply concentration risk during cross-border logistics disruptions or technology export control escalations.
Strategic Opportunities
- AI Training Data Lake Expansion:Generative AI workloads are creating demand for object storage architectures optimized for unstructured training corpora, with financial services and media sectors piloting petabyte-scale repositories.
- ISO 27001 Certification Differentiation:BSI Hong Kong's promotion of audited information security management systems as procurement thresholds creates white space for vendors with established certification pathways.
- Hybrid Cloud Storage Orchestration:Convergence of on-premise arrays with public cloud tiering is enabling new service models for mid-market enterprises seeking to balance residency compliance against elasticity requirements.
Industry Challenges
- Cloud-Native Storage Engineering Shortage:Legacy SAN administrators face skill obsolescence as Kubernetes-based container storage interfaces and software-defined platforms displace traditional Fibre Channel expertise. Training pipelines at Hong Kong universities and vocational institutes lag demand curves.
- Retrofit Capex Burden:Existing facilities require cooling system upgrades and power density modifications to accommodate all-flash arrays and GPU-attached storage, straining balance sheets already pressured by land lease renewals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hong Kong Data Center Storage Market |
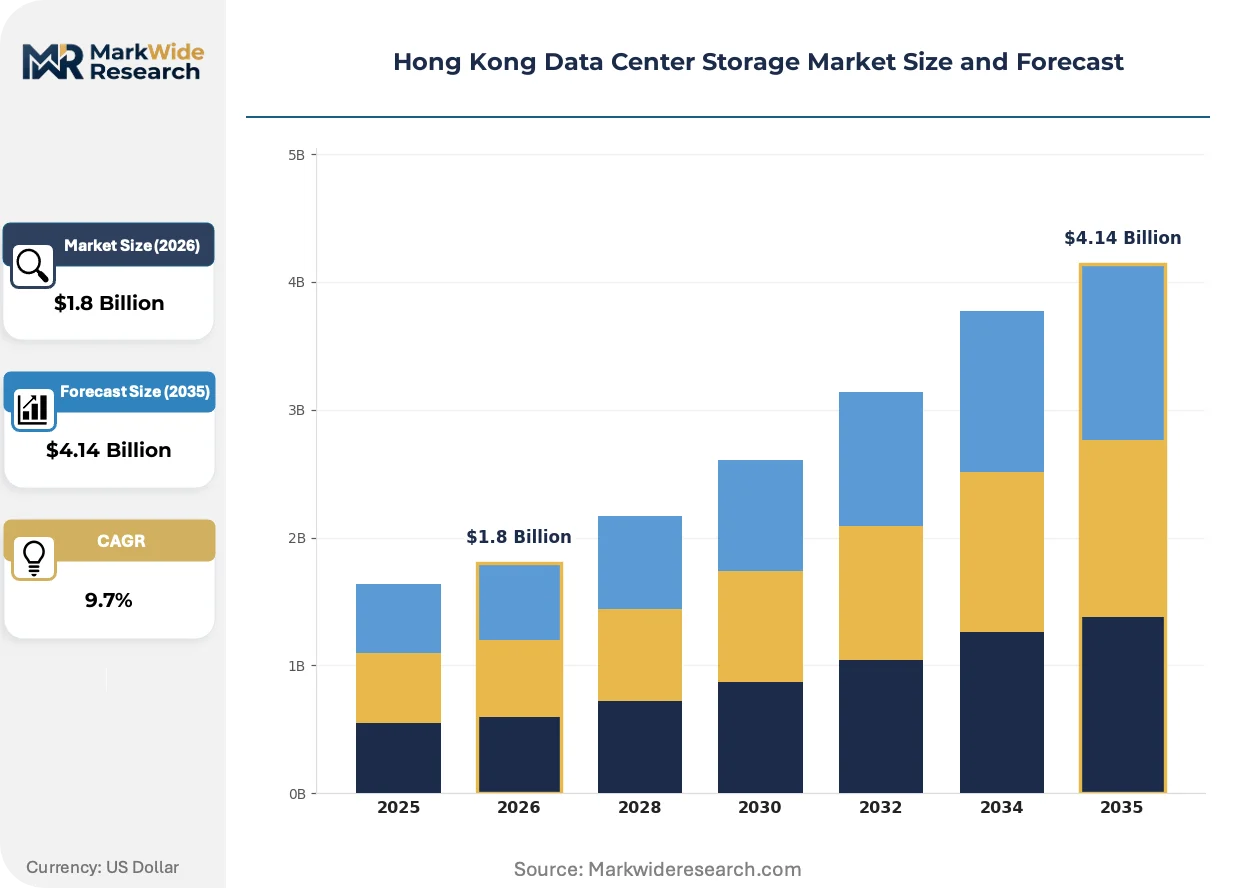
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Attached Storage, Network Attached Storage, Storage Area Network, Object Storage Technology: Flash Storage, HDD, Hybrid Storage, SSD End User: Telecommunications, Healthcare, Finance, E-commerce Deployment: On-Premise, Cloud-Based, Hybrid, Colocation |
| Companies Covered | Dell Inc., Hewlett Packard Enterprise, NetApp Inc., Huawei Technologies Co. Ltd., Hitachi Vantara LLC, IBM, Fujitsu, Arista Networks, Atos, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hong Kong Data Center Storage Market Trends and Innovations
Storage architecture in Hong Kong is splitting along performance-residency axes as regulatory mandates collide with AI workload demands, forcing vendors to engineer dual-purpose platforms rather than unified solutions.
Software-defined storage is bifurcating the Hong Kong market between latency-sensitive transactional systems and throughput-optimized analytics repositories. Financial institutions in Admiralty and Central are deploying NVMe-oF fabrics for sub-millisecond trading applications, while media and AI training operators in Tseung Kwan O favor object storage with erasure coding for cost-efficient petabyte scaling. This architectural divergence is compressing mid-tier hybrid array margins as buyers polarize toward specialized endpoints.
The Office of the Privacy Commissioner for Personal Data is tightening cross-border data transfer assessments under amended Ordinance provisions. Storage vendors must now embed encryption-at-rest and access logging as default configurations rather than premium options. Financial services and healthcare verticals are responding by demanding hardware security modules and key management services bundled with primary storage contracts.
Consumption-based financing is displacing capital purchase models for enterprise storage refreshes. Colocation providers in Kwai Chung and Tsuen Wan are offering storage-as-a-service tiers that transfer depreciation risk from CIO balance sheets to operator portfolios. This shift is most visible among mid-market professional services firms seeking to preserve credit capacity for core business investments while meeting tightening data residency requirements.
Hong Kong Data Center Storage Market Segmentation
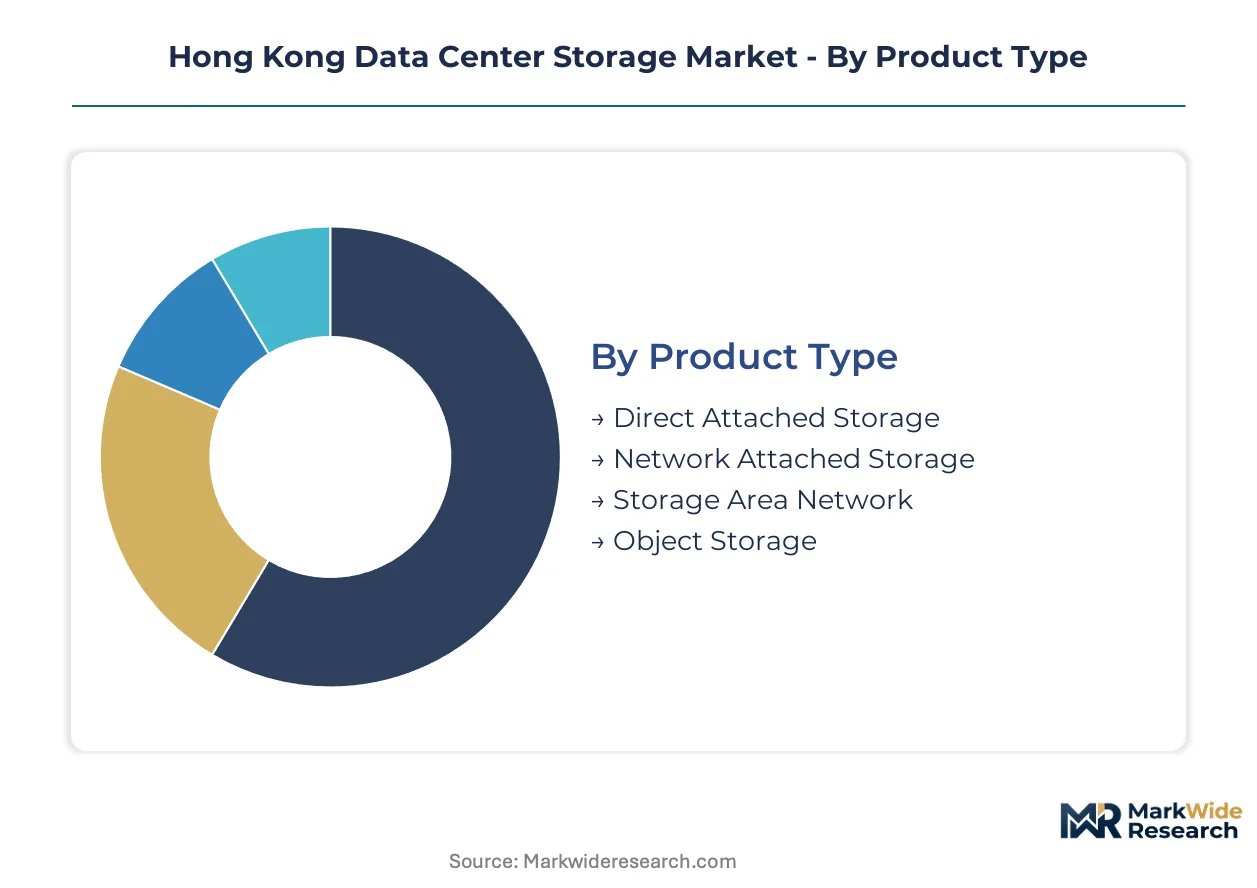
Storage procurement patterns in Hong Kong diverge sharply across product architectures and deployment models. Regulatory mandates from the Personal Data (Privacy) Ordinance and workload-specific latency requirements create distinct demand pockets that resist one-size-fits-all solutions.
Product Type:
Direct Attached Storage and Network Attached Storage dominate domestic enterprise deployments, while Storage Area Network and Object Storage installations cluster in Tseung Kwan O hyperscale facilities serving regional cloud operators.
- Storage Area Network:Fibre Channel and NVMe-oF fabrics deliver deterministic sub-millisecond latency for transactional workloads. Financial institutions in Central and Admiralty districts mandate SAN architectures for trading systems and real-time risk analytics, with procurement specifications hardened by the Office of the Privacy Commissioner for Personal Data encryption requirements.
- Object Storage:Erasure-coded distributed architectures scale to petabyte capacity for unstructured data lakes. Tseung Kwan O hyperscale operators deploy object storage for AI training corpora and video streaming archives, capitalizing on lower per-gigabyte economics despite higher access latency.
- Direct Attached Storage:Internal server storage serves legacy applications and edge computing nodes where network overhead is unacceptable. Small professional services firms in Wan Chai and Causeway Bay retain DAS for compliance archives with minimal retrieval frequency.
- Network Attached Storage:File-level protocols support collaborative workflows in mid-market enterprises. Healthcare providers in Kowloon deploy NAS for medical imaging PACS systems requiring shared access across radiology departments.
Storage Area Network commands the established base. The steepest expansion runs through Object Storage.
Technology:
Cost tiers separate all-flash deployments from hybrid configurations, with HDD retaining relevance only in cold archive applications where access latency tolerance exceeds 50 milliseconds.
- Flash Storage:NAND-based arrays with NVMe interfaces deliver sub-100 microsecond response times. Premium pricing restricts flash deployments to customer-facing transaction systems at securities firms and high-frequency trading operations in the International Finance Centre.
- SSD:Solid-state drives bridge performance and cost considerations for tiered storage implementations. E-commerce platforms in Kwun Tong utilize SSD caching layers to accelerate database queries during promotional flash sales without full array replacement.
- Hybrid Storage:Automated tiering algorithms migrate hot data to flash and cold data to spinning media. Mid-market legal and accounting firms in Quarry Bay adopt hybrid arrays to balance performance against constrained IT budgets.
- HDD:Mechanical drives persist in high-capacity, low-access archival repositories. Telecommunications operators utilize HDD for call detail record retention meeting statutory periods with minimal retrieval probability.
Flash Storage captures premium-margin transactions. Hybrid Storage gains share fastest among budget-constrained verticals.
End User:
Finance and telecommunications drive capacity expansion, while healthcare and e-commerce present contrasting procurement patterns shaped by regulatory exposure and seasonality.
- Finance:Banks, securities firms, and insurers generate petabyte-scale transactional and analytical storage demand. Cross-border wealth management growth and real-time compliance reporting requirements from the Securities and Futures Commission force continuous capacity upgrades.
- Telecommunications:Mobile network operators and fixed-line carriers store subscriber data, network telemetry, and content delivery caches. 5G rollout intensifies edge storage requirements across Hong Kong Island and New Territories base stations.
- Healthcare:Public hospitals and private clinics archive diagnostic imaging and electronic health records. Clustered Epic and Cerner deployments at Hospital Authority facilities strain existing SAN infrastructure.
- E-commerce:Online retailers and marketplace operators manage product catalogs, transaction logs, and customer behavioral data. Seasonal demand spikes around Singles' Day and Lunar New Year drive cloud burst requirements.
Finance commands the established base. E-commerce climbs the fastest as direct-to-consumer platforms expand fulfillment infrastructure.
Deployment:
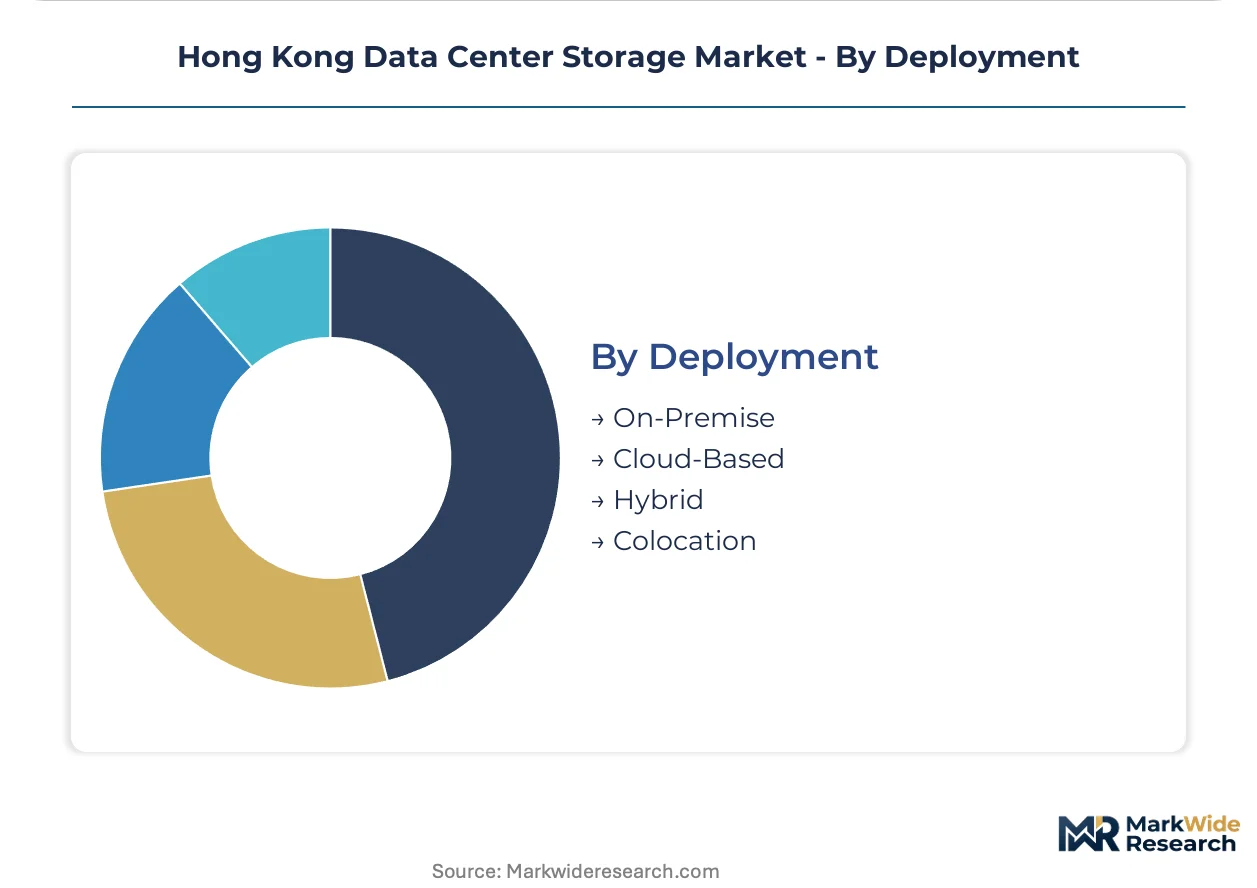
On-premise retention persists in regulated verticals, while cloud-based and hybrid models gain traction among digitally native enterprises seeking elasticity.
- On-Premise:Captive data centers and server rooms maintain physical control over sensitive assets. Banks with mainland Chinese parent institutions retain on-premise storage to satisfy dual jurisdiction data sovereignty requirements.
- Hybrid:Tiered architectures combine local performance tiers with cloud archival. Professional services firms balance resident compliance data against elastic compute bursts for month-end analytics.
- Colocation:Leased rack space and cage deployments transfer facility management to specialized operators. Tseung Kwan O and Kwai Chung facilities attract enterprises seeking certified Tier III infrastructure without capital construction.
- Cloud-Based:Fully managed storage services eliminate hardware ownership. Startups and fintech challengers in Cyberport and Science Park bypass on-premise investment entirely.
On-Premise retains the established base. Hybrid deployment expands most quickly as enterprises navigate residency compliance against capital efficiency pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Office of the Privacy Commissioner for Personal Data anchors Hong Kong's regulatory framework, mandating encrypted storage and cross-border transfer safeguards that reshape procurement across the territory. Storage demand concentrates in financial districts and industrial estates where hyperscale facilities cluster.
Hong Kong Island
Central and Admiralty districts host securities firms and international banks generating petabyte-scale transactional storage demand. The Securities and Futures Commission enforces real-time compliance reporting that forces continuous SAN infrastructure upgrades. The International Finance Centre anchors high-frequency trading operations requiring sub-millisecond NVMe-oF fabrics.
Kowloon
Kwun Tong industrial zone houses e-commerce platforms and cloud service operators managing seasonal demand spikes. The Hospital Authority operates clustered Epic and Cerner deployments at public hospital facilities that strain existing storage infrastructure. Colocation providers in Kwai Chung offer Tier III certified facilities to enterprises avoiding capital construction.
New Territories
Tseung Kwan O Industrial Estate concentrates hyperscale operators creating network effects for secondary data center developments. The territory's land scarcity forces expensive brownfield retrofits rather than greenfield construction. AI training operators deploy erasure-coded object storage for petabyte-scale unstructured data lakes.
Greater Bay Area Connectivity
Cross-border wealth management growth from mainland Chinese parent institutions drives dual-jurisdiction data sovereignty requirements. Shenzhen and Dongguan suppliers provide integrated compute-storage-network bundles with logistics concentration risk. Financial institutions maintain on-premise retention to satisfy both Hong Kong and mainland Chinese regulatory mandates.
Lantau and Outlying Areas
Cyberport and Hong Kong Science Park host startups and fintech challengers bypassing on-premise investment through cloud-based storage services. The Airport Authority's logistics hub generates edge computing storage requirements for real-time cargo tracking. Limited land availability constrains expansion despite lower real estate costs versus core districts.
Hong Kong Data Center Storage Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure in Hong Kong's data center storage market. Dell Inc. and Huawei Technologies Co. Ltd. anchor the integrated tier with bundled infrastructure offerings, while NetApp Inc. and Hitachi Vantara LLC occupy specialist positions in software-defined and high-performance segments. Strategic moves concentrate on certification differentiation through ISO 27001 pathways and hybrid cloud orchestration partnerships that address residency compliance requirements.
Within the integrated infrastructure tier, Dell Inc. and Huawei Technologies Co. Ltd. exemplify contrasting geographic anchoring strategies for Hong Kong's bifurcated customer base. Dell leverages direct sales force and local service partnerships to capture enterprise refresh cycles, while Huawei anchors through integrated bundles tailored to mainland Chinese enterprises operating in the territory. IBM occupies a distinct position serving financial institutions maintaining hybrid mainframe estates. Specialists including NetApp Inc. and Hitachi Vantara LLC represent the software-defined and high-performance storage archetypes respectively.
| Leading Market Players |
|---|
| Dell Inc. |
| Hewlett Packard Enterprise |
| NetApp Inc. |
| Huawei Technologies Co. Ltd. |
| Hitachi Vantara LLC |
| IBM |
| Fujitsu |
| Arista Networks |
| Atos |
| Others |
Pricing and Supply Chain Analysis
Hyperscale facility concentration in Tseung Kwan O creates procurement scale advantages that compress unit costs for flash storage while elevating price floors for customized enterprise deployments. This geographic clustering shapes both supply allocation and buyer negotiation leverage across Hong Kong's bifurcated storage market.
Pricing Analysis
Price spreads between Central district financial institutions and Kwai Chung colocation operators reflect divergent service bundling rather than hardware differentiation alone. Three-tier pricing structure across premium, standard, and economy levels governs enterprise procurement, with ISO 27001 certification tier and after-sales service intensity as primary price differentiation drivers. Cost compression in mid-tier hybrid arrays is intensifying because object storage alternatives erode marginal utility. Fintech challengers in Cyberport exhibit highest price sensitivity, while securities firms at International Finance Centre prioritize latency guarantees over unit economics.
Supply Chain Analysis
Inventory cycles for NVMe controllers and NAND flash memory currently stretch lead times for all-flash array deliveries to financial sector buyers. Component sourcing draws from Taiwan, South Korea, and Japan, with specialized ASICs and enterprise-grade NAND wafers as critical inputs. Single-source vulnerability concentrates in advanced controller silicon from TSMC-fabricated designs. Distribution runs through direct vendor sales forces for hyperscale contracts and systems integrators for mid-market enterprise deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hong Kong's data center storage market sits in early-cycle expansion as AI training workloads penetrate financial services and media verticals, creating fresh capacity demand alongside regulatory-mandated encryption upgrades. This dual tailwind supports sustained infrastructure investment across the territory.
For Market Incumbents: Consolidate service partnerships with CLP Power and HK Electric to lock in preferential electricity tariffs for high-density flash deployments. Deepen ISO 27001 certification pathways to filter out specialist competitors lacking audited information security management systems. Capacity addition in Tseung Kwan O Industrial Estate anchors scale economies against mainland Chinese equipment suppliers threatening margin compression.
For New Entrants and Emerging Players: Kubernetes-native container storage interfaces represent a service-layer gap where legacy SAN administrators face skill obsolescence and incumbents under-serve. Target mid-market professional services firms in Wan Chai and Causeway Bay with consumption-based storage-as-a-service offerings that transfer depreciation risk from CIO balance sheets. Go-to-market execution should leverage channel partnerships with Hong Kong Science Park incubators to bypass direct competition with Dell and Huawei field sales organizations.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among colocation providers offering tiered storage-as-a-service with embedded data residency compliance. Long-term viability across the next decade hinges on positioning for hybrid cloud orchestration convergence rather than pure hardware supply. Acquisition target archetype: software-defined storage specialists with established Kubernetes CSI integrations and existing BSI Hong Kong certification relationships. Signal to watch: cross-border wealth management product volume growth forcing dual-jurisdiction data sovereignty investments at mainland Chinese parent banks.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Converges on-premise SAN with public cloud tiering for residency-compliant elasticity at professional services firms. |
| Strategic Partnership | Aligns storage vendors with CLP Power for preferential tariff structures on high-density flash deployments. |
| Acquisition of Specialist Firm | Absorbs Kubernetes-native storage software talent scarce in Hong Kong's legacy Fibre Channel administrator pool. |
| Geographic Expansion | Establishes secondary presence in Kwai Chung colocation facilities to capture mid-market enterprise demand. |
| Green Certification Program | Positions all-flash arrays for carbon-conscious procurement thresholds as HK Electric tariff adjustments bite. |
Research Methodology
Initial hypotheses were tested against primary input from data center engineering directors, storage procurement officers at financial institutions, colocation facility operators, and cloud solution architects, then refined through secondary validation. Primary fieldwork encompassed structured interviews with CIOs at securities firms in Central, infrastructure planners at Hospital Authority facilities, and technical leads at Tseung Kwan O hyperscale operators. Secondary sources included Securities and Futures Commission compliance filings, CLP Power tariff adjustment notices, BSI Hong Kong certification registries, and Office of the Privacy Commissioner enforcement bulletins. Bottom-up capacity installation tracking and top-down expenditure modeling were triangulated against vendor shipment disclosures.
Variance decomposition across product architecture, deployment model, and end-user vertical shaped the analytical framework over the projection horizon. Segmentation dimensions encompassed storage system type, technology tier, customer industry, and facility location cluster. CAGRs were derived from installed base evolution and replacement cycle analysis rather than extrapolation of point estimates. Forecast inputs incorporated electricity tariff trajectory assumptions and Personal Data (Privacy) Ordinance amendment implementation pacing.
Underlying assumptions cover stable cross-border logistics connectivity with mainland Chinese equipment suppliers, with deviation risk concentrated in technology export control escalations and land lease renewal cost trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Poland Data Center Storage Market
Storage Solutions
Mexico Data Center Storage Market
Storage Solutions
Belgium Data Center Storage Market
Storage Solutions
Virtual Machine Backup and Recovery Market
Storage Solutions
Hybrid Cloud Storage Market
Storage Solutions
Global in Memory Data Grid Market
Storage Solutions
Automated Storage and Retrieval System (AS & RS) Market
Storage Solutions
Cloud Block Storage Market
Storage Solutions
Cloud Native Storage Market
Storage Solutions
Europe in-Memory Database Market
Storage Solutions
Stand Alone Cloud Storage Market
Storage Solutions
Philippines Data Center Storage Market
Storage Solutions
Global Ethernet Storage Fabric Market
Storage Solutions
Storage and Backup Software Market
Storage Solutions
Spain Data Center Storage Market
Storage Solutions
Software Defined Storage Market