
 Global Single-Use Bioreactor Market | 2026-2036
Global Single-Use Bioreactor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Single-Use Bioreactor Market Foresight
Market Context
ISO 14644 cleanroom certification compliance is collapsing the supplier base as smaller fabricators fail qualification audits. Sartorius AG leverages its membrane filtration heritage to dominate bag film supply chains. Thermo Fisher Scientific anchors North American demand through integrated bioproduction workflows. Danaher competes across sensors and automation layers via its operating company structure.
Technical Definition and Structural Segments
Single-use bioreactors are disposable culture vessels manufactured from multilayer polymer films, typically ethylene vinyl acetate or low-density polyethylene composites, designed for sterile mammalian or microbial cell propagation without cleaning validation cycles. Stirred tank systems occupy the largest installed base owing to their equivalence with legacy stainless-steel protocols, while wave-induced motion platforms represent the fastest-expanding segment for seed train and perfusion applications. Automated controls capture disproportionate margin pools as biopharmaceutical manufacturers seek real-time process analytical technology integration.
Regulatory Framework and Outlook
FDA process validation guidance, EMA Annex 1 revisions on sterile manufacturing, and ISO 13485 quality management standards collectively elevate barrier-to-entry for new single-use suppliers. REACH compliance for polymer extractables and leachables testing shapes material selection and regional sourcing decisions. Stakeholders must monitor evolving biosafety classification requirements for novel gene therapy vectors as regulatory scope widens beyond conventional monoclonal antibodies.
Market Dynamics
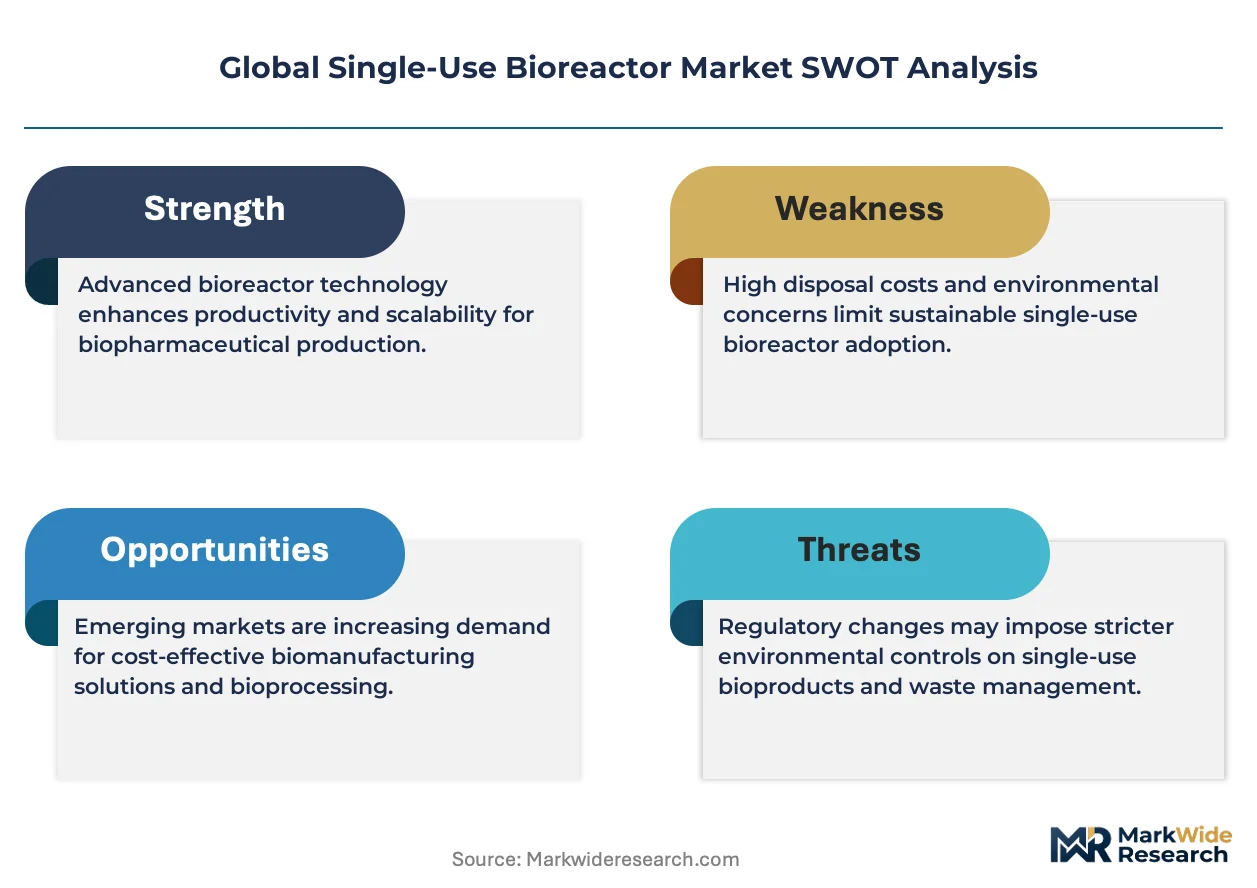
ISO 14644 cleanroom certification requirements are collapsing the supplier base as smaller polymer fabricators fail qualification audits, concentrating film supply among membrane specialists with validated manufacturing footprints.
Growth Catalysts
- EMA Annex 1 revisions:The updated sterile manufacturing guidance mandates closed-system processing for high-risk biologics, accelerating single-use adoption over stainless-steel alternatives in European facilities.
- Perfusion platform expansion:Wave-induced motion bioreactors enable continuous processing for cell therapy seed trains, capturing demand from contract manufacturers scaling autologous production.
- China biologics cluster densification:NMPA streamlined approval pathways for biosimilars concentrate manufacturing investment in Suzhou and Shanghai industrial zones, driving regional equipment procurement.
Market Restraints
- Polymer resin cost volatility:Ethylene vinyl acetate and low-density polyethylene feedstock prices fluctuate with petrochemical cycles, compressing margins for bag fabricators without backward integration into resin production.
- German film supply concentration:Multilayer polymer manufacturing clusters in Southern Germany create geographic single-point vulnerability for European bioreactor assembly operations.
- Extractables testing burden:REACH compliance requirements for comprehensive leachables characterization extend material qualification timelines and exclude uncertified regional suppliers.
Strategic Opportunities
- India biologics manufacturing:CDSCO production-linked incentive schemes attract multinational investment in biosimilar capacity, creating first-mover advantage for single-use vendors establishing local technical service presence.
- Gene therapy vector production:Novel AAV and lentiviral manufacturing protocols require flexible, low-cross-contamination systems distinct from monoclonal antibody infrastructure.
- Real-time PAT integration:Convergence of single-use sensors with automated process analytical technology enables closed-loop control for perfusion density management.
Industry Challenges
- Bioprocess engineering talent scarcity:Qualified personnel for disposable system validation and tech transfer remain concentrated at established biopharma hubs, constraining CMO expansion timelines.
- Legacy stainless-steel integration:Hybrid facilities face operational complexity bridging disposable upstream with fixed downstream purification trains, requiring customized automation architecture.
Report Scope
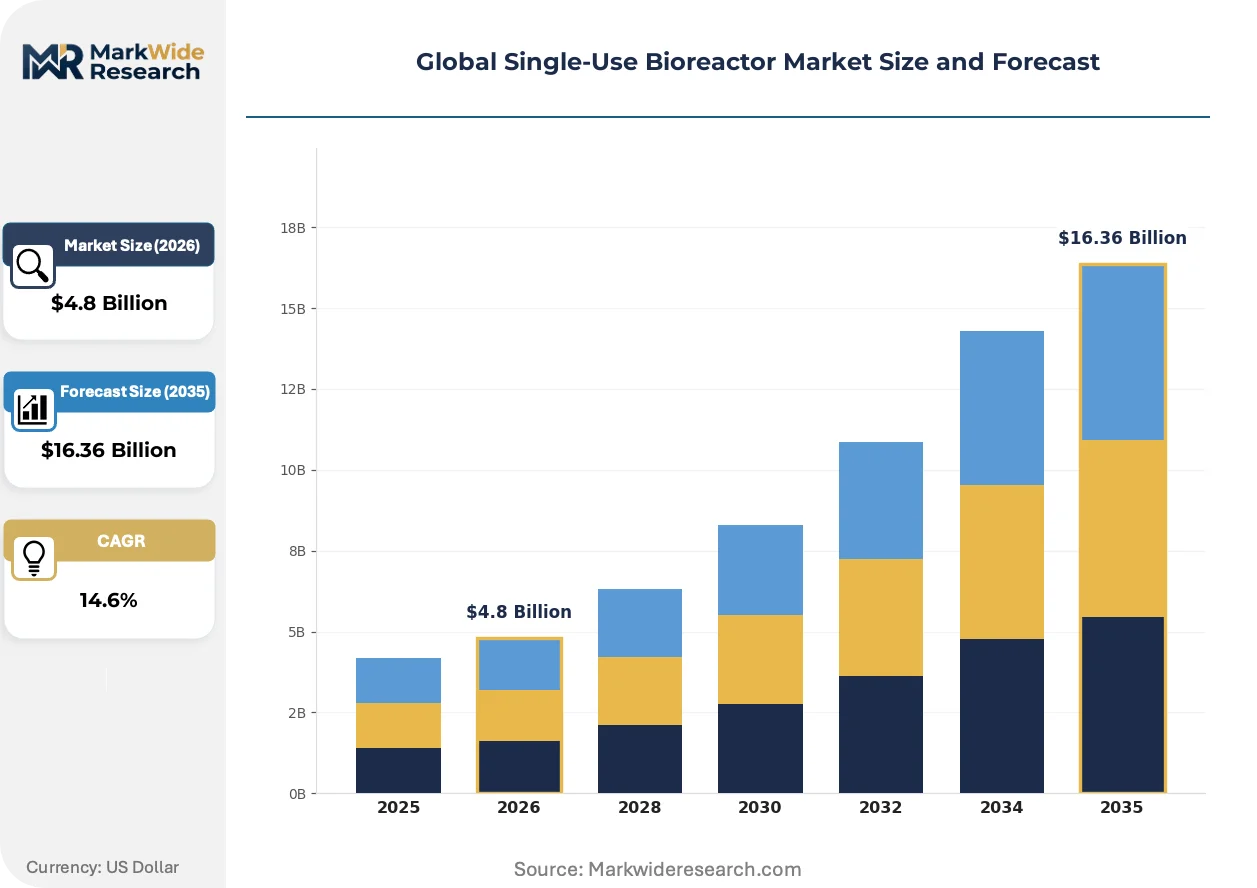
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Single-Use Bioreactor Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stirred Tank, Airlift, Wave, Tubular, Others Technology: Disposable Bags, Integrated Sensors, Automated Controls, Modular Systems Application: Monoclonal Antibodies, Recombinant Proteins, Vaccines, Cell Therapy End User: Biopharmaceutical Manufacturers, Contract Manufacturing Organizations, Academic Institutions, Research Labs |
| Companies Covered | Sartorius AG, Thermo Fisher Scientific, Danaher, Merck KGaA, Eppendorf AG, GE HealthCare, Getinge AB, PBS Biotech, Cellexus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Single-Use Bioreactor Market Shifts & Advancements
Disposable sensor layers and modular automation architectures are actively compressing the validation burden for multi-product facilities while enabling real-time release paradigms.
Multi-layer polymer film technology with embedded optical dissolved oxygen and pH sensors is bifurcating the sensor supply chain between integrated bag suppliers and specialized electronics fabricators. Gene therapy CDMOs adopt these systems fastest for rapid campaign changeover. The technology is bifurcating competitive positioning between film-integrated and probe-based measurement approaches.
REACH polymer registration requirements and EMA Annex 1 sterile manufacturing revisions collectively elevate extractables documentation burdens. Suppliers must maintain comprehensive chemical characterization databases for every film formulation. Biologics manufacturers in Germany and Switzerland now require supplier audit rights to polymer resin sources.
Biopharma procurement departments increasingly unbundle equipment purchase from consumables supply, awarding bioreactor hardware to automation specialists while negotiating multi-year film bag contracts separately. This bifurcation pressures integrated vendors to defend position through technical service differentiation. The pattern is most visible among mid-cap biotechs in the United States managing cash-constrained capacity buildouts.
Global Single-Use Bioreactor Market Segmentation
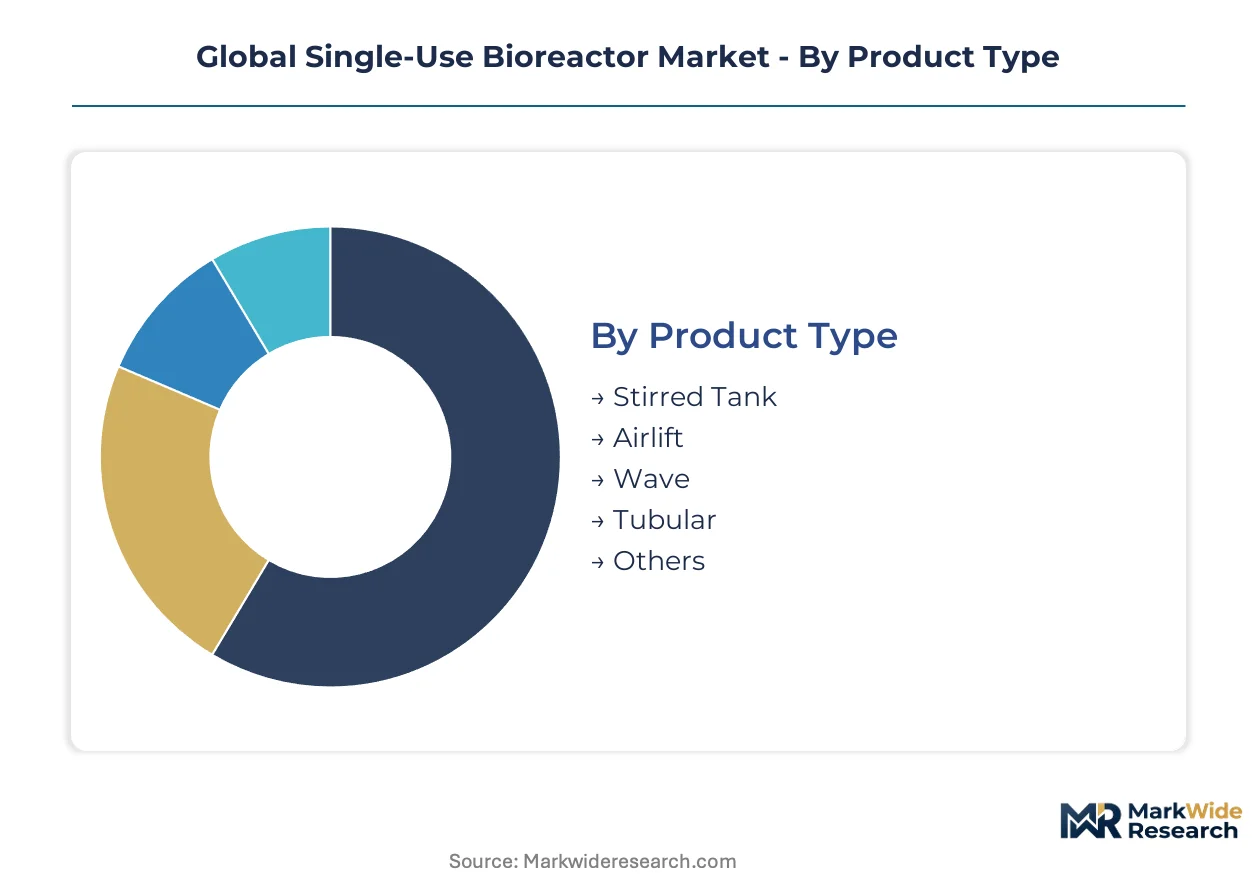
Single-use bioreactor segmentation reveals distinct margin architectures across hardware, consumables, and control layers. Product type determines capital intensity while technology and application layers govern recurring revenue streams and qualification burdens.
Product Type:
Margin pools concentrate in stirred tank systems where equivalence with legacy stainless-steel protocols commands premium pricing, while wave platforms capture value through perfusion-enabling continuous processing.
- Stirred Tank:Cylindrical polymer vessels with impeller-based mixing replicate conventional bioprocess parameters. Demand clusters at CMOs in the United States and Germany where tech transfer from stainless-steel infrastructure minimizes validation overhead.
- Wave:Rocking-motion platforms eliminate mechanical seals through fluid wave action. Cell therapy manufacturers in Suzhou and Shanghai industrial zones drive procurement for seed train applications requiring rapid campaign turnover.
- Airlift:Bubble-driven circulation suits shear-sensitive mammalian cultures. Niche adoption at academic institutions with limited automation infrastructure.
- Tubular:Linear flow path configurations for perfusion density management. Emerging interest from gene therapy CDMOs scaling AAV production.
- Others:Hybrid geometries and custom geometries for specialized microbial fermentation. Fragmented demand across research labs with project-specific procurement.
The dominant share belongs to Stirred Tank, while Wave is closing the gap fastest.
Technology:
Technology layering determines supplier power — integrated sensors and automated controls capture disproportionate value through qualification lock-in, while disposable bags face commoditization pressure.
- Disposable Bags:Multilayer EVA or LDPE films form the sterile barrier. German and Swiss manufacturers now mandate supplier audit rights to polymer resin sources under REACH documentation requirements.
- Integrated Sensors:Embedded optical dissolved oxygen and pH layers eliminate probe penetration. Gene therapy CDMOs adopt these systems fastest for closed-system processing mandated by EMA Annex 1 revisions.
- Automated Controls:Programmable logic controllers with PAT data integration enable real-time release paradigms. Biopharma procurement departments increasingly unbundle hardware purchase from consumables supply.
- Modular Systems:Skid-mounted configurations compress installation timelines. Mid-cap biotechs in the United States favor these for cash-constrained capacity buildouts.
Disposable Bags retain volume leadership, though Integrated Sensors show the steepest expansion trajectory as PAT convergence accelerates.
Application:
Application segmentation tracks biologics pipeline maturation — established modalities face pricing pressure while novel vectors command flexible system premiums.
- Monoclonal Antibodies:Established downstream purification protocols enable platform approaches. Biosimilar manufacturers in China concentrate demand as NMPA streamlines approval pathways.
- Cell Therapy:Autologous production requires patient-specific batch tracking and rapid changeover. Contract Manufacturing Organizations across the United States and Germany are expanding dedicated capacity.
- Vaccines:Pandemic response infrastructure created surplus mRNA capacity now repurposing for other modalities. Demand volatility exceeds other segments.
- Recombinant Proteins:Insulin and growth factor production utilizes standardized stirred tank configurations. Price-sensitive procurement at established biopharma manufacturers.
Monoclonal Antibodies maintain installed base dominance, yet Cell Therapy is gaining share fastest through CMO capacity expansion.
End User:
End user structure reflects outsourcing trends — biopharma manufacturers retain process development while production gravity shifts to CMOs with validated multi-product facilities.
- Biopharmaceutical Manufacturers:In-house capacity for pipeline assets and process characterization. FDA process validation guidance shapes qualification requirements for internal facilities.
- Contract Manufacturing Organizations:Multi-client facilities amortize validation costs across campaigns. CDSCO production-linked incentive schemes in India attract multinational investment creating procurement opportunities.
- Academic Institutions:Teaching and early-stage research with limited scale requirements. Budget constraints favor wave platforms over stirred tank systems.
- Research Labs:Discovery-stage screening and cell line development. Fragmented purchasing with minimal supplier loyalty.
Biopharmaceutical Manufacturers hold the largest committed spend, though Contract Manufacturing Organizations are expanding procurement fastest through dedicated cell therapy facility construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharmaceutical manufacturers in the United States, Germany, and China account for the dominant share of committed capital expenditure on single-use infrastructure, with contract manufacturing organizations driving procurement acceleration across all three markets.
United States
FDA process validation guidance shapes qualification requirements for biopharma manufacturers expanding cell therapy capacity. Greater Boston and San Francisco Bay Area clusters concentrate gene therapy CDMO construction. Sartorius AG and Thermo Fisher Scientific anchor equipment supply relationships through integrated workflow partnerships.
Germany
Southern Germany's multilayer polymer manufacturing belt creates geographic concentration risk for European bioreactor assembly operations. EMA Annex 1 sterile manufacturing revisions mandate closed-system processing for high-risk biologics. Bavaria-based membrane specialists dominate validated film supply chains under REACH compliance requirements.
China
NMPA streamlined approval pathways for biosimilars concentrate manufacturing investment in Suzhou and Shanghai industrial zones. CDMOs in these clusters scale autologous cell therapy production using wave-induced motion platforms. Domestic procurement favors vendors with localized technical service presence.
India
CDSCO production-linked incentive schemes attract multinational biosimilar investment, creating first-mover opportunity for single-use vendors establishing local validation support. Maharashtra and Gujarat host expanding biologics manufacturing infrastructure. Regional suppliers face exclusion from qualified vendor lists without comprehensive extractables documentation.
Switzerland
Swissmedic oversight of gene therapy manufacturing elevates barrier-to-entry for disposable system suppliers. Basel and Zurich biologics clusters demand supplier audit rights to polymer resin sources. Biopharma procurement departments negotiate multi-year film bag contracts separately from hardware awards.
Global Single-Use Bioreactor Market Competitive Landscape
Player mix skews toward integrated life science conglomerates with membrane filtration heritage, creating a tiered structure where membrane specialists capture disproportionate value in film supply while automation specialists dominate control layer procurement. Three strategic archetypes define competitive positioning: integrated workflow providers spanning hardware and consumables, membrane-focused film suppliers with validated cleanroom footprints, and automation-centric control system vendors. M&A activity concentrates on sensor technology tuck-ins and regional service network expansion.
Within the integrated conglomerate tier, Sartorius AG represents membrane heritage players leveraging polymer film supply chain control, while Thermo Fisher Scientific exemplifies North American workflow integration spanning equipment and consumables. Danaher occupies a position across sensors and automation layers through its operating company structure. These three anchors demonstrate how competitive advantage flows from qualification lock-in rather than hardware differentiation alone.
| Leading Market Players |
|---|
| Sartorius AG |
| Thermo Fisher Scientific |
| Danaher |
| Merck KGaA |
| Eppendorf AG |
| GE HealthCare |
| Getinge AB |
| PBS Biotech |
| Cellexus |
| Others |
Supply & Pricing Matrix
Multi-year film bag offtake agreements lock in polymer resin access and stabilize unit economics for biopharma procurement teams navigating volatile ethylene vinyl acetate feedstock markets. These structures concentrate pricing power among membrane specialists with validated cleanroom footprints while excluding uncertified regional fabricators from qualified vendor lists.
Pricing Analysis
Cost-plus contracts with ethylene indexation dominate multilayer polymer film procurement, tying bag fabricator margins to petrochemical cycle volatility. Price differentiation rests on ISO 14644 cleanroom certification tier and REACH extractables documentation depth. Cost compression in standard stirred tank configurations intensifies as biosimilar manufacturers in China consolidate purchasing volume. Academic institutions exhibit highest price sensitivity, while gene therapy CDMOs prioritize qualification speed over unit cost.
Supply Chain Analysis
Germany and Switzerland anchor multilayer polymer film manufacturing for bioreactor assembly operations across Europe. The supply chain draws from ethylene vinyl acetate resin production concentrated in petrochemical hubs, optical sensor components from specialized electronics fabricators, and automated control modules from industrial automation centers. Single-source vulnerability concentrates in Southern Germany's membrane manufacturing belt. Distribution runs through validated cold-chain logistics to biopharma manufacturing clusters in the United States, Germany, and China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment moat where qualification lock-in creates switching costs that compound with each validation cycle. EMA Annex 1 sterile manufacturing mandates and FDA process validation guidance erect barriers that favor incumbents with established audit trails.
For Market Incumbents: Secure backward integration into polymer resin characterization capabilities to defend margin position against feedstock volatility. Expand technical service presence in Suzhou and Shanghai industrial zones to capture NMPA-driven biosimilar capacity buildout. Prioritize sensor-integrated film development as gene therapy CDMOs mandate closed-system processing. For New Entrants and Emerging Players: Lead with modular automation architectures targeting mid-cap biotechs in the United States managing cash-constrained capacity expansions. India's CDSCO production-linked incentive schemes offer the most penetrable geographic entry point for vendors establishing local validation support. Position around rapid extractables documentation turnaround as a service differentiator. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among membrane specialists with validated cleanroom footprints and multi-year film supply contracts. Long-term viability favors targets with embedded sensor technology portfolios and regional service density across three or more biologics manufacturing clusters. Monitor EMA Annex 1 enforcement patterns as an inflection indicator for closed-system processing demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin Characterization | REACH compliance requirements in Germany and Switzerland mandate comprehensive extractables databases. |
| Sensor-Integrated Film Development | Gene therapy CDMOs adopt embedded optical dissolved oxygen layers fastest for EMA Annex 1 compliance. |
| Regional Technical Service Expansion | NMPA streamlined approval pathways concentrate procurement in Suzhou and Shanghai industrial zones. |
| Modular Automation Architecture Launch | Mid-cap biotechs in the United States favor skid-mounted configurations for compressed installation timelines. |
| Extractables Documentation Service Differentiation | Biopharma procurement departments in Germany and Switzerland now require supplier audit rights to resin sources. |
Research Methodology
Desk research of FDA guidance documents, EMA Annex 1 revisions, and ISO 14644 certification databases preceded structured interviews with bioprocess engineering directors, regulatory affairs leads at single-use suppliers, CMO procurement managers, and polymer film quality assurance heads. Primary fieldwork combined with secondary validation across REACH compliance filings, NMPA approval pathway records, and customs trade data for bioreactor equipment imports. Bottom-up segment sizing triangulated against top-down industry expenditure estimates.
Variance decomposition across product type, technology layer, application modality, and end-user archetype shaped the analytical framework over the projection horizon. CAGRs derived from installed base growth rates, replacement cycle assumptions, and penetration modeling across cell therapy and gene therapy manufacturing expansions. Forecast inputs incorporated NMPA biosimilar approval velocity, EMA Annex 1 enforcement timelines, and CDSCO incentive scheme uptake patterns.
The analysis sits within stated boundaries; outcomes outside sustained biologics pipeline investment or polymer resin supply stability would require recalibration. Forecasts reflect documented assumptions regarding regulatory guidance implementation pace and CMO capacity expansion commitments. Recalibration cycles align with material shifts in EMA Annex 1 enforcement, NMPA approval pathway modifications, and REACH polymer registration requirement expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Bioprocess Containers and Fluid Transfer Solutions Market
Biotechnology Equipment
Cell Culture Media, Sera, and Reagents Market
Biotechnology Equipment
RNA Isolation and Enrichment Reagent Market
Biotechnology Equipment
Global Latex Agglutination Test Kits Market
Biotechnology Equipment
Histology Equipment Market
Biotechnology Equipment
Cellbag Bioreactor Chambers Market
Biotechnology Equipment
Automated Cell Counting Market
Biotechnology Equipment
Low Endotoxin Gelatin Market
Biotechnology Equipment
Global Photobiostimulation Devices Market
Biotechnology Equipment
Robotic Arms in Laboratories Market
Biotechnology Equipment
Global Life Sciences Tools Market
Biotechnology Equipment
Global Bioreactor Market
Biotechnology Equipment
United States Transfection Technologies Market
Biotechnology Equipment
North America Life Science Tools Market
Biotechnology Equipment
Global Automated Biochemical Analyzer Market
Biotechnology Equipment
Global Biological Safety Cabinets Market