
 US Cell and Gene Therapy Clinical Trial Services Market | 2026-2036
US Cell and Gene Therapy Clinical Trial Services Market Size, Share, and Industry Trends Forecast 2026-2036
US Cell and Gene Therapy Clinical Trial Services Market Insights
The divergence between premium bespoke trial execution and commodity site management is repositioning vendor selection criteria across the industry. IQVIA leverages its integrated data network to dominate large-scale oncology gene therapy studies. Charles River Laboratories International Inc. anchors its position through specialized viral vector analytics capabilities. Catalent competes by extending manufacturing-linked clinical services into contiguous trial phases.
Cell and gene therapy clinical trial services encompass the specialized operational, regulatory, and scientific support required to execute human studies involving genetically modified cellular products, including vector characterization, patient-specific supply chain coordination, and long-term follow-up protocols exceeding fifteen years for durability assessment. These services enable sponsors to navigate the complexity of first-in-human through registrational trials for products that often require single-patient manufacturing batches and cryogenic logistics chains. Viral vector technology leads service demand due to manufacturing complexity and regulatory scrutiny around replication-competent shedding. Patient recruitment services represent the fastest-growing segment as rare disease trials require global geolocation of ultra-small eligible populations. Data management functions occupy mature margin pools where automation standardization has compressed differentiation.
FDA's regenerative medicine advanced therapy designation and corresponding breakthrough therapy pathways compress trial design consultation demand while elevating quality system expectations. The central bank of clinical evidence standards, including HIPAA privacy frameworks and 21 CFR Part 11 electronic records requirements, shapes vendor qualification thresholds and sponsor risk allocation. Stakeholders must monitor how CMS coverage determination precedents for gene therapies reshape endpoint design and health economics data collection obligations in pivotal trials.
Market Dynamics
The divergence between premium bespoke trial execution and commodity site management is repositioning vendor selection criteria across the US cell and gene therapy sector. Sponsors now separate high-complexity vector characterization work from standardized data management functions, creating tiered procurement frameworks that reward specialized capabilities over scale alone.
Growth Catalysts
- Regenerative Medicine Advanced Therapy (RMAT) Designation:FDA's accelerated pathway compresses clinical development timelines and elevates demand for integrated regulatory consulting services. Sponsors pursuing RMAT status require specialized CRO partners capable of navigating breakthrough therapy coordination.
- Viral Vector Manufacturing Complexity:Replication-competent shedding protocols and lentiviral stability requirements mandate dedicated analytical testing infrastructure. Contract research organizations with captive vector analytics capabilities capture disproportionate sponsor commitment.
- Massachusetts and California Biotech Cluster Concentration:Geographic proximity between gene therapy developers and specialized CRO infrastructure in Boston-Cambridge and San Francisco-San Diego corridors reduces supply chain latency for patient-specific investigational products.
Market Restraints
- Cryogenic Logistics Cost Structure:Liquid nitrogen-cooled shipping containers and validated cold chain monitoring systems impose per-patient logistics costs exceeding traditional biologics by an order of magnitude. Small-cap sponsors face working capital constraints that limit trial scale.
- Qualified Investigator Site Scarcity:Gene therapy protocols require principal investigators with advanced therapy-specific training and institutional biosafety committee clearance. The concentration of qualified academic medical centers in fewer than twelve US metropolitan areas creates site access bottlenecks.
- Fifteen-Year Durability Follow-Up Requirements:Long-term safety surveillance protocols mandated for integrating vectors extend trial obligations well beyond traditional study closeout. CRO pricing models struggle to capture full lifecycle service costs within initial contracts.
Strategic Opportunities
- Decentralized Clinical Trial Infrastructure:Home health nursing networks and local infusion centers enable gene therapy administration outside traditional academic medical centers. CROs building validated decentralized capabilities access previously unreachable rare disease patient populations in secondary US markets.
- Real-World Evidence Integration:FDA's expanding comfort with externally controlled trials and historical comparator data creates demand for registry-linked analytics services. Vendors with proprietary patient database access differentiate from commodity trial execution providers.
- Health Economics and Outcomes Research Capabilities:CMS coverage determination precedents for gene therapies reshape endpoint design requirements. CROs with embedded HEOR functions capture value demonstration work previously outsourced to specialized consultancies.
Industry Challenges
- Cell Therapy Manufacturing Scientist Shortage:GMP facility operators with autologous cell processing experience command compensation premiums exceeding 40% above traditional biologics manufacturing roles. CROs compete with product sponsors for identical talent pools.
- Electronic Data Capture System Integration:Gene therapy protocols require specialized modules for chain-of-identity tracking and patient-specific supply chain reconciliation. Legacy EDC platforms demand costly customization to support autologous product workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Cell and Gene Therapy Clinical Trial Services Market |
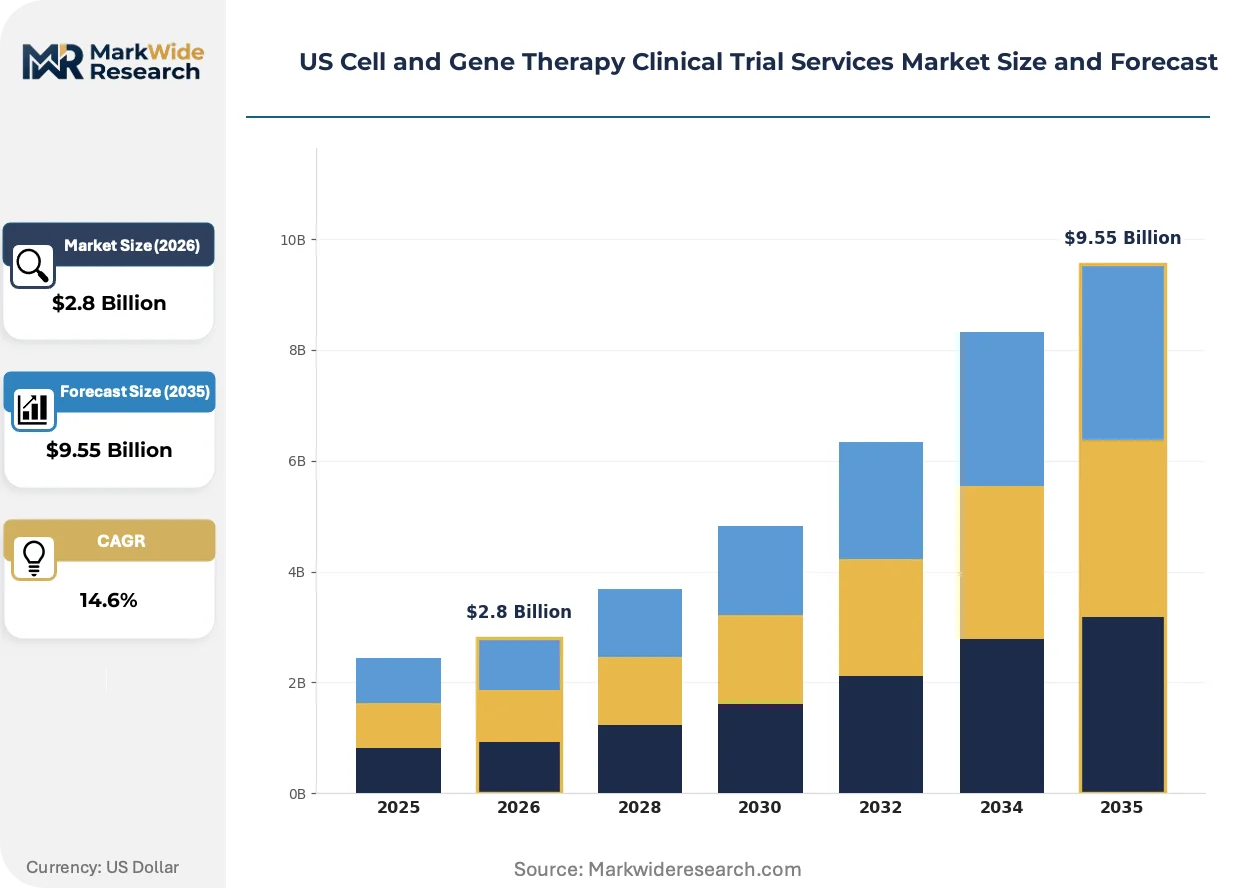
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Patient Recruitment, Regulatory Affairs, Data Management, Biostatistics Technology: CRISPR, RNA Interference, Viral Vectors, Genomic Sequencing End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Academic Centers Therapy Area: Oncology, Rare Diseases, Genetic Disorders, Autoimmune Diseases |
| Companies Covered | IQVIA, Charles River Laboratories International Inc., Catalent, Parexel International, ICON PLC, Syneos Health, Medpace, Inc., Thermo Fisher Scientific, LabCorp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Cell and Gene Therapy Clinical Trial Services Market Trends and Innovations
Artificial intelligence and machine learning applications are compressing traditional clinical trial execution timelines across the US gene therapy sector. These technologies reshape everything from patient identification to regulatory submission preparation.
Natural language processing is automating adverse event narrative generation and medical coding review for gene therapy trials. Mid-tier CROs deploy these tools to match larger competitors' throughput without proportional headcount expansion. The technology is automating routine pharmacovigilance tasks previously requiring dedicated safety physician review, enabling resource reallocation toward complex vector-specific toxicology assessment.
FDA's Project Orbis and parallel review coordination with Health Canada and Australia's TGA is harmonizing multi-regional submission strategies. US sponsors increasingly structure development programs for simultaneous regulatory engagement across Anglo-Pacific markets. Oncology gene therapy developers with international aspirations now prioritize CRO partners with established Health Canada and TGA rapporteur relationships.
Biopharma procurement functions are unbundling full-service CRO contracts into functional component sourcing. Large pharmaceutical sponsors now separately contract data management, clinical monitoring, and regulatory writing services rather than accepting bundled proposals. This disaggregation is most pronounced among Massachusetts-based gene therapy developers with sufficient internal program management capacity to coordinate multiple specialty vendors.
US Cell and Gene Therapy Clinical Trial Services Market Segmentation
Cell and gene therapy trials demand specialized service capabilities that vary dramatically across therapeutic modalities and sponsor types. Segment-specific procurement patterns reflect the divergence between large pharmaceutical sponsors with captive program management capacity and emerging biotechnology firms requiring full-service integration.
Service Type:
Supply concentration for specialized gene therapy expertise has created distinct procurement tiers, with sponsors unbundling full-service contracts into functional components based on internal capability gaps.
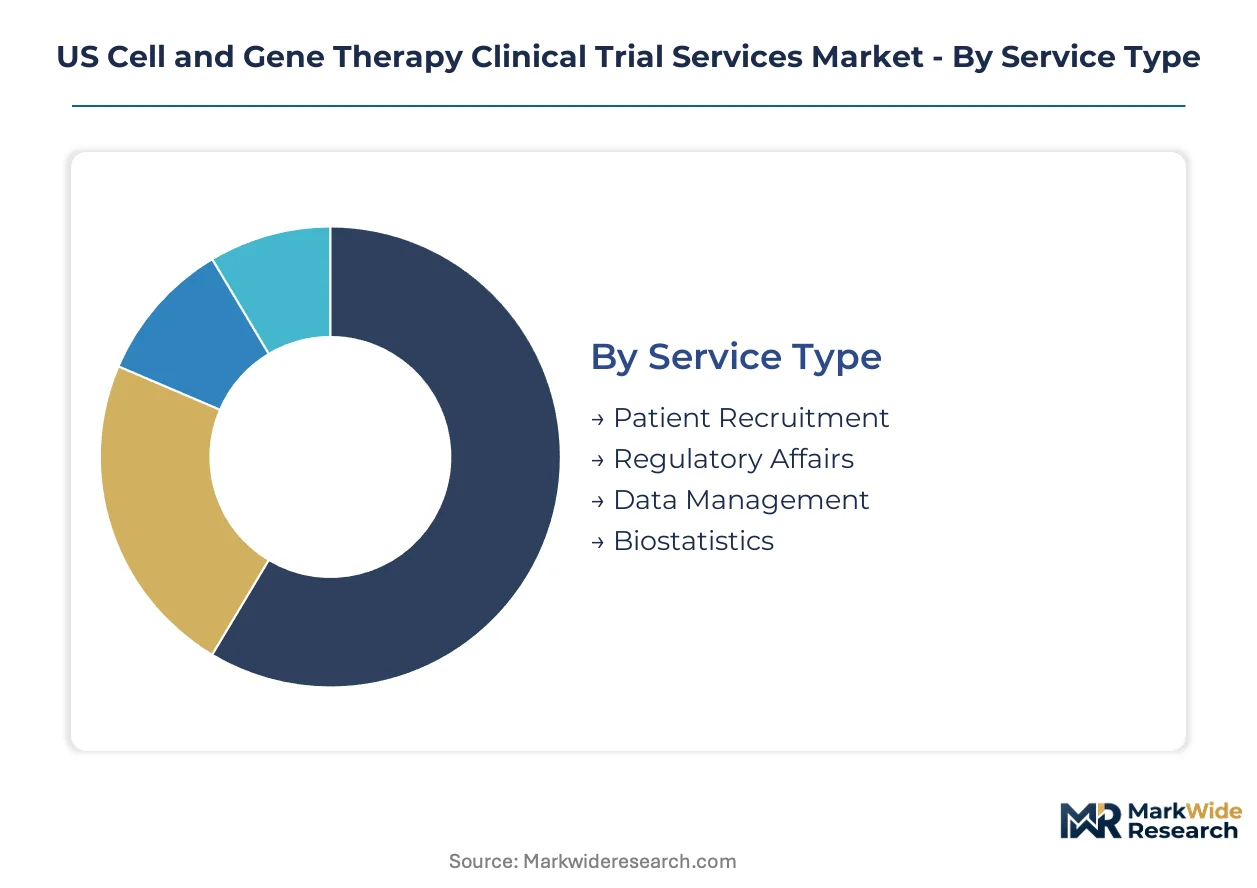
- Patient Recruitment:Ultra-rare disease indications require geolocation of eligible patients across dispersed geographies. Massachusetts and California biotech clusters anchor specialized recruitment infrastructure for gene therapy trials targeting single-digit incidence populations. Demand concentrates here as FDA's RMAT designation compresses enrollment timelines.
- Regulatory Affairs:RMAT and breakthrough therapy coordination demands specialized consulting for accelerated pathway navigation. Sponsors in Boston-Cambridge corridor prioritize CROs with established FDA rapporteur relationships for complex vector submissions.
- Data Management:Chain-of-identity tracking modules and patient-specific supply chain reconciliation require EDC customization. Legacy platform limitations compress margins through standardization.
- Biostatistics:Bayesian adaptive designs and small population methodologies dominate gene therapy protocols. External control arm construction using historical comparator data elevates statistical consulting demand.
Today's leader: Patient Recruitment. Tomorrow's challenger: Regulatory Affairs.
Technology:
Cost tier differentiation separates premium bespoke analytical capabilities from commoditized manufacturing support functions.
- Viral Vectors:Lentiviral and AAV stability requirements mandate dedicated analytical testing infrastructure. Replication-competent shedding protocols command premium pricing. Charles River Laboratories anchors market position through captive vector analytics capabilities in this segment.
- CRISPR:Off-target editing assessment and long-term genotoxicity surveillance reshape trial design. Editing efficiency validation requires specialized molecular biology workflows. Demand concentrates among Cambridge-based developers pursuing in vivo gene editing indications.
- RNA Interference:siRNA and miRNA therapeutic modalities require distinct pharmacokinetic modeling. Hepatic delivery optimization dominates current development pipelines.
- Genomic Sequencing:Companion diagnostic integration and clonal tracking applications support patient stratification. Next-generation sequencing cost compression has shifted value toward interpretation services.
Viral Vectors capture current revenue concentration. CRISPR platforms are climbing the fastest as editing therapies advance toward registrational trials.
End User:
Customer type fragmentation produces divergent vendor selection criteria across sponsor scale and internal capability maturity.
- Pharmaceutical Companies:Large sponsors unbundle contracts into functional component sourcing. IQVIA leverages integrated data networks to dominate large-scale oncology gene therapy studies. Internal program management capacity enables multi-vendor coordination.
- Biotechnology Firms:Emerging developers require full-service integration due to limited operational infrastructure. Working capital constraints favor milestone-based pricing structures.
- Research Institutions:Academic medical centers with qualified investigator sites command premium access fees. Institutional biosafety committee clearance creates site scarcity bottlenecks.
- Academic Centers:Investigator-initiated trials drive early-phase gene therapy exploration. Limited commercial scale restricts service contract values.
Pharmaceutical Companies dominate contract value. Biotechnology Firms represent expanding volume as venture funding flows into gene therapy platforms.
Therapy Area:
Maturity gradients separate established oncology infrastructure from emerging therapeutic domains requiring protocol innovation.
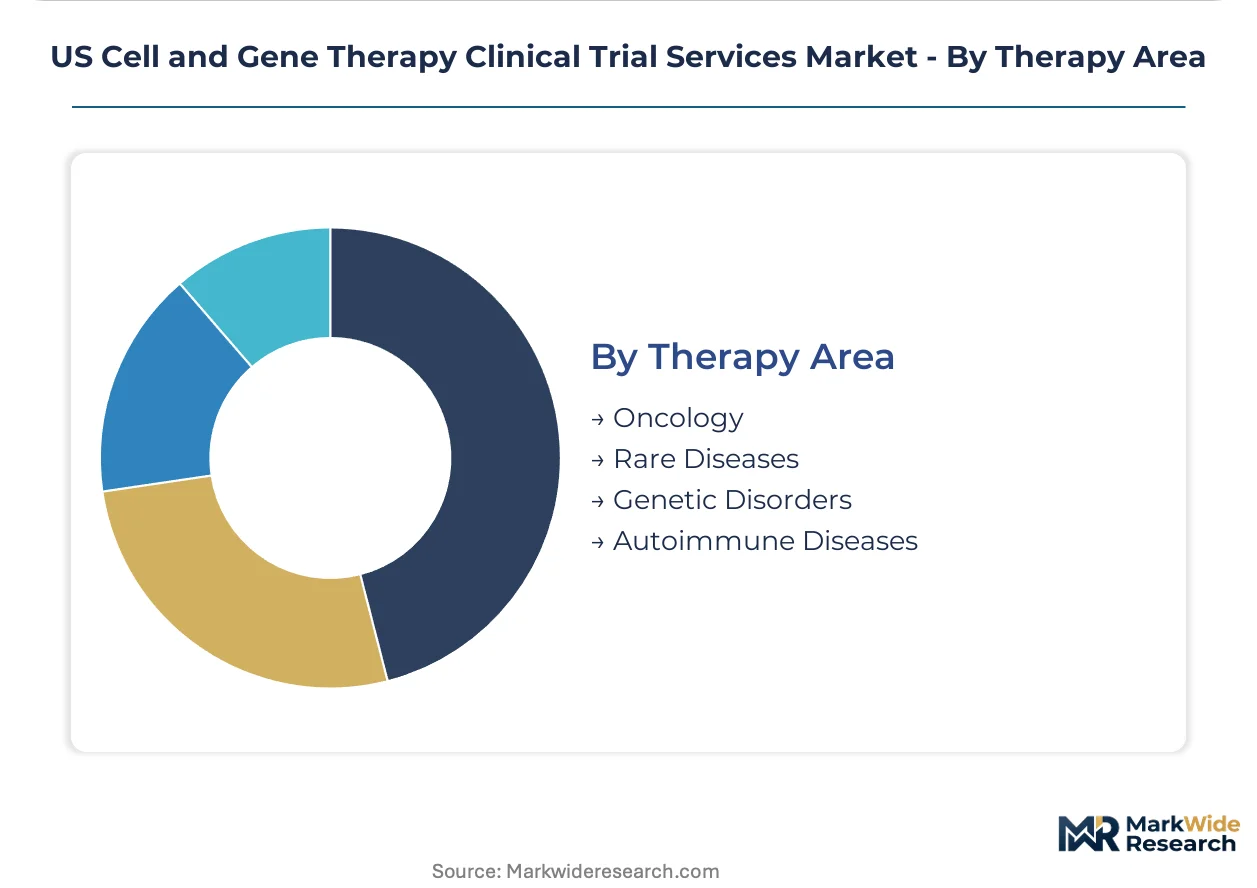
- Oncology:CAR-T and TCR-T cell therapies leverage established hematologic malignancy trial infrastructure. FDA's Project Orbis harmonizes multi-regional submission strategies for US sponsors with international aspirations.
- Rare Diseases:Ultra-small eligible populations require global patient geolocation. Single-patient manufacturing batches and cryogenic logistics chains impose per-patient costs exceeding traditional biologics by an order of magnitude.
- Genetic Disorders:In vivo gene replacement therapies mandate fifteen-year durability follow-up protocols. Long-term safety surveillance extends CRO obligations beyond traditional study closeout.
- Autoimmune Diseases:Treg and CAR-Treg modalities represent emerging therapeutic frontiers. Regulatory precedent uncertainty elevates trial design consultation demand.
Oncology maintains revenue leadership. Rare Diseases are gaining share fastest as FDA's RMAT designation accelerates development timelines for ultra-orphan indications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized gene therapy talent concentrates in Massachusetts and California, anchoring the national market for clinical trial services. These biotech clusters house the qualified investigators, viral vector scientists, and regulatory specialists that sponsors require for complex cell therapy development.
Massachusetts
FDA's RMAT designation accelerates trial timelines for Cambridge-based developers, compressing patient recruitment windows. The state's regenerative medicine tax incentive program subsidizes early-stage gene therapy manufacturing infrastructure. Boston-Cambridge corridor anchors specialized CRO facilities serving oncology and rare disease indications.
California
San Francisco-San Diego biotech concentration drives demand for lentiviral and AAV vector analytics services. California's stem cell research funding agency (CIRM) provides non-dilutive capital for academic gene therapy trials. South San Francisco and La Jolla host captive vector manufacturing sites integrated with clinical operations.
North Carolina
Research Triangle Park attracts gene therapy sponsors seeking lower-cost clinical operations outside coastal metros. The state's biotechnology center offers workforce training grants for cell therapy manufacturing roles. Durham and Raleigh anchor mid-Atlantic patient recruitment infrastructure for decentralized trial models.
Maryland
Proximity to FDA headquarters in Silver Spring facilitates sponsor-regulator engagement for breakthrough therapy coordination. NIH's intramural gene therapy programs generate investigator-initiated trial demand. Bethesda and Rockville concentrate regulatory consulting specialists serving emerging biotechnology firms.
Texas
Houston's Texas Medical Center expands gene therapy clinical capacity through MD Anderson's CAR-T infrastructure. The state's emerging biotech tax credit program attracts cell therapy sponsors seeking operational cost advantages. Dallas-Fort Worth develops cryogenic logistics hubs serving Southwest patient populations.
US Cell and Gene Therapy Clinical Trial Services Market Competitive Landscape
Capital-heavy CROs with captive manufacturing infrastructure compete with asset-light clinical specialists for sponsor contracts. The market structures around three tiers: integrated data network operators, specialized viral vector analytics providers, and regional site management organizations. Consolidation pressure favors scale in patient recruitment networks while fragmentation persists in regulatory consulting niches. Strategic moves center on backward integration into manufacturing-linked services and geographic expansion into secondary US markets.
Among integrated network operators, IQVIA leverages its data infrastructure to anchor large-scale oncology gene therapy studies. Charles River Laboratories International Inc. exemplifies the specialized analytics tier through its viral vector capabilities. Catalent occupies the manufacturing-contiguous position, extending GMP services into clinical trial execution. These three archetypes represent the competitive vectors reshaping vendor selection criteria across sponsor segments.
| Leading Market Players |
|---|
| IQVIA |
| Charles River Laboratories International Inc. |
| Catalent |
| Parexel International |
| ICON PLC |
| Syneos Health |
| Medpace, Inc. |
| Thermo Fisher Scientific |
| LabCorp |
| Others |
Pricing and Supply Chain Analysis
Captive viral vector manufacturing integration anchors both supply security and pricing power for cell and gene therapy clinical trial services. Sponsors with backward integration into GMP facilities command premium positioning, while asset-light CROs compete on project-based flexibility for emerging biotechnology firms.
Pricing Analysis
Bundled full-service contracts separate from unbundled functional component sourcing across sponsor tiers. Pharmaceutical companies with internal program management capacity favor à la carte procurement of patient recruitment, regulatory consulting, and data management functions. Biotechnology firms lacking operational infrastructure accept premium pricing for integrated trial execution. Price differentiation rests on vector analytics certification and geographic proximity to qualified investigator sites. Cost compression in standardized data management functions intensifies as automation standardization erodes margins, while bespoke regulatory consulting for FDA RMAT navigation sustains premium tiers.
Supply Chain Analysis
Domestic-content requirements for viral vector manufacturing reshape sourcing patterns toward US-based GMP facilities. Supply concentration centers on Massachusetts and California biotech corridors, with secondary nodes emerging in North Carolina and Maryland. Raw material dependencies span plasmid DNA, cell culture media, and cryopreservation reagents. Single-source vulnerability for lentiviral packaging cell lines creates bottlenecks during scale-up phases. Distribution runs through validated cold chain networks with liquid nitrogen-cooled containers and real-time temperature monitoring systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications for gene therapy trial execution have tightened as FDA's RMAT designation compresses timelines and elevates compliance thresholds. Sponsors now prioritize CRO partners with demonstrated vector characterization capabilities over commodity site management providers.
For Market Incumbents: Cement market position through captive expansion of viral vector analytics infrastructure in Boston-Cambridge and San Francisco-San Diego corridors. Deepen relationships with qualified academic medical centers holding institutional biosafety committee clearance. Address emerging platform competition from CRISPR-focused specialists by extending lentiviral and AAV capabilities into contiguous gene editing trial support. Prioritize backward integration into patient-specific manufacturing coordination to capture full lifecycle service value.
For New Entrants and Emerging Players: Begin with decentralized clinical trial infrastructure targeting secondary US markets outside coastal biotech clusters. Home health nursing networks and local infusion centers in Texas, Florida, and Ohio present underpenetrated access points for rare disease patient populations. Pursue white-space positioning in health economics and outcomes research capabilities as CMS coverage determinations reshape endpoint design requirements. Differentiate through milestone-based pricing structures that accommodate emerging biotechnology firm working capital constraints.
For Investors and Strategic Acquirers: Roll-up economics work for specialized regulatory consulting boutiques because FDA's breakthrough therapy coordination demands have fragmented advisory services across multiple niche providers. Platform consolidation of RMAT navigation specialists, viral vector scientists, and decentralized trial operators captures sponsor procurement unbundling trends. Monitor Health Canada and TGA rapporteur relationship development as inflection indicators for international expansion viability. Long-term positioning favors asset-light clinical specialists with proprietary patient database access over capital-heavy manufacturing-integrated competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | RMAT designation from FDA compresses development timelines and elevates CRO selection criteria. |
| Manufacturing Scale-Up | Captive viral vector GMP capacity anchors premium positioning in sponsor procurement frameworks. |
| Strategic Partnership | Collaboration with qualified academic medical centers unlocks site access for rare disease trials. |
| Geographic Expansion | Decentralized trial infrastructure in secondary markets reaches previously inaccessible patient populations. |
| Acquisition of Specialist Firm | Health economics and outcomes research capabilities capture value demonstration work from consultancies. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct the market assessment. Primary fieldwork engaged drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers across pharmaceutical, biotechnology, and academic medical center segments. Secondary validation drew from FDA filings, ClinicalTrials.gov registry data, CMS coverage determination precedents, and SEC disclosures from publicly traded CRO operators. Bottom-up service line analysis and top-down market sizing triangulated volume and value estimates.
Comparable historical periods anchored the projection horizon, with growth trajectories calibrated to observed adoption patterns across gene therapy modalities. Segmentation modeling incorporated service type, technology platform, end-user category, and therapeutic area dimensions. Bayesian adaptive trial design prevalence and RMAT designation velocity informed demand elasticity assumptions. CAGRs derived from regression analysis of sponsor outsourcing ratios and clinical development pipeline composition.
Several conditions sit outside the modeled scope, including preclinical-stage program attrition, regulatory pathway reversals, and manufacturing facility inspection outcomes. Forecasts reflect underlying assumptions about FDA's continued RMAT program expansion and stable venture capital flows into gene therapy platforms. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Cryopreservation Cell Lines Market
Cell & Gene Therapy
Autologous Stem Cell and Non Stem Cell Based Therapies Market
Cell & Gene Therapy
Gene Panel Market
Cell & Gene Therapy
Inherited Orphan Blood Disorders Therapeutics Market
Cell & Gene Therapy
Automated and Closed Cell Therapy Processing Systems Market
Cell & Gene Therapy
Cell Therapy Biomanufacturing Market
Cell & Gene Therapy
Gene Therapy Products Market
Cell & Gene Therapy
Oncolytic Adenovirus Market
Cell & Gene Therapy
High Density (HD) Cell Banking Market
Cell & Gene Therapy
Cancer Stem Cells Market
Cell & Gene Therapy
Global Mrna Therapeutics Market
Cell & Gene Therapy
North America Stem Cell Market
Cell & Gene Therapy
Adeno Associated Virus Vector Manufacturing Market
Cell & Gene Therapy
Viral Vector Purification Market
Cell & Gene Therapy
Global Cell and Gene Therapy Manufacturing Services Market
Cell & Gene Therapy
Regenerative Medicine Market