
 Global Pharmacy Benefit Management (PBM) Market | 2026-2036
Global Pharmacy Benefit Management (PBM) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pharmacy Benefit Management (PBM) Market Foresight
Modular benefit bundling is repositioning how employers and health plans purchase pharmacy services, unbundling traditional full-service contracts into standalone specialty pharmacy, data analytics, and utilization management components. CVS Health leverages its vertically integrated retail and PBM infrastructure to control formulary access across multiple channels. Express Scripts anchors large employer accounts through captive mail-order fulfillment networks. OptumRx competes by embedding pharmacy benefits within UnitedHealth Group's broader care management ecosystem.
Pharmacy benefit management encompasses the administration of prescription drug programs through formulary development, rebate negotiation, claims adjudication, and utilization review, operating on transaction fees and retained rebates as primary revenue mechanisms. The specialty pharmacy segment dominates margin pools due to high-cost biologics and limited distribution drug networks requiring intensive patient management. Cloud-based PBM software is displacing legacy on-premise systems as health plans demand real-time eligibility verification and predictive analytics for fraud detection.
The US Department of Health and Human Services and the Centers for Medicare & Medicaid Services shape PBM contracting through Medicare Part D oversight and forthcoming transparency regulations on rebate pass-through. The Federal Trade Commission scrutinizes vertical integration between PBMs and specialty pharmacies for anti-competitive formulary steering. Stakeholders must monitor how state-level pharmacy benefit transparency laws in California, New York, and Ohio alter disclosure requirements for spread pricing and rebate retention.
Market Dynamics
The US Inflation Reduction Act's Medicare drug price negotiation provisions are forcing PBMs to reconstruct rebate retention models and formulary placement strategies, while employer-sponsored self-insured plans multiply and demand unbundled service components.
Growth Catalysts
- Employer Self-Insurance Expansion:Large corporations in the United States are abandoning fully insured arrangements for self-funded pharmacy benefit structures, creating direct contracting demand for standalone PBM services.
- Specialty Biologic Proliferation:High-cost gene therapies and limited distribution drugs require intensive patient management programs that PBMs monetize through manufacturer access fees and adherence contracts.
- Real-Time Claims Processing:Cloud-native eligibility verification systems are replacing legacy batch processing, enabling instant prior authorization and fraud detection at point-of-sale.
Market Restraints
- Rebate Disclosure Mandates:State-level transparency laws in California, New York, and Ohio compel PBMs to report spread pricing and retained rebate volumes, compressing margin opacity.
- FTC Vertical Scrutiny:The Federal Trade Commission's ongoing investigation into insurer-PBM-specialty pharmacy consolidation threatens formulary steering practices and captive pharmacy economics.
- Generic Substitution Saturation:Patent cliffs for small-molecule blockbusters have exhausted easy generic conversion opportunities, limiting traditional cost-containment leverage.
Strategic Opportunities
- International Expansion:Canada and the United Kingdom present underpenetrated markets where integrated care models and national formularies favor PBM-style pharmacy management adoption.
- Digital Therapeutics Integration:FDA-cleared prescription digital therapeutics for diabetes and psychiatric conditions create new formulary categories requiring PBM distribution infrastructure.
- Value-Based Contracting:Outcomes-based pharmaceutical agreements tied to real-world evidence collection align PBM data assets with manufacturer risk-sharing demands.
Industry Challenges
- Legacy System Migration:Decades-old claims adjudication platforms require costly replacement to support API-driven interoperability and real-time analytics demanded by modern health plans.
- Specialty Pharmacy Credentialing:Limited distribution drug networks impose stringent accreditation requirements that strain operational capacity and capital allocation for patient support services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pharmacy Benefit Management (PBM) Market |
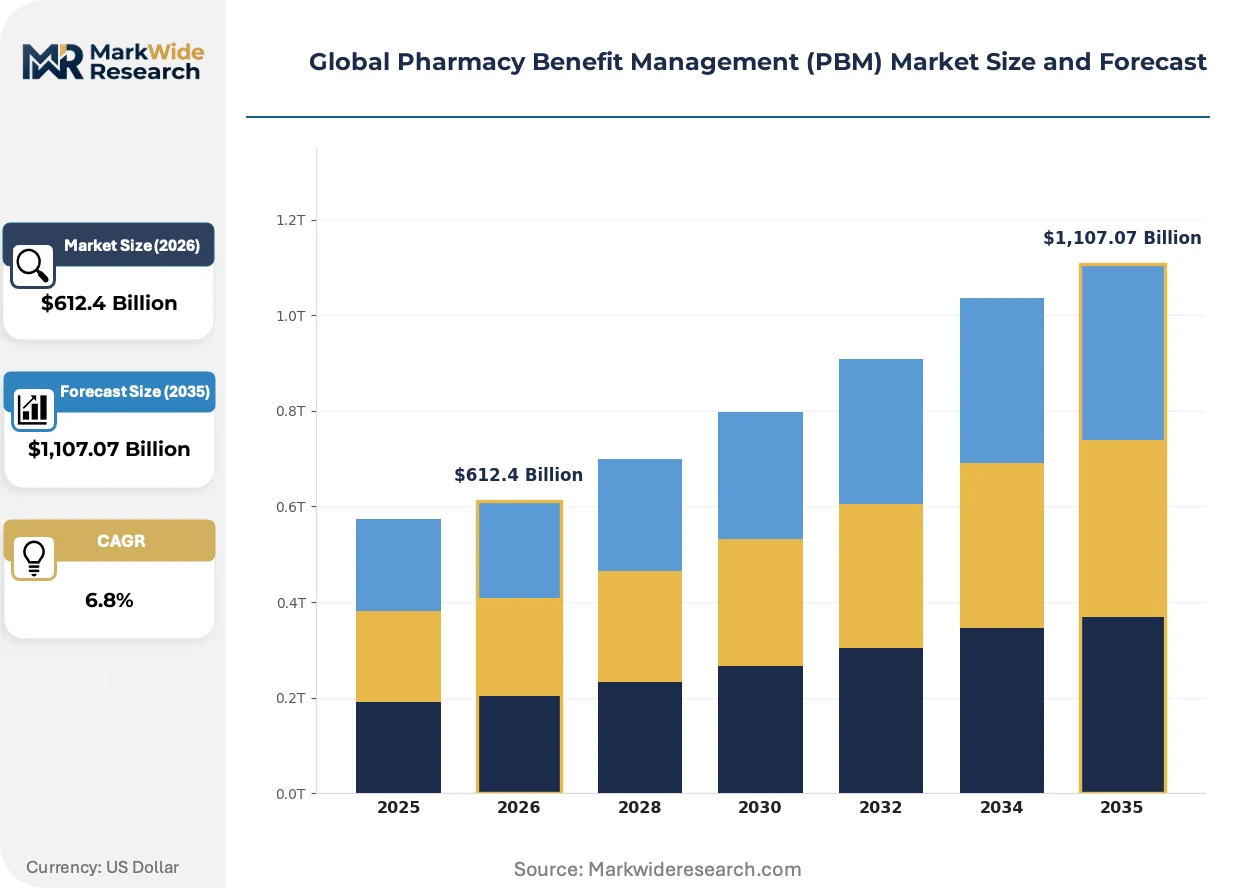
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $1,107.07 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mail-Order Pharmacy, Specialty Pharmacy, Retail Pharmacy, Online Pharmacy End User: Health Plans, Employers, Government Programs, Pharmacy Chains Service Type: Claims Processing, Drug Utilization Review, Customer Service, Data Analysis Technology: Automated PBM Software, Cloud-Based Solutions, Mobile Applications, Analytics Tools |
| Companies Covered | Express Scripts, CVS Health, OptumRx, Prime Therapeutics, MedImpact Healthcare Systems, Humana Pharmacy Solutions, Magellan Health, Anthem, Centene Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pharmacy Benefit Management (PBM) Market Shifts & Advancements
Technology convergence and regulatory transparency mandates are dismantling traditional full-service PBM bundling, creating modular procurement patterns and specialized vendor ecosystems.
Cloud-native pharmacy benefit platforms are modularizing core functions into interoperable components. Health plans and large employers are adopting standalone specialty pharmacy management, utilization review, and rebate administration modules from competing vendors rather than single-source contracts. This architectural shift compresses switching costs and enables best-of-breed procurement strategies.
The US Inflation Reduction Act's Medicare price negotiation provisions are restructuring manufacturer-PBM contracting dynamics. Pharmaceutical companies must now account for federal ceiling prices in rebate calculations, altering net price reporting and formulary placement incentives. Medicare Part D plans are responding by reconfiguring tier structures and prior authorization criteria to maintain actuarial soundness.
Employer purchasing patterns are fragmenting across channel types. Large corporations are unbundling pharmacy benefits from medical carriers and contracting directly with PBMs or consortium arrangements, bypassing traditional insurer intermediaries. This disintermediation is most visible among Fortune 500 self-insured employers in the United States seeking transparent pass-through pricing and direct rebate arrangements.
Global Pharmacy Benefit Management (PBM) Market Segmentation
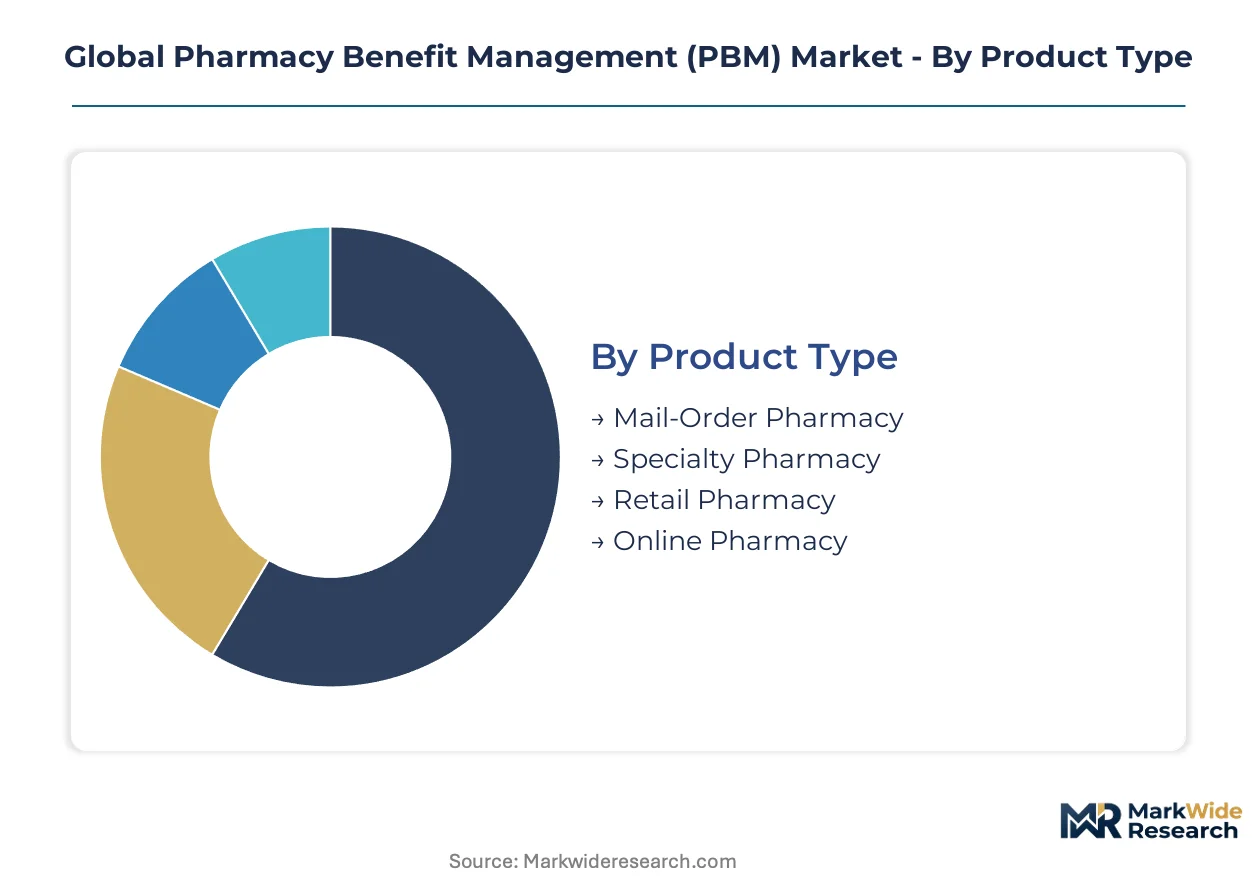
PBM market segmentation reflects divergent procurement strategies across self-insured employers, government payers, and integrated health systems. Channel selection and technology architecture determine rebate capture efficiency and patient adherence outcomes.
Product Type:
Channel economics separate high-touch specialty fulfillment from commodity retail dispensing, with ownership structure dictating margin retention.
- Specialty Pharmacy:Limited distribution drug networks require temperature-controlled logistics, patient risk evaluation, and manufacturer access program administration. High-cost biologics for oncology and autoimmune conditions concentrate demand in captive specialty pharmacies operated by vertically integrated PBMs.
- Mail-Order Pharmacy:90-day maintenance medication dispensing leverages central fill automation to reduce per-script labor costs below retail benchmarks. Large employers in the United States mandate mail-order mandatory programs for chronic condition medications to capture spread pricing arbitrage.
- Retail Pharmacy:Community-based dispensing networks provide acute medication access and face-to-face pharmacist consultation for Medicare Part D beneficiaries preferring brick-and-mortor pickup.
- Online Pharmacy:Direct-to-consumer platforms with automated refill management and price transparency tools attract uninsured cash-pay patients seeking generic drug cost comparisons.
Volume sits with retail pharmacy networks; growth tilts toward specialty pharmacy.
End User:
Purchasing sophistication varies by scale and regulatory exposure, with self-insured employers demanding unbundled transparency unavailable to smaller fully insured plans.
- Employers:Fortune 500 self-insured corporations negotiate direct PBM contracts with pass-through rebate arrangements and explicit spread pricing disclosure. These buyers unbundle pharmacy benefits from medical carriers to capture administrative fee savings and direct manufacturer rebate payments.
- Health Plans:Medicare Advantage and commercial insurers integrate PBM services within broader care management platforms, prioritizing formulary alignment with medical benefit cost containment. UnitedHealth Group's OptumRx exemplifies embedded pharmacy benefits within integrated delivery networks.
- Government Programs:Medicare Part D plans operate under CMS actuarial soundness requirements with federal ceiling price constraints from IRA negotiations. State Medicaid programs mandate supplemental rebate agreements beyond federal statutory minimums.
- Pharmacy Chains:Independent and regional pharmacy cooperatives contract for PBM network participation and reimbursement rate negotiation against dominant national formularies.
Health plans dominate current transaction volume; employer direct contracting climbs the fastest.
Service Type:
Core function unbundling enables best-of-breed procurement as cloud infrastructure reduces switching costs between specialized vendors.
- Claims Processing:Real-time adjudication engines with NCPDP D.0 standard compliance enable instant eligibility verification and copay calculation at point-of-sale. Legacy batch systems migrate to API-driven architectures supporting interoperability mandates.
- Drug Utilization Review:Prospective and retrospective medication therapy management programs identify polypharmacy risks and generic substitution opportunities. Medicare Star Ratings tie bonus payments to PBM-conducted medication adherence interventions for chronic conditions.
- Customer Service:Member and provider call center operations handle prior authorization appeals, formulary exceptions, and benefit interpretation. Offshore and domestic contact center location decisions balance labor arbitrage against HIPAA compliance requirements.
- Data Analysis:Predictive models for fraud detection, specialty drug trend forecasting, and outcomes-based contract performance measurement monetize PBM accumulated claims repositories.
Claims processing commands the largest service expenditure; data analysis shows the steepest expansion trajectory.
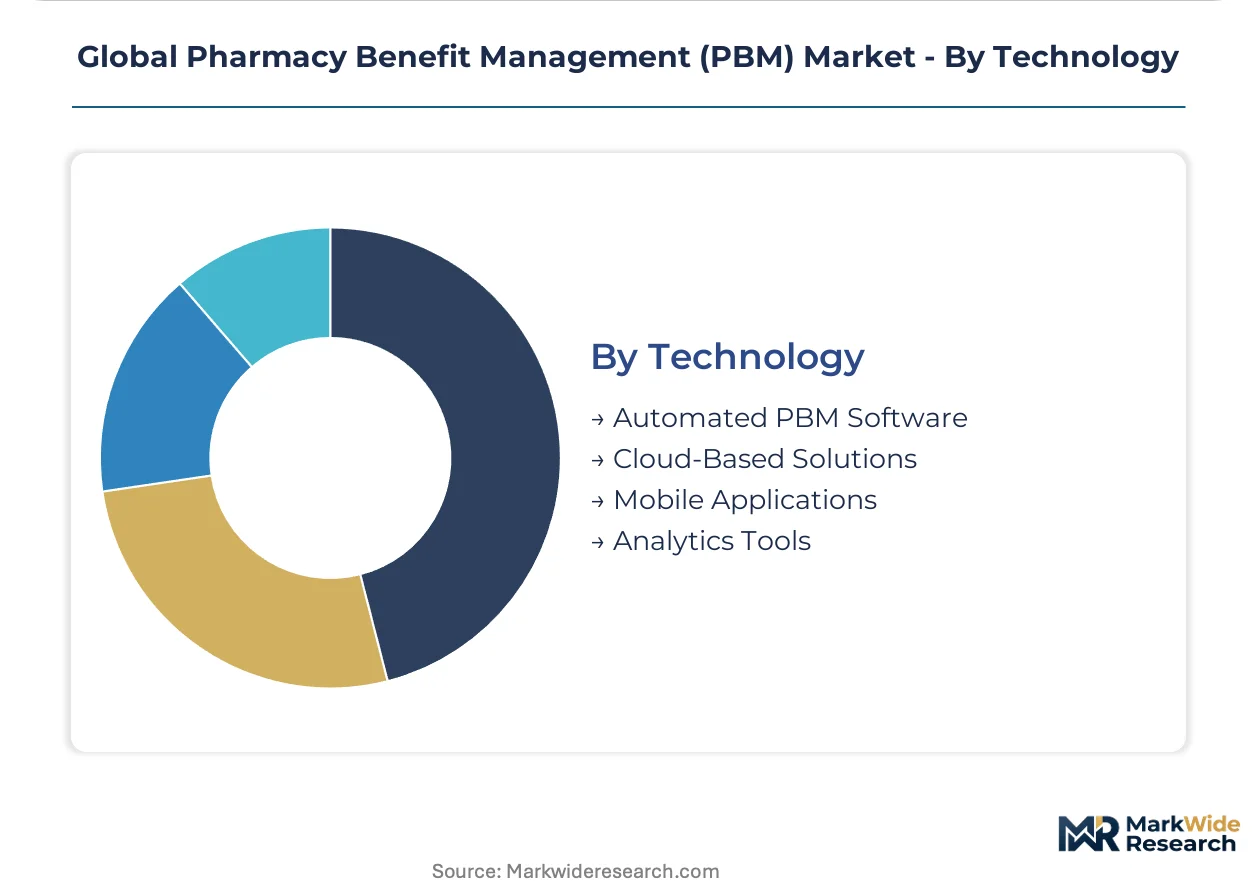
Technology:
Infrastructure investment separates cloud-native entrants from legacy platform incumbents burdened by technical debt.
- Cloud-Based Solutions:SaaS PBM platforms with elastic compute capacity support seasonal enrollment spikes and real-time analytics without on-premise data center capital expenditure. Health plans in the United States and Canada prioritize cloud deployments for disaster recovery and geographic redundancy.
- Automated PBM Software:Rules-based formulary management and rebate accrual engines automate previously manual configuration tasks. Robotic process automation reduces claims exception handling labor intensity.
- Mobile Applications:Member-facing apps with prescription refill scheduling, price lookup, and digital ID card display improve engagement metrics tied to Medicare Star Ratings and employer renewal decisions.
- Analytics Tools:Machine learning models trained on historical claims patterns predict high-cost claimant emergence and opioid misuse risk for proactive intervention program targeting.
Automated software retains the installed base; cloud solutions gain share fastest among new implementations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmacy benefit management services concentrate where employer-sponsored insurance and Medicare Part D enrollment dominate consumption, while technology infrastructure investments cluster in established healthcare IT corridors.
United States
Employer self-insurance expansion and Medicare Part D enrollment drive PBM demand concentration. The Inflation Reduction Act's drug price negotiation provisions reshape rebate structures and formulary design. The Minneapolis-Saint Paul corridor hosts Prime Therapeutics and UnitedHealth Group's OptumRx operations, where integrated care model development accelerates.
Germany
Statutory health insurance fund consolidation creates procurement scale for pharmacy management services. The EMA's centralized marketing authorization procedures align national formularies with cross-border rebate negotiation potential. The Rhine-Main region around Frankfurt anchors health insurer headquarters and digital health infrastructure investment.
United Kingdom
NHS England's integrated care board restructuring opens procurement channels for medication optimization services. NICE technology appraisals determine formulary placement for high-cost biologics across regional commissioning groups. London's health tech cluster attracts PBM software vendors targeting NHS pharmacy informatics contracts.
Canada
Provincial drug benefit programs and private employer plans generate dual-track PBM demand. Health Canada's drug pricing review board investigations influence manufacturer rebate negotiations for public formularies. The Toronto-Waterloo corridor concentrates health IT development and pharmacy benefit platform engineering talent.
Japan
Aging demographics and biologic drug reimbursement expansion drive pharmacy cost management demand. PMDA's regenerative medicine and gene therapy approval pathways require specialized patient management infrastructure. The Tokyo-Osaka corridor hosts pharmaceutical distributor consolidation and hospital chain pharmacy integration initiatives.
Global Pharmacy Benefit Management (PBM) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered service segments. Three vertically integrated health insurers dominate transaction volume through captive PBM operations. Strategic imperatives center on cloud platform migration and specialty pharmacy credentialing expansion. Consolidation pressure intensifies as employer purchasers demand unbundled transparency unavailable from legacy bundled contracts.
Within the integrated health system tier, CVS Health, UnitedHealth Group's OptumRx, and Express Scripts exemplify divergent structural approaches to pharmacy benefit control. CVS Health leverages retail pharmacy density for formulary enforcement. OptumRx embeds pharmacy services within broader care management workflows. Express Scripts anchors large employer accounts through centralized fulfillment infrastructure. Each represents a distinct archetype of how scale and channel configuration translate to rebate capture efficiency.
| Leading Market Players |
|---|
| Express Scripts |
| CVS Health |
| OptumRx |
| Prime Therapeutics |
| MedImpact Healthcare Systems |
| Humana Pharmacy Solutions |
| Magellan Health |
| Anthem |
| Centene Corporation |
| Others |
Supply & Pricing Matrix
Pass-through rebate arrangements versus retained-spread pricing models bifurcate PBM contracting structures, with self-insured employers demanding transparent administrative fees while Medicare Part D plans absorb opaque rebate retention. This divergence concentrates supply chain control among vertically integrated incumbents in the United States who can cross-subsidize transparent employer pricing with retained manufacturer rebates.
Pricing Analysis
Margin tightening in employer-sponsored segments reflects unbundling pressure as Fortune 500 corporations negotiate direct PBM contracts with explicit spread pricing disclosure. Transaction-based per-claim fees and retained rebate volumes dominate revenue models, with price differentiation tracking formulary control intensity and specialty pharmacy credentialing depth. Cost-down pressure on mail-order fulfillment accelerates because cloud-native entrants undercut legacy platform maintenance overhead. Self-insured employers exhibit highest price sensitivity; Medicare Advantage plans demonstrate lowest sensitivity due to actuarial soundness buffers.
Supply Chain Analysis
Workforce availability constraints in United States health IT corridors and Indian software engineering hubs shape platform development capacity for cloud-native PBM systems. Supply concentration centers on the United States for integrated insurer-PBM operations, India for claims processing back-office functions, and Ireland for European pharmaceutical distribution coordination. Raw material dependencies include proprietary formulary databases, NCPDP standard compliance modules, and manufacturer rebate contract repositories. Single-source vulnerability permeates limited distribution drug networks for gene therapies. Distribution runs through captive specialty pharmacies, retail network agreements, and direct-to-patient mail-order channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PBM market operates as a cost-of-compliance story where Medicare Part D actuarial soundness requirements and state-level rebate transparency laws erect regulatory moats favoring incumbents with dedicated compliance infrastructure.
For Market Incumbents: Lock in employer direct contracting relationships through transparent pass-through rebate arrangements before cloud-native modular vendors capture self-insured accounts. Expand captive specialty pharmacy credentialing for limited distribution drug networks to defend against disintermediation from manufacturer hub services. Vertical integration of data analytics capabilities anchors formulary control against unbundled competitors. For New Entrants and Emerging Players: Cloud-native real-time claims adjudication platforms offer a technology-first wedge into mid-market employer segments underserved by legacy batch-processing incumbents. White-space targets include standalone specialty pharmacy management modules for regional health plans and digital therapeutics distribution infrastructure for FDA-cleared prescription software. A consortium-based go-to-market angle aggregates purchasing power among self-insured public sector employers. For Investors and Strategic Acquirers: Re-rating potential sits with cloud-native modular PBM specialists given employer procurement fragmentation toward best-of-breed component sourcing. Long-term viability over the next decade hinges on API interoperability and real-time analytics differentiation rather than captive pharmacy assets. Monitor FTC vertical integration scrutiny intensity as an inflection indicator for forced divestiture opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Migration | API-driven architectures enable real-time eligibility verification demanded by Medicare Star Ratings. |
| Specialty Pharmacy Credentialing | Limited distribution drug network accreditation secures high-margin biologic dispensing exclusivity. |
| Rebate Transparency Compliance | California and Ohio disclosure mandates require operational retooling to retain employer contracts. |
| Digital Therapeutics Integration | FDA-cleared prescription software creates new formulary categories requiring PBM distribution infrastructure. |
| International Market Entry | NHS England integrated care board restructuring opens procurement for medication optimization services. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with PBM contract directors, health plan formulary managers, employer benefits consultants, and specialty pharmacy operations executives combined with secondary validation from CMS Medicare Part D enrollment files, state insurance commissioner rebate transparency reports, and FTC vertical integration investigation dockets. Bottom-up employer plan adoption modeling and top-down pharmaceutical expenditure trend analysis provided triangulation.
Segment-level granularity modeled service type unbundling patterns, technology deployment architecture, and end-user purchasing sophistication across the projection horizon. Product type segmentation captured channel economics divergence between specialty and retail fulfillment. CAGRs derived from pharmaceutical expenditure trend extrapolation and employer self-insurance penetration assumptions. Forecast inputs incorporated IRA Medicare price negotiation implementation pace and cloud platform switching cost trajectories.
Several conditions sit outside the modeled scope, including potential federal PBM reform legislation, FTC mandated divestiture outcomes, and breakthrough gene therapy approval volumes beyond current pipeline visibility. Forecasts reflect documented assumptions about regulatory implementation timelines and employer procurement pattern stability. Material deviation in FTC enforcement intensity or federal rebate pass-through mandates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
SGLT2 Inhibitors Market
Pharmaceuticals
Global DPT Vaccine Market
Pharmaceuticals
Traumatic Brain Injury Drugs Market
Pharmaceuticals
North America Hormone Replacement Therapy Market
Pharmaceuticals
Controlled Substance Market
Pharmaceuticals
North America Dipeptide Peptidase 4 (Dpp-4) Inhibitors Market
Pharmaceuticals
Global Finasteride Market
Pharmaceuticals
Global Lyophilized Injectable Drugs Market
Pharmaceuticals
Global Colorectal Cancer Therapeutics Market
Pharmaceuticals
Buprenorphine and Naloxone Market
Pharmaceuticals
North America Anesthesia Drugs Market
Pharmaceuticals
Latin America FMD Vaccine Market
Pharmaceuticals
Cyclosporine Drugs Market
Pharmaceuticals
Amylin Analogs Market
Pharmaceuticals
Antidepressant Drugs Market
Pharmaceuticals
India Pharmaceutical Contract Sales Organizations Market