
 Anti-Inflammatory Drugs Market | 2026-2036
Anti-Inflammatory Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Inflammatory Drugs Market Intelligence
Biologics-grade potency standards is reorganizing competitive expectations across the anti-inflammatory landscape. AbbVie Inc. anchors its position through deep vertical control over monoclonal antibody manufacturing infrastructure. Pfizer Inc. competes via broad-spectrum portfolio breadth spanning small-molecule and biologic modalities. Novartis AG differentiates through targeted R&D intensity in interleukin pathway inhibitors.
Anti-inflammatory drugs comprise pharmacological agents that modulate immune-mediated inflammatory cascades through cyclooxygenase inhibition, cytokine neutralization, or corticosteroid receptor agonism, typically formulated for oral bioavailability above 80% or subcutaneous depot delivery. Their primary commercial purpose centers on symptomatic control and disease modification in chronic autoimmune and degenerative joint conditions. Non-steroidal anti-inflammatory drugs occupy the largest volume tier due to generic saturation and primary-care accessibility, while disease-modifying antirheumatic drugs capture disproportionate margin pools through biologic pricing power and infusion-center administration requirements. COX-2 inhibitors retain a narrower but defensible niche in gastrointestinal-risk patient populations requiring selective cyclooxygenase-2 blockade.
The FDA's breakthrough therapy designation and the EMA's PRIME eligibility scheme are compressing development timelines and reshaping preclinical investment thresholds for novel anti-inflammatory mechanisms. ISO 13485 quality management standards and ICH Q5D cell-substrate guidelines govern biologics manufacturing consistency and lot-release protocols across regulated markets. Stakeholders must monitor how evolving pharmacovigilance requirements for immunogenicity reporting will reshape post-market surveillance obligations and label expansion strategies.
Market Dynamics
Biologics manufacturing concentration and FDA accelerated approval pathways are compressing development timelines while concentrating commercial power among vertically integrated antibody producers with captive cell-line infrastructure.
Growth Catalysts
- Breakthrough Therapy Designation:The FDA's accelerated pathway compresses Phase II-to-approval timelines for novel interleukin inhibitors, rewarding first-in-class mechanisms with earlier market access and extended exclusivity.
- Rheumatology Referral Network Expansion:United States specialty pharmacy networks concentrate prescribing volume for infusion-center biologics, creating efficient distribution channels that pull through high-margin therapies.
- Interleukin Pathway R&D:Targeted investment in IL-17 and IL-23 neutralization mechanisms is expanding addressable populations beyond TNF-alpha refractory patients into psoriatic arthritis and axial spondyloarthritis.
Market Restraints
- Bioreactor Capacity Bottlenecks:Stainless steel fermentation infrastructure for mammalian cell culture concentrates in Massachusetts, North Carolina, and Switzerland, creating single-source dependency for clinical-to-commercial scale-up.
- Immunogenicity Surveillance Burden:Post-market pharmacovigilance requirements for anti-drug antibody reporting under ICH E2E guidelines extend label maintenance costs and constrain indication expansion timelines.
- Biosimilar Price Erosion:European Medicines Agency-approved adalimumab and infliximab biosimilars are capturing hospital formulary slots, compressing originator pricing power in tender-driven procurement systems.
Strategic Opportunities
- Subcutaneous Depot Formulation:Self-administration technologies that eliminate infusion-center dependency open primary care and patient-direct channels, reducing healthcare system overhead and capturing pharmacy benefit manager volume.
- EMA PRIME Eligibility:Priority medicines designation offers enhanced scientific advice and accelerated assessment for novel anti-inflammatory mechanisms targeting unmet need in lupus and vasculitis populations.
- Real-World Evidence Integration:FDA's guidance on RWE for regulatory decision-making enables label expansion through patient registry data, compressing traditional randomized trial requirements for secondary indications.
Industry Challenges
- Cell-Line Development Expertise Scarcity:Mammalian expression system optimization and clone selection require rare hybridoma engineering capabilities concentrated among contract development organizations with decade-long queue backlogs.
- Cold Chain Integrity Complexity:Temperature excursions during subcutaneous biologic distribution through specialty pharmacy networks risk lot degradation and patient safety events requiring redundant monitoring infrastructure.
- Patent Thicket Navigation:Freedom-to-operate analysis for cytokine-neutralizing antibodies confronts dense intellectual property estates around Fc-engineering and glyco-optimization technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Inflammatory Drugs Market |
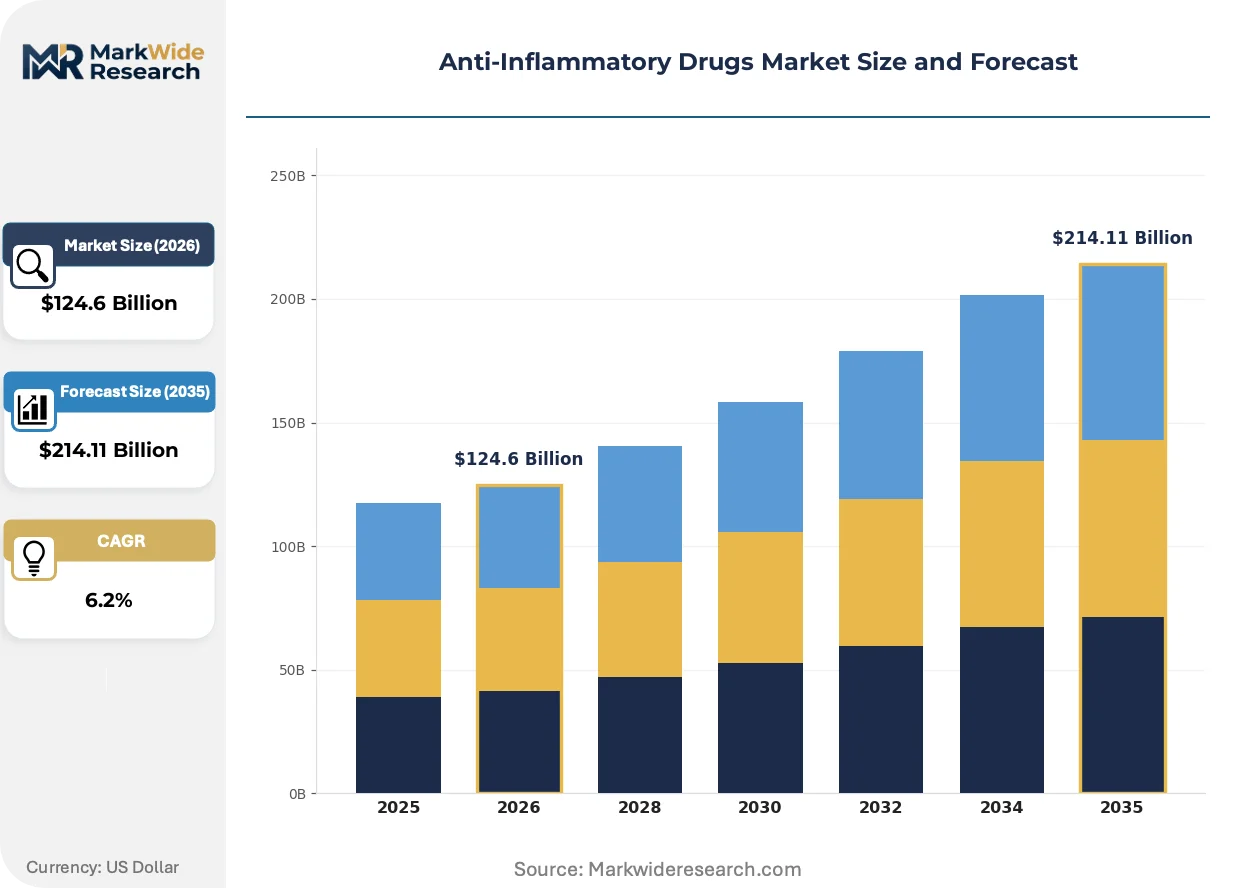
| Market Size in 2026 | $124.6 Billion |
| Market Size in 2035 | $214.11 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Steroidal Anti-Inflammatory Drugs, Corticosteroids, COX-2 Inhibitors, Disease-Modifying Antirheumatic Drugs, Analgesics Therapy Area: Rheumatoid Arthritis, Osteoarthritis, Psoriatic Arthritis, Ankylosing Spondylitis, Gout End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Research Laboratories, Home Healthcare Providers Delivery Mode: Oral, Injectable, Topical, Transdermal, Rectal |
| Companies Covered | AbbVie Inc., Johnson & Johnson Services, Inc., Pfizer Inc., Novartis AG, Merck & Co., Inc., GlaxoSmithKline plc, AstraZeneca, Amgen Inc., Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Inflammatory Drugs Market Strategic Shifts & Innovations
Mechanism diversification and administration route innovation are fragmenting competitive positioning, with subcutaneous delivery platforms and bispecific architectures challenging incumbent monoclonal antibody dominance.
Oral small-molecule JAK inhibitors are supplanting parenteral biologics in moderate rheumatoid arthritis segments where patients prioritize convenience over maximal efficacy. Rheumatology practices in the United States and Germany are adopting these agents as first-line advanced therapy before stepping up to TNF-alpha or IL-6 blockade. This substitution pattern is compressing biologic initiation rates and forcing infusion-center operators to diversify into administration of complex specialty generics.
The European Medicines Agency's PRIME eligibility scheme and FDA's breakthrough therapy designation are synchronizing regulatory feedback loops, compressing preclinical-to-Phase-I investment thresholds for novel mechanisms. Sponsors are front-loading CMC development and quality attribute characterization to meet accelerated assessment timelines. Small and mid-cap developers with platform technologies are capturing these designations disproportionately, reshaping partnership dynamics with large-cap commercialization partners.
Specialty pharmacy networks are consolidating patient onboarding and adherence monitoring functions that rheumatology practices previously managed. United States payers are mandating exclusive distribution through CVS Specialty, Accredo, and similar entities to capture rebate transparency and patient data. This channel compression concentrates pricing negotiation leverage among three national distributors while fragmenting prescriber influence over product selection.
Anti-Inflammatory Drugs Market Segmentation
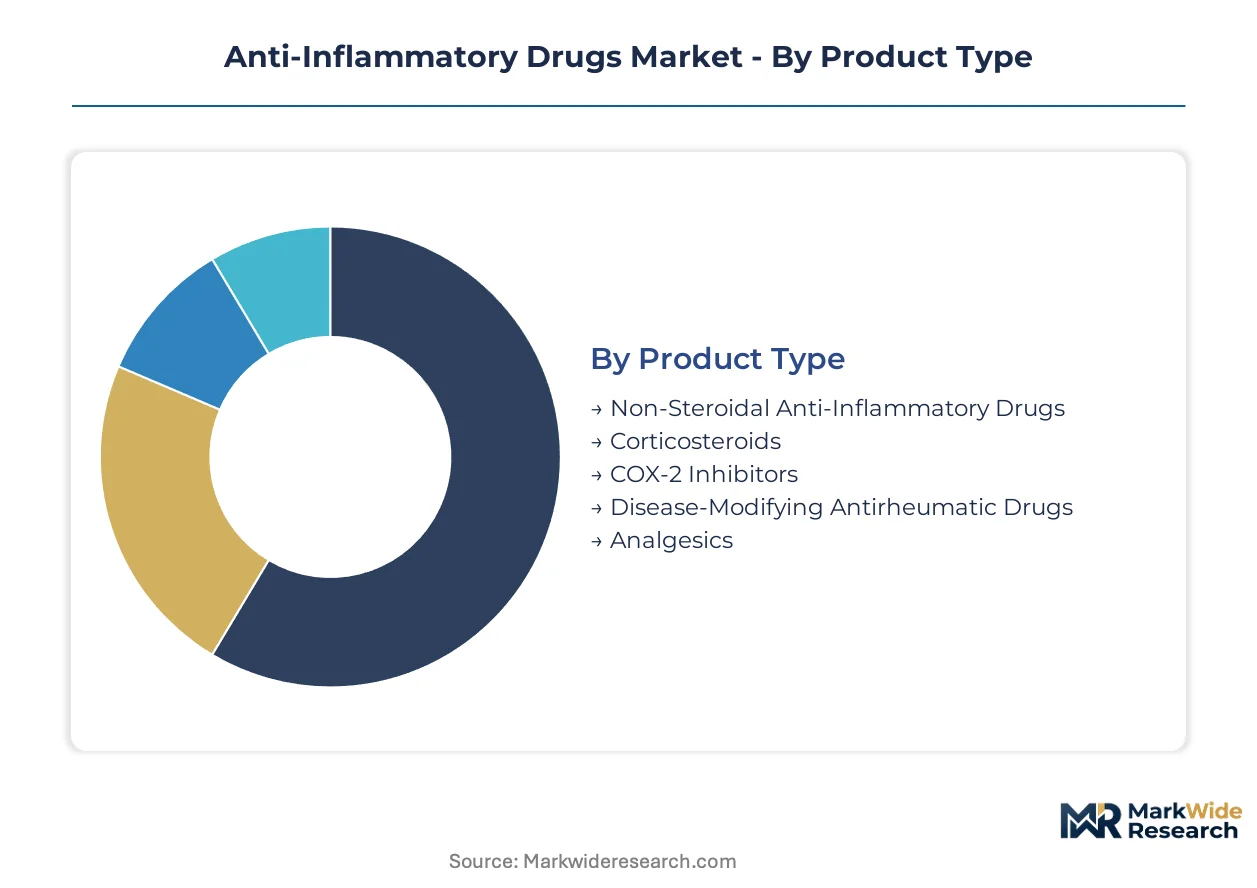
Channel economics and reimbursement pathways fragment demand across distinct product tiers in the anti-inflammatory drugs market. Therapy selection hinges on prescriber specialty, site-of-care requirements, and pharmacy benefit manager formulary positioning.
Product Type:
Distribution channels stratify sharply by product type, with hospital-based infusion centers capturing biologic volumes while retail pharmacies dominate small-molecule dispensing.
- Non-Steroidal Anti-Inflammatory Drugs:Generic oral formulations achieve near-universal pharmacy coverage through primary care prescribing. United States retail chains and European community pharmacies move highest volumes for osteoarthritis and acute pain flares, though gastrointestinal risk profiles constrain long-term utilization in elderly populations.
- Disease-Modifying Antirheumatic Drugs:Biologic DMARDs require cold-chain distribution through specialty pharmacy networks with captive infusion-center relationships. Massachusetts and North Carolina manufacturing clusters feed United States rheumatology referral centers where prior authorization requirements filter patient access.
- Corticosteroids:Intra-articular injections and oral taper packs flow through ambulatory surgical centers and urgent care facilities for acute inflammatory episodes.
- COX-2 Inhibitors:Selective cyclooxygenase-2 blockers retain formulary slots in gastroprotection-required patient segments, distributed through specialty pharmacy channels with risk evaluation and mitigation strategy compliance.
- Analgesics:Adjunct pain management agents complement anti-inflammatory regimens in multimodal protocols, dispensed primarily through retail and mail-order pharmacy.
By volume, non-steroidal anti-inflammatory drugs lead. By growth pace, disease-modifying antirheumatic drugs are expanding most quickly.
Therapy Area:
Cost tier stratification across therapy areas reflects biologic penetration depth and generic availability, with TNF-refractory populations commanding premium pricing.
- Rheumatoid Arthritis:First-line methotrexate failure triggers step-therapy protocols toward TNF-alpha inhibitors and IL-6 pathway blockers. United States commercial payers mandate 90-day retail pharmacy fills for oral JAK inhibitors before biologic authorization.
- Psoriatic Arthritis:IL-17 and IL-23 neutralization mechanisms capture patients with concurrent skin involvement, requiring dermatology-rheumatology co-management and specialty pharmacy coordination.
- Osteoarthritis:Hyaluronic acid injections and oral NSAIDs dominate this high-prevalence, low-acuity segment with minimal biologic penetration.
- Ankylosing Spondylitis:Axial spondyloarthritis classifications expanded IL-17 inhibitor addressable populations through MRI-based diagnosis protocols.
- Gout:Colchicine and urate-lowering therapy combinations manage acute flares and chronic prevention through primary care channels.
By patient volume, osteoarthritis dominates. By revenue intensity per treated patient, psoriatic arthritis leads.
End User:
Site-of-care economics and reimbursement rate differentials concentrate biologic administration in hospital outpatient departments and freestanding infusion centers.
- Hospitals:340B drug pricing program eligibility and buy-and-bill reimbursement models attract biologic infusion volumes to hospital outpatient departments. Academic medical centers in Boston, Basel, and Singapore anchor clinical trial recruitment for novel mechanisms.
- Specialty Clinics:United States rheumatology group practices with in-office infusion suites capture pharmacy benefit manager preferred network status through outcomes reporting contracts.
- Ambulatory Surgical Centers:Intra-articular injection procedures and same-day infusion protocols migrate to lower-cost settings where state licensure permits.
- Research Laboratories:Phase I-III clinical trial sites concentrate in regulatory-efficient jurisdictions with established investigator networks.
- Home Healthcare Providers:Self-administered subcutaneous biologics and prefilled syringe training services expand patient-direct delivery models.
By infusion volume concentration, hospitals lead. By patient convenience preference, home healthcare providers gain share fastest.
Delivery Mode:
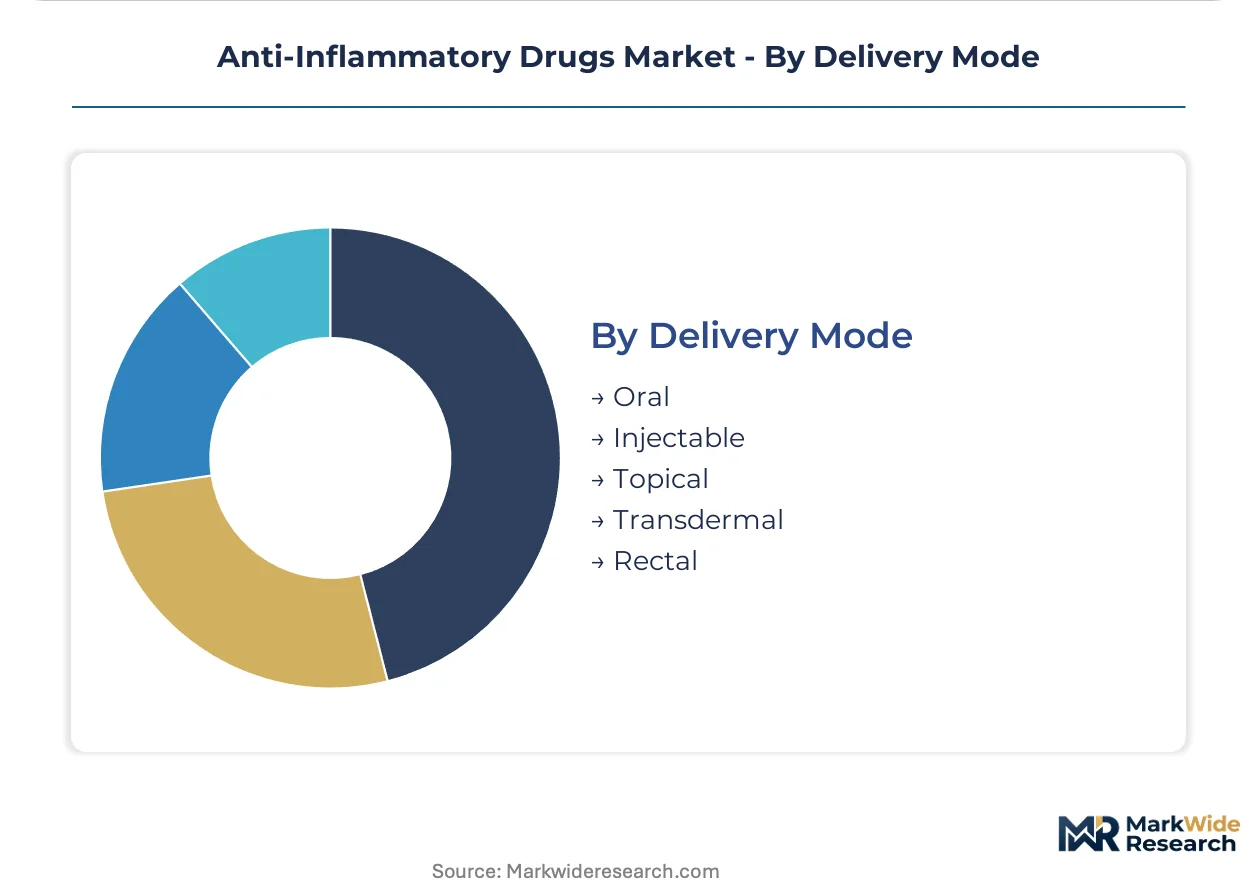
Patient adherence patterns and healthcare system overhead costs drive formulation innovation toward self-administration platforms.
- Injectable:Intravenous infusion and subcutaneous autoinjector formats command biologic pricing tiers with 28-day dosing intervals. Prefilled pen devices from Swiss and German device manufacturers reduce nurse training burden.
- Oral:Small-molecule JAK inhibitors and NSAIDs achieve highest primary care penetration through 30-day retail pharmacy dispensing with automatic refill programs.
- Topical:Diclofenac gels and corticosteroid creams serve localized inflammatory conditions with minimal systemic exposure.
- Transdermal:Patch delivery systems for chronic pain adjuncts remain limited by skin irritation rates and adhesion variability.
- Rectal:Suppository formulations retain niche utilization in pediatric and post-surgical populations with oral intake restrictions.
By prescription volume, oral formulations lead. By pipeline investment intensity, injectable biologics show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for anti-inflammatory therapies diverges sharply across markets. United States patients and payers absorb biologic premiums through specialty pharmacy networks, while European tender systems and Japanese reference pricing compress margins for originator molecules.
United States
Specialty pharmacy networks concentrate prescribing volume for infusion-center biologics through CVS Specialty and Accredo. FDA breakthrough therapy designation accelerates IL-17 and IL-23 inhibitor approvals, compressing Phase II-to-market timelines. Massachusetts and North Carolina manufacturing clusters supply rheumatology referral centers in Boston and Research Triangle Park with mammalian cell-culture products.
Germany
Hospital formulary committees and sickness funds drive biosimilar substitution for adalimumab and infliximab through tender-driven procurement. EMA PRIME eligibility supports accelerated assessment for novel mechanisms targeting lupus and vasculitis. Baden-Württemberg and Bavaria host contract development organizations with decade-long queue backlogs for hybridoma engineering.
Japan
PMDA sakigake designation mirrors FDA breakthrough pathways, front-loading regulatory consultation for first-in-class interleukin inhibitors. Reference pricing for biologics resets every two years, eroding originator revenue post-launch. Tokyo and Osaka anchor clinical trial recruitment for axial spondyloarthritis and psoriatic arthritis indications.
Switzerland
Swissmedic alignment with EMA centralized procedures enables rapid market entry for biologics approved in Brussels. Basel anchors Novartis manufacturing infrastructure for IL-6 pathway blockers. The country's bilateral agreements with the EU extend mutual recognition of GMP inspections, reducing regulatory duplication for antibody producers.
India
CDSCO accelerated approval pathways for drugs addressing unmet need in autoimmune disease are expanding domestic biologic development. Contract manufacturing organizations in Hyderabad and Bengaluru supply active pharmaceutical ingredients for oral JAK inhibitors. Export-oriented production of biosimilar infliximab serves regulated markets through partnerships with European distributors.
Anti-Inflammatory Drugs Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the anti-inflammatory landscape. Vertically integrated biologics manufacturers with captive cell-line infrastructure command premium pricing through manufacturing consistency and lot-release reliability. Small-molecule specialists compete on formulation convenience and primary-care accessibility. The competitive arena fragments across three strategic archetypes: monoclonal antibody platform holders, small-molecule JAK inhibitors, and emerging bispecific developers. Consolidation pressure manifests through strategic partnerships for subcutaneous depot technologies and real-world evidence generation capabilities.
Among North American platform holders, AbbVie Inc. and Pfizer Inc. occupy positions reflecting deep manufacturing infrastructure and broad-spectrum portfolio breadth respectively. Novartis AG anchors European R&D intensity in interleukin pathway inhibition. These three exemplify how geographic clustering of regulatory expertise and manufacturing capability shapes competitive positioning without guaranteeing market outcomes.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Johnson & Johnson Services, Inc. |
| Pfizer Inc. |
| Novartis AG |
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| AstraZeneca |
| Amgen Inc. |
| Sanofi |
| Others |
Cost & Logistics Intelligence
Biosimilar substitution in European hospital tenders is displacing originator biologic premiums while simultaneously concentrating manufacturing in Switzerland and Massachusetts, where captive cell-line infrastructure commands residual pricing power through lot-release reliability.
Pricing Analysis
Infusion-center administration fees and patient adherence monitoring contracts drive lifetime value capture beyond molecule pricing alone. Three-tier pricing structure across premium biologics, standard small-molecules, and economy generics stratifies by site-of-care requirements and prior authorization burden. Price compression runs through biosimilar tendering in Germany and France, where sickness funds mandate substitution. Hospital procurement managers exhibit highest price sensitivity; rheumatology practices with in-office infusion suites retain lowest sensitivity due to buy-and-bill margin capture.
Supply Chain Analysis
Massachusetts and North Carolina anchor mammalian cell-culture production for clinical-to-commercial scale-up. Stainless steel bioreactor infrastructure draws from Swiss precision engineering for single-use system components. Single-source dependency on Puerto Rico fill-finish capacity creates tariff exposure vulnerability. Distribution runs through specialty pharmacy networks with captive cold-chain monitoring to infusion centers and patient-direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a regulatory-entrenchment defensive moat, where FDA breakthrough therapy designation and EMA PRIME eligibility create multi-year head starts that compound through manufacturing scale and prescriber habit formation.
For Market Incumbents: Fortify position through backward integration into cell-line development capabilities currently bottlenecked at contract organizations with decade-long queues. Expand captive bioreactor capacity in Research Triangle Park to offset single-source risk from Massachusetts concentration. Prioritize real-world evidence generation for label expansion ahead of biosimilar entry.
For New Entrants and Emerging Players: Lead with subcutaneous depot formulations that eliminate infusion-center dependency and open primary care channels underserved by incumbent intravenous portfolios. Target axial spondyloarthritis and lupus populations where unmet need attracts accelerated regulatory pathways. Partner with national specialty pharmacy distributors for patient onboarding infrastructure.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract development organizations holding hybridoma engineering expertise and decade-long client relationships. Five-to-ten year viability hinges on platform technology durability rather than single-product revenue streams. Monitor FDA breakthrough therapy designation velocity as inflection indicator for partnership pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Breakthrough Therapy Designation Pursuit | FDA accelerated pathway compresses Phase II-to-approval timelines for IL-17 and IL-23 inhibitors. |
| Subcutaneous Formulation Development | Self-administration platforms open pharmacy benefit manager channels beyond infusion-center capture. |
| Real-World Evidence Integration | Patient registry data enables label expansion without traditional randomized trial requirements. |
| Biosimilar Manufacturing Partnership | European tender systems reward cost-positioned entrants with hospital formulary slots. |
| Specialty Pharmacy Network Exclusivity | CVS Specialty and Accredo concentrate patient data and rebate transparency for payer compliance. |
Research Approach
The analysis maps biologic manufacturing infrastructure, small-molecule formulation platforms, and specialty pharmacy distribution networks, each validated through drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Primary interview findings triangulate against FDA filings, EMA submissions, ClinicalTrials.gov protocols, and formulary database audits. Bottom-up patient-flow modeling and top-down revenue reconciliation ensure cross-validation across segmentation dimensions.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions include therapy area, product type, delivery mode, end-user site-of-care, and regional regulatory cluster. CAGRs derive from patient population epidemiology, treatment penetration curves, and pricing trajectory assumptions. Forecast inputs incorporate biosimilar entry timelines, prior authorization approval rates, and infusion-center capacity expansion plans.
Forecasts assume regulatory continuity in FDA breakthrough therapy pathways and EMA PRIME eligibility; material policy shifts toward stricter immunogenicity surveillance would require re-modeling. Recalibration cycles align with material shifts in biosimilar substitution rates and specialty pharmacy network consolidation events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Nasal Drug Delivery Technology Market
Pharmaceuticals
Oncology Small Molecule Drugs Market
Pharmaceuticals
Novel Drug Delivery Systems in Cancer Therapy Market
Pharmaceuticals
Global Nausea Medicine Market
Pharmaceuticals
Erectile Dysfunction Market
Pharmaceuticals
Respiratory Virus Vaccines Market
Pharmaceuticals
Rosuvastatin Market
Pharmaceuticals
Peptide Therapeutics Market
Pharmaceuticals
Sildenafil Drug Market
Pharmaceuticals
Lithuania Pharmaceutical Market
Pharmaceuticals
Global Human Rabies Vaccine Market
Pharmaceuticals
Meningococcal Vaccines Market
Pharmaceuticals
Betahistine Mesilate Market
Pharmaceuticals
Global Bispecific Antibody Therapeutics Market
Pharmaceuticals
Global Calcitonin Salmon Market
Pharmaceuticals
Global Tetanus Toxoid Vaccine Market