
 Global Endometriosis Drugs Market | 2026-2036
Global Endometriosis Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Endometriosis Drugs Market Foresight
A shortage of reproductive endocrinology specialists is redrawing how pharmaceutical firms allocate medical science liaison resources across key markets. AbbVie leverages its established gynecology sales infrastructure to sustain physician engagement in hormonal therapy categories. Bayer anchors its competitive position through deep manufacturing scale in progestin-based formulations. Pfizer competes by extending its commercial reach into outpatient care networks where diagnostic volumes are rising.
Endometriosis drugs comprise pharmaceutical agents that modulate estrogen-progesterone signaling, suppress ovarian steroidogenesis, or attenuate inflammatory mediators to reduce ectopic endometrial tissue proliferation and associated pelvic pain; these therapies are formulated as oral tablets, depot injections, transdermal systems, or implantable devices with release kinetics calibrated to maintain therapeutic hormone suppression over weeks to months. Gonadotropin-releasing hormone agonists dominate current prescribing patterns due to decades of clinical validation, though aromatase inhibitors represent the fastest-expanding segment as off-label use in refractory cases gains specialist acceptance. Progestins occupy a mature margin pool where generic competition has compressed returns, while selective estrogen receptor modulators remain confined to research-intensive settings awaiting definitive trial outcomes.
The FDA, EMA, and Japan's PMDA each enforce distinct preclinical and reproductive toxicology requirements that lengthen development timelines for novel endometriosis candidates and shape regional launch sequencing decisions. REACH compliance in Europe and evolving EPA pharmaceutical effluent standards in the United States add manufacturing cost layers that influence active pharmaceutical ingredient sourcing strategies. Stakeholders must monitor how payer formularies reconcile chronic pain management indications with fertility preservation goals as pipeline agents advance through late-stage evaluation.
Market Dynamics
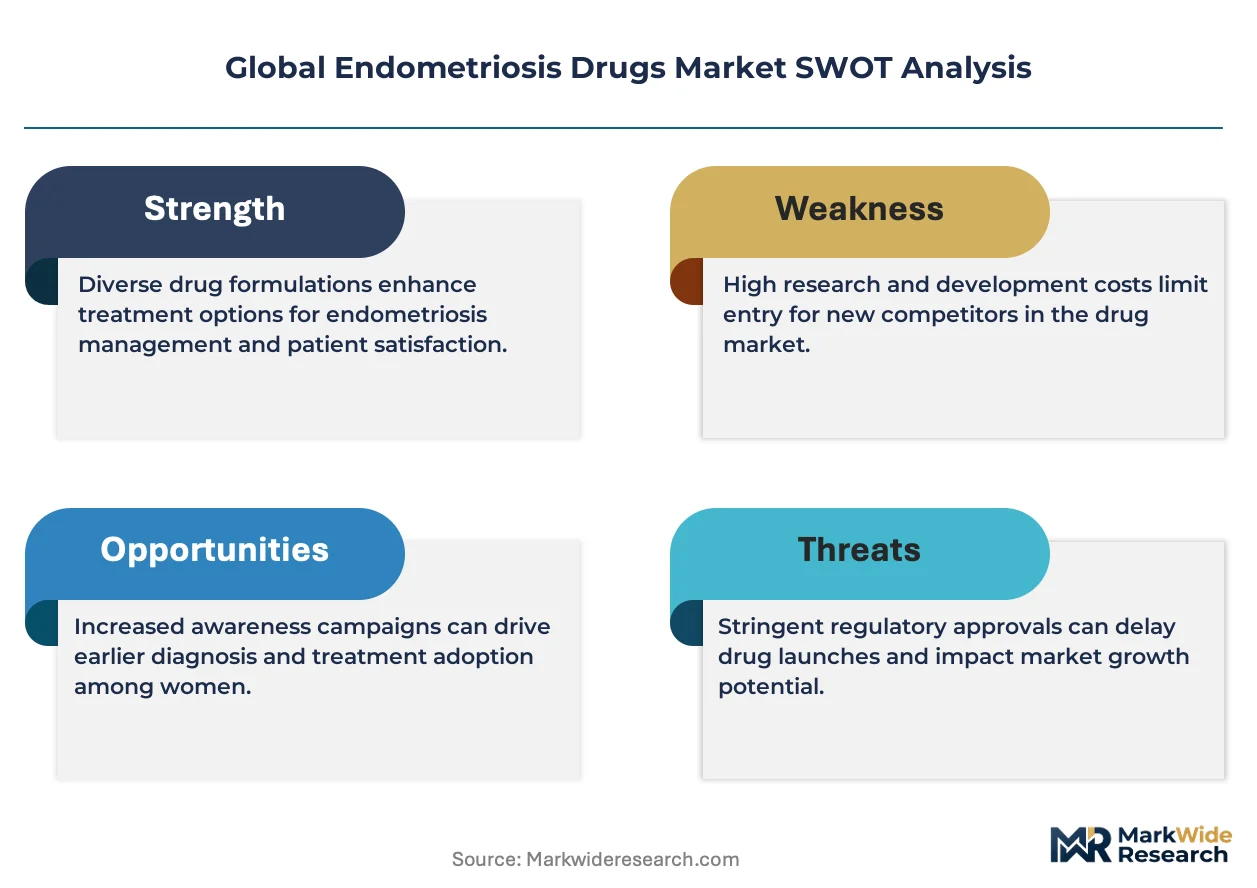
The central structural force reshaping the endometriosis drugs market is the regulatory bifurcation between fertility-sparing and pain-suppression indications, forcing developers to navigate divergent clinical trial endpoints across jurisdictions while payer formularies harden access criteria for hormonal suppressants.
Growth Catalysts
- Orphan Drug Pathways:The FDA's orphan drug designation accelerates review timelines for novel GnRH antagonists, reducing development risk for candidates targeting refractory disease populations.
- Diagnostic Volume Expansion:Rising laparoscopic confirmation rates in United States outpatient networks are expanding the addressable patient pool for maintenance hormonal therapy.
- Japan's PMDA Priority Review:The sakigake designation system compresses approval timelines for innovative endometriosis treatments, drawing pipeline investment toward Japanese market entry sequencing.
Market Restraints
- API Supply Concentration:Synthetic progestin active pharmaceutical ingredient production clusters in Chinese chemical manufacturing zones, exposing formulators to import tariff volatility and environmental compliance disruptions.
- Reproductive Toxicology Burden:The FDA's extended preclinical teratogenicity requirements for hormonal modulators add 18-24 months to IND-to-Phase I timelines, compressing patent-protected revenue windows.
- Generic Erosion:Patent expiry on depot leuprolide formulations has triggered price collapse in the GnRH agonist segment, eliminating margin pools that historically subsidized R&D for novel mechanisms.
Strategic Opportunities
- Germany's Digital Health Reimbursement:The DiGA fast-track pathway creates regulatory precedent for app-integrated adherence monitoring in chronic hormonal therapy, opening subscription revenue models.
- Aromatase Inhibitor Convergence:Combination protocols pairing letrozole with add-back estrogen are gaining specialist acceptance for deep infiltrating disease, expanding addressable severity segments.
- Direct-to-Patient Channels:Telehealth platforms in United States markets are compressing the diagnosis-to-treatment interval for hormonal therapy initiation, capturing patients who delay specialist referral.
Industry Challenges
- Reproductive Endocrinology Specialist Scarcity:Fellowship training pipeline constraints in United States academic medical centers limit the clinical investigator pool for Phase III enrollment.
- Legacy EMR Integration:Pelvic pain tracking modules in hospital information systems lack standardized severity metrics, fragmenting real-world evidence collection for payer negotiations.
- Cross-Border Licensing Complexity:Patent thickets around sustained-release depot formulations require multi-territory freedom-to-operate analyses that delay partnership timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Endometriosis Drugs Market |
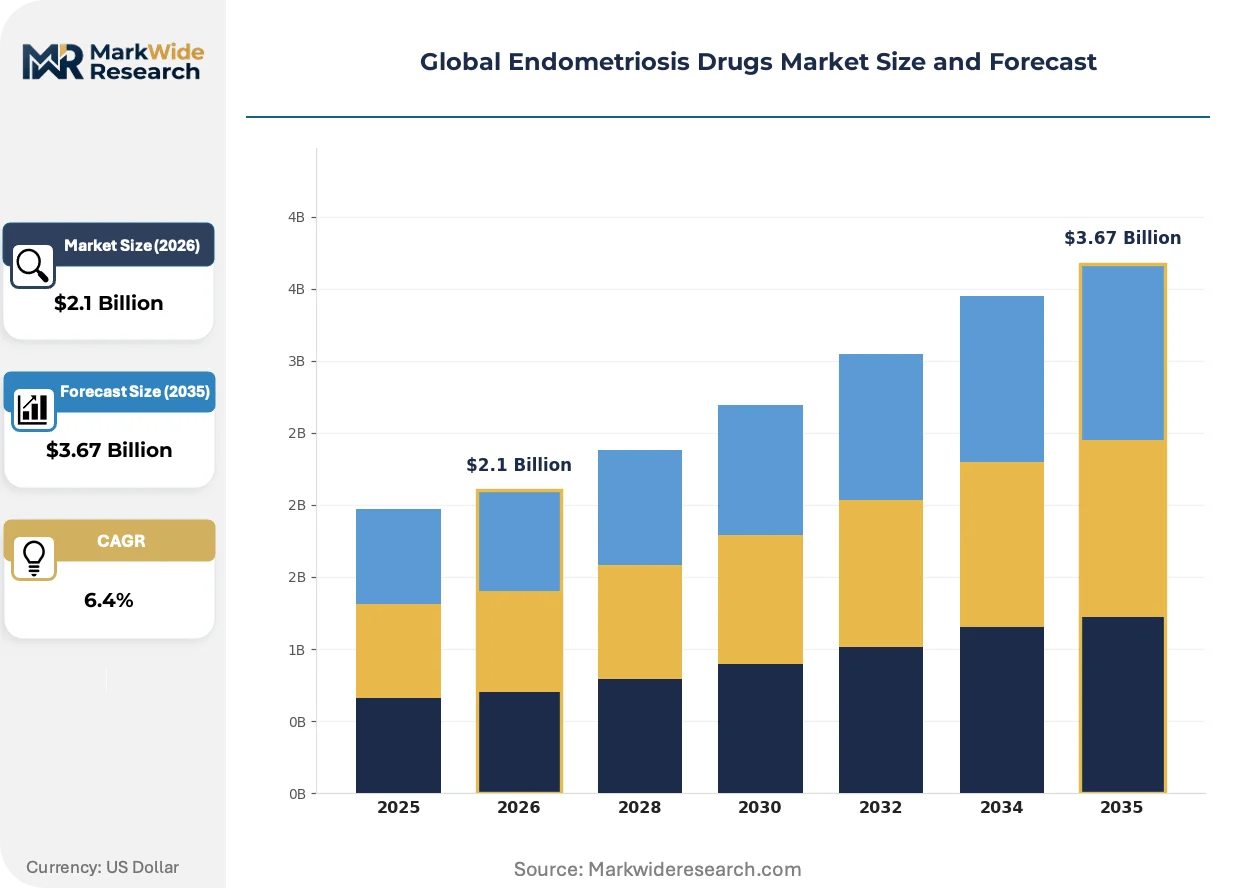
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gonadotropin-Releasing Hormone Agonists, Progestins, Aromatase Inhibitors, Non-Steroidal Anti-Inflammatory Drugs, Selective Estrogen Receptor Modulators Therapy Area: Pain Management, Hormonal Regulation, Fertility Enhancement, Menstrual Cycle Control, Inflammation Reduction End User: Gynecology Clinics, Specialized Hospitals, Fertility Centers, Outpatient Care Facilities, Research Institutes Delivery Mode: Oral Administration, Injectable Formulations, Transdermal Patches, Vaginal Suppositories, Implantable Devices |
| Companies Covered | AbbVie, Bayer, Pfizer, AstraZeneca, Gedeon Richter, Teva Pharmaceutical Industries, ObsEva, Takeda Pharmaceutical Company, Lupin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Endometriosis Drugs Market Shifts & Advancements
Oral GnRH antagonists are compressing the treatment paradigm for moderate-to-severe endometriosis, eliminating the flare-and-suppress cycle of agonist therapy while enabling patient self-administration that reshapes care site economics.
Elagolix and similar oral antagonists function by competitively blocking pituitary GnRH receptors without initial stimulation, achieving rapid estradiol suppression. Gynecology clinics in United States metropolitan markets are converting depot injection patients to oral regimens at accelerating velocity. This transition is supplanting the infusion center revenue model that historically anchored hospital outpatient department profitability in chronic pelvic pain management.
REACH compliance amendments in Europe are mandating environmental risk assessments for excreted hormonal active pharmaceutical ingredients, compelling manufacturers to invest in advanced wastewater treatment validation or reformulate for reduced metabolic persistence. The regulatory burden falls most heavily on progestin-based products with established manufacturing footprints, driving German and Swiss contract manufacturers to retrofit production lines with closed-loop solvent recovery systems.
Patient advocacy networks are demanding fertility preservation counseling as a mandatory precursor to hormonal suppression, pressuring prescribers to document reproductive life goals before initiating GnRH-modulating therapy. This behavioral shift is restructuring the United States prior authorization landscape, with commercial payers now requiring attestation of fertility discussion before approving extended-duration antagonist courses. The requirement is most visible in employer-sponsored plans administered through large Midwestern health systems where patient satisfaction metrics influence network contracting decisions.
Global Endometriosis Drugs Market Segmentation
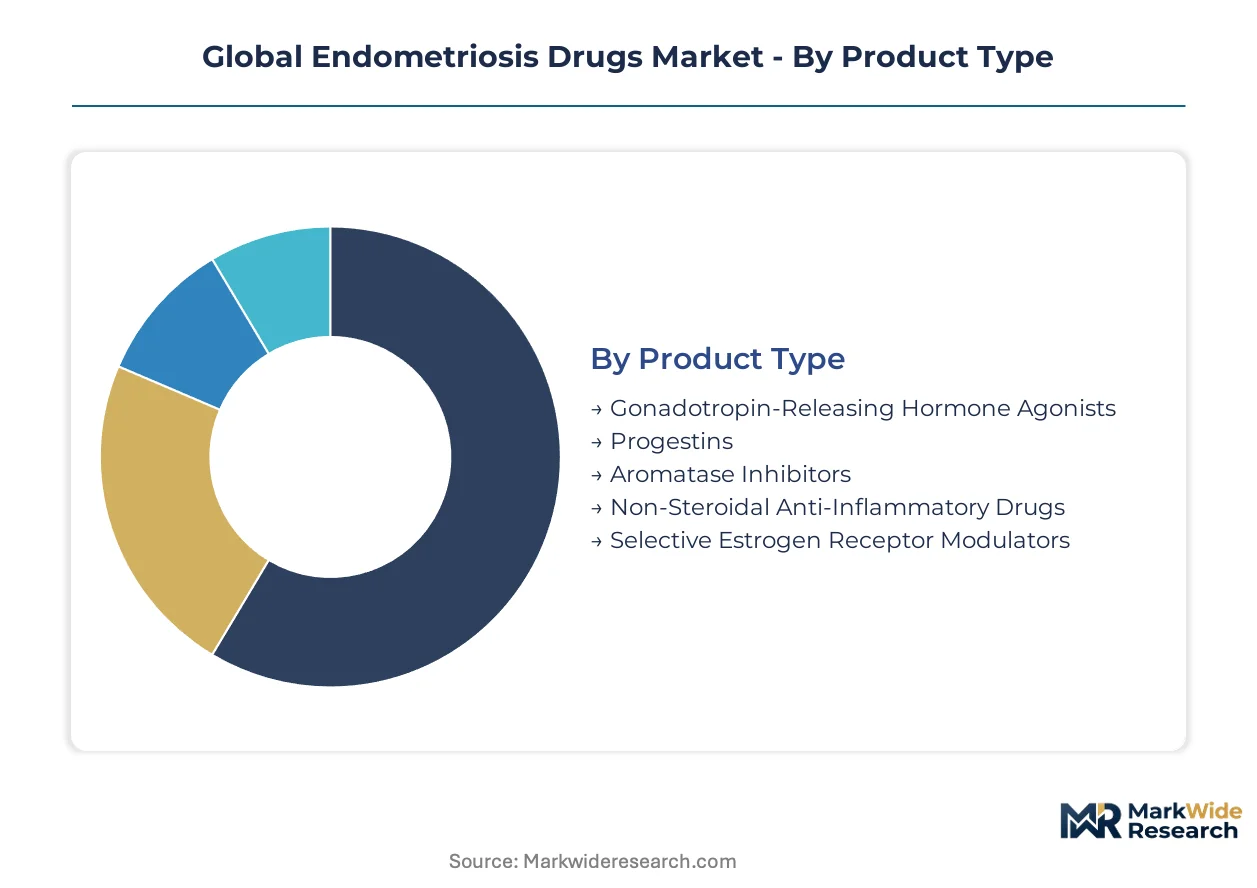
Segmentation in the endometriosis drugs market determines which therapeutic modalities reach patients through hospital formularies versus retail pharmacy channels. Prescribing patterns diverge sharply between fertility centers seeking ovulation-sparing options and pain clinics prioritizing rapid hormonal suppression.
Product Type:
Hospital outpatient departments in the United States and Germany channel GnRH agonists through infusion centers, while oral antagonists flow through retail pharmacy networks with telehealth prescribing support.
- Gonadotropin-Releasing Hormone Agonists:Depot leuprolide formulations deliver sustained pituitary desensitization through monthly or quarterly intramuscular injections. Demand concentrates in United States academic medical centers where prior authorization requirements favor established protocols with decades of safety documentation.
- Progestins:Synthetic progesterone derivatives including dienogest and norethindrone acetate suppress endometrial proliferation through direct receptor agonism. German gynecology clinics favor these for long-term maintenance therapy where bone density preservation outweighs ovulation suppression concerns.
- Aromatase Inhibitors:Off-label letrozole protocols are gaining traction in Japanese specialized hospitals for deep infiltrating disease refractory to first-line hormonal therapy.
- Non-Steroidal Anti-Inflammatory Drugs:Adjunctive naproxen and ibuprofen regimens address inflammatory pain mediators without hormonal disruption.
- Selective Estrogen Receptor Modulators:Experimental raloxifene applications remain confined to research-intensive settings awaiting definitive Phase III outcomes.
By volume, GnRH agonists lead through established hospital contracts. By growth pace, oral GnRH antagonists are expanding most quickly as patient self-administration preferences reshape channel economics.
Therapy Area:
Cost tiering separates acute pain management covered under standard pharmacy benefits from fertility-sparing protocols requiring specialized prior authorization.
- Pain Management:Chronic pelvic pain protocols drive the majority of United States commercial payer spending, with step-therapy requirements mandating NSAID failure before hormonal escalation.
- Hormonal Regulation:Estrogen-progesterone modulation represents the clinical standard across European markets where EMA guidelines emphasize bone health monitoring during extended suppression.
- Fertility Enhancement:Ovulation-sparing approaches command premium pricing in Japanese fertility centers where delayed childbearing trends elevate reproductive preservation demand.
- Menstrual Cycle Control:Cycle regulation applications concentrate in outpatient networks serving adolescent and perimenopausal demographics.
- Inflammation Reduction:Cytokine-targeting approaches remain investigational, with most prescribing limited to research protocols.
By reimbursement complexity, fertility enhancement requires the most documentation. By patient volume, pain management dominates prescribing.
End User:
Geographic clustering of specialized expertise determines which delivery settings capture novel therapy launches versus generic substitution.
- Gynecology Clinics:Independent practice networks in United States metropolitan markets are converting to oral GnRH antagonist prescribing fastest, displacing hospital-based infusion revenue.
- Specialized Hospitals:Academic medical centers in Germany and Japan retain dominance for complex surgical cases requiring integrated hormonal and excisional therapy.
- Fertility Centers:Reproductive endocrinology practices in Spain and Italy prioritize ovulation-sparing progestin protocols for patients pursuing concurrent conception.
- Outpatient Care Facilities:Community-based settings handle maintenance therapy refills with limited specialist oversight.
- Research Institutes:Phase III trial sites concentrate in United States coastal cities and Swiss university hospitals.
By prescription volume, gynecology clinics lead. By therapy innovation access, specialized hospitals capture pipeline agents first.
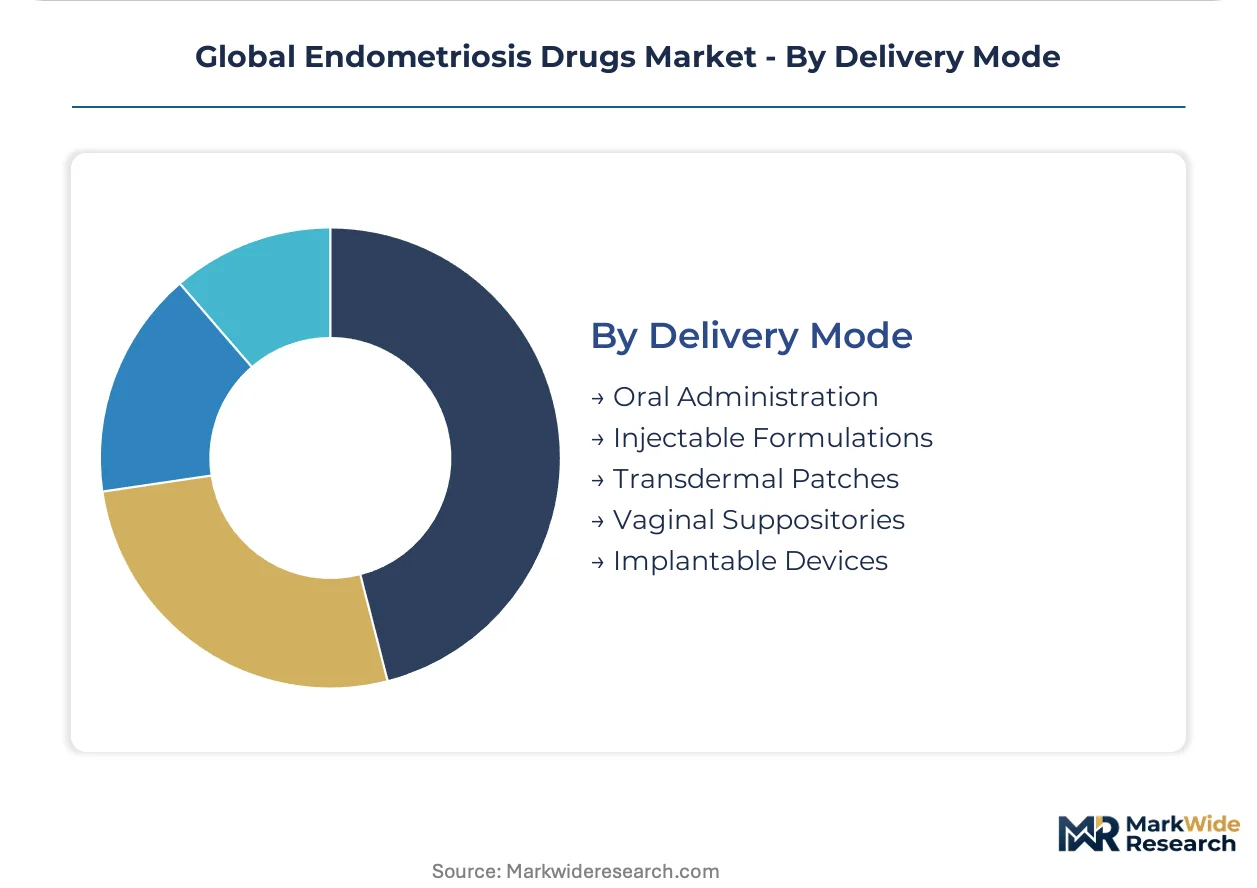
Delivery Mode:
Supply concentration in Chinese API manufacturing shapes which formulations achieve cost competitiveness versus import-dependent niche delivery systems.
- Oral Administration:Daily tablet regimens eliminate injection site reactions and enable patient-managed titration, driving fastest adoption in United States direct-to-patient channels.
- Injectable Formulations:Depot suspensions requiring cold-chain distribution concentrate manufacturing in European contract development organizations with validated aseptic filling capacity.
- Transdermal Patches:Estradiol-progestin combination patches face EMA environmental risk assessment requirements under REACH amendments.
- Vaginal Suppositories:Localized delivery systems remain limited to compounding pharmacies in select European markets.
- Implantable Devices:Subdermal etonogestrel implants compete with long-acting reversible contraceptives in overlapping patient populations.
By manufacturing scale, oral formulations lead. By clinical convenience innovation, implantable devices show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug designations for GnRH antagonists anchor United States market development, while EMA priority medicines pathways and Japan's PMDA sakigake system create parallel regulatory accelerants across distinct geographies.
United States
Commercial payers in employer-sponsored plans now mandate fertility preservation documentation before approving extended GnRH antagonist courses. The FDA's 18-24 month preclinical teratogenicity requirements compress patent-protected revenue windows for hormonal modulators. Gynecology clinic networks in metropolitan markets are converting depot injection patients to oral regimens at accelerating velocity.
Germany
The DiGA fast-track pathway establishes regulatory precedent for app-integrated adherence monitoring in chronic hormonal therapy. EMA guidelines emphasize bone health monitoring during extended estrogen suppression. Bavarian contract manufacturers are retrofitting production lines with closed-loop solvent recovery systems to meet REACH environmental risk assessment mandates.
Japan
PMDA's sakigake designation compresses approval timelines for innovative endometriosis treatments, drawing pipeline investment toward Japanese market entry sequencing. Delayed childbearing trends elevate reproductive preservation demand in fertility centers. The Kanto region's specialized hospitals retain dominance for complex surgical cases requiring integrated hormonal and excisional therapy.
United Kingdom
NHS England's chronic pain management frameworks are expanding diagnostic referral pathways for laparoscopic confirmation. MHRA post-Brexit regulatory autonomy enables faster adoption of novel depot formulations. London-based academic medical centers concentrate Phase III trial site capacity for pipeline hormonal therapies.
India
CDSCO accelerated approval pathways for orphan indications are attracting contract manufacturing investment for progestin active pharmaceutical ingredients. Domestic generic producers are expanding capacity for norethindrone acetate formulations. Maharashtra's chemical manufacturing zones are developing alternative synthetic routes to reduce import dependency from Chinese API clusters.
Global Endometriosis Drugs Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding hospital formulary placement through established gynecology sales infrastructure and the lower tier competing on manufacturing scale for mature hormonal categories. Strategic archetypes include diversified pharmaceutical conglomerates with chronic disease portfolios, European specialty pharma firms with progestin manufacturing heritage, and emerging biotech developers targeting refractory disease populations. Dominant competitive moves include backward integration into active pharmaceutical ingredient production and geographic expansion through telehealth-enabled direct-to-patient channels.
Among North American pharmaceutical conglomerates, AbbVie and Pfizer exemplify the integrated leader archetype through their gynecology sales infrastructure and outpatient network penetration. Bayer anchors the European manufacturing heritage tier with deep progestin formulation scale. These three entities occupy positions that reflect distinct strategic bets: AbbVie on oral GnRH antagonist conversion, Pfizer on retail pharmacy channel expansion, and Bayer on environmental compliance leadership under REACH amendments.
| Leading Market Players |
|---|
| AbbVie |
| Bayer |
| Pfizer |
| AstraZeneca |
| Gedeon Richter |
| Teva Pharmaceutical Industries |
| ObsEva |
| Takeda Pharmaceutical Company |
| Lupin |
| Others |
Supply & Pricing Matrix
Ninety-day API inventory buffers at European formulators now govern pricing power distribution between depot injection and oral tablet segments, compressing margins where Chinese synthetic progestin supply faces REACH environmental compliance disruptions. This lead-time exposure concentrates cost pass-through capability in manufacturers with backward-integrated hormone synthesis or validated alternative sourcing corridors.
Pricing Analysis
United States retail pharmacy pricing for oral GnRH antagonists runs 40-60% above German hospital procurement bands for equivalent monthly therapy days, reflecting divergent reimbursement density and prior authorization friction. Three-tier pricing structure across originator, authorized generic, and pure generic levels separates fertility-preservation protocols from chronic pain maintenance scripts. Cost compression in depot leuprolide is intensifying because patent expiry eliminated exclusivity premiums. Employer-sponsored plans show highest price sensitivity; Japanese fertility centers demonstrate lowest.
Supply Chain Analysis
Zhejiang Province chemical manufacturing zones anchor synthetic progestin API output, creating single-source vulnerability for European formulators dependent on just-in-time ocean freight. Active pharmaceutical ingredient production draws from norethindrone acetate, dienogest, and leuprolide acetate feedstocks. Tariff exposure on Chinese-origin hormone intermediates threatens cost stability for depot formulations. Distribution runs through hospital outpatient departments for infusion-center products and retail pharmacy networks for oral self-administered regimens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surgical excision and fertility-sparing hormonal protocols are substituting for chronic suppressive therapy in refractory patient populations, forcing pharmaceutical incumbents to defend prescription duration and reimbursement positioning against procedural alternatives.
For Market Incumbents: Compound gynecology sales infrastructure depth with telehealth-enabled direct-to-patient channel control to capture patients delaying specialist referral. Prioritize backward integration into GnRH peptide synthesis to offset API supply concentration risk from Chinese chemical manufacturing zones. Defend against oral antagonist substitution by documenting bone health outcomes that sustain depot agonist formulary placement.
For New Entrants and Emerging Players: Differentiate on fertility preservation counseling integration, capturing employer-sponsored plans where patient satisfaction metrics influence network contracting. Target Germany's DiGA fast-track pathway for app-integrated adherence monitoring subscription models. Penetrate aromatase inhibitor combination protocols for deep infiltrating disease severity segments underserved by first-line hormonal therapy.
For Investors and Strategic Acquirers: Long-term, this sits as a chronic disease maintenance play because delayed childbearing trends expand the addressable pool of patients requiring multi-year hormonal management before fertility intervention. Prioritize acquisition targets with validated manufacturing scale under REACH environmental compliance and established European hospital formulary placement. Watch FDA orphan drug designation velocity for GnRH antagonist pipeline candidates as inflection indicator for competitive intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Oral GnRH antagonist Phase III enrollment in United States academic medical centers accelerates regulatory submission timelines. |
| Regulatory Approval Pathway | PMDA sakigake designation in Japan compresses review periods for novel hormonal therapies. |
| Manufacturing Scale-Up | Bavarian contract manufacturers retrofit production lines with closed-loop solvent recovery for REACH compliance. |
| Pipeline Diversification | Aromatase inhibitor combination protocols expand addressable severity segments beyond first-line hormonal therapy. |
| Licensing Agreement | Telehealth platform partnerships in United States markets compress diagnosis-to-treatment intervals for oral therapy initiation. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases to triangulate market sizing across bottom-up prescription volume analysis and top-down payer spending estimates. Interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers informed pipeline positioning and access barrier assessment. Secondary validation incorporated SEC 10-K pharmaceutical segment disclosures and European customs trade data for API import volumes.
Segmentation dimensions modeled include therapeutic modality, administration route, patient population severity tier, and regional regulatory cluster across the projection horizon. CAGRs derive from patient volume forecasts calibrated to laparoscopic diagnostic incidence trends and therapy continuation rates. Industry-specific inputs encompass prior authorization approval velocity by payer archetype and fertility preservation counseling documentation requirements.
The analysis sits within stated boundaries; outcomes outside sustained reimbursement density for chronic hormonal suppression or accelerated generic entry timelines would require recalibration. Practitioners should keep alternative scenarios live as FDA reproductive toxicology requirements and EMA environmental risk assessments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Azithromycin Market
Pharmaceuticals
Traumatic Brain Injury Drugs Market
Pharmaceuticals
Radioligand Therapy (RLT) Market
Pharmaceuticals
Europe Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Spain OTC Drugs Market
Pharmaceuticals
Ciclopirox Olamine Market
Pharmaceuticals
Angiogenesis Inhibitors and Stimulators Market
Pharmaceuticals
Gastric Cancer Drugs Market
Pharmaceuticals
South Africa Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Anti-Radiation Drugs Market
Pharmaceuticals
Large Molecule Contract Development and Manufacturing Organization Market
Pharmaceuticals
OTC Cough, Cold & Allergy Medicine Market
Pharmaceuticals
Global Inhaled Antibiotics Market
Pharmaceuticals
Flumazenil Market
Pharmaceuticals
Global Vaccine Market
Pharmaceuticals
Herpes Labialis Treatment Market