
 Hospital Pharmaceuticals Market | 2026-2036
Hospital Pharmaceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
Hospital Pharmaceuticals Market Outlook
Multi-source API procurement is pivoting toward captive manufacturing networks among top hospital pharmaceutical suppliers. Pfizer sustains vertical integration across sterile injectable production, securing supply continuity for acute-care settings. Roche specializes in high-complexity biologics manufacturing, commanding premium positioning in oncology wards. Novartis anchors its hospital portfolio through advanced therapy medicinal product infrastructure, differentiating from commodity generic suppliers.
Hospital pharmaceuticals encompass prescription drug formulations administered within institutional settings, requiring sterile manufacturing under cGMP conditions with documented batch release protocols and cold-chain integrity for temperature-sensitive biologics. These products serve acute intervention, perioperative care, and inpatient chronic disease management where parenteral delivery ensures rapid bioavailability. Oncology biologics dominate margin pools due to patent-protected monoclonal antibodies and CAR-T cell therapies, while infectious disease injectables face accelerating generic substitution. Oral medications retain volume leadership in cardiology and neurology maintenance protocols, though inhalants represent the fastest-expanding delivery category in respiratory intensive care.
FDA cGMP enforcement and EMA's Good Manufacturing Practice inspections shape facility investment requirements, directly constraining which manufacturers qualify for hospital tenders. The EU AI Act and FDA's evolving guidance on AI-enabled drug discovery are creating new compliance layers for automated dispensing and clinical decision support systems. Stakeholders must monitor how decentralized manufacturing regulations in Germany and Japan reshape regional supply architectures.
Market Dynamics
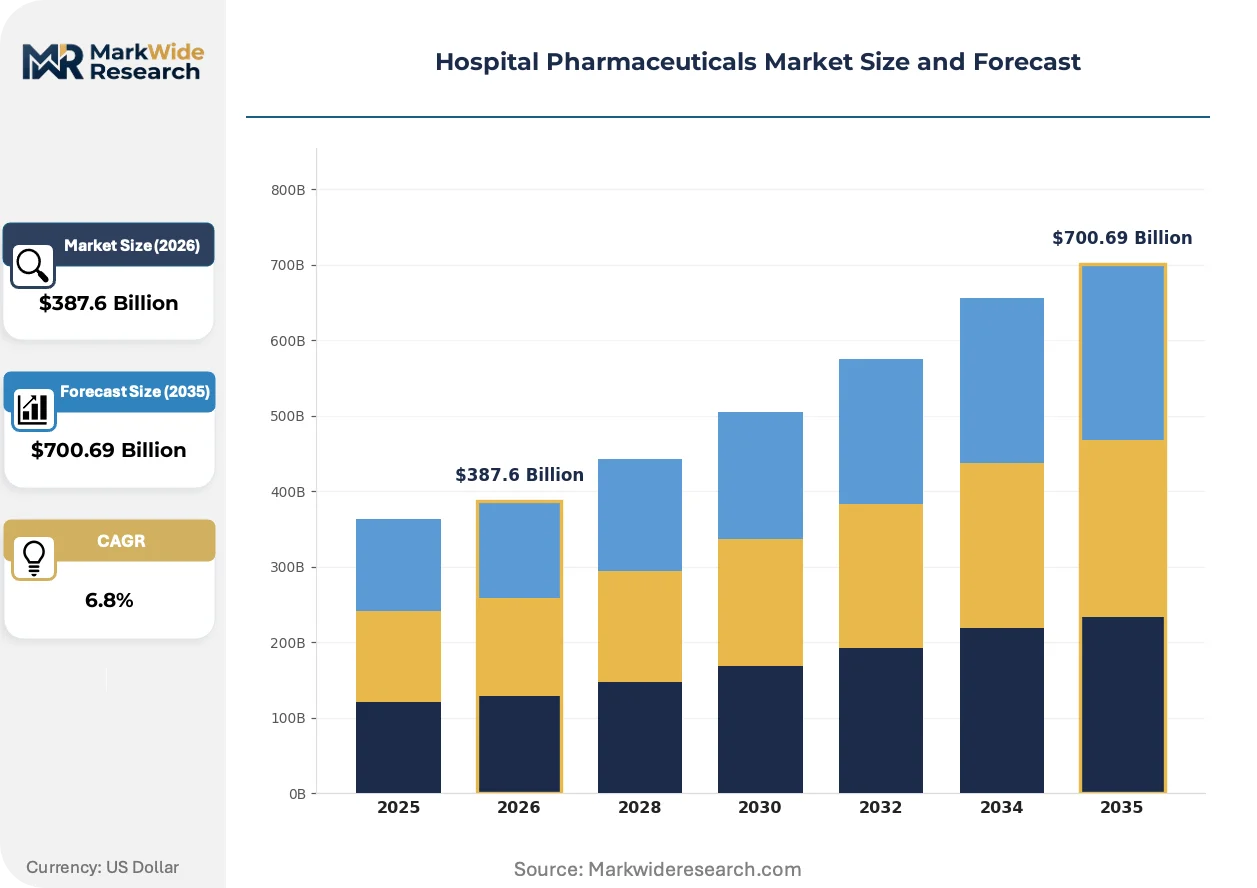
Hospital pharmaceutical supply chains are compressing around sterile injectable capacity as acute-care demand concentrates in tertiary centers requiring continuous biologic availability. This structural force is redrawing competitive boundaries between integrated manufacturers and commodity suppliers.
Growth Catalysts
- FDA Accelerated Approval Pathway:Breakthrough therapy designation compresses development timelines for oncology biologics, expanding hospital formulary access to novel monoclonal antibodies.
- Oncology Infusion Center Expansion:Tertiary care networks in the United States, Germany, and Japan are scaling biologic administration capacity, pulling demand for temperature-stable injectable formulations.
- CAR-T Cell Therapy Infrastructure:Advanced therapy medicinal product manufacturing requirements are creating captive production networks that secure supply continuity for cellular therapies.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing clusters in China create geographic vulnerability for hospital antibiotic and analgesic procurement.
- Cold-Chain Cost Escalation:Temperature-sensitive biologics require validated storage and transport infrastructure that inflates per-unit logistics expenditure by 40-60% versus standard pharmaceuticals.
- Generic Substitution Pressure:Off-patent infectious disease injectables face rapid commoditization as multi-source suppliers enter hospital tender processes.
Strategic Opportunities
- Decentralized Manufacturing:Point-of-care sterile compounding regulations in Germany and Japan enable regional production hubs that reduce transport risk for time-critical therapies.
- AI-Enabled Clinical Decision Support:FDA guidance on automated dispensing systems creates compliance pathways for integrated medication management platforms in acute-care settings.
- Respiratory Intensive Care Inhalants:Nebulized biologic delivery represents the fastest-expanding administration category as critical care units adopt targeted pulmonary therapy protocols.
Industry Challenges
- cGMP Compliance Talent Scarcity:Sterile manufacturing facilities face acute shortages of qualified quality assurance personnel capable of managing batch release documentation under FDA and EMA inspection protocols.
- Legacy System Integration:Automated dispensing technologies require costly retrofitting of hospital pharmacy infrastructure to achieve interoperability with electronic health record platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospital Pharmaceuticals Market |
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectables, Oral Medications, Topical Agents, Inhalants Therapy Area: Oncology, Cardiology, Neurology, Infectious Diseases Delivery Mode: Patient-Centric, Centralized, Decentralized, Automated Dispensing End User: Hospitals, Clinics, Research Facilities, Specialty Pharmacies |
| Companies Covered | Johnson & Johnson, Merck & Co., Pfizer, Roche, AbbVie, AstraZeneca, Novartis, Sanofi, Bristol-Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospital Pharmaceuticals Market Strategic Shifts
Biologic delivery modalities are fragmenting as hospital pharmacies adopt patient-specific manufacturing workflows. This shift is compressing traditional batch production economics while elevating real-time quality verification requirements.
Closed-system drug transfer devices are overtaking open-vial compounding in oncology pharmacy operations. These containment technologies eliminate hazardous drug exposure during monoclonal antibody preparation. Leading cancer centers in the United States and Germany are mandating their use for all cytotoxic handling. The structural consequence is a forced equipment upgrade cycle that is overtaking capital budgets previously allocated to inventory expansion.
EMA's Good Manufacturing Practice Annex 1 revision imposes stricter environmental monitoring requirements on sterile injectable facilities. Manufacturers must install continuous particle monitoring systems and enhanced barrier isolation technology. High-complexity biologics production in Switzerland and the Netherlands faces the steepest compliance cost escalation as existing cleanroom infrastructure requires wholesale reconstruction.
Hospital consortium purchasing is consolidating procurement authority into centralized pharmacy committees. Independent community hospitals are ceding formulary control to integrated delivery networks with specialized biologic contracting expertise. This behavioral shift is most pronounced in the United States, where health system mergers have concentrated buying power among ten national organizations controlling 40% of acute-care bed capacity.
Hospital Pharmaceuticals Market Segmentation
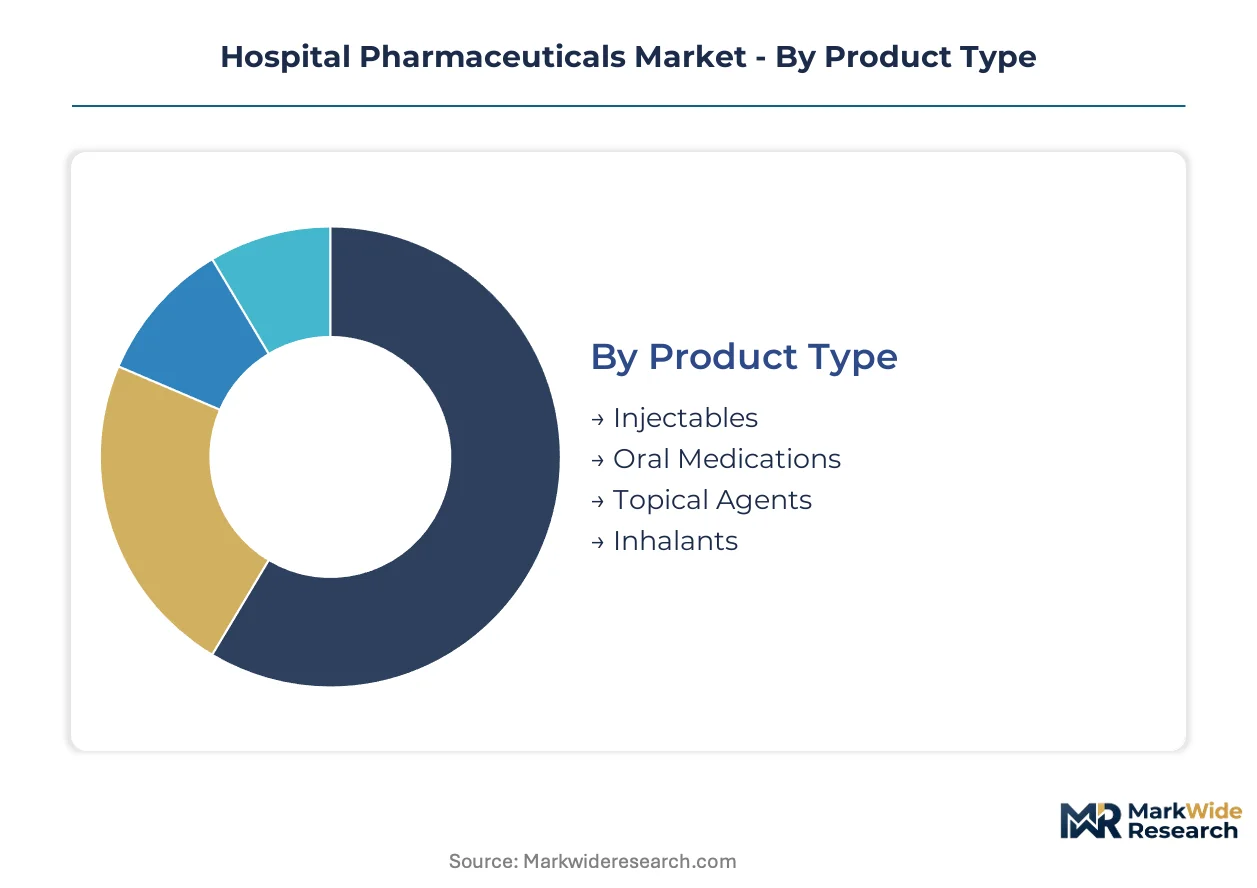
Hospital pharmaceutical procurement varies sharply by clinical setting and therapy complexity. Formulary committees weight sterility requirements, bioavailability demands, and cold-chain feasibility when segmenting purchasing authority across product categories.
Product Type:
Cost tiers separate acute-intervention formulations from maintenance therapies in hospital tenders.
- Injectables:Sterile parenteral formulations manufactured under cGMP with validated batch release protocols. Demand concentrates in United States oncology infusion centers and German tertiary care networks, pulled by CAR-T cell therapy administration requirements and continuous biologic availability mandates.
- Inhalants:Nebulized and dry-powder delivery systems for respiratory intensive care. United States critical care units are adopting targeted pulmonary biologics fastest, driving nebulizer-compatible formulation development.
- Oral Medications:Solid-dose and liquid formulations for cardiology and neurology maintenance protocols in inpatient settings.
- Topical Agents:Dermatological and perioperative preparations with localized action profiles for wound care units.
Volume sits with injectables; growth tilts toward inhalants.
Therapy Area:
Margin concentration follows patent protection duration and manufacturing complexity.
- Oncology:Monoclonal antibodies, checkpoint inhibitors, and cellular therapies requiring advanced therapy medicinal product infrastructure. Japanese cancer centers and Swiss university hospitals anchor demand, constrained by EMA Good Manufacturing Practice Annex 1 environmental monitoring requirements.
- Infectious Diseases:Antibiotic and antiviral injectables facing accelerating generic substitution in hospital tenders.
- Cardiology:Anticoagulants and antiarrhythmics for perioperative and intensive care management.
- Neurology:Antiepileptics and neuroprotective agents for stroke and trauma protocols.
Revenue concentrates in oncology; infectious diseases face steepest price compression.
Delivery Mode:
Supply chain architecture determines which configurations qualify for hospital accreditation.
- Automated Dispensing:Robotic medication management systems integrated with electronic health records. United States health systems and Dutch hospital networks are retrofitting pharmacy infrastructure to meet FDA guidance on AI-enabled clinical decision support.
- Centralized:Hub-and-spoke distribution from health system pharmacy committees controlling formulary access.
- Patient-Centric:Unit-dose packaging and bedside verification workflows reducing administration errors.
- Decentralized:Point-of-care sterile compounding enabled by Germany and Japan regional manufacturing regulations.
Capital deployment favors automated dispensing; regulatory momentum supports decentralized models.
End User:
Purchasing sophistication varies with scale and biologic handling certification.
- Hospitals:Acute-care institutions with integrated delivery network purchasing power and captive biologic storage capacity. United States health system mergers have concentrated procurement authority among ten national organizations.
- Specialty Pharmacies:Limited-distribution networks for temperature-sensitive oncology and rare disease therapies.
- Clinics:Ambulatory infusion centers expanding biologic administration capacity outside traditional hospital walls.
- Research Facilities:Academic medical centers with investigational drug services and early-access protocol management.
Transaction volume dominates hospitals; specialty pharmacies capture highest per-unit margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API manufacturing clusters in Zhejiang province and the Yangtze River Delta anchor pharmaceutical supply chains serving hospital networks across three continents. Finished formulation capacity concentrates in the United States, Germany, and Japan where tertiary care expansion drives sterile injectable demand. Cold-chain infrastructure investments in Switzerland and the Netherlands support high-complexity biologics distribution.
United States
Oncology infusion center expansion and CAR-T cell therapy infrastructure drive biologic procurement across tertiary care networks. FDA accelerated approval pathways compress development timelines for breakthrough monoclonal antibodies. The Boston-Cambridge corridor anchors advanced therapy medicinal product manufacturing with captive production networks securing supply continuity.
Germany
Decentralized manufacturing regulations enable point-of-care sterile compounding in regional hospital hubs. EMA Good Manufacturing Practice Annex 1 revisions impose continuous particle monitoring requirements on sterile facilities. The Rhine-Ruhr metropolitan region concentrates cleanroom reconstruction investments as existing infrastructure faces wholesale compliance upgrades.
Japan
PMDA streamlined approval processes for regenerative medicines accelerate hospital formulary adoption of cellular therapies. METI incentives support domestic biologics manufacturing capacity expansion. The Kansai region around Osaka anchors high-complexity biologics production with specialized containment infrastructure for cytotoxic handling.
Switzerland
Swissmedic inspection protocols exceed EMA baseline requirements for sterile injectable environmental monitoring. Basel-based manufacturing clusters command premium positioning in oncology ward supply chains. The country's dual-track regulatory alignment with both EU and independent Swissmedic standards creates specialized compliance expertise pools.
India
CDSCO manufacturing license reforms attract sterile injectable capacity investments serving export markets. PLI scheme incentives for active pharmaceutical ingredients reduce import dependency for hospital antibiotic procurement. The Hyderabad-Visakhapatnam corridor concentrates US FDA-inspected facilities with documented batch release protocols for parenteral formulations.
Hospital Pharmaceuticals Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers retrofit sterile facilities to meet EMA Annex 1 environmental monitoring mandates. The vendor base stratifies across three tiers: integrated biologics specialists with captive cell therapy infrastructure, multi-source generic injectable suppliers competing on tender price, and regional compounders serving decentralized manufacturing regulations. M&A activity concentrates on advanced therapy medicinal product capabilities while strategic partnerships secure API supply continuity.
Among integrated biologics manufacturers, Pfizer and Roche occupy positions exemplifying vertical control over sterile injectable production. Novartis anchors the advanced therapy infrastructure tier with specialized containment manufacturing. Johnson & Johnson represents the diversified health science archetype spanning pharmaceutical, medical device, and consumer health segments with hospital channel penetration across multiple therapy areas.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Merck & Co. |
| Pfizer |
| Roche |
| AbbVie |
| AstraZeneca |
| Novartis |
| Sanofi |
| Bristol-Myers Squibb |
| Others |
Value Chain & Pricing Dynamics
Cold-chain logistics expenditure for temperature-sensitive biologics flows through three distinct pricing tiers, with validated storage infrastructure costs separating premium oncology formulations from commodity injectables in hospital tenders across the United States, Germany, and Japan.
Pricing Analysis
Warranty and batch-release documentation bundling separates originator biologics from multi-source generics in hospital procurement negotiations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under FDA cGMP and EMA Good Manufacturing Practice protocols. Cost compression in infectious disease injectables is intensifying because Indian and Chinese API suppliers are entering tender processes with documented bioequivalence. Community hospitals within integrated delivery networks exhibit highest price sensitivity, while academic medical centers with captive CAR-T infrastructure accept premium positioning for supply continuity.
Supply Chain Analysis
API manufacturing for sterile hospital formulations rests on production clusters in Zhejiang province and the Yangtze River Delta in China, with secondary concentration in the Hyderabad-Visakhapatnam corridor in India. Key inputs include fermentation-derived active pharmaceutical ingredients, specialized containment equipment for cytotoxic handling, and single-use bioreactor systems. Single-source vulnerability concentrates in Chinese antibiotic intermediate production. Distribution runs through health system pharmacy committees controlling formulary access across consolidated United States networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital pharmaceutical supply chains are compressing into a vertical-integration race, with sterile manufacturing capacity and captive biologics infrastructure serving as the decisive upstream lever separating integrated manufacturers from commodity suppliers.
For Market Incumbents: To counter generic substitution pressure in infectious disease injectables, secure backward integration into fermentation-derived API production in India through CDSCO-inspected facilities. Augment this with EMA Annex 1 compliance investments in continuous particle monitoring systems for Swiss and Dutch biologics plants. For New Entrants and Emerging Players: Begin with decentralized manufacturing opportunities in Germany and Japan where point-of-care sterile compounding regulations enable regional production hubs. Target respiratory intensive care inhalants as the fastest-expanding delivery category with nebulizer-compatible formulation development partnerships. For Investors and Strategic Acquirers: FDA breakthrough therapy designation acceleration is the leading indicator that advanced therapy medicinal product infrastructure will command scarcity premiums. Position acquisition screening around cell therapy manufacturing capabilities with validated cold-chain networks. Watch EMA inspection enforcement intensity as the signal for compliance-driven consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA accelerated approval compresses oncology biologic development timelines for hospital formulary access. |
| Manufacturing Scale-Up | EMA Annex 1 cleanroom reconstruction in Switzerland secures environmental monitoring compliance for sterile injectables. |
| Backward Integration | Captive API production in India reduces geographic vulnerability for hospital antibiotic procurement. |
| Strategic Partnership | Closed-system drug transfer device mandates in United States cancer centers force equipment upgrade cycles. |
| Geographic Expansion | Decentralized compounding hubs in Germany and Japan reduce transport risk for time-critical cellular therapies. |
Study Parameters
FDA filings, EMA submission databases, and ClinicalTrials.gov records formed the secondary backbone, cross-referenced with formulary database audits and hospital procurement contract disclosures. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers validated demand assumptions. Bottom-up and top-down triangulation reconciled patient-volume projections with manufacturer capacity disclosures across sterile injectable and biologics segments.
Bottom-up modeling anchored volume estimates to tertiary care bed expansion in the United States, Germany, and Japan, while top-down analysis cross-checked against pharmaceutical spending patterns in acute-care settings. Segmentation across therapy area, product type, delivery mode, and end user informed the analytical framework over the projection horizon. CAGRs derived from patient population growth, regulatory approval velocity, and manufacturing capacity absorption rates.
Regulatory enforcement intensity, API supply disruption events, and health system merger consolidation are the dominant revision risks to modeled assumptions. Forecasts reflect documented stakeholder input and secondary source triangulation. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Postpartum Depression Drugs Market
Pharmaceuticals
Extended Oral Antibiotics Market
Pharmaceuticals
Steroid-Free Nasal Sprays Market
Pharmaceuticals
New Zealand Diabetes Drugs Market
Pharmaceuticals
Immunoglobulin Market
Pharmaceuticals
Next-Generation Immunology Drugs Market
Pharmaceuticals
Global Self-Administered Drugs Market
Pharmaceuticals
Teriflunomide Market
Pharmaceuticals
Global Muscle Relaxant Drugs Market
Pharmaceuticals
Ginkgo Leaf Extract and Dipyridamole Injection Market
Pharmaceuticals
Global Gout Therapeutics Market
Pharmaceuticals
Global Antipsychotic Drugs Market
Pharmaceuticals
Germany Opioids Market
Pharmaceuticals
Global Genitourinary Drugs Market
Pharmaceuticals
Middle East and Africa Psychedelic Drugs Market
Pharmaceuticals
Europe Oral Anti-Diabetic Drug Market