
 Paper Bag Box Market | 2026-2036
Paper Bag Box Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Bag Box Market Analytics
The capital-intensity gap between integrated mills and regional converters is bifurcating competitive outcomes in paper bag box supply. International Paper leverages its captive pulp supply and North American mill network to sustain margin resilience on large-format kraft orders. Mondi Group anchors European demand through integrated forestry-to-packaging operations that dominate block-bottom bag production for grocery retail chains.
A paper bag box is a rigid or semi-rigid paper-based container formed from multiply kraft or recycled paperboard, typically ranging from 80 to 350 grams per square meter, engineered for product protection, stacking strength, and printability in retail and logistics environments. Flat bags and block bottom bags lead volume, with block bottom variants commanding premium positioning in food service due to superior shelf stability and automated filling compatibility. Kraft paper and recycled paper substrates are expanding fastest as brand sustainability mandates and EPR fee structures shift procurement toward unbleached, post-consumer content grades.
The EU Packaging and Packaging Waste Regulation and FDA food-contact substance notifications shape material selection and barrier coating approvals across the value chain, with REACH compliance adding testing burdens for imported coated papers. The US EPA recycled content guidelines and state-level extended producer responsibility laws in California and New York are tightening domestic sourcing requirements. Stakeholders must monitor how diverging regional recycling infrastructure investments affect the economic viability of multi-material paper bag box designs versus mono-material alternatives.
Market Dynamics
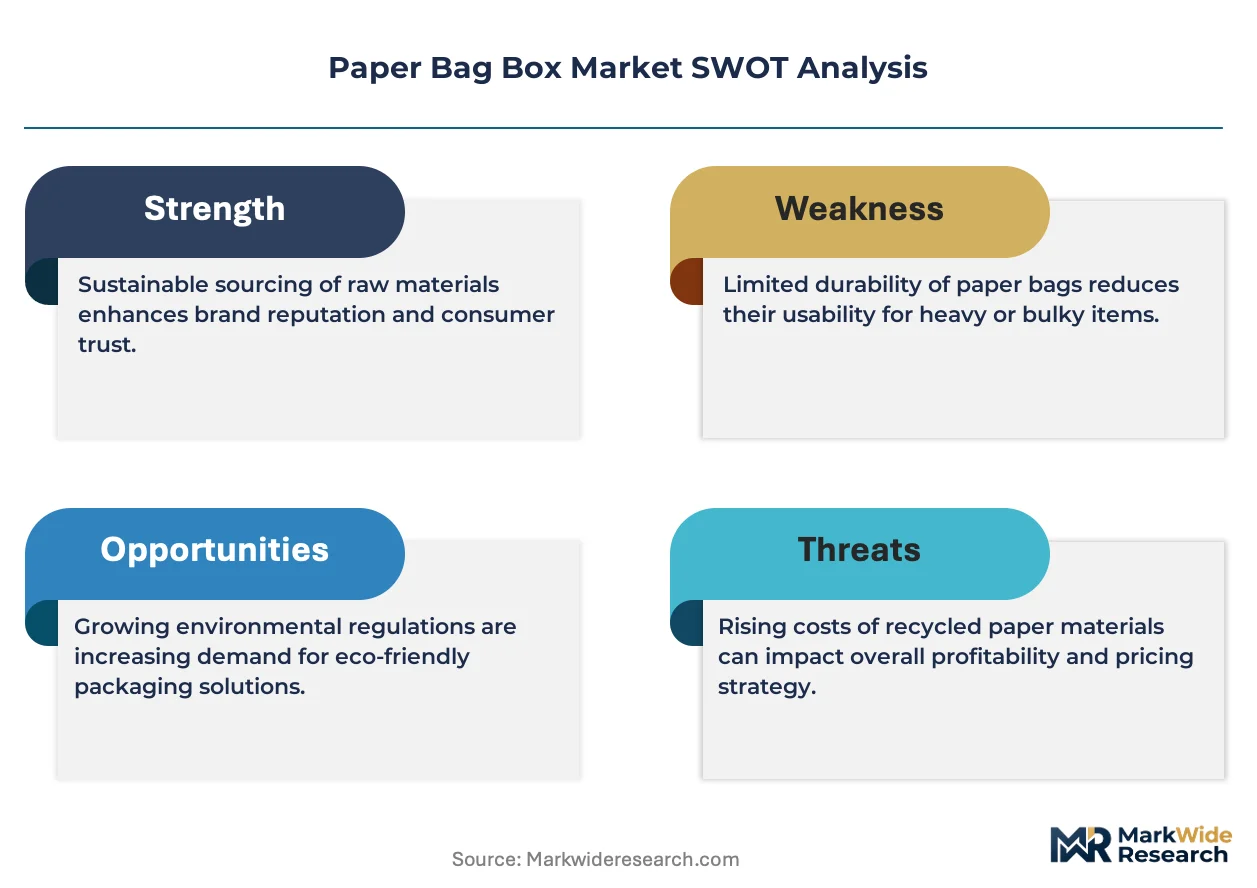
EU Packaging and Packaging Waste Regulation enforcement is compressing design cycles for converters, forcing rapid transitions from multi-material laminates to mono-material paper structures that satisfy EPR fee structures and material recovery targets.
Growth Catalysts
- E-commerce fulfillment standardization:Amazon and Zalando fulfillment centers are mandating paper-based void fill and protective packaging for third-party sellers, creating pull-through demand for block-bottom bag boxes in automated sortation environments.
- EPR fee restructuring:Germany's Verpackungsgesetz amendment imposes sharply higher fees on plastic versus paper packaging, tilting total cost of ownership calculations toward kraft-based alternatives for grocery delivery.
- Barrier coating chemistry advances:Water-based and bio-derived coatings from Clariant and BASF are achieving grease resistance parity with polyethylene, unlocking paper bag box penetration into prepared food service previously reserved for plastic.
Market Restraints
- Pulp cost volatility:Northern bleached softwood kraft pulp pricing swings of 30-40% within 18-month windows compress converter margins and destabilize long-term contract economics.
- Integrated mill concentration:North American containerboard supply concentrates among five producers, creating bottleneck risk for independent converters lacking captive pulp or backward integration into recovered fiber sourcing.
- Moisture sensitivity threshold:Uncoated kraft structures fail at 85% relative humidity, limiting paper bag box deployment in tropical logistics corridors and cold-chain applications without capital-intensive conditioning investments.
Strategic Opportunities
- India organized retail expansion:Reliance Retail and D-Mart are building cold-chain distribution networks that favor rigid paper containers over expanded polystyrene for fresh produce last-mile delivery.
- Pharmaceutical serialization compliance:EU Falsified Medicines Directive secondary packaging requirements favor tamper-evident paper bag boxes with integrated authentication features over flexible alternatives.
- Reusable bag-as-a-service models:Loop and similar circular economy platforms are piloting durable paper-based containers with deposit-return infrastructure, creating recurring revenue streams distinct from single-use sales.
Industry Challenges
- Barrier coating migration testing:FDA food-contact substance notification timelines extend 12-18 months for novel bio-based coatings, delaying product launches and freezing R&D pipelines.
- Automated filling line retrofit costs:Converting from plastic to paper bag box formats requires gripper, sealer, and dimensioning system replacements costing $2-4 million per production line.
- Recyclability certification fragmentation:Divergent testing protocols between How2Recycle, OPRL, and Blue Angel create compliance duplication for brands selling across US, UK, and German markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Bag Box Market |
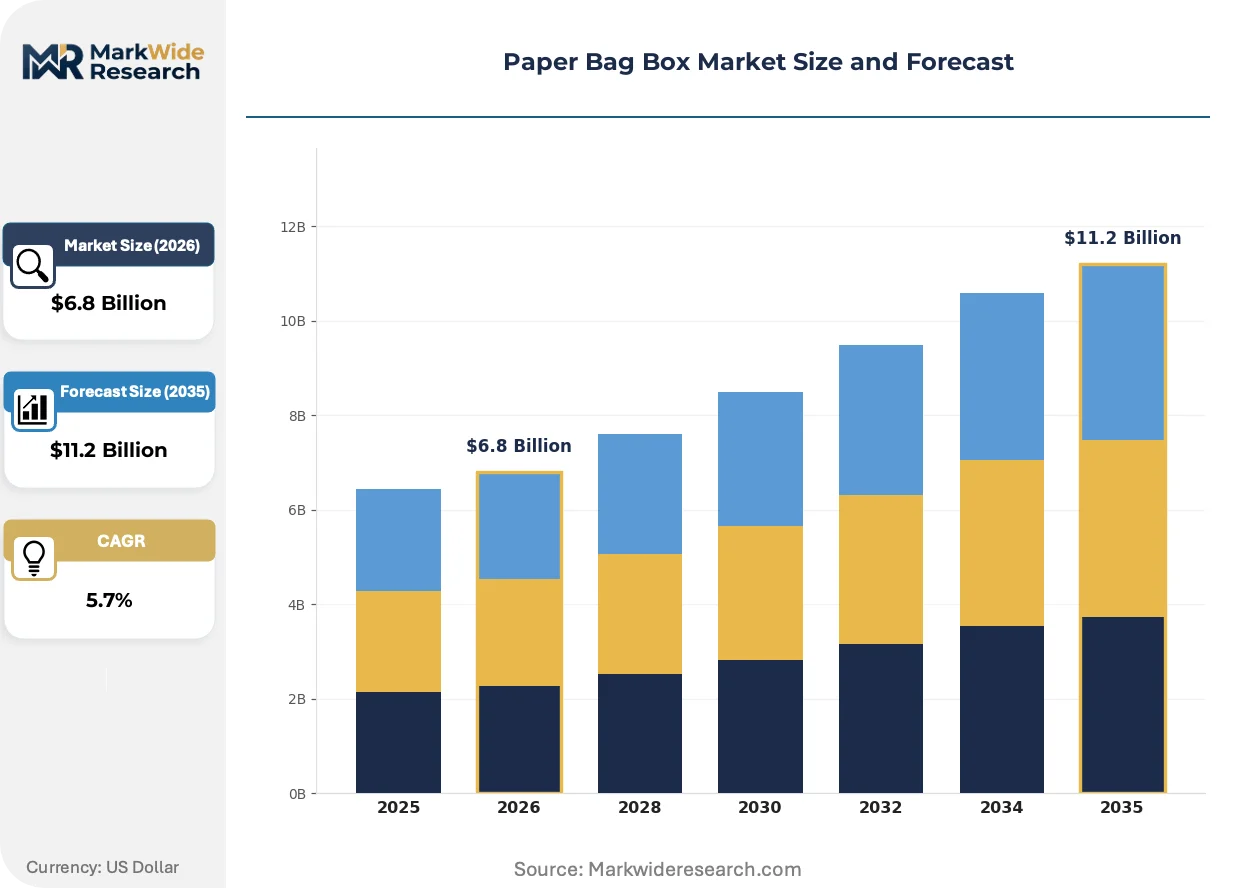
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Satchel Bags, Pouch Bags, Block Bottom Bags End User: Retailers, Food Service, E-commerce, Healthcare Material: Kraft Paper, Recycled Paper, Bleached Paper, Coated Paper Size: Small, Medium, Large, Custom Sizes |
| Companies Covered | International Paper, Mondi Group, Smurfit Kappa, WestRock, DS Smith, Oji Holdings Corporation, Stora Enso, Packaging Corporation of America, ProAmpac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Bag Box Market Evolving Landscape
Active redesign of substrate architecture and coating chemistry is compressing the performance gap between paper and plastic protective packaging, with automation compatibility emerging as the decisive specification criterion.
High-speed digital printing on kraft substrates is fragmenting the traditional divide between commodity unprinted volume and high-margin branded short runs. Nestlé and Unilever procurement teams are adopting variable-data printing for regional promotional campaigns, collapsing minimum order quantities from 50,000 to 500 units. This capability is fragmenting converter customer portfolios toward micro-segmentation and away from scale-driven commodity production.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating oil-and-grease-resistant fluorochemical coatings from food-contact paper packaging by 2026. ECHA enforcement is accelerating migration to silicone, clay, and bio-wax alternatives that require line-speed adjustments and heat-seal parameter revalidation. German bakery chains and French ready-meal producers are most exposed, with reformulation timelines compressing against certification deadlines.
Direct-to-consumer brand teams are consolidating specifications around mono-material paper structures that satisfy both curbside recyclability claims and automated sortation compatibility. Warby Parker and Allbirds packaging engineers are rejecting multi-layer laminates regardless of performance advantages, prioritizing end-of-life messaging consistency over functional optimization. This specification consolidation is most visible in US coastal metropolitan markets where municipal composting infrastructure remains underdeveloped relative to paper recycling streams.
Paper Bag Box Market Segmentation
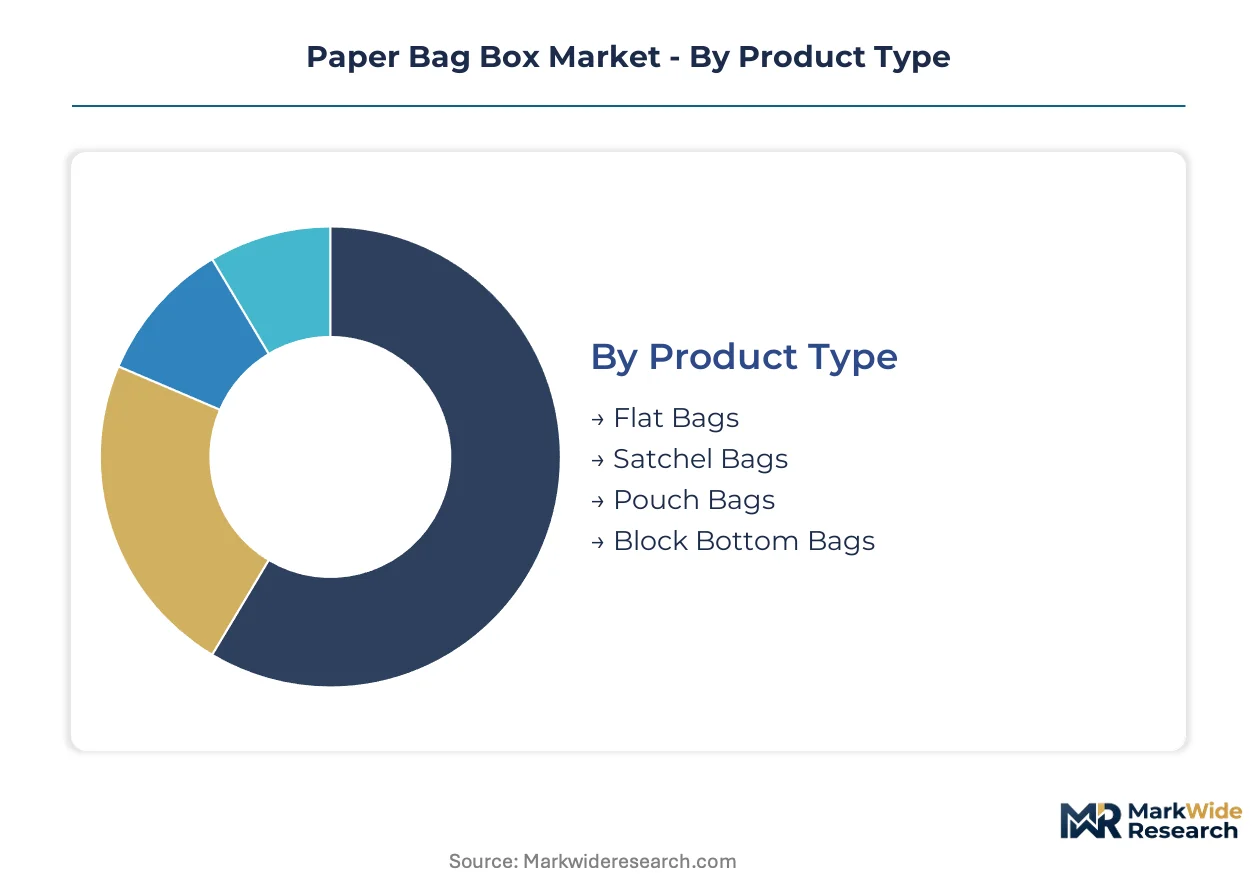
Paper bag box procurement splits sharply between commodity volume plays and specification-driven premium tiers. Converters must align capacity investments with where margin pools concentrate versus where tonnage flows.
Product Type:
Block bottom bags command the widest margin spreads due to automated filling compatibility and structural rigidity requirements.
- Flat Bags:Single-ply kraft constructions with glued or stitched closures dominate commodity retail carryout. German grocery chains and US dollar stores rotate procurement toward these for cost-sensitive high-volume applications where shelf presentation is secondary.
- Block Bottom Bags:Multi-ply constructions with folded rectangular bases provide self-standing stability for automated filling lines. French bakery cooperatives and Dutch meal-kit distributors specify these for vertical shelf placement and conveyor compatibility, paying premiums for precise dimension tolerance.
- Satchel Bags:Envelope-style closures with gusseted sides serve pharmaceutical sample distribution and luxury cosmetics.
- Pouch Bags:Flexible bottom-sealed formats without rigid structure suit loose-fill dry goods and promotional inserts.
Block bottom bags hold installed capacity. Flat bags are rotating up the share rankings in discount retail channels.
End User:
E-commerce fulfillment specifications are displacing traditional retail as the primary volume driver.
- E-commerce:Protective mailer formats with tear-strip openings and return-ready closures dominate third-party seller packaging mandates. Amazon fulfillment centers in Poland and Zalando logistics hubs in Germany specify paper-based void fill and rigid mailers, creating pull-through demand for crush-resistant kraft constructions.
- Food Service:Grease-resistant barriers and heat-seal compatibility unlock prepared meal and bakery applications. French ready-meal producers and German bakery chains specify clay-coated or bio-wax treated papers to meet ECHA fluorochemical restrictions.
- Retailers:Branded carryout and promotional packaging concentrates in supermarket and department store channels.
- Healthcare:Tamper-evident closures and serialization compatibility serve pharmaceutical secondary packaging under EU Falsified Medicines Directive requirements.
Food service holds installed capacity. E-commerce is climbing the fastest in procurement volume.
Material:
Unbleached and post-consumer grades capture pricing power as EPR fee structures penalize virgin content.
- Kraft Paper:Unbleached virgin pulp delivers tear strength and printability for heavy-duty applications. Nordic forestry-integrated producers supply German automotive parts distributors and Dutch agricultural cooperatives with specified burst strength ratings.
- Recycled Paper:Post-consumer fiber content satisfies California and New York extended producer responsibility thresholds. US corrugated converters blend recovered OCC with virgin kraft to balance cost and performance for Amazon and Target private-label packaging.
- Bleached Paper:Whitened pulp grades serve premium cosmetics and pharmaceutical branding requirements.
- Coated Paper:Polyethylene or bio-based barriers enable moisture and grease resistance for food contact.
Kraft paper holds installed capacity. Recycled paper is gaining share fastest under regulatory pressure.
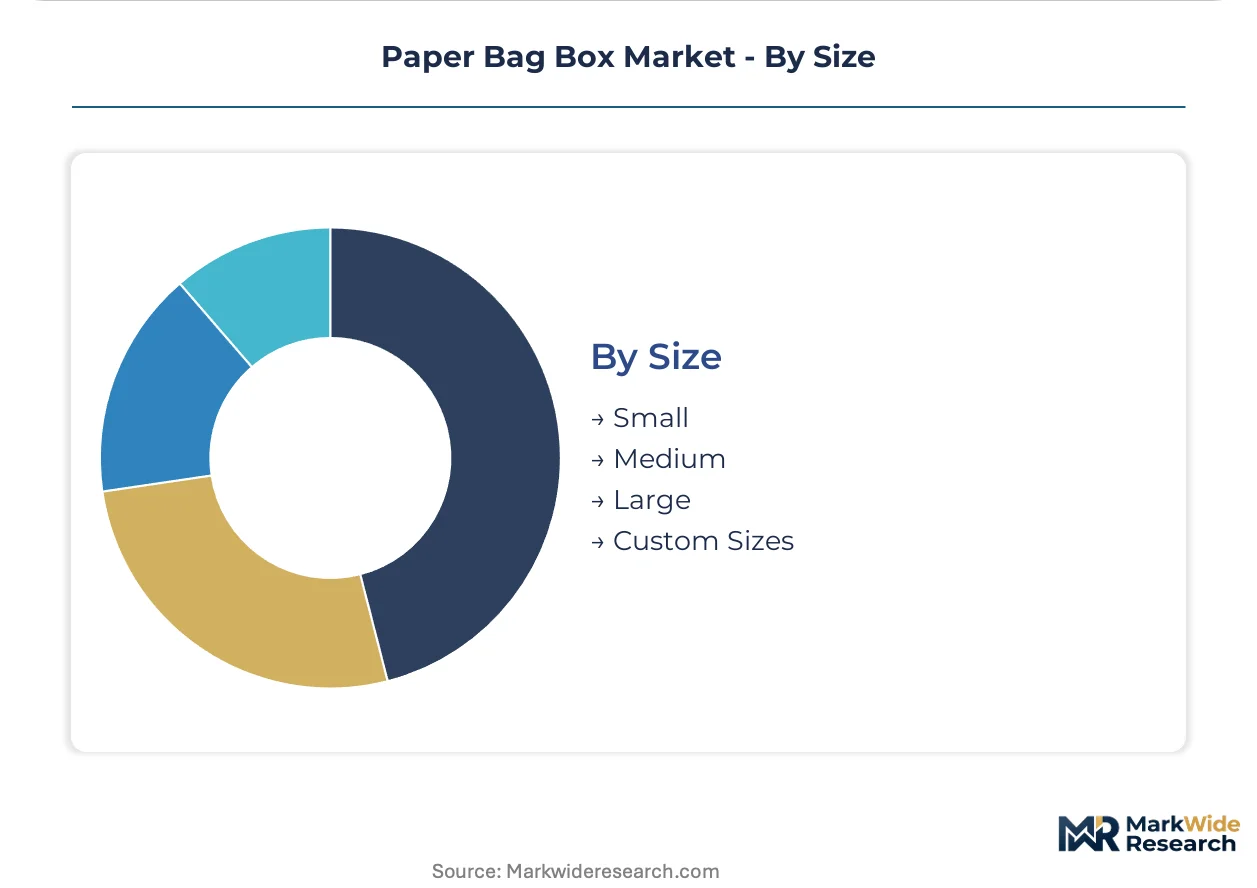
Size:
Custom dimensioning captures margin premiums as digital printing collapses minimum order quantities.
- Custom Sizes:Variable-dimension production from digital cutting and creasing equipment serves micro-segmented brand campaigns. Nestlé and Unilever procurement teams specify precise height-width-depth ratios for automated case packing, collapsing minimum runs from 50,000 to 500 units.
- Large:Bulk retail and industrial packaging formats accommodate 10-25 kilogram loads for agricultural and construction materials.
- Medium:Standard grocery carryout and apparel retail formats concentrate volume production.
- Small:Pharmaceutical sample, jewelry, and cosmetics applications prioritize premium substrate feel over structural load.
Medium sizes hold installed capacity. Custom sizes are rotating up the share rankings with digital production adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. German buyers absorb premium kraft grades under strict EPR compliance, while Indian discount retailers drive hard on recycled-content sourcing. Brazilian food service operators sit between these poles, trading barrier performance against total landed cost.
Germany
Amazon and Zalando fulfillment hubs in Leipzig and Dortmund mandate paper-based protective formats for third-party sellers. The Verpackungsgesetz amendment imposes steep fee differentials favoring kraft over plastic. The Ruhr industrial corridor hosts converter clusters serving grocery delivery chains with block-bottom specifications.
United States
California and New York EPR laws tighten post-consumer content thresholds for Amazon and Target private-label packaging. EPA recycled content guidelines pressure converters toward OCC-blended substrates. The Pacific Northwest pulp-to-packaging corridor supplies West Coast e-commerce fulfillment with specified burst-strength kraft.
China
Alibaba and JD.com logistics networks standardize rigid paper mailers for cross-border export fulfillment. SAMR packaging waste regulations accelerate mono-material adoption over multi-layer laminates. The Yangtze River Delta converter belt serves export-oriented brands with high-speed digital printing capacity.
India
Reliance Retail and D-Mart cold-chain expansion favors rigid paper containers for fresh produce last-mile delivery. FSSAI food-contact notifications delay coated-paper approvals, compressing product launch timelines. The Gujarat industrial corridor hosts emerging converter capacity targeting organized retail procurement.
France
Ready-meal producers and bakery cooperatives specify clay-coated papers to meet ECHA fluorochemical restrictions. ANSM pharmaceutical serialization rules favor tamper-evident paper secondary packaging. The Lyon-Auvergne packaging cluster supplies automated filling lines with precision-dimensioned block-bottom formats.
Paper Bag Box Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with pulp supply ownership determining margin resilience. International Paper and Mondi Group anchor the upper tier through captive forestry and mill networks. Mid-scale converters compete on digital printing agility and custom dimensioning. Capacity expansion and barrier coating chemistry partnerships constitute the dominant competitive moves as automation compatibility becomes the decisive specification criterion.
Among North American integrated producers, International Paper and WestRock exemplify scale-driven archetypes with backward control over pulp supply. Mondi Group occupies a parallel position in European forestry-to-packaging integration. Smurfit Kappa represents the converter-specialist model, competing through geographic reach and automated format expertise rather than upstream resource ownership.
| Leading Market Players |
|---|
| International Paper |
| Mondi Group |
| Smurfit Kappa |
| WestRock |
| DS Smith |
| Oji Holdings Corporation |
| Stora Enso |
| Packaging Corporation of America |
| ProAmpac |
| Others |
Value Network & Pricing Analysis
EU Packaging and Packaging Waste Regulation certification gates both supplier qualification and price differentiation simultaneously, forcing converters to absorb compliance costs that separate certified mono-material producers from uncertified competitors while EPR fee structures reward post-consumer content with measurable cost advantages.
Pricing Analysis
After-sales service contracts for automated filling line maintenance and coating revalidation drive lifetime value capture for integrated producers. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified block-bottom specifications from commodity flat bags and discount recycled grades. Pricing pressure stems from pulp cost volatility compressing converter margins on long-term contracts. Grocery delivery chains and discount retailers exhibit highest price sensitivity, while pharmaceutical and luxury cosmetics buyers absorb premiums for tamper-evident and branded specifications.
Supply Chain Analysis
Strait of Malacca transit congestion risk shadows kraft pulp shipments from Southeast Asian mills to European converters. Supply concentrates in Germany, the United States, and China as dominant production hubs for block-bottom and mailer formats. Raw material dependencies center on northern bleached softwood kraft pulp, recovered OCC fiber, and bio-based barrier coatings. Single-source vulnerability concentrates in five North American containerboard producers controlling pulp-to-board supply. Distribution runs through converter-direct relationships with Amazon, Zalando, and Target fulfillment networks, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted toward consolidated e-commerce fulfillment networks that mandate paper-based specifications across third-party seller bases, fragmenting converter bargaining position.
For Market Incumbents: Compound backward integration into captive pulp supply or recovered fiber sourcing to defend margin resilience against integrated mill concentration. Prioritize barrier coating chemistry partnerships with Clariant or BASF to lock in grease-resistant formulations before FDA notification timelines freeze competitor pipelines. Geographic capacity expansion into India's Gujarat corridor captures organized retail procurement from Reliance Retail and D-Mart. For New Entrants and Emerging Players: Differentiate on digital printing agility serving micro-segmented brand campaigns with 500-unit minimum order quantities. Target India's cold-chain distribution buildout where FSSAI notification delays have compressed incumbent product launch timelines. Pursue Loop-style reusable bag-as-a-service pilots to establish recurring revenue streams outside commodity spot markets. For Investors and Strategic Acquirers: ECHA fluorochemical restrictions by 2026 reshape the acquisition landscape toward coating chemistry specialists and silicone-alternative formulators. Five-to-ten year viability favors forestry-integrated producers with captive pulp and mill networks over pure-play converters exposed to fiber cost volatility. Signal to watch: FDA food-contact substance notification approval velocity for novel bio-based coatings as inflection indicator for R&D pipeline viability.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating Partnership | Bio-wax and silicone alliances with BASF unlock prepared food service penetration for German bakery chains. |
| Digital Printing Capacity Expansion | High-speed kraft substrate printing serves Nestlé and Unilever micro-segmented regional promotional campaigns. |
| Backward Integration into Recovered Fiber | Captive OCC sourcing insulates margins from pulp volatility and satisfies California EPR thresholds. |
| Mono-Material Certification Investment | How2Recycle and Blue Angel dual compliance enables cross-border sales for Amazon and Zalando sellers. |
| Geographic Manufacturing Footprint | Gujarat corridor capacity targets Reliance Retail cold-chain procurement for fresh produce last-mile delivery. |
Research Methodology
Desk research of trade customs data, SEC filings from packaging producers, and EU regulatory databases preceded structured interviews with converter operations managers, brand sustainability officers, e-commerce fulfillment procurement leads, and barrier coating R&D directors. Primary fieldwork across Germany's Ruhr corridor, the US Pacific Northwest pulp belt, and India's Gujarat industrial zone validated secondary estimates. Bottom-up volume modeling triangulated against top-down value projections from disclosed capacity expansions.
Variance decomposition across product type, material grade, end-use vertical, and regional regulatory cluster shaped the analytical framework. CAGRs derived from segment-level volume trajectories weighted by EPR fee impact and automation compatibility specifications. Industry-specific inputs included Amazon and Zalando fulfillment center packaging mandates, ECHA fluorochemical restriction timelines, and FDA food-contact notification approval rates.
Forecasts assume regulatory continuity in EU Packaging and Packaging Waste Regulation, German Verpackungsgesetz, and California EPR implementation; material policy shifts would require re-modeling across the projection horizon. Practitioners should keep alternative scenarios live as ECHA enforcement intensity and FDA coating approval velocity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Kraft Paper Shopping Bag Market
Paper & Paperboard Packaging
Paperboard Protectors Market
Paper & Paperboard Packaging
Fast Food Wrapping Paper Market
Paper & Paperboard Packaging
Global Cooking and Baking Papers Market
Paper & Paperboard Packaging
Butchers Paper Market
Paper & Paperboard Packaging
Machine Glazed Kraft Paper Market
Paper & Paperboard Packaging
Middle East Corrugated Packaging Market
Paper & Paperboard Packaging
Disposable Paper Plates Market
Paper & Paperboard Packaging
Paperboard Jars Market
Paper & Paperboard Packaging
Impregnated Paper Market
Paper & Paperboard Packaging
Packing Paper Market
Paper & Paperboard Packaging
Coated Duplex Board Market
Paper & Paperboard Packaging
Paperboard Mailer Market
Paper & Paperboard Packaging
Foam Cups Market
Paper & Paperboard Packaging
Italy Paper Packaging Market
Paper & Paperboard Packaging
Middle-East and Africa Corrugated Packaging Market