
 Release Paper Market | 2026-2036
Release Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Release Paper Market Intelligence
Food-grade silicone specification is bifurcating the Release Paper landscape as converters demand higher purity substrates for direct-contact packaging. Ahlstrom-Munksjö Oyj leverages its European pulp supply network to sustain consistent food-grade output. Mondi anchors Southern European demand through integrated kraft pulp-to-coating operations. Loparex competes in North America with specialized medical-release formulations that meet stringent biocompatibility protocols.
Release paper is a functional substrate, typically glassine or supercalendered kraft, coated with cross-linked polydimethylsiloxane to achieve controlled release forces between 5 and 50 grams per inch. Its primary purpose is to carry pressure-sensitive adhesives through die-cutting, printing, and converting operations before clean removal at end-use. Silicone-coated grades dominate value generation due to their thermal stability and broad adhesive compatibility, while biodegradable material formulations represent the fastest-expanding structural pocket as brand owners pursue substrate circularity. Release liners for medical applications command premium positioning because of cleanroom manufacturing requirements and lot-level traceability mandates.
FDA substrate guidelines govern direct food-contact release papers in the United States, while REACH restricts certain silicone catalyst residues in European coatings, and ISO 15378 sets pharmaceutical packaging quality benchmarks that medical-grade producers must satisfy. These frameworks elevate compliance costs for smaller coaters while creating certification moats for established manufacturers. Stakeholders must monitor evolving biodegradable substrate standards and regional recycling infrastructure readiness to align capacity investments with forthcoming material-transition requirements.
Market Dynamics
REACH compliance in Europe and evolving FDA substrate guidelines in the United States are tightening silicone purity requirements, bifurcating supply chains into food-grade and industrial-grade tiers while elevating compliance costs for smaller coaters.
Growth Catalysts
- Medical-grade sterilization protocols:Wound-care manufacturers are expanding sterile release liner adoption, driven by ISO 15378 pharmaceutical packaging quality benchmarks that mandate lot-level traceability and cleanroom manufacturing.
- REACH catalyst residue restrictions:ECHA enforcement against platinum-cured silicone residues is accelerating substrate purification investments, creating certification moats for established European coaters.
- German label-converting clusters:Munich and Hamburg specialty-grade demand concentrates consumption, with converters demanding higher-purity substrates for direct-contact food packaging applications.
Market Restraints
- Silicone feedstock volatility:Polydimethylsiloxane precursor costs fluctuate with petrochemical pricing, compressing margins for coaters lacking backward integration into siloxane production.
- European supply concentration:Specialty-grade pulp dependence on Nordic kraft suppliers creates bottleneck risk for food-grade release paper manufacturers.
- Biodegradable performance gap:Starch-based and PLA substrates exhibit inferior thermal stability versus silicone-coated glassine, limiting high-speed converting line compatibility.
Strategic Opportunities
- India pharmaceutical packaging:CDSCO alignment with EU MDR standards creates entry pathways for medical-grade liner producers meeting ISO 15378 benchmarks.
- Direct-to-brand procurement:CPG manufacturers are bypassing traditional label converters, contracting release liner supply directly to secure substrate circularity credentials.
- EU Green Deal packaging mandates:The EU Packaging and Packaging Waste Regulation creates regulatory tailwind for biodegradable substrate formulations with verified end-of-life pathways.
Industry Challenges
- Cleanroom operator scarcity:Medical-grade production requires technicians trained in ISO 14644 particulate control, with talent concentrated in established pharmaceutical manufacturing regions.
- Multi-certification timeline compression:Simultaneous FDA food-contact, REACH, and ISO 15378 approvals extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Release Paper Market |
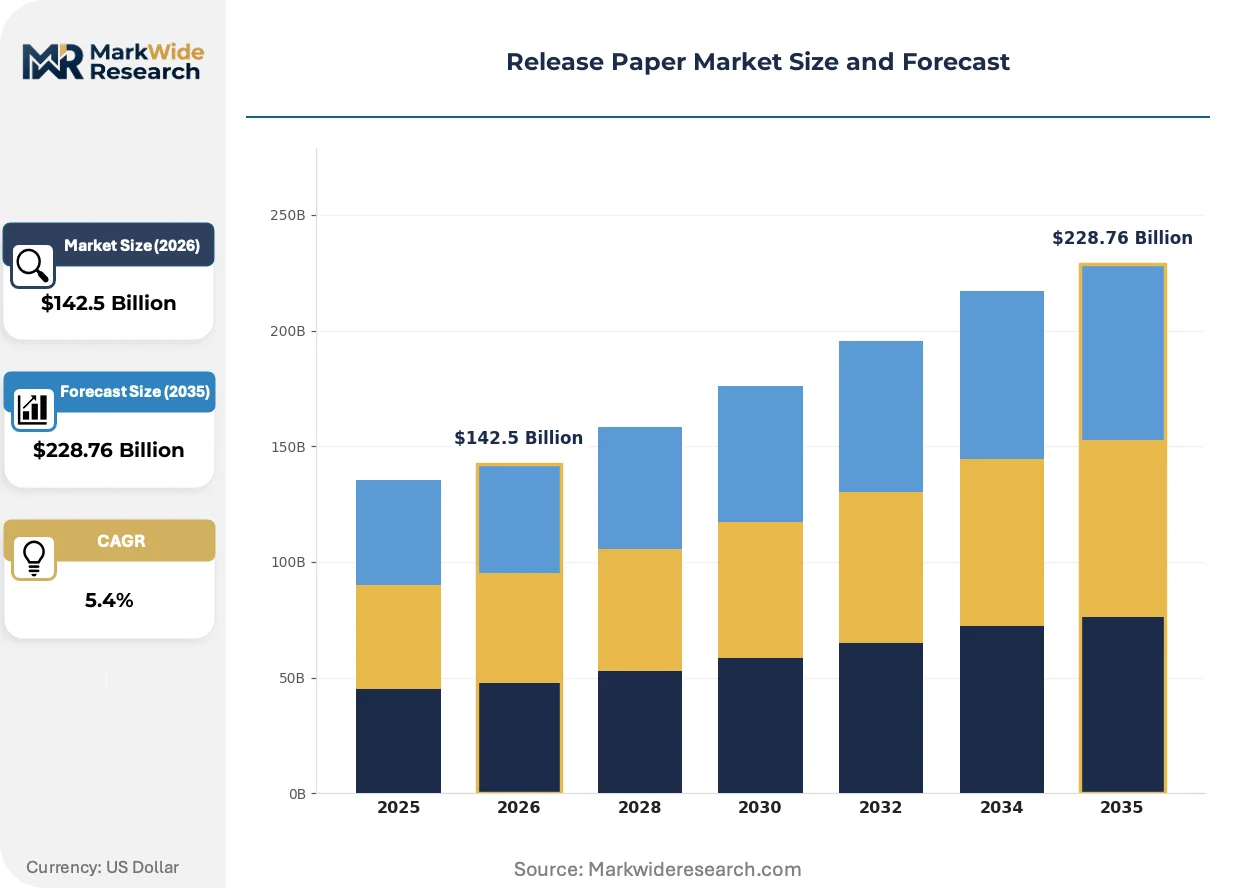
| Market Size in 2026 | $142.5 Billion |
| Market Size in 2035 | $228.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone-coated, Non-silicone-coated, Specialty papers, Release liners End User: Label manufacturers, Adhesive tape producers, Medical device manufacturers, Industrial packaging Material: Pulp-based, Plastic-based, Biodegradable, Synthetic Application: Food packaging, Consumer goods, Electronics, Medical applications |
| Companies Covered | Lintec Corporation, 3M, Ahlstrom-Munksjö Oyj, Loparex, Mondi, Avery Dennison Corporation, UPM, Sappi, Fox River Associates, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Release Paper Market Strategic Shifts & Innovations
Substrate circularity mandates and adhesive compatibility requirements are reshaping coating chemistry and end-of-life design priorities across the value chain.
Water-based silicone emulsion coatings are supplanting solvent-cured systems in European food-contact applications. Brand owners in dairy and confectionery packaging are specifying aqueous formulations to eliminate residual hexane concerns. This transition is compressing capital equipment lifecycles as coaters retrofit drying lines for water-based cure profiles.
EU Green Deal packaging regulations are mandating minimum recycled content thresholds and extended producer responsibility frameworks. Coaters must now verify substrate recyclability through accredited third-party certification bodies. Medical-grade producers face the steepest compliance burden, as sterilization barriers complicate mechanical recycling pathways.
Brand-led sustainability scorecards now weight release liner circularity in adhesive supplier selection criteria. Major CPG procurement teams are unbundling liner specification from adhesive contracts, directly negotiating substrate terms with specialty paper mills. This disintermediation is most visible in Germany, where label-converting clusters around Munich have seen direct mill-brand contracting triple since 2023.
Release Paper Market Segmentation
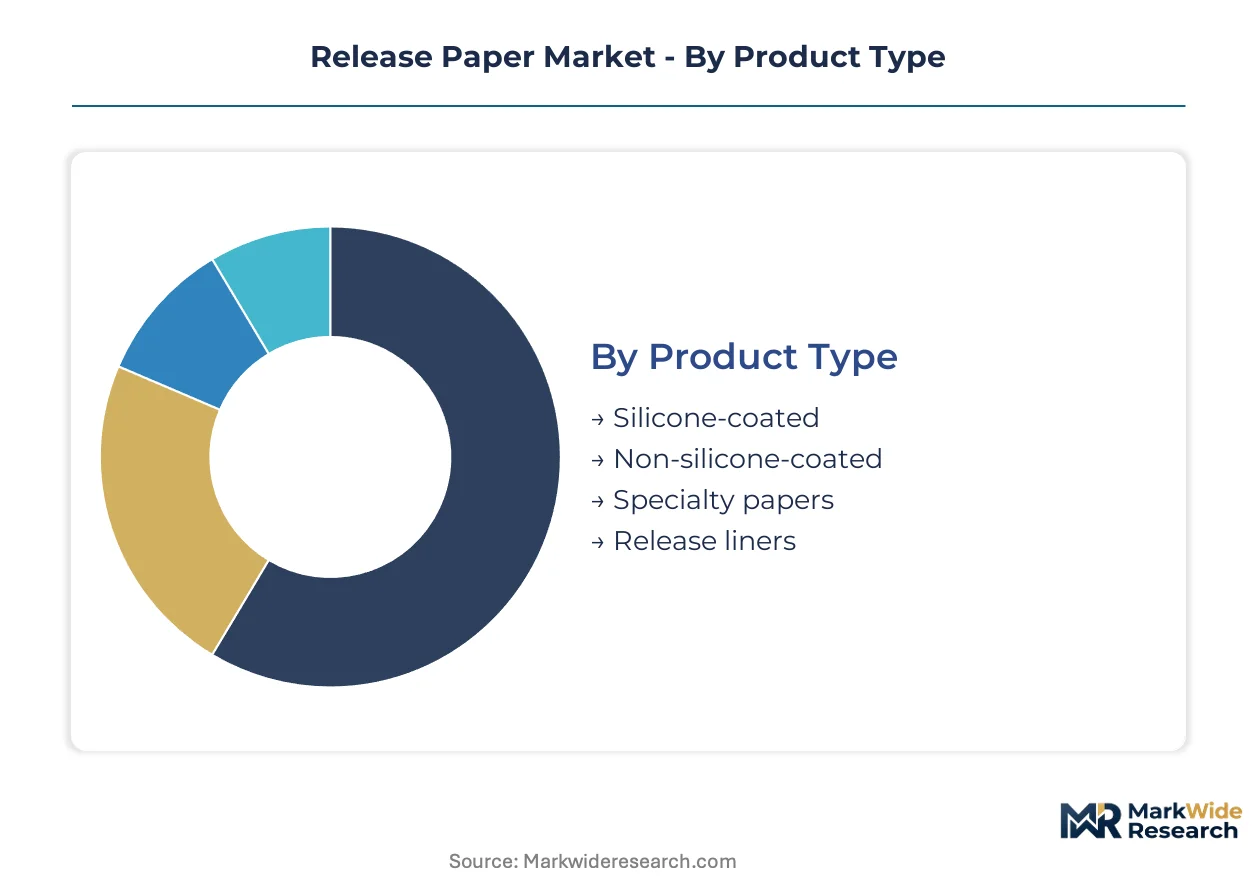
Release paper segmentation reveals how coating chemistry, substrate origin, and end-use certification requirements stratify manufacturing investments. Each dimension carries distinct regulatory burdens and margin structures that determine competitive positioning.
Product Type:
Domestic consumption dominates silicone-coated and specialty grades in Germany and the United States, while release liners for medical export markets concentrate production in Switzerland and Ireland.
- Silicone-coated:Cross-linked polydimethylsiloxane applied to glassine or supercalendered kraft achieves controlled release forces between 5 and 50 grams per inch. German label converters around Munich specify these grades for high-speed dairy packaging lines requiring thermal stability.
- Specialty papers:Custom-engineered substrates incorporate fluoropolymer or hybrid coatings for extreme-temperature adhesive applications. Medical device manufacturers in Switzerland source these for sterilization-resistant wound-care liners.
- Non-silicone-coated:Polyethylene-extruded or clay-coated alternatives serve cost-sensitive industrial masking applications.
- Release liners:Multi-layer constructions with barrier coatings protect pressure-sensitive adhesives through die-cutting and converting operations.
Silicone-coated commands the established base. The steepest expansion runs through specialty papers.
End User:
Cost tier stratification separates premium medical-grade producers from commodity label converters, with certification investments creating divergent margin floors.
- Label manufacturers:Food-grade specification demands dominate procurement, with German converters around Hamburg requiring REACH-compliant silicone purity for direct-contact packaging.
- Medical device manufacturers:ISO 15378 mandates lot-level traceability and cleanroom manufacturing for sterile wound-care liners. Ireland's pharmaceutical cluster sources these exclusively from certified European coaters.
- Adhesive tape producers:Industrial-grade release liners for automotive and construction applications prioritize release force consistency over purity certification.
- Industrial packaging:Corrugated and protective packaging applications consume lower-specification kraft-based liners with minimal coating investment.
Label manufacturers anchor volume demand. Medical device manufacturers capture the fastest margin expansion.
Material:
Application requirements dictate substrate selection, with food-contact and medical end-uses imposing stricter purity thresholds than industrial applications.
- Pulp-based:Nordic kraft and European glassine supply chains serve food-grade and medical-grade specifications. ECHA catalyst residue restrictions have elevated purification costs for platinum-cured silicone coatings.
- Biodegradable:Starch-based and PLA formulations address EU Green Deal packaging mandates. Thermal stability limitations restrict adoption to lower-speed converting lines in German confectionery packaging.
- Plastic-based:Polyethylene and polypropylene films offer moisture barrier properties for electronics and industrial applications.
- Synthetic:Aramid and fluoropolymer substrates serve extreme-temperature aerospace and automotive specifications.
Pulp-based materials dominate certified applications. Biodegradable formulations are climbing the fastest.
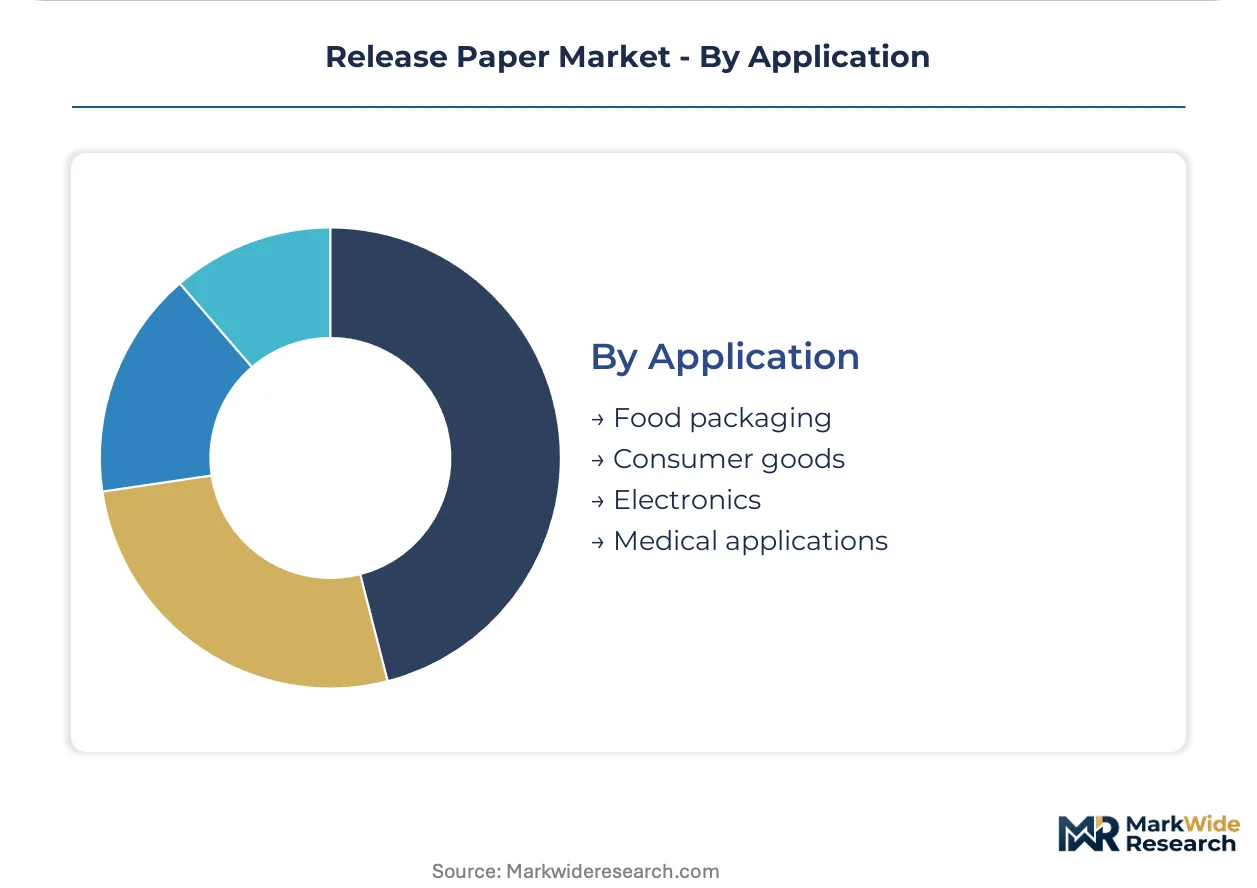
Application:
Customer type segmentation separates brand-direct procurement from converter-mediated supply, with CPG manufacturers increasingly unbundling liner specification from adhesive contracts.
- Food packaging:FDA substrate guidelines and REACH compliance bifurcate supply chains into direct-contact and indirect-contact tiers. German dairy and confectionery brand owners now contract directly with specialty mills.
- Medical applications:Sterile release liners for wound care command premium positioning due to cleanroom manufacturing requirements and ISO 15378 traceability mandates. Swiss and Irish production clusters serve this demand.
- Consumer goods:Pressure-sensitive label applications for personal care and household products balance cost and performance across mid-tier specifications.
- Electronics:Static-dissipative and ultra-clean liners protect sensitive components during assembly and shipment.
Food packaging anchors volume scale. Medical applications deliver the steepest value expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German specialty-grade exports supply label converters across France and the Netherlands, while Swiss medical-grade production serves sterile wound-care demand in Ireland and the United Kingdom.
United States
FDA substrate guidelines govern direct food-contact release papers, with evolving purity requirements tightening silicone catalyst specifications. The agency's updated guidance on polydimethylsiloxane residues is accelerating substrate purification investments among domestic coaters. Converters in the Midwest industrial corridor source medical-grade liners for diagnostic tape applications.
Germany
REACH compliance mandates from ECHA restrict platinum-cured silicone residues in coatings, bifurcating supply chains into food-grade and industrial-grade tiers. Munich and Hamburg host dense label-converting clusters demanding higher-purity substrates for direct-contact dairy and confectionery packaging. Specialty-grade pulp dependence on Nordic kraft suppliers creates supply bottleneck risk for domestic manufacturers.
Switzerland
Swissmedic pharmaceutical packaging standards align with ISO 15378 benchmarks, mandating lot-level traceability for sterile release liners. The country's precision manufacturing heritage supports cleanroom production capabilities for wound-care applications. Basel and Zurich anchor medical-grade coating operations serving export demand from Irish pharmaceutical clusters.
India
CDSCO alignment with EU MDR standards creates regulatory pathways for medical-grade liner producers meeting international quality benchmarks. The national pharmaceutical regulator's updated packaging guidelines are elevating compliance expectations for domestic wound-care manufacturers. Maharashtra and Gujarat host emerging converting capacity for sterile medical applications.
China
NMPA medical device packaging regulations are converging with ISO standards, creating certification complexity for export-oriented coaters. The national medical products administration's substrate guidelines for sterile barriers are tightening manufacturing protocol requirements. Yangtze River Delta industrial zones concentrate domestic production for electronics and consumer goods labeling applications.
Release Paper Market Key Industry Players
Listed leaders compete with private specialists across coating chemistry and certification tiers, producing a market structure where scale advantages intersect with regulatory specialization. The vendor base stratifies around three archetypes: integrated pulp-to-coating operators with captive fiber supply, specialty coaters focused on medical-grade certification moats, and diversified materials conglomerates leveraging cross-segment technology transfer. Dominant competitive moves include strategic partnerships with adhesive formulators and capacity expansion into biodegradable substrate formulations.
Within the integrated operator tier, Ahlstrom-Munksjö Oyj and Mondi exemplify pulp-network anchoring strategies that sustain food-grade output consistency. Loparex occupies a position among North American specialists competing through medical-release formulation expertise. These three entities represent distinct geographic and certification positioning vectors without exhaustive market coverage.
| Leading Market Players |
|---|
| Lintec Corporation |
| 3M |
| Ahlstrom-Munksjö Oyj |
| Loparex |
| Mondi |
| Avery Dennison Corporation |
| UPM |
| Sappi |
| Fox River Associates |
| Others |
Cost & Logistics Intelligence
Ninety-day silicone precursor inventory cycles at Nordic kraft mills concentrate pricing leverage among backward-integrated coaters while compressing margin buffers for spot-market dependent converters. This lead-time structure amplifies cost pass-through volatility when polydimethylsiloxane feedstock prices fluctuate with petrochemical indices.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across standard-grade release liners. Three-tier pricing structure across premium, standard, and economy levels separates ISO 15378-certified medical grades from food-contact REACH tiers and industrial masking specifications. Cost compression in commodity kraft-based liners is intensifying because adhesive tape producers prioritize release force consistency over purity certification. Medical device manufacturers exhibit lowest price sensitivity due to sterilization barrier requirements and lot-level traceability mandates.
Supply Chain Analysis
Strategic stockpile preferences dominate medical-grade coating operations where cleanroom manufacturing protocols demand buffer inventory against particulate contamination risks. Geographic supply concentration centers on Germany, Switzerland, and Finland for specialty-grade pulp and coating capacity. Raw material dependencies rest on Nordic kraft suppliers, platinum-cured silicone catalysts, and pharmaceutical-grade barrier films. Single-source vulnerability from ECHA catalyst residue restrictions creates bottleneck exposure for European food-grade manufacturers. Distribution runs through label-converting clusters in Munich and Hamburg before downstream delivery to dairy and confectionery brand owners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The release paper market tracks a cyclical recovery pattern as pharmaceutical packaging capital expenditure cycles normalize following post-pandemic inventory destocking. Wound-care sterilization protocol upgrades at major device manufacturers provide the demand-side cyclical driver.
For Market Incumbents: Shield certification moats by accelerating ISO 15378 audit frequency ahead of competitor catch-up timelines. Prioritize backward integration into siloxane production to offset platinum catalyst cost volatility from REACH compliance mandates. Channel control through direct-to-brand contracting agreements in Germany reduces converter disintermediation risk.
For New Entrants and Emerging Players: Anchor in biodegradable substrate formulations where EU Green Deal packaging mandates create regulatory tailwind and incumbent retooling lags extend competitive windows. India's CDSCO-aligned pharmaceutical packaging sector offers the most penetrable geography for medical-grade liner entry. Pursue toll-coating partnerships with established Nordic pulp suppliers to bypass capital-intensive cleanroom construction requirements.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified paper conglomerates where release liner divisions lack strategic parent prioritization. Five-to-ten year viability hinges on circularity credential verification capabilities as brand-owner sustainability scorecards harden procurement criteria. Watch biodegradable substrate thermal stability breakthroughs as the inflection signal for high-speed converting line compatibility expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Production | Captive catalyst supply shields margins from ECHA platinum residue restriction enforcement. |
| ISO 15378 Certification Acceleration | Lot-level traceability compliance opens sterile wound-care liner contracts with Swissmedic-aligned manufacturers. |
| Biodegradable Substrate Capacity Expansion | EU Packaging and Packaging Waste Regulation mandates create certified end-of-life pathway demand. |
| Direct-to-Brand Procurement Contracts | Unbundled liner specification from adhesive terms secures circularity credential visibility with CPG procurement teams. |
| Cleanroom Operator Training Partnerships | ISO 14644 technician pipeline development addresses talent scarcity constraining medical-grade production scaling. |
Research Approach
Operator-level perspectives from coating line supervisors, pharmaceutical packaging procurement managers, label converter technical directors, and ECHA compliance officers anchored the qualitative base. Secondary validation drew from FDA substrate guideline updates, REACH catalyst residue restriction enforcement records, ISO 15378 audit documentation, and Nordic kraft pulp trade flow data. Bottom-up capacity assessments at German and Swiss coating facilities were triangulated against top-down demand modeling from medical device and food packaging end-use sectors.
Sensitivity analysis across silicone feedstock price bands, certification timeline scenarios, and biodegradable substrate adoption curves informed the analytical framework. Segmentation dimensions modeled include coating chemistry tier, substrate material origin, end-use certification requirement, and geographic regulatory cluster. CAGRs were derived from installed capacity expansion announcements cross-referenced with end-use demand elasticity parameters. Forecast inputs incorporated cleanroom manufacturing yield assumptions and EU Green Deal implementation pace variations.
Material uncertainties — abrupt REACH catalyst reclassification, FDA substrate guideline revisions, or biodegradable thermal stability breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and brand-owner sustainability procurement commitment durability. Revision becomes warranted when platinum-cured silicone purification cost inflation crosses thresholds that trigger rapid solvent-based coating substitution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Packing Paper Market
Paper & Paperboard Packaging
Kitchen Oil Absorbing Paper Market
Paper & Paperboard Packaging
Global Solid Board Market
Paper & Paperboard Packaging
Global Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Boxboard Packaging Market
Paper & Paperboard Packaging
Cardboard Tubs Market
Paper & Paperboard Packaging
Box Liners Market
Paper & Paperboard Packaging
South Korea Paper Packaging Market
Paper & Paperboard Packaging
Australia Paper Packaging Market
Paper & Paperboard Packaging
Decal Paper Market
Paper & Paperboard Packaging
Chipboard Box Market
Paper & Paperboard Packaging
GCC Paper Cup Market
Paper & Paperboard Packaging
Paper Bubble Wrap Market
Paper & Paperboard Packaging
Push-Up Paperboard Tube Market
Paper & Paperboard Packaging
Latin America Paper Packaging Market
Paper & Paperboard Packaging
France Paper Packaging Market