
 Vietnam Flexible Plastic Packaging Market | 2026-2036
Vietnam Flexible Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Flexible Plastic Packaging Market Insights
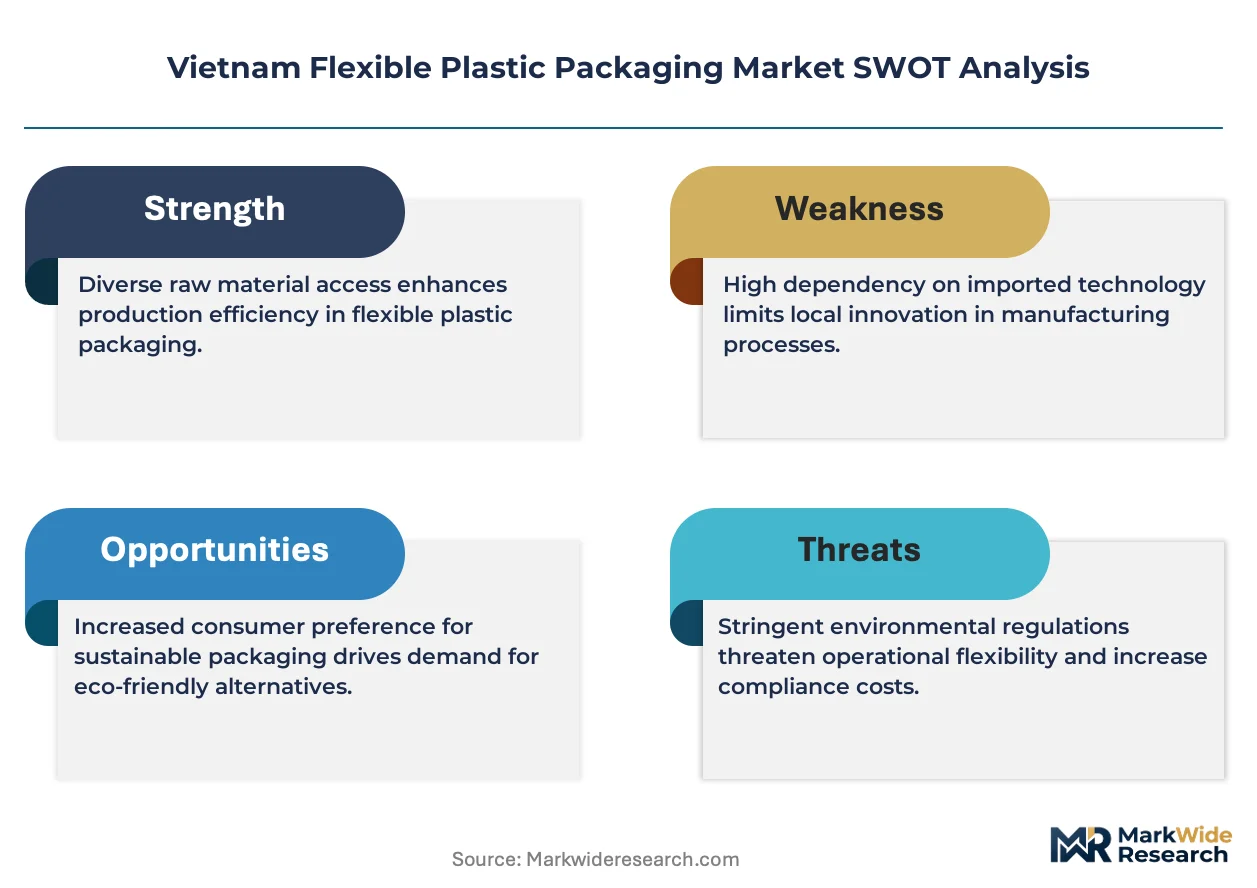
Premium multilayer barrier films and commodity-grade polyethylene wraps are consolidating along separate supply chains in Vietnam. Amcor Plc leverages its technical film capabilities to serve multinational food brands requiring oxygen and moisture barriers. An Phat Holdings JSC anchors domestic supply through integrated resin-to-film operations in Hai Duong province. Tan Tien Packaging Company differentiates via specialized printing and lamination for cosmetics exporters.
Vietnam flexible plastic packaging denotes pliable polymer structures—typically polyethylene, polypropylene, PET, or BOPP between 12 and 250 microns—manufactured through blown film extrusion, cast film, or biaxial orientation processes, designed to protect, contain, and preserve goods during distribution and storage. Pouches represent the fastest-growing product configuration as beverage and condiment brands shift from rigid containers to stand-up formats with spouts and resealable zippers. Films command the largest volume share across labeling and protective applications where cost-per-unit and throughput speed determine procurement decisions.
Vietnam's Ministry of Natural Resources and Environment enforces Circular 08/2022 on plastic waste management, compelling converters to redesign packaging for recyclability or face extended producer responsibility fees. BIS-aligned technical regulations for food-contact materials, administered through the country's quality standards body, restrict certain additives and mandate migration testing for imports and domestic production alike. Stakeholders must monitor how EPR compliance costs and recycled content mandates reshape material selection and converter profitability across the northern, central, and southern manufacturing zones.
Market Dynamics
Extended Producer Responsibility mandates from Vietnam's Ministry of Natural Resources and Environment are forcing converters to redesign multilayer structures for recyclability, compressing margins while reshaping material selection across the northern, central, and southern manufacturing zones.
Growth Catalysts
- High-barrier pouch adoption:Processed food manufacturers in the Ho Chi Minh City industrial corridor are expanding shelf-stable product lines using oxygen and moisture barrier films for extended ambient storage.
- Circular 08/2022 compliance investment:EPR fee structures are accelerating capital deployment into mono-material compatible extrusion lines and compatible adhesive systems.
- Export-oriented food processing:Foreign direct investment into condiment and seafood packaging for European and North American retail channels is pulling technical film demand.
Market Restraints
- Resin import dependency:Vietnam's polyethylene and polypropylene feedstock relies on regional petrochemical suppliers, exposing converters to freight and currency volatility.
- Multilayer recyclability deadlock:Current adhesive lamination technologies create incompatible polymer combinations that mechanical recycling infrastructure cannot process.
- Barrier performance trade-offs:Mono-material alternatives to EVOH or aluminum oxide coatings sacrifice shelf-life extension required for tropical climate distribution.
Strategic Opportunities
- Central Highlands beverage expansion:Coffee and fruit juice processors in Dak Lak and Lam Dong provinces remain underserved by technical film converters concentrated in the north and south.
- Chemical recycling partnerships:Pyrolysis and dissolution infrastructure development could unlock value recovery from currently non-recyclable post-industrial scrap streams.
- Digital printing integration:Narrow-web inkjet systems combined with conventional gravure are enabling shorter run lengths for cosmetics exporters requiring rapid design turnover.
Industry Challenges
- Migration testing capacity:BIS-aligned food-contact certification requires laboratory infrastructure that smaller converters in central Vietnam lack proximity to.
- Retrofitting legacy extrusion assets:Blown film lines installed during the 2010-2015 capacity expansion require substantial modification to process recycled content at specified melt flow rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Flexible Plastic Packaging Market |
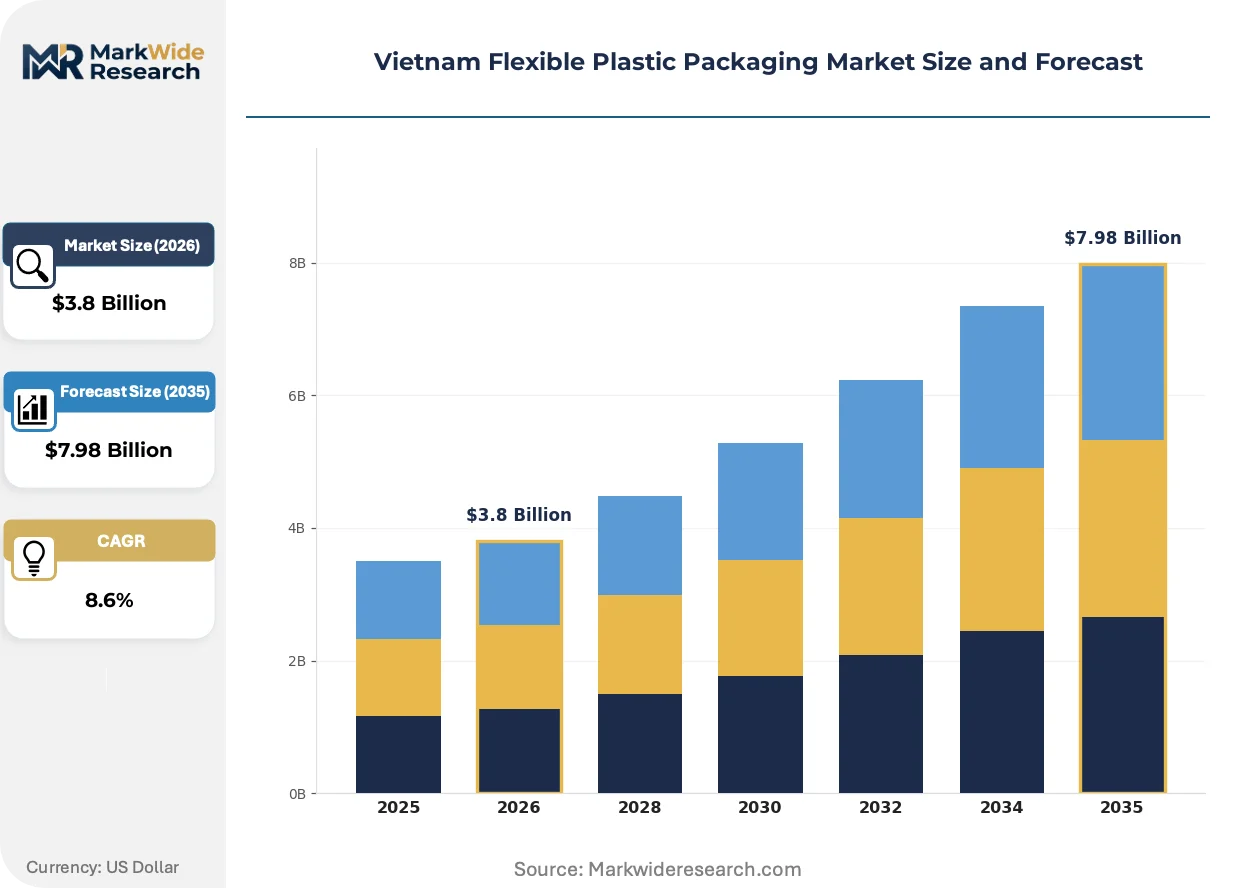
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Pouches, Wraps, Films End User: Food, Pharmaceuticals, Cosmetics, Electronics Material: Polyethylene, Polypropylene, PET, BOPP Application: Packaging, Labeling, Protective, Decorative |
| Companies Covered | Amcor Plc, Huhtamaki Oyj, SIG Group AG, Genpack Co., Ltd., An Phat Holdings JSC, Rang Dong Long An Plastic JSC, Tan Tien Packaging Company, Duy Tan Plastic Manufacturing Corp., Batico, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Flexible Plastic Packaging Market Trends and Innovations
Material science breakthroughs and regulatory compliance architectures are converging to redefine competitive capability in Vietnamese flexible packaging, with sustainability credentials becoming inseparable from technical performance specifications.
Mono-material barrier films incorporating metallized BOPP or high-density polyethylene with modified surface energy treatments are electrifying the transition away from incompatible multilayer structures. Seafood exporters to Japan and the European Union are specifying these formats to preempt EPR liability and satisfy retailer plastic reduction commitments. The structural consequence is compression of conventional adhesive lamination capacity while rewarding extrusion coating and coextrusion investments.
Vietnam's Ministry of Natural Resources and Environment is tightening enforcement timelines for Circular 08/2022, with mandatory recycled content thresholds and eco-modulated EPR fees taking effect across the forecast window. Industrial consequence includes accelerated converter consolidation as compliance costs disproportionately burden sub-scale operations. Small and mid-sized enterprises in Hai Duong and Binh Duong provinces are responding through cooperative collection schemes and shared testing laboratory investments.
Brand-led specification of mass balance certified resins is altering procurement evaluation criteria for multinational food and personal care companies operating in Vietnam. Direct engagement between converters and petrochemical suppliers is displacing distributor-mediated purchasing for volume accounts. This pattern is most visible in the southern manufacturing zone where export-oriented processing clusters maintain direct technical service relationships with regional polymer producers.
Vietnam Flexible Plastic Packaging Market Segmentation
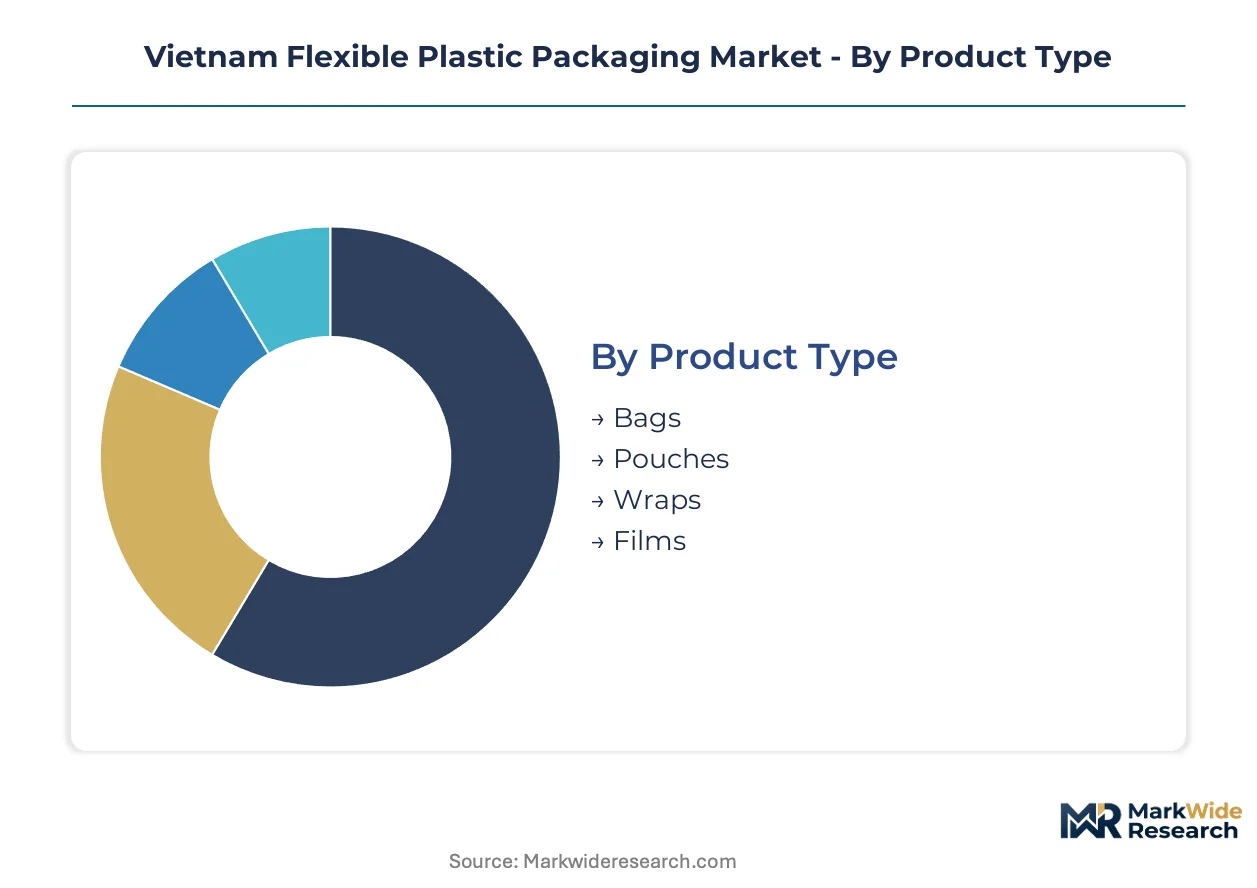
Segmentation in Vietnam's flexible plastic packaging market reveals how regulatory compliance costs and technical performance requirements stratify procurement decisions across converter tiers. Material certification burdens, barrier specifications, and end-use migration testing create distinct competitive battlegrounds within each dimension.
Product Type:
BIS-aligned food-contact certification from Vietnam's quality standards body applies differentially across formats, with pouches and films facing the most stringent migration testing protocols for direct food contact applications.
- Bags:Side-seal and bottom-gusseted configurations dominate commodity produce and retail carryout applications. Ho Chi Minh City grocery distributors specify these for cost-driven fresh vegetable distribution where oxygen transmission rates matter less than mechanical puncture resistance.
- Pouches:Stand-up formats with spouts and resealable zippers incorporate multilayer barrier structures of metallized BOPP or EVOH coextrusion. Seafood exporters to Japan and the European Union drive specification of these formats to satisfy retailer plastic reduction commitments while maintaining shelf stability.
- Wraps:Stretch and shrink films for palletization and unitization prioritize cling force and tear propagation resistance over barrier properties. Industrial logistics operators in the northern manufacturing zone consume these for electronics and appliance distribution.
- Films:Cast and blown varieties serve labeling, overwrap, and lamination substrates. Converters in Hai Duong province process these through gravure and flexographic printing lines for cosmetics exporters requiring rapid design turnover.
Leading the category by volume: Films. Growing fastest: Pouches.
End User:
Customer procurement sophistication separates segments, with multinational food and personal care brands imposing mass balance certification requirements that domestic Vietnamese converters struggle to satisfy at scale.
- Food:Processed meat, condiment, and instant noodle manufacturers in the Ho Chi Minh City industrial corridor specify high-barrier structures for tropical climate distribution. Circular 08/2022 compliance costs are accelerating consolidation among sub-scale converters serving this segment.
- Pharmaceuticals:Blister lidding and sachet formats demand particulate-free manufacturing environments and extractables testing. The segment concentrates procurement among converters with cleanroom extrusion capability and documented validation protocols.
- Cosmetics:Premium brands require specialized printing and lamination with metallic effects and tactile finishes. Tan Tien Packaging Company anchors domestic supply for this segment through narrow-web gravure and digital hybrid systems.
- Electronics:Antistatic and moisture barrier bags protect semiconductors and components during export shipment. Specifications align with JIS standards referenced by Japanese manufacturing investors in northern Vietnam.
Dominant by procurement volume: Food. Expanding most quickly: Cosmetics.
Material:
Resin import dependency from regional petrochemical suppliers exposes each polymer type to freight and currency volatility, with polyethylene and polypropylene converters maintaining larger safety stocks than PET or BOPP specialists.
- Polyethylene:LDPE and LLDPE grades dominate blown film extrusion for general-purpose bags and wraps. Recycled content mandates are forcing retrofitting of legacy extrusion lines installed during the 2010-2015 capacity expansion.
- Polypropylene:Cast and biaxially oriented variants serve high-clarity labeling and metallized barrier applications. An Phat Holdings JSC maintains captive resin-to-film integration for this material in Hai Duong province.
- PET:Metallized and clear films serve decorative and high-barrier pouch applications. The material's compatibility with existing mechanical recycling infrastructure positions it favorably under tightening EPR enforcement timelines.
- BOPP:Tenter-frame oriented films provide stiffness and printability for snack food lamination. Amcor Plc leverages technical capabilities in this segment to serve multinational brand requirements for oxygen and moisture barriers.
Highest volume consumption: Polyethylene. Steepest expansion trajectory: PET.
Application:
Functional performance requirements separate segments, with packaging applications demanding the most complex multilayer structures while labeling and decorative applications prioritize print fidelity and surface aesthetics.
- Packaging:Primary and secondary containment functions drive the majority of flexible plastic consumption. Extended Producer Responsibility fees are compelling redesign toward mono-material compatible structures.
- Labeling:Pressure-sensitive and shrink-sleeve formats require precise dimensional stability and ink adhesion. Beverage bottlers in the Central Highlands specify these for coffee and fruit juice branding.
- Protective:Vapor corrosion inhibitor and antistatic films safeguard metal components and electronics during ocean freight. Industrial manufacturers in Binh Duong province source these for machinery export.
- Decorative:Holographic and specialty finishes enhance shelf presence for premium consumer goods. The segment rewards converters with integrated printing and metallization capability.
Largest value capture: Packaging. Gaining share fastest: Labeling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ho Chi Minh City and its surrounding industrial corridor anchor Vietnam's flexible plastic packaging demand, hosting export-oriented food processing clusters that consume high-barrier pouches and technical films. The country's regional distribution splits across three distinct manufacturing zones, each shaped by infrastructure access, regulatory enforcement intensity, and end-user concentration.
Northern Manufacturing Zone
Hai Duong province hosts integrated resin-to-film operations serving domestic food brands and electronics exporters. Vietnam's Ministry of Natural Resources and Environment enforces Circular 08/2022 compliance timelines most stringently here due to proximity to Hanoi administrative centers. Bac Ninh and Vinh Phuc industrial parks concentrate converters supplying Japanese electronics manufacturers with antistatic and moisture barrier formats.
Central Manufacturing Zone
Da Nang and Quang Nam provinces remain underserved by technical film converters despite growing seafood processing capacity. The central region lacks proximity to BIS-aligned food-contact testing laboratories, forcing smaller operators to ship samples to Hanoi or Ho Chi Minh City. Thua Thien Hue province hosts emerging beverage bottlers requiring pressure-sensitive labeling materials for coffee and fruit juice branding.
Southern Manufacturing Zone
Binh Duong and Dong Nai provinces house multinational converter subsidiaries serving European and North American retail channels. Direct technical service relationships between regional petrochemical suppliers and volume converters displace distributor-mediated purchasing. Long An province's plastic industrial parks concentrate commodity-grade polyethylene bag production for domestic grocery distribution.
Central Highlands
Dak Lak and Lam Dong provinces process coffee and fruit juice for domestic and export markets, yet technical film converter presence remains sparse. Beverage processors source packaging materials from Ho Chi Minh City suppliers, incurring freight cost penalties. The region's isolation from northern and southern manufacturing clusters creates procurement inefficiencies for high-barrier pouch specifications.
Mekong Delta
Can Tho and An Giang provinces support rice and seafood processing for export, driving demand for protective and primary packaging. Local converter capacity concentrates on commodity-grade formats, with technical barrier films imported from Binh Duong or Hai Duong. The delta's waterway logistics favor bulk resin delivery but complicate finished film distribution to dispersed processing facilities.
Vietnam Flexible Plastic Packaging Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technical capability and compliance certification dimensions, with multinational converters commanding pricing power through barrier film expertise while domestic integrated operators compete on resin cost and geographic proximity. The market structure fragments across three tiers: global packaging conglomerates with Vietnamese subsidiaries, domestic integrated resin-to-film producers, and specialized printing and lamination houses. Strategic moves concentrate on mono-material line retrofits for EPR compliance and cooperative collection schemes among sub-scale operators.
Within the multinational tier, Amcor Plc and Huhtamaki Oyj represent technical barrier film archetypes serving export-oriented food brands. An Phat Holdings JSC anchors domestic supply through integrated operations. Tan Tien Packaging Company occupies a position within specialized printing and lamination for premium cosmetic applications. These three exemplify how competitive positioning stratifies by end-user procurement sophistication and regulatory compliance burden.
| Leading Market Players |
|---|
| Amcor Plc |
| Huhtamaki Oyj |
| SIG Group AG |
| Genpack Co., Ltd. |
| An Phat Holdings JSC |
| Rang Dong Long An Plastic JSC |
| Tan Tien Packaging Company |
| Duy Tan Plastic Manufacturing Corp. |
| Batico |
| Others |
Pricing and Supply Chain Analysis
Barrier certification tiers bifurcate Vietnam's flexible plastic packaging landscape, with BIS-aligned food-contact validation and EPR compliance status separating premium converters from commodity operators in both pricing power and supply chain access. This divergence concentrates procurement relationships around Hai Duong and Binh Duong provinces while marginalizing uncertified competitors.
Pricing Analysis
Value-based pricing anchors on shelf-life extension performance and migration test compliance, with multinational food brands paying premiums for oxygen barrier films that withstand tropical distribution. Price differentiation separates mass balance certified converters from uncertified rivals, while volume scale and geographic proximity to Ho Chi Minh City industrial clusters determine contract terms. Pricing pressure stems from EPR fee structures compressing margins on legacy multilayer designs, with domestic grocery distributors exhibiting highest price sensitivity and export-oriented seafood processors showing lowest.
Supply Chain Analysis
BIS food-contact certification gates supply relationships, with only validated converters accessing multinational brand procurement lists. Resin feedstock draws from Thailand, South Korea, and Singapore, exposing converters to freight cost volatility and currency fluctuation. Mono-material compatible extrusion lines and compatible adhesive systems represent critical component dependencies. Single-source vulnerability concentrates in regional petrochemical supply, with distributor-mediated purchasing displaced by direct technical service relationships in the southern manufacturing zone.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's flexible plastic packaging market is consolidating into a winner-take-most structure, with Circular 08/2022 compliance costs forcing sub-scale operators toward cooperative exit or acquisition.
For Market Incumbents: Anchor barrier film expertise through coextrusion line retrofits for mono-material compatibility, defending against commodity polyethylene converters gaining technical capability. Prioritize captive recycling infrastructure partnerships to preempt EPR liability accumulation. Consolidation leverage rests with Hai Duong and Binh Duong facilities holding BIS certification and direct petrochemical supplier relationships. For New Entrants and Emerging Players: The premium-commodity price-point gap in Central Highlands beverage packaging offers white-space entry, with Dak Lak and Lam Dong coffee processors currently sourcing from distant Ho Chi Minh City suppliers at freight penalties. Target technical film capacity deployment in Da Nang to capture underserved seafood and beverage demand. Go-to-market through cooperative collection scheme participation to share EPR compliance infrastructure costs with established operators. For Investors and Strategic Acquirers: Re-rating potential sits with integrated resin-to-film operators given recycled content mandate acceleration and petrochemical supply volatility. Long-term viability favors converters with backward integration into resin production and forward relationships with export-oriented food brands. Watch for inflection in chemical recycling partnership announcements as signal of value recovery capability from currently non-recyclable scrap streams.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-material Line Retrofit | Enables Circular 08/2022 compliance while maintaining barrier performance for tropical distribution. |
| Backward Integration into Resin | An Phat Holdings JSC model reduces exposure to regional petrochemical freight volatility. |
| Chemical Recycling Partnership | Pyrolysis infrastructure unlocks value recovery from adhesive-laminated post-industrial scrap. |
| Central Highlands Capacity Expansion | Dak Lak and Lam Dong proximity cuts freight penalties for coffee and juice processors. |
| Digital Printing Integration | Narrow-web inkjet systems serve cosmetics exporters requiring rapid design turnover. |
Research Methodology
Trade statistics from Vietnam Customs, BIS certification registries, and petrochemical import declarations formed the secondary backbone, cross-referenced with primary interviews involving extrusion line operators, food brand procurement managers, EPR compliance officers, and regional resin distributors. Bottom-up capacity assessments at Hai Duong and Binh Duong industrial parks were triangulated against top-down demand estimates from Ho Chi Minh City export processing zones.
Historical trendline analysis tracked blown film extrusion capacity additions and barrier film specification shifts across the analysis window, with segmentation modeling across material type, product configuration, end-use industry, and regional manufacturing zone. CAGRs were derived from elasticity-adjusted demand projections incorporating EPR enforcement intensity and recycled content mandate phase-ins. Forecast inputs included resin price volatility scenarios and mechanical recycling infrastructure buildout timelines.
Inputs from converter facility audits and BIS laboratory certification records were available through the study window; gaps in real-time EPR fee implementation data introduce uncertainty bands around compliance cost assumptions. Forecasts reflect documented assumptions on regulatory enforcement timelines and petrochemical supply continuity. A model refresh is warranted upon material change in Circular 08/2022 penalty structures or chemical recycling partnership announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Indonesia Flexible Packaging Market
Flexible Packaging
Confectionery Flexible Packaging Market
Flexible Packaging
GCC Shrink Sleeves Market
Flexible Packaging
Asia Pacific Single-Use Packaging Market
Flexible Packaging
Egypt Flexible Packaging Market
Flexible Packaging
China Flexible Packaging Market
Flexible Packaging
Morocco Flexible Plastic Packaging Market
Flexible Packaging
Mexico Flexible Plastic Packaging Market
Flexible Packaging
United States Flexible Plastic Packaging Market
Flexible Packaging
Germany Flexible Plastic Packaging Market
Flexible Packaging
APAC Flexible Packaging Market
Flexible Packaging
Africa Flexible Packaging Market
Flexible Packaging
UAE Flexible Packaging Market
Flexible Packaging
Canada Flexible Plastic Packaging Market
Flexible Packaging
Argentina Flexible Plastic Packaging Market
Flexible Packaging
ASEAN Flexible Packaging Market