
 Retail Paper Bags Market | 2026-2036
Retail Paper Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Paper Bags Market Analytics
EU REACH compliance is expanding the cost-of-entry calculus for imported paper substrates, forcing non-European suppliers to certify fiber sourcing and chemical migration limits. Smurfit Kappa leverages integrated pulp-to-bag operations across Ireland and Spain to sustain margin control amid rising kraft pulp volatility. Huhtamaki Group anchors its retail bag portfolio through specialty coatings that resist grease penetration in food service channels. Mondi Group competes on lightweight high-strength constructions that reduce freight cost per unit for grocery distributors.
Retail paper bags are multi-ply kraft or recycled fiber containers, typically 70–150 gsm basis weight, formed through flat or satchel-bottom conversion with twisted paper or rope handles, designed for point-of-sale merchandise transport and brand display. Gusseted paper bags now dominate volume in clothing retail due to expandable side panels that accommodate irregular apparel shapes without tearing. Recycled paper bags command premium positioning in European grocery networks where post-consumer fiber thresholds are tightening under extended producer responsibility schemes. E-commerce end users represent the fastest-growing demand pool as corrugated outer boxes increasingly require internal paper cushioning and branded unboxing elements.
FDA food-contact substance notifications govern bleached kraft migration limits in US food service applications, while EPA industrial effluent guidelines constrain pulp mill discharge chemistry affecting North American substrate pricing. The EU F-Gas Regulation indirectly shapes bag economics by elevating energy costs for virgin pulp drying relative to recycled fiber processing. Stakeholders must monitor how California's SB 54 implementation timeline and India's BIS paper standards harmonization reshape procurement qualification criteria across multinational retail supply chains.
Market Dynamics
The Retail Paper Bags Market operates under intense regulatory compression as single-use plastic prohibitions cascade through national legislations, forcing substrate substitution at scale while kraft pulp volatility squeezes converter margins.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility mandates are compelling supermarket chains to eliminate lightweight plastic carry bags, redirecting volume toward certified paper alternatives.
- Quick-service restaurant packaging conversion:North American burger and coffee chains are replacing polyethylene-lined bags with grease-resistant paper constructions for hot food transport.
- Germany's national plastic ban:Grocery retailers face hard deadlines for checkout packaging transformation, creating guaranteed offtake for domestic and imported kraft bag suppliers.
Market Restraints
- Kraft pulp price volatility:Energy-intensive virgin fiber drying exposes converters to natural gas cost spikes under the EU F-Gas Regulation.
- Recycled fiber supply concentration:Post-consumer recovered paper collection networks cluster in Western European urban corridors, creating geographic chokepoints for substrate access.
- Polypropylene woven bag substitution:Reusable plastic totes retain cost advantage in bulk retail applications, limiting paper penetration in warehouse club channels.
Strategic Opportunities
- India BIS standards harmonization:Emerging formalization of paper bag specifications creates qualification pathways for exporters into organized retail supply chains.
- E-commerce unboxing experience:Branded interior paper cushioning and tissue elements represent incremental revenue per shipment for premium online retailers.
- California SB 54 implementation:Source-reduction mandates for plastic packaging are accelerating paper adoption in US West Coast grocery and apparel distribution.
Industry Challenges
- REACH chemical migration certification:Non-European substrate suppliers face 12-18 month qualification timelines to demonstrate compliance with fiber sourcing and chemical limit documentation.
- Coating equipment capex intensity:Water-based barrier coating lines require seven-figure capital commitments to achieve grease resistance parity with legacy polyethylene-laminated constructions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Paper Bags Market |
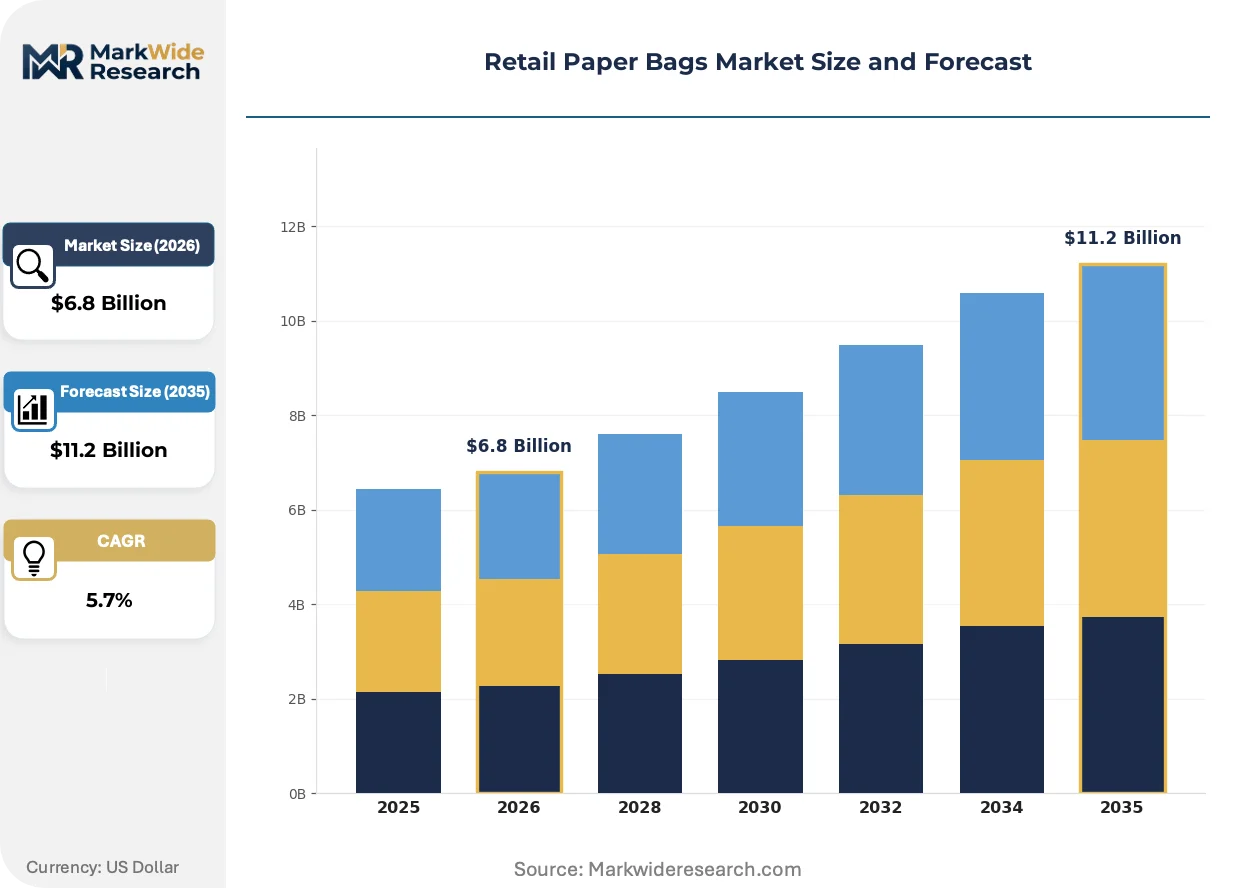
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Paper Bags, Gusseted Paper Bags, Kraft Paper Bags, Recycled Paper Bags End User: Grocery Stores, Clothing Retailers, Food Service, E-commerce Size: Small, Medium, Large, Extra Large Distribution Channel: Online Retailers, Offline Stores, Direct Sales, Third-party Distributors |
| Companies Covered | Smurfit Kappa, Huhtamaki Group, WestRock Company, Hotpack Packaging, Napco National, International Paper, Novolex Holdings, ProAmpac Intermediate Inc., Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Paper Bags Market Evolving Landscape
Active innovation across the Retail Paper Bags Market centers on functional barrier performance, regulatory compliance automation, and supply chain traceability as converters race to capture plastic-displacement volume.
Water-based fluorine-free grease barrier coatings are converging with high-speed flexographic printing to enable single-pass production of food-service-grade bags. Quick-service restaurant chains in France and Germany are specifying these constructions for hot sandwich and fried item packaging. This convergence is compressing the cost gap between polyethylene-laminated legacy bags and fully recyclable paper alternatives.
REACH Article 33 supply chain communication requirements are forcing substrate importers to deploy blockchain-traceable fiber certification systems. Industrial consequence includes mandatory documentation of recycled content percentages and chemical additive inventories for each production lot. Grocery distributors in the Netherlands and Belgium are now rejecting non-certified shipments, creating compliance-driven supplier selection.
Consolidated procurement by multinational retail banners is compressing supplier qualification cycles from multi-year frameworks to 90-day competitive tenders. Regional paper converters are losing shelf space to integrated pulp-to-bag operators capable of volume guarantees and pan-European logistics. This concentration is most visible in German and French supermarket network purchasing, where three-banner consolidation controls majority bag volume.
Retail Paper Bags Market Segmentation
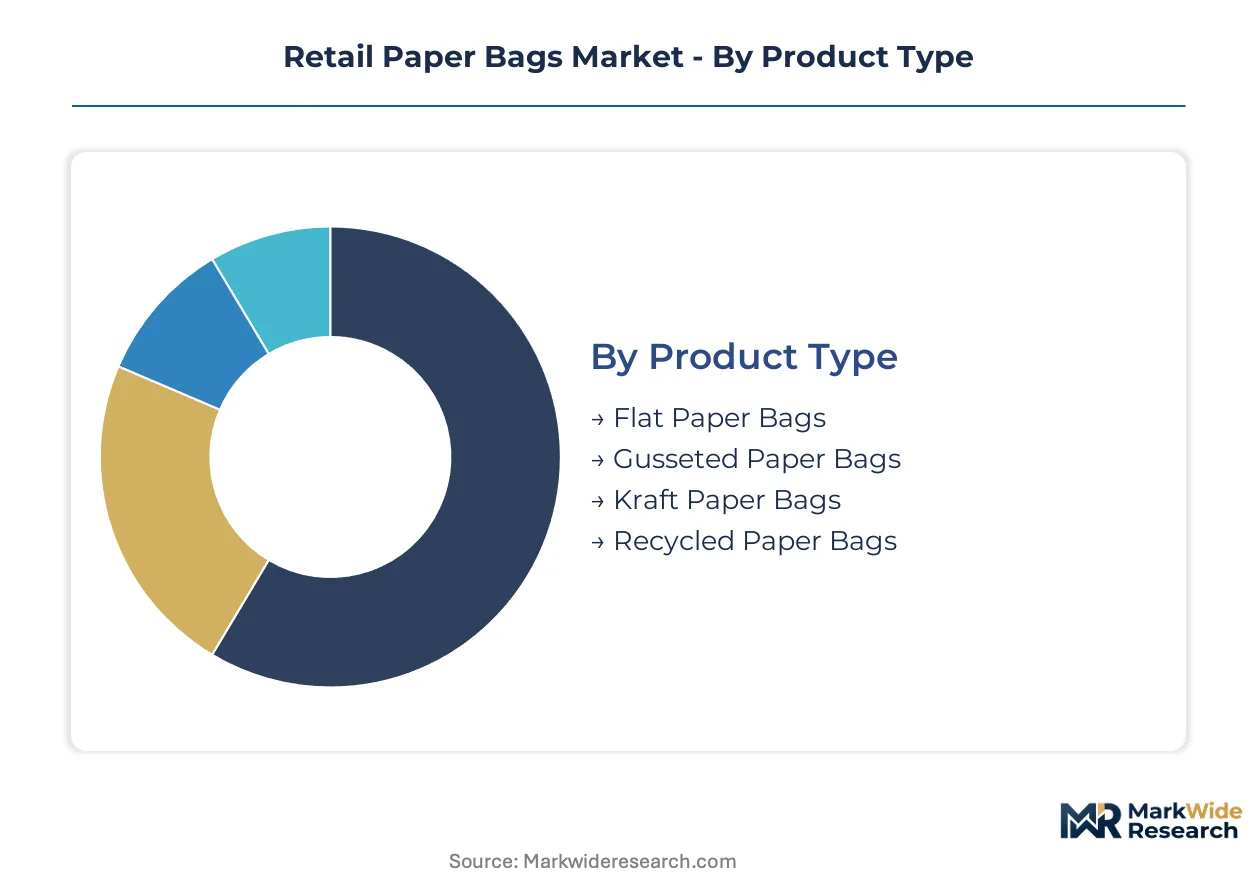
Paper bag converters must align production lines with distinct performance specifications across end-use applications. Each segment carries unique barrier requirements, handle strength tolerances, and print compatibility that determine equipment investment and margin structure.
Product Type:
Supply concentration in virgin kraft pulp processing has elevated the strategic importance of fiber sourcing flexibility across product categories.
- Gusseted Paper Bags:Expandable side panels constructed from multi-ply kraft (90–120 gsm) accommodate irregular merchandise shapes without seam failure. Clothing retailers in France and Germany specify these constructions for apparel transport, driven by plastic carry bag prohibitions that mandate paper alternatives at checkout.
- Recycled Paper Bags:Post-consumer fiber content ranging from 60% to 100% requires specialized pulping and de-inking to meet print quality standards. European grocery networks under extended producer responsibility schemes are tightening minimum recycled content thresholds, redirecting procurement toward certified suppliers with documented fiber chain-of-custody.
- Flat Paper Bags:Single-ply constructions (70–90 gsm) serve lightweight merchandise with minimal dimensional variation. Pharmacy and cosmetics retailers favor these for cost efficiency in high-volume, low-margin categories.
- Kraft Paper Bags:Virgin unbleached fiber delivers superior tensile strength for heavy-load applications. Quick-service restaurant chains specify these for hot food transport where grease resistance coatings add functional value.
Today's leader: Gusseted Paper Bags. Tomorrow's challenger: Recycled Paper Bags.
End User:
Application-specific barrier requirements create divergent margin profiles across customer categories.
- Food Service:Grease-resistant coatings and FDA food-contact compliance dominate specification sheets. Burger and coffee chains in North America are converting polyethylene-lined inventories to fluorine-free paper alternatives, compressing qualification timelines for approved suppliers.
- E-commerce:Branded interior elements and protective cushioning functions expand paper bag utility beyond pure transport. Premium online retailers specify custom-printed tissue and void-fill configurations to differentiate unboxing experiences.
- Grocery Stores:High-volume, standardized formats prioritize unit economics and supply security. German supermarket networks operate under national plastic ban deadlines that guarantee offtake for domestic and imported kraft bag suppliers.
- Clothing Retailers:Aesthetic print quality and handle durability drive specification. Seasonal collection launches demand flexible order quantities with rapid turnaround.
Food Service commands current volume. E-commerce climbs the fastest.
Size:
Equipment configuration and substrate width requirements vary substantially across dimensional categories.
- Medium:Standard checkout dimensions (250 x 120 x 300 mm) align with European supermarket conveyor systems and North American quick-service counter configurations. This format captures the highest production volume across automated bag-making lines.
- Large:Expanded capacity serves bulk grocery and family-portion food service applications. Warehouse club channels specify these for multi-item transport despite competition from reusable polypropylene totes.
- Small:Compact formats serve pharmacy, cosmetics, and specialty confectionery with limited dimensional requirements. Premium positioning supports higher per-unit margins.
- Extra Large:Reinforced constructions with rope handles accommodate bulky or heavy merchandise. Limited volume reflects niche application in home goods and seasonal retail.
Medium dominates throughput. Large gains share fastest.
Distribution Channel:
Procurement consolidation by multinational retail banners is compressing channel diversity and supplier access.
- Third-party Distributors:Pan-European logistics networks aggregate demand across multiple retail banners, offering volume guarantees that attract integrated pulp-to-bag operators. Smurfit Kappa and Mondi Group leverage these relationships to defend margin control.
- Direct Sales:Large-format grocery and restaurant chains negotiate multi-year supply agreements with converters capable of dedicated production lines. These arrangements require capital commitment to coating and printing equipment.
- Offline Stores:Traditional wholesale and cash-and-carry channels serve independent retailers with standardized inventory and minimal customization. Price competition is intense.
- Online Retailers:Digital procurement platforms enable smaller converters to reach fragmented end-users without established distributor relationships. Quality verification and certification documentation remain barriers to scaling.
Third-party Distributors anchor volume. Direct Sales expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pulp mill engineers and paper converting technicians concentrate in Western European industrial corridors and select North American manufacturing belts. These workforce clusters anchor production capacity for kraft bag substrates and finished retail packaging. Geographic proximity to recovered paper collection networks shapes regional competitive positioning.
Germany
Supermarket checkout conversion and quick-service restaurant chains drive bag demand under the national plastic carry bag prohibition. The Verpackungsgesetz packaging law mandates extended producer responsibility compliance for all checkout packaging formats. The Rhine-Ruhr industrial corridor hosts integrated pulp-to-bag operations serving pan-European grocery distributors.
France
Apparel retail networks and bakery chains specify gusseted paper constructions for merchandise transport and food service applications. The AGEC anti-waste law imposes recycled content minimums for single-use packaging placed on the market. The Lyon-Saint-Étienne manufacturing cluster specializes in high-print-quality bag finishing for luxury retail brands.
United States
Quick-service burger and coffee chains convert polyethylene-lined inventories to grease-resistant paper alternatives for hot food transport. FDA food-contact substance notifications govern bleached kraft migration limits in food service applications. The Wisconsin-Michigan paper belt maintains virgin kraft pulp capacity serving North American bag converters.
India
Organized retail expansion and e-commerce fulfillment operations generate demand for standardized bag formats in urban consumption centers. BIS paper standards harmonization creates formal qualification pathways for domestic and imported substrate suppliers. The Mumbai-Pune industrial corridor hosts emerging converting capacity targeting modern trade grocery networks.
Netherlands
Grocery distributors and food service wholesalers prioritize certified fiber sourcing with blockchain-traceable documentation. REACH Article 33 supply chain communication requirements mandate chemical additive disclosure for each production lot. The Rotterdam port logistics cluster facilitates substrate importation for Benelux converting operations.
Retail Paper Bags Market Competitive Landscape
The competitive structure tilts toward integrated pulp-to-bag operators capable of volume guarantees and pan-European logistics coverage. Regional converters face procurement consolidation as multinational retail banners compress supplier qualification cycles from multi-year frameworks to competitive tenders. Two strategic archetypes dominate: vertically integrated forest products conglomerates with captive pulp supply, and specialized coating and printing converters focused on food-service barrier performance. Capacity expansion and strategic partnerships represent the dominant competitive moves as players race to capture plastic-displacement volume.
Among Ireland-based integrated operators, Smurfit Kappa occupies a position exemplifying captive fiber sourcing across Iberian and British production networks. Finnish Huhtamaki Group and Austrian Mondi Group represent the specialty-coated tier, with the former anchoring grease-resistant food service applications and the latter occupying lightweight high-strength constructions for grocery distribution. These three names illustrate how geographic diversification and substrate integration separate scale leaders from regional competitors.
| Leading Market Players |
|---|
| Smurfit Kappa |
| Huhtamaki Group |
| WestRock Company |
| Hotpack Packaging |
| Napco National |
| International Paper |
| Novolex Holdings |
| ProAmpac Intermediate Inc. |
| Mondi Group |
| Others |
Value Network & Pricing Analysis
Water-based fluorine-free barrier coating adoption is compressing production economics for food-service-grade bags while simultaneously concentrating supply among converters with seven-figure capital commitments. This technology transition rewards integrated pulp-to-bag operators with captive coating capacity, squeezing regional competitors dependent on toll-coating arrangements.
Pricing Analysis
Coating and printing services are increasingly unbundled from substrate supply, with buyers negotiating barrier-function contracts separately from kraft paper procurement. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified European supply from BIS-qualifying Indian exports and uncertified spot-market inventory. Price differentiation rests on recycled content thresholds and blockchain-traceable fiber documentation. Cost compression in standard-grade kraft is intensifying because energy-intensive virgin fiber drying exposes converters to natural gas spikes under EU F-Gas Regulation. Quick-service restaurant chains demonstrate highest price sensitivity due to high-volume, low-margin food transport economics, while luxury apparel retailers absorb premium positioning for custom-printed gusseted constructions.
Supply Chain Analysis
Dual-sourcing mandates from German and French supermarket networks require buyers to qualify minimum two substrate suppliers per production lot, fragmenting volume across integrated operators. Geographic supply concentration centers on Finland, Ireland, and Austria for virgin kraft pulp, with Spain and Portugal hosting secondary converting capacity. Raw material dependencies draw from Nordic softwood fiber, post-consumer recovered paper from Western European urban collection networks, and water-based barrier chemistries from specialty coatings manufacturers. Single-source vulnerability persists in blockchain-traceable fiber certification systems, where only three providers meet REACH Article 33 documentation standards. Distribution runs through pan-European third-party logistics networks aggregating demand across consolidated retail banners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through fluorine-free coating technology premiums and recycled fiber certification tiering, with converters capturing value from plastic-displacement mandates.
For Market Incumbents: Cement captive supply security through backward integration into Nordic softwood pulp assets or long-term offtake agreements with Finnish and Swedish mill operators. Invest in multi-line coating capacity to service parallel qualification tracks for EU REACH and US FDA food-contact compliance, defending against specialty converters targeting quick-service restaurant chains with faster certification timelines.
For New Entrants and Emerging Players: Begin with e-commerce interior packaging and unboxing elements, where branded tissue and void-fill configurations face lower barrier-to-entry than food-service grease resistance. Target Indian organized retail networks ahead of BIS standards harmonization completion, offering documented fiber chain-of-custody as qualification differentiator. Pursue direct sales relationships with premium online retailers seeking rapid-turn customization unavailable from volume-focused integrated operators.
For Investors and Strategic Acquirers: Roll-up economics work for regional European converters with established REACH certification and underutilized coating lines because multinational retail banner consolidation is compressing supplier counts and creating distressed asset opportunities. Target mid-scale operators in the Lyon-Saint-Étienne and Rhine-Ruhr clusters with proven quick-service restaurant relationships. Watch California SB 54 implementation pace as inflection indicator for North American plastic-displacement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Barrier Coating Scale-Up | REACH compliance and FDA food-contact certification unlock quick-service restaurant volume in France and Germany. |
| Blockchain-Traceable Fiber Certification | Netherlands and Belgium distributors now reject non-documented shipments, creating compliance-driven supplier selection. |
| Recycled Content Threshold Expansion | AGEC anti-waste law minimums in France redirect procurement toward certified post-consumer fiber suppliers. |
| Pan-European Logistics Integration | Three-banner consolidation in German and French supermarket networks demands volume guarantees across multiple jurisdictions. |
| E-Commerce Interior Packaging Development | Premium online retailers specify custom-printed tissue configurations to differentiate unboxing experiences. |
Research Methodology
Coverage spans Western Europe, North America, and South Asia, with primary inputs from each region combined with secondary validation. Interviews with paper converting plant managers, grocery procurement directors, quick-service restaurant packaging specification leads, and EU regulatory compliance officers informed substrate sourcing and barrier coating technology assessments. Secondary sources include ECHA REACH registration databases, FDA food-contact substance notification filings, BIS draft paper standards documentation, and customs trade data for kraft pulp and finished bag movements. Bottom-up volume estimates triangulated against top-down pulp consumption and converting capacity analyses.
Granularity extends to product type, end-use application, size format, and distribution channel dimensions across the modeling period. Segment-level CAGRs derived from elasticity-adjusted demand curves incorporating regulatory mandate timelines and substrate price volatility scenarios. Forecast inputs include EU Packaging and Packaging Waste Regulation implementation pace, Germany Verpackungsgesetz enforcement intensity, and California SB 54 source-reduction milestone adherence.
Several conditions sit outside the modeled scope, including unforeseen delays in India BIS standards finalization, abrupt natural gas price dislocations affecting Nordic pulp drying economics, and substitution acceleration toward reusable polypropylene totes in warehouse club channels. Forecasts reflect assumptions around regulatory compliance cost pass-through and coating technology diffusion rates. Deviation in EU F-Gas Regulation energy cost trajectory or REACH chemical migration limit tightening would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Global Fanfold Corrugated Market
Paper & Paperboard Packaging
Waxing Base Paper Market
Paper & Paperboard Packaging
South Africa Paper Packaging Market
Paper & Paperboard Packaging
Middle East and Africa Paper Cone Market
Paper & Paperboard Packaging
China Corrugated Packaging Market
Paper & Paperboard Packaging
Australia Paper Packaging Market
Paper & Paperboard Packaging
Egypt Paperboard Packaging Market
Paper & Paperboard Packaging
South Korea Paper Packaging Market
Paper & Paperboard Packaging
US Paper Cups and Paper Plates Market
Paper & Paperboard Packaging
Poly Coated Paperboard Market
Paper & Paperboard Packaging
Coated Duplex Board Market
Paper & Paperboard Packaging
UAE Corrugated Board Packaging Market
Paper & Paperboard Packaging
Hanging Box Market
Paper & Paperboard Packaging
Unbleached Kraft Paperboard Market
Paper & Paperboard Packaging
Paper Band Market
Paper & Paperboard Packaging
C1S Packaging Paper Market