
 North America Paper Bags Market | 2026-2036
North America Paper Bags Market Size, Share, and Industry Trends Forecast 2026-2036
North America Paper Bags Market Analytics
Canadian kraft paper mill expansions are realigning raw material flows across the continent. International Paper Company leverages its integrated pulp-to-bag infrastructure to sustain cost advantages in heavyweight segments. WestRock Company anchors regional supply through extensive corrugated and paperboard recycling networks. Georgia-Pacific LLC competes aggressively on scale, dominating bulk orders from national grocery chains with consistent quality standards.
North America paper bags are multiwall or single-ply containers manufactured from bleached or unbleached kraft pulp, typically ranging from 30 to 120 pounds per ream in basis weight, designed for carrying, protecting, or displaying retail and food products. Kraft bags lead product type demand due to superior tensile strength and printability for branded retail applications. E-commerce end users represent the fastest-growing segment as corrugated alternatives face pressure from dimensional weight pricing; grocery chains remain the volume anchor with stable, high-frequency replenishment cycles. Heavyweight thickness grades capture disproportionate margin pools because they command premium pricing in specialty food and industrial chemical packaging where failure tolerance is minimal.
The EPA enforces recycled content standards under the Resource Conservation and Recovery Act, while state regulators in California and New York administer plastic bag bans that directly expand addressable demand for paper substitutes. OSHA and FDA rules govern worker safety in converting facilities and food-contact compliance for packaging materials, respectively. Stakeholders must monitor pending federal extended producer responsibility legislation and assess capacity commitments before regional pulp supply tightens further.
Market Dynamics
The North America paper bags market is being fundamentally restructured by state-level plastic bag bans cascading across the United States and Canada, forcing grocery and retail chains into rapid packaging transitions while pulp supply tightens across the continent.
Growth Catalysts
- New York's plastic bag ban:The state's Bag Waste Reduction Act eliminates single-use plastic at checkout, redirecting volume toward paper alternatives in one of the highest-density retail corridors on the continent.
- E-commerce dimensional weight pricing:Major carriers penalize bulky corrugated, pushing fulfillment centers toward lightweight paper mailers and flat-bottom bags for apparel and soft goods.
- California's recycled content mandates:The state's rigid post-consumer fiber requirements for packaging create guaranteed offtake for domestic recycled pulp mills serving bag converters.
Market Restraints
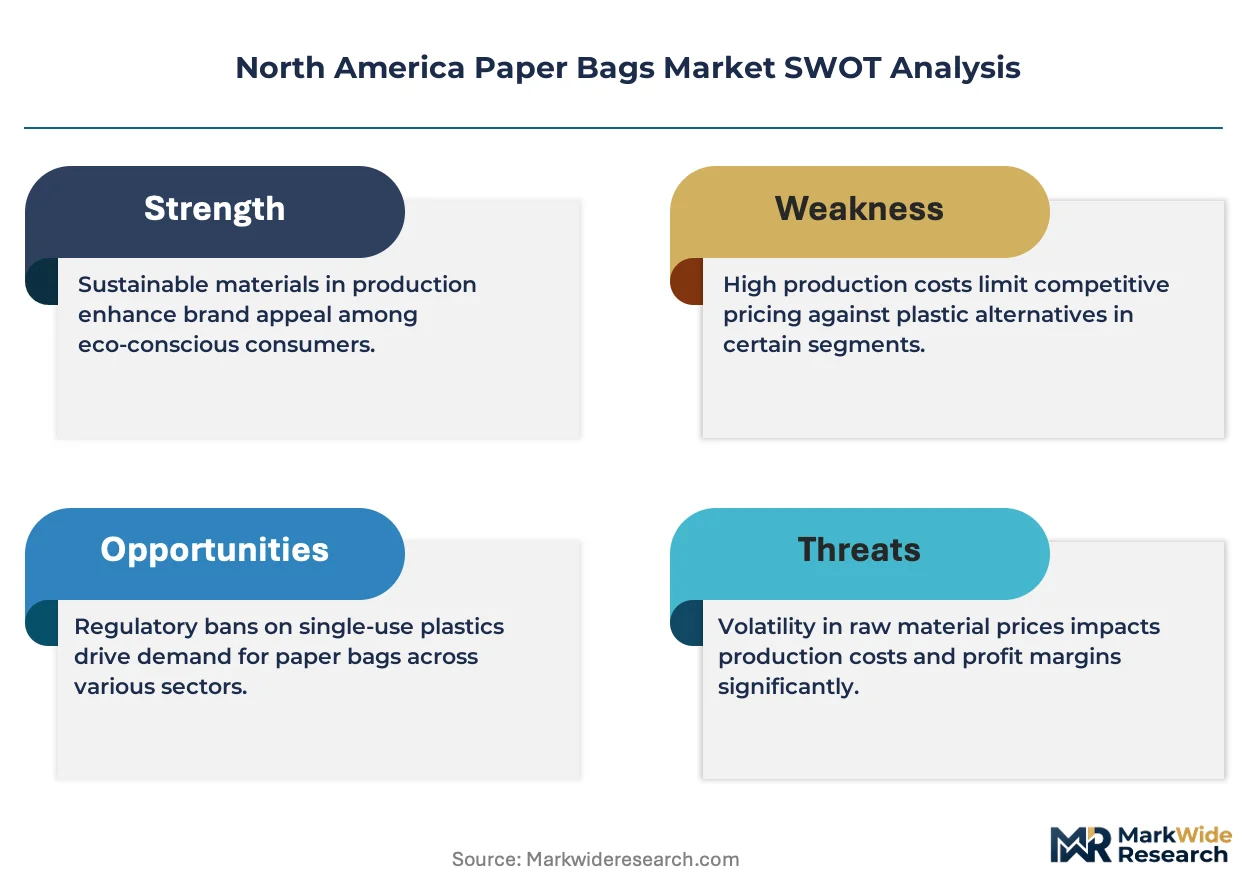
- Kraft pulp price volatility:Canadian mill maintenance cycles and energy input spikes transmit directly to bag converter margins, compressing profitability in single-ply commodity segments.
- Southeast Asian recycled fiber competition:Lower-cost imported recovered paper undercuts domestic recycling economics, threatening the feedstock base for EPA-compliant recycled content bags.
- Reusable bag substitution:Durable polypropylene and cotton totes, promoted by environmental groups and some municipal ordinances, capture repeat-use occasions that paper cannot serve.
Strategic Opportunities
- Quebec's underpenetrated grocery sector:Provincial retailers lag Ontario and British Columbia in plastic-to-paper transitions, creating first-mover expansion potential for bag suppliers with French-language print capabilities.
- Food service delivery packaging:Third-party delivery platforms need grease-resistant paper bags for hot prepared foods, a specification gap that specialty barrier coatings can fill.
- USDA BioPreferred program:Federal procurement preference for biobased products opens institutional channels—military commissaries, national park concessions, federal cafeterias—unavailable to conventional suppliers.
Industry Challenges
- Flexographic print technician shortage:Converters struggle to staff presses capable of the high-resolution branding that retail chains demand for private-label bag programs.
- FDA food-contact compliance timelines:New barrier coatings require extensive migration testing, delaying product launches by 12-18 months against aggressive customer deadlines.
- Legacy warehouse management integration:Paper bag specifications vary by SKU in ways that confound automated picking systems designed for uniform plastic film products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Paper Bags Market |
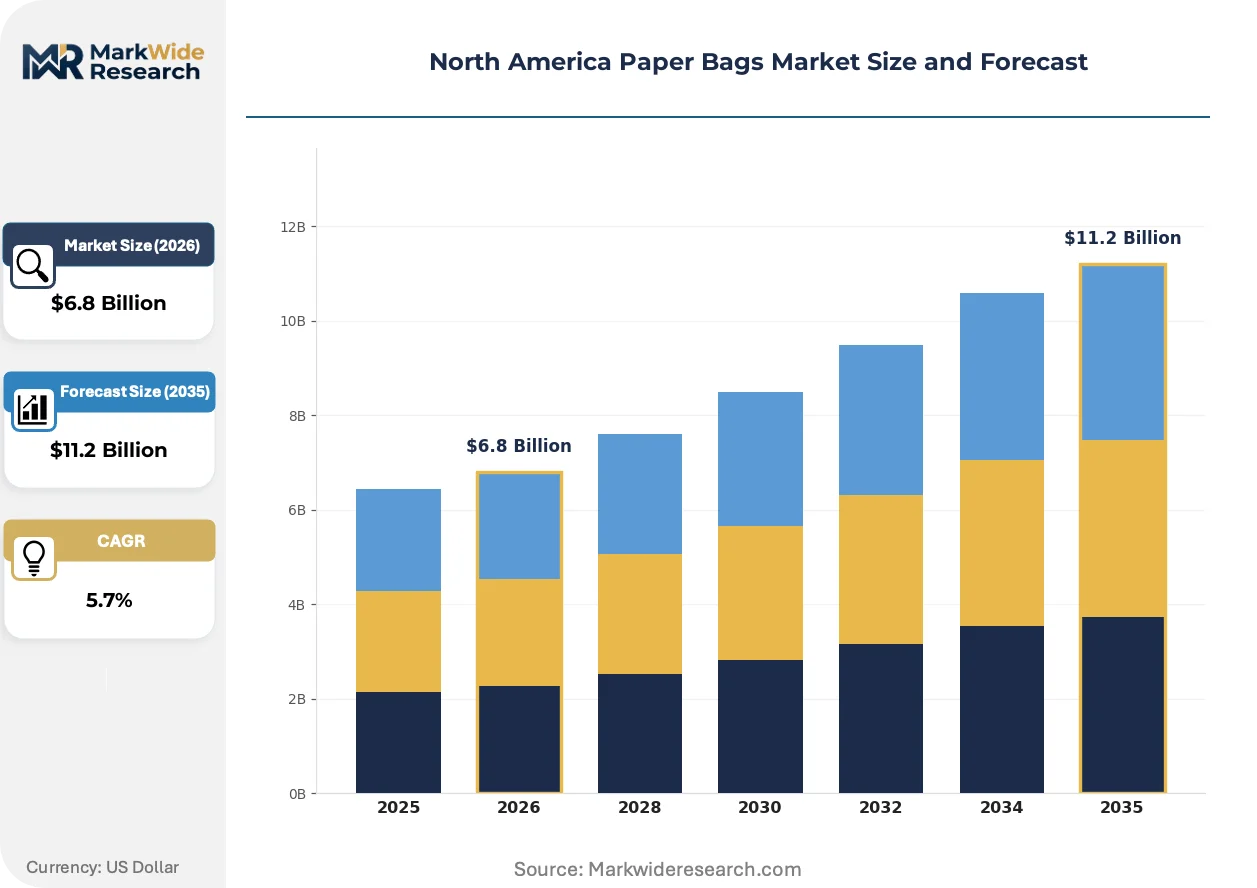
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Paper Bags, Satchel Bags, Pouch Bags, Kraft Bags End User: Retail Stores, Food Service, E-commerce, Grocery Chains Thickness: Lightweight, Medium Weight, Heavyweight, Extra Heavyweight Closure Type: Open Top, Self-Sealing, Taped, Folded |
| Companies Covered | ProAmpac, American Packaging Corporation, International Paper Company, Gateway Packaging Company, Fischer Paper Products, WestRock Company, Georgia-Pacific LLC, Graphic Packaging International, Novolex Holdings, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Paper Bags Market Evolving Landscape
Material science advances and regulatory sequencing are compressing product development cycles across the North American paper bag value chain. Converters now compete on barrier performance and print fidelity rather than commodity tonnage.
Water-based barrier coatings are converging with traditional kraft substrates to create grease-resistant, heat-stable packaging without plastic lamination. Quick-service restaurant chains in California and New York are adopting these specifications for fried food carryout. The technology is converging with fiber-based packaging to displace polyethylene-lined alternatives in municipal composting jurisdictions where film contamination is prohibited.
The EPA's recycled content standards under the Resource Conservation and Recovery Act are tightening enforcement timelines for packaging sold into federal supply chains. Domestic mills must now document chain-of-custody from recovered paper collection through finished bag production. Food-contact bag manufacturers face the steepest compliance burden, as FDA migration limits apply simultaneously with EPA fiber tracking requirements.
Consolidated grocery procurement teams are centralizing bag specifications across banner networks, compressing supplier rosters from regional fragmentation toward national-scale contracts. Independent converters in the US Midwest and Atlantic Canada are losing shelf space to integrated producers with multi-plant redundancy. Texas and Florida grocers exhibit the most aggressive consolidation pace, driven by population growth and private-label expansion.
North America Paper Bags Market Segmentation
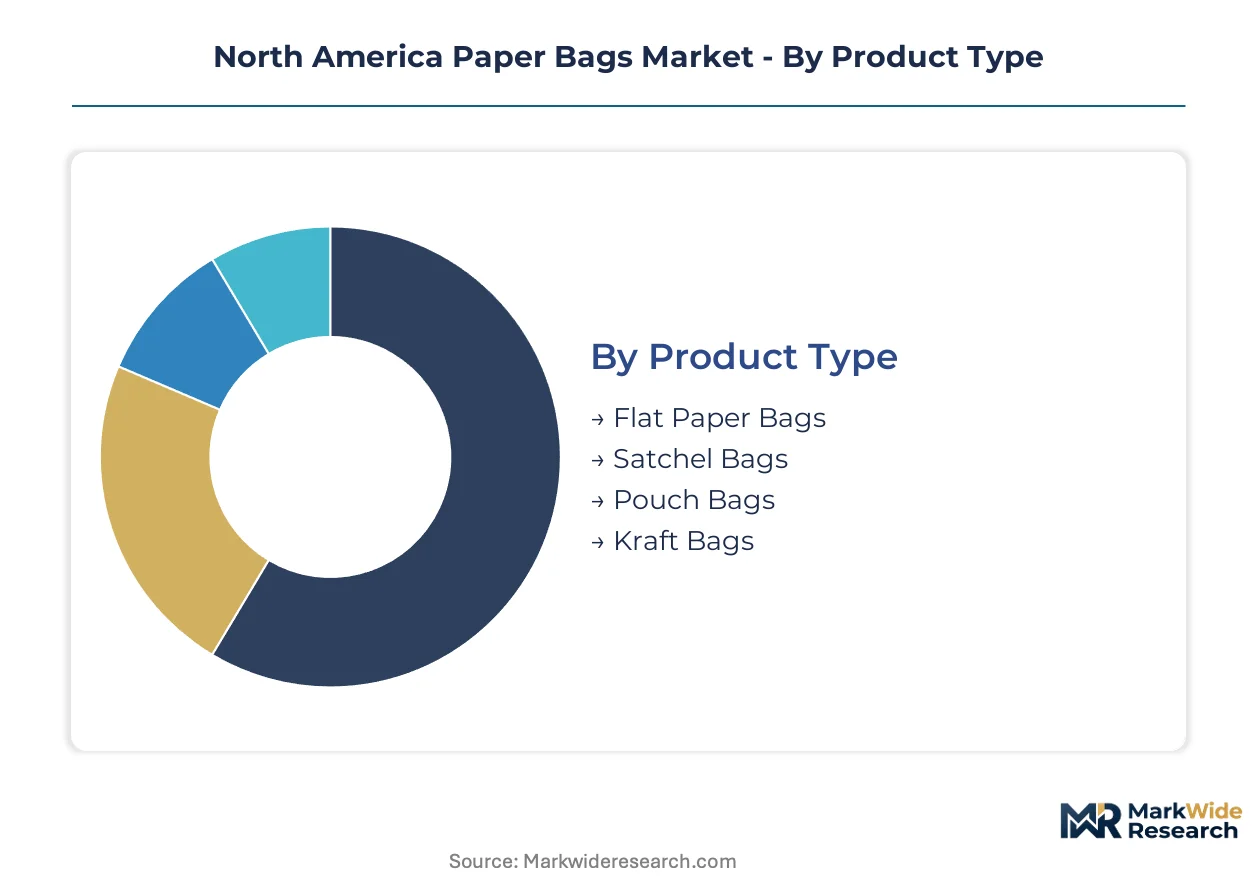
Paper bag specifications diverge sharply across North American end-uses, with grocery volume requirements clashing against e-commerce dimensional constraints and food-service barrier demands. Converters must maintain parallel production lines for commodity kraft sacks and precision-printed retail carriers.
Product Type:
Volume concentrates in utilitarian formats while premium positioning shifts toward branded, structured designs.
- Kraft Bags:Unbleached sulfate pulp construction delivers tensile strength exceeding 30 pounds per square inch, suiting bulk grocery loads. Demand clusters in California and New York checkout lanes where municipal plastic bans have eliminated film alternatives. EPA recycled content mandates reinforce domestic kraft's feedstock advantage over imported substrates.
- Satchel Bags:Gusseted side panels and flat bottoms enable stable shelf presentation for apparel and specialty retail. Northeast US department stores and Toronto fashion retailers specify high-grammage satchels with four-color flexographic branding. The format commands margin premiums through print complexity that commodity grocery sacks cannot match.
- Flat Paper Bags:Single-ply construction without side expansion serves lightweight pharmacy and boutique applications.
- Pouch Bags:Envelope-style closures protect documents and small electronics in e-commerce fulfillment.
Today's leader: Kraft Bags. Tomorrow's challenger: Satchel Bags.
End User:
Procurement patterns separate high-frequency replenishment from specification-intensive custom orders.
- Grocery Chains:National banners operate centralized purchasing with strict basis-weight tolerances and 48-hour replenishment cycles. Texas and Florida operators drive volume growth through population in-migration and private-label expansion.
- E-commerce:Dimensional weight pricing from major carriers penalizes corrugated bulk, pushing fulfillment centers toward lightweight paper mailers. The segment climbs fastest as apparel and soft-goods shippers abandon box-based packaging.
- Retail Stores:Department and specialty stores demand print fidelity for brand consistency across banner networks.
- Food Service:Third-party delivery platforms require grease-resistant barriers for hot prepared foods.
Volume dominance: Grocery Chains. Specification complexity: Food Service.
Thickness:
Margin pools concentrate at extremes while mid-grades face commoditization pressure.
- Heavyweight:Exceeding 80 pounds per ream basis weight, these grades serve industrial chemical and specialty food packaging where failure tolerance approaches zero. FDA food-contact compliance and OSHA handling requirements add regulatory layering that smaller converters cannot navigate.
- Lightweight:Sub-50 pound per ream construction dominates pharmacy and single-item retail carryout. California recycled content mandates favor domestic lightweight production using post-consumer fiber streams.
- Medium Weight:General-purpose grocery sacks balance cost and durability for standard checkout loads.
- Extra Heavyweight:Reinforced constructions exceed 100 pounds per ream for abrasive or moisture-critical contents.
Premium capture: Heavyweight. Volume anchor: Lightweight.
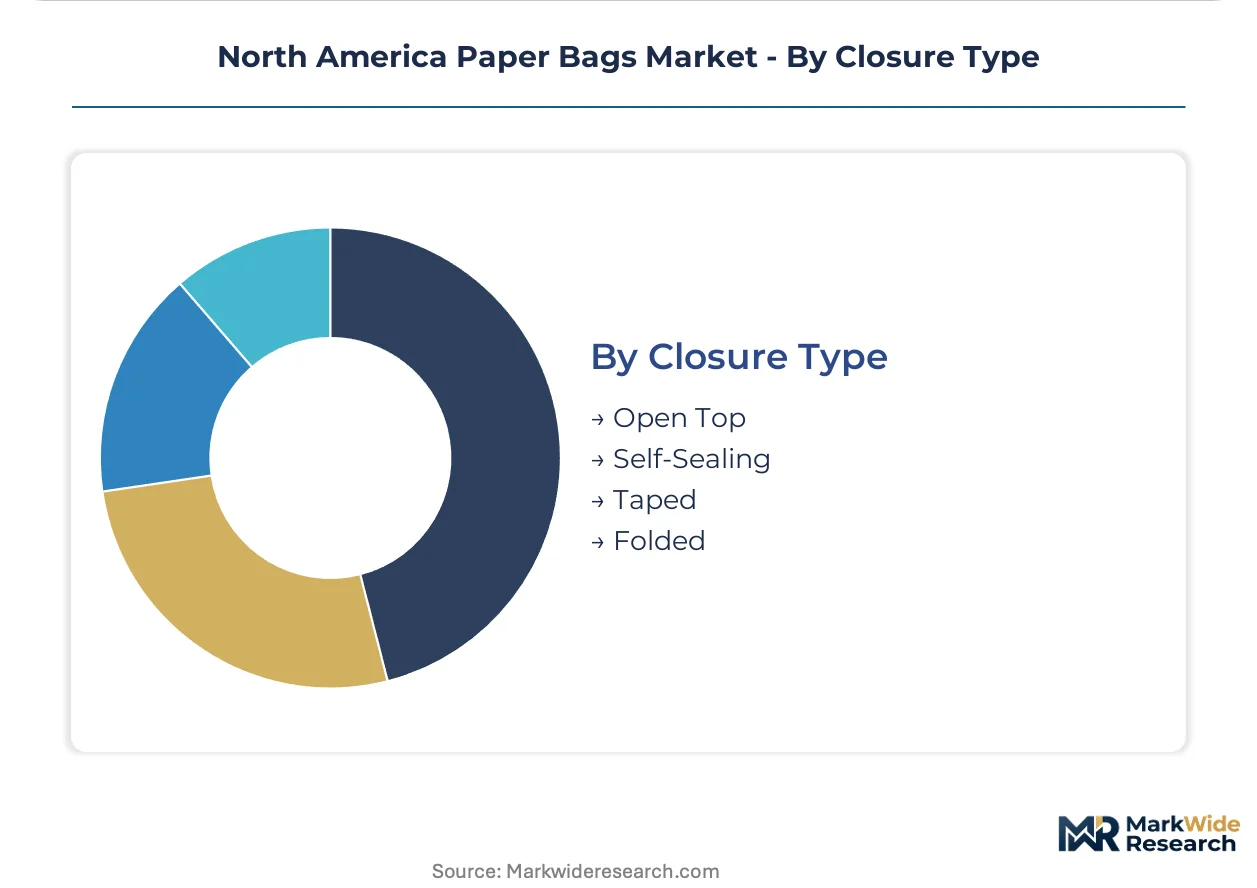
Closure Type:
Automation compatibility and theft deterrence drive specification divergence.
- Open Top:Unobstructed access suits high-throughput grocery checkout where speed trumps security. The format maintains cost leadership through minimal converting steps.
- Self-Sealing:Adhesive strips enable tamper-evident e-commerce delivery without additional packing tape. The format gains share fastest as fulfillment centers automate final-mile packaging.
- Taped:Reinforced gummed closures secure document and currency transport in banking and legal services.
- Folded:Interlocking flap designs provide reclosable food service applications without plastic mechanisms.
Commodity standard: Open Top. Automation enabler: Self-Sealing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing production maps as bag converters chase compliance-cost advantages across state and provincial boundaries. Canadian mills leverage lower energy-input costs and integrated pulp supply to serve cross-border demand, while US converters cluster near population centers with the strictest plastic-ban enforcement.
United States
State-level plastic bag bans in California and New York redirect massive grocery volume toward paper alternatives. The EPA's recycled content standards under the Resource Conservation and Recovery Act create compliance layering that favors domestic converters with chain-of-custody documentation. Texas and Florida grocers drive volume growth through population in-migration and centralized procurement consolidation.
Canada
Quebec's underpenetrated grocery sector lags Ontario and British Columbia in plastic-to-paper transitions, creating first-mover expansion potential. Provincial kraft paper mill expansions in Ontario realign raw material flows across the continent. Toronto fashion retailers specify high-grammage satchels with four-color flexographic branding that commands margin premiums.
Mexico
Cross-border manufacturing clusters in Nuevo León and the Bajío Region supply lightweight paper bags for US pharmacy and boutique applications under USMCA tariff preferences. Mexican converters exploit labor-cost advantages in single-ply commodity segments. Monterrey industrial parks host specialty coating operations serving California food-service demand.
North America Paper Bags Market Competitive Landscape
United States producers anchor the high-volume grocery tier; Canadian specialists hold pulp-integrated positions in kraft sack supply. The vendor base splits between national-scale integrated producers and regional converters with print-specialization capabilities. Three archetypes dominate: pulp-to-bag integrated giants, flexographic print specialists, and recycled-fiber niche operators. Competitive moves center on multi-plant redundancy investments and French-language print capacity for Quebec expansion.
Within the integrated-producer tier, International Paper Company and WestRock Company exemplify scale-driven positioning through captive pulp supply and extensive recycling networks. Georgia-Pacific LLC anchors the bulk-order segment with consistent quality standards for national grocery chains. These three entities represent the consolidation pressure squeezing independent Midwest and Atlantic Canada converters.
| Leading Market Players |
|---|
| ProAmpac |
| American Packaging Corporation |
| International Paper Company |
| Gateway Packaging Company |
| Fischer Paper Products |
| WestRock Company |
| Georgia-Pacific LLC |
| Graphic Packaging International |
| Novolex Holdings, LLC |
| Others |
Value Network & Pricing Analysis
Flexographic print technician shortages in the US Midwest and Atlantic Canada compress converter margins while widening spreads between commodity grocery sacks and precision-branded retail carriers. Labor-cost differentials between Quebec's underpenetrated converting base and Ontario's integrated mill networks enable tiered pricing that rewards French-language print capabilities.
Pricing Analysis
Retailer markup layers dominate final bag pricing, with national grocery chains extracting volume rebates that compress converter margins to single digits. Three-tier pricing structure across premium, standard, and economy levels separates FDA-compliant food-contact grades from industrial chemical specifications and lightweight pharmacy carryouts. Price differentiation hinges on barrier coating complexity and recycled content certification tier. Pricing pressure stems from Southeast Asian recycled fiber imports undercutting domestic pulp economics. Independent converters exhibit highest price sensitivity due to single-plant dependency; integrated producers with captive pulp supply demonstrate lowest.
Supply Chain Analysis
Workforce availability constraints in Nuevo León and Monterrey industrial parks limit specialty coating capacity expansion despite USMCA tariff advantages. Supply concentrates in Canada, the United States, and Mexico, with Canadian mills anchoring kraft pulp supply through integrated infrastructure. Raw material flows draw from recovered paper collection networks, unbleached sulfate pulp streams, and water-based barrier coating chemistries. Single-source vulnerability pervades the FDA-compliant food-contact segment where migration testing timelines lock in supplier relationships. Distribution runs through national grocery procurement hubs, corrugated recycling networks, and third-party logistics providers serving e-commerce fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quebec's lagging plastic-to-paper transition against California's and New York's mature ban regimes creates a geographic-arbitrage window where provincial regulatory delay meets Ontario's pulp-integrated cost base.
For Market Incumbents: To counter Southeast Asian recycled fiber price competition, International Paper Company and WestRock Company should deepen backward integration into Ontario kraft mill capacity while securing chain-of-custody documentation for EPA-compliant federal supply chains. Georgia-Pacific LLC must defend national grocery banner relationships through multi-plant redundancy investments in Texas and Florida growth corridors. For New Entrants and Emerging Players: E-commerce platform direct procurement channels offer the most penetrable entry vector for lightweight mailer specialists unburdened by legacy warehouse management integration debt. Quebec grocery retailers represent the highest white-space opportunity, requiring French-language print capabilities that incumbent Midwest converters lack. Food service delivery packaging specifications for grease-resistant barriers provide a specification-gap entry point against commoditized grocery sack incumbents. For Investors and Strategic Acquirers: Integrated pulp-to-bag producers are the most active acquirer in this space, seeking flexographic print specialists to fill technician shortages and barrier-coating innovators to capture food service delivery demand. The five-to-ten year viability window favors targets with USDA BioPreferred certification access and Quebec expansion-ready French-language assets. Watch for federal extended producer responsibility legislation as the inflection signal that accelerates consolidation beyond organic growth rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Pulp | Captive supply from Ontario mill expansions insulates margins against Canadian maintenance cycle volatility. |
| Barrier Coating R&D Investment | FDA-compliant grease-resistant specifications unlock third-party delivery platform contracts in California and New York. |
| French-Language Print Capacity | Quebec grocery sector penetration requires localized branding capabilities that Midwest converters cannot match. |
| Multi-Plant Redundancy Buildout | Texas and Florida population in-migration demands geographic distribution resilience for national banner contracts. |
| USDA BioPreferred Certification | Federal procurement preference opens institutional channels including military commissaries and national park concessions. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market. The analysis combines interviews with flexographic print technicians, grocery chain procurement directors, FDA regulatory consultants, and kraft mill operations managers with secondary validation from EPA waste reduction guidelines, state-level plastic bag ban statutes, USMCA tariff schedules, and SEC filings from integrated paper producers. Bottom-up converter capacity estimates triangulate against top-down grocery and e-commerce packaging demand projections.
Rate-of-change decomposition separates volume growth from price realization across the analysis window. The analytical framework models product type, end user, thickness grade, and closure configuration dimensions alongside regional regulatory cluster intensity. CAGRs derive from segment-level demand elasticity coefficients and pulp input cost trajectory assumptions. Forecast inputs incorporate dimensional weight pricing adoption curves from major carriers and municipal composting jurisdiction expansion patterns.
The model assumes a particular technology adoption path; alternative pathways for water-based barrier coatings would alter the outlook if FDA migration testing timelines compress or extend. Forecasts reflect assumptions about state-level plastic ban cascade velocity and Canadian mill maintenance cycle regularity. Material deviation in federal extended producer responsibility legislation or Southeast Asian recycled fiber tariff policy warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Global Multi Depth Corrugated Boxes Market
Paper & Paperboard Packaging
Die Cut Box Market
Paper & Paperboard Packaging
South Africa Paper Packaging Market
Paper & Paperboard Packaging
MMA Film & Sheet Market
Paper & Paperboard Packaging
Kitchen Roll Market
Paper & Paperboard Packaging
Coated Duplex Board Market
Paper & Paperboard Packaging
United States Corrugated Packaging Market
Paper & Paperboard Packaging
Paper IBC Container Market
Paper & Paperboard Packaging
Postage Stamp Paper Market
Paper & Paperboard Packaging
United Kingdom Corrugated Packaging Market
Paper & Paperboard Packaging
Medical Packaging Paper Market
Paper & Paperboard Packaging
Egypt Paper Packaging Market
Paper & Paperboard Packaging
GCC Paper Cup Market
Paper & Paperboard Packaging
Converting Paper Market
Paper & Paperboard Packaging
Qatar Paper Packaging Products Market
Paper & Paperboard Packaging
Paper Bag Box Market