
 Vegetable Parchment Paper Market | 2026-2036
Vegetable Parchment Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Vegetable Parchment Paper Market Outlook
Asset-light contract manufacturing and third-party tolling arrangements are reconfiguring competitive entry barriers for mid-tier parchment producers. Nordic Paper leverages its integrated pulp-to-paper operations across Scandinavian mills to sustain cost discipline in bleached grades. Ahlstrom-Munksjö anchors European supply through specialty coating capabilities that differentiate performance for high-temperature baking applications. Reynolds Consumer Products competes via dominant shelf placement in North American retail channels, while Paterson Pacific Parchment Company specializes in custom-width rolls for industrial converters.
Vegetable parchment paper is a cellulose-based sheet material produced by passing unsized paper through a sulfuric acid bath that gelatinizes surface fibers, creating a dense, grease-resistant barrier with wet strength exceeding 30% of dry tensile values. Its primary commercial purpose centers on non-stick food preparation surfaces and moisture-resistant wrapping for baked goods, roasted proteins, and confectionery items. Unbleached grades retain natural fiber coloration and command preference among organic-certified food producers, while coated variants incorporating silicone layers represent the fastest-expanding margin pool as home baking participation stays elevated. Specialty parchment integrating compostability certifications sits at early commercial scale but attracts disproportionate R&D allocation from sustainability-focused mills.
The U.S. FDA regulates vegetable parchment paper as an indirect food additive under 21 CFR 176.170, specifying extractives limits that govern acid bath chemistry and rinse protocols. The EU's Framework Regulation EC 1935/2004 and Good Manufacturing Practice Regulation EC 2023/2006 impose migration testing requirements that shape export qualification costs for non-European suppliers. California's SB 54 extended producer responsibility mandates and Germany's Verpackungsgesetz recycling quotas are forcing reformulation investments toward fiber-based barrier coatings. Stakeholders must monitor evolving compostability certification fragmentation between BPI, TÜV Austria, and home-composting standards as these labels increasingly determine distributor acceptance and retail listing decisions.
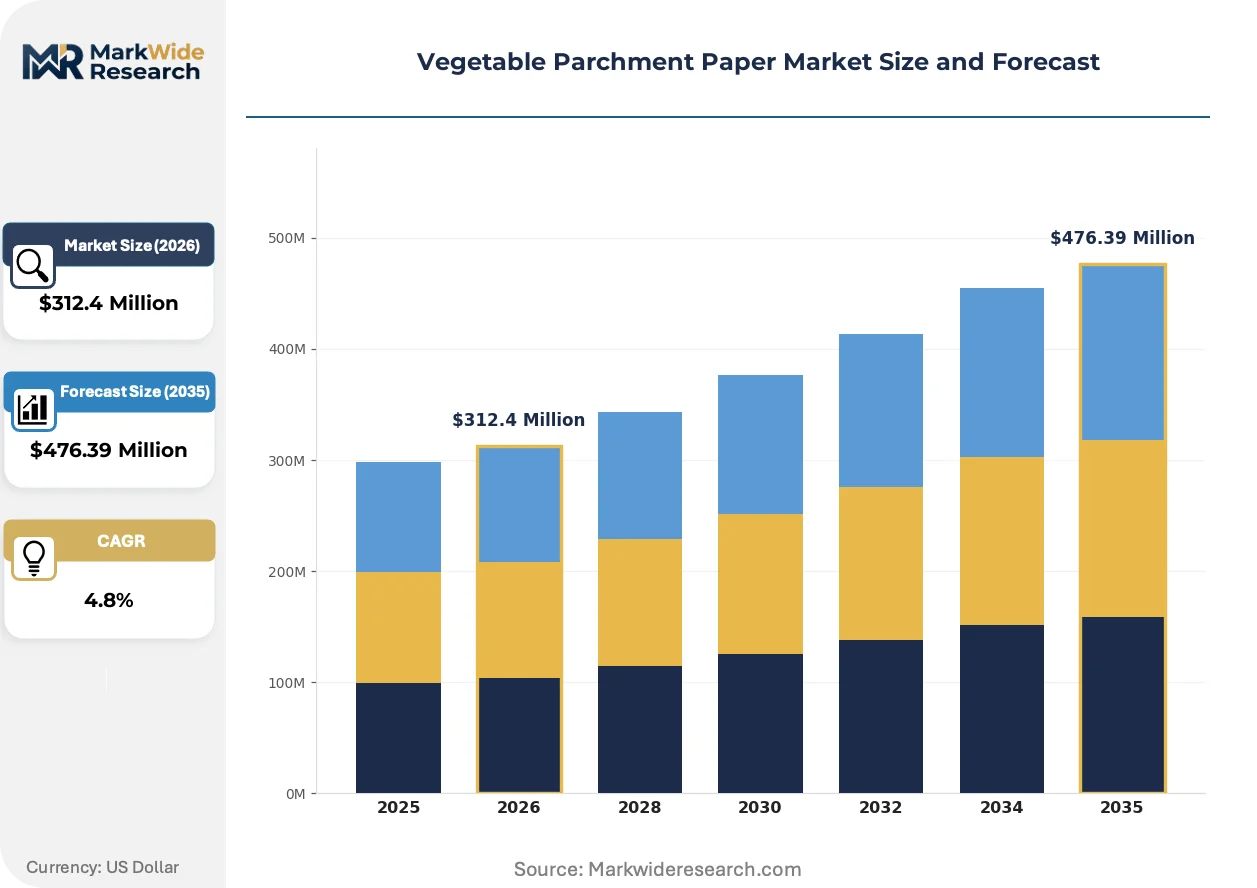
Market Dynamics
The EU's Single-Use Plastics Directive is compressing demand for petroleum-based food packaging alternatives, forcing converters to accelerate silicone-coated parchment qualification timelines and redirect capex toward fiber-based barrier coating lines.
Growth Catalysts
- California SB 54 Extended Producer Responsibility:State-level mandates in the US are compelling food service distributors to eliminate plastic wrap SKUs, creating immediate pull-through for compostable parchment alternatives in West Coast supply chains.
- Home Baking Participation:Sustained elevation in residential confectionery preparation is expanding retail shelf space for silicone-treated rolls, with specialty grocers allocating incremental facings to unbleached grades.
- Germany's Verpackungsgesetz Recycling Quotas:The packaging law is pressuring industrial bakeries to demonstrate fiber recovery rates, accelerating substitution of aluminum foil with certified recyclable parchment in automated production lines.
Market Restraints
- Sulfuric Acid Input Volatility:Gelatinization chemistry depends on consistent acid supply pricing, with energy-intensive sulfur processing creating margin compression for non-integrated converters lacking captive chemical production.
- Scandinavian Pulp Concentration:Nordic integrated mills control bleached softwood fiber supply, exposing mid-tier tolling operations to freight disadvantage and volume allocation risk during peak baking seasons.
- Silicone Coating Technical Ceiling:Current plasma deposition methods limit maximum operating temperatures to 220°C, constraining penetration into high-temperature roasting applications above this threshold.
Strategic Opportunities
- India Food Processing Expansion:Central government PLI scheme incentives for processed food exports are creating first-mover advantage for parchment suppliers establishing local tolling partnerships in Gujarat and Maharashtra industrial corridors.
- Home-Composting Certification Gap:Fragmentation between BPI industrial composting and TÜV Austria home-composting standards presents white space for mills achieving dual-label status and commanding premium placement in specialty retail.
- Direct-to-Consumer Subscription Channels:Artisan bakery ingredient kits shipped through monthly subscription services are bypassing traditional distributor markups, enabling margin capture for parchment brands with e-commerce fulfillment infrastructure.
Industry Challenges
- Migration Testing Compliance Timeline:EU Framework Regulation EC 1935/2004 extractives protocols require 12-18 month qualification cycles, delaying market entry for reformulated barrier coatings and straining working capital for mid-tier producers.
- Acid Bath Process Engineering Talent:Gelatinization line optimization requires specialized chemical engineering expertise concentrated in legacy European paper science programs, constraining capacity expansion in emerging production geographies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegetable Parchment Paper Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unbleached, Bleached, Coated, Specialty End Use Industry: Food Service, Bakery, Confectionery, Catering Packaging Type: Rolls, Sheets, Pre-Cut, Custom Sizes Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Nordic Paper, JK Paper, Reynolds Consumer Products, Pudumjee Paper Products, Black Label Paper Company, Paterson Pacific Parchment Company, AMOL Group, McNairn Packaging, Ahlstrom-Munksjö, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegetable Parchment Paper Market Strategic Shifts
Silicone deposition technology is digitizing quality control protocols, while regulatory fragmentation around compostability certification is reshaping supplier qualification requirements and procurement screening criteria.
Plasma-enhanced chemical vapor deposition systems for silicone coating are digitizing real-time thickness monitoring and defect detection. Artisan and industrial bakeries alike are adopting these precision-coated grades to reduce waste from stick-related product loss. The technology is digitizing specification-setting, enabling buyers to demand lot-level performance data rather than accepting batch certificates.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluorochemical barrier alternatives from food contact applications. Industrial converters serving EU export markets must now validate parchment-only solutions for grease resistance previously achieved through fluoropolymer laminates. High-temperature baking segments in France and Germany are responding with accelerated R&D into cellulose nanofibril reinforcement.
Certification-driven preference shifts are fragmenting procurement decision criteria. Food service operators are unbundling supplier relationships, maintaining separate qualified vendor lists for BPI-certified versus home-composting-certified grades. This bifurcation is most visible in Pacific Northwest metropolitan markets, where municipal composting infrastructure varies block-by-block and operators must stock multiple certification tiers.
Vegetable Parchment Paper Market Segmentation
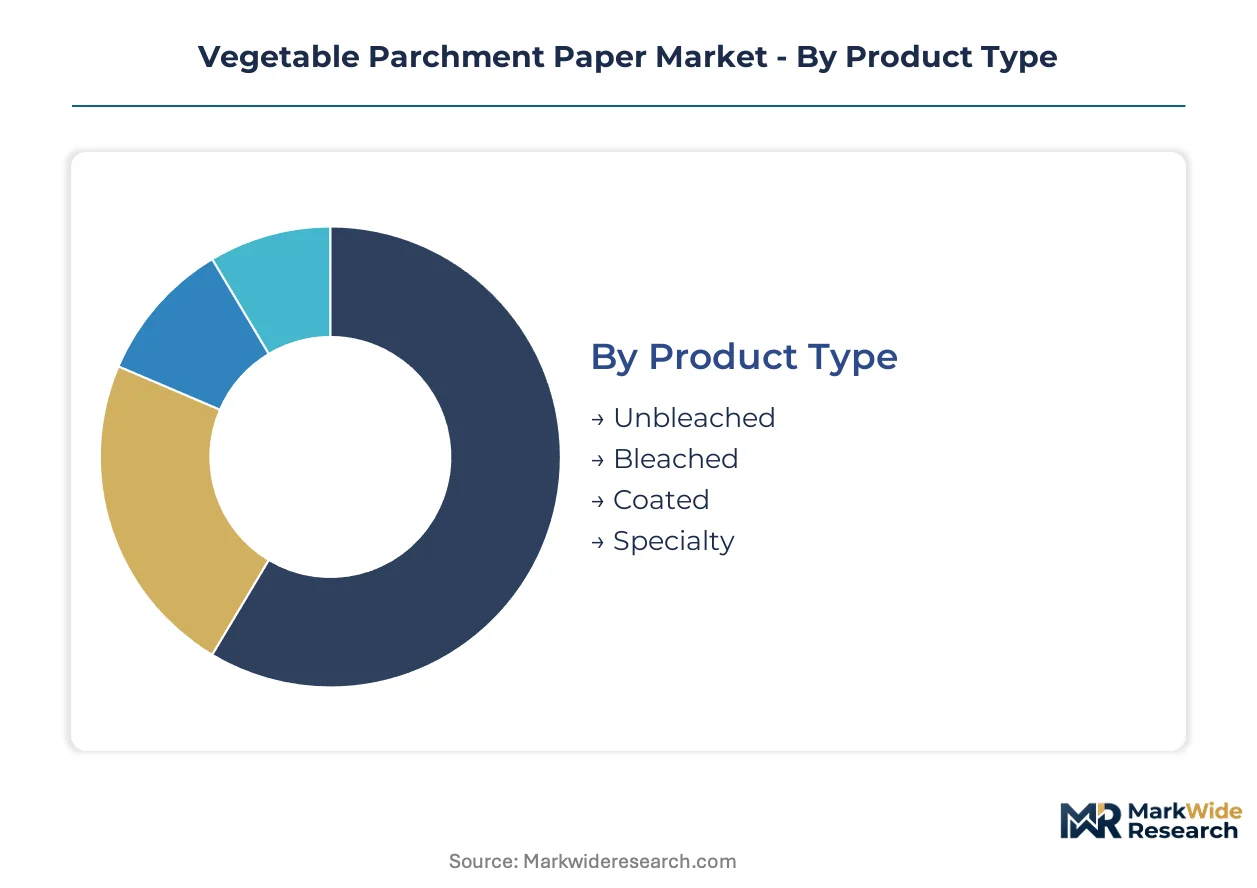
Segmentation in vegetable parchment paper reflects divergent performance requirements across baking temperatures, grease resistance thresholds, and compostability certifications. Each dimension shapes procurement patterns and margin capture differently.
Product Type:
Mature bleached grades dominate institutional procurement while emerging specialty variants reshape premium positioning.
- Bleached:Sulfuric acid gelatinization produces bright white surfaces preferred by industrial bakeries for visual product presentation. European and North American food service operators specify this grade for high-volume automated production lines where consistent release properties reduce waste.
- Coated:Silicone deposition via plasma-enhanced chemical vapor deposition creates non-stick surfaces capable of withstanding repeated use cycles. Home baking participation in Germany and France is accelerating retail demand for reusable silicone-treated rolls.
- Unbleached:Natural fiber coloration aligns with organic certification requirements.
- Specialty:Compostability-certified grades integrating cellulose nanofibril reinforcement.
Bleached handles the majority of throughput; coated is the fastest mover on share.
End Use Industry:
Volume concentration varies sharply between artisan-scale operations and industrial throughput facilities.
- Food Service:Restaurants and institutional kitchens demand pre-cut sheets optimized for speed of service. California's SB 54 mandates are displacing plastic wrap in West Coast hotel and restaurant supply chains.
- Bakery:Artisan and industrial producers require moisture-resistant barriers for proofing and baking. German industrial bakeries under Verpackungsgesetz quotas are substituting aluminum foil with certified recyclable parchment.
- Confectionery:Chocolate and candy manufacturers need grease-resistant release surfaces.
- Catering:Event service operators prioritize portability and presentation.
Bakery commands the largest volume base; food service is expanding most quickly on regulatory pull-through.
Packaging Type:
Format selection tracks operational scale and equipment automation levels.
- Rolls:Continuous format suits high-throughput operations with in-house cutting equipment. Nordic Paper's integrated Scandinavian mills supply bleached rolls to automated bakery lines.
- Sheets:Flat-packed formats eliminate cutting labor for mid-size operations.
- Pre-Cut:Dimension-standardized pieces align with commercial oven specifications.
- Custom Sizes:Width and length specifications match proprietary equipment.
Rolls handle the majority of throughput; pre-cut is climbing the fastest on labor cost reduction.
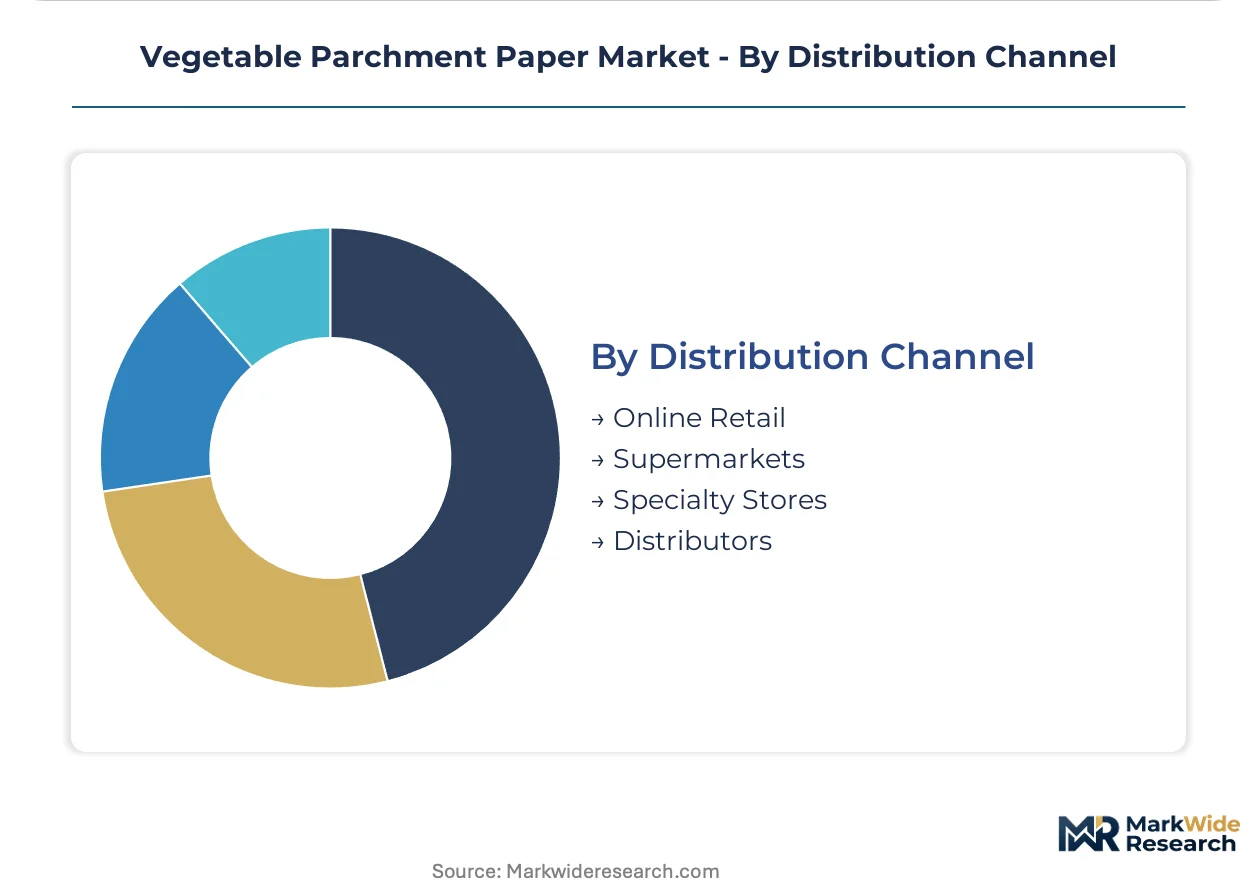
Distribution Channel:
Channel fragmentation reflects divergent buyer sophistication and order scale.
- Distributors:Broadline and specialty food service distributors consolidate procurement for multi-location operators. Reynolds Consumer Products leverages dominant shelf placement through these channels in North America.
- Online Retail:Direct-to-consumer subscription services bypass traditional markups. Artisan bakery ingredient kits shipped monthly create margin capture opportunities for parchment brands with e-commerce infrastructure.
- Supermarkets:Mass retail placement reaches residential bakers.
- Specialty Stores:Culinary supply retailers serve enthusiast segments.
Distributors handle the majority of throughput; online retail is gaining share fastest on subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scandinavian integrated mills extract pricing premiums from captive pulp supply, while South Asian tolling operations compete on conversion economics alone. This asymmetry shapes procurement patterns across food service and industrial bakery supply chains.
United States
West Coast food service distributors are eliminating plastic wrap SKUs under California's SB 54 mandates. The FDA's 21 CFR 176.170 extractives limits govern acid bath chemistry for domestic producers. Pacific Northwest metropolitan markets show block-by-block variation in municipal composting infrastructure, forcing operators to stock multiple certification tiers.
Germany
Industrial bakeries under Verpackungsgesetz recycling quotas are substituting aluminum foil with certified recyclable parchment. The EU's Framework Regulation EC 1935/2004 imposes migration testing requirements that shape export qualification costs. Artisan bakery supply chains in Bavaria and Baden-Württemberg concentrate demand for unbleached grades.
France
High-temperature baking segments are accelerating R&D into cellulose nanofibril reinforcement. REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluorochemical barrier alternatives from food contact applications. Industrial converters in Île-de-France and Auvergne-Rhône-Alpes are validating parchment-only solutions for grease resistance.
India
Central government PLI scheme incentives for processed food exports are creating first-mover advantage for parchment suppliers. FSSAI food contact material regulations govern import qualification timelines. Gujarat and Maharashtra industrial corridors are emerging as tolling partnership locations for export-oriented production.
Sweden
Nordic integrated mills control bleached softwood fiber supply for European food service operators. The EU Green Deal circular economy targets are accelerating investment in fiber-based barrier coatings. Stockholm and Gothenburg industrial zones concentrate acid bath process engineering expertise.
Vegetable Parchment Paper Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the parchment value chain. The market structures around three to four dominant integrated producers with captive pulp supply, surrounded by a fragmented tier of tolling operations and regional converters. Strategic archetypes include Scandinavian pulp-to-paper integrators, European specialty coaters, and North American retail channel dominators. Competitive moves concentrate on backward integration into pulp supply and geographic expansion through tolling partnerships.
Among Scandinavian integrated producers, Nordic Paper anchors the bleached grade segment through mill network concentration. Ahlstrom-Munksjö occupies a position within the specialty coating tier, exemplifying performance differentiation for high-temperature applications. Reynolds Consumer Products represents the retail channel archetype, leveraging shelf placement scale in North American mass market distribution.
| Leading Market Players |
|---|
| Nordic Paper |
| JK Paper |
| Reynolds Consumer Products |
| Pudumjee Paper Products |
| Black Label Paper Company |
| Paterson Pacific Parchment Company |
| AMOL Group |
| McNairn Packaging |
| Ahlstrom-Munksjö |
| Others |
Value Chain & Pricing Dynamics
Overcapacity signals from Scandinavian bleached-grade mills are compressing spot pricing for standard rolls while tightening availability of acid-bath process engineering talent, forcing buyers into longer contract terms and suppliers into selective capacity discipline.
Pricing Analysis
Configured-to-order pricing for custom-width industrial rolls commands spreads exceeding standard retail SKUs by certification tier and volume commitment. Three-tier pricing structure across premium silicone-coated, standard bleached, and economy unbleached levels tracks raw fiber grade and migration testing compliance. Pricing pressure stems from sulfuric acid input volatility and energy-intensive gelatinization chemistry, with mid-tier tolling operations absorbing margin compression. Food service distributors demonstrate highest price sensitivity due to SB 54 mandate-driven SKU consolidation, while artisan bakery supply chains in Germany and France accept premiums for dual-certification grades.
Supply Chain Analysis
Export-control regimes on sulfuric acid concentration technologies limit process equipment flows to emerging production geographies, constraining capacity expansion outside legacy European paper science clusters. Supply concentrates in Sweden, Finland, and Germany for bleached softwood fiber, with India and China emerging as tolling locations for export-oriented conversion. Raw material dependencies center on Scandinavian pulp supply, silicone coating chemicals, and acid bath chemistry inputs. Single-source vulnerability sits with Nordic integrated mills controlling bleached fiber allocation during peak baking seasons. Distribution runs through broadline food service distributors consolidating procurement for multi-location operators, with direct-to-consumer subscription channels gaining incremental share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as certification interoperability between BPI industrial composting and TÜV Austria home-composting standards creates ecosystem lock-in effects for dual-label suppliers.
For Market Incumbents: Insulate acid-bath process engineering expertise through targeted hiring from legacy European paper science programs and captive training pipelines, while locking in Scandinavian pulp supply via long-term offtake agreements with Nordic integrated mills. Defend against specialty-grade erosion by accelerating cellulose nanofibril reinforcement R&D for high-temperature applications above silicone coating thresholds. For New Entrants and Emerging Players: Build out tolling partnerships in Gujarat and Maharashtra industrial corridors to capture PLI scheme incentives for processed food export growth, targeting first-mover positioning before qualification timelines extend. Prioritize home-composting certification as the most penetrable white space, leveraging dual-label status to command premium placement in Pacific Northwest metropolitan markets with fragmented municipal infrastructure. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across tolling-dependent mid-tier operations as asset-light contract manufacturing reconfigures entry barriers, favoring acquisition targets with established certification portfolios over greenfield capacity. Monitor acid bath process engineering talent availability as the critical inflection signal for sustainable competitive positioning. Cross-checking against EU Framework Regulation EC 1935/2004 migration testing backlog durations is advised before commitment-grade decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Nordic Paper's captive Scandinavian fiber operations sustain cost discipline against tolling competitors. |
| Dual-Compostability Certification Investment | BPI plus TÜV Austria labeling commands premium placement in Pacific Northwest specialty retail channels. |
| Plasma-Enhanced Silicone Deposition Scale-Up | Ahlstrom-Munksjö's coating capabilities differentiate performance for high-temperature baking applications. |
| Direct-to-Consumer Subscription Launch | Artisan bakery ingredient kits bypass distributor markups and capture margin through e-commerce fulfillment. |
| India Tolling Partnership Establishment | Gujarat and Maharashtra locations leverage PLI scheme incentives for processed food export growth. |
Study Parameters
Operator-level perspectives from plant managers at integrated mills, procurement leads at industrial bakeries, distribution channel partners, and regulatory affairs specialists anchored the qualitative base. Primary interviews combined with secondary validation from customs and trade data, SEC filings, EU Framework Regulation migration testing protocols, and FSSAI food contact material guidelines. Bottom-up volume modeling across product type, end-use industry, packaging format, and distribution channel triangulated against top-down macroeconomic drivers.
Scenario-bracketing framed analytical outputs across the analysis window, with segmentation dimensions spanning bleached versus unbleached versus coated versus specialty grades, food service versus bakery versus confectionery versus catering end uses, and distributor versus online retail versus supermarket channels. CAGRs derived from historical trajectory analysis and regulatory mandate timing, incorporating sulfuric acid input cost curves and silicone coating technology adoption rates as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by mid-tier tolling operations or accelerated EU Green Deal circular economy target revisions would shift outcomes. Cross-checking against BPI and TÜV Austria certification database growth rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
North America Corrugated Packaging Market
Paper & Paperboard Packaging
Box Liners Market
Paper & Paperboard Packaging
Tracing Paper Market
Paper & Paperboard Packaging
India Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Global VCI Paper Market
Paper & Paperboard Packaging
Europe Paper Cone Market
Paper & Paperboard Packaging
Kraftliner Market
Paper & Paperboard Packaging
India Paper Packaging Market
Paper & Paperboard Packaging
Italy Paper Packaging Market
Paper & Paperboard Packaging
France Paper Packaging Market
Paper & Paperboard Packaging
Tissue and Hygiene Paper Packaging Market
Paper & Paperboard Packaging
Malaysia Corrugated Boxes Market
Paper & Paperboard Packaging
Commercial Paper Bags Market
Paper & Paperboard Packaging
Silicone Release Paper Market
Paper & Paperboard Packaging
Paper Bottles Market
Paper & Paperboard Packaging
Folding Paperboard Boxes Market