
 South Korea Paper Packaging Market | 2026-2036
South Korea Paper Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Paper Packaging Market Analytics
Modular box configurations with variable interior dividers is broadening buyer choice across electronics and cosmetics fulfillment channels. Hansol PaperTech leverages its integrated pulp-to-box manufacturing to sustain cost advantages in kraft-based shipping containers. Smurfit WestRock competes through scale in corrugated board while Rengo Korea anchors regional supply networks for just-in-time delivery to Busan port operations.
South Korea paper packaging encompasses fiber-based containers, wraps, and cartons manufactured from bleached, unbleached, or recycled pulp stocks with basis weights typically ranging from 80 to 350 grams per square meter, engineered to protect goods during distribution while meeting printability and barrier requirements. The product mix spans boxes, bags, wrapping paper, and cartons, with corrugated boxes occupying the dominant margin pool due to e-commerce volume while bags and wrapping paper capture premium positioning in personal care and gift segments. Kraft paper and recycled paper lead the material split, reflecting both cost efficiency and compliance pressure from Korea's packaging waste reduction mandates.
MFDS food-contact material standards, Ministry of Environment extended producer responsibility frameworks, and KSA recycling content guidelines collectively shape permissible substrates and post-consumer recovery obligations for domestic converters. Korea's carbon-neutral roadmap for 2050 is tightening energy and emissions benchmarks for paper mills, pushing producers toward biomass boilers and process efficiency investments. Stakeholders must track how Seoul's municipal waste sorting enforcement and Incheon's green port initiatives redirect logistics packaging specifications before committing to capacity expansions.
Market Dynamics
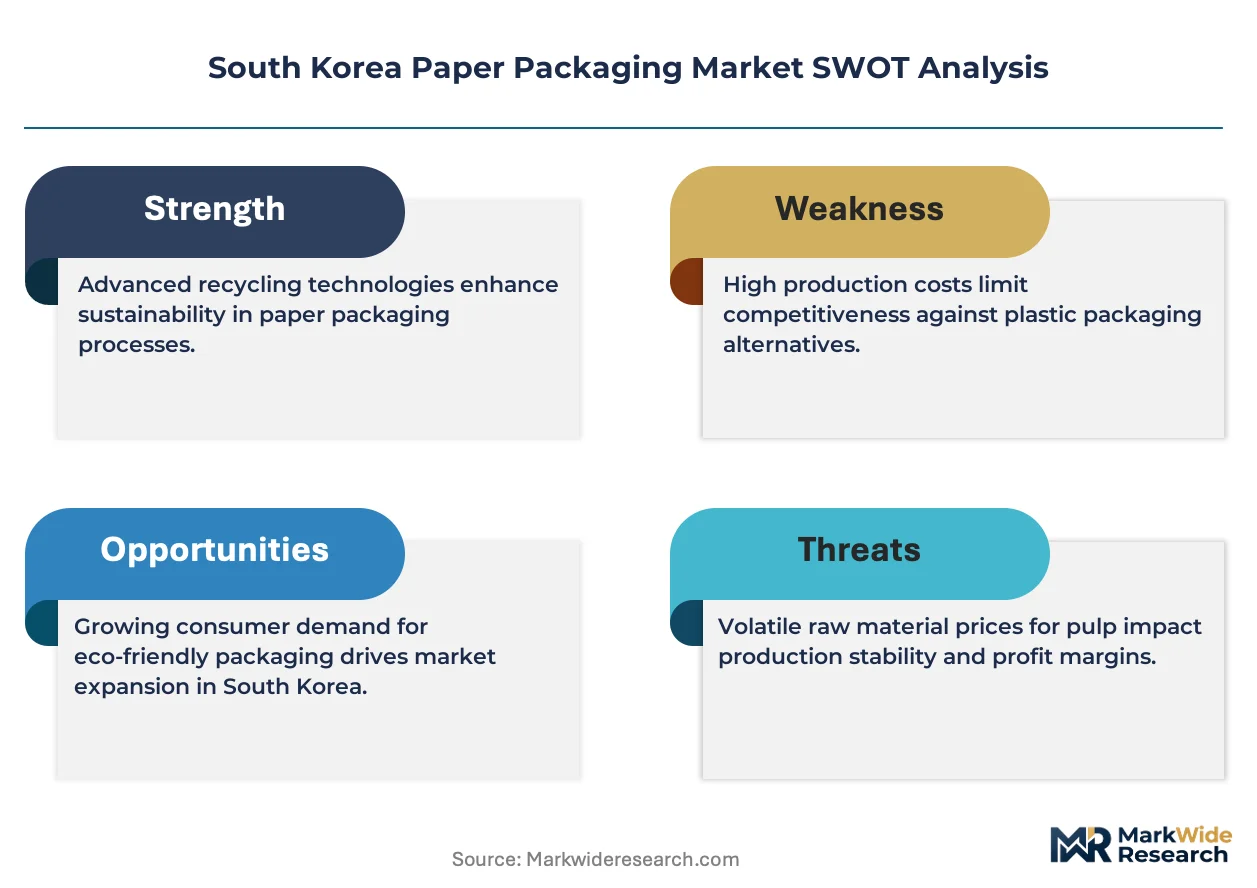
Extended producer responsibility mandates from the Ministry of Environment are forcing converters to redesign material flows and recover packaging waste at higher rates, compressing margins while opening circular-economy service revenue streams.
Growth Catalysts
- E-commerce fulfillment surge:Electronics and cosmetics brands in the Seoul metropolitan area are tripling corrugated box consumption for direct-to-consumer shipping.
- MFDS food-contact standards:Stricter migration limits for mineral oils and heavy metals are accelerating migration to virgin kraft substrates for ready-meal packaging.
- Recycled pulp technology:Advanced de-inking and fiber recovery systems are lowering the cost gap between recycled and virgin board, improving converter competitiveness.
Market Restraints
- Imported OCC price volatility:South Korea relies on overseas old corrugated container feedstock, exposing mills to shipping cost swings and yen-dollar exchange rate pressure.
- Energy cost escalation:Natural gas and electricity tariffs under Korea's carbon-neutral roadmap are raising drying and pressing expenses at integrated mills.
- Plastic film substitution:Barrier-coated paper still loses to multilayer plastic in wet-food and frozen-meat applications where shelf-life extension dominates purchasing criteria.
Strategic Opportunities
- Busan port logistics hub:Expanding transshipment volumes create demand for weather-resistant export packaging with RFID-enabled tracking layers.
- Cosmetics gift-set premiumization:Rigid set-up boxes with embossed finishes and magnetic closures command price premiums in duty-free and domestic premium channels.
- Green packaging subsidies:Ministry of Trade, Industry and Energy tax credits for bio-based coatings and water-based inks reduce retrofit capex burdens for mid-tier converters.
Industry Challenges
- De-inking chemist scarcity:Specialized knowledge of flotation chemistry and enzymatic bleaching is concentrated among retiring engineers at legacy mills.
- Legacy ERP integration:Batch-oriented manufacturing execution systems at family-owned converters resist real-time connectivity with brand-customer supply chain platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Paper Packaging Market |
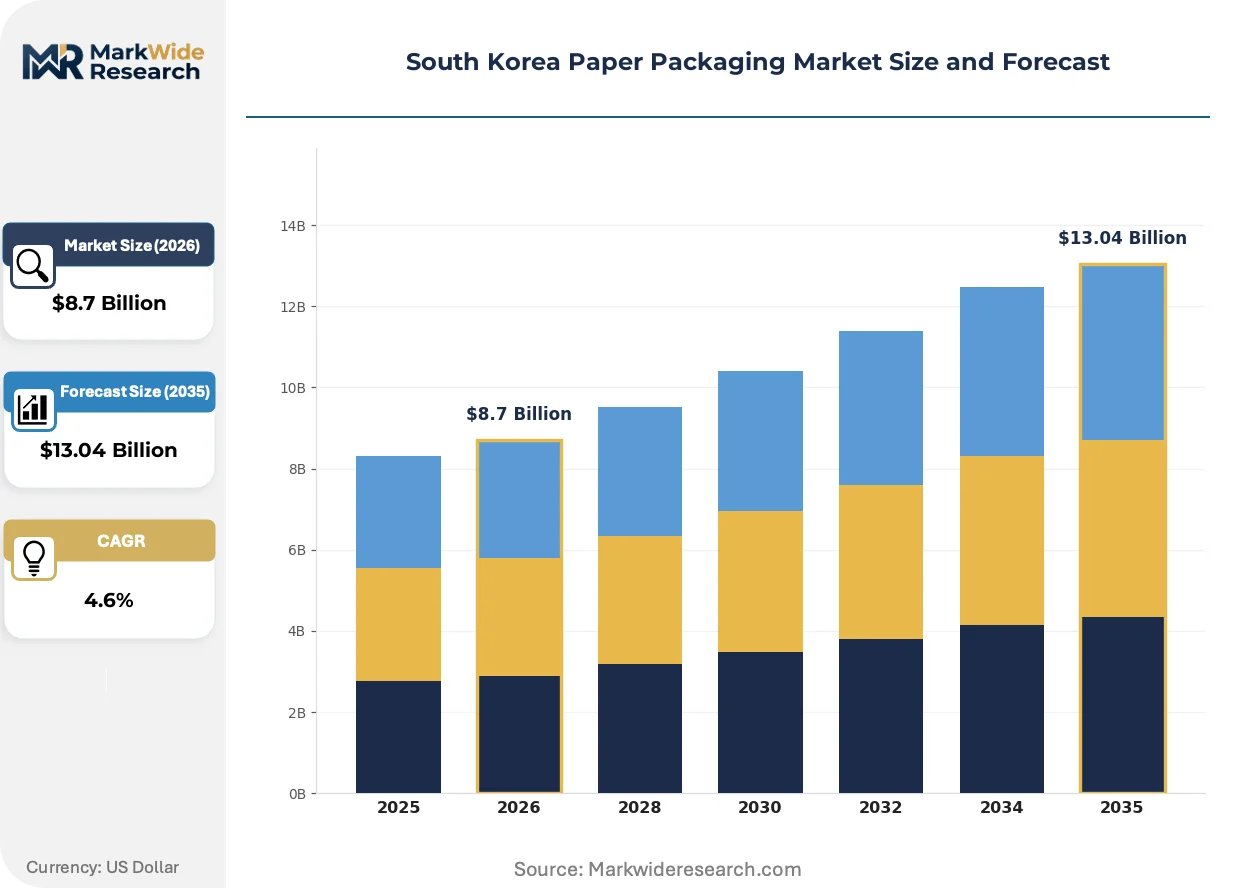
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Bags, Wrapping Paper, Cartons End Use Industry: Food & Beverage, Consumer Goods, Healthcare, Personal Care Material: Kraft Paper, Recycled Paper, Bleached Paper, Coated Paper Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | International Paper Company, Tetra Laval Group, Hansol PaperTech, Amcor plc, Smurfit WestRock, Rengo Korea, Graphic Packaging International Corporation, Hansol Paper Co., Ltd., Oji Interpack Korea, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Paper Packaging Market Evolving Landscape
Material science advances and regulatory tightening are converging to reshape substrate selection, with converters racing to certify bio-based barriers before extended producer responsibility penalties phase in.
Nano-fibrillated cellulose barrier coatings are absorbing moisture and oxygen protection functions previously served by polyethylene laminates. Premium chocolate and dried-seafood exporters in Gangwon-do are piloting these coatings to eliminate plastic layers while maintaining shelf stability. The technology is absorbing compliance risk as brands preempt Korea's 2027 packaging waste reduction targets.
Ministry of Environment extended producer responsibility rules are tightening sorting and recovery obligations for e-commerce platforms and brand owners. Retailers must now fund collection infrastructure for paper packaging waste or face per-ton penalties. Electronics fulfillment centers in Gyeonggi-do are responding by specifying mono-material corrugated designs that eliminate tape and labels incompatible with pulping.
Direct mill-to-brand contracting is displacing traditional trader-mediated pulp procurement for large corrugated producers. Major appliance manufacturers in Suwon and Gwangju are negotiating annual volume commitments with Hansol PaperTech and Moorim P&P to lock in basis weight consistency and carbon footprint verification. This pattern concentrates purchasing power among top-ten buyers while squeezing margin for distributors.
South Korea Paper Packaging Market Segmentation
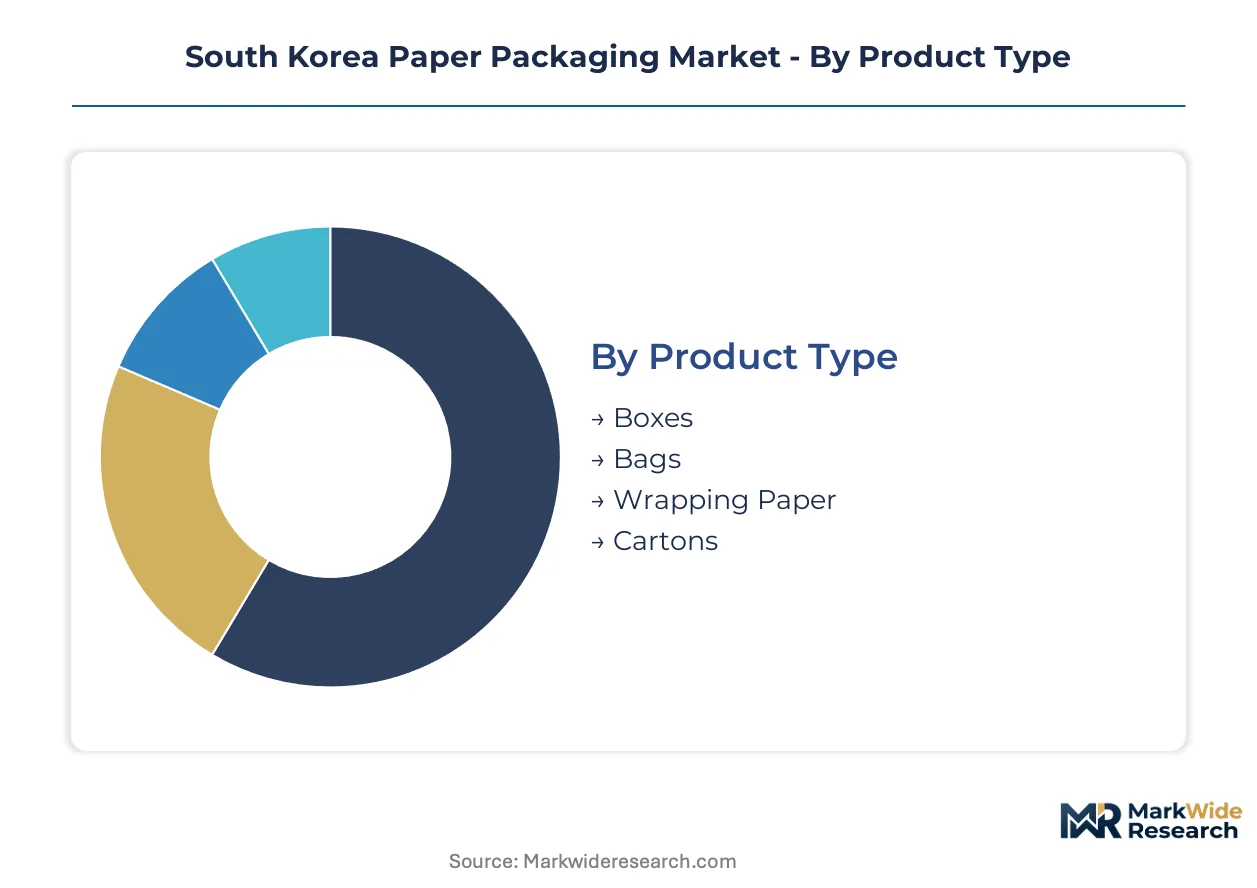
Paper packaging segmentation in South Korea reflects the tension between regulatory compliance and channel-specific performance requirements. Each dimension carries distinct implications for converter capability investments and margin structures across the Seoul metropolitan supply base.
Product Type:
Structural configurations differentiate by load-bearing capacity, print surface quality, and fulfillment automation compatibility.
- Boxes:Corrugated fiberboard constructions with flute profiles ranging from A-flute to F-flute serve e-commerce fulfillment and appliance shipping. Electronics brands in Gyeonggi-do specify ECT ratings above 32 lb/in for stackability in automated warehouses. The segment captures volume concentration from direct-to-consumer channel expansion.
- Cartons:Folding carton substrates from 200-350 gsm solid bleached sulfate deliver premium surface for cosmetics and pharmaceutical blister packs. MFDS migration limits for mineral oils push converters toward virgin kraft backings for ready-meal applications. Demand clusters around Incheon-area pharmaceutical clusters and Seoul duty-free channels.
- Bags:Multiwall sacks and retail carry bags utilize 80-120 gsm kraft for grocery and fashion retail distribution.
- Wrapping Paper:Tissue and kraft wrapping grades serve gift packaging and protective interleaving for ceramics and glassware exports.
Mature deployment sits with Boxes. Newer deployment is concentrated in Cartons as cosmetics brands upgrade packaging specifications for premium positioning.
End Use Industry:
Regulatory exposure and channel velocity create divergent specification requirements across buyer verticals.
- Food & Beverage:Barrier-coated board for ready meals and retort pouches faces MFDS food-contact compliance audits. Migration testing for heavy metals and mineral oil saturated hydrocarbons limits recycled content ratios in direct-contact applications. Major retailers in Seoul enforce lot-level traceability for packaging substrates.
- Consumer Goods:Electronics fulfillment demands crush-resistant corrugated with anti-static coatings for semiconductor components. Samsung and LG supply chain specifications mandate FSC-certified fiber and carbon footprint disclosure at the SKU level.
- Personal Care:Rigid set-up boxes with embossed finishes and magnetic closures serve duty-free gift sets targeting Chinese tourist channels.
- Healthcare:Sterile barrier systems and cold-chain shipping containers require particulate-controlled manufacturing environments.
Procurement concentration is tightest in Food & Beverage. Specification complexity is climbing fastest in Consumer Goods as sustainability verification layers multiply.
Material:
Fiber sourcing strategy determines compliance posture and cost volatility exposure for integrated mills.
- Kraft Paper:Unbleached virgin pulp delivers tear strength and printability for shipping containers and heavy-duty sacks. Domestic pulp integration at Hansol PaperTech and Moorim P&P insulates against OCC import price swings. The material anchors e-commerce box specifications where recycled fiber strength variability creates fulfillment risk.
- Recycled Paper:De-inked post-consumer fiber meets Ministry of Environment extended producer responsibility mandates for packaging waste recovery. Advanced flotation systems at legacy mills in Busan and Ulsan produce DS-compliant board for non-food applications. Cost parity with virgin grades is improving as de-inking chemistry advances.
- Bleached Paper:Chlorine-free bleached kraft serves pharmaceutical inserts and premium cosmetic folding cartons.
- Coated Paper:Clay or polymer coatings enable high-fidelity printing for retail-ready packaging.
Volume leadership belongs to Kraft Paper. Recycled Paper is gaining share fastest as EPR enforcement tightens and de-inking technology matures.
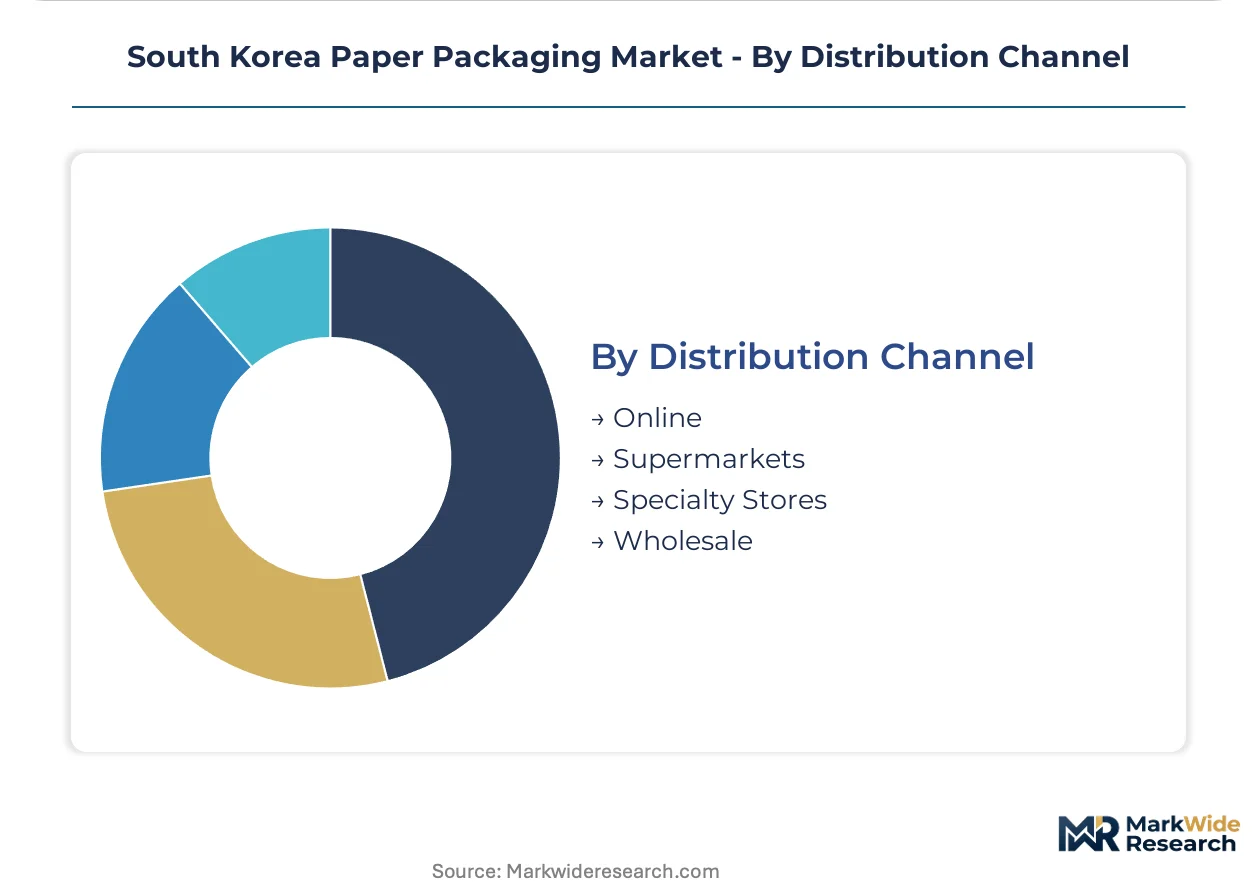
Distribution Channel:
Channel selection dictates order fragmentation, lead time compression, and customization depth.
- Online:Direct-to-brand e-procurement platforms enable specification upload and proofing workflows for mid-sized cosmetics brands. Gyeonggi-do fulfillment centers require 48-hour turnaround on corrugated box orders with variable print runs. The channel demands modular die-cut designs compatible with automated packing lines.
- Wholesale:Trader-mediated bulk supply of standardized sheet and roll stock serves small converters without pulp integration. Busan port logistics clusters concentrate inventory holding for export-oriented packaging buyers.
- Supermarkets:Private-label packaging procurement for retail-ready produce and bakery items.
- Specialty Stores:Boutique converters serving artisanal food and craft gift segments with short-run customization.
Order aggregation is strongest in Wholesale. Specification sophistication is expanding most quickly in Online as brand-direct procurement bypasses traditional distributor tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gwangju Free Economic Zone tax incentives and Incheon Free Economic Zone infrastructure subsidies are concentrating packaging converter investments in designated industrial corridors. Seoul Capital Area logistics density and Busan port throughput differentials are widening regional specialization patterns across the Korean peninsula.
Seoul Capital Area
E-commerce fulfillment centers in Gyeonggi-do tripled corrugated box consumption for direct-to-consumer electronics and cosmetics shipping. Ministry of Environment extended producer responsibility rules mandate packaging waste collection infrastructure funding by major retailers. Songdo International Business District hosts automated packaging specification platforms serving mid-sized cosmetics brands with 48-hour turnaround requirements.
Busan-Ulsan
Transshipment volume growth through Busan Port drives demand for weather-resistant export packaging with RFID-enabled tracking layers. Korea Customs Service green port initiatives redirect logistics packaging specifications toward mono-material designs compatible with automated sorting. Ulsan industrial belt converters specialize in heavy-duty kraft shipping containers for petrochemical and automotive component exports.
Daegu-Gyeongbuk
Textile and machinery manufacturers in Daegu metropolitan area source protective wrapping and interleaving papers for ceramic and glassware export shipments. Regional employment incentives under the Korea Free Economic Zone Authority attract de-inking technology investments. Gumi electronics industrial complex demands anti-static coated corrugated for semiconductor component distribution.
Daejeon-Sejong
Government agency procurement concentration in Sejong City creates institutional demand for certified sustainable packaging with carbon footprint disclosure. Korea Forest Service bio-economy programs subsidize pulp-to-packaging integration projects in adjacent Chungcheong provinces. Daejeon technology cluster startups pilot nano-fibrillated cellulose barrier coatings for food-contact applications.
Gwangju-Honam
Agricultural product exporters in Jeolla provinces utilize multiwall sacks and retail carry bags for rice and specialty food distribution. Gwangju Free Economic Zone tax credits reduce retrofit capital expenditure burdens for mid-tier converters adopting water-based ink systems. Yeosu petrochemical complex proximity enables integrated supply chains for barrier-coated board production.
South Korea Paper Packaging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across substrate integration levels and channel coverage breadth. Market structure tilts toward consolidation among integrated pulp-to-box manufacturers while fragmentation persists in short-run specialty converters. Three archetypes dominate: vertically integrated paper mill operators, regional corrugated scale players, and niche premium packaging specialists. Capacity expansion and direct mill-to-brand contracting represent the dominant competitive moves reshaping procurement relationships.
Among integrated pulp-to-box manufacturers, Hansol PaperTech and Hansol Paper Co., Ltd. exemplify captive fiber supply strategies. Smurfit WestRock and International Paper Company represent multinational scale operators leveraging global board supply networks. Rengo Korea anchors regional just-in-time delivery capabilities for port logistics clusters. These named entities occupy positions across the integration spectrum without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| International Paper Company |
| Tetra Laval Group |
| Hansol PaperTech |
| Amcor plc |
| Smurfit WestRock |
| Rengo Korea |
| Graphic Packaging International Corporation |
| Hansol Paper Co., Ltd. |
| Oji Interpack Korea |
| Others |
Value Network & Pricing Analysis
Captive pulp integration at Hansol PaperTech and Moorim P&P anchors both supply security and pricing power across South Korea's paper packaging landscape. These integrated producers leverage in-house kraft pulp production to buffer against imported old corrugated container volatility while commanding premium positioning for food-contact certified substrates.
Pricing Analysis
Lead-time compression commands measurable premiums in the Seoul metropolitan corridor, where Gyeonggi-do fulfillment centers pay up for 48-hour corrugated turnaround. Three-tier pricing structure across premium FSC-certified, standard virgin kraft, and economy recycled grades reflects certification tier and volume scale differentiation. Pricing pressure stems from energy cost escalation under Korea's carbon-neutral roadmap, tightening dryer and pressing margins at integrated mills. Mid-sized cosmetics brands exhibit highest price sensitivity, while major electronics OEMs prioritize specification consistency over unit cost.
Supply Chain Analysis
Regional distribution centers in Busan and Incheon free economic zones orchestrate hub-and-spoke patterns feeding Gyeonggi-do manufacturing clusters. Geographic supply concentration draws from Indonesia, Vietnam, and domestic Jeolla province pulp plantations for virgin fiber feedstock. Raw material dependencies center on imported OCC from Japan and Southeast Asia, natural gas for drying operations, and proprietary barrier coating chemistries. Single-source vulnerability runs through Busan Port transshipment chokepoints. Distribution runs through direct mill-to-brand contracting for top-ten buyers, with wholesale traders serving fragmented converter tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's paper packaging sector is accelerating into a vertical-integration race as extended producer responsibility mandates force converters upstream into captive fiber recovery and downstream into packaging waste collection services.
For Market Incumbents: Deepen backward integration into de-inking technology and OCC preprocessing to secure feedstock against import price volatility. Consolidate regional corrugated capacity around Busan and Incheon port logistics clusters to capture transshipment packaging demand. Defend margin position by locking multi-year carbon footprint verification contracts with Samsung and LG supply chain specifications before MFDS food-contact audits tighten further. For New Entrants and Emerging Players: Direct-to-brand e-procurement platforms offer the most penetrable entry vector, bypassing entrenched wholesale trader networks serving mid-sized cosmetics brands. Target rigid set-up box specialization for duty-free gift channels where embossed finishes and magnetic closures command sustainable premiums. White-space sits with nano-fibrillated cellulose barrier coating pilot programs in Daejeon-Sejong technology clusters, leveraging Korea Forest Service bio-economy subsidies for capital-light market entry. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational scale operators seeking Asia-Pacific regional hub positioning. Long-term viability favors integrated pulp-to-box manufacturers with Ministry of Environment extended producer responsibility compliance infrastructure already deployed. Acquisition target archetype: mid-tier converters in Gwangju Free Economic Zone with water-based ink retrofit capabilities and Yeosu petrochemical complex proximity for barrier-coated board integration. Watch de-inking chemist scarcity as inflection indicator for technology-labor arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into OCC Preprocessing | Insulates margin from yen-dollar shipping cost swings and Japanese export quota volatility. |
| Direct Mill-to-Brand Contracting | Concentrates purchasing power with Samsung and LG while squeezing wholesale distributor tiers. |
| Green Packaging Subsidy Capture | Ministry of Trade, Industry and Energy tax credits reduce water-based ink retrofit capex burdens. |
| RFID-Enabled Export Packaging Development | Korea Customs Service green port initiatives mandate mono-material designs compatible with automated sorting. |
| De-Inking Technology Acquisition | Flotation chemistry expertise concentrates among retiring engineers at legacy Busan and Ulsan mills. |
Research Methodology
Independent corroboration across converter operations directors, brand supply chain managers, and Ministry of Environment regulatory officials underwrites the qualitative findings in this study. Primary interviews with pulp procurement leads at integrated mills, corrugated plant managers in Gyeonggi-do, and cosmetics packaging specification officers provided operational ground-truth. Secondary validation drew from Korea Forest Service bio-economy program disclosures, MFDS food-contact material filings, and Busan Port transshipment statistics. Bottom-up capacity and consumption estimates triangulated against top-down macroeconomic absorption models.
Rate-of-change decomposition across product type, material grade, end-use industry, and regional production cluster dimensions structured the analytical framework. CAGRs were derived from segment-level volume trajectories weighted by value-per-ton differentials across kraft, recycled, and coated paper categories. Forecast inputs incorporated Ministry of Environment extended producer responsibility penalty schedules, e-commerce fulfillment center expansion pipelines, and carbon-neutral roadmap energy tariff escalations throughout the projection horizon.
Inputs from regulatory filings and port logistics databases were available through the study window; gaps in real-time OCC import pricing and de-inking chemistry cost curves introduce uncertainty bands around margin projections. Forecasts reflect documented assumptions regarding MFDS enforcement timing and green subsidy renewal probabilities. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Letterpress Card Market
Paper & Paperboard Packaging
Folding Paperboard Boxes Market
Paper & Paperboard Packaging
Vietnam Paper Packaging Market
Paper & Paperboard Packaging
Converting Paper Market
Paper & Paperboard Packaging
Ultraflute Paper Market
Paper & Paperboard Packaging
Composite Paper Cans Market
Paper & Paperboard Packaging
Europe Paper Cone Market
Paper & Paperboard Packaging
Japan Paper Packaging Market
Paper & Paperboard Packaging
Kraft Paper SOS Bag Market
Paper & Paperboard Packaging
Global Folding Boxboards Market
Paper & Paperboard Packaging
Paperboard Mailer Market
Paper & Paperboard Packaging
Cold Seal Paper Market
Paper & Paperboard Packaging
Tacky Transfer Paper Market
Paper & Paperboard Packaging
Paperboard Tray Market
Paper & Paperboard Packaging
Silicone Release Paper Market
Paper & Paperboard Packaging
Plastic Toilet Paper Dispenser Market