
 Global VCI Paper Market | 2026-2036
Global VCI Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Global VCI Paper Market Outlook
Food-grade and military-specification VCI formulations is bifurcating the competitive landscape into premium and commodity supply tiers. Cortec Corporation leverages its proprietary VCI chemistry portfolio to dominate military and aerospace certification channels. Daubert Cromwell anchors North American automotive supply chains through integrated manufacturing and distributor partnerships. Armor Protective Packaging differentiates via biodegradable VCI substrates that align with EU packaging waste directives.
VCI paper comprises kraft or specialty paper substrates impregnated with volatile corrosion inhibitor chemicals that vaporize to form a molecular protective layer on ferrous and non-ferrous metal surfaces, typically achieving 2-5 year protection cycles depending on packaging integrity and storage conditions. The product type dimension shows bags capturing the largest volume share due to their adaptability across irregular component geometries, while biodegradable material grades are accelerating fastest as exporters face landfill restrictions in Germany, France, and the Netherlands. Application concentration in automotive parts reflects just-in-time supply chain requirements where corrosion-related rejects trigger severe penalty clauses from OEMs.
REACH registration requirements from ECHA govern chemical substance authorization for VCI actives sold across European Union member states, while EPA regulations under TSCA mandate pre-manufacture notification for new corrosion inhibitor chemistries in the United States. China's SAMR enforces GB/T standards for packaging material safety that directly affect VCI paper import compliance. Stakeholders must monitor evolving substance restriction lists and certification migration timelines to avoid supply disqualification in regulated end-use sectors.
Market Dynamics
Automotive OEMs now mandate VCI-certified packaging for all export-bound metal assemblies, creating a certification bottleneck that filters supplier eligibility and compresses margins for uncertified converters.
Growth Catalysts
- REACH substance authorization:ECHA's tightening disclosure requirements for volatile corrosion inhibitors force metalworking suppliers to upgrade packaging specifications, expanding addressable demand for compliant VCI paper grades.
- Biodegradable substrate mandates:Germany's packaging waste directive and France's anti-waste law obligate exporters to source landfill-compliant protective materials, accelerating material substitution cycles.
- Precision component transit:Just-in-time automotive supply chains in Baden-Württemberg and Bavaria impose severe penalty clauses for corrosion-related rejects, institutionalizing VCI paper as non-negotiable protective infrastructure.
Market Restraints
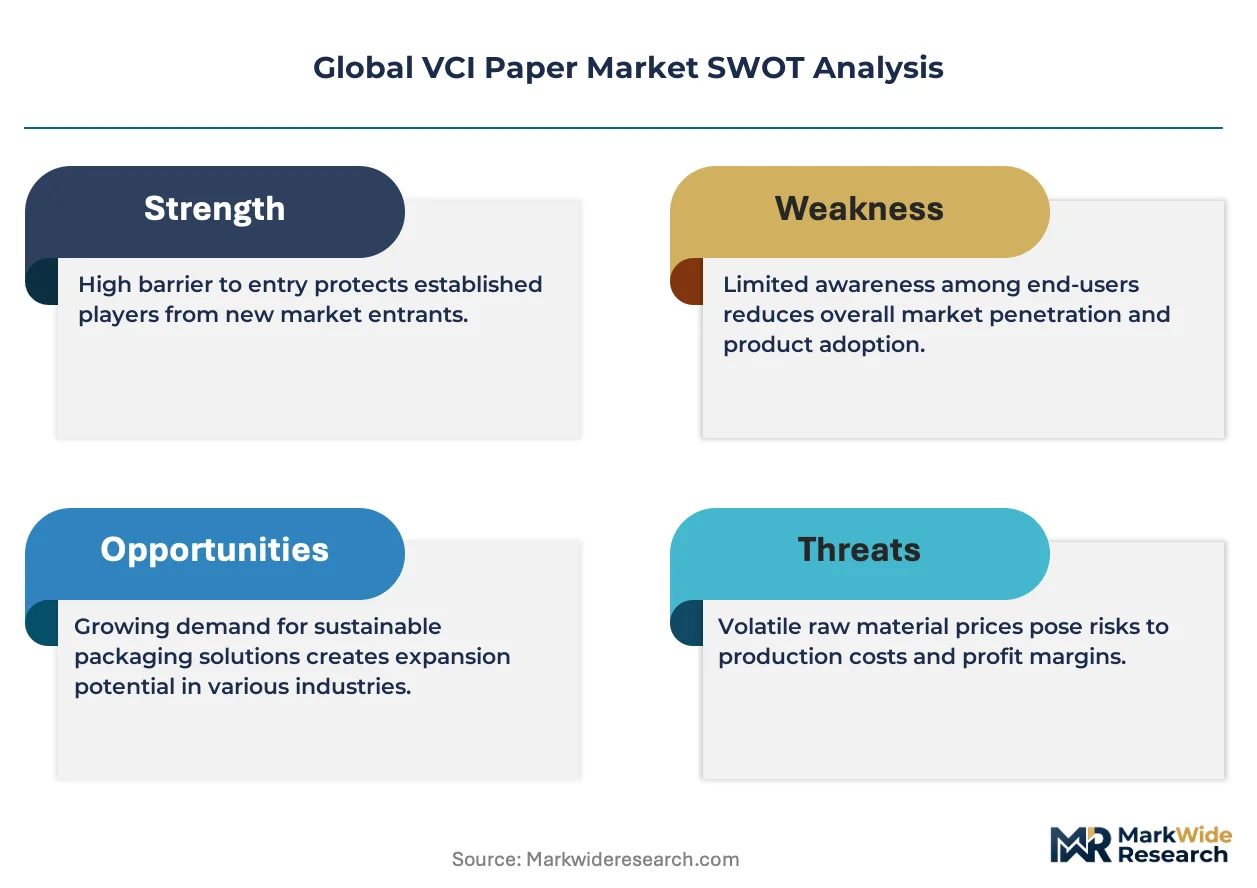
- Kraft pulp input volatility:Unbleached kraft paper substrates face price swings tied to Scandinavian pulp mill capacity and energy costs, compressing converter margins during raw material spikes.
- Active chemistry supply concentration:Specialty amine and nitrite-based corrosion inhibitor precursors concentrate among German and Japanese chemical specialists, creating single-source vulnerability for formulated VCI producers.
- Performance ceiling in extreme climates:Standard VCI formulations degrade in high-humidity tropical storage conditions above 85% relative humidity, limiting addressable applications in Southeast Asian metal warehousing.
Strategic Opportunities
- Indian automotive component export corridor:Tamil Nadu and Gujarat-based Tier 1 suppliers serving European OEMs remain underpenetrated by certified VCI paper distributors, offering first-mover consolidation potential.
- Copper and brass alloy protection:Existing VCI formulations optimized for ferrous metals show performance gaps on non-ferrous substrates, creating white space for copper-specific chemistry development.
- Digital inventory integration:Smart packaging with embedded humidity sensors and blockchain traceability enables predictive corrosion monitoring, opening premium service contracts with aerospace MRO facilities.
Industry Challenges
- Multinational certification synchronization:Simultaneous compliance with MIL-PRF-3420 military specifications, ASTM D1748 industrial standards, and OEM-specific audit protocols stretches quality assurance bandwidth and extends product launch timelines.
- Legacy coating equipment retrofit:Conventional paper impregnation lines require capital-intensive upgrades to handle water-based VCI emulsions replacing solvent-borne systems, straining mid-tier converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global VCI Paper Market |
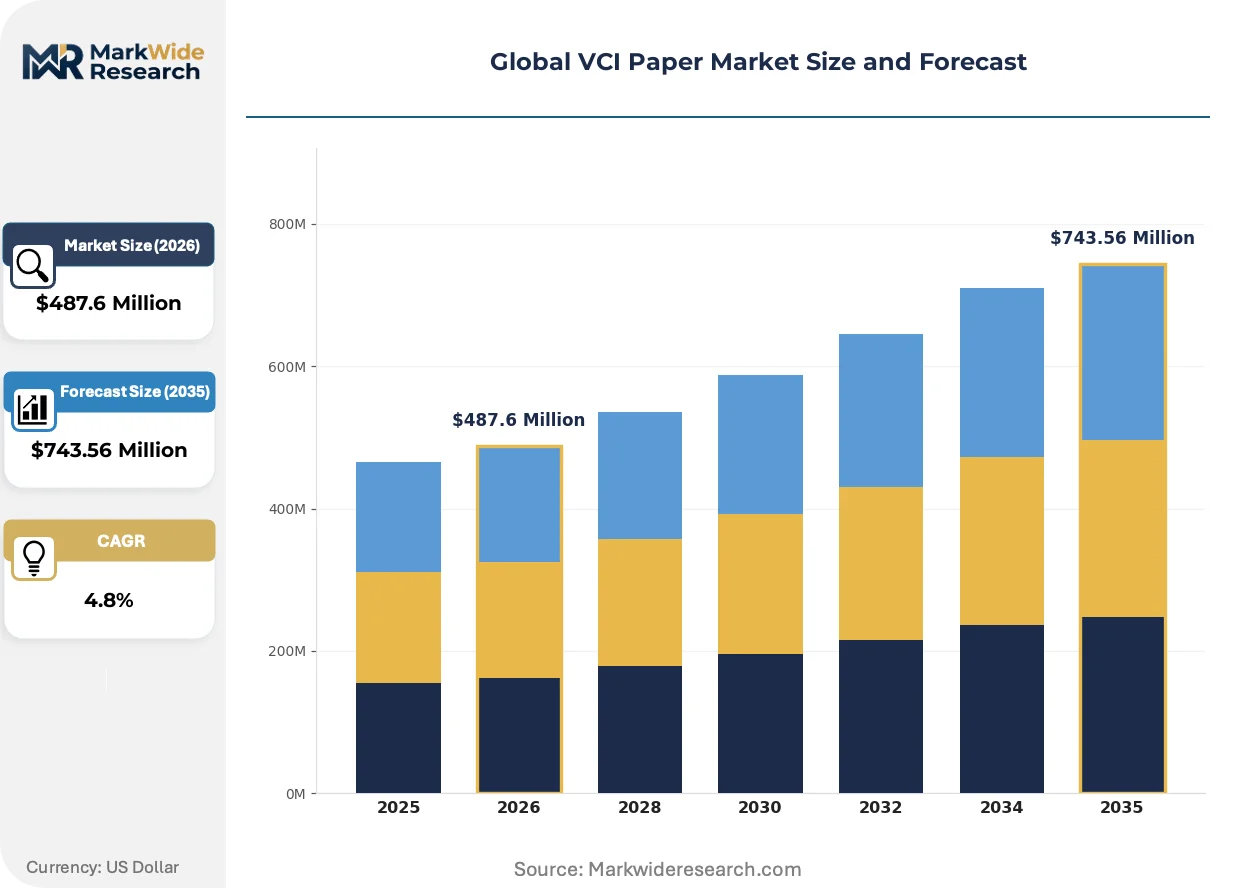
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foil, Sheets, Bags, Tubes Application: Automotive Parts, Electronics, Metal Components, Tools End User: Manufacturers, Distributors, Retailers, Exporters Material: Paper, Biodegradable, Polyethylene, Coated |
| Companies Covered | Cortec Corporation, Daubert Cromwell, Armor Protective Packaging, Branopac GmbH, Northern Technologies International Corporation, Aicello Corporation, Transcendia Inc., Technology Packaging Ltd., Green Packaging, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global VCI Paper Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are converging to reshape formulation strategies and substrate selection across the protective packaging value chain.
Water-based VCI emulsion technology is supplanting solvent-borne coating systems in European converter operations. Automotive suppliers in Stuttgart and Munich now specify aqueous formulations to satisfy workplace exposure limits under Germany's TRGS 615 technical rule. The shift compresses volatile organic compound emissions reporting burdens while extending drying line footprints and energy consumption profiles.
China's GB/T 16716 packaging safety standards are tightening migration limits for nitrite-based corrosion inhibitors in food-contact-adjacent logistics scenarios. SAMR enforcement actions against non-compliant imports have triggered chemistry reformulation investments among export-oriented Chinese paper converters. Metal component suppliers serving dual-use industrial and food equipment markets now face dual-track inventory requirements.
Consolidated procurement desks at Volkswagen, BMW, and Mercedes-Benz parent entities now mandate centralized VCI paper qualification across all continental assembly plants. Formerly autonomous plant-level purchasing managers lose specification authority to corporate sustainability and quality councils. The concentration shifts bargaining power toward OEMs and compresses supplier diversification strategies in Germany's automotive supply corridor.
Global VCI Paper Market Segmentation
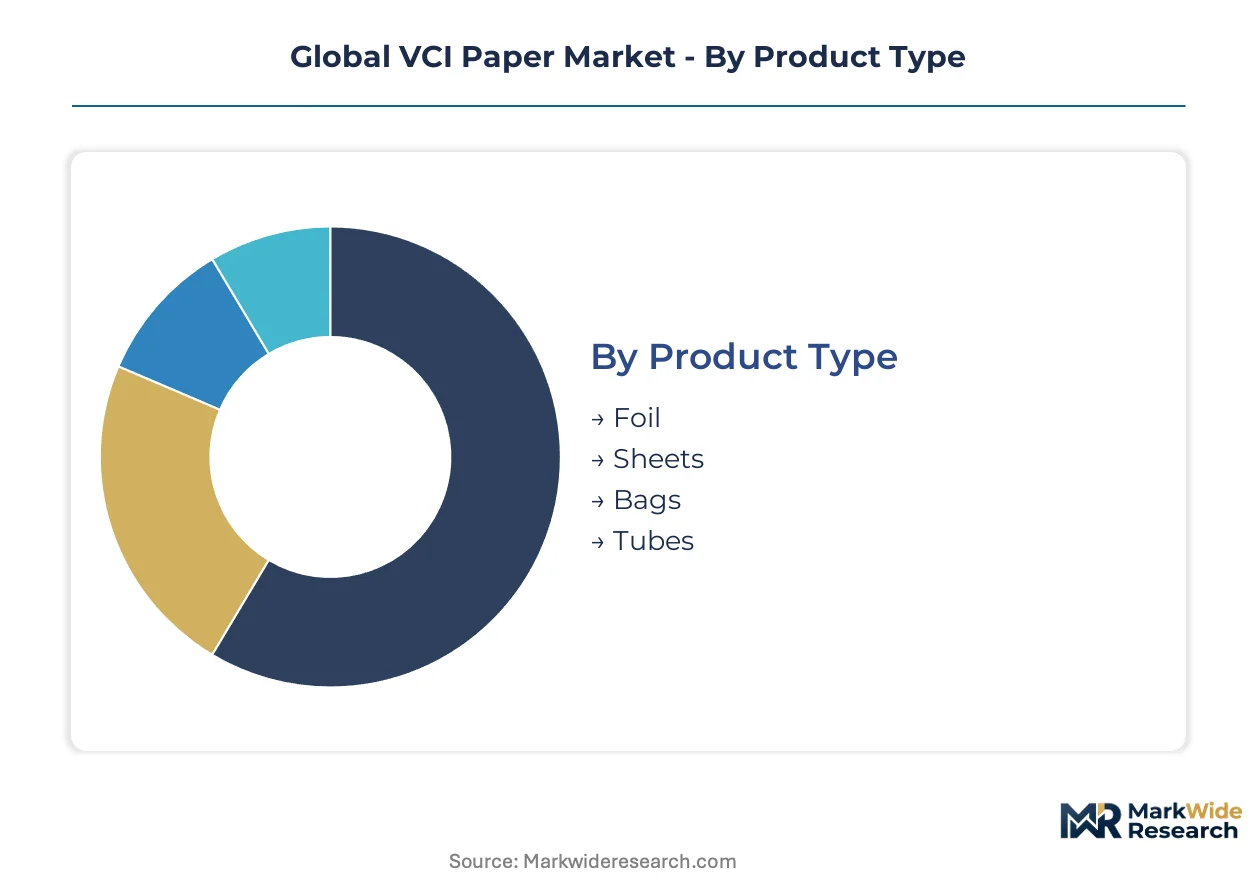
VCI paper segmentation reveals how corrosion protection specifications diverge across supply chain tiers. Channel requirements from automotive OEMs, military procurement desks, and export logistics operators create distinct performance thresholds that reshape converter product portfolios.
Product Type:
Channel mix varies sharply: bags and tubes flow through industrial distributors serving job shops, while sheets and foils ship direct to Tier 1 automotive suppliers under blanket purchase orders.
- Bags:Heat-sealed or gusseted configurations adapt to irregular component geometries without custom tooling. Stuttgart and Munich automotive clusters specify VCI bags for camshafts, transmission gears, and brake calipers moving through just-in-time supply chains.
- Sheets:Flat-stock format enables manual wrapping of large castings and machined assemblies. German tool manufacturers in Solingen and Remscheid source kraft-based VCI sheets for high-carbon steel blade protection during overseas shipment.
- Foil:Metallized barrier layers extend protection cycles in humid maritime transit.
- Tubes:Cylindrical format suits bearing races, hydraulic rods, and linear motion components.
By volume, bags lead. By growth pace, tubes are climbing the fastest as precision component exports from Tamil Nadu and Gujarat accelerate.
Application:
Cost tier segmentation separates military-aerospace qualification premiums from commodity industrial grades.
- Automotive Parts:OEM penalty clauses for corrosion-related rejects institutionalize VCI paper as mandatory protective infrastructure. BMW and Mercedes-Benz parent entities mandate centralized qualification across all continental assembly plants.
- Metal Components:Foundries and machine shops serving construction equipment and agricultural machinery represent volume baseline demand.
- Electronics:Copper trace and solder joint protection requires vapor-phase inhibitors compatible with polymeric substrates.
- Tools:Hand tool and cutting instrument manufacturers specify VCI packaging for retail display durability.
Automotive parts command premium pricing tiers. Electronics applications are expanding most quickly as PCB export volumes from Shenzhen and Dongguan climb.
End User:
Customer type determines specification authority and contract structure.
- Manufacturers:In-house packaging operations at automotive OEMs and aerospace primes drive direct procurement of certified VCI grades.
- Exporters:Freight forwarders and 3PL providers bundle corrosion protection into door-to-door service contracts.
- Distributors:Industrial supply houses stock standard SKUs for spot purchases by metalworking job shops.
- Retailers:Hardware and home improvement channels demand consumer-labeled VCI products with multilingual instructions.
Manufacturers dominate value capture. Exporters are gaining share fastest as integrated logistics contracts proliferate.
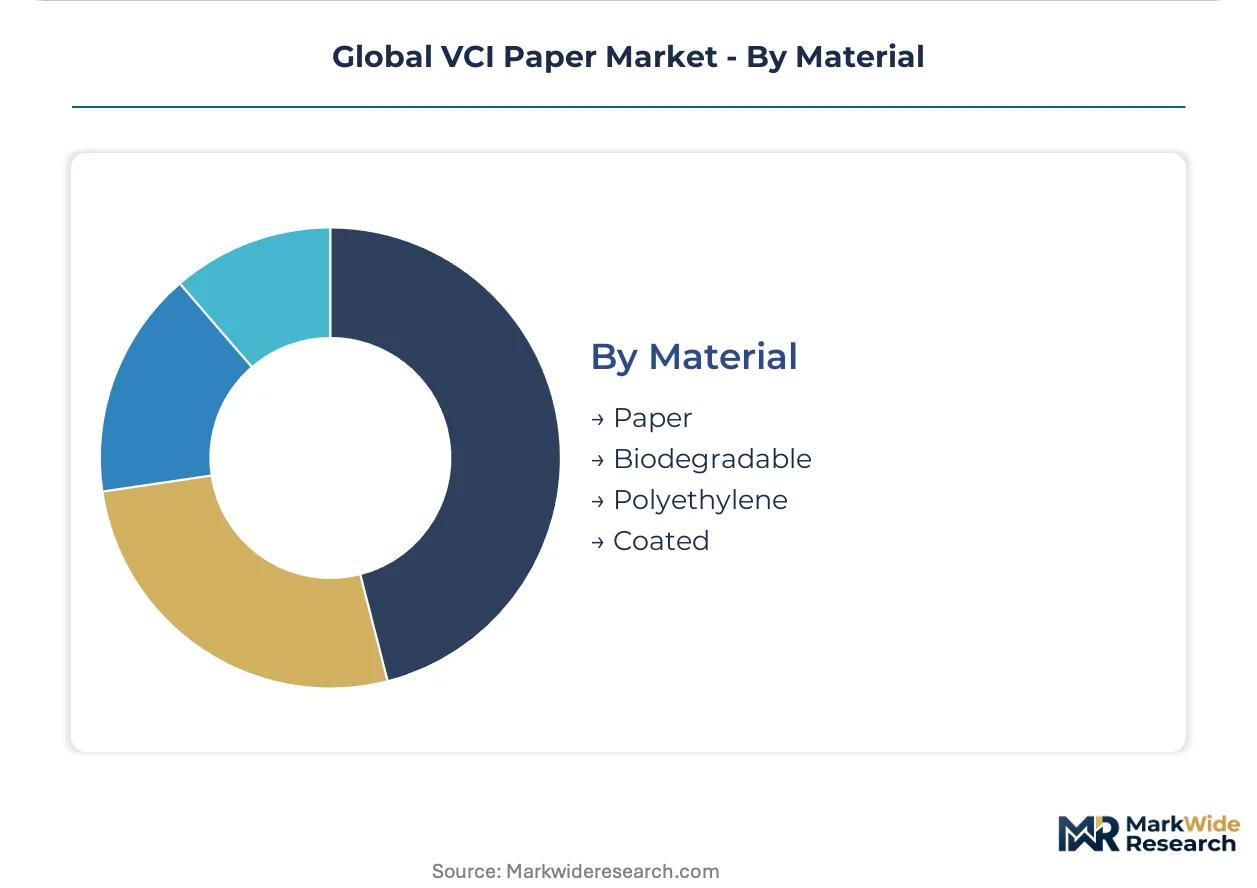
Material:
Margin structure bifurcates between commodity kraft substrates and certified biodegradable alternatives.
- Paper:Unbleached kraft remains the cost-optimized standard for ferrous metal protection in non-regulated supply chains.
- Biodegradable:EU packaging waste directive compliance and France's anti-waste law obligate landfill-compliant sourcing for export-bound goods.
- Polyethylene:Extruded film substrates with vapor-phase inhibitor additives serve applications requiring moisture barrier plus corrosion protection.
- Coated:Wax or polymer barrier coatings extend protection cycles in tropical storage conditions above standard humidity thresholds.
Paper substrates dominate tonnage. Biodegradable grades show the steepest expansion trajectory as German, French, and Dutch landfill restrictions tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty chemical formulators and paper converters cluster in Germany, the United States, China, and Japan, with certified VCI production capacity concentrating near automotive manufacturing corridors and military procurement hubs.
Germany
Baden-Württemberg and Bavaria host Europe's densest automotive supplier networks, where BMW and Mercedes-Benz parent entities enforce centralized VCI paper qualification across continental assembly plants. ECHA's REACH substance authorization requirements tighten chemical disclosure mandates for volatile corrosion inhibitors, compelling metalworking suppliers to upgrade packaging specifications. Stuttgart-based Tier 1 suppliers now mandate landfill-compliant biodegradable VCI substrates under Germany's packaging waste directive.
United States
Defense and aerospace procurement drives demand for MIL-PRF-3420 certified VCI formulations, with concentration near Great Lakes manufacturing corridors serving Department of Defense supply chains. EPA regulations under TSCA mandate pre-manufacture notification for new corrosion inhibitor chemistries, extending product development timelines for formulated VCI producers. Chicago and Detroit industrial distributors stock certified grades for automotive and heavy machinery exporters.
China
Shenzhen and Dongguan electronics manufacturers generate accelerating demand for copper-compatible VCI protection as PCB export volumes climb. SAMR enforces GB/T 16716 packaging safety standards with tightening migration limits for nitrite-based inhibitors, triggering chemistry reformulation investments among export-oriented paper converters. Yangtze River Delta metal component suppliers now face dual-track inventory requirements for industrial and food-adjacent logistics.
Japan
Precision machinery and automotive component exports from Nagoya and Osaka industrial zones sustain demand for extended-protection VCI grades compatible with maritime transit cycles. METI oversees industrial chemical safety frameworks that align with REACH-equivalent substance management protocols. Aichi Prefecture-based Tier 2 suppliers increasingly specify smart packaging with embedded humidity monitoring for high-value spindle and bearing shipments.
India
Tamil Nadu and Gujarat-based Tier 1 automotive suppliers serving European OEMs remain underpenetrated by certified VCI paper distributors, creating first-mover consolidation opportunities. BIS certification requirements for packaging materials intersect with DGFT export incentive schemes for value-added manufactured goods. Chennai and Ahmedabad industrial corridors show rising specification awareness as just-in-time supply chain penalties from multinational OEMs take effect.
Global VCI Paper Market Competitive Environment
Concentration sits with integrated chemical-paper converters and specialty coating specialists who control proprietary VCI formulation IP and maintain multi-standard certification portfolios. The competitive terrain splits between military-aerospace qualification holders and automotive supply chain integrators, with mid-tier regional converters facing margin compression from raw material volatility and capital equipment retrofit requirements. Dominant competitive moves include backward integration into active chemistry synthesis and strategic partnerships with pulp suppliers to secure kraft substrate allocation.
Within the integrated chemical-paper converter tier, Cortec Corporation and Daubert Cromwell exemplify archetypes combining proprietary formulation development with direct OEM qualification pathways. Armor Protective Packaging occupies a position emphasizing biodegradable substrate innovation aligned with EU packaging waste directives. Branopac GmbH represents the European specialist model anchored in automotive supply chain certification density.
| Leading Market Players |
|---|
| Cortec Corporation |
| Daubert Cromwell |
| Armor Protective Packaging |
| Branopac GmbH |
| Northern Technologies International Corporation |
| Aicello Corporation |
| Transcendia Inc. |
| Technology Packaging Ltd. |
| Green Packaging, Inc. |
| Others |
Value Chain & Pricing Dynamics
MIL-PRF-3420 military specifications and REACH substance authorization requirements from ECHA simultaneously gate supply qualification and price differentiation, compressing margins for uncertified converters while enabling premium capture by multi-standard certificate holders serving automotive OEMs and aerospace primes.
Pricing Analysis
REACH substance authorization dictates the pricing tier structure across European supply chains, separating military-aerospace qualification premiums from commodity industrial grades. Certification density with BMW and Mercedes-Benz parent entities commands premium-mid-economy pricing differentiation based on compliance bandwidth and audit protocol coverage. Pricing pressure stems from kraft pulp input volatility tied to Scandinavian pulp mill capacity, squeezing converter margins during raw material spikes. Tier 1 automotive suppliers show lowest price sensitivity due to penalty clause exposure, while metalworking job shops through industrial distributors exhibit highest elasticity.
Supply Chain Analysis
Just-in-time supply chain requirements from Stuttgart and Munich automotive clusters favor lean inventory strategies with blanket purchase orders and scheduled delivery windows over strategic stockpiling. Production gravity centers on Germany, the United States, and China near automotive manufacturing corridors and military procurement hubs. Unbleached kraft paper substrates and specialty amine-based corrosion inhibitor precursors draw from Scandinavian pulp mills and German-Japanese chemical specialists respectively. Single-source vulnerability for formulated VCI actives creates structural risk exposure. Distribution runs through direct OEM qualification pathways for certified grades and industrial distributor networks for standard SKUs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as biodegradable substrate mandates across Germany, France, and the Netherlands accelerate material substitution cycles and open premium positioning for landfill-compliant VCI paper grades.
For Market Incumbents: Shield certification portfolios against chemistry reformulation investments triggered by China's GB/T 16716 tightening on nitrite-based inhibitors through backward integration into active synthesis and captive supply of REACH-registered precursors. Deepen vertical control over kraft substrate allocation via strategic pulp supplier partnerships to defend margin position during raw material volatility spikes. For New Entrants and Emerging Players: MIL-PRF-3420 certification fast-track programs unlock military-aerospace qualification channels where Cortec Corporation dominates and price premiums sustain new entrant economics. Target Tamil Nadu and Gujarat Tier 1 automotive corridors serving European OEMs as the most penetrable geography, leveraging BIS certification intersections with DGFT export incentive schemes for value-added manufactured goods. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across water-based VCI emulsion coating line retrofits as European converters replace solvent-borne systems to satisfy Germany's TRGS 615 workplace exposure limits. Five-to-ten year viability favors integrated chemical-paper converters with proprietary formulation IP and multi-standard certification density. Watch for SAMR enforcement action intensity against non-compliant Chinese imports as inflection indicator for chemistry reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Chemistry Synthesis | Captive supply of REACH-registered precursors reduces single-source vulnerability for German and Japanese specialty amine suppliers. |
| Biodegradable Substrate Certification Investment | Landfill-compliant VCI paper grades align with EU packaging waste directive enforcement in Germany, France, and the Netherlands. |
| Water-Based Emulsion Coating Line Retrofit | Aqueous formulation capacity satisfies Germany's TRGS 615 technical rule while compressing volatile organic compound emissions reporting burdens. |
| Indian Automotive Corridor Distribution Partnership | Chennai and Ahmedabad industrial corridor penetration captures rising specification awareness from multinational OEM just-in-time penalty clauses. |
| Smart Packaging with Embedded Humidity Monitoring | Predictive corrosion monitoring capabilities open premium service contracts with aerospace MRO facilities and Aichi Prefecture Tier 2 suppliers. |
Study Parameters
Operator-level perspectives from VCI paper plant managers, Tier 1 automotive supplier procurement leads, industrial distribution channel partners, and technical R&D directors anchored the qualitative base for this study. Primary interview insights combined with customs and trade data, ACC and Cefic chemical industry reports, SEC 10-K filings from listed packaging converters, and SAMR enforcement action records for secondary validation. Bottom-up demand modeling across product type, application, end user, and material grade dimensions triangulated against top-down market sizing from production capacity assessments.
Sensitivity analysis tested forecast robustness across the projection horizon by varying kraft pulp input cost assumptions, REACH substance authorization timeline scenarios, and biodegradable mandate adoption rates in core European markets. Segmentation dimensions modeled include product format, corrosion protection specification tier, substrate material certification status, and regional regulatory cluster alignment. CAGRs derived from normalized growth trajectory fitting against historical adoption patterns in automotive parts packaging and electronics export corridors. Industry-specific forecast inputs incorporated OEM penalty clause severity indices and maritime transit protection cycle requirements.
Decision-makers should treat outputs as directional under sustained automotive OEM certification centralization and ECHA substance restriction evolution; material deviation would warrant model refresh. Forecasts reflect assumptions regarding pulp mill capacity stability and nitrite-based inhibitor phase-out timelines. Revision becomes warranted when SAMR enforcement intensity or biodegradable landfill restriction thresholds cross materiality bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Sublimation Paper Market
Paper & Paperboard Packaging
Middle East and Africa Corrugated Box Market
Paper & Paperboard Packaging
Paper Tubes Market
Paper & Paperboard Packaging
Schrenz Paper Market
Paper & Paperboard Packaging
United States Corrugated Packaging Market
Paper & Paperboard Packaging
Australia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Paper Cup Lids Market
Paper & Paperboard Packaging
Retail Paper Bags Market
Paper & Paperboard Packaging
Converting Paper Market
Paper & Paperboard Packaging
Qatar Paper Packaging Products Market
Paper & Paperboard Packaging
Cardboard Tubs Market
Paper & Paperboard Packaging
Polycoated Paper Packaging Market
Paper & Paperboard Packaging
Waxing Base Paper Market
Paper & Paperboard Packaging
Protective Paperboard Market
Paper & Paperboard Packaging
Paper Edge Protectors Market
Paper & Paperboard Packaging
MMA Film & Sheet Market