
 Vietnam Freight and Logistics Market | 2026-2036
Vietnam Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Freight and Logistics Market Outlook
Vietnam's port and highway infrastructure expansion is reshaping regional cargo flows. Gemadept leverages its deep-water terminal network to dominate container handling along Vietnam's coastline. PetroVietnam Transportation Corporation anchors hydrocarbon logistics through specialized tanker and pipeline operations. A.P. Moller - Maersk competes by integrating ocean freight with inland container depot coverage across northern and southern Vietnam.
Vietnam freight and logistics encompasses the coordinated movement, storage, and customs clearance of goods across air, sea, road, and rail networks, with cold-chain specifications and bonded warehouse protocols governing perishable and dutiable cargo. The sector enables manufacturing supply chains and retail distribution throughout Southeast Asia's most dynamic production base. Freight forwarding and transportation services capture the dominant value pools as manufacturing exports surge, while warehouse management systems represent the fastest-growing technology segment as operators automate inventory tracking. E-commerce end users are driving disproportionate capacity investment in last-mile delivery networks.
Vietnam's Ministry of Transport and the Vietnam Logistics Business Association shape market access through infrastructure licensing and professional certification standards. The Logistics Development Strategy mandates digital customs platforms and green fleet conversion timelines that filter participant eligibility. Stakeholders must monitor how enforcement of axle-load regulations and emissions standards reconfigures fleet economics and terminal access across the Red River and Mekong Delta corridors.
Market Dynamics
Vietnam's freight and logistics sector is undergoing structural transformation driven by the Ministry of Transport's axle-load enforcement tightening across the Red River and Mekong Delta corridors, forcing fleet operators to reconfigure truck configurations and terminal access protocols.
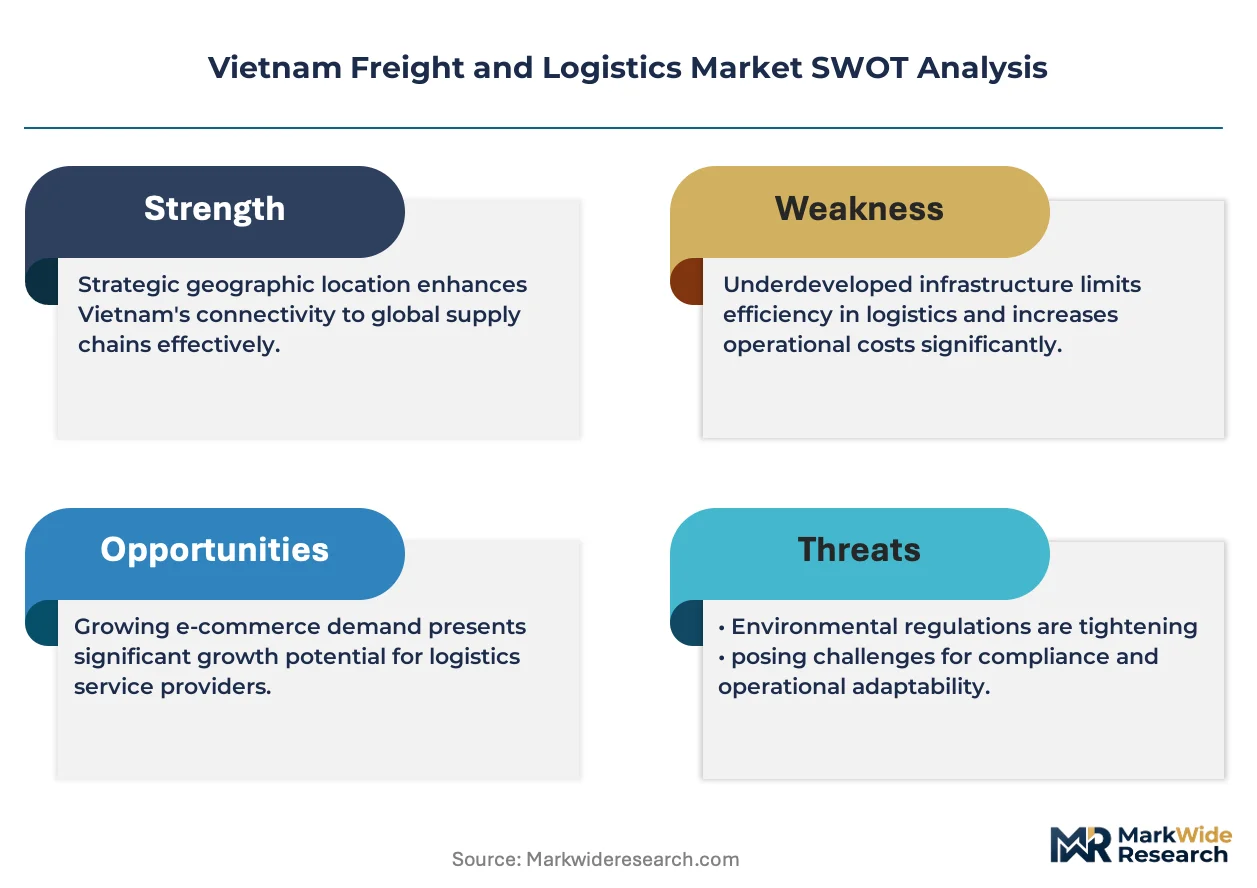
Growth Catalysts
- E-commerce fulfillment networks:Provincial distribution centers are expanding into secondary cities like Can Tho and Da Nang to serve Shopee and Lazada fulfillment demands.
- Logistics Development Strategy:Vietnam's national framework mandates digital customs platforms and green fleet conversion timelines that filter participant eligibility.
- Manufacturing export surges:Electronics and textile producers in the Hanoi-Haiphong-Quang Ninh cluster require bonded warehouse capacity and cold-chain specifications.
Market Restraints
- Fuel cost volatility:Diesel price fluctuations compress margins for road freight operators serving the Ho Chi Minh City-Dong Nai corridor.
- Deep-water terminal concentration:Container handling capacity clusters at Cai Mep and Lach Huyen, creating chokepoint vulnerability.
- Emissions compliance friction:Euro 4 engine standards and green fleet timelines impose retrofit capital burdens on smaller operators.
Strategic Opportunities
- Central Highlands penetration:Lam Dong and Dak Lak provinces remain underserved for temperature-controlled agricultural logistics.
- Rail-sea intermodal:The North-South railway corridor convergence with Cai Mep port offers multimodal alternatives to pure trucking.
- Digital freight matching:Mobile platforms connecting shippers with available truck capacity address fragmentation in the long-haul segment.
Industry Challenges
- Warehouse management system integration:Legacy inventory tracking infrastructure resists API connectivity with e-commerce order management platforms.
- Certified cold-chain technician scarcity:HACCP-qualified personnel shortages constrain pharmaceutical and seafood logistics expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Freight and Logistics Market |
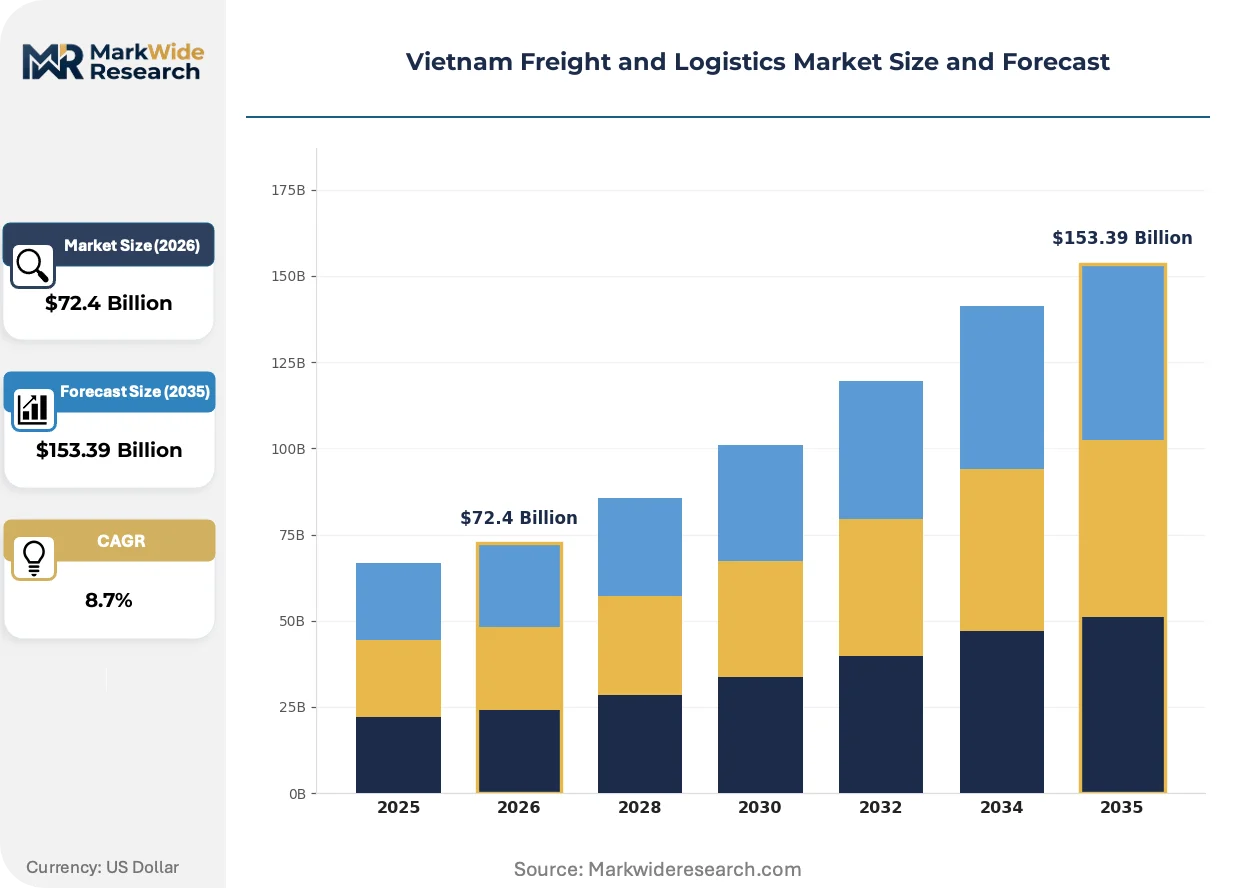
| Market Size in 2026 | $72.4 Billion |
| Market Size in 2035 | $153.39 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Customs Brokerage End User: E-commerce, Manufacturing, Retail, Pharmaceuticals Technology: Track & Trace, Warehouse Management Systems, Automated Inventory, Blockchain Delivery Mode: Air, Sea, Road, Rail |
| Companies Covered | Gemadept, PetroVietnam Transportation Corporation, A.P. Moller - Maersk, Kuehne+Nagel, ViettelPost, DHL Group, Bee Logistics Corporation, Transimex, FedEx, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Freight and Logistics Market Strategic Shifts
Automation and regulatory digitization are compressing operational timelines across Vietnam's logistics value chain. Technology deployment concentrates in inventory tracking and customs clearance, while policy mandates reshape fleet economics and terminal access.
Internet-of-Things sensor networks are digitizing container monitoring across Vietnam's coastline. Seafood exporters and pharmaceutical distributors are deploying temperature-logging devices at the pallet level. Real-time visibility is digitizing supply chain coordination between manufacturers and port operators, reducing detention fees and demurrage exposure.
Vietnam's Logistics Development Strategy mandates customs modernization through digital platform integration. The framework requires electronic manifest submission and risk-based inspection protocols. Bonded warehouse operators and freight forwarders are restructuring compliance workflows to meet accelerated clearance timelines.
Shippers are consolidating procurement through integrated logistics service contracts rather than fragmented point solutions. Electronics manufacturers in Bac Ninh and Hai Duong provinces are bundling freight forwarding with warehousing under single-provider agreements. This concentration is visible most acutely in the northern economic cluster where supply chain managers prioritize vendor reduction.
Vietnam Freight and Logistics Market Segmentation
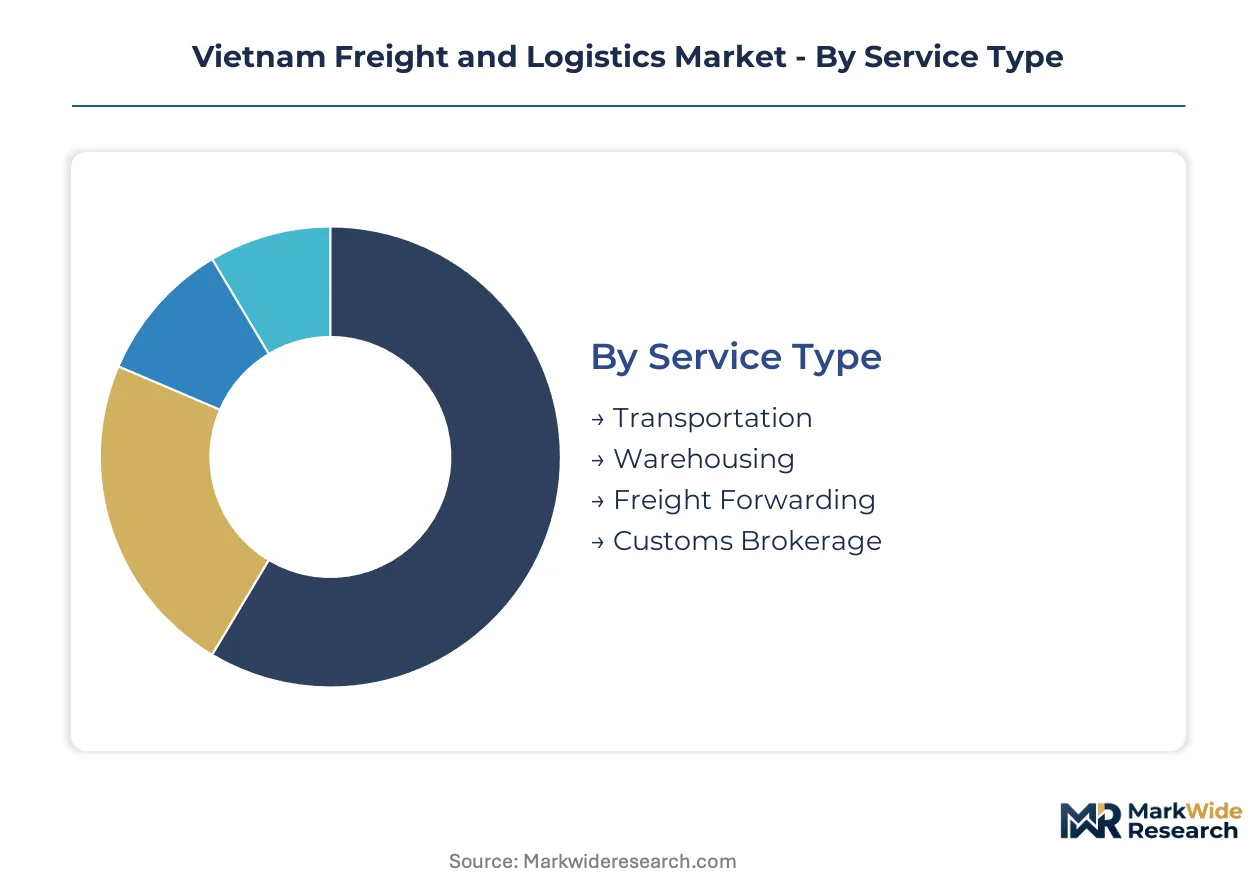
Segmentation in Vietnam's freight and logistics market reveals distinct operational velocities. Service types and delivery modes exhibit divergent asset turnover cycles, while technology adoption rates vary sharply across end-user sophistication levels.
Service Type:
Cycle times compress from weeks to hours across this spectrum. Transportation assets turn daily, warehousing contracts lock in months, freight forwarding reconciles in days, and customs brokerage completes in hours.
- Transportation:Fleet-based movement of containerized and bulk cargo across the Red River and Mekong Delta corridors. Demand concentrates around the Hanoi-Haiphong-Quang Ninh cluster as electronics exporters require just-in-time truck availability to port terminals. Fuel cost volatility and axle-load enforcement are compressing operator margins and forcing fleet reconfiguration.
- Freight Forwarding:Intermediary coordination of multimodal routing, documentation, and carrier procurement. Manufacturing exporters in Bac Ninh and Hai Duong provinces are consolidating procurement through integrated service contracts rather than fragmented point solutions. Customs modernization timelines are accelerating clearance workflows.
- Warehousing:Bonded and standard storage facilities with inventory management protocols. Cold-chain specifications for seafood and pharmaceuticals are driving temperature-controlled capacity investment in secondary cities.
- Customs Brokerage:Documentation preparation and regulatory compliance facilitation for import-export transactions. Digital platform mandates from Vietnam's Logistics Development Strategy are filtering participant eligibility.
Transportation anchors the volume base while Freight Forwarding gains share at the steepest rate.
End User:
Procurement sophistication tiers separate this category. E-commerce platforms demand real-time visibility, manufacturing requires bonded warehouse integration, retail prioritizes cost efficiency, and pharmaceuticals mandate HACCP-certified cold chains.
- E-commerce:Last-mile and fulfillment center logistics serving Shopee and Lazada networks. Provincial distribution centers are expanding into Can Tho and Da Nang to serve secondary city demand. Warehouse management system integration with legacy inventory infrastructure remains a constraint.
- Manufacturing:Electronics and textile supply chain logistics with bonded warehouse and export documentation requirements. The southern Ho Chi Minh City-Dong Nai-Ba Ria Vung Tau corridor concentrates demand as production bases expand.
- Retail:Distribution center replenishment and store delivery networks. Cost pressures dominate procurement decisions as diesel fluctuations compress road freight margins.
- Pharmaceuticals:Temperature-controlled logistics with regulatory compliance for drug distribution. Certified cold-chain technician scarcity constrains expansion despite demand concentration in urban centers.
Manufacturing commands the revenue base while E-commerce is expanding most quickly.
Technology:
Deployment maturity spreads from proven infrastructure to experimental pilots. Track and trace systems operate at scale, warehouse management systems automate rapidly, automated inventory pilots in select facilities, and blockchain remains conceptual.
- Track & Trace:Internet-of-Things sensor networks monitoring container location and condition across Vietnam's coastline. Seafood exporters deploy temperature-logging devices at the pallet level to reduce detention fee exposure.
- Warehouse Management Systems:Software platforms automating inventory tracking, order fulfillment, and labor coordination. E-commerce fulfillment networks are driving disproportionate capacity investment as operators integrate API connectivity with order management platforms.
- Automated Inventory:Robotics and autonomous systems for picking, sorting, and storage operations. Large distribution centers in the northern economic cluster are piloting deployments.
- Blockchain:Distributed ledger applications for documentation verification and supply chain transparency. Adoption remains limited to pilot programs with major freight forwarders.
Warehouse Management Systems anchor technology spending while Automated Inventory shows the steepest adoption trajectory.
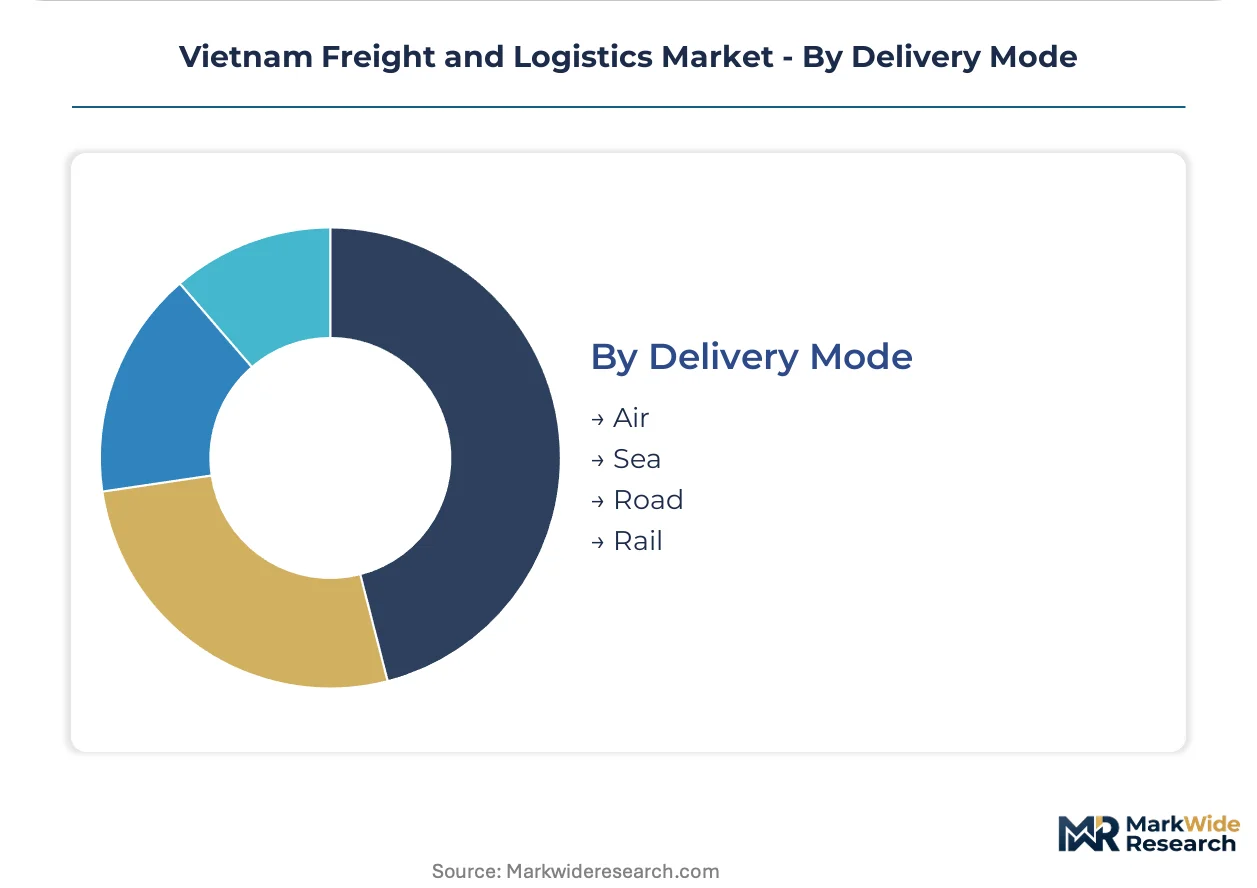
Delivery Mode:
Speed-cost tradeoffs structure modal selection. Air freight moves in hours at premium rates, sea freight spans weeks at lowest unit cost, road freight balances flexibility with moderate expense, and rail offers emerging intermodal alternatives.
- Sea:Container and bulk vessel operations through deep-water terminals at Cai Mep and Lach Huyen. Chokepoint vulnerability concentrates at these facilities as manufacturing export volumes surge.
- Road:Truck-based freight across national highway networks connecting economic corridors. Axle-load enforcement tightening is forcing fleet reconfiguration and terminal access protocol changes.
- Air:Cargo aircraft and belly-hold freight through Noi Bai and Tan Son Nhat airports. Electronics and pharmaceutical shippers absorb premium rates for time-sensitive delivery.
- Rail:North-South railway corridor freight convergence with Cai Mep port for multimodal alternatives. Infrastructure limitations constrain competitive positioning against pure trucking.
Road freight dominates volume throughput while Rail is climbing the fastest as intermodal investment expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Lach Huyen deep-water terminal anchors northern Vietnam's container throughput capacity, while Cai Mep port complex underwrites southern export corridors. These maritime assets concentrate manufacturing supply chains along two dominant economic axes.
Red River Delta
Electronics exporters in Bac Ninh and Hai Duong provinces drive bonded warehouse demand for just-in-time component delivery. Vietnam's Logistics Development Strategy mandates digital customs platforms that filter terminal access eligibility. The Hanoi-Haiphong-Quang Ninh cluster concentrates cold-chain investment as seafood processors expand temperature-controlled distribution.
Southeast Region
Textile manufacturers in Dong Nai and Binh Duong provinces absorb road freight capacity along the Ho Chi Minh City corridor. Axle-load enforcement tightening by the Ministry of Transport forces fleet reconfiguration and compresses operator margins. The Ba Ria Vung Tau sub-region anchors petroleum logistics through specialized tanker operations and pipeline networks.
Mekong Delta
Agricultural shippers in Can Tho and An Giang provinces generate temperature-controlled cargo flows for rice and seafood exports. Euro 4 emissions standards impose retrofit capital burdens on smaller trucking operators serving provincial routes. Lam Dong province remains underserved for pharmaceutical cold-chain distribution despite growing demand.
Central Coast
Da Nang's port infrastructure supports manufacturing diversification away from northern and southern saturation. The Ministry of Transport's multimodal corridor investments converge rail and sea freight at Tien Sa terminal. Quang Nam province attracts electronics assembly logistics as supply chains seek geographic risk distribution.
Central Highlands
Coffee and pepper exporters in Dak Lak and Gia Lai provinces face infrastructure gaps for agricultural logistics. HACCP-certified technician scarcity constrains pharmaceutical-grade cold-chain expansion into these provinces. The North-South railway corridor offers emerging intermodal alternatives to pure trucking for bulk commodity movement.
Vietnam Freight and Logistics Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream. The Vietnam freight and logistics market structures around three distinct player tiers: global shipping lines with integrated inland networks, domestic terminal operators with coastal asset concentration, and specialized freight forwarders with customs brokerage capabilities. Strategic moves center on bonded warehouse capacity expansion and digital platform integration for customs clearance acceleration.
Among Vietnam-based operators, Gemadept exemplifies the domestic terminal archetype through its deep-water port network position. PetroVietnam Transportation Corporation anchors the hydrocarbon logistics specialization with tanker and pipeline infrastructure. A.P. Moller - Maersk represents the global integrator model, combining ocean freight with inland depot coverage across both northern and southern corridors.
| Leading Market Players |
|---|
| Gemadept |
| PetroVietnam Transportation Corporation |
| A.P. Moller - Maersk |
| Kuehne+Nagel |
| ViettelPost |
| DHL Group |
| Bee Logistics Corporation |
| Transimex |
| FedEx |
| Others |
Value Chain & Pricing Dynamics
Axle-load enforcement tightening by Vietnam's Ministry of Transport determines both fleet reconfiguration costs and corridor-specific pricing spreads across the Red River and Mekong Delta networks. Diesel price volatility feeds back into carrier procurement decisions, compressing margins for road freight operators and accelerating modal shift toward rail-sea intermodal alternatives.
Pricing Analysis
Volume-discount tiering structures dominate contract negotiations between electronics manufacturers and integrated logistics providers across the Hanoi-Haiphong-Quang Ninh cluster. Pricing stratifies across premium bonded-warehouse tiers, standard container-yard storage, and economy cross-dock facilities based on customs clearance speed and temperature-control certification. Cost compression in the economy tier is intensifying because smaller operators struggle with Euro 4 retrofit capital burdens. E-commerce platforms demonstrate the least price sensitivity, absorbing premium rates for real-time warehouse management system integration, while agricultural exporters in the Mekong Delta face acute margin pressure.
Supply Chain Analysis
Export-control regimes on semiconductor manufacturing equipment limit technology flows into northern Vietnam's electronics assembly corridors, constraining supply chain upgrading timelines. Component sourcing draws from China, South Korea, and Taiwan for precision electronics parts, while cold-chain equipment depends on Japanese and German refrigeration technology. Single-source vulnerability concentrates at Cai Mep and Lach Huyen deep-water terminals, where container handling capacity chokes export flows. Distribution runs through bonded warehouse networks integrated with provincial distribution centers, with last-mile density varying sharply between Ho Chi Minh City and secondary cities like Can Tho.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's freight and logistics market demands substitution defense against regional hub competition from Thailand and Indonesia, where port automation and customs efficiency threaten to divert manufacturing supply chain investment.
For Market Incumbents: Harden terminal access protocols through digital customs platform pre-certification, locking in bonded warehouse eligibility before the Logistics Development Strategy tightens participant filters. Deepen backward integration into cold-chain equipment leasing to offset certified technician scarcity in pharmaceutical logistics. Defensive positioning against Indonesian port automation requires accelerated warehouse management system deployment in the southern corridor. For New Entrants and Emerging Players: Establish a beachhead in Central Highlands agricultural logistics, where Lam Dong and Dak Lak provinces remain underserved for temperature-controlled cargo flows despite growing coffee and pepper export volumes. Target digital freight matching platforms for the long-haul segment, addressing fragmentation between shippers and available truck capacity. A go-to-market angle anchored in HACCP-certified cold-chain technician training programs unlocks pharmaceutical distribution contracts in secondary cities. For Investors and Strategic Acquirers: Vietnam's green fleet conversion timeline reshapes the acquisition landscape, filtering terminal access eligibility toward operators with Euro 4-compliant assets and API-integrated warehouse systems. Long-term viability centers on platform consolidation plays across the 5-10 year regulatory compliance window. Acquisition target archetypes include domestic freight forwarders with customs brokerage capabilities in the northern economic cluster. The signal to watch is enforcement acceleration of axle-load regulations across provincial highway networks, which would force distressed asset sales from non-compliant operators.| Strategic Initiative | Industry Significance |
|---|---|
| Bonded Warehouse Capacity Expansion | Secures terminal access eligibility under Vietnam's Logistics Development Strategy mandates. |
| Digital Customs Platform Integration | Accelerates clearance workflows for electronics exporters in Bac Ninh and Hai Duong provinces. |
| Cold-Chain Technician Certification Programs | Addresses HACCP-qualified personnel scarcity constraining pharmaceutical logistics expansion. |
| Rail-Sea Intermodal Infrastructure Investment | Creates multimodal alternatives to pure trucking along the North-South railway corridor. |
| Last-Mile Network Penetration | Captures Shopee and Lazada fulfillment demand in secondary cities like Can Tho and Da Nang. |
Study Parameters
The analysis maps transportation, freight forwarding, warehousing, and customs brokerage sub-sectors, each validated through fleet operators, bonded warehouse managers, customs brokers, and e-commerce logistics directors. Primary interviews with these stakeholders combined with secondary validation from Vietnam Logistics Business Association publications, Ministry of Transport infrastructure disclosures, and customs modernization policy documents. Bottom-up service-type segmentation triangulates against top-down corridor-level volume estimates across the Red River and Mekong Delta economic axes.
Assumption sets held fuel cost volatility and regulatory enforcement timelines fixed while varying manufacturing export growth rates and e-commerce penetration scenarios across the projection horizon. Segmentation dimensions modeled include service type, end-user sophistication tier, technology deployment maturity, and delivery mode speed-cost positioning. CAGRs derive from corridor-specific capacity utilization trends and modal shift elasticity parameters, with forecast inputs incorporating bonded warehouse stock levels and cold-chain asset deployment rates.
Macroeconomic conditions sit as an overlay; deviation in manufacturing FDI flows, diesel price trajectories, or regional trade agreement implementation would shift the trajectory. Forecasts reflect documented assumptions about infrastructure completion schedules and regulatory enforcement intensity. Material shifts in green fleet conversion deadlines or deep-water terminal expansion timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Australia 3PL Market
Logistics and Shipping
Uruguay Freight and Logistics Market
Logistics and Shipping
High-Tech Logistics Market
Logistics and Shipping
Logistics Data Quality and Normalization Services Market
Logistics and Shipping
Logistics Visualization System Market
Logistics and Shipping
Latin America Contract Logistics Market
Logistics and Shipping
Europe Contract Logistics Market
Logistics and Shipping
Europe FMCG Logistics Market
Logistics and Shipping
North America Cargo Handling Equipment Market
Logistics and Shipping
United Kingdom Third Party Logistics (3PL) Market
Logistics and Shipping
GCC Secure Logistics Market
Logistics and Shipping
Latin America Freight Forwarding Market
Logistics and Shipping
APAC Contract Logistics Market
Logistics and Shipping
Container Terminal Automation Market
Logistics and Shipping
Global Port Logistics Market
Logistics and Shipping
Mexico Containerized Shipping Market