
 Logistics Visualization System Market | 2026-2036
Logistics Visualization System Market Size, Share, and Industry Trends Forecast 2026-2036
Logistics Visualization System Market Outlook
Cloud-native rendering architectures are rebalancing infrastructure economics away from legacy on-premises visualization stacks. SAP leverages its ERP integration depth to anchor enterprise-grade logistics control towers across European manufacturing hubs. Oracle sustains competitive pressure through database-layer optimization for high-velocity supply chain telemetry. Manhattan Associates specializes in warehouse-centric visualization modules that dominate North American retail distribution networks.
A logistics visualization system integrates geospatial mapping, sensor telemetry aggregation, and predictive analytics engines to render multimodal freight movements across supply chain nodes with sub-minute refresh rates. These platforms synthesize GPS coordinates, RFID tag states, and IoT device streams into unified operational dashboards for dispatchers, fleet managers, and customs brokers. Cloud-based deployment architectures now capture the fastest expansion trajectory as transportation operators abandon capital-intensive server farms for elastic compute consumption. Real-time tracking functionality commands premium pricing relative to static 2D mapping modules due to its direct linkage with penalty avoidance in time-definite logistics contracts. IoT Solutions as a technology layer increasingly determines margin pools, since edge-device connectivity density correlates with subscription renewal rates and upsell velocity.
The EU AI Act imposes explainability mandates on automated route-optimization algorithms, forcing vendors to retrofit visualization layers with decision-audit trails. The US FAA and DOT jointly shape commercial drone integration standards that expand last-mile visualization requirements for aerial freight corridors. Stakeholders must weigh compliance engineering investments against the revenue premium attached to certified transparent routing platforms.
Market Dynamics
Cloud-native rendering architectures are compressing infrastructure economics and forcing legacy on-premises visualization stacks into accelerated obsolescence cycles across freight operators.
Growth Catalysts
- Cold Chain Expansion:Pharmaceutical logistics operators in Germany and the Netherlands are deploying temperature-monitoring dashboards for biologic shipments. The EU Good Distribution Practice mandates real-time thermal logging.
- EU AI Act Compliance:Automated routing vendors must embed explainability layers into visualization platforms. This creates mandatory upgrade cycles for algorithmic audit trails.
- Multimodal Corridor Consolidation:Hamburg-Rotterdam freight operators are integrating rail, barge, and truck telemetry into unified control towers. Sensor density correlates directly with contract renewal rates.
Market Restraints
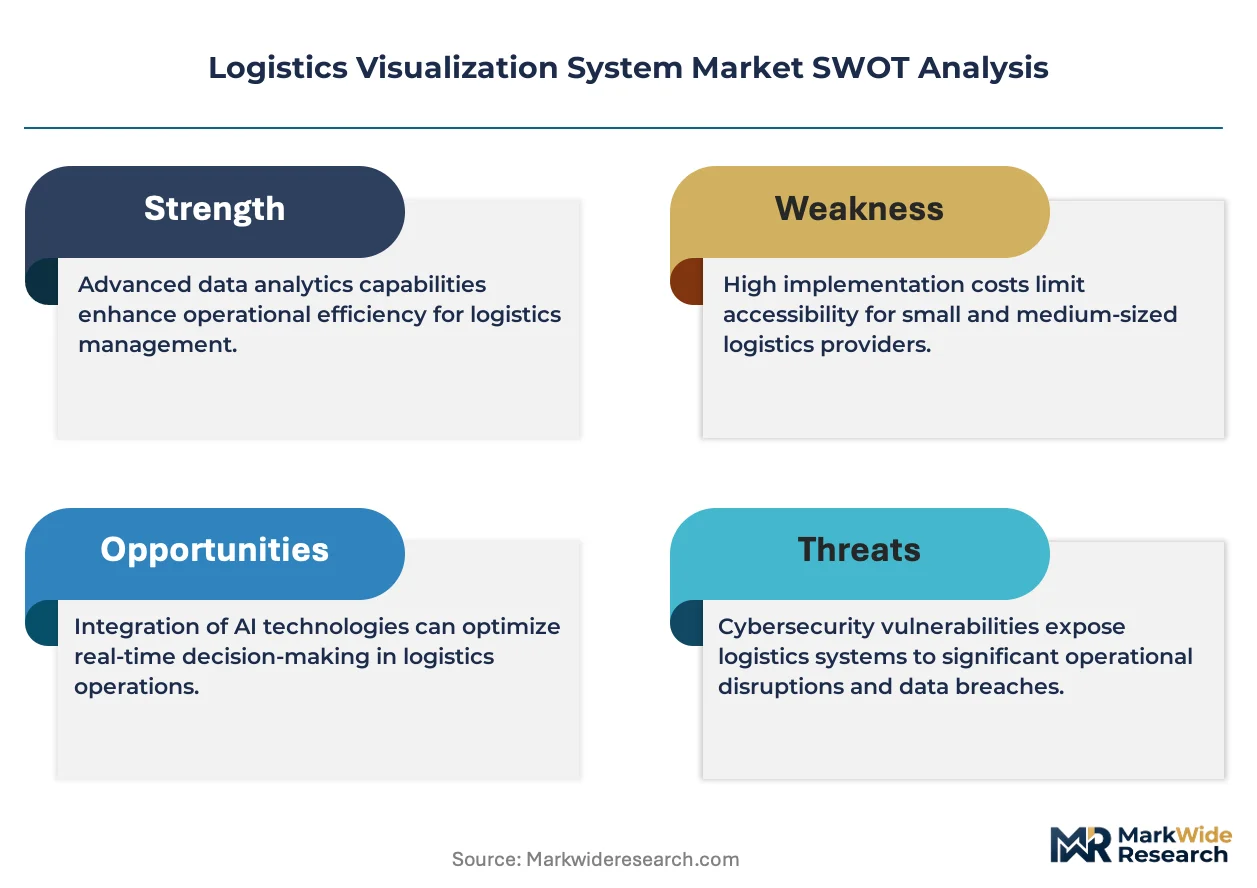
- Edge Hardware Costs:IoT gateway density requirements for sub-minute refresh rates strain capital budgets at mid-tier 3PLs. Device procurement cycles lag software deployment timelines.
- Data Sovereignty Fragmentation:Cross-border telemetry flows face divergent national storage mandates. Operators serving multiple EU member states must maintain redundant infrastructure stacks.
- Legacy ERP Lock-in:SAP and Oracle control tower integrations create switching friction. Migration costs exceed three-year subscription values for established manufacturing shippers.
Strategic Opportunities
- Drone Corridor Visualization:The US FAA and DOT are finalizing commercial unmanned aerial freight standards. Last-mile aerial tracking modules represent unpenetrated white space.
- CE Marking Acceleration:EU medical device logistics mandates IoT-enabled supply chain documentation. Visualization platforms with embedded compliance reporting capture premium positioning.
- Digital Twin Convergence:Warehouse digital twins are merging with freight visualization layers. Manhattan Associates and SAP are bridging these previously siloed systems.
Industry Challenges
- Geospatial Data Science Talent:Sub-minute telemetry rendering requires specialized GIS-analytics hybrid skills. European technical universities produce insufficient graduates for current hiring pipelines.
- Interoperability Certification Delays:ISO 19844 supply chain data exchange standards remain in draft. Vendors await ratification before committing development resources to unified APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Logistics Visualization System Market |
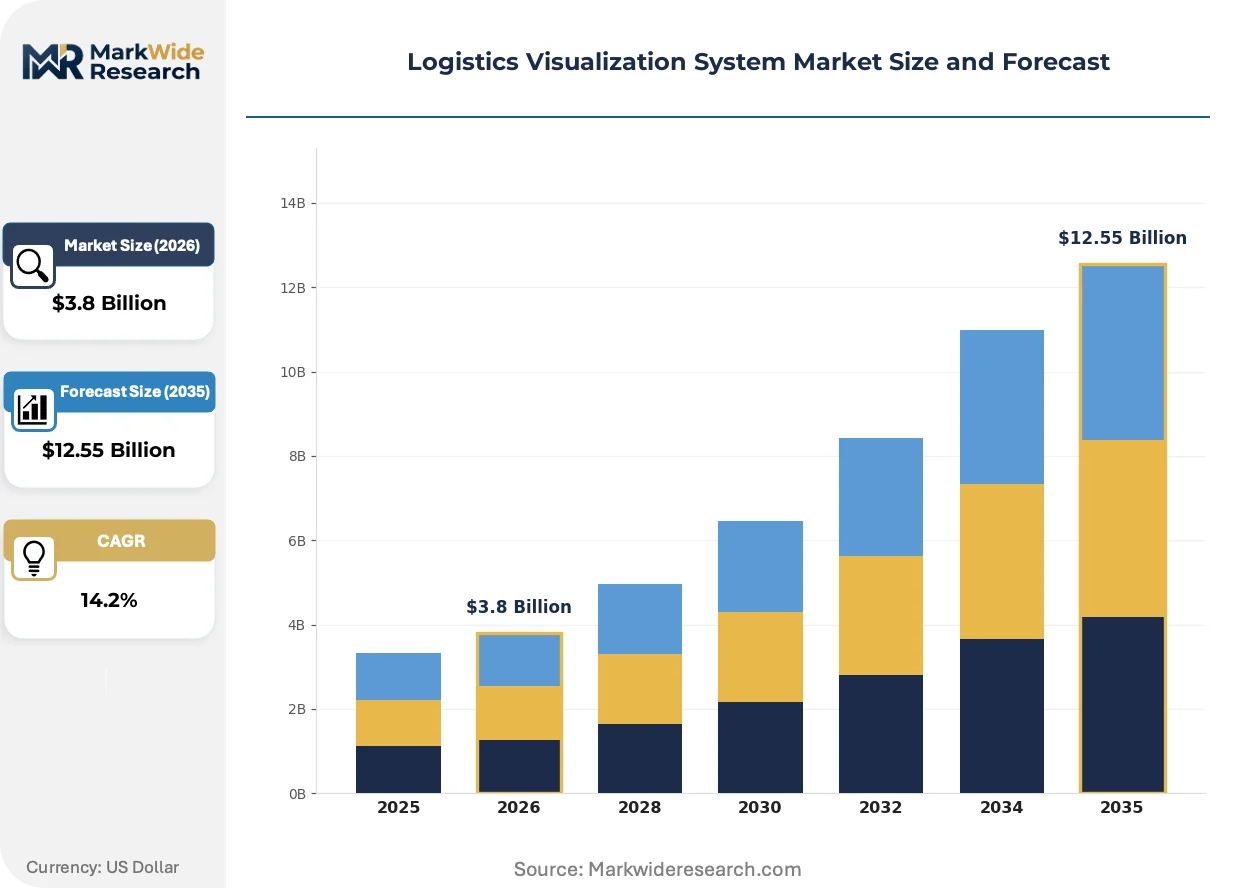
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Mapping, 3D Visualization, Real-Time Tracking, Fleet Management Technology: GPS Tracking, RFID, IoT Solutions, Cloud Computing End User: Retail, Manufacturing, Transportation, Supply Chain Management Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Solutions |
| Companies Covered | SAP, Oracle, IBM, Microsoft, Manhattan Associates, The Descartes Systems Group, Körber AG, C.H. Robinson, Blue Yonder, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Logistics Visualization System Market Strategic Shifts
Real-time sensor telemetry is collapsing the latency gap between physical freight movement and digital representation, redefining competitive minimums for operational visibility.
Digital twin technology is unifying warehouse operations with over-the-road freight tracking. Cold chain pharmaceutical distributors in Germany are deploying these converged models first. The technology is unifying previously separate capital allocation decisions for storage and transport infrastructure.
The EU AI Act mandates algorithmic explainability for automated routing decisions. Vendors must retrofit visualization layers with decision-audit trails showing why specific corridors were selected. European pharmaceutical logistics operators face the steepest compliance engineering investments due to time-definite contract penalties.
Buyer procurement patterns are compressing vendor evaluation cycles from eighteen months to under six. Mid-sized 3PLs in the Netherlands are bypassing lengthy RFP processes for pilot-to-scale SaaS conversions. This acceleration is most visible among temperature-sensitive freight specialists where operational downtime costs exceed software subscription values.
Logistics Visualization System Market Segmentation
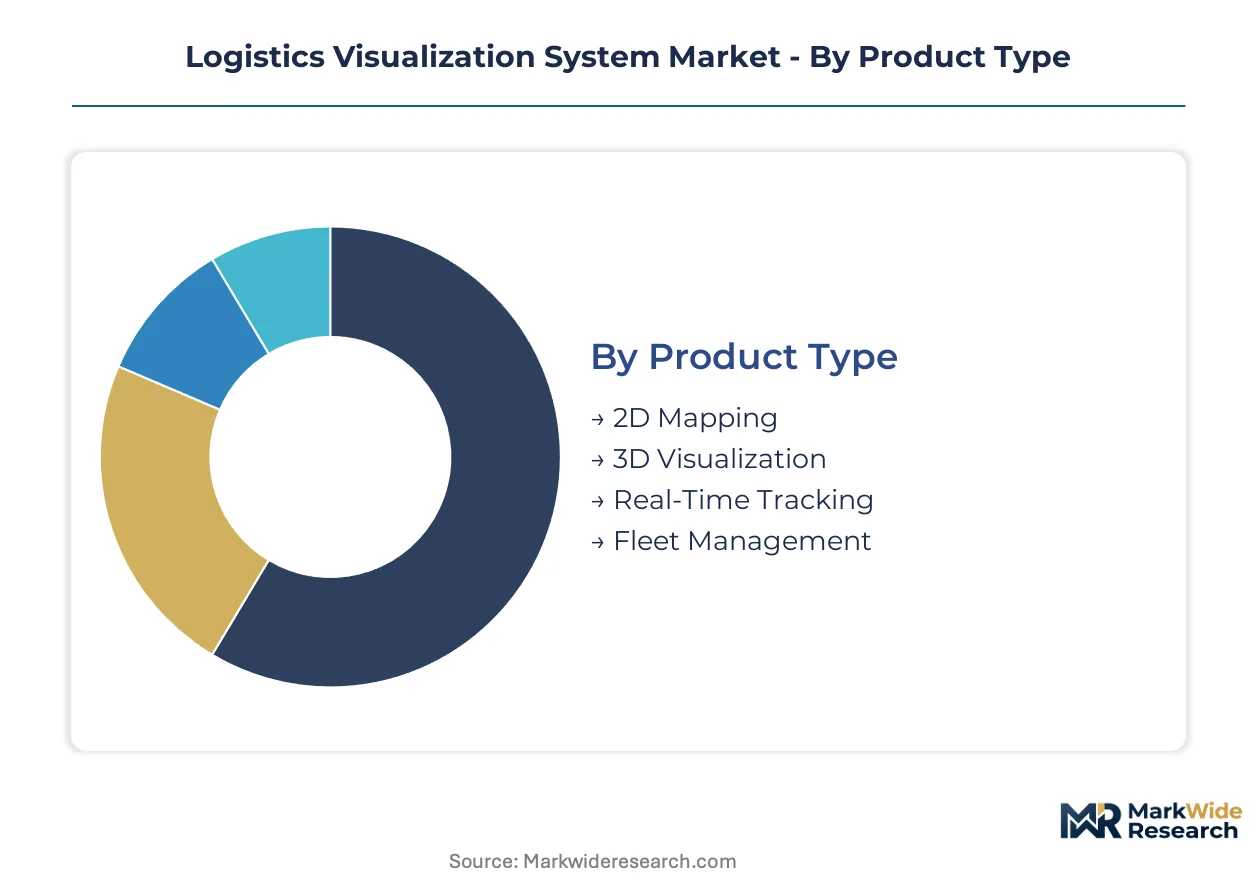
Logistics visualization systems fragment across technical architecture, connectivity layers, operational domains, and infrastructure models. Each segmentation axis carries distinct margin profiles and buyer procurement behaviors that shape vendor competitive positioning.
Product Type:
Standardization dominates basic mapping layers while premium functionality demands deep customization for operational integration.
- Real-Time Tracking:Sub-minute telemetry refresh rates synchronize GPS coordinates, sensor states, and predictive ETA calculations into unified dispatcher dashboards. Pharmaceutical cold chain operators in Germany and the Netherlands pay premium subscription multiples for this capability due to EU Good Distribution Practice thermal logging mandates and time-definite contract penalty structures.
- 3D Visualization:Geospatial rendering engines model multimodal freight corridors with elevation data, warehouse interiors, and drone flight paths. Hamburg-Rotterdam corridor operators deploy these layers for barge-rail-truck interchange optimization where vertical clearance and berth availability constrain routing decisions.
- 2D Mapping:Static cartographic baselines serve cost-sensitive mid-tier 3PLs with limited sensor infrastructure.
- Fleet Management:Driver behavior analytics and maintenance scheduling modules integrate with telematics hardware.
Most installed capacity flows through Real-Time Tracking. Expansion is steepest in 3D Visualization.
Technology:
Edge-to-cloud connectivity density determines subscription renewal economics and upsell velocity across this layer.
- IoT Solutions:Gateway architectures aggregate RFID tag states, temperature sensors, and shock monitors into unified telemetry streams. Edge-device connectivity density correlates directly with platform stickiness and expansion revenue in pharmaceutical logistics networks subject to continuous environmental monitoring requirements.
- Cloud Computing:Elastic render farms replace capital-intensive server deployments for freight operators abandoning on-premises infrastructure. European manufacturing hubs favor consumption-based pricing models that align visualization costs with shipment volume volatility.
- GPS Tracking:Satellite positioning remains the foundational location layer for over-the-road visibility.
- RFID:Yard management and warehouse gate automation rely on passive and active tag infrastructures.
Revenue concentrates in IoT Solutions. Cloud Computing is climbing the fastest as migration accelerates.
End User:
Procurement sophistication varies sharply between asset-heavy operators and orchestration-focused intermediaries.
- Supply Chain Management:Control tower platforms synthesize multi-enterprise visibility across tiered supplier networks. Customs brokers and freight forwarders in the Hamburg-Rotterdam corridor deploy these systems to manage documentary compliance and exception handling across modal handoffs.
- Transportation:Fleet operators and 3PLs prioritize dispatch optimization and driver communication tools.
- Retail:Distribution network operators focus on last-mile ETA accuracy and customer notification automation.
- Manufacturing:Plant logistics teams emphasize inbound material synchronization with production schedules.
Supply Chain Management commands the highest per-seat pricing. Transportation is gaining share fastest among mid-market buyers.
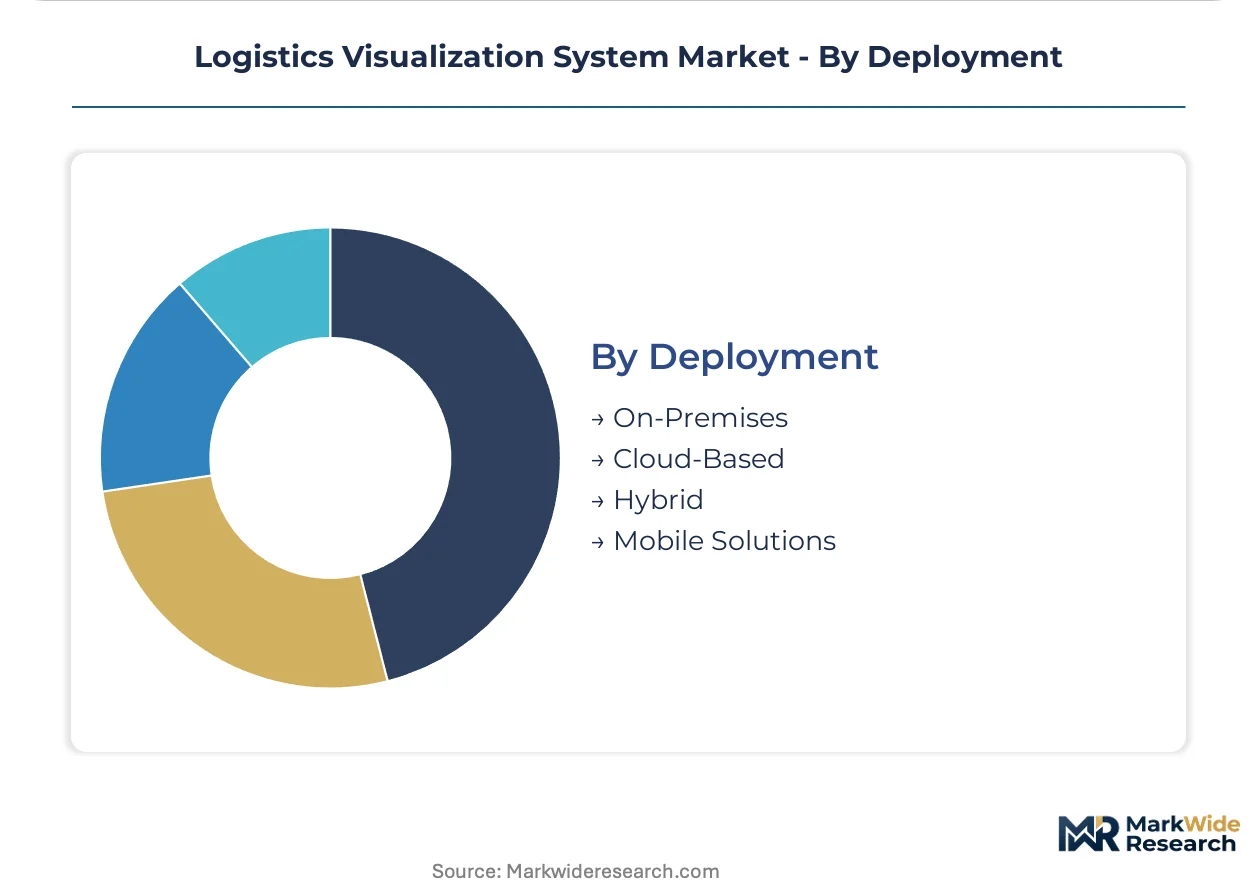
Deployment:
Infrastructure ownership preferences split between regulatory compliance requirements and capital efficiency priorities.
- Cloud-Based:SaaS delivery eliminates server procurement cycles and enables pilot-to-scale conversions compressed under six months. Mid-sized Dutch temperature-sensitive freight specialists bypass lengthy RFP processes for elastic consumption models where operational downtime costs exceed subscription values.
- Hybrid:Sensitive telemetry processing remains on-premises while rendering and analytics migrate to cloud instances. Data sovereignty fragmentation across EU member states drives this architecture for cross-border operators facing divergent national storage mandates.
- On-Premises:Legacy ERP integration depth anchors established manufacturing shippers with high switching friction.
- Mobile Solutions:Driver-facing applications and field dispatcher tools extend core platform functionality to edge users.
Cloud-Based carries the dominant installed base. Hybrid is expanding most quickly due to regulatory complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Hamburg-Rotterdam freight corridor anchors European logistics visualization demand. Pharmaceutical cold chain operators along this axis drive premium adoption for temperature-monitoring dashboards. Cross-border multimodal integration shapes procurement priorities across the continent.
Germany
Biologic pharmaceutical shipments through Hamburg and Frankfurt airports mandate real-time thermal logging dashboards under EU Good Distribution Practice. The EU AI Act forces automated routing vendors to embed explainability layers into visualization platforms. Bavarian automotive manufacturers deploy control towers synchronizing inbound component flows with assembly schedules.
Netherlands
Rotterdam port operators consolidate barge-rail-truck telemetry into unified visibility platforms for modal interchange optimization. The country's national pharmaceutical regulator enforces continuous environmental monitoring for vaccine distribution networks. Dutch temperature-sensitive freight specialists compress vendor evaluation cycles from eighteen months to under six through pilot-to-scale SaaS conversions.
United States
The FAA and DOT jointly shape commercial drone integration standards that expand last-mile visualization requirements for aerial freight corridors. Pharmaceutical distributors in Memphis and Louisville deploy sensor-dense tracking for time-definite contract penalty avoidance. Midwest manufacturing hubs anchor enterprise-grade control tower investments through SAP ERP integration depth.
China
Yangtze River Delta logistics operators migrate from capital-intensive server farms to elastic cloud compute consumption for rendering architectures. The national standardization administration drives IoT gateway density requirements through smart logistics infrastructure mandates. Shanghai port authorities consolidate multimodal visibility across rail, barge, and trucking networks.
India
Maharashtra pharmaceutical exporters deploy temperature-monitoring dashboards to meet EU import compliance requirements. The national pharmaceutical regulator aligns with international cold chain standards for biologic shipments. Mumbai-Pune corridor operators invest in sub-minute telemetry refresh rates to synchronize with European contract penalty structures.
Logistics Visualization System Market Competitive Environment
Global majors compete with regional champions across ERP integration depth and cloud-native rendering capabilities. The vendor base stratifies between enterprise control tower platforms and specialized warehouse-centric modules. Three archetypes dominate: ERP-anchored suites, database-optimized telemetry engines, and warehouse-focused visualization specialists. Competitive moves concentrate on strategic partnerships with IoT gateway manufacturers and compliance certification acceleration for EU AI Act mandates.
Within the ERP-anchored tier, SAP and Oracle occupy positions defined by integration depth across manufacturing hubs. Manhattan Associates exemplifies the warehouse-centric specialist archetype through retail distribution network penetration. The Descartes Systems Group sits within the logistics service provider-focused segment, anchoring customs brokerage and freight forwarding visibility. These three companies represent distinct competitive vectors rather than direct substitution threats.
| Leading Market Players |
|---|
| SAP |
| Oracle |
| IBM |
| Microsoft |
| Manhattan Associates |
| The Descartes Systems Group |
| Körber AG |
| C.H. Robinson |
| Blue Yonder |
| Others |
Value Chain & Pricing Dynamics
Cloud compute spot pricing indices cascade through logistics visualization supply chains, compressing SaaS subscription tiers as hyperscaler cost volatility feeds into vendor margin structures. European pharmaceutical operators absorb premium pricing for EU AI Act-compliant audit-trail modules while mid-tier 3PLs face downward pressure on standard-tier subscriptions.
Pricing Analysis
Input-cost pass-through from IoT gateway hardware and elastic cloud render farms shapes subscription economics across vendor tiers. Three-tier pricing structure across premium, standard, and economy levels separates EU AI Act-certified platforms with embedded explainability layers from basic 2D mapping modules. Price differentiation hinges on sensor density thresholds and real-time refresh rate guarantees. Cost compression in the standard tier intensifies because mid-sized Dutch freight operators compress evaluation cycles and demand pilot-to-scale conversions. Small 3PLs with limited telemetry infrastructure exhibit highest price sensitivity; cold chain pharmaceutical distributors face lowest sensitivity due to contract penalty avoidance value.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based GPU foundry capacity for geospatial rendering engines and Chinese IoT gateway manufacturing for edge-device density requirements. Component sourcing draws from South Korean memory modules and German industrial sensor assemblies. Supply chain risk centers on semiconductor lithography equipment export restrictions affecting render-farm scalability. Distribution runs through direct enterprise sales for SAP and Oracle control tower integrations, with channel partners penetrating mid-market 3PL segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as buyer procurement shifts toward premium-tier platforms with embedded compliance certification and sub-minute telemetry guarantees.
For Market Incumbents: Anchor defensive positioning through backward integration into IoT gateway manufacturing to secure sensor density economics against emerging cloud-native challengers. Deepen ERP integration moats with manufacturing shippers in German automotive hubs. Prioritize EU AI Act certification acceleration to capture mandatory upgrade cycles before compliance deadlines force vendor switches. For New Entrants and Emerging Players: Mid-sized temperature-sensitive 3PLs in the Netherlands present the most penetrable buyer archetype, bypassing eighteen-month RFP timelines for six-month pilot conversions. Drone corridor visualization modules for US FAA aerial freight standards represent unclaimed white space. Pursue channel partnerships with IoT hardware distributors to accelerate SaaS landing velocity. For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native rendering specialists possessing GIS-analytics hybrid talent pipelines and EU regulatory certification momentum. Long-term viability favors platforms bridging warehouse digital twins with over-the-road freight layers. Watch Hamburg-Rotterdam corridor operator consolidation patterns as the inflection signal for multimodal control tower demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Embedded explainability layers capture mandatory upgrade spend from pharmaceutical logistics operators. |
| IoT Gateway Manufacturing Integration | Backward control over sensor density economics defends margin structure against cloud-native entrants. |
| Drone Corridor Visualization Development | US FAA aerial freight standards create first-mover positioning in unmanned last-mile tracking. |
| Warehouse Digital Twin Convergence | Unified storage-transport capital allocation decisions deepen platform stickiness with retail distributors. |
| Pilot-to-Scale SaaS Channel Expansion | Six-month conversion cycles with Dutch 3PLs bypass incumbent RFP lock-in advantages. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with logistics control tower directors, IoT platform engineers, pharmaceutical supply chain managers, and customs brokerage operators with secondary validation. SEC filings from SAP and Oracle, EU regulatory documentation from EMA and EU AI Act implementation guidance, and customs trade data on IoT gateway imports anchored supply-side sizing. Bottom-up telemetry platform deployment counts triangulated against top-down enterprise software spending estimates.
Segment-weighting approaches distributed value across cloud-based, hybrid, and on-premises deployment models; real-time tracking, 3D visualization, 2D mapping, and fleet management product tiers; and IoT solutions, cloud computing, GPS tracking, and RFID technology layers. CAGRs derived from elasticity modeling of sensor density versus subscription renewal correlations, with cold chain pharmaceutical compliance mandates and FAA drone integration timelines as industry-specific trajectory inputs across the projection horizon.
Underlying measurement precision varies by segment; cloud-based deployment and real-time tracking carry tighter precision than legacy on-premises stacks due to disclosed SaaS metrics. Forecasts reflect documented assumptions on regulatory ratification timelines and hyperscaler pricing stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
UAE Contract Logistics Market
Logistics and Shipping
Global Automated Container Terminal Market
Logistics and Shipping
Tanker Shipping Market
Logistics and Shipping
Ukraine Freight and Logistics Market
Logistics and Shipping
Control Towers Market
Logistics and Shipping
Delivery Tracking Platform Market
Logistics and Shipping
US Cross-Border Road Freight Transport Market
Logistics and Shipping
Cross-Border Logistics Services Market
Logistics and Shipping
Flat Rack Containers Market
Logistics and Shipping
United States FTL Freight Brokerage Market
Logistics and Shipping
Europe Domestic Courier Market
Logistics and Shipping
Cargo Shipping Market
Logistics and Shipping
Germany Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
United Kingdom Cold Chain Logistics Market
Logistics and Shipping
Thailand E-Commerce Logistics Market
Logistics and Shipping
South America Freight and Logistics Market