
 Freight and Logistics Market | 2026-2036
Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Freight and Logistics Market Intelligence
The integration of Internet of Things (IoT) sensors with real-time tracking platforms is reshaping visibility and efficiency across supply chains. DHL Group leverages its extensive global network to provide integrated express and logistics services for time-sensitive shipments. Kuehne + Nagel specializes in complex sea freight and contract logistics, particularly for industrial and automotive clients. C.H. Robinson differentiates through its technology-driven, asset-light freight brokerage model connecting a vast network of shippers and carriers.
Freight and logistics encompasses the planning, execution, and management of the physical movement and storage of goods from origin to consumption. This process involves coordinating multiple modes of transport and managing inventory levels through specific stock keeping units (SKUs). Road Freight dominates volume due to its critical role in last-mile delivery, while Air Freight commands premium pricing for speed-sensitive cargo. The Third-Party Logistics (3PL) service type is expanding as manufacturing and consumer goods companies increasingly outsource complex supply chain functions.
Regulatory frameworks such as the US FMCSA's hours-of-service rules and the EU's Mobility Package directly influence carrier operations and costs. China's national standards and dual carbon goals are accelerating investment in electric vehicle fleets and sustainable logistics infrastructure. Navigating these divergent compliance landscapes while managing fuel price volatility remains a central strategic challenge for all logistics providers.
Market Dynamics
The freight and logistics market is shaped by the fundamental tension between the drive for globalized, hyper-efficient supply chains and the friction of fragmented, divergent national regulatory systems. This dynamic forces providers to balance investments in universal technologies like AI against the need for localized compliance expertise.
Growth Catalysts
- E-Commerce Expansion:The sustained growth of online retail, particularly cross-border e-commerce, directly fuels demand for parcel delivery, last-mile services, and sophisticated fulfillment and returns logistics.
- Pharmaceutical Cold Chain:Stringent requirements for temperature-controlled transport of biologics, vaccines, and other sensitive medical products create a high-value niche demanding specialized equipment, monitoring, and validation services.
- Manufacturing Nearshoring:A shift in global supply chains, with companies moving production to Mexico and Vietnam to serve regional markets, generates new, concentrated freight corridors and demand for cross-border logistics.
Market Restraints
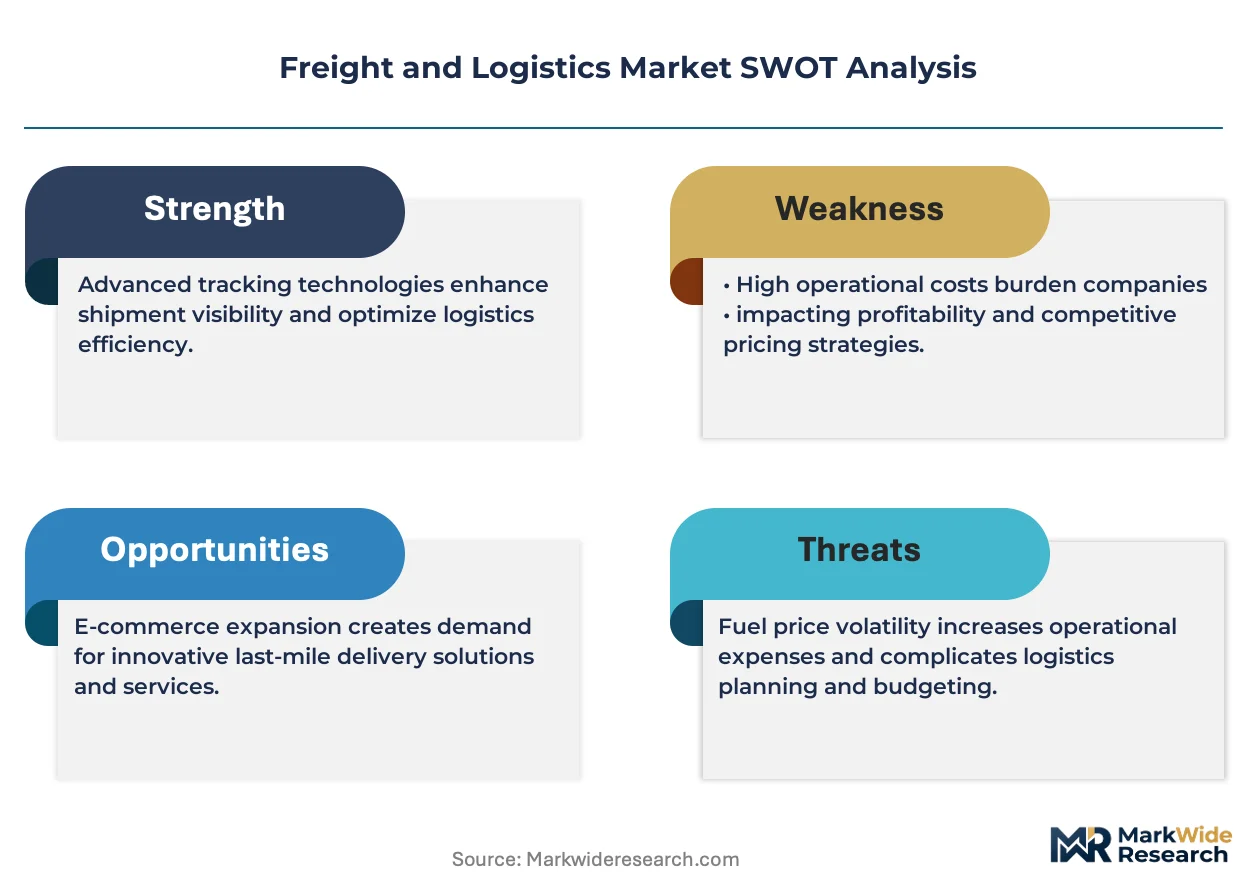
- Fuel Price Volatility:Diesel and jet fuel prices represent a significant and unpredictable operating cost, directly impacting carrier profitability and creating pricing instability for shippers across road, air, and sea freight modes.
- Infrastructure Bottlenecks:Congestion at major ports, aging rail networks, and inadequate road infrastructure in key production and consumption regions limit capacity, increase transit times, and add systemic costs.
- Divergent Regulations:Conflicting rules such as the US FMCSA's hours-of-service mandates and the EU's Mobility Package create complex compliance burdens for international carriers, increasing administrative overhead and operational constraints.
Strategic Opportunities
- Sustainable Logistics:Growing pressure from regulators, such as through China's dual carbon goals, and corporate ESG initiatives creates a market for green logistics solutions, including electric vehicle fleets, alternative fuels, and optimized, low-emission routing.
- Digital Freight Brokerage:Technology platforms that connect shippers directly with smaller carriers and owner-operators offer an opportunity to disintermediate traditional brokerage models, increasing transparency and efficiency in the highly fragmented road freight market.
- Reverse Logistics Services:The rise of the circular economy and e-commerce returns presents an opportunity to develop specialized service lines for managing, refurbishing, and recycling returned goods, turning a cost center into a value stream.
Industry Challenges
- Driver and Labor Shortages:A chronic, global shortage of qualified truck drivers, warehouse workers, and logistics specialists constrains capacity, drives up labor costs, and limits the ability of carriers to expand their operations.
- Cybersecurity Threats:The increasing digitization of supply chains, with connected sensors and platforms, exposes logistics operations to greater risks of ransomware attacks, data breaches, and operational disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freight and Logistics Market |
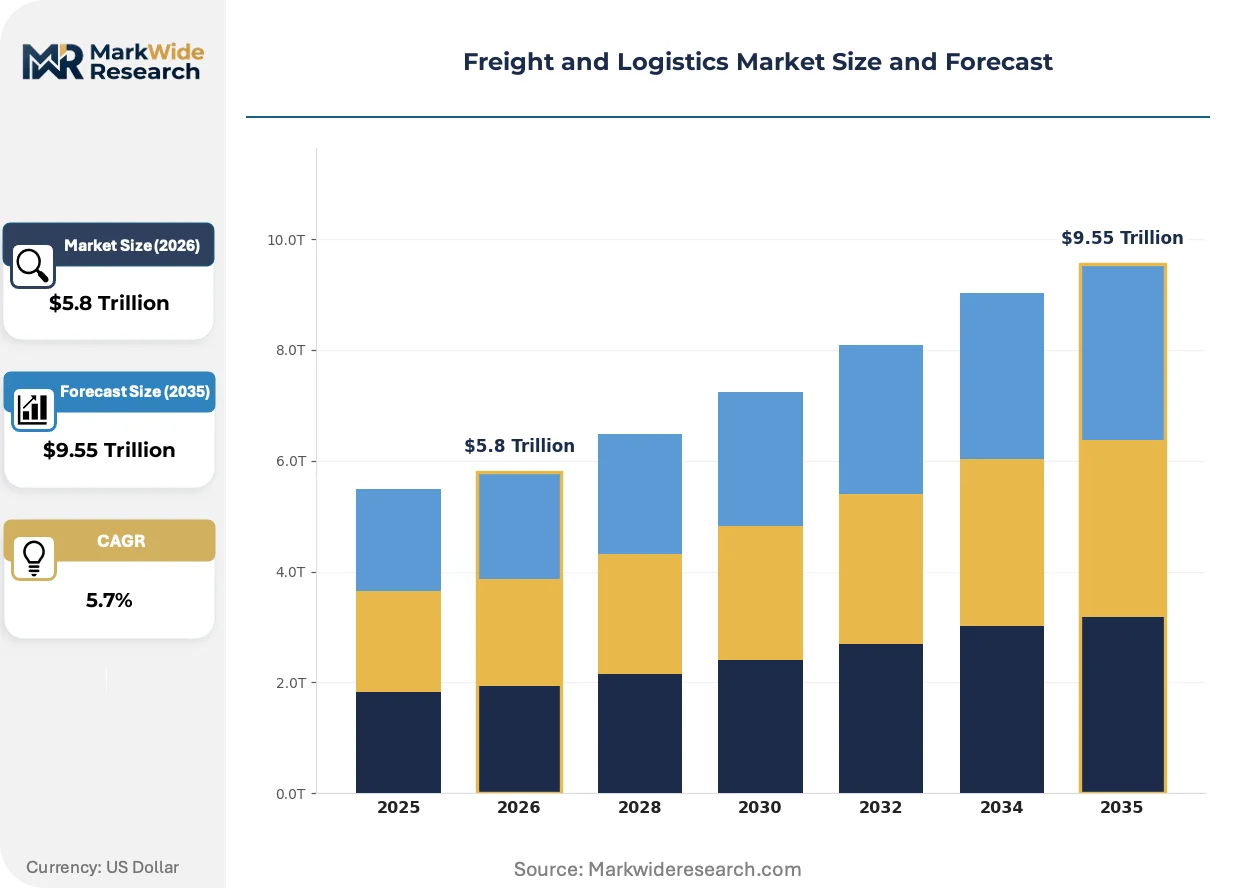
| Market Size in 2026 | $5.8 Trillion |
| Market Size in 2035 | $9.55 Trillion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Third-Party Logistics, Freight Forwarding, Warehousing, Distribution Management, Courier Services, Inventory Management Mode of Transport: Road Freight, Rail Freight, Sea Freight, Air Freight, Pipeline Transport End User Industry: Manufacturing, Consumer Goods, Electronics, Pharmaceuticals, Agriculture Deployment Type: Cloud-Based Solutions, On-Premise Software, Hybrid Platforms, Mobile Applications |
| Companies Covered | Kuehne + Nagel, DHL Group, DSV, DB Schenker, A.P. Moller - Maersk, C.H. Robinson, CMA CGM Group, Sinotrans, FedEx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freight and Logistics Market Strategic Shifts & Innovations
The competitive landscape is defined by a dual focus on digitalization for operational efficiency and sustainability for regulatory and brand alignment. Technology is not just an enabler but a core differentiator, while environmental performance is becoming a non-negotiable aspect of service delivery.
Digital twin technology is creating virtual models of physical supply chains, including warehouses, transport networks, and inventory flows. Shippers and 3PLs use these simulations to test network designs, predict disruptions, and optimize inventory placement without physical risk. This technology is hybridizing strategic planning with real-time operational control, moving beyond static analysis to dynamic, continuous optimization.
The European Union's Carbon Border Adjustment Mechanism (CBAM) is a significant regulatory development impacting global trade flows. It effectively places a price on the carbon emitted during the production of goods imported into the EU, requiring meticulous emissions tracking throughout the supply chain. This directly affects logistics providers handling goods for sectors like steel, aluminum, and cement, forcing investment in carbon accounting capabilities.
A notable behavioral shift is the unbundling of logistics services, allowing shippers to procure specific functions from different specialist providers. Instead of contracting with a single 3PL for an end-to-end solution, companies now often use a digital freight broker for transport, a separate firm for warehousing, and another for customs clearance. This trend is most prominent in the consumer goods and retail verticals, where flexibility is prioritized over single-vendor integration.
Freight and Logistics Market Segmentation
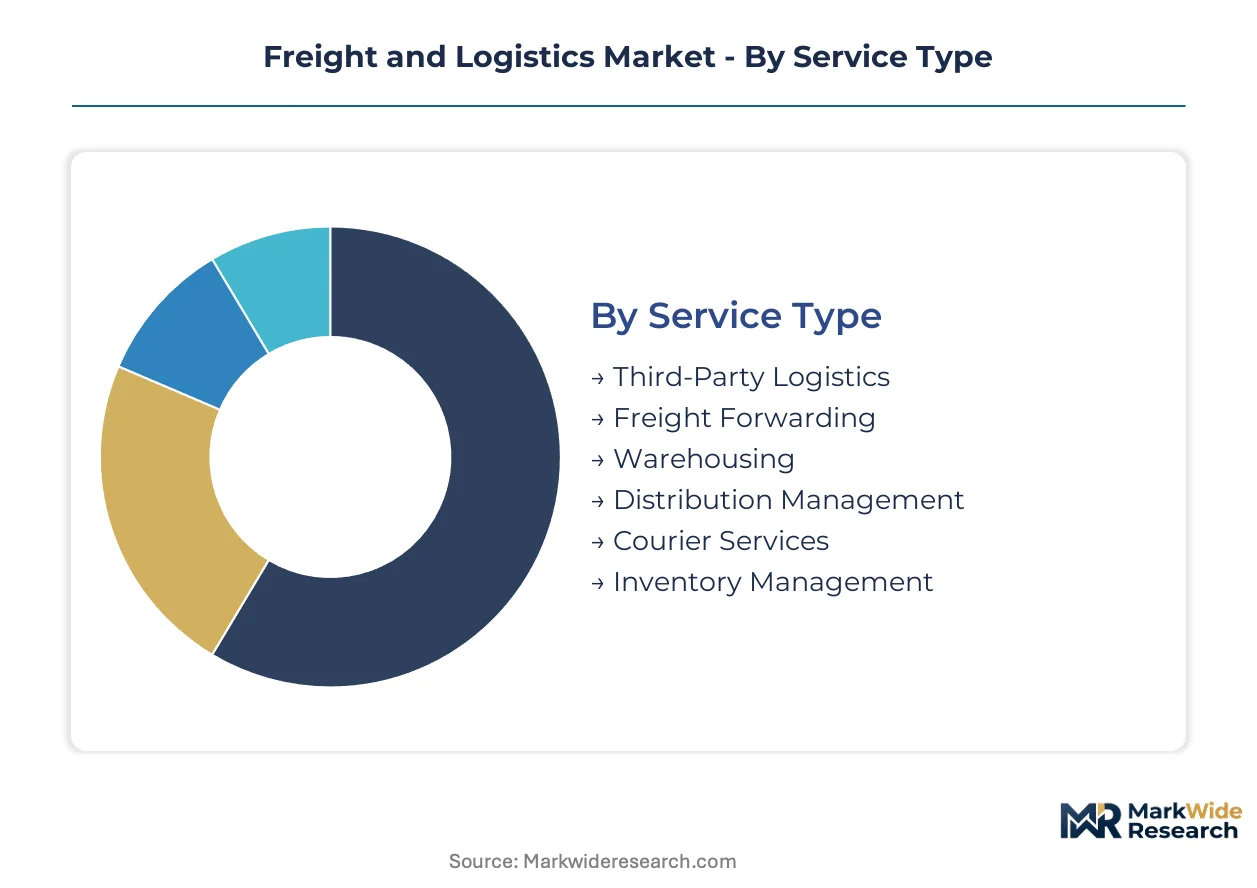
The freight and logistics market segmentation delineates distinct operational models and specialized services, enabling providers to tailor solutions for diverse client requirements. Analyzing these segments reveals how various industry participants position themselves to capture specific value pools across the supply chain.
Service Type:
The service type segmentation reveals a maturity spectrum, from established core functions to rapidly evolving outsourced models.
- Third-Party Logistics:These providers offer comprehensive, integrated supply chain solutions, including transportation, warehousing, and value-added services, allowing companies to outsource complex logistics operations. The expansion of manufacturing nearshoring in Mexico and Vietnam increases demand for these integrated services.
- Warehousing:This segment involves the storage of goods before distribution, encompassing inventory management, order fulfillment, and cross-docking operations within strategically located facilities. E-commerce expansion in China drives demand for sophisticated, automated warehousing solutions.
- Freight Forwarding:Freight forwarders act as intermediaries, organizing shipments for individuals or corporations to get goods from the manufacturer to the market, often involving multiple carriers and modes.
- Distribution Management:This service focuses on the efficient movement of goods from a central point to various end-points, optimizing routes and delivery schedules for retail and industrial clients.
- Courier Services:Specialized in rapid, door-to-door delivery of small parcels and documents, courier services are critical for time-sensitive e-commerce shipments and urgent business needs.
- Inventory Management:Providers in this segment optimize stock levels, track goods, and manage storage to minimize holding costs and ensure product availability for manufacturers and retailers.
Third-Party Logistics retains volume leadership; Inventory Management holds the steepest expansion curve.
Mode of Transport:
Modes of transport differentiate by speed, capacity, and cost efficiency, directly influencing supply chain design.
- Road Freight:This mode involves the transportation of goods via trucks and other road vehicles, offering unparalleled flexibility and critical last-mile delivery capabilities across urban and rural areas. Infrastructure bottlenecks in India frequently impact road freight efficiency.
- Air Freight:Air transport provides the fastest delivery option for high-value, time-sensitive, and perishable goods, commanding premium pricing due to its speed and global reach. Pharmaceutical cold chain requirements often necessitate air freight for biologics.
- Rail Freight:Rail transport offers a cost-effective solution for moving large volumes of bulk goods over long distances, particularly across continents like Europe and North America.
- Sea Freight:This mode handles the largest volume of international trade, utilizing container ships for cost-effective transportation of diverse cargo across global oceans.
- Pipeline Transport:Pipelines are specialized for the continuous movement of liquids and gases, such as oil, natural gas, and water, offering high efficiency and low operating costs for specific commodities.
Road Freight maintains its critical role in last-mile delivery; Pipeline Transport offers specialized, continuous flow for specific commodities.
End User Industry:
End-user industries present distinct demand characteristics, from high-volume standardized goods to specialized, regulated cargo.
- Manufacturing:This segment encompasses logistics services for raw materials, components, and finished goods supporting production processes across automotive, machinery, and electronics sectors. Manufacturing hubs in China and Mexico drive significant freight volumes.
- Pharmaceuticals:Logistics for the pharmaceutical industry demands stringent temperature control, cold chain integrity, and regulatory compliance for sensitive medications, vaccines, and medical devices. The EU's MDR regulations impact pharmaceutical logistics within Europe.
- Consumer Goods:This category includes logistics for a wide array of products, from food and beverages to apparel and household items, often requiring rapid turnaround and extensive distribution networks for retail.
- Electronics:Logistics for electronics involves handling high-value, often fragile components and finished products, requiring secure transport and specialized handling to prevent damage.
- Agriculture:This segment covers the transport and storage of agricultural products, including fresh produce, grains, and livestock, often requiring specialized equipment and temperature-controlled environments.
Manufacturing remains a foundational demand driver; Pharmaceuticals command premium services due to stringent regulatory needs.
Deployment Type:
Deployment types reflect the technological approaches adopted for managing logistics operations, impacting scalability and integration.
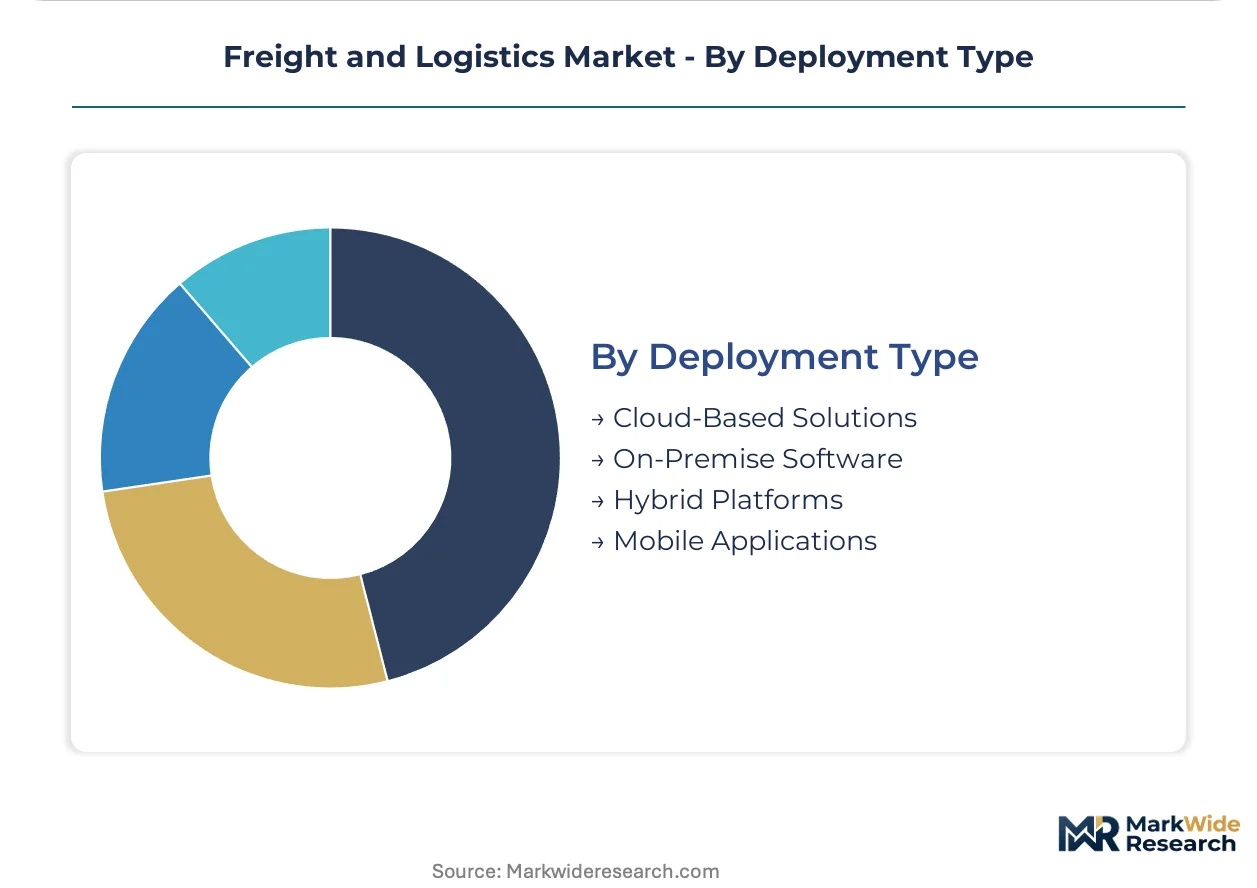
- Cloud-Based Solutions:These platforms host logistics software and data on remote servers, accessible via the internet, offering scalability, real-time analytics, and reduced infrastructure costs for global operations. AI-powered predictive analytics often utilize cloud infrastructure.
- Mobile Applications:Mobile apps provide on-the-go access to tracking, dispatch, and inventory management tools, enhancing operational flexibility for drivers, warehouse staff, and field agents. These improve efficiency for last-mile delivery services.
- On-Premise Software:This involves installing logistics management software directly on a company's own servers and infrastructure, offering greater control and customization for specific enterprise requirements.
- Hybrid Platforms:Hybrid models combine elements of both cloud-based and on-premise solutions, balancing data security and control with the flexibility and scalability of cloud services.
Cloud-Based Solutions are increasingly central to digital transformation; Mobile Applications enhance operational flexibility across diverse logistics functions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration significantly influences freight and logistics demand across various regions. Manufacturing and export hubs, alongside e-commerce growth centers, drive substantial freight volumes. These areas require specialized logistics solutions tailored to complex supply chain needs.
China
China's e-commerce expansion and manufacturing exports create immense demand for logistics services. The nation's dual carbon goals accelerate investment in sustainable logistics infrastructure and electric vehicle fleets. Major production zones like the Yangtze River Delta focus on smart warehousing and efficient distribution.
Mexico
Mexico's manufacturing nearshoring trend generates new freight corridors, particularly with the United States. The Mexican government's infrastructure projects aim to enhance connectivity and reduce border congestion. Automotive and electronics production in regions like Nuevo León require sophisticated cross-border logistics.
United States
The United States freight market is driven by vast domestic consumption and diversified industrial output. US FMCSA's hours-of-service rules directly influence carrier operations and costs for road freight. Major distribution centers around Chicago serve as critical hubs for national goods movement.
Germany
Germany's robust industrial base and central European location create strong demand for complex sea freight and contract logistics. The EU's Mobility Package directly impacts driver regulations and operational costs for German carriers. The Rhine-Ruhr metropolitan region serves as a major multimodal logistics gateway.
India
India's expanding consumer goods market and manufacturing initiatives fuel significant logistics requirements. Infrastructure bottlenecks, particularly in road freight, challenge efficient goods movement across the country. Industrial corridors like the Delhi-Mumbai Industrial Corridor are attracting new logistics investments.
Freight and Logistics Market Key Industry Players
Channel-controlling players compete with product-specialist players across the freight and logistics market. The market structure exhibits a blend of large, integrated global operators and numerous localized, niche providers, creating a fragmented yet interconnected ecosystem. Strategic archetypes include global network integrators, technology-driven freight brokers, and specialized contract logistics providers. Dominant competitive moves involve significant investments in digital platforms for optimization and strategic partnerships to expand geographic reach and service offerings.
Specialists in integrated solutions and complex logistics include DHL Group and Kuehne + Nagel, both representing global network integrators with extensive international reach and diverse service portfolios. C.H. Robinson exemplifies a technology-driven freight brokerage model, leveraging digital platforms to efficiently connect a vast network of shippers and carriers. These prominent firms sit within distinct operational archetypes, influencing efficiency and service delivery across the sector by catering to varying customer needs and logistical complexities, from express parcels to intricate supply chain management.
| Leading Market Players |
|---|
| Kuehne + Nagel |
| DHL Group |
| DSV |
| DB Schenker |
| A.P. Moller - Maersk |
| C.H. Robinson |
| CMA CGM Group |
| Sinotrans |
| FedEx |
| Others |
Cost & Logistics Intelligence
Fuel price volatility, a critical risk vector, determines both pricing tier spreads and supply chain shape across the freight and logistics market. This unpredictability mandates flexible pricing structures and diversified transport strategies for logistics providers.
Pricing Analysis
Cost-plus contract patterns with specific fuel surcharges indexed to global oil benchmarks define pricing in freight and logistics. Price differentiation stems from geographic delivery cost and the required service level, such as temperature control for pharmaceuticals. Pricing pressure stems from infrastructure bottlenecks and intense competition among carriers. E-commerce shippers exhibit high price sensitivity for standard parcel delivery, while pharmaceutical clients prioritize reliability and compliance over cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are increasingly common, supporting cash flow for carriers and optimizing working capital for shippers. Geographic supply concentration for manufacturing hubs sits in China, Mexico, and Vietnam, feeding vast export volumes. Dependencies on diesel and jet fuel represent significant input costs for all transport modes. Regulatory divergence, such as the EU's Mobility Package, creates a structural risk for cross-border operations. Distribution runs through complex multi-modal networks, culminating in localized last-mile delivery services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The freight and logistics market is in a cyclical recovery phase, driven by resurgent manufacturing output and sustained e-commerce expansion.
For Market Incumbents: Entrench core market positions by investing heavily in AI-powered predictive analytics for route optimization and network efficiency. Counter the threat from digital freight brokers by enhancing proprietary technology platforms and integrating IoT sensors for real-time tracking. Consolidate capacity in high-demand corridors, particularly for pharmaceutical cold chain logistics, to maintain service quality and regulatory compliance.
For New Entrants and Emerging Players: Build out specialized service lines focusing on sustainable logistics solutions, including electric vehicle fleets and alternative fuels, to meet growing ESG demands. Target the reverse logistics segment, particularly for consumer goods and electronics, which remains underpenetrated by comprehensive, value-added services. A technology-first go-to-market angle, offering transparency and efficiency through digital platforms, can attract smaller shippers and owner-operators.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors technology-enabled niche providers and regional specialists with strong compliance capabilities. Long-term viability rests on firms adept at navigating divergent regulatory landscapes and integrating advanced digital solutions. Acquire companies with proven expertise in green logistics or specialized cold chain services. The signal to watch is the adoption rate of digital twin technology across major logistics operations.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI-Powered Predictive Analytics | Optimizes route planning and inventory management, significantly reducing operational costs and transit times. |
| Expand Sustainable Logistics Offerings | Addresses regulatory pressures like China's dual carbon goals and corporate ESG mandates, attracting environmentally conscious clients. |
| Acquire Reverse Logistics Specialists | Captures value from the circular economy trend and e-commerce returns, turning a cost center into a new revenue stream. |
| Enhance Cold Chain Infrastructure | Meets stringent pharmaceutical industry requirements for temperature-controlled transport, securing high-value contracts. |
| Develop Digital Freight Brokerage Platforms | Increases transparency and efficiency in fragmented road freight markets, connecting shippers with a wider carrier network. |
Research Approach
Cross-validation between primary interviews and secondary data anchors the qualitative findings and quantitative forecasts within this study. The research team conducted discussions with logistics managers, freight forwarders, fleet operators, and supply chain directors. Secondary validation drew from customs data, International Energy Agency reports, and company financial filings, triangulating market dynamics. Both bottom-up and top-down approaches informed market sizing and segmentation analysis.
The calibration approach integrated historical market performance with future projections across the analysis window. Segmentation dimensions modeled included service type, mode of transport, end user industry, deployment type, and regional compliance frameworks. Compound Annual Growth Rates (CAGRs) were derived from a multi-factor regression analysis, incorporating e-commerce growth projections and manufacturing output forecasts. This framework ensures robust and consistent market estimations.
The forecast holds incumbent behavior within observed patterns; aggressive moves by global network integrators or technology-driven freight brokers would shift outcomes. Forecasts reflect assumptions concerning global trade stability and technological adoption rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Singapore Last Mile Delivery Market
Logistics and Shipping
Canada Project Logistics Market
Logistics and Shipping
Cold Chain Logistics Market
Logistics and Shipping
Netherlands Cold Chain Logistics Market
Logistics and Shipping
Netherlands Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Air Cargo Capacity and Allotment Marketplace Platforms Market
Logistics and Shipping
Switzerland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Ukraine Freight and Logistics Market
Logistics and Shipping
UAE Logistics Market
Logistics and Shipping
GCC Dangerous Goods Logistics Market
Logistics and Shipping
North America Shipping Agency Market
Logistics and Shipping
North America Shipping Supplies Market
Logistics and Shipping
Car Carrier Market
Logistics and Shipping
Poland Cold Chain Logistics Market
Logistics and Shipping
Sweden Freight and Logistics Market
Logistics and Shipping
Philippines Freight and Logistics Market