
 Europe FMCG Logistics Market | 2026-2036
Europe FMCG Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe FMCG Logistics Market Foresight
Recyclable corrugated packaging is broadening cost structures for FMCG shippers across Europe. DHL Group leverages its parcel network density to dominate last-mile coverage in German metropolitan corridors. DSV AS anchors cross-border consolidation through its European road freight platform. Kuehne + Nagel International AG specializes in temperature-controlled pharmaceutical-adjacent FMCG flows, extending its cold chain expertise into perishable grocery segments.
Europe FMCG logistics encompasses the planning, execution, and control of fast-moving consumer goods movement across warehousing, transport, and distribution nodes, typically operating on inventory turnover cycles measured in days rather than weeks to preserve product freshness and shelf-life viability. The sector serves manufacturers and retailers requiring synchronized replenishment of high-volume, low-margin goods across fragmented European consumption markets. Warehousing and transportation together constitute the core service backbone where margin pools concentrate, while cold chain solutions within the solution category are expanding fastest as fresh and frozen grocery e-commerce penetrates Southern and Eastern European markets. IoT-enabled tracking and AI-driven demand forecasting represent the technology layers where competitive differentiation is accelerating, though blockchain adoption remains nascent outside pilot programs with major supermarket chains.
The EU Green Deal and its accompanying F-Gas Regulation are compelling logistics operators to transition refrigerated fleets away from high-global-warming-potential coolants, while REACH compliance shapes packaging material specifications for cross-border FMCG shipments. Germany's KBA enforces commercial vehicle emissions standards that directly affect fleet renewal timelines for road-based distributors operating across the Rhine-Alpine corridor. Stakeholders must monitor how the EU AI Act will classify automated warehouse decision systems and whether this triggers additional compliance layers for AI-enabled inventory management platforms before scaling automation investments.
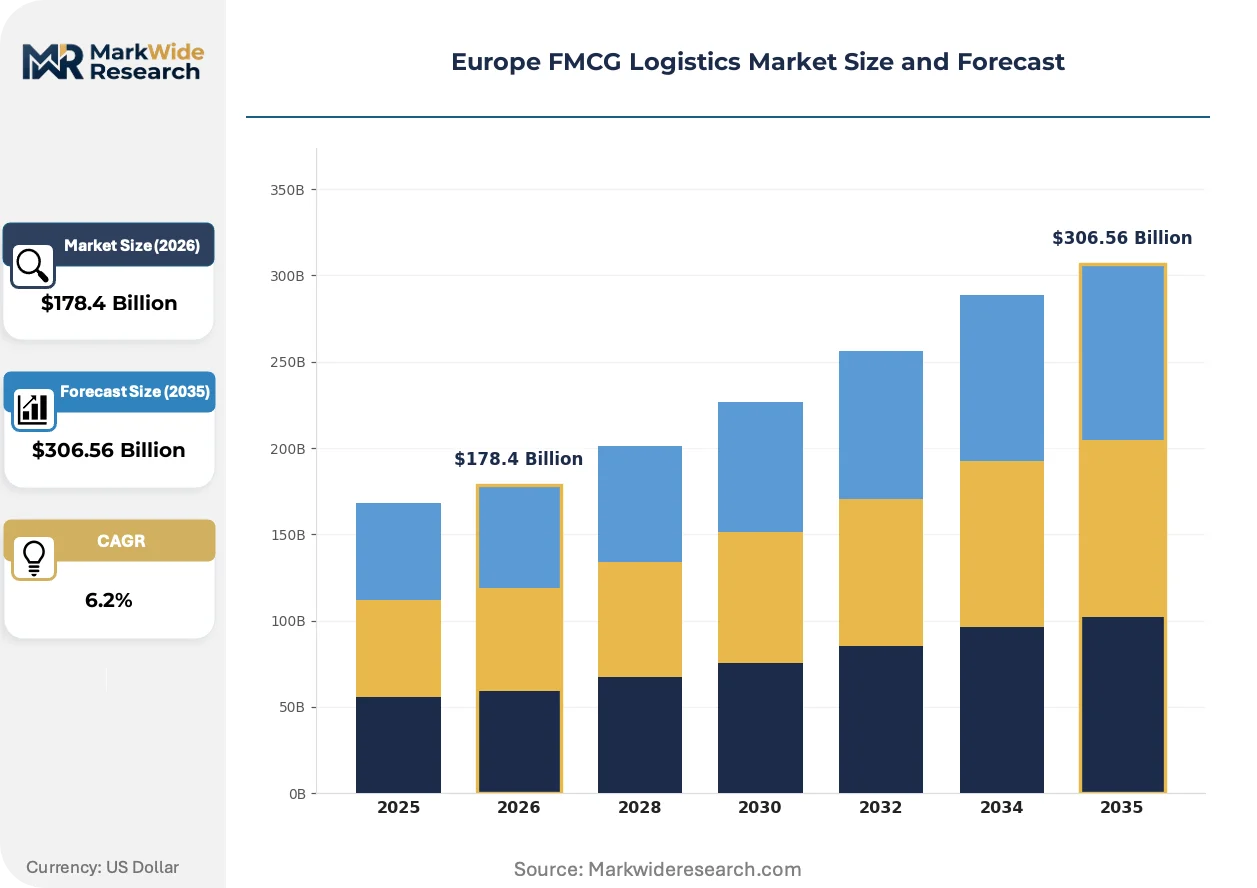
Market Dynamics
The EU Green Deal's fleet decarbonization mandates are forcing refrigerated transport operators to replace diesel-dependent cold chain assets before end-of-life cycles complete, compressing capital recovery timelines and reshaping competitive positioning among European road freight providers.
Growth Catalysts
- Fresh grocery e-commerce penetration:Southern and Eastern European markets are accelerating demand for temperature-controlled last-mile infrastructure as online food retail scales beyond metropolitan cores.
- REACH packaging compliance:Material specification rules for cross-border shipments are standardizing corrugated formats, reducing SKU complexity for multinational FMCG shippers.
- IoT-enabled tracking deployment:Real-time visibility platforms are cutting inventory buffer requirements by synchronizing warehouse replenishment with retail shelf depletion rates.
Market Restraints
- Refrigerant transition costs:The F-Gas Regulation is mandating coolant replacements that require complete fleet retrofits or premature vehicle retirement for operators with refrigerated assets.
- Hub concentration risk:Distribution density clusters in Germany, France, and the Netherlands create single-point vulnerability for pan-European replenishment networks.
- AI Act compliance uncertainty:Automated warehouse decision systems face pending classification thresholds that delay scaling investments in AI-driven inventory platforms.
Strategic Opportunities
- Poland and Romania corridor development:Underpenetrated Central European markets offer greenfield consolidation hubs for cross-border road freight platforms serving Eastern European retail expansion.
- Blockchain pilot scaling:Major supermarket chains are expanding traceability pilots into full-chain deployment for high-value perishable categories.
- CSRD reporting integration:Sustainability disclosure mandates are creating service differentiation for logistics operators with verified emissions tracking across Scope 3 boundaries.
Industry Challenges
- Cold chain technician scarcity:Refrigerated fleet maintenance requires specialized HVAC-R skills that outpace vocational training output in multiple European labor markets.
- Legacy WMS integration friction:AI-driven demand forecasting platforms face data architecture conflicts with decades-old warehouse management systems still operational in family-owned distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe FMCG Logistics Market |
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $306.56 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Warehousing, Transportation, Inventory Management, Distribution End User: Retailers, Wholesalers, E-commerce, Supermarkets Solution: Cold Chain, Last-Mile Delivery, Freight Forwarding, Packaging Technology: IoT, AI, Automation, Blockchain |
| Companies Covered | CEVA Logistics, DSV AS, DB Schenker, Hellmann Worldwide Logistics, FedEx Corp., DHL Group, DACHSER SE, C.H. Robinson Worldwide Inc., Kuehne + Nagel International AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe FMCG Logistics Market Shifts & Advancements
Digital infrastructure investments are compressing inventory turnover cycles from weeks to days across European FMCG networks. Three developments are altering how goods move from manufacturer to shelf.
Autonomous mobile robots in warehouse fulfillment are rewriting labor economics for high-velocity FMCG distribution. Retailers operating dense metropolitan fulfillment centers are deploying coordinated robot fleets for case-picking and pallet transport. The technology is rewriting facility design standards, shrinking aisle widths and eliminating mezzanine infrastructure that conventional forklifts require.
The EU AI Act's risk classification framework for automated decision systems is forcing warehouse operators to document algorithmic transparency before scaling predictive inventory platforms. Industrial consequence includes mandatory human-in-the-loop requirements for high-risk AI applications affecting stock allocation. Temperature-controlled pharmaceutical-adjacent FMCG flows face the steepest compliance preparation timelines given existing GxP documentation protocols.
Quick commerce platforms are fragmenting procurement authority away from centralized retail category managers toward hyperlocal fulfillment operators. Dark store networks in Paris, Berlin, and Amsterdam are displacing traditional wholesale replenishment relationships with direct manufacturer-to-microhub contracts. Grocery verticals with short shelf-life profiles exhibit the most visible demand rotation toward sub-15-minute delivery promises.
Europe FMCG Logistics Market Segmentation
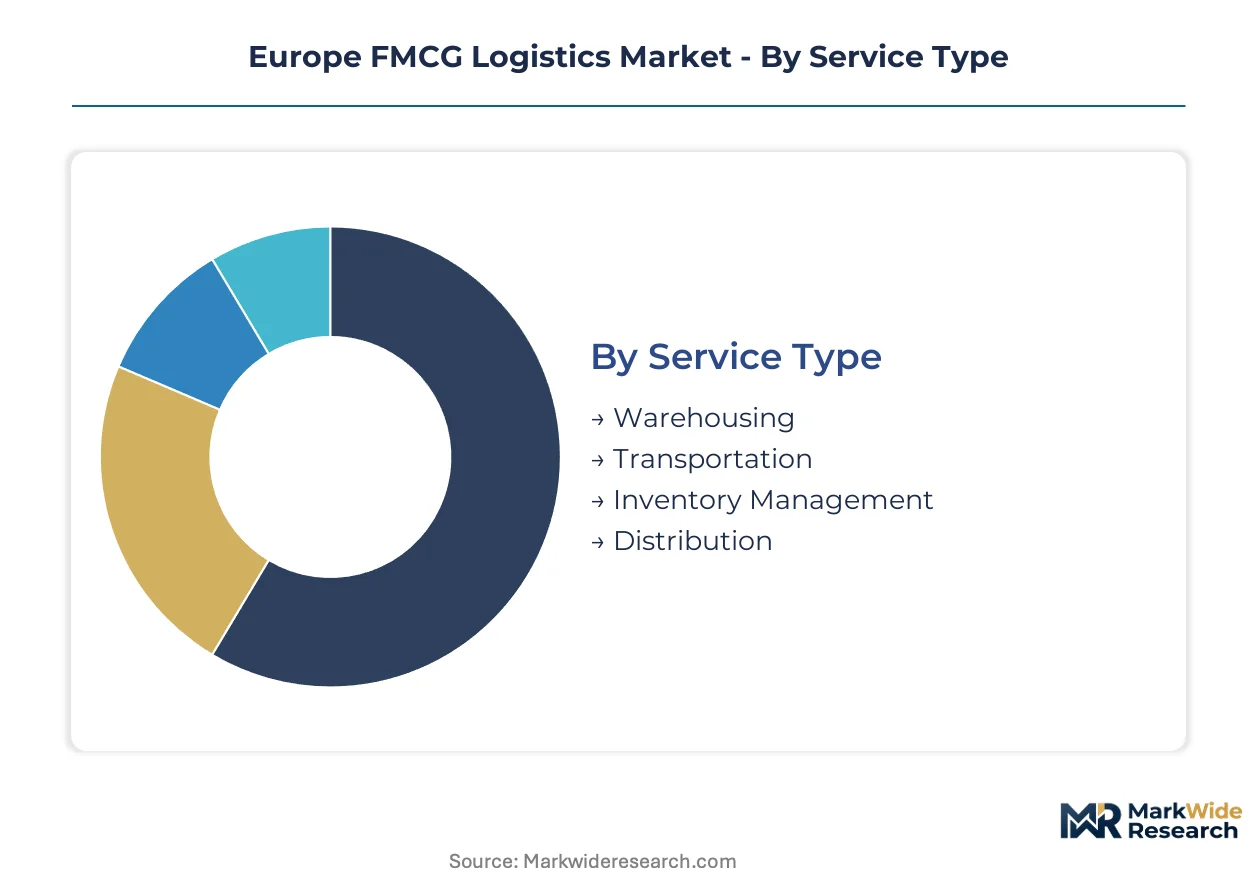
Segmentation in European FMCG logistics reveals where margin pools concentrate and which service layers command premium pricing. The market fragments across operational functions, customer archetypes, solution sophistication, and technology intensity.
Service Type:
Volume-heavy infrastructure services dominate revenue, while premium-margin layers concentrate in synchronized coordination functions.
- Warehousing:Multi-temperature storage facilities with automated racking systems handle ambient, chilled, and frozen FMCG stock-keeping units under one roof. Demand clusters in the Rhine-Alpine corridor where Germany, France, and Netherlands distribution density supports just-in-time replenishment cycles for pan-European retail networks.
- Transportation:Road freight platforms execute the physical movement of palletized and parcelized goods across national borders and last-mile drops. Cross-border consolidation through Central European hubs is gaining share fastest as shippers seek to bypass congested Western European freight corridors.
- Inventory Management:Demand forecasting and stock optimization services synchronize manufacturer output with retail shelf depletion. AI-driven replenishment algorithms are compressing safety stock requirements for fresh grocery categories with short shelf-life windows.
- Distribution:Final-mile orchestration connects regional hubs to retail storefronts and consumer doorsteps. Quick commerce platforms in Berlin, Paris, and Amsterdam are fragmenting traditional wholesale relationships with direct-to-microhub procurement models.
Today's leader: Warehousing. Tomorrow's challenger: Inventory Management.
End User:
Customer type determines service packaging complexity, with centralized procurement favoring integrated contracts and fragmented buyers demanding modular solutions.
- Retailers:National and regional chains require synchronized replenishment across hundreds of storefronts with strict on-shelf availability targets. German and French retail consolidators are driving standardization of corrugated packaging formats to simplify cross-border handling.
- Wholesalers:Intermediate distributors aggregate fragmented manufacturer output for redistribution to smaller retail and foodservice accounts. Margin pressure from direct-to-store manufacturer programs is compressing wholesaler logistics spend per case.
- E-commerce:Online grocery platforms demand temperature-controlled last-mile infrastructure with sub-24-hour delivery windows. Southern and Eastern European markets are accelerating cold chain investments as online food retail penetrates beyond metropolitan cores.
- Supermarkets:Large-format grocery operators balance centralized distribution center replenishment with direct store delivery for high-velocity perishables. Dark store networks in dense urban corridors are displacing traditional supermarket receiving docks with hyperlocal fulfillment nodes.
Supermarkets anchor current infrastructure utilization. E-commerce platforms are expanding the fastest.
Solution:
Solution sophistication correlates with regulatory intensity, with environmental and safety mandates driving premium service tiers.
- Cold Chain:Temperature-controlled transport and storage infrastructure preserves product integrity across frozen, chilled, and controlled ambient categories. The EU F-Gas Regulation is forcing fleet coolant transitions that require complete refrigerated vehicle retrofits or premature asset retirement.
- Last-Mile Delivery:Final-segment orchestration spans parcel networks, courier fleets, and gig-economy platforms for consumer-facing fulfillment. Quick commerce operators in Amsterdam and Paris are compressing delivery promises below 15 minutes for ultra-fresh grocery verticals.
- Freight Forwarding:Cross-border documentation and customs coordination services facilitate pan-European FMCG movement. Poland and Romania corridor development offers greenfield consolidation opportunities for road freight platforms serving Eastern European retail expansion.
- Packaging:Protective and promotional material specification ensures product integrity and regulatory compliance across transit. REACH material rules are standardizing corrugated formats and reducing SKU complexity for multinational FMCG shippers.
Cold Chain commands the steepest premium. Last-Mile Delivery is climbing the fastest.
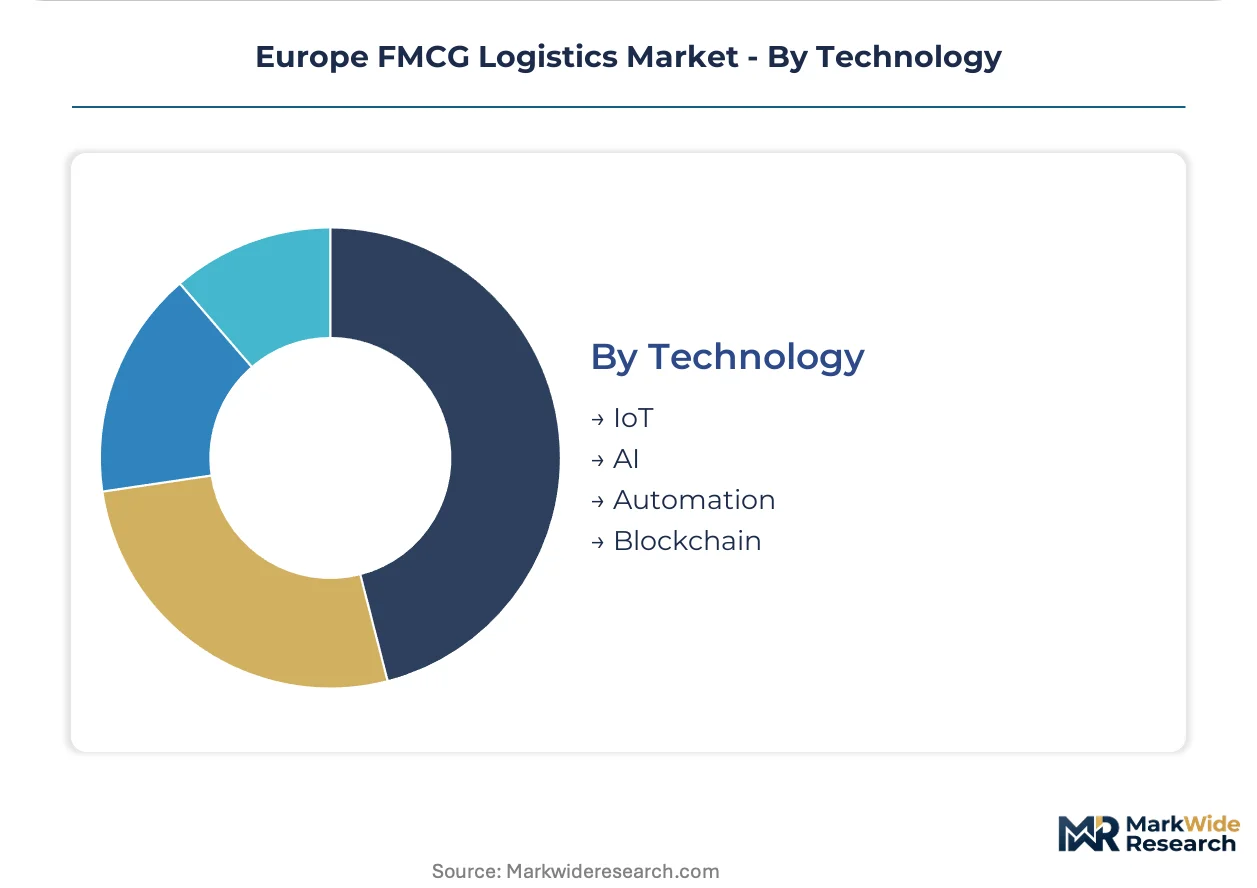
Technology:
Technology layers differentiate competitive positioning, with proven deployments separating from experimental pilots.
- IoT:Sensor networks provide real-time visibility into location, temperature, and shock events across transit lanes. Asset tracking deployments are cutting inventory buffer requirements by synchronizing warehouse replenishment with retail shelf depletion rates.
- AI:Predictive algorithms optimize routing, demand forecasting, and warehouse labor allocation. The EU AI Act's risk classification framework is forcing operators to document algorithmic transparency before scaling automated inventory platforms.
- Automation:Autonomous mobile robots and automated storage retrieval systems rewrite facility labor economics. Metropolitan fulfillment centers in German cities are deploying coordinated robot fleets that shrink aisle widths and eliminate mezzanine infrastructure.
- Blockchain:Distributed ledger pilots trace product provenance for high-value perishable categories. Major supermarket chains are expanding traceability pilots into full-chain deployment for premium fresh segments.
IoT anchors current competitive differentiation. AI faces the steepest compliance preparation timeline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine corridor anchors European FMCG logistics density, with distribution infrastructure clustering where Germany, France, and the Netherlands converge. This concentration shapes cross-border replenishment patterns for pan-European retail networks. National regulatory frameworks and urban logistics constraints create distinct operational environments across the region.
Germany
Automotive-adjacent logistics expertise and dense parcel networks drive FMCG distribution efficiency. KBA emissions standards compress fleet renewal timelines for refrigerated road freight operators. The Rhine-Ruhr metropolitan zone hosts multi-temperature consolidation hubs serving Central European retail replenishment cycles.
France
Quick commerce platforms in Paris are fragmenting traditional wholesale procurement with dark store micro-fulfillment models. ANSM pharmaceutical traceability requirements extend into adjacent FMCG categories with health claims. The Île-de-France logistics ring concentrates automated warehousing investment for fresh grocery e-commerce.
Netherlands
Rotterdam-Europoort maritime connectivity positions the country as Atlantic gateway for FMCG container flows. REACH compliance documentation for packaging materials streamlines cross-border shipment handling. Randstad distribution clusters specialize in synchronized replenishment for Benelux supermarket networks.
Poland
Central European location advantages attract greenfield consolidation hub development for Eastern European retail expansion. EU Cohesion Fund infrastructure investment upgrades road freight corridors toward Ukraine and Baltic states. Warsaw-Łódź logistics zone emerges as alternative to congested Western European freight routes.
Spain
Southern European fresh produce exports generate temperature-controlled freight demand toward Northern markets. National climate adaptation plans shape warehouse energy efficiency requirements for refrigerated storage. Barcelona-Valencia corridor development targets Mediterranean maritime connectivity for FMCG import flows.
Europe FMCG Logistics Market Competitive Landscape
Strategic partnerships dominate the current landscape as operators seek to defray cold chain infrastructure costs and expand last-mile coverage without asset-heavy balance sheets. The vendor base concentrates among integrated logistics groups with pan-European road networks and specialized temperature-controlled capabilities. Three archetypes prevail: parcel-network operators leveraging density for metropolitan delivery, freight forwarders anchoring cross-border consolidation, and cold chain specialists extending pharmaceutical expertise into perishable grocery. M&A activity and fleet decarbonization partnerships represent the dominant competitive vectors reshaping market structure.
Within the integrated logistics tier, DHL Group, DSV AS, and Kuehne + Nagel International AG exemplify divergent strategic positioning. DHL Group occupies a position anchored in parcel network density for German metropolitan corridors. DSV AS represents the cross-border consolidation archetype through its European road freight platform architecture. Kuehne + Nagel International AG sits within the temperature-controlled specialization vector, extending cold chain capabilities from pharmaceutical flows into perishable FMCG segments. These three entities collectively illustrate how scale, geographic coverage, and solution sophistication define competitive differentiation in European FMCG logistics.
| Leading Market Players |
|---|
| CEVA Logistics |
| DSV AS |
| DB Schenker |
| Hellmann Worldwide Logistics |
| FedEx Corp. |
| DHL Group |
| DACHSER SE |
| C.H. Robinson Worldwide Inc. |
| Kuehne + Nagel International AG |
| Others |
Supply & Pricing Matrix
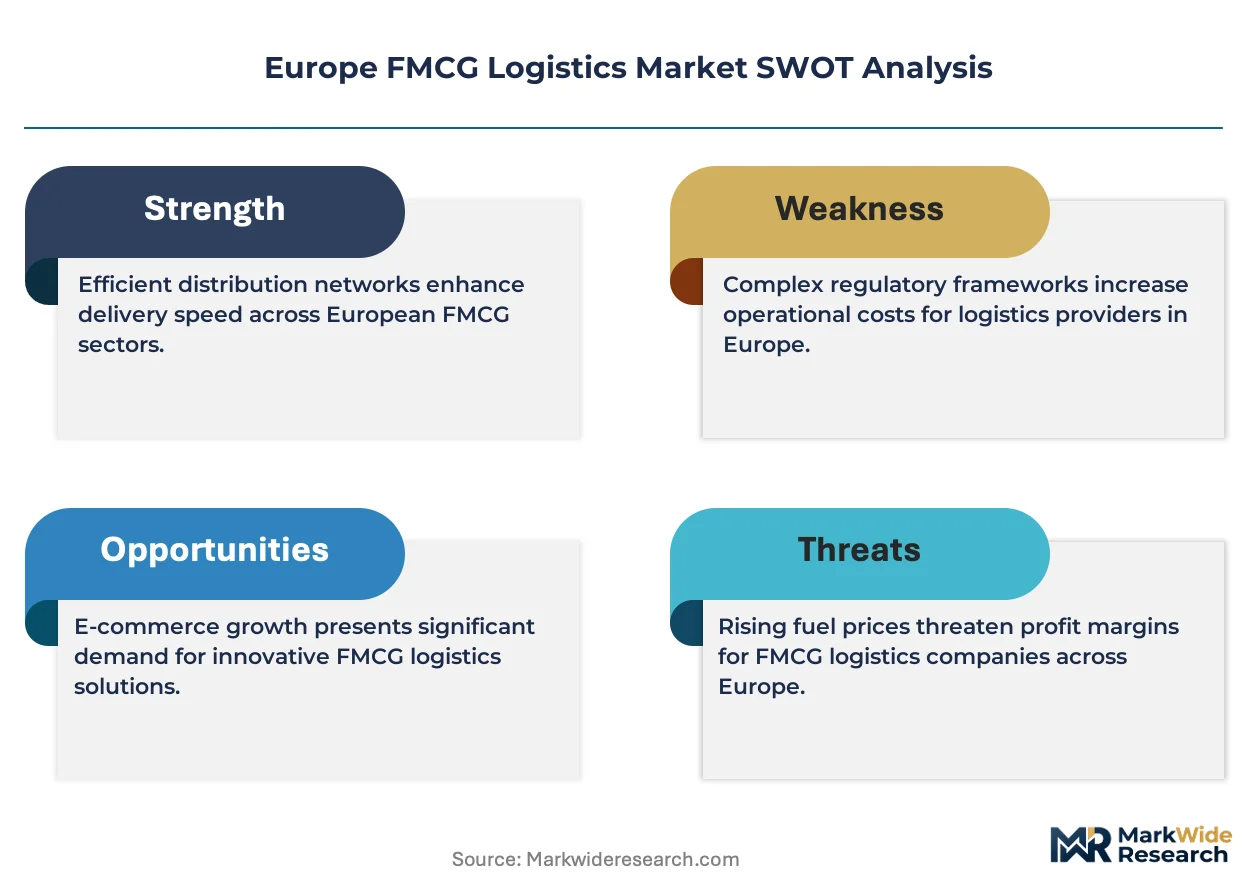
Cold chain certification tiers bifurcate service pricing across European FMCG logistics, with EU F-Gas Regulation-compliant refrigerated fleets commanding 15-25% premiums over legacy diesel-dependent assets while simultaneously forcing supply chain reconfiguration toward multi-temperature consolidation hubs in Germany, France, and the Netherlands.
Pricing Analysis
Input-cost pass-through from refrigerant transitions and fleet decarbonization mandates is compressing margins for non-compliant operators while elevating pricing power for certified cold chain providers. Three-tier pricing structure across premium temperature-controlled, standard ambient, and economy parcel tiers reflects divergent compliance burdens and asset utilization rates. Pricing pressure stems from quick commerce platforms demanding sub-15-minute delivery windows at wholesale-equivalent rates. National retail chains exhibit lowest price sensitivity due to synchronized replenishment requirements, while independent wholesalers face acute margin compression from direct-to-store manufacturer programs.
Supply Chain Analysis
Workforce availability constraints in Germany, Poland, and the Netherlands are elevating labor costs for refrigerated fleet maintenance and automated warehouse operations. Supply concentration draws from Rhine-Alpine corridor distribution clusters where multi-temperature facilities anchor pan-European replenishment networks. Raw material dependencies span aluminum for vehicle lightweighting, lithium-ion for electric fleet transitions, and corrugated formats standardized under REACH compliance. Single-source vulnerability concentrates in specialized HVAC-R technician pools across Central European labor markets. Distribution runs through hub-and-spoke architectures with cross-border consolidation platforms displacing point-to-point road freight.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in premium cold chain tiers where EU Green Deal compliance creates scarcity value, while automation investments compress labor intensity across high-velocity fulfillment networks.
For Market Incumbents: Deploy fleet decarbonization partnerships to defray refrigerated asset transition costs under F-Gas Regulation timelines. Incumbents should anchor cross-border consolidation capacity in Poland and Romania corridors before Eastern European retail density matures, while integrating IoT-enabled tracking platforms to reduce inventory buffer requirements for supermarket clients facing quick commerce displacement. For New Entrants and Emerging Players: Quick commerce dark store operators represent the most penetrable channel partner type for modular micro-fulfillment solutions. New entrants should target Southern and Eastern European temperature-controlled last-mile infrastructure where fresh grocery e-commerce penetration lags Western benchmarks, leveraging direct manufacturer-to-microhub procurement models that bypass legacy wholesale relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where family-owned distribution networks lack capital for AI-driven warehouse automation and REACH-compliant packaging standardization. Investors should prioritize mid-scale cold chain specialists with verified Scope 3 emissions tracking capabilities across the analysis window, monitoring CSRD disclosure adoption rates as the inflection signal for sustainability-linked logistics premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Partnership | EU Green Deal compliance accelerates refrigerated vehicle transitions beyond asset lifecycles. |
| Cross-Border Hub Development | Poland-Romania corridor investments bypass congested Western European freight routes. |
| AI Warehouse Automation | Autonomous mobile robots shrink aisle widths and eliminate mezzanine infrastructure in German fulfillment centers. |
| Blockchain Traceability Scaling | Supermarket chain pilots expand into full-chain deployment for premium perishable categories. |
| CSRD Reporting Integration | Verified Scope 3 emissions tracking creates service differentiation for sustainability-mandated retail procurement. |
Research Methodology
Direct dialogue with fleet operations directors, cold chain logistics managers, supermarket procurement leads, and EU regulatory affairs specialists grounded qualitative insights, supplemented by secondary validation from ECHA REACH documentation, EU Green Deal implementation reports, KBA emissions filings, and customs trade data for FMCG container flows. Bottom-up service provider capacity assessments and top-down retail consumption pattern analysis enabled triangulation across modeling approaches.
Segmentation outputs reflect dimensional modeling across service type, end-user archetype, solution sophistication tier, and technology deployment intensity throughout the forecast period. CAGRs derived from historical infrastructure investment trajectories, fleet renewal cycles under F-Gas Regulation mandates, and e-commerce penetration elasticity in fresh grocery verticals. Cold chain capacity expansion rates and automated warehouse deployment timelines served as primary forecast inputs.
Revisions become necessary when EU AI Act classification thresholds for automated inventory systems materialize ahead of anticipated timelines, or when refrigerant transition cost pass-through exceeds modeled absorption capacity. Material deviation in fleet decarbonization subsidy availability or Central European labor market tightness warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Total Logistics Market
Logistics and Shipping
North America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Tank Container Shipping Market
Logistics and Shipping
New York Freight and Logistics Market
Logistics and Shipping
Germany Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
North America Freight and Logistics Market
Logistics and Shipping
Australia Last Mile Delivery Market
Logistics and Shipping
Liquid Chemical Tanker Shipping Market
Logistics and Shipping
Czech Republic Third-Party Logistics Market
Logistics and Shipping
Government and Education Logistics Market
Logistics and Shipping
Singapore Chemical Logistics Market
Logistics and Shipping
Japan Cross-Border E-Commerce Logistics Market
Logistics and Shipping
Global Retail 3PL Market
Logistics and Shipping
Tanker Cargo Ship Market
Logistics and Shipping
GCC Warehousing and Distribution Logistics Market
Logistics and Shipping
Brazil 3PL Market