
 Mexico Containerized Shipping Market | 2026-2036
Mexico Containerized Shipping Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Containerized Shipping Market Insights
Buyer concentration among Mexican automotive and electronics manufacturers is shifting toward larger integrated importers that negotiate direct vessel allocations. Maersk leverages its Pacific terminal partnerships to secure dedicated berth windows at Manzanillo. Mediterranean Shipping Company anchors capacity on Asia-Mexico services through long-term slot agreements with Lazaro Cardenas operators. CMA CGM competes by specializing in reefer-heavy routes serving perishable exporters from Sinaloa and Jalisco.
Containerized shipping moves goods in standardized ISO containers, typically twenty-foot or forty-foot units, designed for intermodal transfer between vessel, rail, and truck without cargo handling. The system depends on stackable steel boxes with uniform corner castings and weather-sealed doors, enabling efficient unitization of manufactured goods, raw materials, and temperature-sensitive cargo across multimodal networks. Full Container Load services dominate trans-Pacific lanes where automotive and appliance manufacturers ship consolidated production inputs, while Less Than Container Load segments attract smaller retailers lacking volume for dedicated boxes. Reefer Services within ocean freight are expanding fastest as Mexican berry, avocado, and seafood exporters build cold-chain reliability for Asian markets.
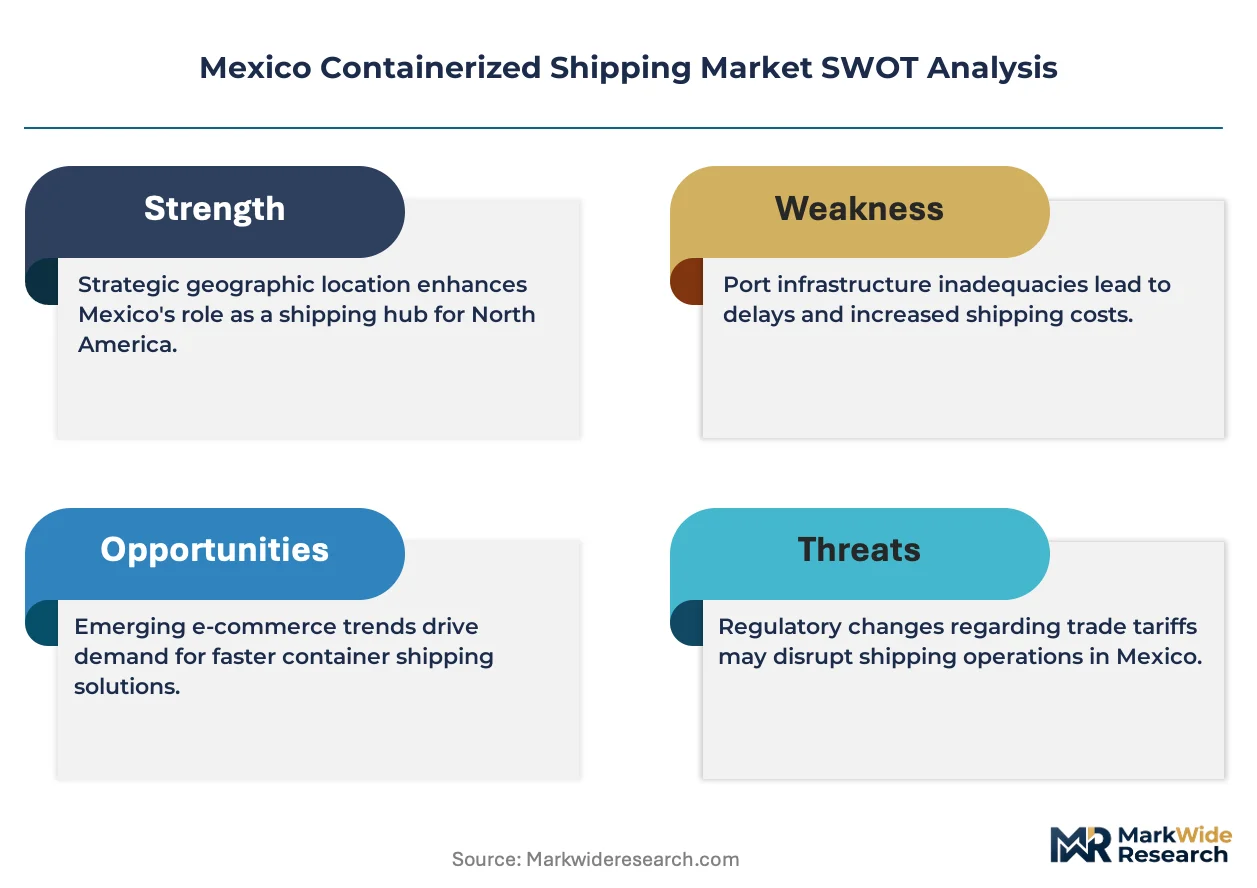
Mexico's Federal Customs Law and SAT tax administration protocols shape import documentation requirements, while port authority regulations under API administrations govern terminal access and dwell-time penalties. The International Maritime Organization's sulfur emission standards affect vessel fuel choices on Mexico's Pacific and Gulf coasts, pushing carriers toward scrubber installations or low-sulfur fuel procurement. Stakeholders must monitor how customs automation investments and emission compliance costs redistribute service economics between Pacific and Gulf port alternatives.
Market Dynamics
Automotive manufacturers in Baja California and Nuevo Leon are consolidating containerized import volumes, reshaping carrier allocation strategies across Pacific ports. This demand concentration is compressing negotiation leverage for smaller shippers while rewarding integrated importers with dedicated vessel access.
Growth Catalysts
- Federal Customs Law modernization:SAT tax administration protocols are automating documentation flows, reducing port clearance dwell times at Lazaro Cardenas and Manzanillo terminals.
- Precision component imports:Electronics manufacturers in Guadalajara industrial corridors are expanding refrigerated container bookings for temperature-sensitive semiconductor inputs.
- Asia-Mexico lane expansion:Long-term slot agreements between terminal operators and major carriers are securing dedicated berth windows for automotive supply chains.
Market Restraints
- Bunker fuel cost volatility:IMO sulfur emission standards are forcing carriers to absorb scrubber installation costs or pay premium low-sulfur fuel differentials on Pacific routes.
- Terminal concentration risk:Manzanillo and Lazaro Cardenas handle the majority of Pacific container volume, creating single-point vulnerability during labor disputes or weather events.
- Rail intermodal bottlenecks:Ferromex and Kansas City Southern de México capacity constraints limit inland distribution speed to Mexico City industrial zones.
Strategic Opportunities
- Sinaloa-Jalisco reefer export corridors:Berry and avocado producers are building cold-chain reliability for Asian market penetration through specialized reefer services.
- Gulf Coast port diversification:Veracruz and Altamira terminals offer underutilized capacity for shippers seeking Pacific alternative routing during congestion.
- Customs automation integration:API port authority digitization investments are creating real-time cargo tracking capabilities that attract premium service contracts.
Industry Challenges
- Maritime logistics talent scarcity:Specialized customs brokerage and refrigerated cargo handling expertise remains concentrated in Mexico City and Monterrey, limiting regional terminal expansion.
- Legacy system integration friction:SAT electronic invoicing mandates require expensive ERP upgrades for mid-sized freight forwarders operating manual documentation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Containerized Shipping Market |
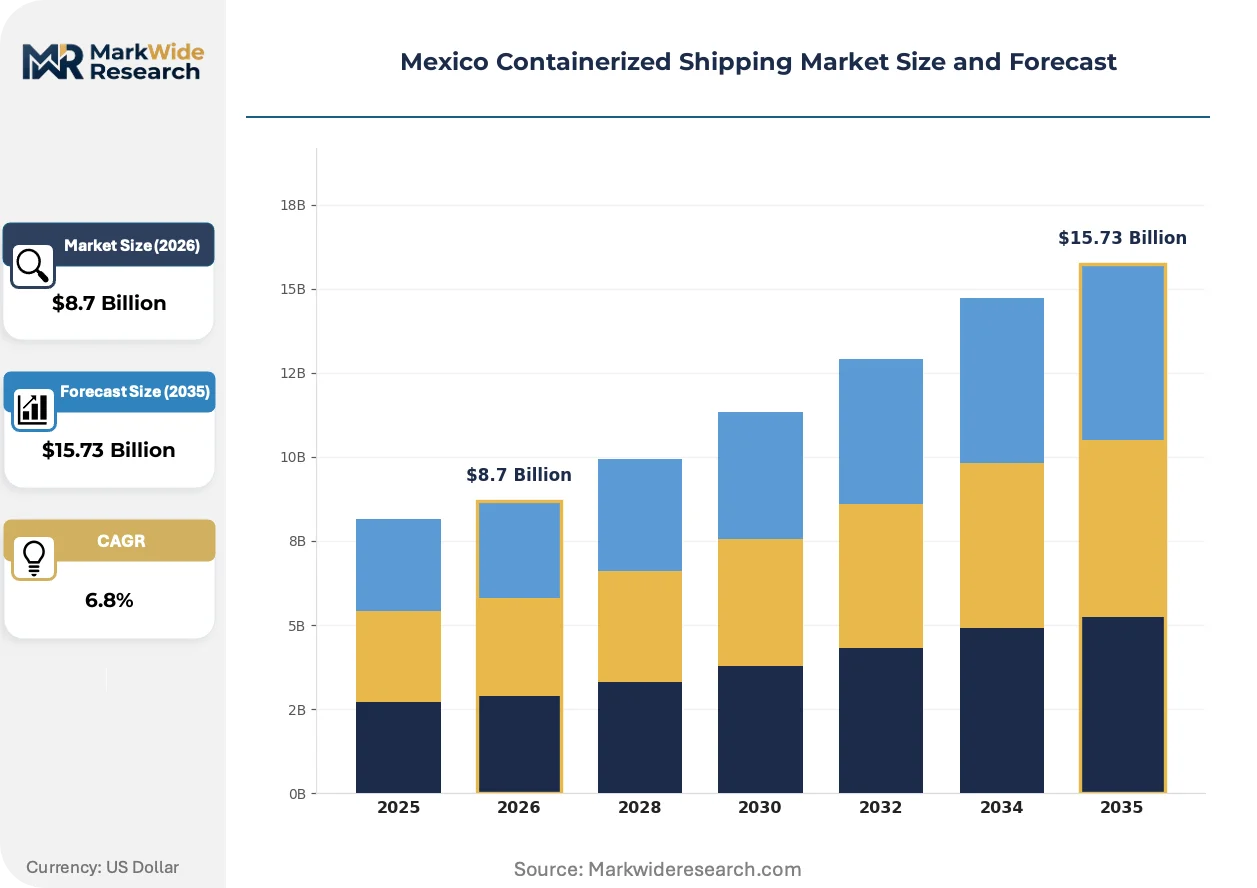
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Container Load, Less Than Container Load, Reefer Services, Special Cargo Shipping Mode: Ocean Freight, Inland Transportation, Intermodal, Port-to-Port Container Type: Standard Dry, Refrigerated, Open Top, Flat Rack Customer Type: Manufacturers, Retailers, Importers, Distributors |
| Companies Covered | Maersk, Mediterranean Shipping Company (MSC), CMA CGM, COSCO Shipping Lines, DHL Mexico, FedEx Mexico, Estafeta, UPS Mexico, Grupo Transportes Monterrey (GTM), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Containerized Shipping Market Trends and Innovations
Digital cargo tracking and automated customs interfaces are compressing information asymmetries between shippers and carriers. These technologies are reallocating value from traditional freight forwarders to platform-enabled logistics orchestrators.
Blockchain-enabled bill-of-lading systems are unifying documentation flows across multimodal handoffs. Automotive manufacturers with just-in-time production schedules are adopting these platforms fastest. The technology is unifying previously fragmented customs, carrier, and inland provider data into single-source visibility.
SAT electronic invoicing mandates under Mexico's Federal Customs Law are standardizing tax documentation across all import transactions. Industrial importers must now integrate certified fiscal software before cargo release. Electronics and automotive verticals are responding fastest due to pre-existing ERP sophistication.
Buyer consolidation among large integrated importers is compressing rate negotiation cycles from annual to quarterly terms. Smaller retailers lacking volume for direct vessel allocations are migrating to NVOCC intermediaries. This pattern concentrates most visibly in Mexico City industrial zones where appliance manufacturers dominate import volumes.
Mexico Containerized Shipping Market Segmentation
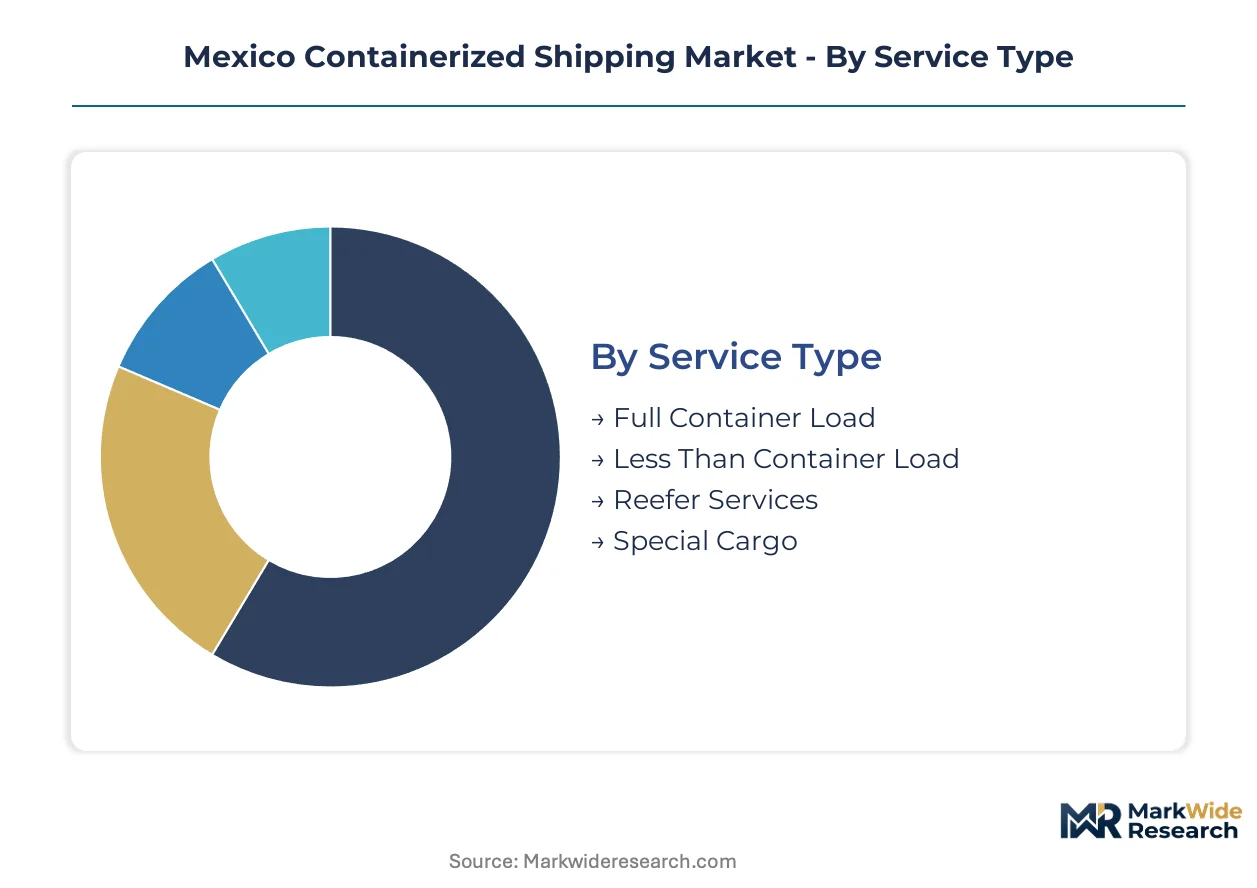
Segmentation in Mexico's containerized shipping market reveals how service configuration, cargo characteristics, and customer scale determine carrier allocation strategies and terminal access priorities across Pacific and Gulf corridors.
Service Type:
Standalone full-container services dominate trans-Pacific automotive flows, while embedded consolidation services address fragmented retail demand across Mexico's industrial zones.
- Full Container Load:Dedicated twenty-foot and forty-foot unit shipments serve consolidated production inputs for Baja California and Nuevo Leon automotive manufacturers. Maersk and Mediterranean Shipping Company negotiate direct vessel allocations with these integrated importers, securing priority berth windows at Manzanillo and Lazaro Cardenas terminals.
- Reefer Services:Temperature-controlled containers maintain precise cold chains for Sinaloa berry and Jalisco avocado exports bound for Asian markets. CMA CGM specializes in these routes, building reliability protocols that justify premium freight rates over standard dry cargo.
- Less Than Container Load:Consolidation services aggregate shipments from smaller retailers lacking volume for dedicated boxes, routing through NVOCC intermediaries.
- Special Cargo:Project freight and out-of-gauge shipments accommodate industrial machinery and construction equipment with non-standard handling requirements.
Full Container Load leads volumes today; Reefer Services is gaining share fastest.
Shipping Mode:
Cost tier separation between asset-heavy ocean operations and flexible inland arrangements shapes how shippers balance control against capital commitment.
- Ocean Freight:Vessel-operating carriers deploy owned or chartered capacity on Asia-Mexico lanes, absorbing bunker fuel volatility and IMO sulfur compliance costs directly.
- Intermodal:Rail-truck combinations through Ferromex and Kansas City Southern de México networks connect Pacific ports to Mexico City industrial zones, though capacity constraints create bottlenecks during peak automotive import seasons.
- Inland Transportation:Pure trucking and barge services handle short-haul distribution from Veracruz and Altamira to central Mexico manufacturing clusters.
- Port-to-Port:Terminal-to-terminal contracts exclude inland liability, attracting cost-sensitive commodity shippers with established drayage relationships.
Ocean Freight commands the highest revenue per ton; Intermodal is climbing the fastest as rail infrastructure investments mature.
Container Type:
Application-driven selection between commodity dry boxes and specialized equipment determines fleet deployment economics across Mexico's export corridors.
- Standard Dry:General-purpose steel containers with weather-sealed doors handle manufactured goods, raw materials, and non-perishable consumer products across the Pacific corridor.
- Refrigerated:Integrated cooling units and insulation systems protect temperature-sensitive semiconductor inputs for Guadalajara electronics manufacturers and perishable exports from coastal agricultural zones.
- Open Top:Removable tarpaulin roofs accommodate heavy machinery and construction materials exceeding standard height clearances.
- Flat Rack:Collapsible end walls support oversized cargo including industrial equipment and vehicle shipments requiring side loading.
Standard Dry boxes dominate fleet deployment; Refrigerated units show steepest expansion trajectory as cold-chain exports accelerate.
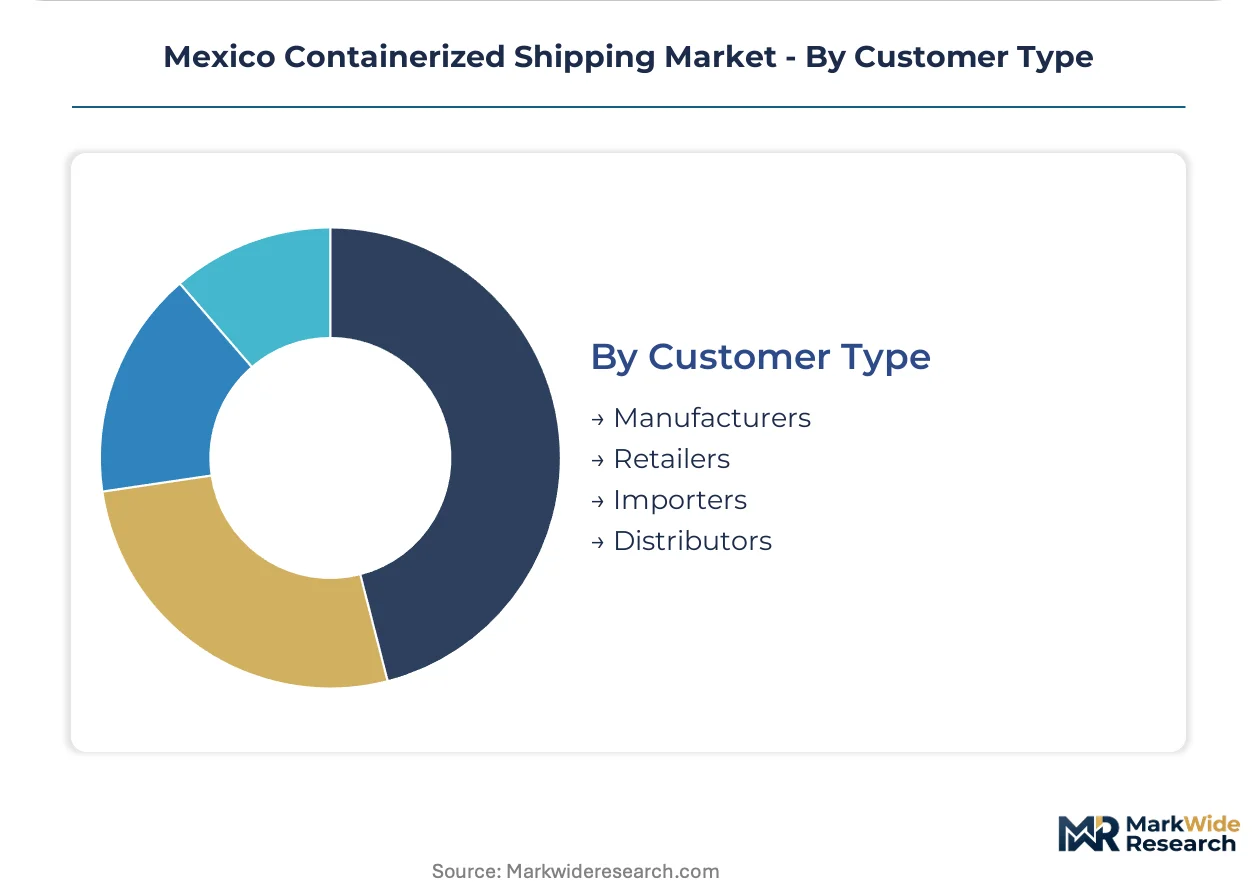
Customer Type:
Customer scale and procurement sophistication determine whether shippers access direct carrier relationships or intermediary-consolidated services.
- Manufacturers:Automotive and electronics producers in Mexico City industrial zones negotiate quarterly rate cycles and dedicated vessel allocations, compressing negotiation leverage for smaller competitors.
- Importers:Integrated trading houses managing precision component flows from Asia leverage volume concentration to secure long-term slot agreements with terminal operators.
- Retailers:Appliance and consumer goods distributors lacking sufficient volume migrate to NVOCC intermediaries for consolidated access to trans-Pacific capacity.
- Distributors:Third-party logistics providers aggregate fragmented demand across multiple end-users, optimizing container utilization through multi-party consolidation.
Manufacturers lead contract values today; Importers are expanding most quickly as nearshoring accelerates component sourcing into Mexico.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Asia-Mexico lane dominance contrasts with Vietnam's emerging role as an alternative sourcing hub for precision components bound for Mexican automotive plants.
China
Shanghai and Shenzhen ports dispatch the majority of containerized electronics and automotive parts to Manzanillo and Lazaro Cardenas. The country's Ministry of Transport enforces port efficiency standards that compress vessel turnaround times. Ningbo-Zhousan terminal operators are negotiating dedicated berth agreements with Mexican importers to secure priority access during peak seasons.
South Korea
Busan anchors semiconductor and display panel exports to Guadalajara electronics corridors. Korea Maritime and Port Administration subsidies support cold-chain infrastructure investments for reefer cargo. Incheon-based shippers are expanding direct vessel strings to Lazaro Cardenas, bypassing transshipment delays at Los Angeles-Long Beach.
United States
Los Angeles and Long Beach terminals handle substantial Mexico-bound transshipment volumes before rail transfer to border crossings. The Federal Maritime Commission monitors carrier alliance practices affecting Mexico service reliability. Texas-based freight forwarders are building cross-border drayage networks to capture automotive supply chain flows from Laredo to Nuevo Leon assembly plants.
Germany
Hamburg and Bremerhaven dispatch precision machinery and automotive tooling to Mexico City industrial zones. The Federal Maritime and Hydrographic Agency enforces EU sulfur emission standards affecting vessel fuel choices on Atlantic routes. Bavarian automotive suppliers are consolidating container bookings through Rotterdam to access Asia-Mexico relay services.
Japan
Yokohama and Kobe terminals export automotive components and electronics to Baja California manufacturing clusters. Japan's Ministry of Land, Infrastructure, Transport and Tourism coordinates port digitalization standards that align with Mexican SAT electronic invoicing protocols. Nagoya-based trading houses are securing long-term slot agreements with Pacific terminal operators to guarantee component delivery schedules.
Mexico Containerized Shipping Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Mexico's containerized shipping corridors. The market structure concentrates around three vessel-operating carriers controlling trans-Pacific berth access, while integrated logistics providers and regional trucking networks fill intermodal gaps. Strategic archetypes include global shipping lines with terminal equity stakes, asset-light NVOCC consolidators, and captive automotive logistics arms. Capacity expansion and customs automation partnerships represent the dominant competitive moves reshaping service economics.
Among global shipping lines, Maersk and Mediterranean Shipping Company exemplify the terminal-integrated archetype through their Pacific port partnerships. CMA CGM occupies a specialized position within reefer-heavy service configurations. These three carriers anchor the competitive structure by controlling direct vessel allocations that smaller importers cannot access without NVOCC intermediation.
| Leading Market Players |
|---|
| Maersk |
| Mediterranean Shipping Company (MSC) |
| CMA CGM |
| COSCO Shipping Lines |
| DHL Mexico |
| FedEx Mexico |
| Estafeta |
| UPS Mexico |
| Grupo Transportes Monterrey (GTM) |
| Others |
Pricing and Supply Chain Analysis
Terminal-operating carriers with sovereign wealth fund backing and private-equity rolled-up port operators anchor supply-side discipline across Mexico's Pacific corridor, translating berth scarcity into quarterly rate renegotiation leverage against automotive manufacturers.
Pricing Analysis
Capacity additions at Lazaro Cardenas are reshaping price floors for standard dry cargo even as reefer premiums widen. Three-tier pricing structure across premium, standard, and economy levels segments automotive manufacturers with dedicated vessel allocations from retailers dependent on NVOCC consolidation. Price differentiation stems from volume scale and customs automation integration, with SAT-certified fiscal software access commanding freight rate premiums. Cost compression in standard dry segments is intensifying because Ferromex rail capacity constraints force modal shifts to higher-cost trucking. Smaller retailers lacking direct carrier relationships exhibit highest price sensitivity, while integrated importers with quarterly rate cycles show least elasticity.
Supply Chain Analysis
USMCA domestic-content mandates are reshaping sourcing patterns for precision components bound for Baja California assembly plants. Supply concentrates in China, South Korea, and Japan for semiconductor inputs, automotive tooling, and display panels. Raw material dependencies include specialized steel for container manufacturing, bunker fuel for vessel operations, and refrigerant gases for reefer units. Single-source vulnerability runs through Manzanillo and Lazaro Cardenas terminal concentration during Pacific hurricane seasons. Distribution runs through Ferromex and Kansas City Southern de México rail networks to Mexico City industrial zones, with drayage operators filling last-mile gaps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's containerized shipping market represents a late-cycle quality story as berry and avocado exporters demand cold-chain reliability specifications that reefer-specialized carriers can premium-price.
For Market Incumbents: Extend terminal equity stakes into customs automation partnerships that lock in SAT-certified importer relationships before API digitization investments mature. Consolidate berth access through long-term slot agreements with Lazaro Cardenas and Manzanillo operators to defend against COSCO's Asia-Mexico lane expansion. Backward integration into Ferromex rail capacity through dedicated train allocations addresses intermodal bottlenecks threatening automotive just-in-time schedules. For New Entrants and Emerging Players: Launch via Gulf Coast port diversification at Veracruz and Altamira terminals where underutilized capacity offers Pacific alternative routing during congestion peaks. Target Sinaloa-Jalisco reefer export corridors where CMA CGM's specialization leaves white-space for regional cold-chain operators. Penetrate through NVOCC consolidation services for mid-sized retailers lacking volume for direct vessel allocations in Mexico City industrial zones. For Investors and Strategic Acquirers: Valuations sit cheapest among asset-light NVOCC consolidators with established SAT electronic invoicing integration and captive automotive forwarder relationships. Long-term viability hinges on nearshoring acceleration sustaining precision component import flows into Nuevo Leon and Baja California. Monitor IMO sulfur compliance cost pass-through as the inflection indicator separating scrubber-equipped carriers from fuel-price-exposed competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Terminal Equity Expansion | Maersk's Pacific partnerships secure dedicated berth windows at Manzanillo during peak automotive import seasons. |
| Reefer Service Specialization | CMA CGM's cold-chain protocols capture premium freight rates from Sinaloa berry exporters penetrating Asian markets. |
| Customs Automation Integration | API port authority digitization investments attract premium service contracts through real-time cargo tracking capabilities. |
| Gulf Coast Port Diversification | Veracruz and Altamira terminals offer underutilized capacity for shippers seeking Pacific alternative routing during congestion. |
| Rail Intermodal Capacity Lock | Ferromex and Kansas City Southern de México dedicated train allocations address bottlenecks to Mexico City industrial zones. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with carrier network planners, API port authority operations directors, SAT customs modernization leads, automotive supply chain managers, and NVOCC consolidation specialists with secondary validation. Trade flow databases, vessel deployment schedules, customs automation investment disclosures, and rail intermodal capacity reports anchored supply-side modeling. Bottom-up container volume builds and top-down corridor revenue estimates triangulated market sizing.
Historical reference periods spanning pre-pandemic baseline, disruption peak, and normalization phases anchored the forecast window across the analysis window. Segmentation dimensions modeled include service type, shipping mode, container equipment category, and customer procurement sophistication tier. CAGRs derived from vessel deployment growth curves, terminal capacity expansion timelines, and customs automation adoption S-curves. Reefer fleet deployment rates and automotive nearshoring pipeline volumes served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including labor dispute durations at concentrated Pacific terminals, bunker fuel price volatility beyond IMO sulfur compliance baselines, and USMCA renegotiation scenarios affecting rules-of-origin enforcement. Forecasts reflect assumptions about customs automation rollout pacing and rail infrastructure investment completion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Global Courier Market
Logistics and Shipping
Germany Freight Forwarding Market
Logistics and Shipping
Europe FMCG Logistics Market
Logistics and Shipping
Qatar Third-Party Logistics (3PL) Market
Logistics and Shipping
Australia Cold Chain Logistics Market
Logistics and Shipping
Intralogistics Containers Market
Logistics and Shipping
Sweden Freight and Logistics Market
Logistics and Shipping
Singapore Chemical Logistics Market
Logistics and Shipping
North America Automotive Logistics Market
Logistics and Shipping
Germany Third-Party Logistics (3PL) Market
Logistics and Shipping
China Shipping Agency Services Market
Logistics and Shipping
Peru Freight and Logistics Market
Logistics and Shipping
Vietnam Freight and Logistics Market
Logistics and Shipping
Chile Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Europe Courier Market
Logistics and Shipping
India 3PL Market