
 Vietnam Logistics Market | 2026-2036
Vietnam Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Logistics Market Insights
E-commerce merchants are bifurcating from traditional manufacturing shippers as the dominant demand archetype in Vietnam's logistics landscape. Viettel Post Joint Stock Corporation leverages its telecom-parent last-mile density to dominate urban parcel networks. Gemadept anchors deep-sea container handling through its strategic port assets along Vietnam's coastline. DHL Group extends international express connectivity into industrial zones near Hanoi and Da Nang.
Logistics encompasses the integrated planning, execution, and control of freight movement, inventory positioning, and information flows across supply chains, typically measured through transit-time reliability, cargo damage rates, and cost-per-ton-kilometer parameters. The sector's primary commercial purpose is to reduce friction between production nodes and consumption endpoints. Freight forwarding commands the largest revenue pool among service types due to cross-border trade complexity, while warehouse management systems within the technology dimension represent the fastest structural expansion as operators automate fulfillment centers. Third-party logistics channels capture disproportionate margin concentration by bundling asset-light coordination with customs brokerage expertise.
Vietnam's Ministry of Transport and the Vietnam Maritime Administration jointly enforce port infrastructure standards and coastal shipping regulations that determine vessel size eligibility and terminal access fees. The country's national logistics development plan imposes digital interoperability mandates on customs clearance platforms, reshaping technology procurement patterns among licensed freight brokers. Stakeholders must monitor how upcoming inland waterway corridor investments alter modal competition between trucking and barge transport for agricultural and manufactured exports.
Market Dynamics
E-commerce fulfillment velocity is compressing traditional freight forwarding margins while forcing warehouse operators toward automated sortation systems. Vietnam's Ministry of Transport mandates on customs clearance platforms are accelerating digital procurement timelines for licensed brokers.
Growth Catalysts
- Port Infrastructure Modernization:The Vietnam Maritime Administration's vessel size eligibility reforms are expanding deep-sea container throughput at Hai Phong and Cai Mep terminals. This unlocks transshipment volume for regional manufacturing exporters.
- Cross-Border E-Commerce:Shopee and Lazada marketplace sellers are generating parcel density that justifies dedicated last-mile sortation hubs in Ho Chi Minh City and Hanoi. This demand archetype pulls freight forwarders into higher-velocity operating models.
- Inland Waterway Corridors:The Red River Delta barge network is capturing agricultural export volume from trucking operators. Modal shift reduces per-ton-kilometer costs for rice and aquaculture shipments.
Market Restraints
- Fuel Cost Volatility:Diesel price fluctuations compress trucking operator margins on contract freight. Spot market exposure concentrates among asset-light forwarders without fuel surcharge mechanisms.
- Port Concentration Risk:Cai Mep-Thi Vai terminal complex handles disproportionate southern Vietnam container volume. Bottleneck vulnerability spikes during monsoon season closures.
- Regulatory Fragmentation:Provincial licensing requirements for warehouse construction create approval timeline variance across the Mekong Delta. This friction slows fulfillment center rollout for e-commerce platforms.
Strategic Opportunities
- Central Highlands Connectivity:Underpenetrated coffee and pepper export corridors around Da Lat lack temperature-controlled consolidation facilities. Cold chain infrastructure investment captures premium agricultural logistics margin.
- Digital Freight Matching:Mobile platform adoption among owner-operator truckers is decomposing traditional broker intermediation. Real-time load-board penetration remains below northern corridor saturation.
- Green Logistics Incentives:Vietnam's national logistics development plan embeds carbon intensity benchmarks for port operators. Electric yard tractor deployment qualifies for accelerated depreciation treatment.
Industry Challenges
- Warehouse Management System Integration:Legacy ERP architectures at state-owned manufacturers resist API connectivity with third-party fulfillment platforms. Custom middleware development extends implementation timelines.
- Customs Broker Certification:Licensed freight broker examination pass rates constrain qualified personnel supply. Digital interoperability mandates amplify training burden for clearance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Logistics Market |
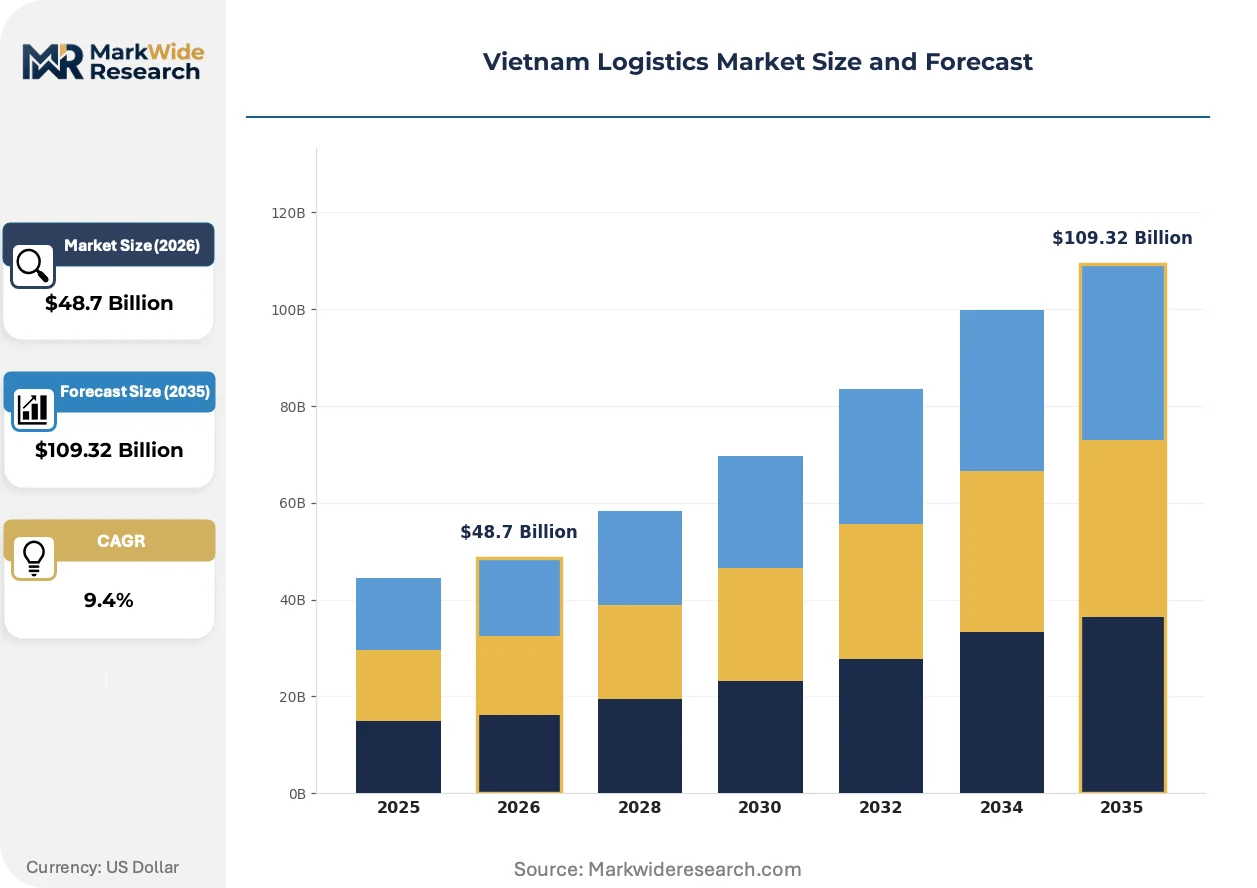
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $109.32 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Freight Forwarding, Warehousing, Transportation, Customs Brokerage End User: Retail, Manufacturing, E-Commerce, Healthcare Technology: Warehouse Management Systems, Fleet Management, IoT Tracking, RFID Solutions Distribution Channel: Direct Shipping, Third-Party Logistics, E-Commerce Platforms, Freight Brokers |
| Companies Covered | Bee Logistics Corporation, Viettel Post Joint Stock Corporation, Kuehne + Nagel, PetroVietnam Transport Corporation, Vietnam Maritime Corporation, A.P. Moller - Maersk, DHL Group, Gemadept, Indo Trans Logistics Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Logistics Market Trends and Innovations
Automation is penetrating Vietnam's logistics stack from port yard equipment through last-mile sortation. Three concurrent shifts are restructuring competitive positioning across service tiers.
Autonomous mobile robots in e-commerce fulfillment centers are decomposing traditional warehouse labor models. Lazada and Shopee-affiliated operators are deploying unit-pick robotics at Hanoi and Ho Chi Minh City hubs. This technology compression enables same-day delivery promises while reducing damage rates on high-velocity parcel handling.
Vietnam's Ministry of Transport digital interoperability mandates are reshaping customs clearance procurement. Licensed brokers must integrate with centralized electronic data interchange platforms by regulatory deadline. Small and mid-tier forwarders face technology procurement decisions that favor cloud-native software vendors over legacy on-premise systems.
Consolidation among Mekong Delta agricultural exporters is shifting procurement toward contracted logistics rather than spot trucking. Large rice millers and seafood processors are negotiating multi-year warehousing and freight agreements. This behavioral pivot concentrates volume with integrated 3PL operators possessing bonded facility credentials.
Vietnam Logistics Market Segmentation
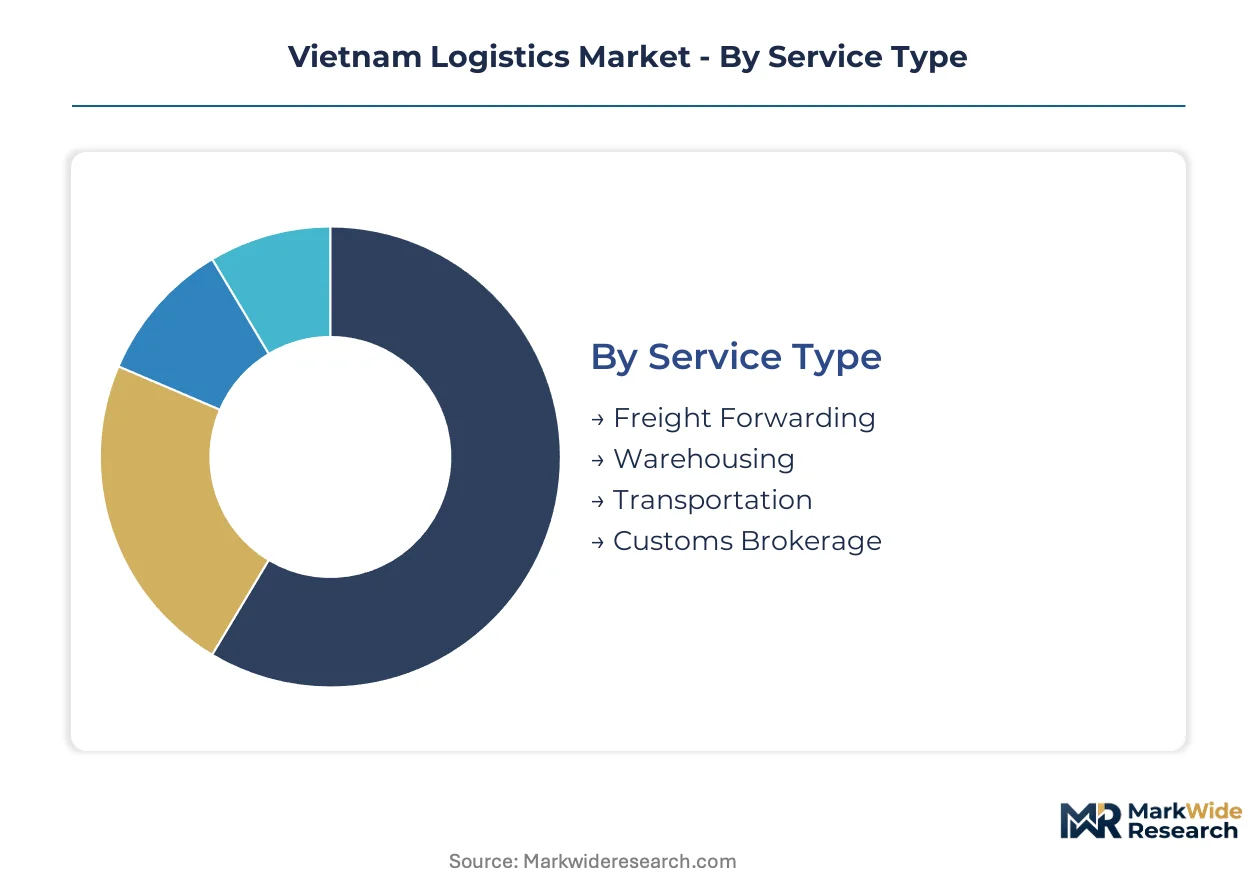
Vietnam's logistics market fragments across service capabilities, end-user requirements, and technology adoption curves. Understanding these segment boundaries reveals where substitution pressures and margin concentration concentrate most intensely.
Service Type:
Freight forwarding faces the most acute substitution threat as digital freight platforms decompose traditional broker intermediation, while asset-heavy segments defend position through bonded facility scarcity.
- Freight Forwarding:Cross-border coordination of multimodal shipments through ocean, air, and land legs. Demand concentrates among manufacturing exporters in the Red River Delta corridor, pressured by mobile load-board penetration among owner-operator truckers that erodes traditional brokerage margins.
- Warehousing:Inventory positioning and fulfillment center operations including bonded storage and cold chain facilities. E-commerce merchants in Ho Chi Minh City and Hanoi drive demand for automated sortation systems that compress labor models and enable same-day delivery promises.
- Transportation:Asset-based trucking and barge services moving cargo between production nodes and port terminals. The Red River Delta barge network captures agricultural export volume from road operators as Vietnam's Ministry of Transport invests in inland waterway corridor modernization.
- Customs Brokerage:Documentation preparation and regulatory compliance for import-export clearance. Licensed broker examination pass rates constrain qualified personnel supply while digital interoperability mandates from the Vietnam Maritime Administration amplify training burdens.
Freight forwarding anchors the volume base while warehousing gains share at the steepest rate.
End User:
Cost tier differentiation separates premium cold chain-dependent healthcare shippers from price-sensitive agricultural exporters, with e-commerce merchants occupying the fastest-expanding middle tier.
- Retail:Traditional brick-and-mortar distribution networks requiring scheduled replenishment and seasonal surge capacity. Consolidation among Mekong Delta agricultural exporters shifts procurement toward contracted logistics rather than spot trucking arrangements.
- Manufacturing:Just-in-time component flows and finished goods export coordination for electronics and textile producers. Industrial zones near Hanoi and Da Nang generate concentrated freight forwarding demand as DHL Group extends international express connectivity into these clusters.
- E-Commerce:High-velocity parcel networks demanding last-mile density and returns processing infrastructure. Shopee and Lazada marketplace sellers generate parcel density justifying dedicated sortation hubs that pull freight forwarders into higher-velocity operating models.
- Healthcare:Temperature-controlled pharmaceutical distribution and medical device logistics requiring GDP compliance. Cold chain infrastructure investment captures premium margin in underpenetrated corridors around Da Lat lacking consolidation facilities for coffee and pepper exports.
Manufacturing anchors the volume base while e-commerce climbs the fastest among end-user categories.
Technology:
Application maturity varies sharply, with warehouse automation penetrating fastest where labor cost arbitrage justifies capital deployment, while fleet solutions lag in owner-operator market fragmentation.
- Warehouse Management Systems:Software platforms coordinating inventory tracking, order fulfillment, and labor optimization across fulfillment centers. Lazada and Shopee-affiliated operators deploy unit-pick robotics at Hanoi and Ho Chi Minh City hubs to reduce damage rates on high-velocity parcel handling.
- Fleet Management:Telematics and route optimization systems for trucking asset utilization. Mobile platform adoption among owner-operator truckers decomposes traditional broker intermediation, though real-time load-board penetration remains below northern corridor saturation.
- IoT Tracking:Sensor-based cargo monitoring for location, temperature, and shock detection. Agricultural exporters negotiating multi-year warehousing agreements demand visibility infrastructure that integrated 3PL operators with bonded facility credentials can provision.
- RFID Solutions:Automated identification and data capture for inventory reconciliation and anti-counterfeiting. Legacy ERP architectures at state-owned manufacturers resist API connectivity with third-party fulfillment platforms, extending implementation timelines for custom middleware development.
Warehouse Management Systems anchor the technology investment base while IoT Tracking expands most quickly as agricultural exporters consolidate.
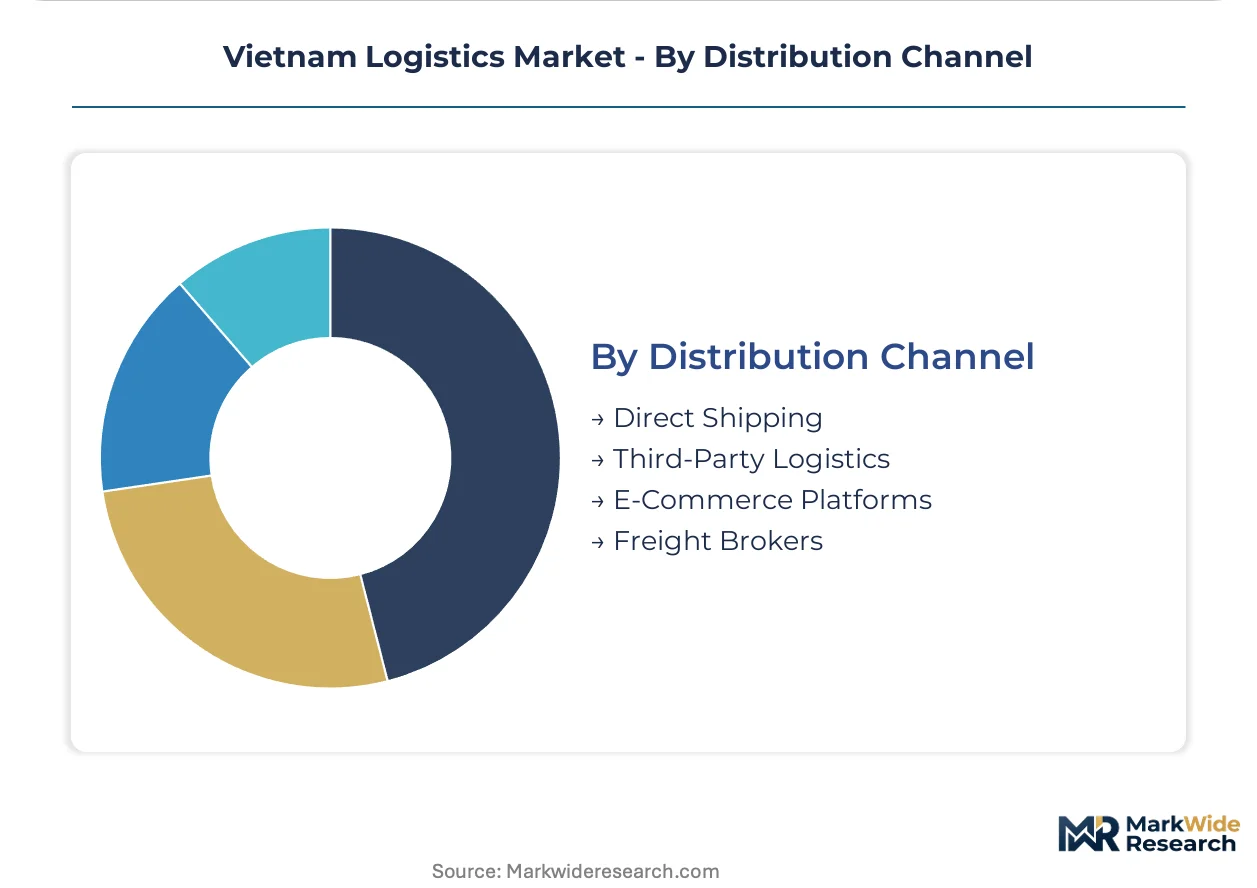
Distribution Channel:
Customer type concentration shapes channel economics, with integrated 3PL operators capturing disproportionate margin through bundled service offerings while pure intermediaries face compression.
- Direct Shipping:Manufacturer-operated fleets and captive logistics assets for vertical integration. Large rice millers and seafood processors in the Mekong Delta bypass intermediaries through contracted multi-year agreements that concentrate volume with bonded facility operators.
- Third-Party Logistics:Bundled warehousing, transportation, and value-added services from integrated providers. Gemadept anchors deep-sea container handling through strategic port assets, while Viettel Post leverages telecom-parent last-mile density to dominate urban parcel networks.
- E-Commerce Platforms:Marketplace-integrated fulfillment services including last-mile delivery and returns processing. Provincial licensing requirements for warehouse construction create approval timeline variance across the Mekong Delta, slowing fulfillment center rollout for platform operators.
- Freight Brokers:Asset-light intermediaries matching shipper demand with carrier capacity. Diesel price fluctuations compress margins on contract freight, concentrating spot market exposure among forwarders without fuel surcharge mechanisms.
Third-Party Logistics anchors the channel volume base while E-Commerce Platforms gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Lach Huyen deep-water port underwrites northern Vietnam's logistics prominence by accommodating post-Panamax vessels that bypass transshipment through Singapore or Hong Kong. This maritime asset anchors the Red River Delta corridor's integration into East Asian manufacturing supply chains.
Red River Delta
Hai Phong port complex processes electronics exports from Samsung and LG manufacturing bases. Vietnam's Ministry of Transport mandates digital customs platforms that compress clearance timelines for bonded warehouse operators. Bac Ninh and Vinh Phuc industrial zones concentrate just-in-time component flows requiring sub-24-hour turnaround.
Southeast Region
Cai Mep-Thi Vai terminal cluster handles southern Vietnam's container volume for textile and footwear exporters. The Vietnam Maritime Administration's vessel size eligibility reforms expanded deep-sea access, reducing per-box costs for Mekong Delta agricultural shippers. Dong Nai and Binh Duong provinces host dense warehousing clusters serving Ho Chi Minh City consumption.
Central Coast
Da Nang port anchors logistics demand from furniture and seafood processors in Quang Nam and Thua Thien-Hue provinces. National logistics development plan investments in highway connectivity link the port to Laos and northeast Thailand cross-border corridors. The city lacks sufficient bonded cold storage for temperature-sensitive pepper and coffee exports.
Central Highlands
Lam Dong and Dak Lak provinces generate agricultural export volume lacking consolidation infrastructure. Provincial licensing variance for warehouse construction slows fulfillment center deployment for e-commerce platforms targeting Da Lat and Buon Ma Thuot. The region remains dependent on road haulage to Nha Trang and Quy Nhon ports.
Mekong Delta
Can Tho and An Giang provinces anchor rice and aquaculture export flows increasingly captured by Red River Delta barge networks. Diesel price volatility compresses trucking operator margins on contract freight to Ho Chi Minh City. The inland waterway corridor investments alter modal competition, reducing per-ton-kilometer costs for bulk agricultural shipments.
Vietnam Logistics Market Competitive Landscape
Concentration sits with port-anchored conglomerates and telecom-backed last-mile operators that bundle asset-heavy infrastructure with digital coordination capabilities. The market fragments across three tiers: integrated 3PLs with bonded facility networks, international forwarders extending express connectivity, and domestic parcel specialists leveraging parent-company infrastructure. Strategic moves center on warehouse automation procurement and inland waterway corridor partnerships that capture agricultural export volume from road operators.
Among port-anchored operators, Gemadept and Vietnam Maritime Corporation exemplify the infrastructure-dependent archetype controlling deep-sea terminal access. Viettel Post Joint Stock Corporation occupies a distinct position leveraging telecom-parent last-mile density for urban parcel networks. International forwarders including DHL Group and Kuehne + Nagel represent the cross-border coordination tier extending express services into industrial zones near Hanoi and Da Nang.
| Leading Market Players |
|---|
| Bee Logistics Corporation |
| Viettel Post Joint Stock Corporation |
| Kuehne + Nagel |
| PetroVietnam Transport Corporation |
| Vietnam Maritime Corporation |
| A.P. Moller - Maersk |
| DHL Group |
| Gemadept |
| Indo Trans Logistics Corporation |
| Others |
Pricing and Supply Chain Analysis
Digital freight matching platforms displacing traditional broker intermediation simultaneously redraw Vietnam's logistics geography and compress margin structures across the Red River Delta corridor. Mobile load-board penetration among owner-operator truckers collapses brokerage spreads while pulling pricing power toward asset-heavy operators with bonded facility credentials.
Pricing Analysis
Volume-discount tiering structures dominate contract negotiations between Mekong Delta agricultural exporters and integrated 3PL operators. Pricing stratifies across premium cold chain, standard bonded warehousing, and economy spot trucking tiers based on certification grade and geographic delivery cost. Cost compression in economy trucking intensifies because diesel price volatility strips fuel surcharge protection from asset-light forwarders. E-commerce merchants in Ho Chi Minh City demonstrate lowest price sensitivity, prioritizing velocity over per-ton-kilometer rates.
Supply Chain Analysis
Cai Mep-Thi Vai terminal chokepoint underwrites southern Vietnam's container throughput concentration for textile and footwear exporters. Manufacturing inputs draw from China, South Korea, and Taiwan for electronics components feeding Red River Delta assembly plants. Single-source vulnerability spikes during monsoon season closures when the terminal complex bottlenecks. Distribution feeds through third-party logistics channels capturing disproportionate margin concentration via bundled customs brokerage expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against digital freight platforms substituting traditional brokerage functions while agricultural exporters consolidate procurement around integrated operators. Substitution pressure from mobile load-board penetration threatens asset-light intermediaries most acutely.
For Market Incumbents: Consolidate port-anchored infrastructure positions through bonded facility expansion at Hai Phong and Cai Mep terminals. Deepen backward integration into inland waterway barge networks capturing agricultural export volume from road operators before digital platforms commoditize trucking coordination. For New Entrants and Emerging Players: Cold chain infrastructure gaps in the Central Highlands around Da Lat present the most penetrable white-space target for temperature-controlled coffee and pepper consolidation facilities. Target healthcare logistics requiring GDP compliance as the go-to-market angle, leveraging certification barriers that slow incumbent response. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated 3PL operators with bonded facility networks and port access rights. Long-term viability across the next decade hinges on automation deployment velocity in fulfillment centers. Monitor digital interoperability mandate compliance timelines as the inflection indicator for technology procurement winners.| Strategic Initiative | Industry Significance |
|---|---|
| Warehouse Automation Deployment | Unit-pick robotics at Hanoi and Ho Chi Minh City hubs enable same-day delivery promises for Shopee and Lazada affiliates. |
| Inland Waterway Partnership | Red River Delta barge network investments capture rice and aquaculture volume from trucking operators facing diesel cost volatility. |
| Bonded Facility Expansion | Licensed warehouse construction in Bac Ninh and Dong Nai provinces secures customs-advantaged positioning for electronics exporters. |
| Digital Platform Integration | Cloud-native customs brokerage software meets Vietnam Maritime Administration interoperability mandates before regulatory deadlines. |
| Cold Chain Infrastructure Buildout | Temperature-controlled consolidation facilities around Da Lat capture premium margin from coffee and pepper agricultural exporters. |
Research Methodology
Operator-level perspectives from port terminal managers, freight forwarding executives, warehouse automation specialists, and agricultural exporter procurement leads anchored the qualitative base. Primary interviews combined with secondary validation from Vietnam Maritime Administration filings, Ministry of Transport infrastructure disclosures, and customs trade flow databases. Bottom-up service provider capacity assessments triangulated against top-down trade volume projections.
Sensitivity analysis tested forecast outputs against modal shift assumptions and e-commerce penetration scenarios across the projection horizon. Segmentation dimensions modeled include service type, end-user industry, technology adoption tier, and distribution channel structure. CAGRs derived from historical trajectory analysis adjusted for infrastructure investment timelines and regulatory implementation schedules. Forecast inputs incorporated vessel size eligibility reforms and digital interoperability mandate compliance curves.
Forecasts assume regulatory continuity in Vietnam's national logistics development plan and Ministry of Transport customs modernization regimes; material policy shifts would require re-modeling. Scenario risks include provincial licensing timeline variance for warehouse construction and monsoon season terminal closure frequency. Practitioners should keep alternative scenarios live as inland waterway corridor investment schedules and diesel price volatility bands evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Italy Apparel Logistics Market
Logistics and Shipping
North America Logistics Market
Logistics and Shipping
Government and Education Logistics Market
Logistics and Shipping
Peru Logistics Market
Logistics and Shipping
Thailand Courier Express Parcel (CEP) Market
Logistics and Shipping
Colombia Cold Chain Logistics Market
Logistics and Shipping
Middle East and Africa Courier Market
Logistics and Shipping
Spain Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Fleet of Containers Market
Logistics and Shipping
Tennessee Freight and Logistics Market
Logistics and Shipping
Nigeria Freight and Logistics Market
Logistics and Shipping
Egypt 3PL Market
Logistics and Shipping
Jordan Freight and Logistics Market
Logistics and Shipping
Latin America Fourth Party Logistics (4PL) Market
Logistics and Shipping
Delivery Tracking Platform Market
Logistics and Shipping
Shipping Container Modification Market