
 United Kingdom Third Party Logistics (3PL) Market | 2026-2036
United Kingdom Third Party Logistics (3PL) Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Third Party Logistics (3PL) Market Analytics
Buyer concentration among UK e-commerce retailers is decoupling from traditional retail logistics patterns as direct-to-consumer volumes fragment across marketplace sellers and specialty brands. DHL Supply Chain leverages pan-European network density to serve omnichannel fulfillment requirements. Culina Group specializes in temperature-controlled food logistics, sustaining its position through dedicated cold-chain infrastructure across England and Wales. GXO Logistics operates automated warehouse systems for major retail clients, extending its technology footprint in automated sortation and robotics.
Third Party Logistics (3PL) encompasses outsourced transportation management, warehousing, inventory control, and value-added services performed by external providers on behalf of shippers, typically governed by service-level agreements specifying delivery windows, inventory accuracy thresholds, and cost-per-unit metrics. The primary commercial purpose is to convert fixed logistics assets into variable costs while accessing specialized operational expertise. Warehousing and order fulfillment services command the largest share of revenue pools, reflecting structural demand from e-commerce and grocery retail verticals. Value-added services represent the fastest-expanding segment, driven by kitting, labeling, and returns processing requirements. The dedicated delivery model dominates contract structures among large enterprises, while shared and on-demand models gain traction among SMEs seeking flexible capacity.
The UK's Driver Certificate of Professional Competence (CPC) requirements and Vehicle Excise Duty frameworks shape fleet composition and labor availability for road transport operators. Health and Safety Executive (HSE) regulations governing warehouse ergonomics and automation safety standards influence capital deployment decisions for facility upgrades. Stakeholders must monitor evolving customs documentation requirements under the UK Border Operating Model and assess how carbon reporting mandates from the Department for Transport reshape long-haul routing and modal choice strategies.
Market Dynamics
Post-Brexit customs complexity is fragmenting inventory positioning across the United Kingdom, forcing shippers to duplicate stockholding in British and EU mainland facilities rather than serving both markets from single locations.
Growth Catalysts
- E-commerce fulfillment density:Direct-to-consumer order volumes from marketplace sellers and specialty brands are expanding dedicated fulfillment center requirements across the Midlands logistics corridor.
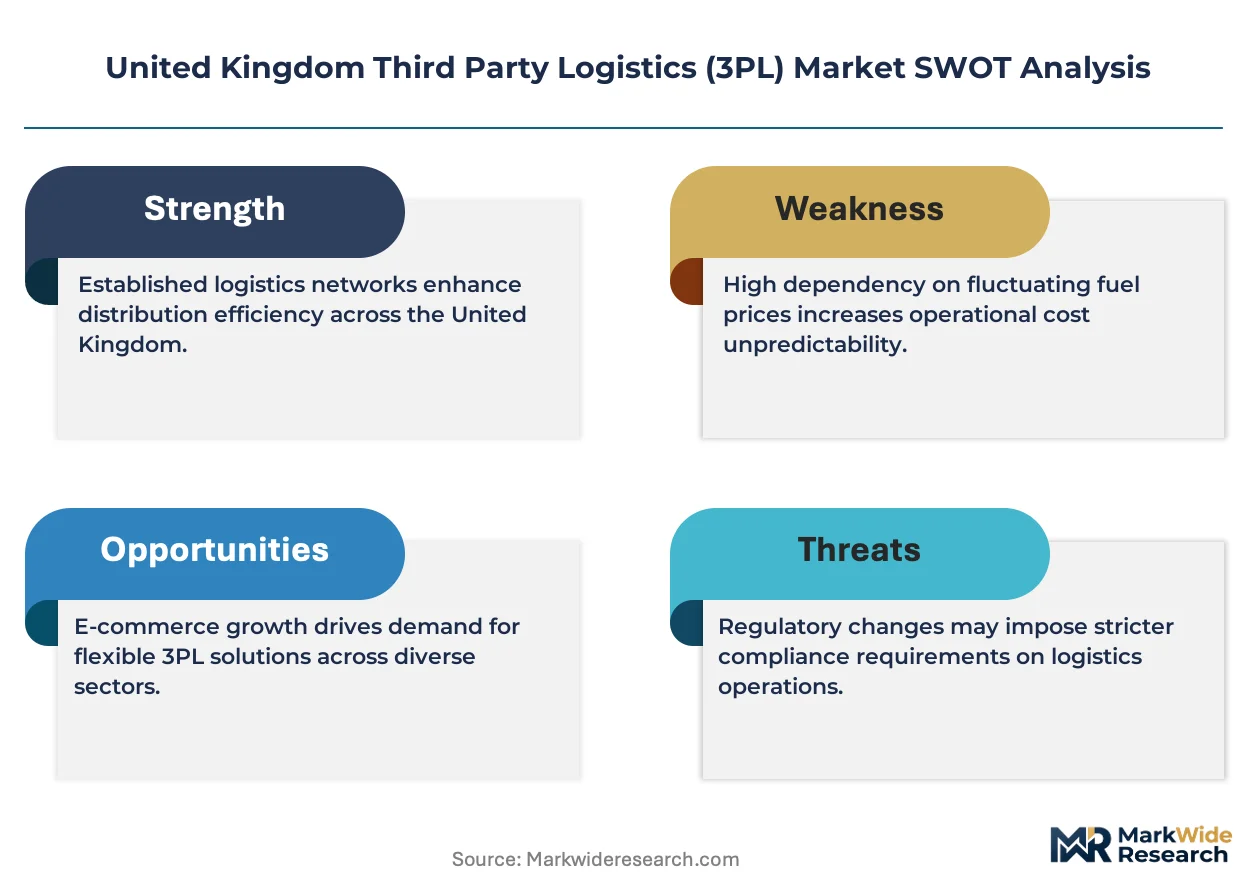
- The UK Border Operating Model:Phased customs documentation requirements are accelerating demand for bonded warehousing and customs brokerage services as shippers navigate post-Brexit trade friction.
- Cold-chain infrastructure investment:Temperature-controlled food logistics operators are expanding capacity to serve grocery retail verticals requiring precise environmental controls throughout distribution.
Market Restraints
- Driver Certificate of Professional Competence (CPC) compliance:The UK's mandatory periodic training requirements for HGV operators are constraining labor availability and inflating wage costs for road transport fleets.
- Vehicle Excise Duty frameworks:Progressive taxation based on emissions ratings is compressing margins for operators running older diesel fleets and accelerating capital replacement cycles.
- Cross-border duplication:Separate inventory positioning for British and EU markets is inflating working capital requirements and reducing network efficiency for pan-European shippers.
Strategic Opportunities
- Automated warehouse robotics:Convergence of autonomous mobile robots with AI-driven inventory optimization is creating differentiation for operators serving high-velocity omnichannel retail.
- Returns processing specialization:Reverse logistics capabilities for apparel and electronics verticals represent underdeveloped service layers with premium pricing potential.
- Carbon reporting mandates:The Department for Transport's emissions disclosure requirements are creating advisory service opportunities around modal shift and route optimization.
Industry Challenges
- Warehouse automation integration:Legacy warehouse management systems require costly retrofitting to interface with robotic sortation and autonomous fulfillment technologies.
- Health and Safety Executive (HSE) compliance:Evolving ergonomics and automation safety standards are extending facility upgrade timelines and certification delays for capital projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Third Party Logistics (3PL) Market |
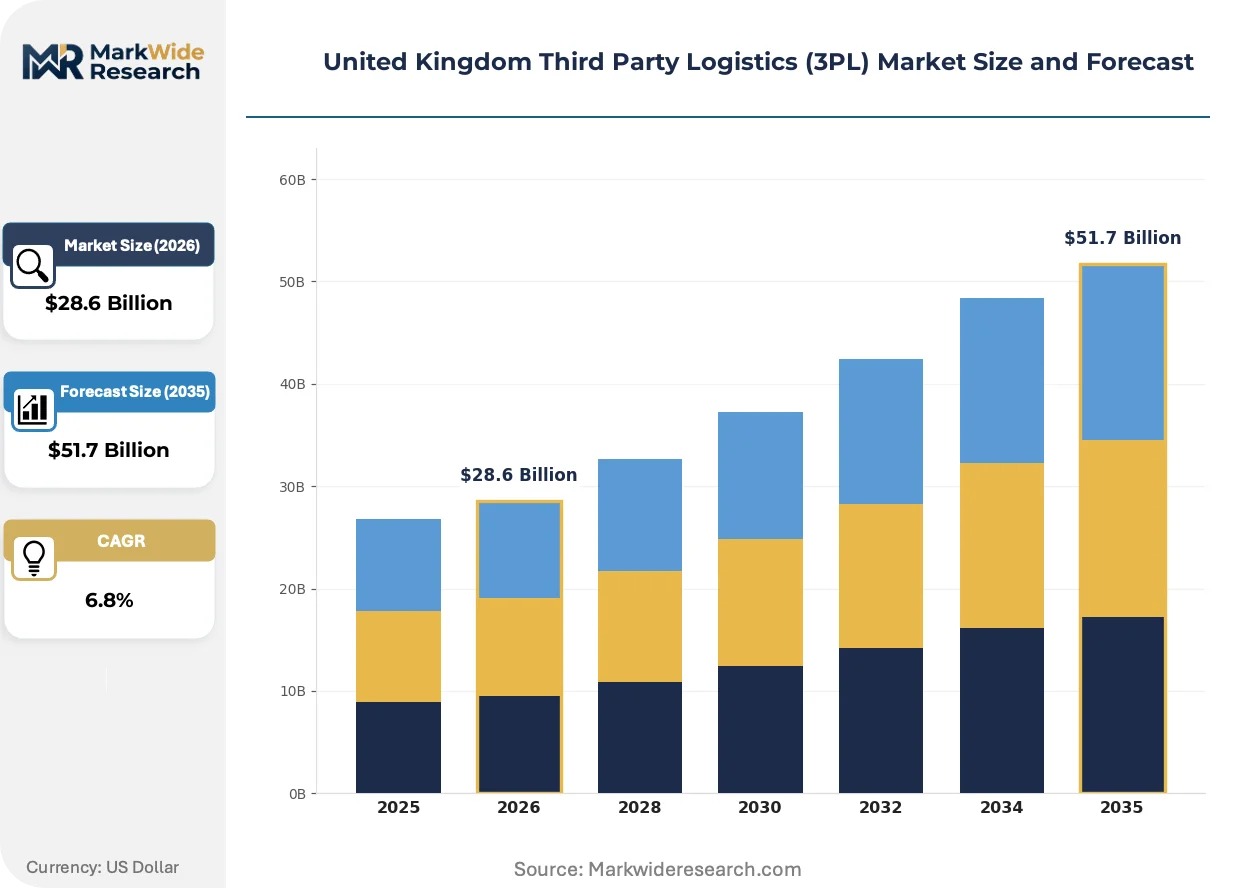
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transport Management, Warehousing, Value-Added Services, Order Fulfillment Industry Vertical: Retail, Manufacturing, E-Commerce, Automotive Delivery Model: Dedicated, Shared, On-Demand, Integrated Customer Type: Large Enterprises, SMEs, Startups, Multinationals |
| Companies Covered | DSV, Yusen Logistics, DHL Supply Chain, Culina Group, Rhenus Logistics, Kuehne + Nagel, CEVA Logistics, DB Schenker, GXO Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Third Party Logistics (3PL) Market Evolving Landscape
Digital orchestration platforms are collapsing the traditional separation between transportation management and warehouse execution, enabling real-time inventory visibility across fragmented fulfillment networks.
Artificial intelligence-driven demand forecasting is unifying inventory positioning decisions across British and continental European networks. Omnichannel retailers are deploying machine learning models to predict regional demand patterns and pre-position stock. This capability is compressing the competitive advantage of operators with static, geographically fixed warehouse networks.
The UK Border Operating Model's phased implementation of full customs controls is reshaping cross-border logistics infrastructure. Shippers are restructuring supply chains to minimize customs clearance delays at British ports. Food and pharmaceutical verticals are most affected, with operators investing in authorized economic operator accreditation to secure expedited processing.
Service-level agreement structures are evolving toward outcome-based metrics rather than activity-based pricing. Retail and consumer goods buyers are contracting for guaranteed delivery windows and inventory accuracy thresholds rather than per-pallet storage rates. This shift is most visible among large e-commerce retailers operating marketplace platforms with seller-fulfilled prime requirements.
United Kingdom Third Party Logistics (3PL) Market Segmentation
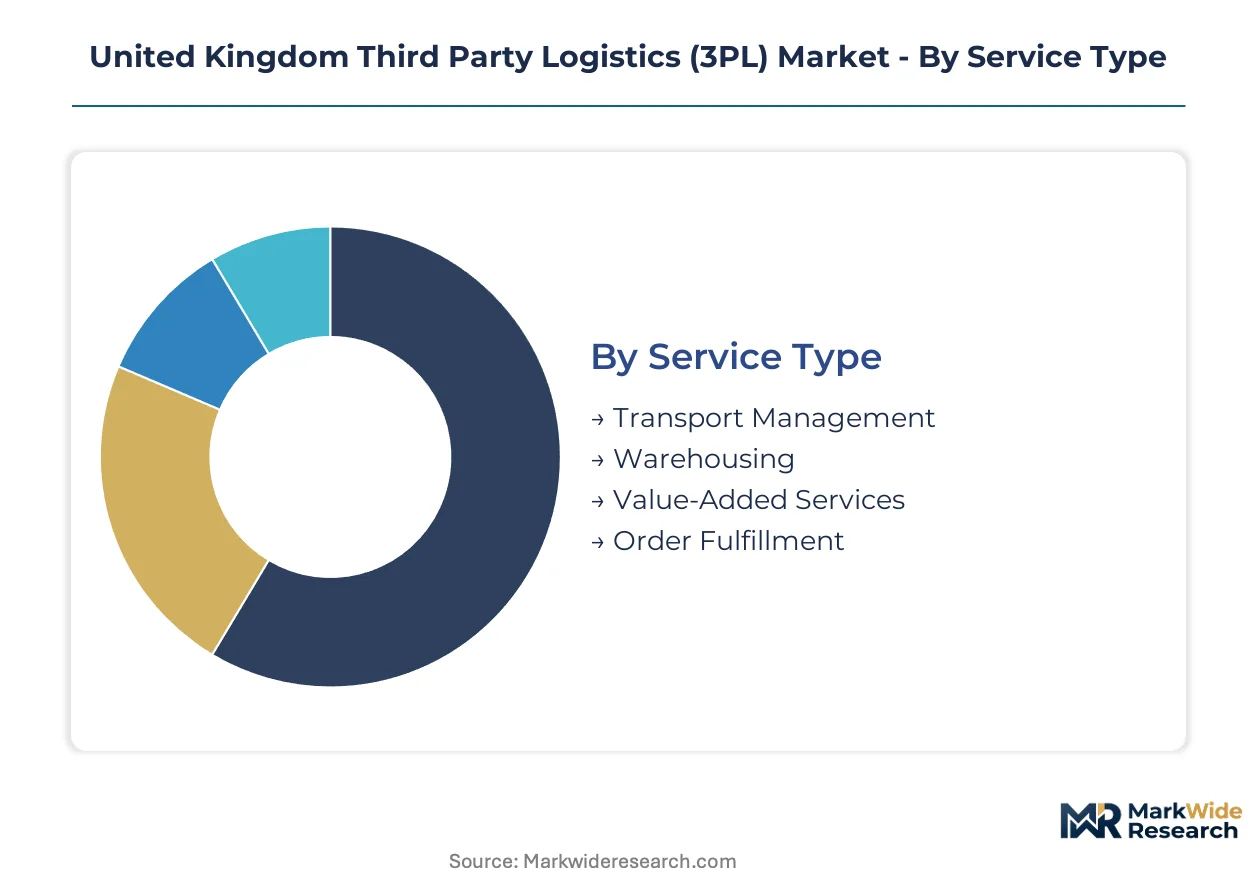
Third-party logistics providers structure their service portfolios around distinct operational capabilities and client requirements. Each segmentation dimension reflects different capital intensity, contract duration, and margin profiles across the UK market.
Service Type:
Upgrade cycles in warehouse automation and transportation management systems are fragmenting service portfolios as clients replace legacy platforms with integrated technology stacks.
- Transport Management:Route optimization platforms consolidate carrier selection, freight audit, and real-time tracking for shippers managing multi-modal networks. Demand concentrates among Midlands-based manufacturers routing goods through the Birmingham-Leicester-Coventry corridor, constrained by Driver CPC compliance costs and Vehicle Excise Duty pressures on fleet renewal.
- Warehousing:Climate-controlled facilities and automated storage systems handle inventory positioning for omnichannel retail and grocery verticals. Investment flows toward the East Midlands where land availability and motorway connectivity support speculative development of speculative Grade A logistics space.
- Value-Added Services:Kitting, labeling, and product customization performed within distribution centers. Food and pharmaceutical clients drive accreditation requirements under HSE automation safety standards.
- Order Fulfillment:Direct-to-consumer picking, packing, and last-mile handoff for e-commerce marketplaces. Same-day delivery promises from London and Manchester-based retailers compress processing windows.
Warehousing sits at the top of the volume ranking, with Value-Added Services climbing the fastest as retailers outsource non-core processing functions.
Industry Vertical:
Application-specific requirements determine facility specifications, labor profiles, and technology investments across vertical segments.
- Retail:Seasonal demand volatility and returns processing complexity characterize contracts with department stores and specialty chains. Peak season staffing surges strain labor markets in Yorkshire distribution clusters.
- Manufacturing:Just-in-time component delivery and vendor-managed inventory programs for automotive and industrial goods producers. The West Midlands automotive corridor generates concentrated demand for sequenced parts delivery.
- E-Commerce:High-velocity fulfillment centers with robotic sortation and same-day delivery capabilities. Marketplace sellers and direct-to-consumer brands are expanding dedicated capacity across England's logistics heartland.
- Automotive:Inbound parts logistics and finished vehicle distribution requiring specialized handling equipment and quality certification. Battery electric vehicle supply chains are reshaping inbound material flows to UK assembly plants.
E-Commerce commands the largest revenue pool, while Automotive is gaining share fastest as electrification transforms parts logistics requirements.
Delivery Model:
Margin structures and capital commitment levels diverge sharply across contract types, with asset ownership patterns determining competitive positioning.
- Dedicated:Exclusive facility and fleet resources contracted to single clients under multi-year agreements. Large grocery retailers and automotive manufacturers anchor this segment with predictable volume commitments.
- Shared:Multi-client facilities with flexible space allocation and pooled transportation capacity. SMEs in the Southeast and Northwest leverage this model to access scale economies without fixed cost exposure.
- On-Demand:Spot-market transportation and surge warehousing capacity activated through digital platforms. E-commerce peak seasons and promotional events drive intermittent utilization.
- Integrated:End-to-end supply chain management combining owned assets with subcontractor networks. Multinationals restructuring post-Brexit supply chains favor this structure for customs brokerage coordination.
Dedicated contracts generate the highest absolute margins, though Shared models are expanding most quickly among mid-market shippers seeking variable cost structures.
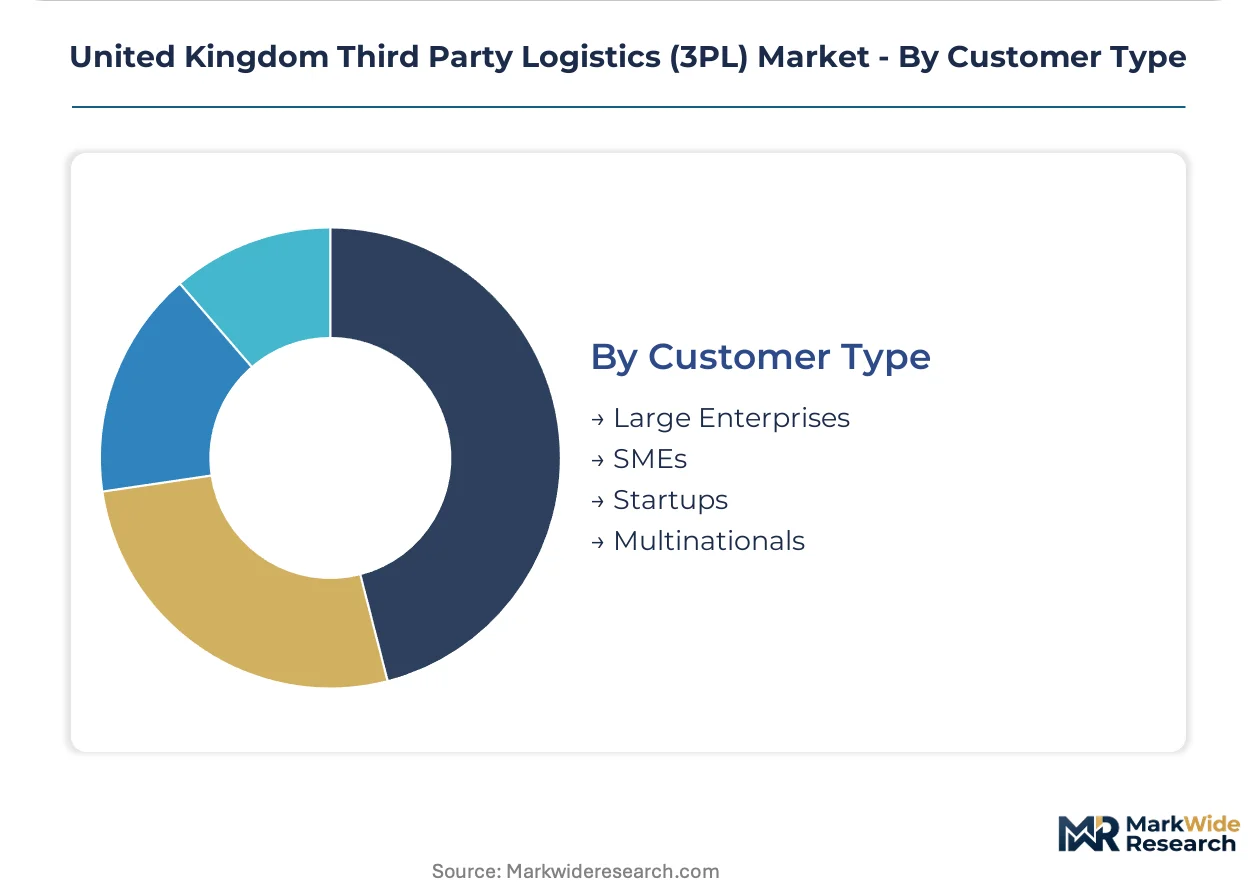
Customer Type:
Procurement sophistication and contract scale create distinct service tiers, with enterprise clients demanding outcome-based metrics unavailable to smaller accounts.
- Large Enterprises:Complex multi-site contracts with customized warehouse management system integration and dedicated account management. Tier-one grocery retailers and national automotive distributors dominate this segment.
- SMEs:Standardized service packages with shorter contract terms and shared infrastructure access. Regional manufacturers and specialty e-commerce brands in the Midlands and North West populate this tier.
- Startups:Flexible, short-term agreements with minimal capital commitment and rapid onboarding protocols. Direct-to-consumer brands testing UK market entry utilize on-demand fulfillment networks.
- Multinationals:Pan-European contracts requiring coordinated inventory positioning across British and continental facilities. Post-Brexit customs complexity has increased demand for bonded warehousing and authorized economic operator status.
Large Enterprises anchor provider revenue, with Multinationals showing the steepest expansion trajectory as supply chains bifurcate across UK-EU borders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Logistics workforce concentration in the Midlands logistics corridor anchors national distribution capacity, with skilled warehouse operatives and HGV drivers clustering around Birmingham, Leicester, and Coventry. This talent density supports the UK's largest concentration of automated fulfillment centers and temperature-controlled food distribution facilities.
London and the Southeast
E-commerce fulfillment demand from marketplace sellers drives same-day delivery infrastructure investment across Greater London and the Thames Valley. The Department for Transport's carbon reporting mandates reshape last-mile routing strategies for operators serving dense urban populations. Dartford and Milton Keynes host speculative Grade A logistics development targeting high-velocity omnichannel retail.
Midlands
Pan-European shippers duplicate inventory holdings here to serve British and EU markets separately post-Brexit. The UK Border Operating Model's phased customs controls accelerate demand for bonded warehousing in the Birmingham-Leicester-Coventry triangle. East Midlands Gateway and Magna Park anchor speculative development of automated fulfillment space for grocery and apparel verticals.
North England
Yorkshire distribution clusters absorb seasonal staffing surges for retail peak periods, straining local labor markets. Health and Safety Executive regulations governing warehouse ergonomics extend facility upgrade timelines for automation projects. Sheffield and Leeds host shared warehousing facilities serving SME manufacturers seeking variable cost structures.
Scotland
Seafood and whisky exports drive cold-chain infrastructure requirements around Aberdeen and the Central Belt. The UK's Driver CPC compliance framework constrains HGV operator availability for long-haul routes connecting Scottish distribution hubs to English markets. Grangemouth anchors petrochemical and bulk liquid logistics serving North Sea energy operations.
Wales
Pharmaceutical manufacturing in South Wales generates specialized temperature-controlled distribution requirements under MHRA oversight. Culina Group maintains dedicated cold-chain infrastructure across England and Wales to serve grocery retail verticals. Cardiff and Newport support cross-border traffic management for Irish Sea routes post-Brexit.
United Kingdom Third Party Logistics (3PL) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across contract structures ranging from dedicated multi-year agreements to on-demand digital platforms. The vendor base organizes around three strategic archetypes: asset-heavy integrated operators owning pan-European networks, temperature-controlled specialists with dedicated cold-chain infrastructure, and technology-forward providers deploying automated warehouse robotics. Consolidation pressure favors operators with balance sheet capacity for speculative Grade A logistics development and customs brokerage accreditation. Geographic expansion and M&A activity dominate competitive moves as shippers restructure post-Brexit supply chains.
Within the integrated logistics tier, DHL Supply Chain and Kuehne + Nagel represent diversified conglomerates with pan-European network density serving omnichannel fulfillment requirements. Culina Group exemplifies the temperature-controlled specialist archetype, sustaining market position through dedicated cold-chain infrastructure across England and Wales. GXO Logistics occupies a position among technology-forward operators, extending automated sortation and robotics capabilities for high-velocity retail clients.
| Leading Market Players |
|---|
| DSV |
| Yusen Logistics |
| DHL Supply Chain |
| Culina Group |
| Rhenus Logistics |
| Kuehne + Nagel |
| CEVA Logistics |
| DB Schenker |
| GXO Logistics |
| Others |
Value Network & Pricing Analysis
The Department for Transport's carbon reporting mandates gate both qualified supply and premium-tier pricing access, as operators investing in emissions disclosure infrastructure secure preferential contracts with sustainability-focused grocery retailers and multinational shippers while legacy fleets face margin compression from progressive Vehicle Excise Duty frameworks.
Pricing Analysis
The bundled-vs-unbundled service split defines contract economics across the UK 3PL landscape, with integrated end-to-end solutions commanding three-tier pricing structure across premium, standard, and economy levels based on automation sophistication and customs brokerage accreditation. Price differentiation hinges on authorized economic operator status and warehouse robotics deployment, with premium tiers capturing multinational clients restructuring post-Brexit supply chains. Cost compression in shared warehousing models is intensifying because SME buyers consolidate fragmented logistics spend. Marketplace sellers and direct-to-consumer startups exhibit highest price sensitivity, while tier-one grocery retailers prioritize service-level guarantees over per-unit rates.
Supply Chain Analysis
Logistics and freight cost pressures concentrate supply chain leverage around the Midlands logistics corridor, where land scarcity and motorway connectivity advantages inflate facility rents across Birmingham, Leicester, and Coventry. The UK 3PL ecosystem draws from Dutch bonded warehousing infrastructure, Irish Sea port capacity, and French cross-channel freight terminals for pan-European coordination. Critical dependencies include HGV operator labor pools, automated sortation equipment, and temperature-controlled trailer fleets. Single-source vulnerability runs through the Driver CPC compliance pipeline constraining qualified labor availability. Distribution feeds from East Midlands Gateway and Magna Park through spoke networks serving retail fulfillment centers and grocery regional distribution hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK 3PL market offers margin expansion through automation-driven cost reduction in high-velocity fulfillment centers and premium-tier pricing capture among multinationals requiring customs brokerage integration.
For Market Incumbents: Deepen automated warehouse robotics deployment to defend against technology-forward entrants capturing omnichannel retail contracts. Consolidate Midlands logistics corridor capacity through speculative Grade A development to anchor dedicated agreements with grocery retailers. Invest in authorized economic operator accreditation to secure expedited customs processing under the UK Border Operating Model. For New Entrants and Emerging Players: The UK Border Operating Model's phased customs controls in the United Kingdom opens a window for bonded warehousing specialization serving food and pharmaceutical verticals. Target SME manufacturers in Yorkshire and the North West seeking shared infrastructure without fixed cost exposure. Lead with digital orchestration platforms offering real-time inventory visibility as the primary go-to-market wedge. For Investors and Strategic Acquirers: Roll-up economics work for temperature-controlled specialists because cold-chain infrastructure scarcity and grocery retail concentration create defendable local moats. Five-to-ten-year viability centers on operators with balance sheet capacity for customs brokerage accreditation and automation capex cycles. Monitor Driver CPC compliance rates as the inflection signal for labor-constrained pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Warehouse Robotics Deployment | GXO Logistics extends autonomous mobile robot fleets to compress order fulfillment windows for high-velocity retail clients. |
| Bonded Warehousing Capacity Expansion | Culina Group and DHL Supply Chain secure authorized economic operator status to expedite food and pharmaceutical customs processing. |
| Midlands Logistics Corridor Land Acquisition | Speculative Grade A development around East Midlands Gateway anchors dedicated contracts with tier-one grocery retailers. |
| Returns Processing Specialization | Apparel and electronics verticals create premium pricing opportunities through reverse logistics capability gaps. |
| Carbon Reporting Advisory Services | Department for Transport mandates generate route optimization and modal shift consulting revenue streams. |
Research Methodology
Direct dialogue with warehouse operations directors, HGV fleet managers, grocery retail supply chain executives, and customs brokerage specialists grounded the qualitative foundation of this study. Secondary validation drew from UK Border Operating Model documentation, Health and Safety Executive automation safety standards, Department for Transport emissions disclosure frameworks, and Vehicle Excise Duty regulatory filings. Bottom-up facility capacity assessments and top-down national logistics spend estimates were triangulated against trade flow data and bonded warehousing license registers.
Segment-level projections across service type, industry vertical, delivery model, and customer type dimensions were generated through the analytical framework spanning the projection horizon. CAGRs were derived from regression analysis against e-commerce fulfillment density trends, Driver CPC compliance rate trajectories, and cold-chain infrastructure investment pipelines. Forecast inputs incorporated Midlands logistics corridor land availability constraints and post-Brexit inventory duplication patterns affecting working capital requirements.
Revisions become necessary when UK-EU trade agreement modifications, carbon reporting mandate acceleration, or warehouse automation technology cost curves materialize differently than modeled. Forecasts reflect documented assumptions about labor market tightness and customs processing efficiency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
United States 3PL Market
Logistics and Shipping
Poland Cold Chain Logistics Market
Logistics and Shipping
Chile Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Spare Part Logistics Market
Logistics and Shipping
Sweden Cold Chain Logistics Market
Logistics and Shipping
Control Towers Market
Logistics and Shipping
India Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Global Container Terminal Operations Market
Logistics and Shipping
Czech Republic Third-Party Logistics Market
Logistics and Shipping
LAOS Freight and Logistics Market
Logistics and Shipping
Saudi Arabia Freight and Logistics Market
Logistics and Shipping
UK Logistics Market
Logistics and Shipping
High-Tech Logistics Market
Logistics and Shipping
Global 5PL Solutions Market
Logistics and Shipping
Turkey Third Party Logistics (3PL) Market
Logistics and Shipping
Vietnam Courier, Express, and Parcel (CEP) Market