
 Latin America Freight Forwarding Market | 2026-2036
Latin America Freight Forwarding Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Freight Forwarding Market Insights
Digital documentation platforms are rebalancing traditional paper-based customs clearance economics across Latin American trade lanes. Bollore Logistics Mexico leverages integrated port-to-port networks along the Pacific corridor. Nuvocargo anchors its position through specialized cross-border trucking technology between Mexico and the United States. GRECARGO dominates agricultural export lanes from Brazil's interior to Santos port terminals.
Freight forwarding encompasses the coordination of multi-modal cargo movement across international boundaries, encompassing customs brokerage, carrier negotiation, and shipment consolidation with cargo tracking specifications tied to ISO container standards and temperature-controlled protocols for perishables. The service structures ocean freight as the volume anchor for bulk commodities while air freight captures premium pharmaceutical and electronics shipments. Customer type segmentation shows manufacturers sustaining the largest contract base, though e-commerce channels are expanding fastest among small-lot importers.
ANVISA in Brazil and COFEPRIS in Mexico enforce pharmaceutical shipment integrity standards that dictate cold-chain documentation requirements across regional forwarding contracts. The International Maritime Organization's container weight verification rules and individual country customs modernization programs reshape compliance costs for logistics providers. Stakeholders must monitor how nearshoring manufacturing shifts alter lane density patterns between Mexico and Central American transshipment hubs.
Market Dynamics
Nearshoring manufacturing relocations from Asia to Mexico are compressing cross-border freight volumes through Laredo-Nuevo Laredo corridors while reshaping carrier capacity allocation across Central American transshipment nodes. This geographic demand rotation forces logistics providers to rebalance asset positioning between Pacific and Atlantic port gateways.
Growth Catalysts
- ANVISA cold-chain mandates:Brazil's pharmaceutical integrity standards enforce temperature-controlled documentation across regional forwarding contracts, elevating compliance-driven service premiums for certified operators.
- Cross-border e-commerce platforms:Digital marketplace cargo volumes are accelerating small-lot consolidation demand across Mexico's manufacturing corridor from Tijuana to Monterrey.
- Reonave maritime updates:Brazil's tightened vessel documentation requirements for coastal operators are filtering informal carriers and concentrating volume with compliant fleet owners.
Market Restraints
- Fuel cost volatility:Diesel price swings across Brazil and Mexico directly compress trucking margins for overland freight operators lacking fuel surcharge mechanisms.
- Port concentration risk:Santos and Manzanillo handle disproportionate container volumes, creating bottleneck vulnerability during labor disputes or weather disruptions.
- Customs modernization friction:Incomplete digitization of Mexico's VUCEM platform and Brazil's Siscomex generates documentation delays that erode just-in-time reliability.
Strategic Opportunities
- Central American transshipment hubs:Panama's Colon Free Trade Zone and Costa Rica's logistics parks offer underutilized capacity for Asia-Mexico cargo relay.
- COFEPRIS pharmaceutical alignment:Harmonized cold-chain standards between Mexican and US regulators create regulatory tailwinds for integrated North American health logistics.
- Blockchain-IoT convergence:Immutable documentation combined with real-time container sensing is expanding into high-value agricultural export lanes from Brazil's interior.
Industry Challenges
- Customs brokerage talent scarcity:Specialized knowledge of ANVISA and COFEPRIS pharmaceutical protocols outpaces training pipeline capacity across São Paulo and Mexico City labor markets.
- Legacy system integration:Forwarders struggle to connect proprietary TMS platforms with port community systems and carrier EDI networks without middleware fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Freight Forwarding Market |
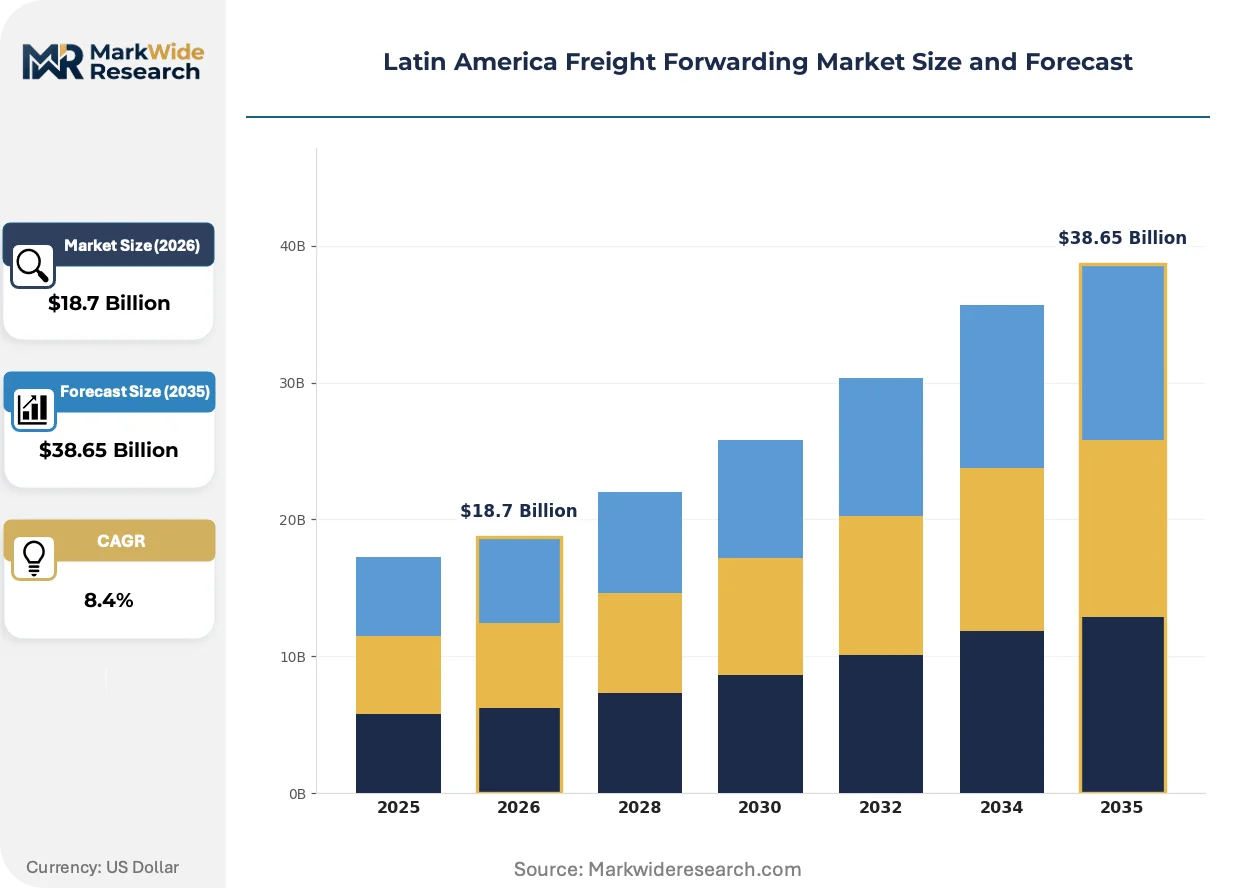
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Air Freight, Ocean Freight, Road Freight, Rail Freight Customer Type: Manufacturers, Retailers, Wholesalers, E-commerce End User: Automotive Industry, Pharmaceuticals, Electronics, Agriculture Delivery Model: Door-to-Door, Port-to-Port, Airport-to-Airport, Terminal-to-Terminal |
| Companies Covered | Grupo Logístico Especializado, Imexlog, Bollore Logistics Mexico, Sea Cargo Logistics SA de CV, GoldCargo, Nuvocargo, GRECARGO, FC Cargo, Forderline, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Freight Forwarding Market Trends and Innovations
Digital documentation platforms are actively displacing paper-based customs clearance across Latin American trade lanes, compressing processing timelines while elevating data interoperability requirements for multi-modal operators.
Blockchain-enabled trade documentation is expanding into cross-border freight contracts, creating immutable audit trails for pharmaceutical and agricultural shipments. Large manufacturers with complex supplier networks are adopting these platforms fastest, particularly for Brazil-Europe coffee and soybean exports. The technology is expanding into customs brokerage service tiers, compressing price premiums previously attached to expedited clearance.
ANVISA and COFEPRIS pharmaceutical integrity standards are tightening cold-chain documentation requirements across regional forwarding contracts. These mandates force logistics providers to deploy temperature logging at pallet level rather than container level, elevating equipment capital intensity. Pharmaceutical manufacturers operating across São Paulo, Mexico City, and Buenos Aires corridors are consolidating supplier relationships with certified cold-chain specialists.
Shipper procurement patterns are compressing contract durations from annual to quarterly cycles, reflecting volatility in capacity pricing and lane reliability. E-commerce platforms and automotive suppliers are driving this shift, replacing long-term rate agreements with spot-market flexibility. Mexico's manufacturing corridor linking Tijuana to Monterrey exhibits the most pronounced procurement cycle compression.
Latin America Freight Forwarding Market Segmentation
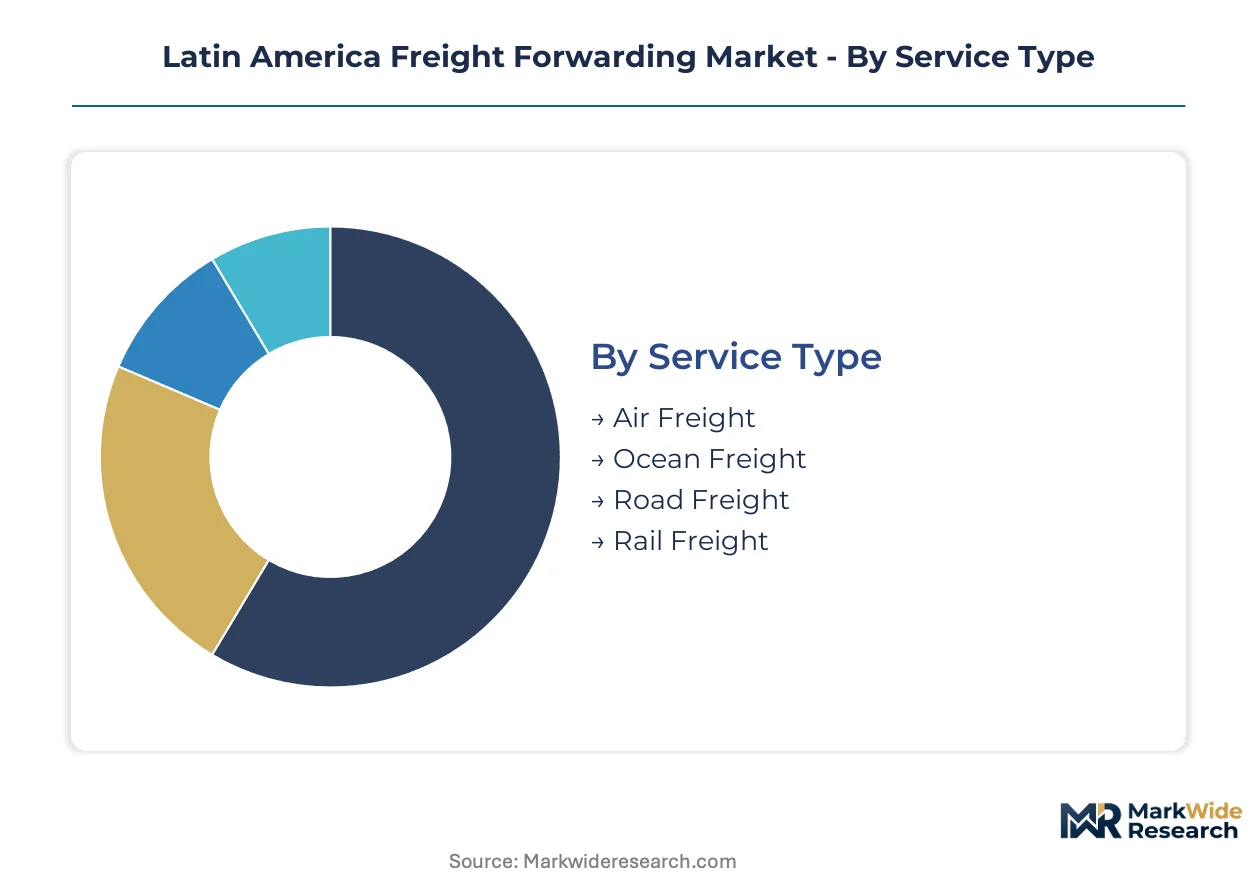
Freight forwarding segmentation in Latin America reveals how service specialization, customer procurement patterns, and regulatory requirements create distinct operational economics across modal and delivery configurations. Understanding these divisions exposes where margin compression and premium pricing opportunities concentrate for logistics providers.
Service Type:
Customization intensity varies sharply across this category, from standardized ocean container movements to highly tailored air freight protocols for temperature-sensitive cargo.
- Ocean Freight:Full-container-load and less-than-container-load movements dominate bulk commodity flows across Pacific and Atlantic corridors. Santos and Manzanillo terminals anchor volume concentration, though Reonave documentation requirements are filtering informal coastal operators and consolidating share with compliant fleet owners.
- Air Freight:Temperature-controlled pharmaceutical and electronics shipments command premium pricing through dedicated cargo terminals. ANVISA and COFEPRIS cold-chain mandates are elevating certification barriers, restricting this segment to operators with pallet-level logging capabilities.
- Road Freight:Cross-border trucking networks link manufacturing clusters to port gateways, with diesel cost volatility compressing margins for operators lacking fuel surcharge mechanisms.
- Rail Freight:Bulk mineral and agricultural movements from Brazil's interior to coastal terminals offer cost advantages over trucking for high-volume, low-velocity cargo.
Most installed capacity flows through Ocean Freight. Expansion is steepest in Air Freight.
Customer Type:
Contract scale and procurement sophistication divide this category, from multinational manufacturers with integrated supply chains to fragmented e-commerce platforms demanding flexible consolidation.
- Manufacturers:Automotive and electronics producers sustain the largest contract base with annual rate agreements and dedicated lane commitments. Nearshoring relocations to Mexico are compressing these contracts toward quarterly cycles as procurement teams seek spot-market flexibility.
- E-commerce:Digital marketplace sellers generate fastest-growing small-lot consolidation demand across Tijuana-Monterrey corridor. These shippers prioritize speed over cost, accepting premium pricing for expedited cross-border clearance.
- Retailers:Seasonal inventory replenishment drives concentrated demand spikes, requiring forwarders to maintain surge capacity for peak periods.
- Wholesalers:Intermediate distributors balance cost sensitivity with reliability requirements, often splitting volume between multiple forwarders to mitigate concentration risk.
Revenue concentration remains heaviest among Manufacturers. Customer acquisition costs are climbing fastest for E-commerce.
End User:
Regulatory intensity and cargo value density create divergent service requirements across this category, from standardized automotive parts movements to pharmaceutical shipments demanding continuous chain-of-custody documentation.
- Pharmaceuticals:ANVISA and COFEPRIS enforcement of temperature integrity standards mandates specialized cold-chain infrastructure. São Paulo and Mexico City corridors exhibit tight supplier consolidation as manufacturers narrow forwarder relationships to certified specialists.
- Automotive Industry:Just-in-time assembly plant feeds require precise scheduling across Laredo-Nuevo Laredo border crossings. Procurement teams are shortening contract durations to preserve flexibility amid capacity volatility.
- Electronics:High-value semiconductor and consumer device shipments favor air freight for velocity-sensitive components, with blockchain-IoT documentation expanding for audit trail requirements.
- Agriculture:Coffee and soybean exports from Brazil's interior to European markets leverage ocean freight economies, with digital documentation platforms displacing paper-based customs processes.
Compliance investment is deepest in Pharmaceuticals. Volume expansion is most pronounced in Automotive Industry.
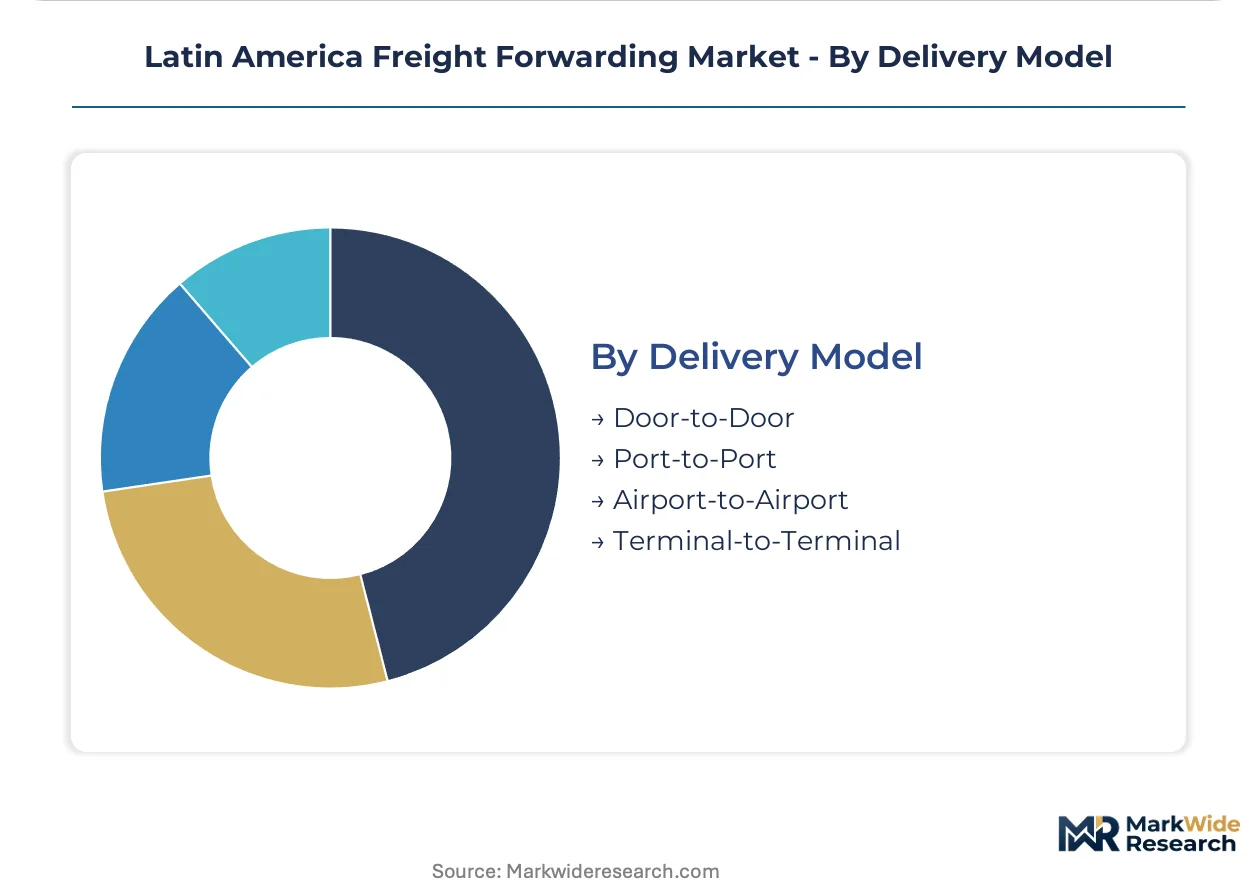
Delivery Model:
Control point configuration determines liability allocation and margin structure across this category, from comprehensive door-to-door responsibility to limited terminal handoffs.
- Door-to-Door:Comprehensive liability from shipper facility to consignee destination commands premium pricing and requires integrated multi-modal coordination. Large manufacturers with complex supplier networks are adopting these arrangements fastest.
- Port-to-Port:Maritime-focused contracts concentrate risk at vessel loading and discharge points, with Bollore Logistics Mexico leveraging Pacific corridor networks for competitive positioning.
- Airport-to-Airport:Air cargo liability boundaries suit time-critical pharmaceutical and electronics shipments where ground distribution is managed separately.
- Terminal-to-Terminal:Lowest-cost option limits forwarder responsibility to facility transfers, appealing to price-sensitive wholesalers with established drayage relationships.
Contract value aggregates most heavily in Door-to-Door. Margin pressure is intensifying fastest in Terminal-to-Terminal.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Tijuana-Monterrey manufacturing corridor concentrates nearshoring-driven freight volumes across Mexico's northern industrial belt. Cross-border cargo flows through Laredo-Nuevo Laredo gateways are reshaping carrier capacity allocation throughout Central American transshipment nodes. This geographic demand rotation elevates strategic importance for Pacific and Atlantic port connectivity across the region.
Brazil
Agricultural export volumes from the interior to Santos port terminals anchor ocean freight demand for bulk commodities. ANVISA pharmaceutical integrity standards enforce temperature-controlled documentation requirements that elevate compliance costs for certified operators. São Paulo's logistics clusters exhibit tight supplier consolidation as manufacturers narrow forwarder relationships to cold-chain specialists.
Mexico
Automotive and electronics manufacturing relocations from Asia are compressing cross-border trucking volumes through Laredo-Nuevo Laredo corridors. COFEPRIS cold-chain mandates align with US FDA standards, creating regulatory tailwinds for integrated North American health logistics. The Bajío Region's industrial parks generate concentrated small-lot consolidation demand from e-commerce platform shippers.
Argentina
Grain and soybean exports through Rosario port terminals sustain bulk ocean freight contract volumes for agricultural commodity traders. The national customs modernization program generates documentation friction that erodes just-in-time reliability for manufacturing supply chains. Buenos Aires pharmaceutical corridors exhibit supplier consolidation patterns similar to São Paulo and Mexico City markets.
Chile
Copper concentrate and lithium carbonate exports drive specialized bulk freight demand through Antofagasta and Valparaíso port gateways. The country's central bank monitors peso volatility impacts on import financing costs for capital equipment shipments. Santiago's logistics infrastructure connects Pacific transshipment routes to Andean mining clusters in the northern desert regions.
Colombia
Flower and coffee exports through Bogotá air cargo terminals command premium pricing for temperature-sensitive agricultural shipments. The national trade facilitation program targets customs digitization to compress clearance timelines for manufacturing inputs. Medellín's industrial corridor links Andean production zones to Caribbean coast container terminals.
Latin America Freight Forwarding Market Competitive Landscape
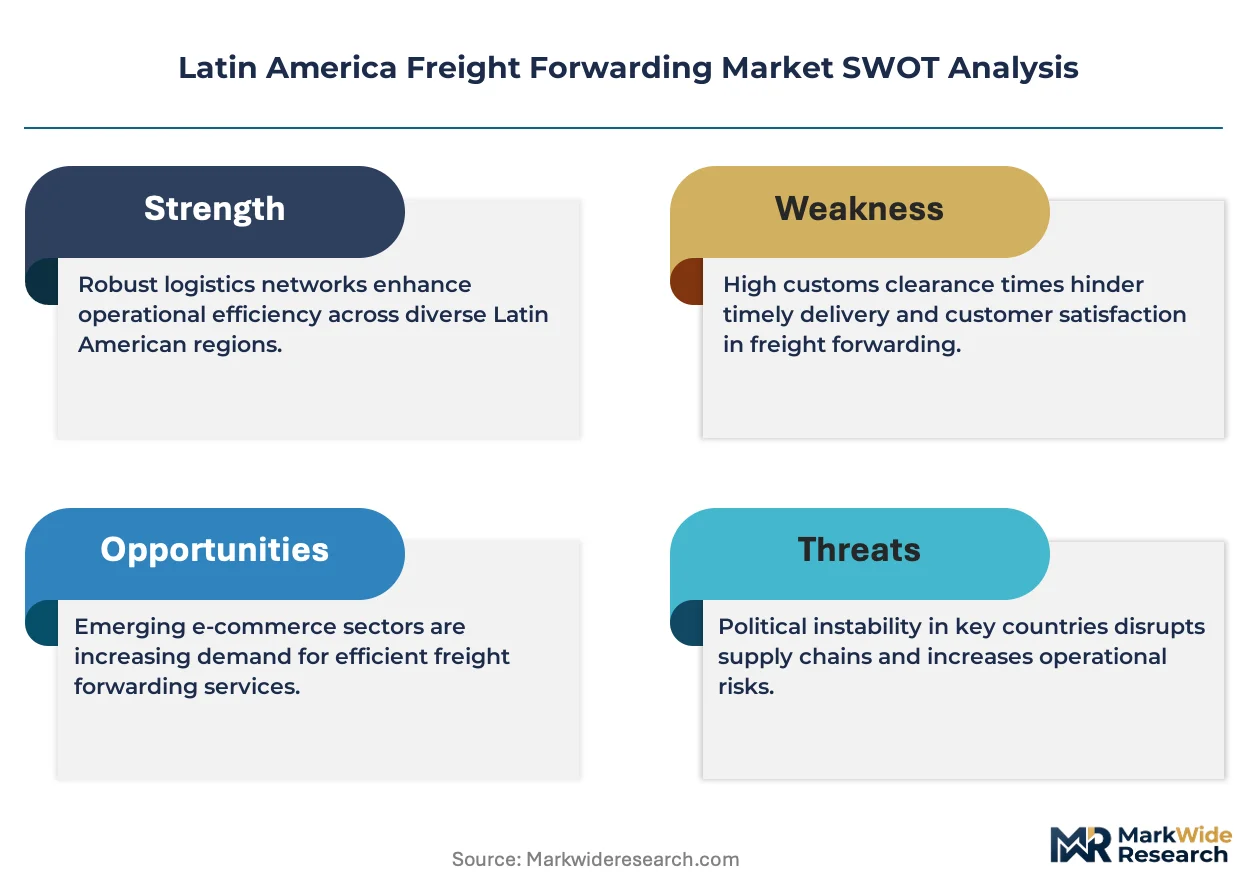
Global majors compete with regional champions across multi-modal network coverage and specialized compliance capabilities. The vendor base organizes into three tiers: integrated port-to-port operators with Pacific corridor dominance, cross-border trucking technology specialists, and agricultural export lane dominators with interior Brazil coverage. Strategic differentiation concentrates on M&A-driven network expansion and proprietary digital documentation platform deployment.
Within the integrated logistics tier, Bollore Logistics Mexico and Nuvocargo exemplify contrasting archetypes. Bollore Logistics Mexico occupies a position representing established port-to-port network operators leveraging Pacific corridor infrastructure. Nuvocargo anchors the cross-border technology specialist segment with specialized trucking platform capabilities between Mexico and the United States. GRECARGO sits within the agricultural export lane category, representing operators dominating bulk commodity flows from Brazil's interior to coastal terminals.
| Leading Market Players |
|---|
| Grupo Logístico Especializado |
| Imexlog |
| Bollore Logistics Mexico |
| Sea Cargo Logistics SA de CV |
| GoldCargo |
| Nuvocargo |
| GRECARGO |
| FC Cargo |
| Forderline |
| Others |
Pricing and Supply Chain Analysis
Certification-tier divergence between ANVISA-compliant cold-chain operators and generalist forwarders manifests in both rate premiums and asset deployment patterns across São Paulo and Mexico City corridors. This bifurcation concentrates pricing power with certified specialists while compressing margins for commodity ocean freight providers lacking temperature-controlled capabilities.
Pricing Analysis
Diesel cost pass-through limitations in Brazil and Mexico compress trucking margins for operators without fuel surcharge mechanisms in contract structures. Three-tier pricing structure across premium certified, standard integrated, and economy spot-market levels reflects ANVISA and COFEPRIS compliance gradients. Pricing pressure stems from procurement cycle compression toward quarterly agreements as manufacturers seek flexibility. E-commerce platforms exhibit lowest price sensitivity, accepting expedited clearance premiums, while bulk agricultural exporters drive hardest rate negotiations.
Supply Chain Analysis
Dual-sourcing requirements from pharmaceutical manufacturers mandate multi-forwarder qualification across São Paulo, Mexico City, and Buenos Aires corridors to mitigate concentration risk. Supply concentration centers on Brazil for agricultural exports, Mexico for nearshoring manufacturing inputs, and Chile for mining logistics. Vessel fuel, refrigerated container equipment, and cross-border trucking capacity constitute critical input dependencies. Single-source vulnerability at Santos and Manzanillo ports creates bottleneck exposure. Distribution runs through Pacific and Atlantic gateway terminals with Central American transshipment relay.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Latin America freight forwarding market compounds steadily as nearshoring manufacturing relocations from Asia to Mexico generate durable lane density expansion across the Laredo-Nuevo Laredo corridor.
For Market Incumbents: Acquire specialized cold-chain certification assets to defend against pharmaceutical manufacturer supplier consolidation toward ANVISA and COFEPRIS specialists. Reinforce Pacific corridor port-to-port network density through integrated TMS platform deployment that connects proprietary systems with carrier EDI networks without middleware fragmentation.
For New Entrants and Emerging Players: Enter via Central American transshipment hub specialization targeting underutilized capacity at Panama's Colon Free Trade Zone and Costa Rica's logistics parks for Asia-Mexico cargo relay. Target cross-border e-commerce consolidation as the most penetrable segment, leveraging digital documentation platforms to compress customs clearance timelines for small-lot Tijuana-Monterrey corridor shippers.
For Investors and Strategic Acquirers: Consolidation pressure builds where customs brokerage talent scarcity outpaces training pipeline capacity for ANVISA and COFEPRIS pharmaceutical protocols. Long-term viability favors vertically integrated operators with captive cold-chain equipment fleets and proprietary blockchain-IoT documentation platforms. Watch procurement cycle compression toward quarterly agreements as the inflection signal for spot-market platform valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Certification Investment | ANVISA and COFEPRIS compliance unlocks pharmaceutical manufacturer supplier consolidation toward certified operators. |
| Blockchain-IoT Platform Deployment | Immutable documentation combined with real-time container sensing expands into Brazil-Europe agricultural export lanes. |
| Central American Hub Capacity Activation | Panama's Colon Free Trade Zone offers underutilized relay capacity for Asia-Mexico nearshoring cargo flows. |
| Cross-Border Trucking Technology Integration | Specialized platforms between Mexico and the United States compress Laredo-Nuevo Laredo clearance timelines. |
| Multi-Forwarder Qualification Programs | Pharmaceutical manufacturers mandate dual-sourcing across São Paulo and Mexico City to mitigate concentration risk. |
Research Methodology
Direct dialogue with freight forwarding operations directors, customs brokerage managers, pharmaceutical supply chain leads, and ocean carrier commercial executives grounded qualitative insights across the analysis window. Secondary validation drew from ANVISA regulatory filings, COFEPRIS pharmaceutical guidance documents, Brazilian Reonave maritime updates, Mexican customs modernization program disclosures, and port authority throughput statistics. Bottom-up carrier capacity assessments and top-down regional trade flow estimates were triangulated to anchor segmentation outputs.
Segmentation outputs reflect modeled dimensions across service type, customer procurement sophistication, end-use regulatory intensity, and delivery model liability configuration throughout the projection horizon. CAGRs were derived from trade volume elasticity to manufacturing relocation patterns and e-commerce platform cargo expansion. Forecast inputs incorporated diesel price volatility assumptions and customs digitization adoption curves for VUCEM and Siscomex platforms.
Inputs from carrier EDI networks and port community systems were available through the study window; gaps in informal coastal operator documentation introduce uncertainty bands around Brazil's interior-to-Santos volume estimates. Forecasts reflect documented assumptions regarding nearshoring momentum and regulatory enforcement consistency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Latin America Logistics Market
Logistics and Shipping
Japan Cross-Border E-Commerce Logistics Market
Logistics and Shipping
Canada 3PL Market
Logistics and Shipping
Inland Container Depot and Dry Port Market
Logistics and Shipping
Germany Third-Party Logistics (3PL) Market
Logistics and Shipping
Roll Trailer Market
Logistics and Shipping
Nigeria Freight and Logistics Market
Logistics and Shipping
Hong Kong Container Transshipment Market
Logistics and Shipping
Sweden Cold Chain Logistics Market
Logistics and Shipping
Jordan Freight and Logistics Market
Logistics and Shipping
Asia-Pacific less-Than Container Load (LCL) Market
Logistics and Shipping
Total Logistics Market
Logistics and Shipping
Contract Logistics Market
Logistics and Shipping
US Hazardous Goods Logistics Market
Logistics and Shipping
US Air Freight Transport Market
Logistics and Shipping
Nigeria Courier, Express, and Parcel (CEP) Market