
 Australia 3PL Market | 2026-2036
Australia 3PL Market Size, Share, and Industry Trends Forecast 2026-2036
Australia 3PL Market Outlook
The capital-intensity divergence between automated fulfillment networks and conventional asset-light brokerage models is unwinding competitive assumptions across the sector. DHL Supply Chain (Australia) leverages its automated distribution centers near Melbourne to anchor high-velocity retail contracts. Linfox Pty Ltd sustains its dominance in temperature-controlled logistics through proprietary fleet ownership across eastern seaboard corridors. Mainfreight Australia differentiates via its integrated domestic-international forwarding platform, while Toll Holdings Limited competes through legacy infrastructure scale in rail-port intermodal links.
Third-party logistics (3PL) in Australia encompasses outsourced supply chain management where providers assume operational control of transportation, warehousing, and inventory coordination on behalf of client enterprises, typically governed by service-level agreements specifying order accuracy thresholds, delivery time windows, and inventory turnover benchmarks. The primary commercial purpose centers on converting fixed logistics costs into variable expenditures while injecting specialized operational expertise that individual shippers rarely maintain in-house. Transportation and warehousing services command the largest revenue pools within the service-type dimension, though fulfillment is accelerating fastest as direct-to-consumer order profiles reshape network design requirements. Within industry verticals, e-commerce and retail together absorb the majority of contracted capacity, while healthcare logistics commands premium margin structures due to cold-chain compliance and serialized tracking mandates.
The National Heavy Vehicle Regulator enforces chain-of-responsibility legislation that extends liability to consigners and loaders, compelling 3PL providers to invest in mass-management technology and driver fatigue monitoring systems. Standards Australia coordinates technical specifications for palletized freight interoperability, shaping equipment procurement decisions across the national fleet. The Therapeutic Goods Administration imposes serialization and temperature-integrity requirements on pharmaceutical logistics contracts, creating compliance barriers that favor established operators with validated quality management systems. Stakeholders must monitor how the proposed federal freight and supply chain strategy reshapes infrastructure prioritization, particularly regarding inland rail terminal access and last-mile electrification timelines.
Market Dynamics
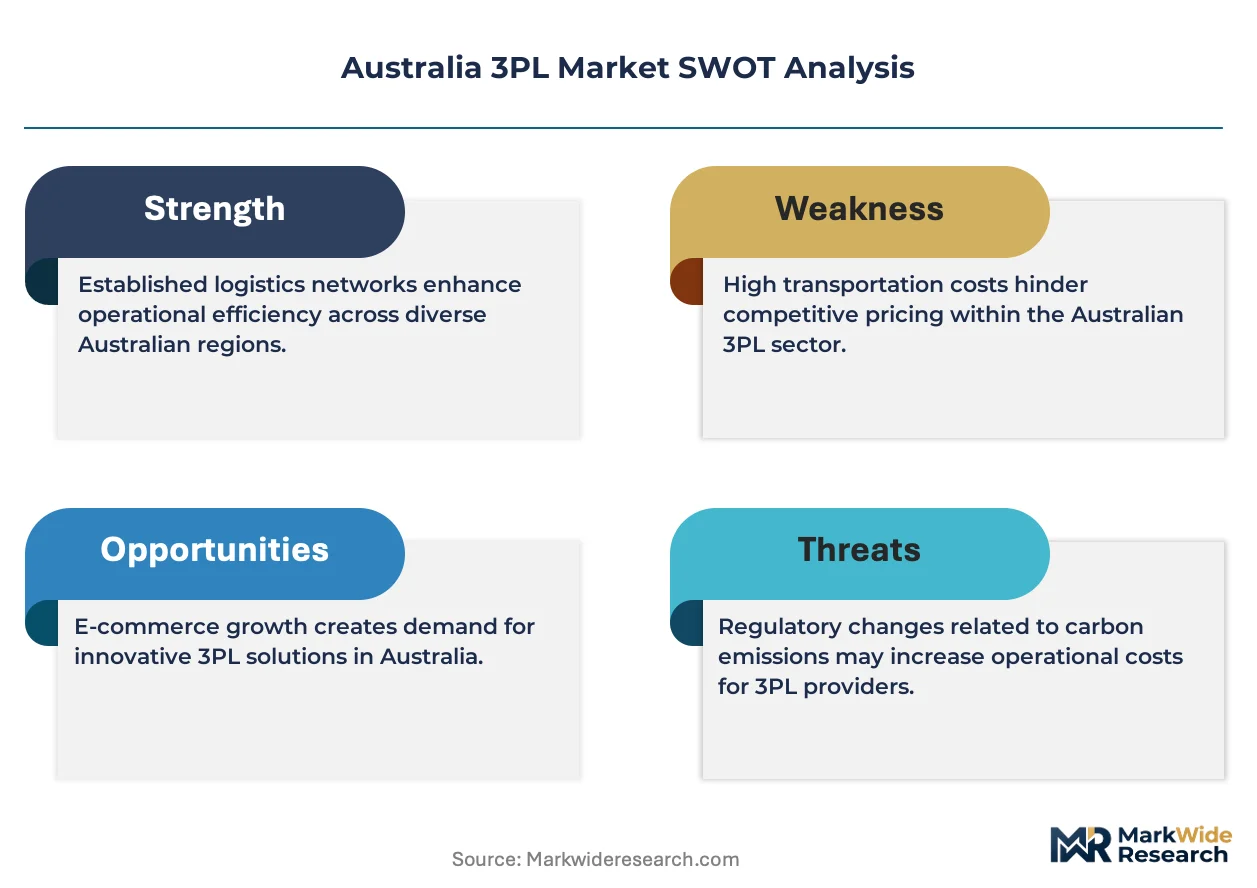
The National Heavy Vehicle Regulator's chain-of-responsibility enforcement is compressing operational margins while forcing capital redeployment into compliance infrastructure across Australian road freight networks.
Growth Catalysts
- E-commerce fulfillment surge:Direct-to-consumer order volumes from Australian retail verticals are accelerating warehouse automation investments and same-day delivery network densification in Sydney and Melbourne corridors.
- Therapeutic Goods Administration serialization mandates:Pharmaceutical cold-chain compliance requirements are locking in long-term contracts with validated quality management systems, favoring established 3PL operators over new entrants.
- Inland Rail terminal access:Federal infrastructure prioritization along the Melbourne-Brisbane corridor is shifting intermodal freight volumes from road to rail, opening terminal-adjacent warehousing opportunities.
Market Restraints
- Fuel cost volatility:Diesel price fluctuations directly compress transport margins for asset-heavy operators running proprietary fleets across eastern seaboard corridors.
- Driver availability constraints:Heavy vehicle license pipeline limitations in New South Wales and Victoria are constraining capacity expansion regardless of equipment investment.
- Warehouse land scarcity:Industrial zoned land availability near Port Botany and Port of Melbourne is structurally limited, inflating facility costs beyond regional benchmarks.
Strategic Opportunities
- Queensland corridor underpenetration:Brisbane and regional Queensland present whitespace for temperature-controlled distribution networks serving agricultural and mining supply chains.
- Last-mile electrification incentives:State-level fleet decarbonization programs are creating first-mover advantages for 3PL providers deploying electric delivery vehicles in metropolitan Sydney and Melbourne.
- Healthcare logistics premiumization:Biopharma clinical trial logistics and cell therapy cold-chain requirements represent high-margin service expansion beyond standard pharmaceutical distribution.
Industry Challenges
- Warehouse management system integration:Legacy enterprise resource planning architectures at mid-market Australian retailers create data interoperability friction with modern 3PL platforms.
- Certified cold-chain technician scarcity:Qualified personnel for pharmaceutical temperature-integrity monitoring and GDP compliance are concentrated among incumbent operators, constraining service expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia 3PL Market |
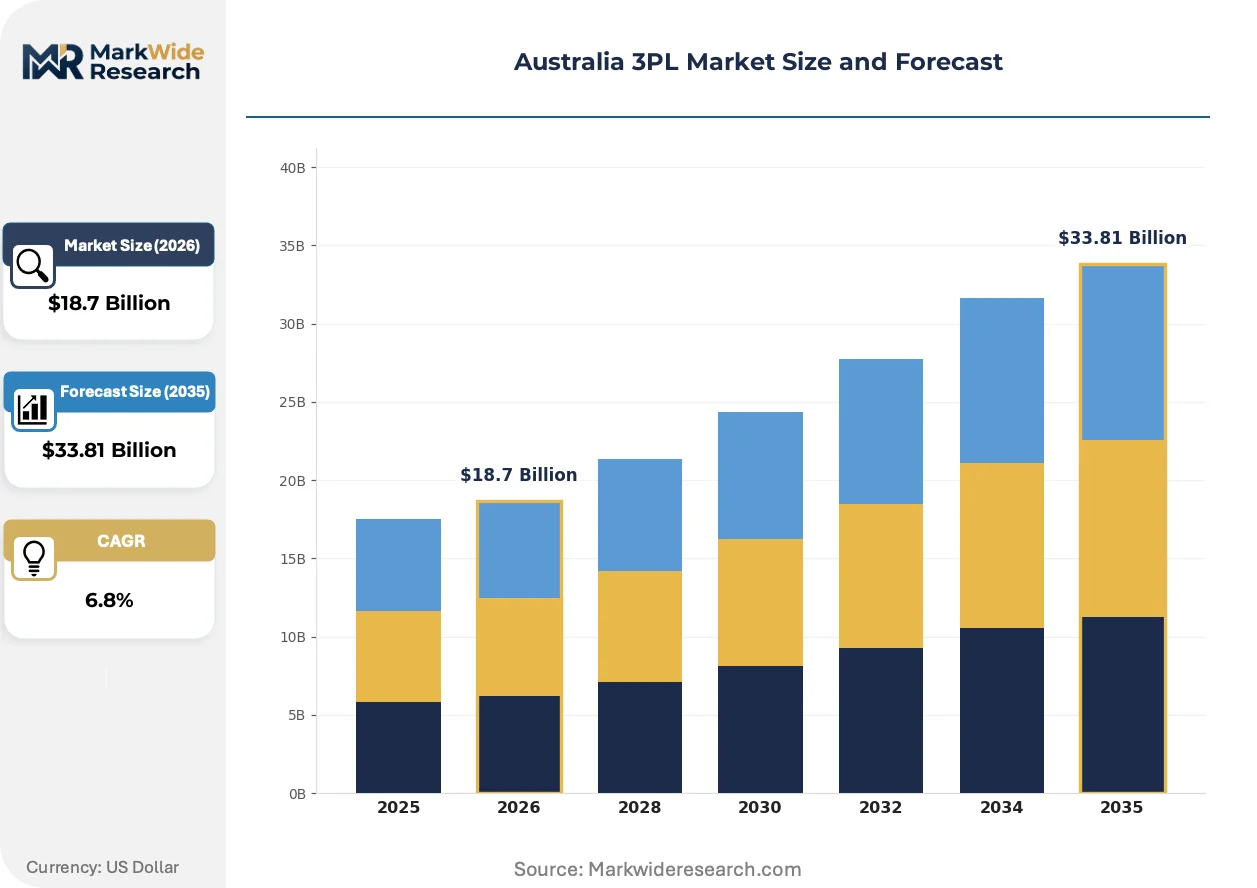
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Fulfillment, Value-Added Services Industry Vertical: Retail, Manufacturing, Healthcare, E-Commerce Client Type: SMEs, Large Enterprises, Startups, Corporates Technology: Automation, IoT, WMS, TMS |
| Companies Covered | DSV, eStore Logistics, Toll Holdings Limited, ACFS Port Logistics, CEVA Logistics (Australia), Linfox Pty Ltd, Mainfreight Australia, Yusen Logistics (Australia), DHL Supply Chain (Australia), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia 3PL Market Strategic Shifts
Automation and regulatory compliance technology are restructuring capital allocation across Australian 3PL networks, with differentiation shifting from scale economies to validated operational precision.
Autonomous mobile robots in high-velocity picking operations are displacing conventional conveyor-and-picker configurations in Sydney and Melbourne distribution centers. Mid-market e-commerce retailers are adopting these systems within eighteen-month payback windows. The technology is displacing labor-dependent fulfillment models that previously dominated Australian retail logistics.
The National Heavy Vehicle Regulator's mass-management enforcement protocols are mandating on-board weighing and telematics integration across all contracted fleets. This regulatory friction is accelerating technology refresh cycles for transport operators. Heavy vehicle consigners in New South Wales and Victoria are responding by consolidating volume with 3PL providers bearing validated compliance infrastructure.
Direct-to-consumer order profiles are fragmenting shipment sizes while compressing delivery windows, forcing network redesign toward micro-fulfillment nodes. Australian grocery and specialty retail verticals are shifting procurement toward 3PL partners offering integrated inventory positioning rather than pure transport services. This pattern is most visible in Melbourne's outer metropolitan ring where dark store conversions are accelerating.
Australia 3PL Market Segmentation
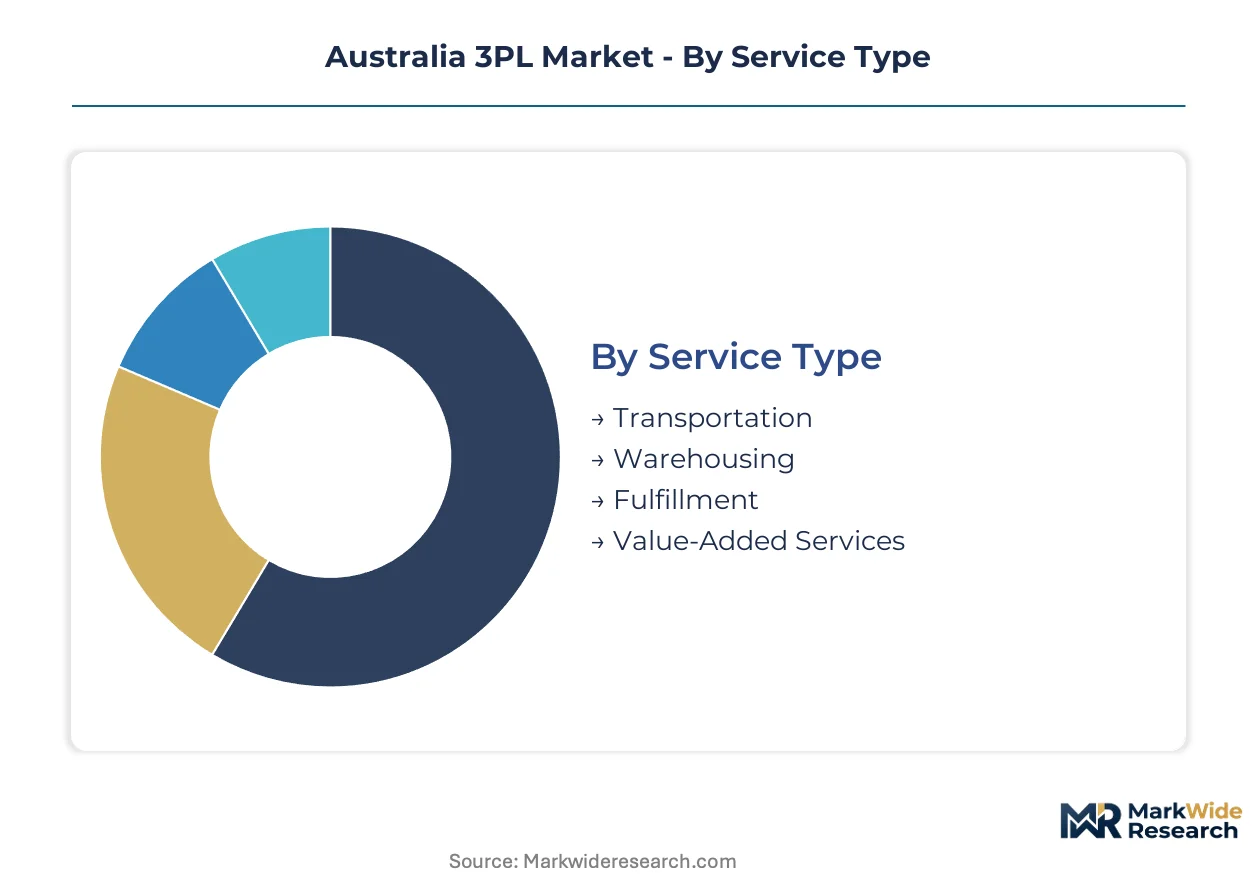
Segmentation in Australian third-party logistics reveals how service specialization, vertical concentration, and technology deployment create distinct competitive arenas. Each dimension carries different margin profiles and capital intensity requirements that reshape provider positioning across Sydney-Melbourne corridors and emerging Queensland markets.
Service Type:
Transportation services face the strongest substitution pressure from in-house fleet investments among large retailers, while fulfillment and value-added segments build stickier client relationships through operational integration.
- Transportation:Road freight operations spanning interstate corridors and metropolitan distribution networks. Demand concentrates in New South Wales and Victoria where the National Heavy Vehicle Regulator's chain-of-responsibility enforcement compels outsourcing to compliant providers with validated mass-management systems.
- Warehousing:Facilities-based inventory storage with racking, climate control, and cross-dock configurations. Sydney and Melbourne absorb the majority of contracted capacity as e-commerce inventory positioning requirements intensify competition for Port Botany and Port of Melbourne-adjacent sites.
- Fulfillment:Order processing, picking, packing, and last-mile preparation services.
- Value-Added Services:Kitting, labeling, returns processing, and quality inspection.
Transportation anchors the volume base while fulfillment gains share at the steepest rate.
Industry Vertical:
Cost tier differentiation separates premium-margin healthcare logistics from commodity-pressured retail and manufacturing segments.
- Retail:General merchandise, apparel, and homewares distribution requiring seasonal surge capacity. Melbourne and Sydney distribution centers handle the bulk of contracted volume as direct-to-consumer order profiles reshape network design toward micro-fulfillment nodes.
- Healthcare:Pharmaceutical, medical device, and clinical trial logistics with cold-chain and serialization mandates. The Therapeutic Goods Administration's temperature-integrity requirements lock in long-term contracts with established operators bearing validated quality management systems.
- Manufacturing:Industrial components and finished goods supply chain coordination.
- E-Commerce:Pure-play online retail fulfillment with same-day and next-day delivery service levels.
Retail commands the largest revenue pool while healthcare delivers the highest margin per unit handled.
Client Type:
Volume concentration and contract stability vary sharply across enterprise scale tiers.
- Large Enterprises:National retailers and manufacturers with multi-site, multi-year contracts requiring dedicated account management and customized service architectures. These clients concentrate demand in Sydney and Melbourne corridors where provider scale economies are most pronounced.
- SMEs:Mid-market retailers and specialty manufacturers purchasing shared warehousing and consolidated transport services. Queensland and regional markets show expanding SME uptake as fulfillment complexity exceeds in-house capabilities.
- Corporates:ASX-listed entities with procurement governance requirements and ESG reporting obligations.
- Startups:Emerging e-commerce ventures with variable volume profiles and rapid scaling requirements.
Large enterprises provide revenue stability while SMEs offer the steepest expansion trajectory.
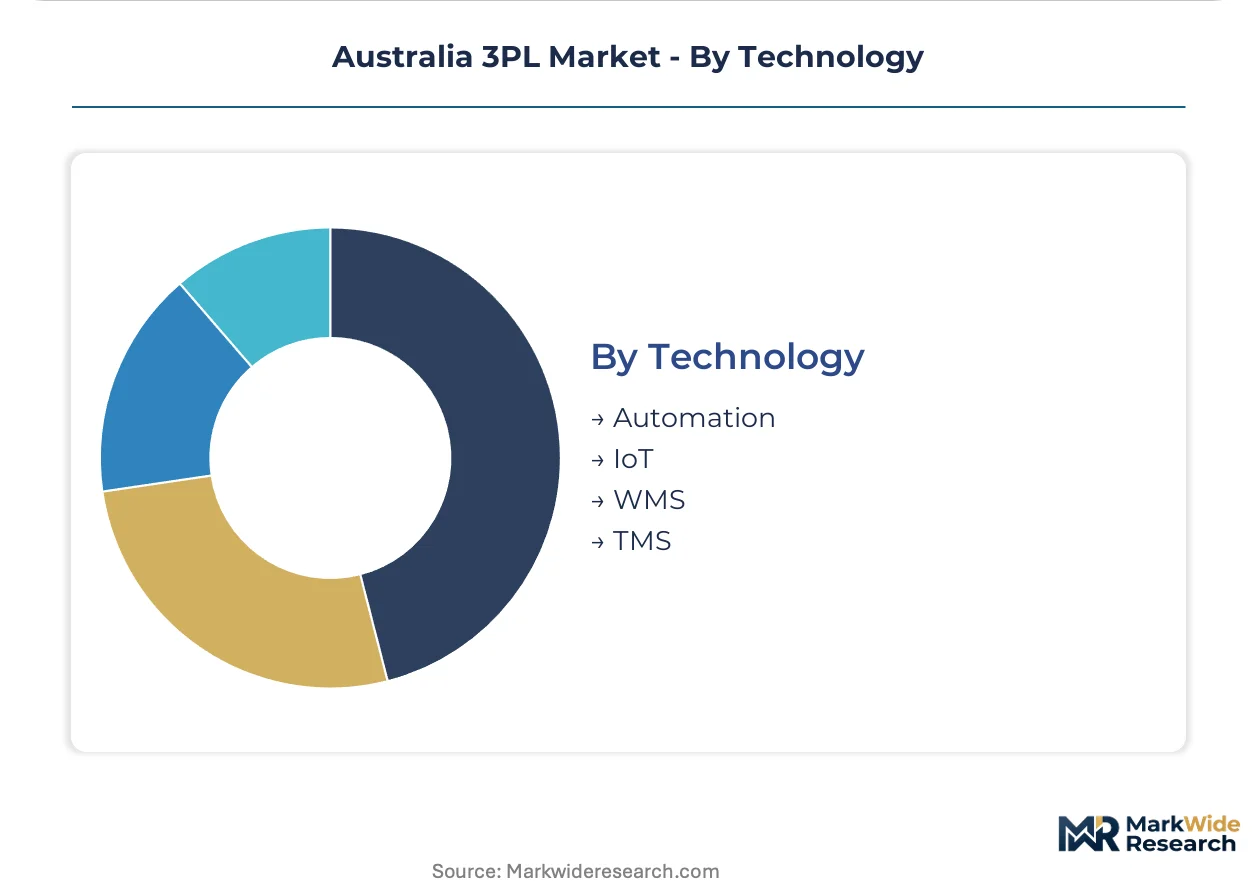
Technology:
Technology deployment maturity separates capital-intensive automated networks from conventional labor-dependent operations.
- Automation:Autonomous mobile robots, automated storage and retrieval systems, and robotic picking configurations. Melbourne distribution centers lead adoption as labor cost pressures and throughput requirements justify eighteen-month payback investments in high-velocity retail operations.
- IoT:Sensor networks for asset tracking, environmental monitoring, and condition-based maintenance. The National Heavy Vehicle Regulator's telematics mandates accelerate fleet-wide deployment across New South Wales and Victoria road freight networks.
- WMS:Warehouse management systems for inventory control, labor optimization, and order orchestration.
- TMS:Transportation management systems for route optimization, carrier selection, and freight audit.
Automation absorbs the largest capital deployment while IoT achieves the broadest penetration across installed infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Australian states, with Victoria and New South Wales buyers absorbing premium pricing for automation-enabled fulfillment while Queensland and Western Australia markets remain acutely price-sensitive on transport rates.
New South Wales
E-commerce inventory positioning and pharmaceutical cold-chain mandates drive 3PL contracting intensity. The National Heavy Vehicle Regulator's chain-of-responsibility enforcement compels mass-management technology deployment across Sydney-based road freight networks. Port Botany-adjacent warehousing commands structural premiums as industrial land scarcity intensifies competition for last-mile nodes.
Victoria
Retail fulfillment automation and same-day delivery densification absorb the majority of national 3PL capital deployment. The Therapeutic Goods Administration's serialization requirements lock pharmaceutical distributors into validated quality management systems. Melbourne's outer metropolitan ring hosts accelerating dark store conversions as grocery retailers shift toward micro-fulfillment architectures.
Queensland
Agricultural export logistics and mining supply chains present underpenetrated whitespace for temperature-controlled distribution. State-level fleet decarbonization programs create first-mover positioning for electric last-mile vehicle deployment in Brisbane. Regional Queensland corridors remain underserved by automated fulfillment infrastructure relative to southern state benchmarks.
Western Australia
Mining equipment logistics and resource sector supply chains dominate contracted transport volumes. The state's distance from eastern seaboard manufacturing centers amplifies reliance on interstate rail-port intermodal links. Perth metropolitan warehousing faces less acute land constraints than Sydney or Melbourne, moderating facility cost inflation.
South Australia
Wine export cold-chain and defense logistics anchor specialized 3PL demand. The state's central geographic position supports interstate distribution consolidation for national retail networks. Adelaide's industrial property market offers relative value for mid-market e-commerce fulfillment operations seeking alternatives to eastern seaboard cost structures.
Australia 3PL Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with scale-driven operators commanding Sydney-Melbourne corridor density while regional specialists defend niche verticals. The market structure rewards validated compliance infrastructure and automated fulfillment capability over pure asset scale. Three archetypes dominate: global network integrators leveraging international forwarding platforms, domestic heavy fleet operators with proprietary temperature-controlled assets, and automation-focused retail fulfillment specialists. Competitive intensity centers on M&A-driven corridor consolidation and technology licensing partnerships for warehouse management system integration.
Among global network integrators, DHL Supply Chain (Australia) and Mainfreight Australia occupy positions exemplifying the automated distribution and integrated forwarding archetypes respectively. Domestic heavy fleet capability concentrates with Linfox Pty Ltd, whose proprietary eastern seaboard infrastructure represents the temperature-controlled logistics specialist tier. Toll Holdings Limited sits within the legacy infrastructure scale segment, anchoring rail-port intermodal positioning. These three patterns—global integration, domestic fleet ownership, and intermodal scale—structure competitive maneuvering across the national market.
| Leading Market Players |
|---|
| DSV |
| eStore Logistics |
| Toll Holdings Limited |
| ACFS Port Logistics |
| CEVA Logistics (Australia) |
| Linfox Pty Ltd |
| Mainfreight Australia |
| Yusen Logistics (Australia) |
| DHL Supply Chain (Australia) |
| Others |
Value Chain & Pricing Dynamics
The National Heavy Vehicle Regulator's chain-of-responsibility certification gates both supplier qualification and price differentiation simultaneously, separating compliant operators with validated mass-management systems from discount competitors while embedding compliance costs into contract premiums across Sydney-Melbourne corridors.
Pricing Analysis
Multi-year service contracts with embedded performance penalties drive lifetime value across Australian 3PL relationships. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and automation capability, with TGA-validated cold-chain operators commanding spreads over conventional transport brokers. Cost compression in standard freight tiers is intensifying because fuel volatility and driver scarcity squeeze asset-heavy operators. SME retailers exhibit acute price sensitivity on pure transport rates, while ASX-listed corporates prioritize compliance infrastructure over per-unit cost minimization.
Supply Chain Analysis
Port Botany and Port of Melbourne container terminal throughput underwrites national distribution velocity for imported retail inventory. Equipment and technology inputs draw from Germany, China, and the USA, while diesel fuel and palletized freight systems rest on domestic refining and Standards Australia specifications. Single-source vulnerability concentrates in automated warehouse robotics supply, where European and East Asian OEMs dominate availability. Distribution runs through rail-port intermodal links along the Melbourne-Brisbane corridor, with last-mile densification accelerating in Sydney and Melbourne metropolitan rings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent 3PL operators face substitution defense against vertically integrated retailer captive fleets and technology-enabled brokerage platforms that disintermediate conventional transport contracting.
For Market Incumbents: Consolidate corridor density through M&A targeting Queensland temperature-controlled specialists before agricultural export logistics lock up. Invest in TGA-validated quality management systems to defend pharmaceutical contract renewals against global integrators. Backward integration into electric last-mile vehicle fleets captures state decarbonization incentives and creates switching costs against retailer insourcing. For New Entrants and Emerging Players: Differentiate on regional Queensland agricultural cold-chain whitespace where incumbent coverage gaps persist. Target Brisbane metropolitan micro-fulfillment for mid-market e-commerce retailers seeking alternatives to Sydney-Melbourne cost structures. Lead with WMS integration partnerships that resolve legacy ERP friction at mid-market Australian retailers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated fulfillment sub-segments as eighteen-month payback windows compress and AMR deployment accelerates. Long-term viability favors operators with validated compliance infrastructure and proprietary terminal-adjacent real estate. Acquisition target archetype: mid-cap specialists with TGA certification and Queensland corridor positioning. Monitor Inland Rail terminal access allocations as inflection indicator for intermodal volume shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Distribution Center Deployment | Melbourne AMR installations anchor high-velocity retail contracts against labor-dependent competitors. |
| TGA Quality Management Certification | Validated cold-chain infrastructure locks pharmaceutical clients into multi-year service agreements. |
| Electric Last-Mile Fleet Conversion | State decarbonization programs in New South Wales and Victoria create first-mover tariff advantages. |
| Queensland Corridor Expansion | Brisbane temperature-controlled networks capture agricultural export logistics underserved by southern operators. |
| WMS Integration Partnership | Middleware solutions resolve legacy ERP friction at mid-market retailers accelerating outsourcing decisions. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, NHVR compliance filings, TGA registration databases, and Standards Australia technical specifications. Interviews with 3PL operations directors, retailer supply chain managers, heavy fleet procurement leads, and pharmaceutical logistics coordinators informed demand-side validation. Bottom-up contract value analysis triangulates against top-down sector expenditure estimates from Australian Bureau of Statistics transport and warehousing indicators.
Segmentation dimensions modeled span service type, industry vertical, client scale tier, and technology deployment maturity across the projection horizon. CAGRs derive from trend extrapolation of e-commerce penetration rates, regulatory compliance cost trajectories, and infrastructure capacity expansion timelines. Forecast inputs incorporate Inland Rail terminal commissioning schedules and state-level fleet electrification incentive programs without binding to specific completion dates.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce volume growth and stable regulatory enforcement intensity would require recalibration. Forecasts reflect assumptions regarding driver availability pipeline constraints and industrial land supply elasticity near Port Botany and Port of Melbourne. Practitioners should keep alternative scenarios live as NHVR enforcement stringency and federal freight infrastructure prioritization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Middle East and Africa Courier Market
Logistics and Shipping
North America Pharmaceutical Logistics Market
Logistics and Shipping
GCC Secure Logistics Market
Logistics and Shipping
Russia Courier Service Market
Logistics and Shipping
Freight Forwarding Market
Logistics and Shipping
India Freight and Logistics Market
Logistics and Shipping
Europe Logistics Automation Market
Logistics and Shipping
United States Automotive Logistics Market
Logistics and Shipping
Bangladesh Freight and Logistics Market
Logistics and Shipping
Russia Freight and Logistics Market
Logistics and Shipping
Egypt Freight and Logistics Market
Logistics and Shipping
Peru Freight and Logistics Market
Logistics and Shipping
Spain Third-Party Logistics (3PL) Market
Logistics and Shipping
Bangladesh Contract Logistics Market
Logistics and Shipping
North America Shipping Agency Market
Logistics and Shipping
Global Load Planning Services and Solutions Market