
 GCC Secure Logistics Market | 2026-2036
GCC Secure Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Secure Logistics Market Insights
Armored vehicle driver certification and specialized security personnel availability is bifurcating the competitive landscape across the GCC. Brink's sustains its regional footprint through dedicated vault networks in Dubai and Riyadh, while Transguard leverages its Emirati workforce base to dominate government contract bidding. Deutsche Post DHL Group competes by integrating secure logistics into its broader GCC freight forwarding infrastructure, allowing bundled service offerings that smaller specialists cannot match.
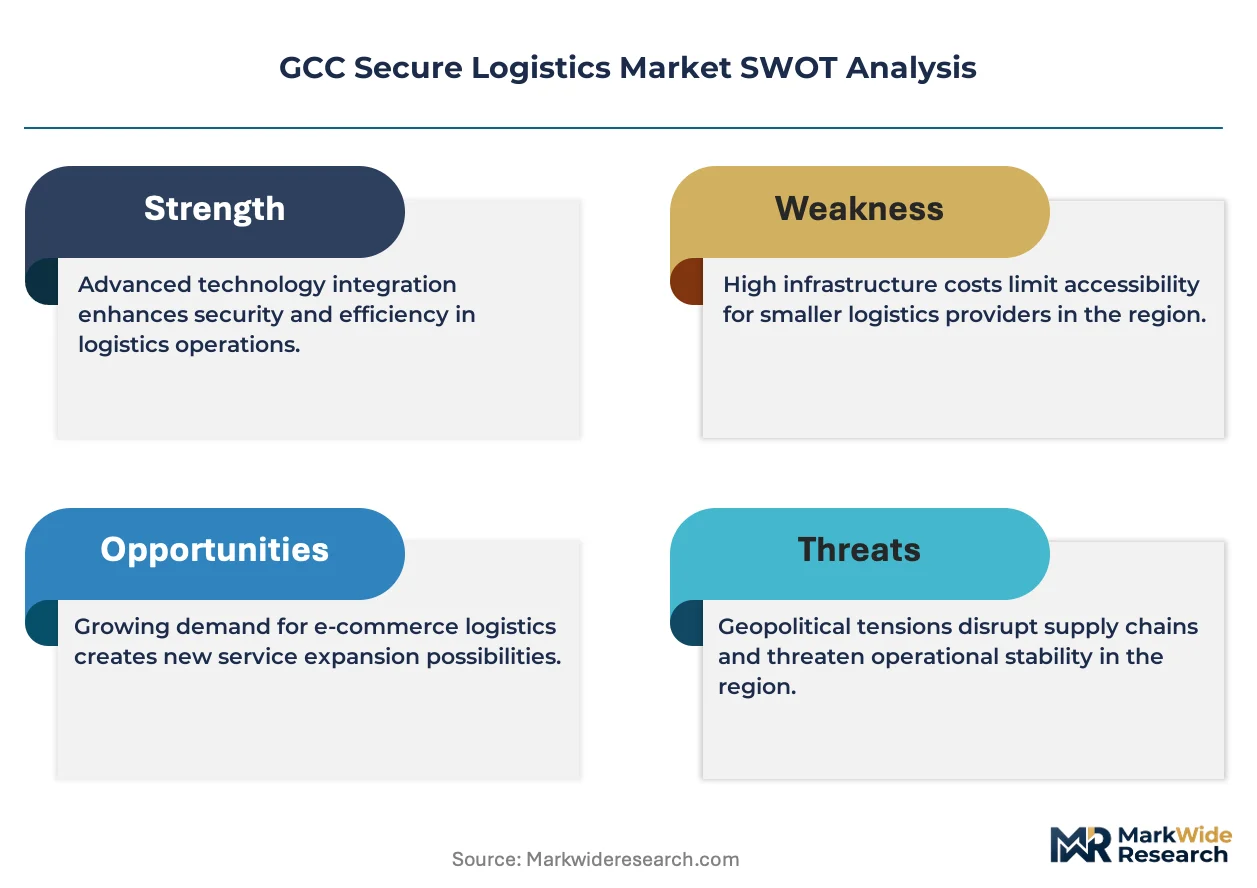
GCC Secure Logistics encompasses the physical movement, storage, and protection of high-value assets, currency, and sensitive materials using armored vehicles, monitored warehouses, and real-time tracking systems with tamper-evident seals and route deviation alerts. The primary purpose centers on mitigating theft, counterfeiting, and diversion risks for financial institutions, government treasuries, and pharmaceutical distributors operating across politically sensitive trade corridors. Armored Transportation generates the deepest margin pools due to vehicle fleet depreciation schedules and fuel pass-through mechanisms, while Biometric Systems within the Technology dimension represents the fastest-expanding segment as ports and free zones mandate identity verification for cargo handlers. Warehousing services remain structurally mature, with oversupply in Dubai's Jebel Ali corridor compressing storage premiums even as value-added services like vaulting and insurance bundling preserve profitability.
The UAE's Security Industry Regulatory Agency and Saudi Arabia's General Authority for Transport enforce divergent vehicle armoring standards and route pre-approval protocols, fragmenting fleet procurement decisions for cross-border operators. Qatar's Ministry of Interior imposes additional screening layers for event security logistics tied to international sporting and diplomatic gatherings, creating seasonal demand spikes that strain regional capacity. Stakeholders must monitor how central bank digital currency pilots across Abu Dhabi and Riyadh reshape cash volume forecasts and armored transit frequency requirements.
Market Dynamics
Central bank mandates across Saudi Arabia and the UAE are tightening vehicle armoring specifications and driver certification protocols, forcing fleet operators to accelerate capital deployment toward compliant assets while compressing margins on legacy contracts.
Growth Catalysts
- Biometric cargo handler verification:UAE ports and free zones now mandate identity verification systems for personnel accessing high-value cargo zones, expanding demand for integrated authentication infrastructure.
- Qatar's event security logistics:International sporting and diplomatic gatherings impose additional screening layers that create seasonal demand spikes, absorbing excess regional capacity during peak periods.
- Saudi banking license proliferation:Government-led financial sector modernization in Riyadh and Jeddah is proliferating secure logistics contracts for new market entrants requiring cash distribution networks.
Market Restraints
- Cross-border regulatory fragmentation:Divergent vehicle armoring standards between the UAE's Security Industry Regulatory Agency and Saudi Arabia's General Authority for Transport fragment fleet procurement decisions for operators serving multiple jurisdictions.
- Fuel pass-through volatility:Armored transportation margins remain exposed to diesel price swings that operators cannot fully hedge, compressing profitability during energy price spikes.
- Central bank digital currency pilots:Abu Dhabi and Riyadh initiatives threaten to reduce physical currency volumes and armored transit frequency requirements over the forecast window.
Strategic Opportunities
- Pharmaceutical cold chain security:Temperature-controlled high-value drug distribution across the GCC remains underpenetrated by specialized secure logistics providers, creating white space for vaulting and monitored transport bundling.
- Value-added warehousing services:Insurance bundling and specialized vaulting capabilities in Jebel Ali corridor facilities allow operators to preserve premiums despite structural oversupply in baseline storage.
- Integrated freight-forwarding bundles:Secure logistics modules embedded within broader supply chain offerings capture procurement consolidation trends among multinational banking groups operating across Dubai and Riyadh.
Industry Challenges
- Armored vehicle driver certification scarcity:Specialized security personnel availability constraints bifurcate competitive positioning, with incumbents holding certified workforces commanding premium contract terms.
- Route pre-approval protocol complexity:Saudi Arabia's General Authority for Transport mandates lengthen operational planning cycles and reduce fleet utilization rates during peak demand periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Secure Logistics Market |
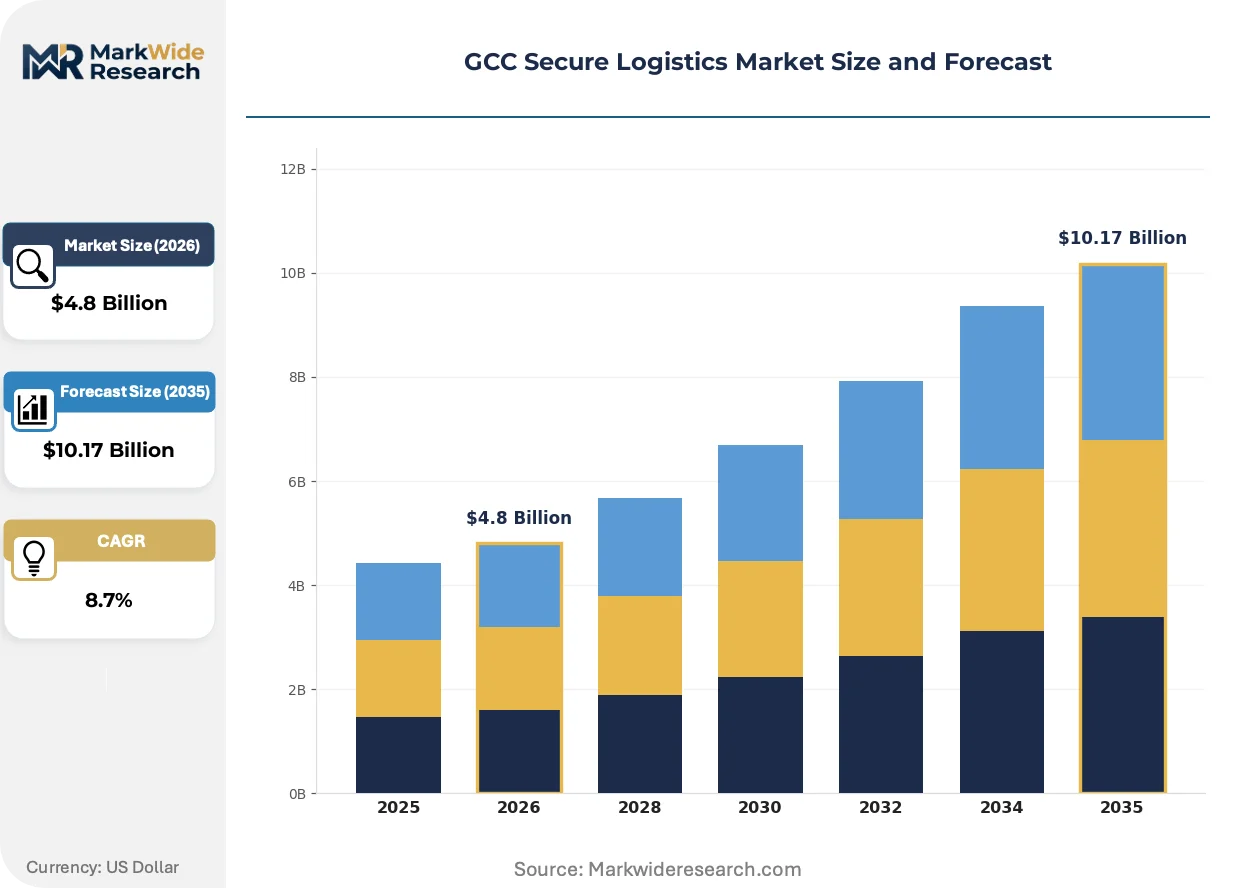
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Armored Transportation, Warehousing, Risk Management, Compliance Services End User: Government Agencies, Financial Institutions, E-Commerce, Retail Technology: GPS Tracking, RFID, Biometric Systems, Surveillance Solutions Application: Cash Transit, High-Value Goods, Pharmaceuticals, Event Security |
| Companies Covered | Kuehne + Nagel, Agility Logistics, Brink's, Deutsche Post DHL Group, CEVA Logistics, Loomis, Transguard, DP World, G4S, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Secure Logistics Market Trends and Innovations
Real-time tracking systems with tamper-evident seals and route deviation alerts are becoming baseline requirements, while biometric authentication and predictive analytics reshape operational standards across financial and government verticals.
Biometric identity verification systems for cargo handlers is supplanting manual badge-checking protocols at UAE ports and Saudi bonded warehouses. Banking and pharmaceutical distributors are adopting these systems at accelerated pace to preempt regulatory non-compliance penalties. The technology is compressing incident response times while elevating facility access control to primary vendor selection criteria.
The UAE's Security Industry Regulatory Agency has tightened armored vehicle specification mandates, requiring ballistic certification upgrades that invalidate prior fleet investments. Operators must now pre-approve transit routes through centralized digital platforms, extending deployment lead times. Saudi Arabia's General Authority for Transport is mirroring these protocols, forcing cross-border operators to maintain dual-compliant asset pools.
Banking procurement committees are consolidating vendor relationships, favoring secure logistics providers offering bundled cash management, vaulting, and insurance services over specialized armored transport-only contracts. This behavioral shift displaces single-service regional specialists. The concentration is most visible among Saudi Arabia's newly licensed financial institutions, which prioritize integrated service level agreements over point solutions.
GCC Secure Logistics Market Segmentation
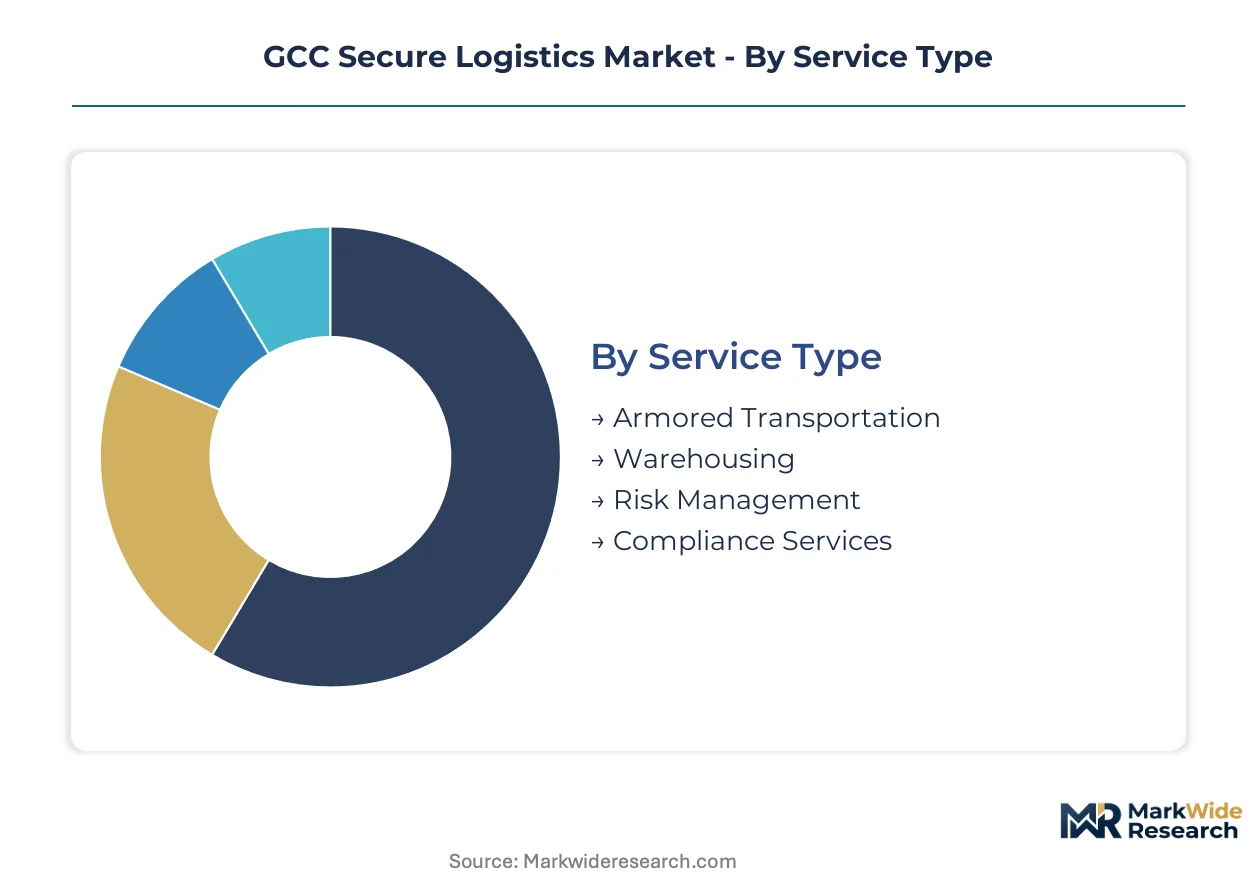
Segmentation in GCC secure logistics reveals how regulatory fragmentation and technology adoption curves create divergent margin structures across service lines. Understanding these divides matters for fleet procurement timing and cross-border operational planning.
Service Type:
UAE's Security Industry Regulatory Agency and Saudi Arabia's General Authority for Transport impose divergent vehicle armoring certifications and route pre-approval protocols, fragmenting service delivery economics.
- Armored Transportation:Ballistic-certified vehicles with tamper-evident seals and real-time route deviation alerts form the technical baseline. Saudi Arabia's Riyadh-Jeddah corridor concentrates demand as banking license proliferation forces new entrants to build cash distribution networks from scratch.
- Warehousing:Vaulting facilities with monitored climate controls and insurance bundling capabilities define operational standards. Dubai's Jebel Ali corridor suffers structural oversupply compressing storage premiums, though value-added services preserve profitability for operators with specialized certifications.
- Risk Management:Route threat assessment and cargo insurance structuring services support high-value transit operations across politically sensitive corridors.
- Compliance Services:Documentation and regulatory navigation support for cross-border operators managing dual-jurisdiction certification requirements.
Armored Transportation handles the majority of throughput; Warehousing is gaining share fastest as banking procurement consolidates around bundled service agreements.
End User:
Customer type determines contract duration, certification stringency, and payment security structures across the GCC.
- Financial Institutions:Central bank mandates in Abu Dhabi and Riyadh dictate armored vehicle specifications and driver certification standards. New banking licenses in Saudi Arabia are proliferating long-term secure logistics contracts with integrated vaulting requirements.
- Government Agencies:Procurement committees favor Emirati workforce quotas and domestic partnership structures, particularly in UAE federal and municipal contracts.
- E-Commerce:High-value parcel authentication and last-mile secure delivery protocols are expanding as cross-border luxury goods volumes rise.
- Retail:Cash collection frequency and store-level vaulting services follow shopping mall density patterns in Dubai and Riyadh.
Financial Institutions anchor contract value; Government Agencies are expanding most quickly on procurement volume.
Technology:
Technology selection reflects port authority mandates and central bank operational standards rather than discretionary investment.
- Biometric Systems:Fingerprint and facial recognition infrastructure for cargo handler identity verification. UAE ports and free zones now mandate these systems for high-value cargo zone access, compressing incident response times while elevating access control to primary vendor selection criteria.
- GPS Tracking:Real-time location monitoring with route deviation alerts and centralized digital pre-approval platforms. Saudi Arabia's General Authority for Transport requires these systems for all certified cash-in-transit operations.
- RFID:Automated cargo authentication and chain-of-custody documentation for pharmaceutical and high-value goods movements.
- Surveillance Solutions:On-vehicle and facility-based monitoring systems with tamper-evident recording protocols.
GPS Tracking handles the majority of installed base; Biometric Systems are climbing the fastest on regulatory mandate penetration.
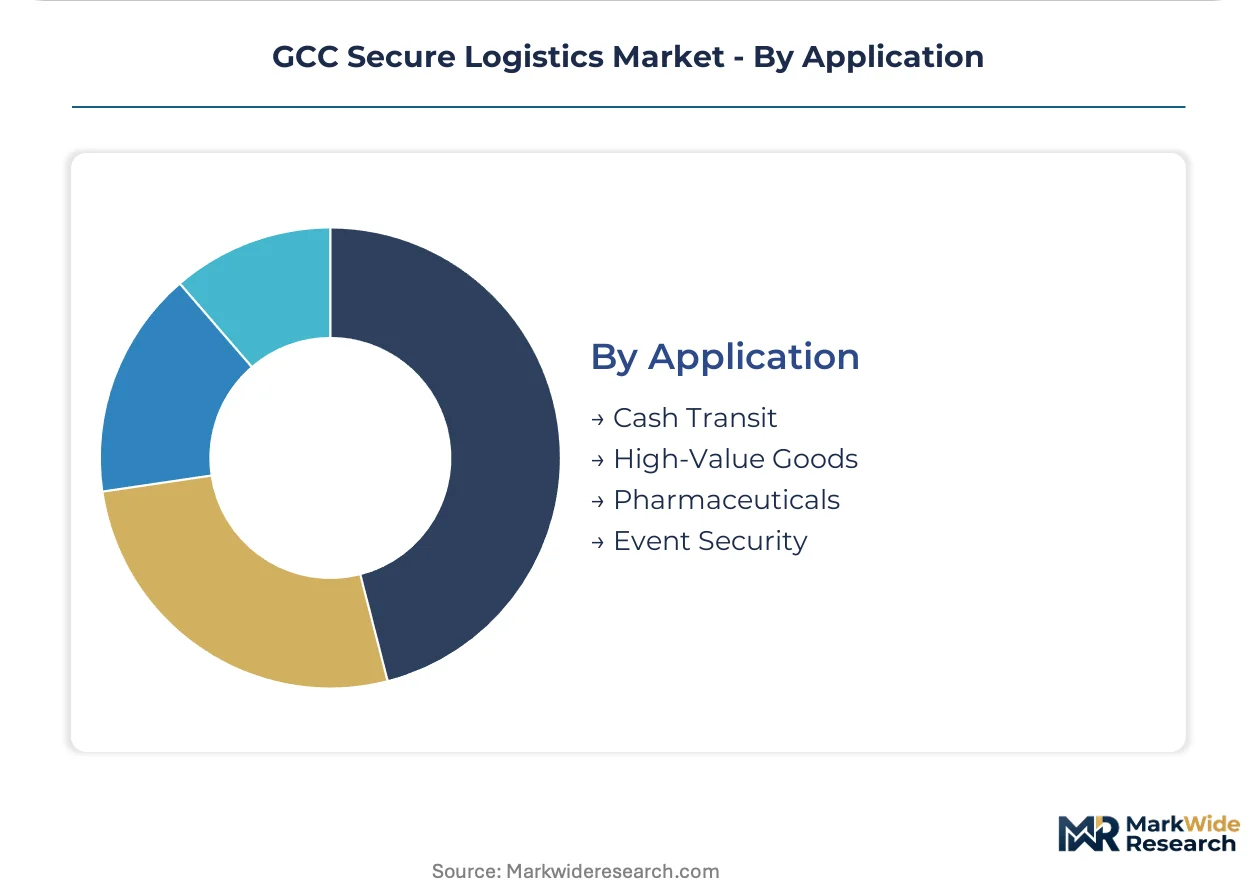
Application:
Application mix shifts with central bank digital currency pilots threatening physical cash volumes while pharmaceutical cold chain security remains underpenetrated.
- Cash Transit:Physical currency movement between bank branches, ATMs, and central bank facilities. Frequency requirements face compression from Abu Dhabi and Riyadh digital currency initiatives, though immediate-term demand holds firm across Saudi Arabia's financial sector modernization.
- Pharmaceuticals:Temperature-controlled high-value drug distribution with monitored chain-of-custody documentation. GCC-wide distribution networks remain underpenetrated by specialized secure logistics providers, creating white space for vaulting and transport bundling.
- High-Value Goods:Luxury products, precious metals, and art authentication with specialized handling protocols.
- Event Security:Seasonal demand spikes tied to Qatar's international sporting and diplomatic gatherings, absorbing excess regional capacity during peak periods.
Cash Transit dominates current throughput; Pharmaceuticals are expanding most quickly on unmet specialized demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia consumes secure logistics services differently from the UAE, with Riyadh-Jeddah corridor demand driven by banking license proliferation rather than port-centric trade flows. Qatar concentrates spending on seasonal event security spikes. Oman and Bahrain serve as secondary transit corridors with lighter regulatory frameworks.
Saudi Arabia
The Riyadh-Jeddah corridor anchors regional armored transit volume as government-led financial sector modernization proliferates secure logistics contracts. The General Authority for Transport mandates route pre-approval protocols through centralized digital platforms, extending deployment lead times. New banking licenses in Riyadh force market entrants to build cash distribution networks from scratch.
United Arab Emirates
Dubai's Jebel Ali corridor concentrates warehousing capacity while Abu Dhabi drives biometric system mandates for high-value cargo zones. The Security Industry Regulatory Agency requires ballistic certification upgrades that invalidate prior fleet investments. Vault networks in Dubai and Riyadh sustain integrated service offerings for banking procurement committees.
Qatar
International sporting and diplomatic gatherings impose additional screening layers that create seasonal demand spikes absorbing excess regional capacity. The Ministry of Interior mandates supplementary security protocols for event logistics, straining certified personnel availability during peak periods. Doha-based operations prioritize workforce scalability over year-round asset utilization.
Oman
Cross-border transit corridors to Saudi Arabia and the UAE sustain armored transportation demand with lighter domestic regulatory frameworks. The central bank maintains baseline cash-in-transit specifications without the granular mandates seen in neighboring jurisdictions. Muscat serves as a secondary routing hub for operators managing dual-compliant asset pools.
Bahrain
Financial sector density in Manama supports specialized cash management services for Islamic banking institutions. The central bank aligns vehicle armoring standards with Saudi protocols while maintaining streamlined certification procedures. Regional operators use Bahraini facilities as overflow capacity during Saudi peak demand periods.
GCC Secure Logistics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with fleet scale and workforce certification separating contract winners from margin-compressed followers. The upper tier commands bundled service agreements spanning armored transit, vaulting, and compliance navigation. Three archetypes dominate: integrated freight-forwarders leveraging existing infrastructure, security-first specialists with certified workforces, and port-centric operators capturing trade flow proximity. Competitive moves concentrate on dual-jurisdiction fleet compliance and insurance bundling capabilities that preserve premiums during storage oversupply.
Among integrated freight-forwarders, Deutsche Post DHL Group and Kuehne + Nagel occupy positions that exemplify bundled secure logistics modules within broader supply chain offerings. Brink's anchors the security-first specialist tier with dedicated vault networks. Transguard represents the workforce-certification advantage in government contract bidding. These three names illustrate how geographic origin and structural positioning shape competitive access rather than product differentiation alone.
| Leading Market Players |
|---|
| Kuehne + Nagel |
| Agility Logistics |
| Brink's |
| Deutsche Post DHL Group |
| CEVA Logistics |
| Loomis |
| Transguard |
| DP World |
| G4S |
| Others |
Pricing and Supply Chain Analysis
Long-term service agreements with embedded fuel pass-through clauses lock in armored fleet access and price visibility for Saudi banking licenses and UAE government contracts. These structures insulate operators from diesel volatility while committing buyers to minimum volume thresholds across multi-year tenures.
Pricing Analysis
Project-based capacity reservations dominate armored transportation contracting, with pricing stratifying across ballistic certification tiers, route complexity premiums, and insurance bundling depth. Fuel pass-through mechanisms expose margins to diesel price swings that operators cannot fully hedge. Cost compression in baseline warehousing runs through Jebel Ali corridor oversupply, while value-added vaulting commands premium retention. New Saudi banking entrants exhibit highest price sensitivity; established UAE federal contractors demonstrate lowest.
Supply Chain Analysis
Germany, the United States, and Turkey anchor armored vehicle chassis and ballistic glass production for GCC fleet procurement. Specialized security personnel certification draws from domestic workforce pools in Saudi Arabia and the UAE, with cross-border mobility restricted by divergent licensing protocols. Single-source vulnerability concentrates in ballistic steel supply from European mills. Distribution runs through Dubai and Riyadh hub-and-spoke networks serving corridor demand clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biometric authentication infrastructure and predictive maintenance subscriptions are expanding faster than armored vehicle hardware sales, creating recurring revenue attach opportunities that reshape contract economics across the GCC.
For Market Incumbents: Fortify certified workforce retention through Emirati and Saudi nationalization quotas that preempt regulatory compliance penalties. Deepen backward integration into vault network ownership across Riyadh and Dubai corridors. Central bank digital currency pilots threaten physical cash volume trajectories; counter by embedding compliance navigation services into bundled offerings that survive currency format transitions. For New Entrants and Emerging Players: Pharmaceutical cold chain security represents the most penetrable white space, with temperature-controlled high-value drug distribution remaining under-served by specialized secure logistics providers. Qatar's seasonal event security spikes absorb excess regional capacity and create partnership entry points with established fleet operators. Pursue joint venture structures with existing vault network holders to bypass capital-intensive facility buildout. For Investors and Strategic Acquirers: Workforce-certified mid-tier specialists with dual-jurisdiction operational licenses command scarcity premiums in fragmented competitive terrain. Long-term viability hinges on service-layer revenue durability rather than hardware fleet scale alone. Monitor biometric mandate penetration rates at UAE ports and Saudi bonded warehouses as inflection indicators for technology attach revenue acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Infrastructure Deployment | UAE port mandates elevate identity verification to primary vendor selection criteria across cargo handler access protocols. |
| Dual-Jurisdiction Fleet Certification | Cross-border operators must maintain compliant asset pools satisfying both Saudi General Authority for Transport and UAE Security Industry Regulatory Agency standards. |
| Pharmaceutical Cold Chain Entry | Temperature-controlled vaulting and monitored transport bundling captures unmet demand in GCC-wide drug distribution networks. |
| Insurance Service Layer Integration | Value-added bundling preserves premiums despite structural oversupply compressing baseline warehousing rates in Jebel Ali corridor. |
| Workforce Nationalization Investment | Emirati and Saudi certification quotas strengthen government contract bidding positioning against foreign-operated competitors. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with armored fleet operators, vault facility managers, banking procurement committees, and regulatory compliance officers; and secondary validation against central bank operational standards, customs trade records, and Security Industry Regulatory Agency filings. Bottom-up service line sizing and top-down macroeconomic triangulation anchored volume and value estimates.
Across the projection horizon, the analytical framework modeled service type, end user vertical, technology adoption tier, and application segment dimensions. CAGRs derived from regression analysis of historical contract proliferation patterns and regulatory mandate implementation timelines. Forecast inputs incorporated banking license issuance trajectories in Saudi Arabia and biometric system deployment schedules at UAE free zones.
Material uncertainties — central bank digital currency volume displacement, fuel price volatility, and cross-border regulatory harmonization delays — sit outside the modeled envelope. Forecasts reflect assumptions about physical cash persistence and certification standard stability. Recalibration cycles align with material shifts in central bank operational mandates and port authority security protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
India Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Germany Dangerous Goods Logistics Market
Logistics and Shipping
North America Freight Forwarding Market
Logistics and Shipping
Mexico Last Mile Delivery Market
Logistics and Shipping
Central and Eastern Europe Cold Chain Logistics Market
Logistics and Shipping
Middle Mile Delivery Market
Logistics and Shipping
UK Logistics Market
Logistics and Shipping
Latin America Logistics Market
Logistics and Shipping
LAOS Freight and Logistics Market
Logistics and Shipping
Armenia Freight and Logistics Market
Logistics and Shipping
Kazakhstan Freight and Logistics Market
Logistics and Shipping
Australia Cold Chain Logistics Market
Logistics and Shipping
Europe Full Container Load (FCL) Market
Logistics and Shipping
US Air Freight Transport Market
Logistics and Shipping
Canada Road Freight Transport Market
Logistics and Shipping
Global Container Terminal Operations Market