
 Uruguay Freight and Logistics Market | 2026-2036
Uruguay Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Uruguay Freight and Logistics Market Insights
ISO-certified cold-chain specifications is unwinding across Uruguay's agricultural export corridors, compelling logistics providers to upgrade temperature-controlled infrastructure. Montecon anchors container handling capacity at the Port of Montevideo through specialized reefer services. DSV A/S extends European-origin freight forwarding networks into Uruguayan hinterlands via Buenos Aires corridor links. Grupo Ras dominates domestic trucking routes connecting interior agricultural zones to coastal terminals.
Uruguay freight and logistics encompasses the physical movement, storage, and customs facilitation of goods across road, rail, maritime, and air modalities, typically operating within temperature bands of minus twenty-five to plus twenty-five degrees Celsius for perishable cargoes and requiring bonded warehouse certification for Mercosur transshipment. Its primary commercial purpose centers on enabling agricultural commodity exports and manufactured imports for a trade-dependent economy with no direct land bridge to Pacific markets. Freight forwarding and customs clearance services capture disproportionate margin pools due to documentary complexity at Mercosur borders, while warehousing concentrates in the Montevideo-Nueva Palmira axis where port-centric inventory positioning reduces dwell-time penalties. Last-mile delivery models remain structurally underdeveloped outside the capital region, creating asymmetric service coverage that favors port-to-port contracts over door-to-door commitments for interior agricultural clients.
Uruguay's national port authority and the Ministry of Transport and Public Works shape terminal concession terms and road freight weight limits, while Mercosur customs protocols administered by the Uruguayan Revenue Service dictate cross-border documentation standards that directly influence freight forwarding service pricing. The country's alignment with ISO container standards and adherence to SOLAS verified gross mass requirements filter market access toward carriers with certified weighing infrastructure. Stakeholders must weigh port capacity expansion timelines at Nueva Palmira against inland road deterioration risks when committing to long-term warehousing lease structures.
Market Dynamics
ISO-certified cold-chain specifications are compelling logistics providers across Uruguay's agricultural export corridors to upgrade temperature-controlled infrastructure, reshaping capital deployment patterns around the Port of Montevideo.
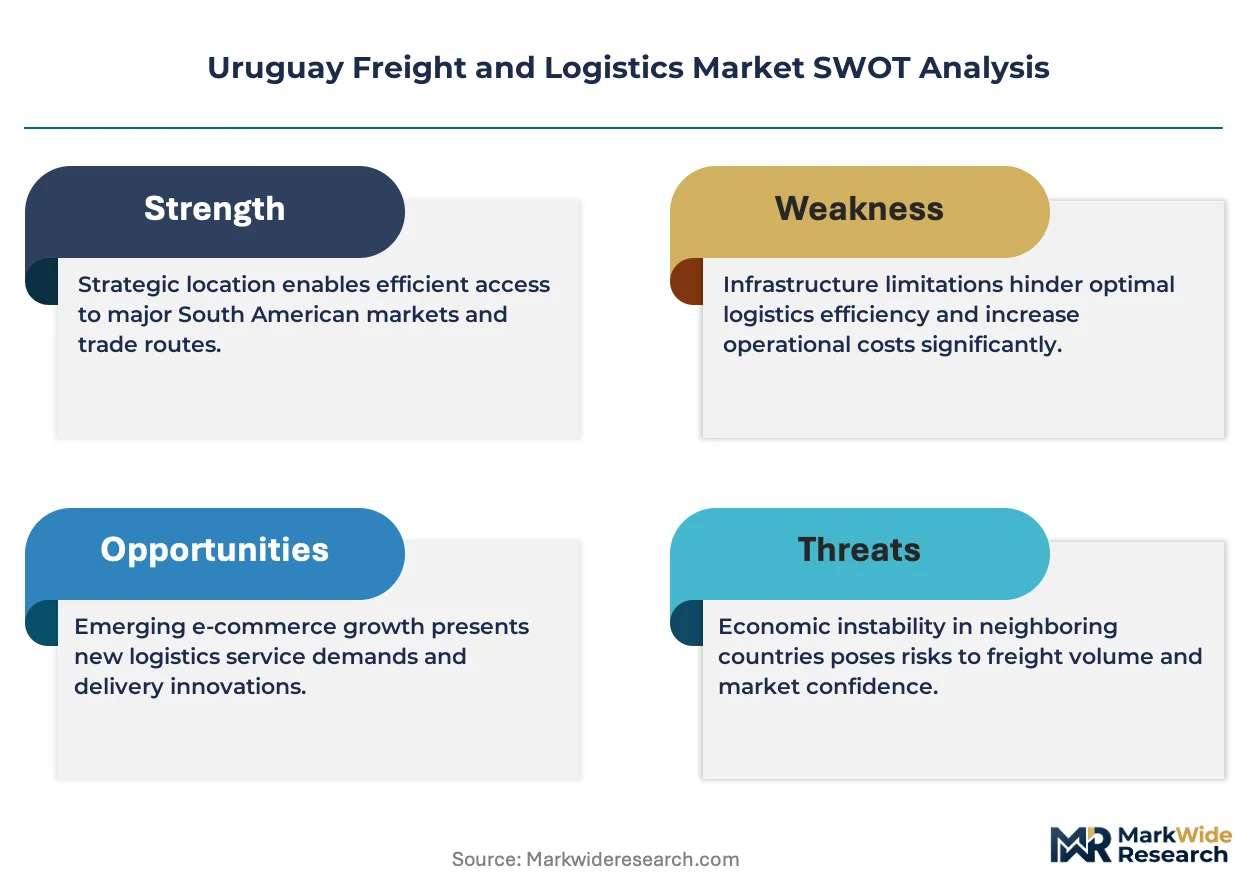
Growth Catalysts
- Mercosur customs protocols:The Uruguayan Revenue Service's documentary requirements for cross-border freight create sustained demand for specialized customs brokerage services.
- Soybean cold-chain investments:Exporters in the Nueva Palmira agricultural belt are scaling refrigerated storage capacity to meet EU and Asian phytosanitary standards.
- Montevideo port modernization:The national logistics plan's container terminal upgrades are expanding reefer handling capacity for transshipment flows.
Market Restraints
- Road freight weight limits:The Ministry of Transport and Public Works enforces axle-load restrictions that constrain interior-to-coastal payload efficiency.
- Pacific market access gap:Uruguay lacks direct land bridge connectivity to Pacific ports, forcing circuitous routing through Argentine or Brazilian corridors.
- Refrigerant input volatility:Temperature-controlled fleets face compressed margins from fluorinated gas pricing fluctuations under EU F-Gas Regulation spillover effects.
Strategic Opportunities
- Colonia Free Trade Zone:Bonded warehouse certification expansion offers Mercosur transshipment tax advantages for regional distribution hubs.
- Digital freight platforms:Real-time cargo matching applications are penetrating underdigitized domestic trucking routes between interior agricultural zones and coastal terminals.
- Agro-industrial corridor development:The Durazno-Río Negro logistics axis presents untapped warehousing positioning for soy derivatives and meat processing exports.
Industry Challenges
- SOLAS certified weighing infrastructure:Verified gross mass compliance requirements filter market access toward carriers with capital-intensive container weighing systems.
- Refrigeration technician scarcity:Specialized cold-chain maintenance skills lag fleet expansion timelines, extending equipment downtime intervals.
- Legacy warehouse management system integration:Bonded inventory tracking platforms require costly retrofitting to interface with national customs electronic data interchange protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uruguay Freight and Logistics Market |
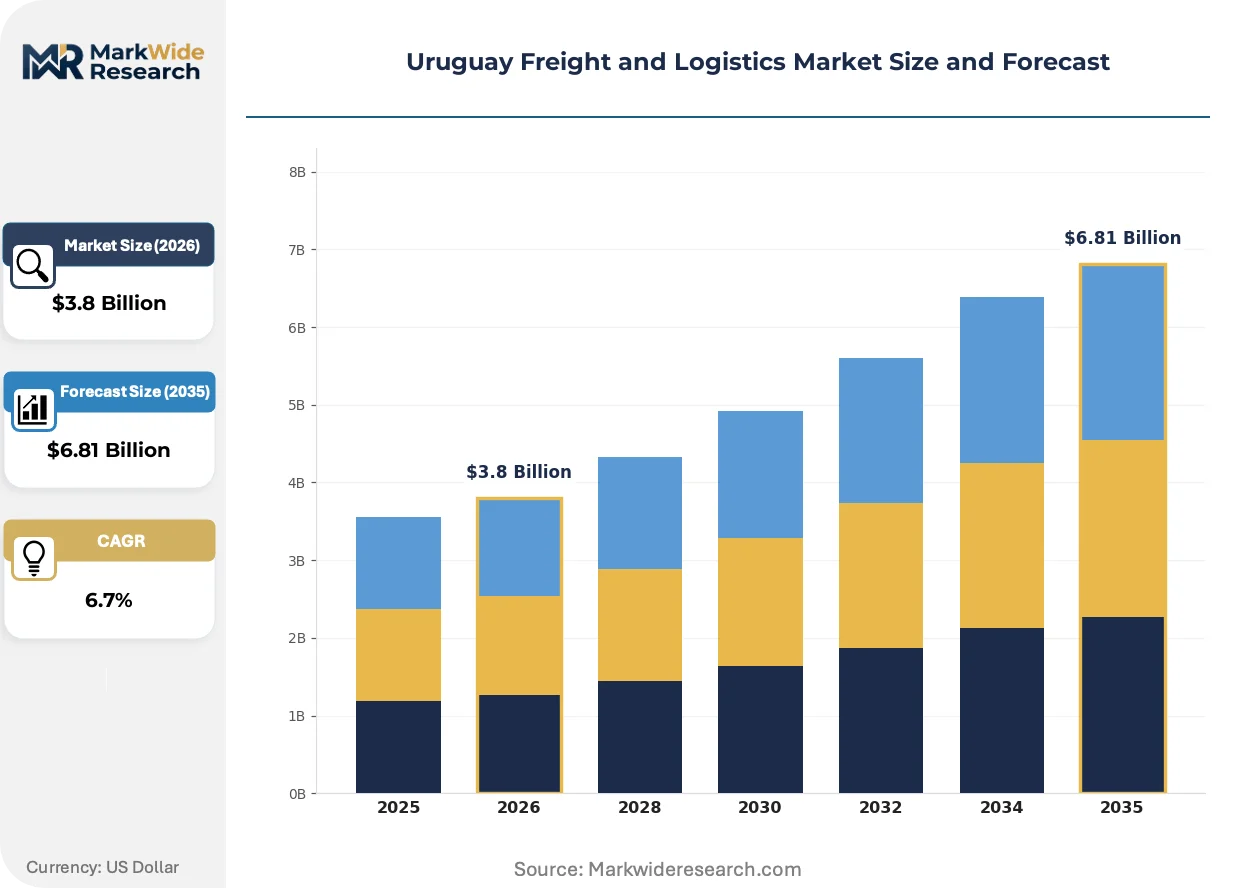
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Freight Forwarding, Warehousing, Transportation, Customs Clearance Delivery Model: Door-to-Door, Port-to-Port, Intermodal, Last-Mile End User: Retail, Manufacturing, Construction, Agriculture Technology: Blockchain, GPS Tracking, IoT Solutions, Automation |
| Companies Covered | Grupo Ras, Montecon, Ues, Corfrisa, Malatic, STL Depot, DHL Group, A.P. Moller-Maersk, DSV A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uruguay Freight and Logistics Market Trends and Innovations
Digital cargo visibility platforms and automated container handling systems are compressing dwell times at Uruguayan port terminals while reconfiguring buyer expectations for shipment transparency.
Telematics-enabled fleet monitoring is supplanting manual dispatch coordination across Uruguay's temperature-controlled trucking sector. Soybean and beef exporters operating through the Nueva Palmira corridor are adopting sensor-based cargo tracking at accelerating rates. This technology is compressing insurance premium structures and enabling outcome-based logistics contracts that penalize temperature excursions.
Uruguay's national port authority has mandated SOLAS verified gross mass compliance for all containerized exports, forcing terminal operators to invest in certified weighing infrastructure. The regulation compresses vessel loading windows and eliminates manual weight declaration practices. Reefer container segments face the steepest compliance costs due to integrated weighing system requirements.
Consolidated procurement of integrated freight forwarding and customs brokerage services is displacing fragmented vendor relationships among agricultural exporters. Trading houses serving Asian soy markets are bundling documentation, warehousing, and ocean freight under single-provider contracts. This pattern concentrates most visibly in the Montevideo metropolitan corridor where Mercosur transshipment complexity rewards full-service logistics integration.
Uruguay Freight and Logistics Market Segmentation
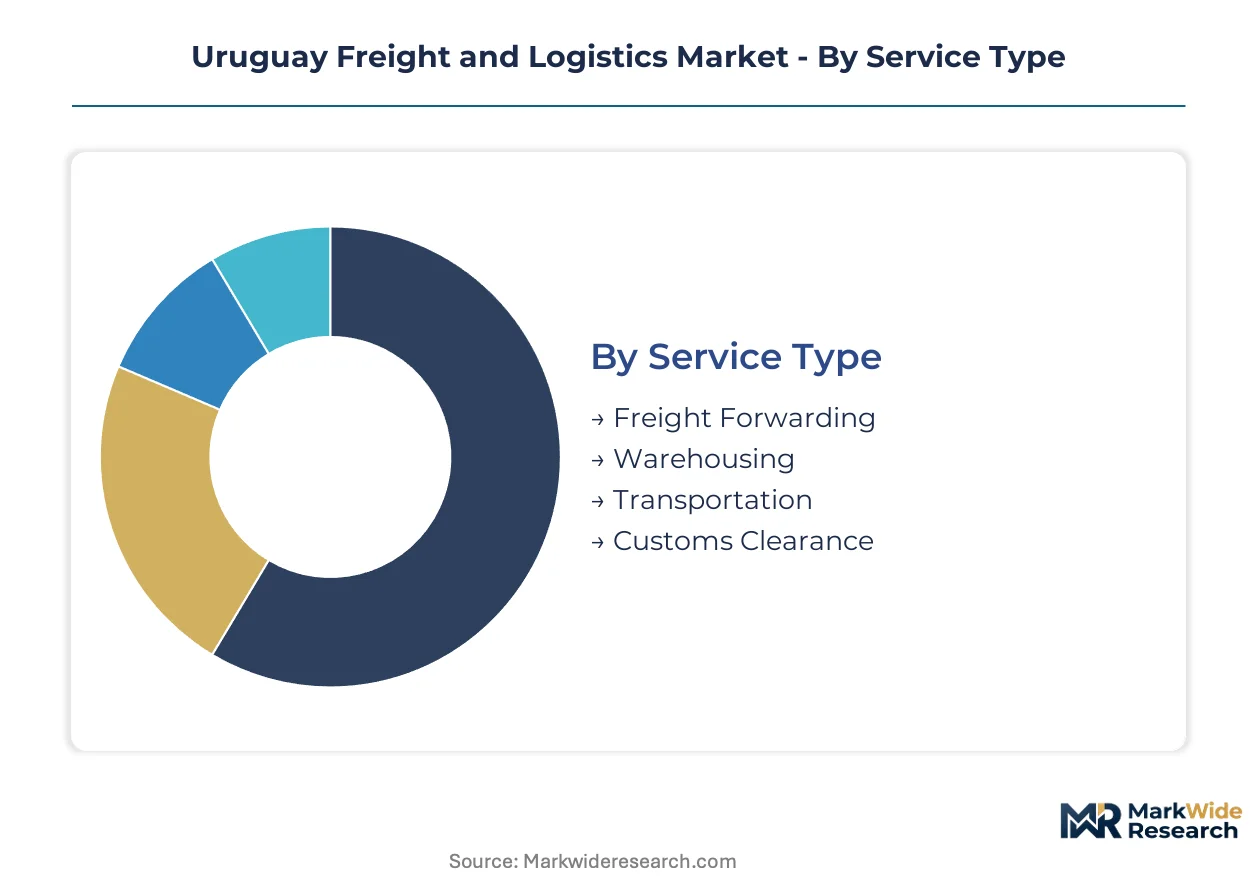
Segmentation in Uruguay's freight and logistics market reveals how service specialization aligns with the country's export-driven agricultural economy and Mercosur transshipment geography. Each dimension exposes distinct margin structures and capital intensity requirements across domestic versus cross-border flows.
Service Type:
Road-based transportation dominates domestic cargo movements while port-centric services concentrate export-led revenue pools.
- Freight Forwarding:Documentary coordination for Mercosur customs protocols commands premium margins due to Uruguayan Revenue Service complexity. Trading houses serving Asian soy markets bundle forwarding with customs brokerage under single-provider contracts in the Montevideo metropolitan corridor.
- Warehousing:Temperature-controlled facilities around Nueva Palmira and Montevideo handle bonded inventory for agricultural exports. Dwell-time reduction imperatives drive demand for port-proximate positioning over interior distribution centers.
- Transportation:Domestic trucking connects interior agricultural zones to coastal terminals under Ministry of Transport axle-load regulations.
- Customs Clearance:Cross-border documentation services capture disproportionate margins from Mercosur regulatory complexity.
Transportation holds the largest share; momentum sits with warehousing as cold-chain specifications tighten.
Delivery Model:
Cost tier differentiation separates commodity bulk flows from premium perishable services requiring temperature integrity guarantees.
- Door-to-Door:End-to-end cargo custody remains structurally underdeveloped outside Montevideo due to fragmented last-mile infrastructure in interior agricultural regions.
- Port-to-Port:Containerized agricultural exports through Montevideo and Nueva Palmira anchor contract volumes with standardized handling protocols.
- Intermodal:Rail-road coordination for soy derivatives and meat processing exports is gaining share along the Durazno-Río Negro logistics axis.
- Last-Mile:E-commerce parcel delivery concentrates in the capital region with asymmetric coverage favoring urban over rural endpoints.
Port-to-Port commands dominant volume; Intermodal is climbing the fastest as agro-industrial corridor investments mature.
End User:
Application-driven demand splits between commodity export logistics and import-dependent manufacturing supply chains.
- Agriculture:Soybean and beef exporters drive refrigerated storage investments to meet EU and Asian phytosanitary standards through the Nueva Palmira belt.
- Manufacturing:Import-reliant industrial operations in Montevideo require just-in-time warehousing for Mercosur-sourced components and overseas machinery.
- Retail:Consumer goods distribution depends on bonded warehouse certification for regional Mercosur transshipment through the Colonia Free Trade Zone.
- Construction:Project cargo for infrastructure development moves through specialized heavy-lift forwarding with extended dwell-time tolerance.
Agriculture holds the largest share; momentum sits with Retail as regional distribution hub strategies expand.
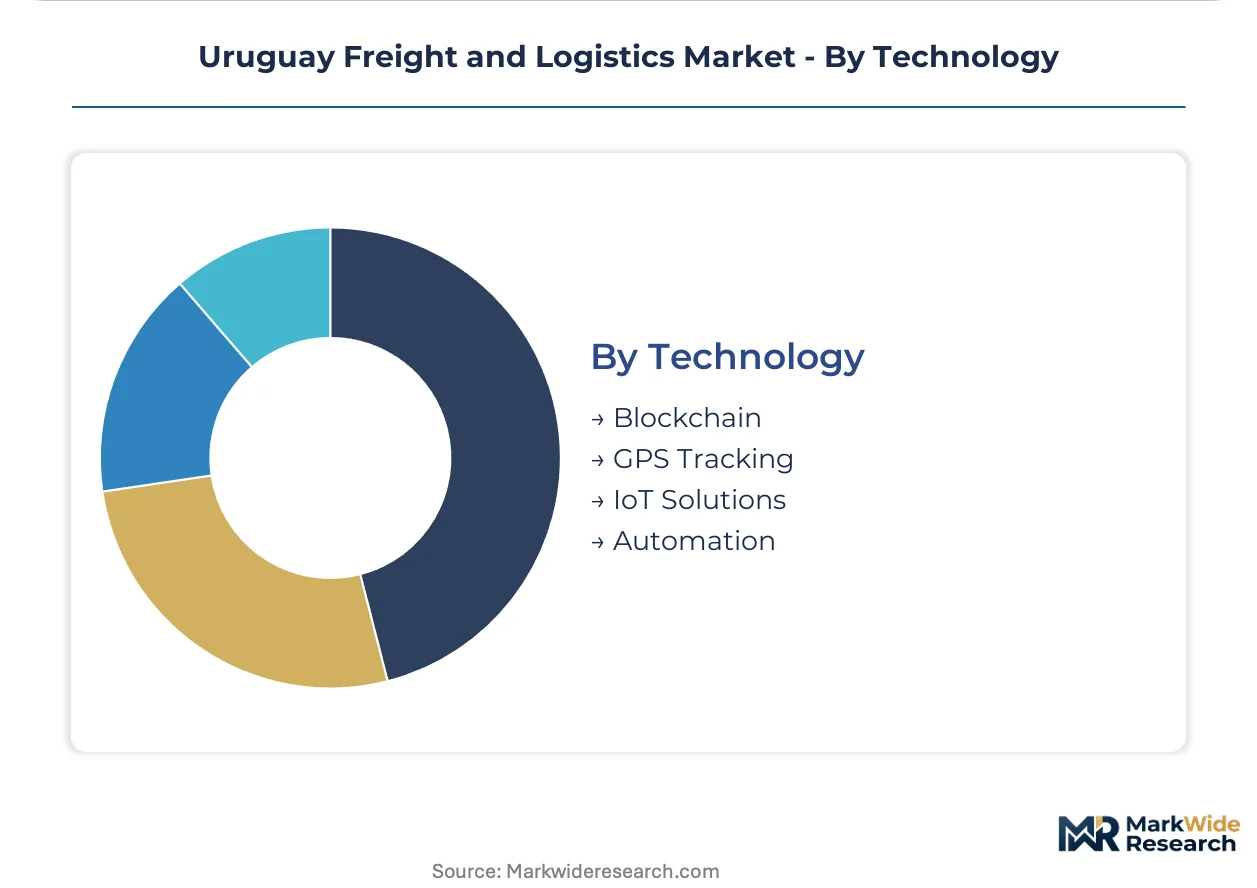
Technology:
Maturity-stage adoption separates proven tracking systems from emerging automation investments with longer payback horizons.
- GPS Tracking:Telematics-enabled fleet monitoring now dominates temperature-controlled trucking dispatch coordination across interior agricultural routes.
- IoT Solutions:Sensor-based cargo tracking for soybean and beef exports compresses insurance premiums and enables temperature-excursion penalties in outcome-based contracts.
- Blockchain:Document verification pilots for Mercosur customs documentation remain experimental with limited carrier adoption.
- Automation:Automated container handling systems at Montevideo terminal upgrades reduce vessel loading windows under SOLAS compliance mandates.
GPS Tracking holds the largest share; IoT Solutions are gaining share fastest as exporter insurance structures evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Uruguay's freight corridors balance agricultural export dominance against import-dependent manufacturing supply chains. The Montevideo-Nueva Palmira axis concentrates container throughput while interior regions struggle with last-mile connectivity gaps. Sub-regional performance splits between port-proximate logistics clusters and underdeveloped agricultural hinterlands.
Montevideo Metropolitan Corridor
Container transshipment flows and bonded warehousing demand anchor logistics investment in the capital region. The Ministry of Transport and Public Works oversees axle-load enforcement on access highways serving the port complex. Specialized reefer services at Montecon's terminal operations compress dwell times for temperature-sensitive agricultural exports bound for Asian markets.
Nueva Palmira Agricultural Belt
Soybean exporters are scaling cold-chain storage capacity to meet EU phytosanitary certification requirements. The Uruguayan Revenue Service administers Mercosur customs protocols that elevate documentation complexity for cross-border grain movements. Temperature-controlled infrastructure clusters around river terminals where barge-to-ship transfers reduce road freight exposure to weight-limit penalties.
Colonia Free Trade Zone
Bonded warehouse certification expansion attracts regional distribution hub strategies targeting Mercosur transshipment tax advantages. National logistics plan incentives prioritize customs facilitation technology deployment in this western corridor. Logistics providers position inventory for Brazilian and Argentine market access without triggering full import duty liability.
Durazno-Río Negro Logistics Axis
Agro-industrial corridor development presents untapped warehousing positioning for soy derivatives and meat processing exports. Intermodal rail-road coordination gains share as infrastructure investments mature along this central route. Cold-chain operators face equipment downtime risks from refrigeration technician scarcity extending maintenance intervals.
Interior Agricultural Zones
Domestic trucking routes connecting remote production areas to coastal terminals operate under fragmented last-mile coverage. Digital freight platforms penetrate underdigitized dispatch coordination between interior zones and port facilities. Grupo Ras dominates these corridors where asymmetric service coverage favors port-to-port contracts over door-to-door commitments.
Uruguay Freight and Logistics Market Competitive Landscape
Concentration sits with port-centric terminal operators and integrated freight forwarding networks serving agricultural export corridors. Market structure splits between specialized cold-chain providers and diversified logistics conglomerates with Mercosur regional coverage. Three archetypes dominate: domestic trucking specialists with interior route control, global forwarders leveraging Buenos Aires corridor links, and terminal operators with reefer handling certification. Capacity expansion at Montevideo container terminals and customs brokerage service bundling represent the primary competitive moves reshaping contract structures.
Among domestic operators, Grupo Ras exemplifies the interior route specialist archetype with established agricultural zone connectivity. Montecon anchors the port-centric operator tier through specialized reefer infrastructure at Montevideo. DSV A/S represents the global forwarder model extending European-origin networks into Uruguayan hinterlands via regional corridor links. These three occupy distinct positioning layers rather than direct competition, with service overlap concentrated in customs brokerage and bonded warehousing segments.
| Leading Market Players |
|---|
| Grupo Ras |
| Montecon |
| Ues |
| Corfrisa |
| Malatic |
| STL Depot |
| DHL Group |
| A.P. Moller-Maersk |
| DSV A/S |
| Others |
Pricing and Supply Chain Analysis
SOLAS verified gross mass compliance gates both carrier market access and pricing power across Uruguay's containerized export corridors, compressing vessel loading windows while forcing capital-intensive weighing infrastructure investments that separate certified operators from price-competitive challengers.
Pricing Analysis
Industrial OEM buyers anchor contract structures around long-term offtake agreements with volume-scale discounts, while agricultural exporters trading spot soybean cargoes absorb premium rates for temperature-integrity guarantees. Price differentiation hinges on ISO reefer certification tier and after-sales maintenance bundling, with door-to-door contracts commanding substantial premiums over port-to-port alternatives. Cost compression in standard container segments is intensifying because Montecon's terminal expansion adds handling capacity, eroding incumbent margins. Trading houses serving Asian markets exhibit lowest price sensitivity due to consolidated procurement power, whereas interior agricultural cooperatives face acute cost pressure from axle-load regulatory constraints.
Supply Chain Analysis
Inventory positioning at port-proximate warehouses compresses lead times for Mercosur transshipment flows, with bonded stock rotating through Montevideo and Nueva Palmira terminals under strict dwell-time penalties. Geographic supply concentration draws from Argentina, Brazil, and Paraguay for cross-border trucking capacity, while refrigerated equipment manufacturing rests on imports from China and Germany. Refrigerant input volatility under EU F-Gas Regulation spillover effects creates single-source vulnerability for cold-chain fleet operators. Distribution runs through Montevideo-centric hub-and-spoke configurations with fragmented last-mile extensions into interior agricultural zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized refrigeration technician scarcity constrains fleet expansion timelines across Uruguay's temperature-controlled trucking sector, creating asymmetric capability gaps that favor incumbent operators with established maintenance networks over capital-rich market entrants.
For Market Incumbents: Consolidate customs brokerage capabilities through acquisition of regional documentation specialists, defending against global forwarders bundling services under single-provider contracts. Deepen backward integration into cold-chain equipment leasing to capture margin pools currently flowing to third-party reefer lessors, while securing exclusive technician training pipelines with Uruguayan technical institutes. For New Entrants and Emerging Players: Anchor in the Durazno-Río Negro logistics axis where agro-industrial corridor investments outpace established service coverage, targeting soy derivatives exporters with intermodal rail-road coordination capabilities. Penetrate through digital freight platforms offering real-time cargo matching on underdigitized interior routes, avoiding direct confrontation with Grupo Ras's entrenched agricultural zone trucking control. For Investors and Strategic Acquirers: Mercosur customs protocol digitization reshapes the acquisition landscape toward technology-enabled customs brokerage platforms with electronic data interchange certification. Five-to-ten-year viability favors targets combining bonded warehouse assets with proprietary tracking software integration. The signal to watch is Uruguayan Revenue Service tender awards for automated clearance system upgrades, indicating regulatory momentum toward platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | ISO-certified reefer capacity at Nueva Palmira meets EU phytosanitary standards for soybean exports. |
| Digital Freight Platform Deployment | Real-time cargo matching penetrates underdigitized interior trucking routes between agricultural zones and coastal terminals. |
| Customs Brokerage Consolidation | Integrated documentation services capture premium margins from Mercosur cross-border complexity. |
| Intermodal Rail-Road Coordination | Durazno-Río Negro logistics axis development reduces road freight exposure to axle-load restrictions. |
| Bonded Warehouse Certification | Colonia Free Trade Zone positioning enables Mercosur transshipment tax advantages for regional distribution hubs. |
Research Methodology
Cross-validation between terminal operator operational data and Uruguayan Revenue Service customs clearance statistics anchors the qualitative findings, supplemented by primary interviews with port authority planners, cold-chain fleet managers, agricultural export trading house logistics directors, and customs brokerage principals. Secondary validation draws from national logistics plan policy documents, Mercosur customs protocol amendments, SOLAS implementation guidelines, and container throughput reports from the national port authority. Bottom-up service provider revenue estimates triangulate against top-down trade flow valuations across the analysis window.
Sensitivity analysis around refrigerant pricing volatility and port capacity expansion timelines informs the analytical framework. Segmentation dimensions modeled include service type, delivery model, end-user industry, and technology adoption tier, with additional granularity on temperature-control certification levels. CAGRs derive from trend extrapolation of historical trade volumes against infrastructure investment pipelines, incorporating soybean export phytosanitary compliance thresholds and meat processing capacity buildouts as industry-specific demand drivers throughout the forecast period.
Material uncertainties — regulatory delays in port concession renewals, accelerated road deterioration beyond maintenance schedules, and Mercosur customs union protocol revisions — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Global Sea Air Logistics Market
Logistics and Shipping
GCC Contract Logistics Market
Logistics and Shipping
Ukraine Freight and Logistics Market
Logistics and Shipping
Global Automated Container Terminal Market
Logistics and Shipping
Malaysia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Egypt 3PL Market
Logistics and Shipping
North America Cargo Handling Equipment Market
Logistics and Shipping
Europe Full Container Load (FCL) Market
Logistics and Shipping
Peru Cold Chain Logistics Market
Logistics and Shipping
Saudi Arabia Secure Logistics Market
Logistics and Shipping
Smart Container Market
Logistics and Shipping
India less than Truckload Road Freight Transport Market
Logistics and Shipping
Netherlands Cold Chain Logistics Market
Logistics and Shipping
China less than-Truck-Load (LTL) Market
Logistics and Shipping
Latin America Air Freight Market
Logistics and Shipping
Asean Freight Forwarding Market