
 Europe Contract Logistics Market | 2026-2036
Europe Contract Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Contract Logistics Market Foresight
Market Context
ISO 9001 certification is rotating as a baseline qualification for contract logistics tenders across European procurement desks, filtering out operators lacking standardized quality management systems. Deutsche Post DHL Group leverages its integrated parcel and freight networks to dominate cross-border e-commerce fulfillment lanes. Kuehne + Nagel sustains competitive position through specialized pharmaceutical cold chain infrastructure. XPO Logistics anchors its European footprint with dense less-than-truckload coverage in France and Iberia.
Technical Definition and Segment Structure
Europe contract logistics encompasses outsourced supply chain management services where third-party providers assume operational control of transportation, warehousing, inventory management, and order fulfillment under multi-year contractual agreements, typically spanning three to seven years with performance-based service level agreements. The primary commercial purpose centers on converting fixed logistics assets into variable costs while injecting network scale and information technology capabilities that individual shippers cannot replicate internally. Warehousing services command the deepest margin pools due to real estate scarcity and automation intensity around automated storage and retrieval systems in the Benelux corridor. Value-added services represent the fastest-expanding segment as brands demand kitting, labeling, and last-mile customization at distribution nodes rather than at origin factories. Transportation services remain structurally mature with thin margins, though dedicated contract arrangements with automotive manufacturers in Germany and eastern Europe offer volume stability.
Regulatory Framework and Outlook
The EU Green Deal and F-Gas Regulation are reshaping fleet procurement standards, pushing logistics operators toward electric and hydrogen-powered tractor units for depot-to-depot haulage. ECHA's REACH compliance requirements extend to chemical storage and handling protocols within contract logistics facilities, particularly affecting warehousing contracts for industrial coatings and pharmaceutical intermediates. GDPR mandates constrain how customer shipment data flows between logistics platforms and end-user visibility systems. Stakeholders must monitor how CSRD disclosure obligations will force contract logistics clients to audit scope three emissions from their outsourced supply chain partners.
Market Dynamics
EU Green Deal emissions mandates are forcing fleet electrification across European logistics corridors, converting diesel tractor assets into stranded capital while reshaping contract tender requirements around carbon disclosure.
Growth Catalysts
- Automotive outsourcing waves:German and Polish manufacturers are transferring inbound parts sequencing and finished vehicle distribution to third-party operators under seven-year dedicated contracts.
- E-commerce fulfillment density:Parcel volume concentration around Rotterdam and Amsterdam distribution nodes is pulling automated warehousing investment into the Netherlands corridor.
- REACH compliance services:ECHA chemical handling protocols are creating specialized contract niches for hazardous goods warehousing and cross-dock operations.
Market Restraints
- Real estate scarcity:Benelux industrial land availability constraints are inflaming site acquisition costs for greenfield distribution centers.
- Electrification capex burdens:Depot charging infrastructure and battery-electric tractor procurement are compressing operating margins before scale economies emerge.
- GDPR data friction:Customer shipment visibility restrictions are limiting platform interoperability between logistics providers and shipper ERP systems.
Strategic Opportunities
- Pharmaceutical cold chain expansion:Temperature-controlled cell and gene therapy distribution is opening premium-margin contract segments across Germany and Switzerland.
- Hydrogen corridor development:EU Green Deal hydrogen infrastructure subsidies are enabling zero-emission long-haul pilot programs along Rhine-Alpine freight corridors.
- Value-added service bundling:Kitting, labeling, and last-mile customization at distribution nodes are displacing origin-factory finishing for consumer electronics brands.
Industry Challenges
- Warehouse automation talent gaps:Automated storage and retrieval system maintenance technicians remain scarce across the Benelux and northern Germany labor markets.
- CSRD audit preparation:Scope three emissions disclosure obligations are forcing logistics providers to reconstruct decade-old subcontractor fuel data.
Report Scope
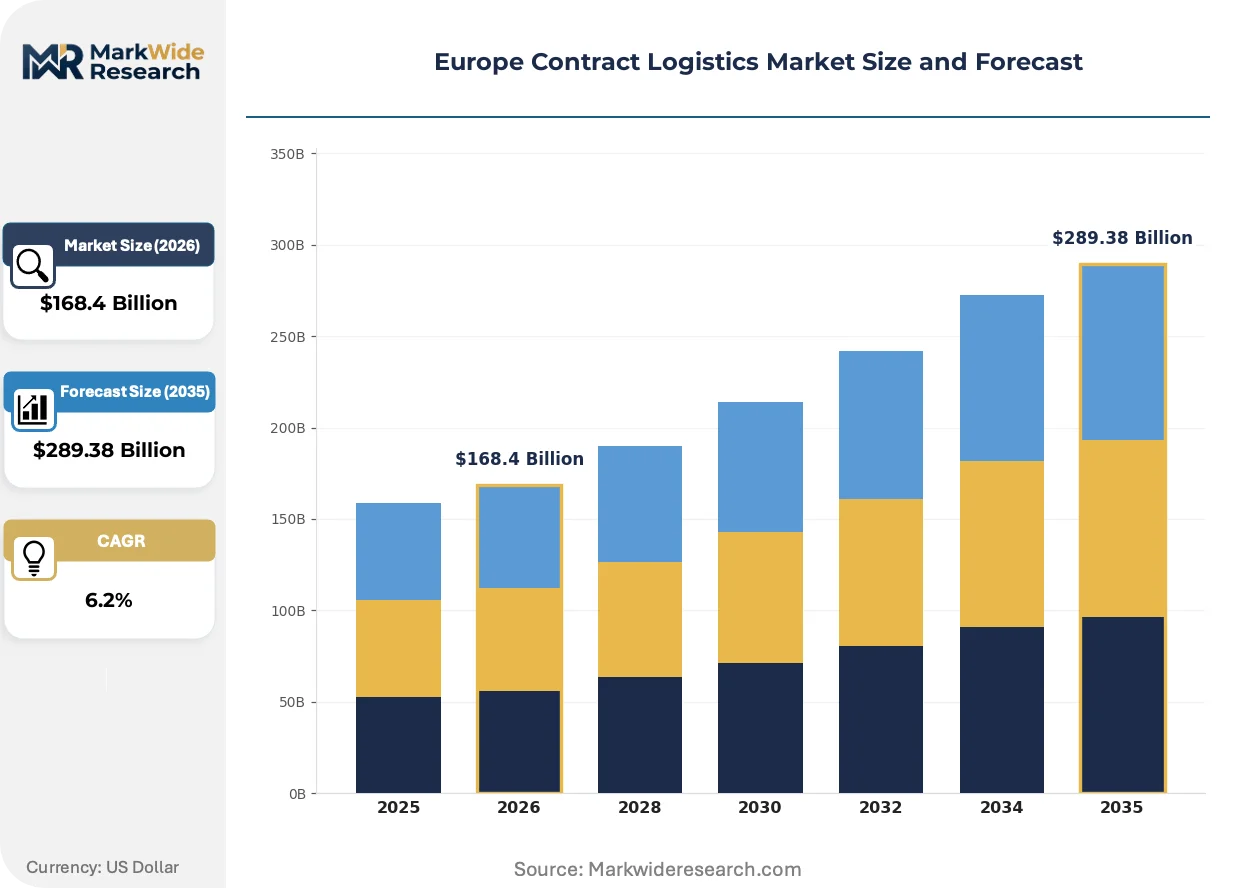
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Contract Logistics Market |
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $289.38 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Value-Added Services Industry Vertical: Manufacturing, Retail, Healthcare, Automotive Distribution Channel: Online, Offline, Hybrid, Direct Contract Type: Outsourced, Managed, Dedicated, Project-Based |
| Companies Covered | XPO Logistics, Kuehne + Nagel, Deutsche Post DHL Group, GEODIS, DB Schenker, DSV, CEVA Logistics, Lineage Logistics, GXO Logistics, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Contract Logistics Market Shifts & Advancements
Digital warehouse management systems and alternative powertrains are restructuring how European contract logistics operators compete on speed, carbon intensity, and labor productivity.
Autonomous mobile robots for goods-to-person picking is bifurcating warehouse labor models across European distribution centers. German automotive parts suppliers are deploying these systems at scale in Saxony and Bavaria facilities. The technology is compressing order cycle times while fragmenting the vendor landscape between robotics specialists and integrated platform providers.
F-Gas Regulation phase-down schedules are accelerating industrial refrigeration retrofits in temperature-controlled warehousing. Cold storage operators face asset write-downs on conventional compressor systems ahead of 2030 bans. Pharmaceutical logistics contracts in Belgium and the Netherlands are incorporating explicit refrigerant transition clauses.
Shippers are consolidating vendor relationships around integrated parcel-freight-warehousing platforms rather than point-solution contracts. Mid-market retailers in France and Spain are terminating single-service agreements in favor of multi-year partnerships with network-scale providers. This concentration is visible most acutely in Iberian e-commerce fulfillment where cross-border complexity demands unified visibility layers.
Europe Contract Logistics Market Segmentation
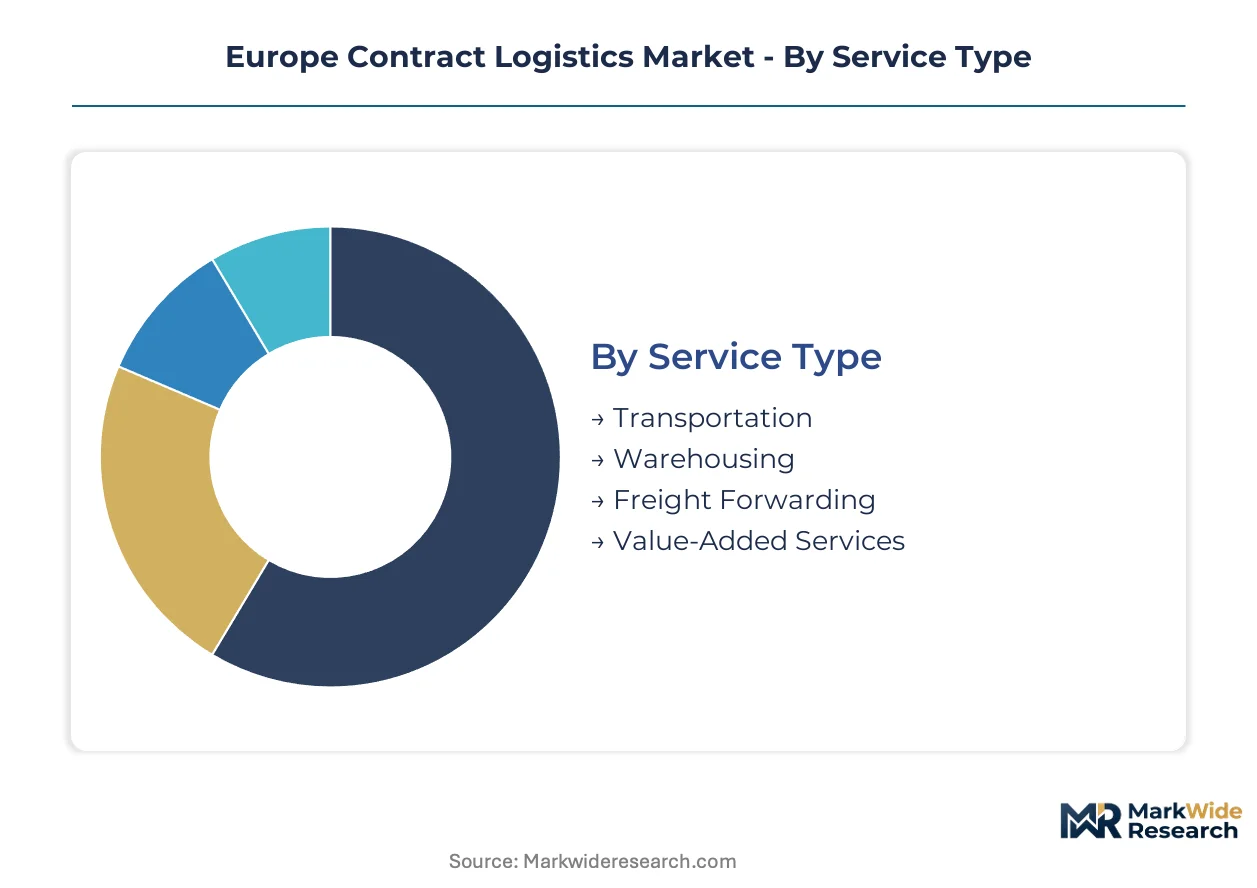
Segmentation reveals how margin pools concentrate across service types and contract structures in European contract logistics. Understanding these divisions exposes where pricing power accumulates and where commoditization pressures dominate.
Service Type:
Warehousing commands the deepest margin pools due to real estate scarcity and automation intensity, while transportation services remain structurally compressed.
- Transportation:Dedicated contract arrangements with automotive manufacturers in Germany and eastern Europe offer volume stability. Thin margins persist across spot freight and general haulage segments.
- Warehousing:Automated storage and retrieval systems in the Benelux corridor extract premium pricing. Real estate constraints around Rotterdam and Amsterdam inflate site acquisition costs while protecting incumbent yields.
- Freight Forwarding:Cross-border customs brokerage and multimodal coordination services concentrate in Rotterdam and Hamburg gateway corridors.
- Value-Added Services:Kitting, labeling, and last-mile customization at distribution nodes are displacing origin-factory finishing for consumer electronics brands.
Warehousing holds installed capacity. Value-added services are rotating up the share rankings.
Industry Vertical:
Automotive and healthcare verticals concentrate premium-margin contracts due to compliance complexity and just-in-time delivery requirements.
- Manufacturing:Inbound parts sequencing and vendor-managed inventory contracts dominate German industrial corridors. OEMs convert fixed logistics assets into variable costs through multi-year agreements.
- Retail:E-commerce fulfillment density around Dutch distribution nodes pulls automated warehousing investment. Parcel volume concentration demands unified visibility layers.
- Healthcare:Temperature-controlled cell and gene therapy distribution opens premium-margin segments across Germany and Switzerland. EMA cold chain validation requirements filter out generalist operators.
- Automotive:German and Polish manufacturers transfer finished vehicle distribution to third-party operators under seven-year dedicated contracts. REACH compliance for coatings and adhesives adds specialized handling protocols.
Automotive holds installed capacity. Healthcare is rotating up the share rankings.
Distribution Channel:
Channel selection determines data architecture requirements and last-mile cost structures across European logistics networks.
- Online:Direct-to-consumer parcel flows demand micro-fulfillment nodes within two-hour delivery radii of major cities. GDPR constraints limit customer shipment visibility between platforms and shipper ERP systems.
- Offline:Traditional retail replenishment relies on scheduled full-truckload movements to regional distribution centers. Volume stability supports dedicated fleet arrangements.
- Hybrid:Buy-online-pickup-in-store models require inventory synchronization across warehouse and retail floor systems. Belgian and Dutch retailers lead deployment.
- Direct:Manufacturer-to-consumer bypass of retail intermediaries compresses margin extraction opportunities for logistics intermediaries.
Offline holds installed capacity. Hybrid is rotating up the share rankings.
Contract Type:
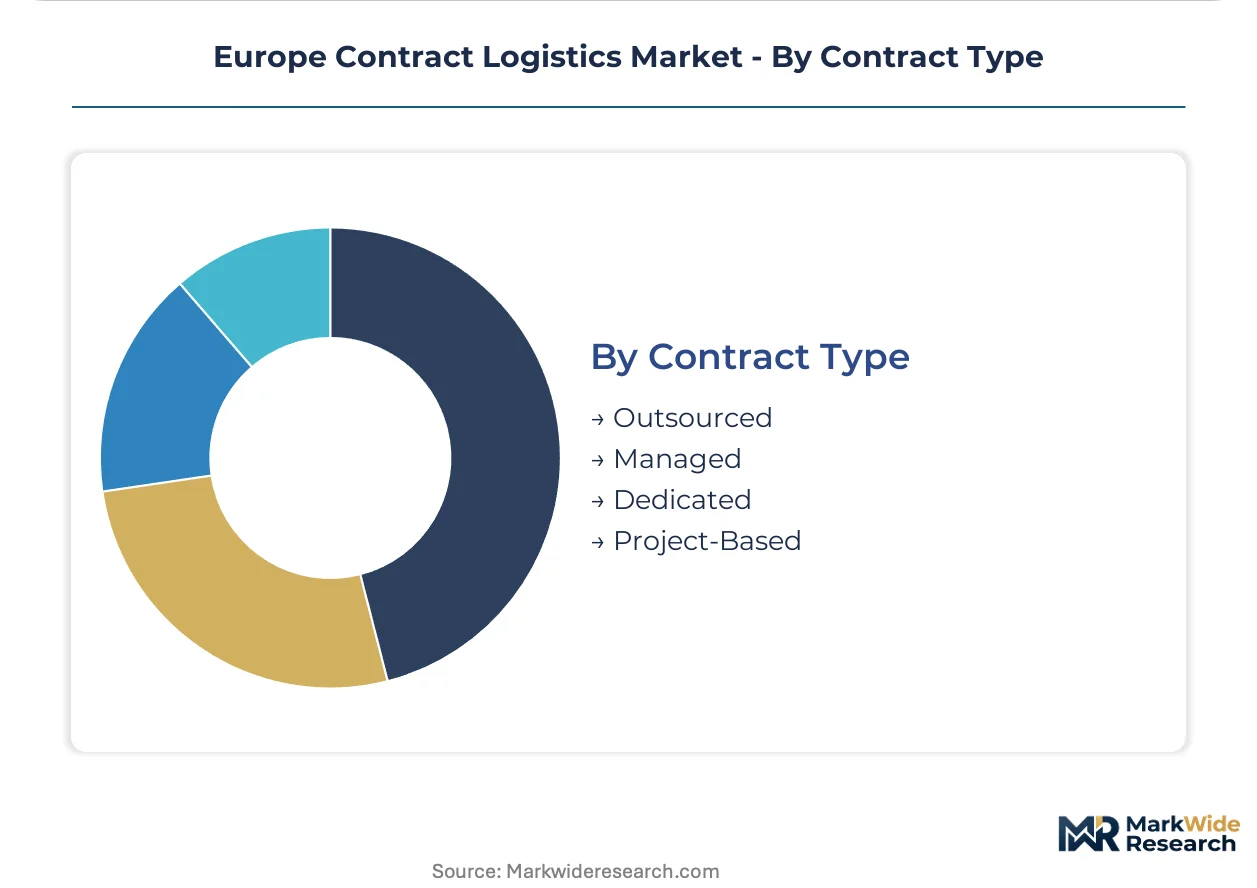
Contract duration and operational control levels segment risk allocation between shipper and provider across European tender processes.
- Outsourced:Third-party providers assume full operational control under three-to-seven year agreements with performance-based service level agreements. ISO 9001 certification filters tender participation.
- Managed:Shipper retains asset ownership while contracting operational execution. CSRD disclosure obligations force reconstruction of decade-old subcontractor fuel data.
- Dedicated:Exclusive fleet and facility commitments for single-shipper volumes. German automotive parts suppliers deploy autonomous mobile robots at scale in Saxony and Bavaria facilities.
- Project-Based:Short-term arrangements for product launches, facility relocations, or seasonal peaks. Limited technology investment recovery constrains automation deployment.
Outsourced holds installed capacity. Dedicated is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive manufacturers and Dutch distribution hubs concentrate procurement authority for contract logistics services across Europe. Buyers in Poland and the Czech Republic are expanding dedicated fleet arrangements. Southern European retailers are consolidating vendor relationships around integrated fulfillment platforms.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg are transferring inbound parts sequencing to third-party operators under seven-year dedicated contracts. The KBA enforces strict commercial vehicle emissions standards that accelerate fleet electrification timelines. Stuttgart and Wolfsburg industrial corridors host dense concentrations of automated warehousing serving just-in-time manufacturing networks.
Netherlands
E-commerce fulfillment density around Rotterdam and Amsterdam is pulling automated storage and retrieval system investment into the Randstad region. The EU Green Deal mandates depot charging infrastructure for electric tractor units operating on cross-border lanes. Eindhoven-Brabant distribution nodes serve as multimodal gateways for northern European consumer goods flows.
Poland
German manufacturers are extending contract logistics networks into Lower Silesia and Greater Poland voivodeships for cost-advantaged warehousing. REACH compliance requirements from ECHA govern chemical handling protocols for industrial coatings storage. Poznań and Wrocław logistics parks are absorbing overflow capacity from saturated Benelux industrial land markets.
France
Mid-market retailers in Île-de-France are terminating single-service agreements in favor of multi-year partnerships with network-scale providers. The F-Gas Regulation accelerates refrigeration retrofits in temperature-controlled facilities serving pharmaceutical distribution. Lyon and Marseille logistics clusters consolidate cross-border customs brokerage for Mediterranean trade corridors.
Switzerland
Pharmaceutical cold chain operators are expanding temperature-controlled cell and gene therapy distribution infrastructure around Basel and Zurich. Swissmedic cold chain validation requirements filter out generalist operators from premium-margin healthcare contracts. The Rhine-Alpine freight corridor connects Swiss pharmaceutical hubs to Rotterdam port gateways.
Europe Contract Logistics Market Competitive Landscape
Player mix skews toward diversified network operators with integrated parcel-freight-warehousing capabilities. Tier-one providers dominate cross-border e-commerce fulfillment through dense European asset footprints. Mid-scale specialists occupy niche positions in pharmaceutical cold chain and hazardous goods handling. Competitive moves center on strategic partnerships for hydrogen corridor development and portfolio diversification into value-added services.
Within the integrated network tier, Deutsche Post DHL Group and Kuehne + Nagel exemplify archetypes that combine parcel density with specialized infrastructure. XPO Logistics anchors a position in less-than-truckload coverage across France and Iberia. These operators represent how scale and specialization combine to capture multi-year contract renewals in automotive and healthcare verticals.
| Leading Market Players |
|---|
| XPO Logistics |
| Kuehne + Nagel |
| Deutsche Post DHL Group |
| GEODIS |
| DB Schenker |
| DSV |
| CEVA Logistics |
| Lineage Logistics |
| GXO Logistics |
| Others |
Supply & Pricing Matrix
Asset utilization rates above 85 percent in Rotterdam and Amsterdam automated warehousing clusters create natural price floors that protect incumbent margins while compressing returns for new greenfield entrants. This scale concentration shapes how automotive OEMs in Germany negotiate multi-year dedicated contracts versus how mid-market retailers in France procure spot transportation services.
Pricing Analysis
Cost-plus contracts with diesel price indexation dominate European transportation procurement, though EU Green Deal carbon disclosure requirements are inserting emissions-adjusted pricing clauses into seven-year automotive agreements. Price differentiation separates ISO 9001-certified operators commanding premium warehousing rates in the Benelux corridor from uncertified competitors competing on spot freight margins. Pricing pressure stems from depot electrification capex burdens compressing operator yields before scale economies emerge in battery-electric tractor procurement. Mid-market retailers in Iberia exhibit highest price sensitivity, while pharmaceutical manufacturers in Switzerland accept premium cold chain rates without volume negotiation.
Supply Chain Analysis
Just-in-time inventory strategies among German automotive OEMs contrast with strategic stockpiling preferences in Polish chemicals warehousing responding to REACH compliance lead times. Supply concentrates in Germany, the Netherlands, and Poland, with component dependencies on automated storage and retrieval systems, battery-electric tractor units, and specialized refrigerants for pharmaceutical cold chains. Single-source vulnerability runs through Benelux industrial land scarcity constraining greenfield distribution center development. Distribution runs through Rotterdam and Hamburg gateway corridors consolidating multimodal freight flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe contract logistics sits in early-cycle expansion as automotive outsourcing waves convert fixed logistics assets into variable costs under multi-year agreements. E-commerce fulfillment density around Dutch distribution nodes accelerates penetration of automated warehousing services among mid-market retailers previously served by fragmented spot providers.
For Market Incumbents: Fortify dedicated contract positions in German automotive corridors through exclusive deployment of autonomous mobile robots at Saxony and Bavaria facilities, insulating against margin erosion from electrification capex. Deepen certification moats around EMA cold chain validation requirements to filter out generalist competitors from pharmaceutical distribution tenders. Prioritize hydrogen corridor pilot programs along Rhine-Alpine freight routes to capture EU Green Deal infrastructure subsidies before scale mandates harden.
For New Entrants and Emerging Players: Temperature-controlled cell and gene therapy distribution in Basel and Zurich represents the most penetrable premium segment, where Swissmedic validation requirements have filtered out incumbent generalists. Polish logistics parks in Poznań and Wrocław offer cost-advantaged warehousing overflow from saturated Benelux land markets. A go-to-market angle anchored in REACH compliance services for industrial coatings storage exploits ECHA protocol complexity that incumbent transport specialists under-serve.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among operators with dedicated automotive contracts and pharmaceutical cold chain infrastructure, where multi-year agreements generate visible cash flows across macro cycles. Long-term viability favors diversified network operators integrating parcel density with specialized vertical capabilities rather than single-service point solutions. Watch hydrogen infrastructure subsidy allocation decisions as the inflection signal separating early zero-emission corridor developers from stranded diesel asset holders.
| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Dedicated Contract Expansion | Seven-year agreements with German OEMs convert fixed assets into variable costs while locking in volume stability. |
| Pharmaceutical Cold Chain Certification | EMA and Swissmedic validation requirements filter out generalists from premium-margin cell therapy distribution. |
| Hydrogen Corridor Development | EU Green Deal subsidies enable zero-emission pilot programs along Rhine-Alpine freight routes before scale mandates. |
| Autonomous Mobile Robot Deployment | Goods-to-person picking systems in Saxony and Bavaria compress order cycle times while fragmenting vendor landscapes. |
| Benelux Industrial Land Acquisition | Rotterdam and Amsterdam site scarcity protects incumbent warehousing yields while inflaming greenfield entry costs. |
Research Methodology
Initial hypotheses were tested against primary input from logistics procurement directors at German automotive OEMs, warehouse operations managers in Dutch distribution clusters, and regulatory compliance officers at pharmaceutical cold chain operators, then refined through secondary validation. Trade data from Eurostat customs filings, ECHA REACH registration databases, EU Green Deal implementation progress reports, and operator SEC disclosures provided demand-side calibration. Bottom-up contract value estimates triangulated against top-down market size benchmarks across service type and industry vertical segmentations.
Variance decomposition across the projection horizon isolates volume drivers from price mix effects within each modeled segment. Segmentation dimensions include service type, industry vertical, distribution channel, and contract structure, with regional adoption patterns capturing divergent electrification timelines under national transpositions of EU fleet mandates. CAGRs derive from logistic curve penetration modeling of automated warehousing adoption and automotive outsourcing saturation. Industry-specific inputs incorporate ECHA chemical handling protocol expansion schedules and KBA commercial vehicle emissions enforcement intensity.
Underlying assumptions cover EU Green Deal implementation continuity, ECHA regulatory scope stability, and automotive production volume recovery, with deviation risk concentrated in hydrogen infrastructure subsidy allocation timing and Benelux industrial land availability shocks. Revision becomes warranted when battery-electric tractor unit procurement cost curves cross diesel parity thresholds ahead of modeled trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Singapore Shipping Agency Services Market
Logistics and Shipping
Multi-Enterprise Logistics Contract and SLA Performance Management Platforms Market
Logistics and Shipping
Multicarrier Shipping Software Market
Logistics and Shipping
Saudi Arabia Contract Logistics Market
Logistics and Shipping
GCC Finished Vehicle Logistics Market
Logistics and Shipping
Asia-Pacific Shipping Agency Services Market
Logistics and Shipping
Fine Art Logistics Market
Logistics and Shipping
South Korea Parcel Delivery Market
Logistics and Shipping
Air Cargo Capacity and Allotment Marketplace Platforms Market
Logistics and Shipping
Japan E-Commerce Logistics Market
Logistics and Shipping
Germany Express Delivery Market
Logistics and Shipping
Germany Freight and Logistics Market
Logistics and Shipping
Indonesia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Last Mile Delivery Transportation Market
Logistics and Shipping
Peru Freight and Logistics Market
Logistics and Shipping
Poland Third Party Logistics (3PL) Market