
 Container Terminal Automation Market | 2026-2036
Container Terminal Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Container Terminal Automation Market Analysis
Software-defined fleet orchestration is recalibrating what terminal operators purchase, shifting capital budgets from standalone hardware toward integrated automation platforms. Konecranes leverages its deep crane automation heritage to anchor long-term service contracts with major shipping lines. ABB competes through its electrification and digital portfolio, extending into shore power and automated stacking systems. CyberLogitec specializes in terminal operating system software, controlling the data layer that coordinates vessel, yard, and gate workflows.
Container terminal automation encompasses the mechanized, sensor-driven, and algorithmically controlled systems that move, stack, and track containers within port facilities, typically operating with positioning precision within centimeters and cycle times measured in seconds per move. Its primary commercial purpose is to compress vessel berthing duration, reduce labor dependency, and raise throughput per hectare of terminal footprint. Crane automation and automated guided vehicles represent the most capital-intensive technology segments, where margin pools concentrate among vendors with proven integration capabilities. Cloud-based and hybrid deployment models are gaining share as terminal operators seek to offload infrastructure costs while retaining operational control over critical yard management functions.
The International Maritime Organization's emissions reduction framework shapes equipment specifications, compelling vendors to electrify automated guided vehicles and crane systems. China's MIIT and SAMR enforce domestic robotics and industrial automation standards that influence product certification for equipment deployed at Chinese ports. The EU's F-Gas Regulation and CE marking requirements constrain refrigerant and hydraulic system choices in European terminal infrastructure. Stakeholders must monitor how evolving cybersecurity mandates for critical port infrastructure reshape software procurement criteria and vendor qualification processes.
Market Dynamics
Software-defined orchestration platforms are compressing traditional equipment procurement cycles as terminal operators consolidate crane, vehicle, and yard management systems under unified automation architectures rather than standalone mechanical upgrades.
Growth Catalysts
- EU Green Deal mandates:Terminal operators across Rotterdam, Hamburg, and Antwerp are electrifying automated guided vehicle fleets to meet emissions reduction frameworks, accelerating replacement of diesel-powered yard equipment.
- China's port modernization:State-backed infrastructure programs at Ningbo, Qingdao, and Shanghai are driving dense deployments of automated stacking cranes and robotic container handling systems.
- Vessel upsizing pressures:Ultra-large container carriers now exceeding twenty-four thousand TEU capacity are forcing terminal operators to automate quay crane cycles to maintain berthing schedule integrity.
Market Restraints
- Specialized steel and sensor input volatility:High-grade structural steel and LiDAR sensor modules face concentrated supply from East Asian foundries and photonics manufacturers, exposing automation project budgets to raw material price swings.
- Cybersecurity compliance friction:Evolving critical infrastructure protection mandates from national port authorities are extending vendor qualification timelines and inflating pre-deployment certification costs.
- Technical integration complexity:Retrofitting automated systems into existing terminal layouts with legacy crane foundations and constrained yard geometries imposes severe civil engineering constraints on brownfield sites.
Strategic Opportunities
- Underpenetrated Southeast Asian hubs:Port authorities in Vietnam, Indonesia, and the Philippines are initiating first-generation automation programs at emerging transshipment terminals with greenfield design flexibility.
- Convergence of digital twin and predictive maintenance:Real-time physics simulation layered with equipment health monitoring is enabling condition-based crane servicing that reduces unplanned downtime.
- Shore power infrastructure expansion:EU F-Gas Regulation and port electrification incentives are creating bundled procurement opportunities where automated yard systems integrate with vessel cold-ironing capabilities.
Industry Challenges
- Control systems engineering talent scarcity:Terminal automation vendors and port operators compete for limited pools of PLC programmers, robotics integration specialists, and maritime cybersecurity architects.
- Legacy TOS migration complexity:Brownfield terminals running decades-old terminal operating systems face data architecture fragmentation when connecting to modern API-driven automation platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Container Terminal Automation Market |
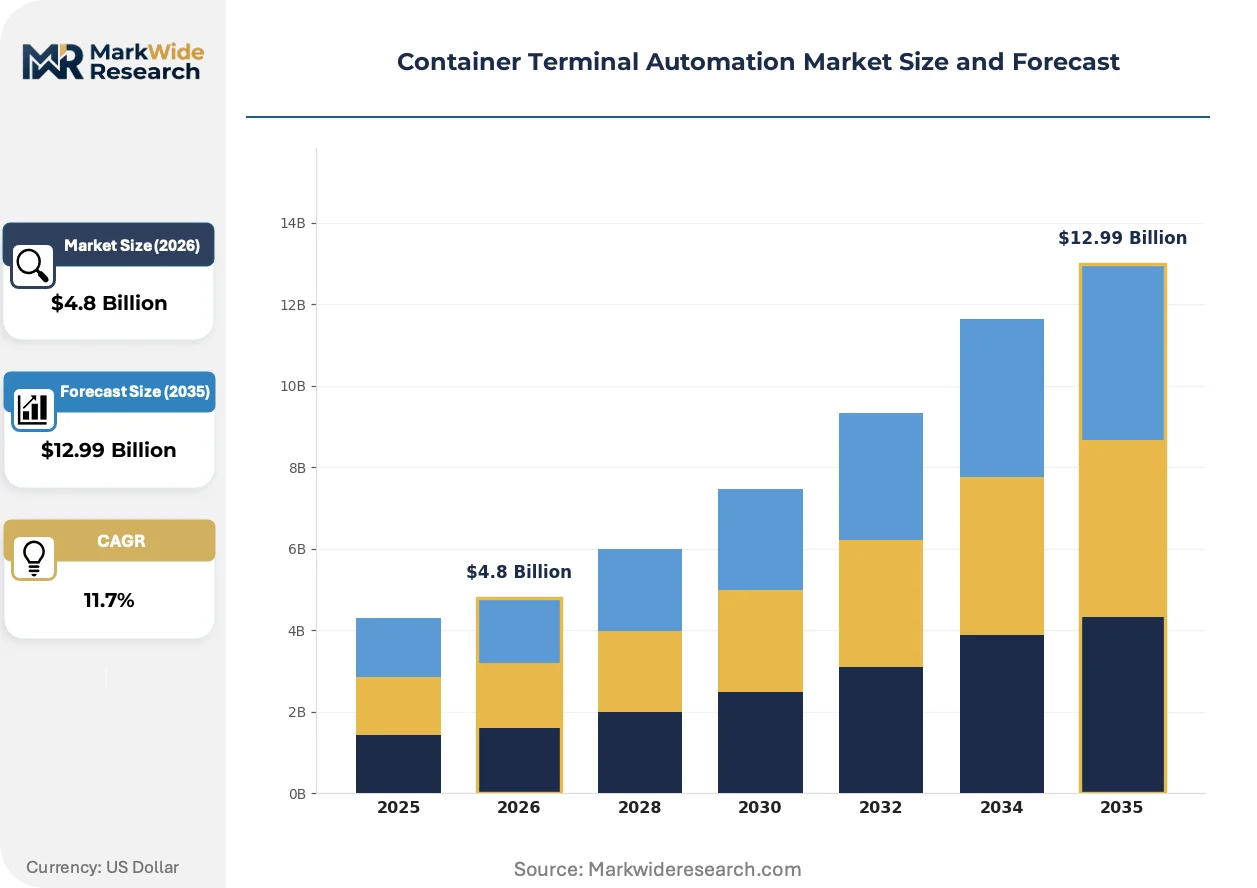
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Automated Guided Vehicles, Docking Systems, Robotic Arms, Crane Automation End User: Shipping Lines, Terminal Operators, Freight Forwarders, Logistics Providers Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Application: Loading Operations, Unloading Operations, Inventory Management, Yard Management |
| Companies Covered | Cargotec (Kalmar), Konecranes, ZPMC, ABB, Liebherr, Siemens Logistics, CyberLogitec, Navis, IDENTEC SOLUTIONS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Container Terminal Automation Market Emerging Trajectories
Artificial intelligence is penetrating every layer of terminal operations, from crane trajectory optimization to predictive berth scheduling, while electrification and edge computing architectures reshape physical infrastructure investment priorities.
Computer vision-based container damage detection is overtaking manual inspection protocols at automated gate complexes and quay cranes. Major European and Chinese terminals are deploying multi-camera arrays with neural network classification to identify structural defects, seal integrity issues, and hazardous material placard discrepancies in under ten seconds per container. This technology is compressing liability exposure and insurance premium structures while eliminating inspection bottlenecks at peak vessel arrival windows.
The EU AI Act's risk classification framework is imposing algorithmic transparency requirements on automated decision systems controlling yard vehicle routing and crane sequencing. Terminal operators must now maintain audit trails for AI-driven equipment dispatch commands and demonstrate human oversight protocols for safety-critical automation functions. Equipment vendors serving Rotterdam, Valencia, and Greek port complexes are restructuring software architectures to embed explainability modules and compliance documentation generators.
Shipping lines are consolidating vendor relationships around integrated automation platforms rather than procuring cranes, vehicles, and operating systems from separate suppliers. Terminal operators at Singapore, Busan, and Los Angeles-Long Beach are negotiating single-source contracts spanning mechanical equipment, control software, and twenty-year service agreements. This concentration is visible most acutely at transshipment hubs where vessel schedule reliability directly determines carrier contract renewals and terminal concession competitiveness.
Container Terminal Automation Market Segmentation
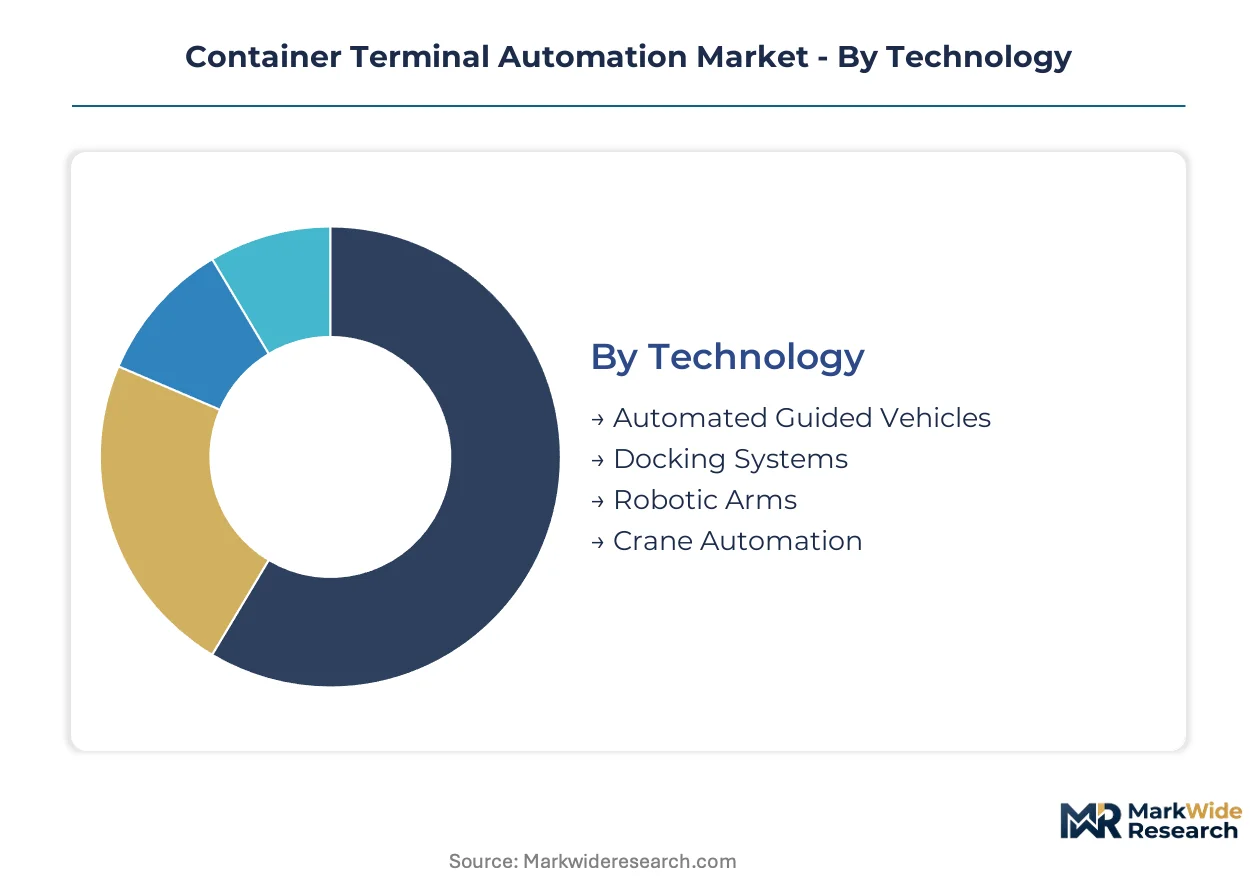
Terminal automation procurement diverges sharply across technology maturity, operational scale, and integration complexity. Shipping lines and port authorities allocate capital differently based on berth throughput requirements and legacy infrastructure constraints.
Technology:
Standardized mechanical systems dominate volume procurement while software-defined orchestration platforms command customization premiums and long-term service attach rates.
- Crane Automation:Quay crane and rubber-tired gantry systems integrate sensor fusion, anti-sway algorithms, and precision positioning to compress vessel berthing windows. Rotterdam and Shanghai terminals are densifying deployments to handle twenty-four thousand TEU vessels. Cybersecurity certification timelines from national port authorities extend deployment schedules.
- Automated Guided Vehicles:Battery-electric and hydrogen fuel cell yard tractors navigate via LiDAR, magnetic tape, or inductive guidance with centimeter positioning accuracy. EU Green Deal mandates at Hamburg and Antwerp are accelerating diesel fleet replacements. Raw material volatility in high-grade structural steel and photonics components inflates project budgets.
- Docking Systems:Mooring automation and vessel alignment sensors reduce gangway deployment time and personnel exposure at berth interfaces.
- Robotic Arms:Container lashing and twistlock handling robots address repetitive strain injuries and labor shortage at high-throughput terminals.
Most installed capacity flows through Crane Automation. Expansion is steepest in Automated Guided Vehicles.
End User:
Capital deployment intensity correlates with asset ownership structure and direct exposure to vessel schedule penalties.
- Terminal Operators:Concession holders at Singapore, Busan, and Los Angeles-Long Beach integrate full-stack automation across quay, yard, and gate operations to secure carrier contract renewals. Brownfield civil engineering constraints at legacy sites complicate retrofit timelines.
- Shipping Lines:Maersk, MSC, and CMA CGM are consolidating vendor relationships around single-source automation platforms spanning mechanical equipment, control software, and twenty-year service agreements. Vessel upsizing pressures force automation investments to maintain schedule integrity.
- Freight Forwarders:NVOCCs and cargo consolidators access automation through terminal service contracts rather than direct capital expenditure.
- Logistics Providers:Third-party logistics firms coordinate with automated terminals for drayage optimization and empty container repositioning.
Terminal Operators control the majority of deployed automation assets. Shipping Lines are expanding fastest through vertical integration into terminal operations.
Deployment:
Infrastructure ownership preferences split between control retention and cost offloading.
- Hybrid:Split architectures keep critical yard management on-premises while pushing analytics and fleet optimization to cloud instances. This model dominates at European and Chinese terminals balancing data sovereignty with compute elasticity.
- Cloud-Based:Fully hosted terminal operating systems reduce capital intensity for mid-tier ports in Vietnam, Indonesia, and the Philippines initiating first-generation automation programs.
- On-Premises:Air-gapped control systems persist at facilities with stringent critical infrastructure protection mandates.
- Managed Services:Vendor-operated automation as a service transfers operational risk and talent scarcity burdens to equipment suppliers.
Hybrid deployments account for the largest installed base. Cloud-Based models are climbing the fastest among greenfield Southeast Asian terminals.
Application:
Operational priority determines automation sequencing with direct revenue impact at the quay crane interface.
- Yard Management:Stacking algorithms, chassis pooling, and container positioning optimization maximize throughput per hectare. State-backed programs at Ningbo, Qingdao, and Shanghai are driving dense automated stacking crane deployments. Legacy terminal operating system migration complexity fragments data architecture at brownfield sites.
- Loading Operations:Automated quay crane cycles and vessel stowage planning compress berthing duration for ultra-large container carriers. Multi-camera computer vision arrays with neural network classification now identify container damage and hazardous material placard discrepancies in under ten seconds.
- Unloading Operations:Discharge automation mirrors loading sophistication with added complexity for customs inspection integration.
- Inventory Management:Real-time container tracking and predictive berth scheduling layer digital twin simulation over equipment health monitoring.
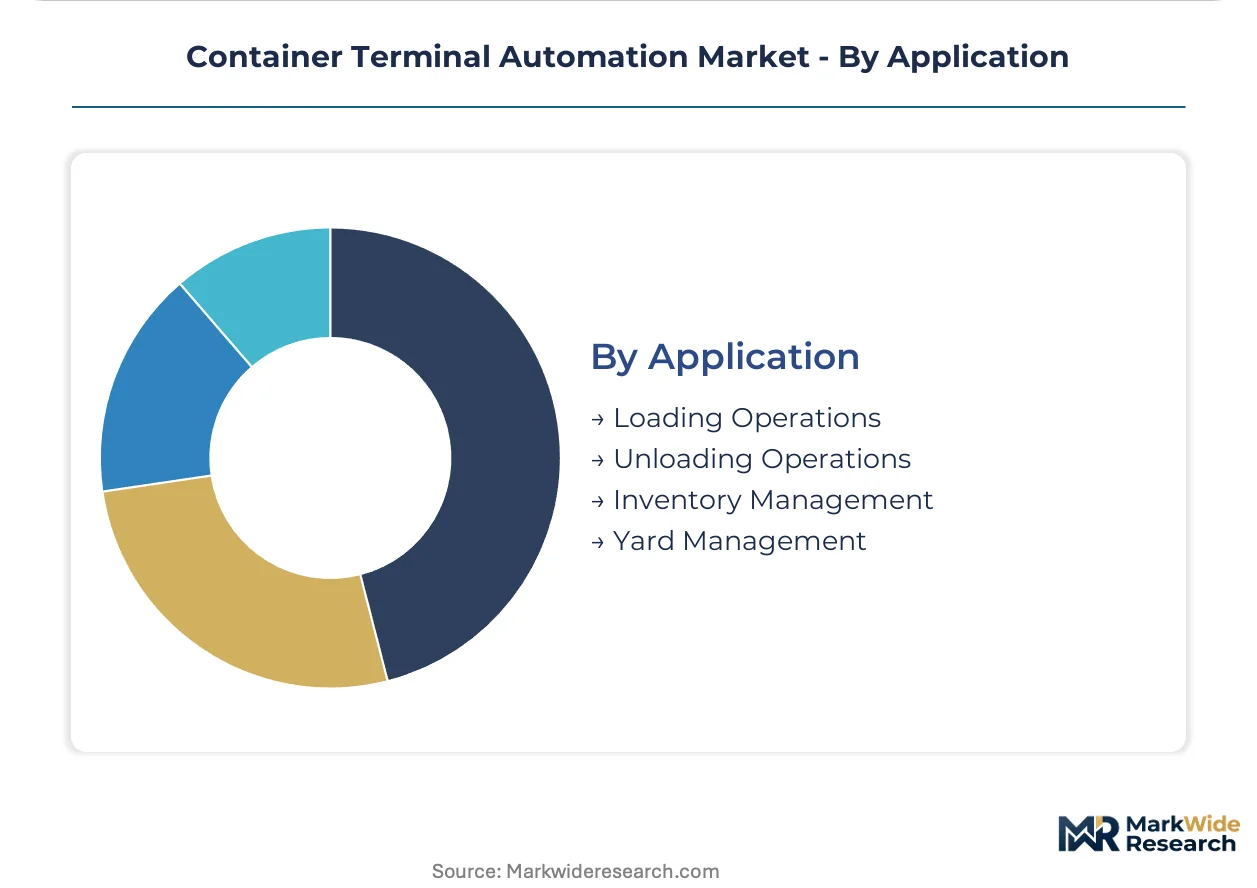
Yard Management absorbs the greatest automation investment. Loading Operations are gaining share fastest from vessel upsizing pressures and carrier schedule reliability demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys automated stacking cranes at three times the density of European terminals, while the United States concentrates investment at transshipment hubs facing labor contract pressures. Regulatory divergence between EU emissions mandates and Chinese state-directed port modernization is fragmenting vendor certification requirements.
China
State-backed infrastructure programs at Ningbo, Qingdao, and Shanghai are accelerating dense deployments of automated stacking cranes and robotic container handling systems. MIIT and SAMR enforce domestic robotics and industrial automation standards that influence equipment certification for port deployments. The Yangtze River Delta and Pearl River Delta clusters absorb the majority of domestic crane automation procurement.
United States
Terminal operators at Los Angeles-Long Beach and Savannah are automating quay crane cycles to mitigate labor availability constraints and vessel schedule penalties. OSHA and Coast Guard cybersecurity directives for critical port infrastructure extend vendor qualification timelines. The Pacific Northwest and Gulf Coast port complexes are initiating first-generation yard automation retrofits.
Germany
Hamburg and Bremerhaven terminal operators are electrifying automated guided vehicle fleets to comply with EU Green Deal emissions reduction frameworks. The F-Gas Regulation constrains refrigerant and hydraulic system choices in terminal infrastructure upgrades. Northern Germany's port cluster leads European procurement of battery-electric yard tractors.
Singapore
The Port of Singapore Authority is consolidating full-stack automation across quay, yard, and gate operations to secure carrier contract renewals amid transshipment competition. Maritime and Port Authority cybersecurity mandates reshape software procurement criteria for terminal operating systems. The Tuas megaport development represents the densest greenfield automation deployment in Southeast Asia.
Netherlands
Rotterdam terminal operators are bundling automated yard systems with vessel cold-ironing shore power infrastructure to capture EU port electrification incentives. ECHA REACH compliance requirements influence material specifications for crane structural components. The Rotterdam port complex anchors European demand for integrated automation platforms.
Container Terminal Automation Market Vendor Landscape
Top-tier vendors anchor integrated automation platforms, while specialized component suppliers compete on crane subsystems and sensor modules. The market structure concentrates around equipment vendors with proven civil engineering integration capabilities and software-defined orchestration expertise. Strategic archetypes include full-stack platform providers, crane automation heritage specialists, and terminal operating system pure-plays. Competitive moves center on twenty-year service contract anchoring and single-source procurement consolidation.
Among heritage crane automation specialists, Konecranes and Liebherr exemplify vendors leveraging mechanical equipment expertise to secure long-term maintenance agreements. ZPMC represents the scale-driven fabrication archetype, while CyberLogitec and Navis occupy positions within the terminal operating system layer that coordinates vessel, yard, and gate workflows. ABB and Siemens Logistics sit within the electrification and digital portfolio segment, extending into shore power and automated stacking systems.
| Leading Market Players |
|---|
| Cargotec (Kalmar) |
| Konecranes |
| ZPMC |
| ABB |
| Liebherr |
| Siemens Logistics |
| CyberLogitec |
| Navis |
| IDENTEC SOLUTIONS |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap crane automation specialists anchor pricing discipline through captive service networks, while sovereign-backed Chinese fabricators compress hardware margins through state-financed capacity expansion. This ownership bifurcation concentrates supply-side pricing power among European and Japanese vendors with proven integration track records, even as procurement officers exploit competitive tension between heritage suppliers and emerging platform providers.
Pricing Analysis
Capacity additions in China are reshaping price floors for standardized crane subsystems, forcing European and Japanese vendors toward bundled automation platforms with twenty-year service contracts. Pricing stratifies across premium certified tiers, mid-market integrated packages, and economy hardware-only configurations, with differentiation resting on cybersecurity certification depth and civil engineering integration guarantees. Cost compression in the economy tier stems from ZPMC's scale-driven fabrication model. Terminal operators at greenfield Southeast Asian sites exhibit highest price sensitivity, while transshipment hub concessionaires at Singapore and Rotterdam prioritize schedule reliability over procurement cost.
Supply Chain Analysis
Freight costs from East Asian photonics clusters to European port automation sites have amplified total landed cost volatility for LiDAR and sensor modules. Supply concentrates in China for high-grade structural steel and precision-machined crane components, Germany for PLC control systems and industrial software, and South Korea for battery-electric vehicle powertrains. Raw material dependencies span rare-earth magnets for AGV motors, high-tensile steel alloys for crane structures, and semiconductor-grade photonics for positioning sensors. Single-source vulnerability runs through concentrated LiDAR module fabrication. Distribution runs through direct vendor-terminal operator contracting with EPC intermediaries for brownfield retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container terminal automation represents a late-cycle quality story where vessel upsizing pressures and EU emissions mandates are concentrating procurement toward premium integrated platforms with proven cybersecurity architectures.
For Market Incumbents: Deepen long-term service contract anchoring with major shipping lines to defend against single-source procurement consolidation by integrated platform competitors. Extend backward integration into shore power and edge computing infrastructure to capture bundled electrification incentives at Rotterdam and Hamburg. Prioritize certification investment for EU AI Act algorithmic transparency requirements. For New Entrants and Emerging Players: Cloud-native terminal operating system deployment offers the most penetrable entry vector for mid-tier Vietnamese and Indonesian ports initiating first-generation automation programs. Target greenfield Southeast Asian transshipment terminals with hybrid deployment models that offload analytics infrastructure costs while retaining operational control. Pursue channel partnerships with regional EPC contractors to bypass direct competition with heritage crane vendors. For Investors and Strategic Acquirers: Valuations sit cheapest among terminal operating system pure-plays with established API architectures but limited mechanical equipment integration. Long-term viability over the next decade hinges on software-defined orchestration capabilities rather than crane fabrication scale. Monitor EU port authority cybersecurity mandate enforcement velocity as the critical inflection signal for vendor qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Single-Source Platform Consolidation | Maersk and MSC are bundling crane, vehicle, and software procurement under unified vendor relationships. |
| Electrification Infrastructure Bundling | Rotterdam terminal operators integrate AGV fleets with vessel cold-ironing shore power to capture EU Green Deal incentives. |
| Cybersecurity Certification Investment | OSHA and Coast Guard directives extend vendor qualification timelines, favoring incumbents with established compliance documentation. |
| Digital Twin Convergence | Real-time physics simulation layered with predictive maintenance reduces unplanned crane downtime at high-throughput terminals. |
| Southeast Asian Greenfield Expansion | Vietnam and Indonesia port authorities initiate first-generation automation programs with design flexibility absent at legacy sites. |
Methodological Framework
Bottom-up terminal operator procurement modeling reconciled against top-down crane and AGV shipment tracking forms the analytical core of this study. Primary interviews with port authority planning officers, terminal operations directors, EPC contractors, and maritime cybersecurity architects were validated against secondary sources including customs trade data, SEC filings of listed port equipment vendors, EU port electrification program disclosures, and Chinese MIIT robotics deployment statistics.
Input-output matrices connect equipment installation volumes to throughput capacity expansion across technology, end-user, deployment, and application dimensions. CAGRs were derived from regression analysis of historical procurement patterns against vessel size trajectories and regulatory mandate timelines. Industry-specific forecast inputs include ultra-large container carrier orderbook data and EU Green Deal compliance deadline clustering.
The model assumes a particular technology adoption path; alternative pathways for hydrogen fuel cell AGV deployment would alter the outlook if fuel infrastructure investments accelerate ahead of battery-electric saturation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Fine Art Logistics Market
Logistics and Shipping
Moving Services (Mover and Packers) Market
Logistics and Shipping
India 3PL Market
Logistics and Shipping
Slovakia Freight and Logistics Market
Logistics and Shipping
North America Sea Freight Forwarding Market
Logistics and Shipping
IoT Spend by Logistics Industry Market
Logistics and Shipping
Asean Freight and Logistics Market
Logistics and Shipping
Global Dry Bulk Shipping Market
Logistics and Shipping
Egypt 3PL Market
Logistics and Shipping
Cross-Border Logistics Services Market
Logistics and Shipping
Singapore Last Mile Delivery Market
Logistics and Shipping
Germany Same Day Delivery Market
Logistics and Shipping
South Africa Freight and Logistics Market
Logistics and Shipping
Mexico Containerized Shipping Market
Logistics and Shipping
Contract Logistics Market
Logistics and Shipping
United Kingdom Contract Logistics Market