
 Fertilizer Bags Market | 2026-2036
Fertilizer Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Fertilizer Bags Market Foresight
Aftermarket logistics services is rewriting margin capture in fertilizer packaging as distributors seek turnkey inventory management rather than commodity bag supply. Greif leverages its industrial packaging footprint to anchor North American bulk container demand through dedicated agricultural field teams. Mondi Group differentiates via kraft paper-based barrier solutions that compete against conventional polyethylene for European horticultural clients. LC Packaging sustains its position in woven polypropylene through regional manufacturing scale across multiple agricultural corridors.
Fertilizer bags are engineered transport and storage containers, typically fabricated from woven polypropylene, multi-layer polyethylene laminates, or kraft paper composites with moisture barriers measured in grams per square meter, designed to prevent caking, spillage, and nutrient degradation during distribution. Granular formulations occupy the dominant volume position due to mechanical handling compatibility with standard filling equipment, while liquid packaging in collapsible intermediate bulk containers represents the fastest-growing material format as precision agriculture expands fertigation systems. Multi-layer material constructions command premium positioning where extended outdoor storage demands ultraviolet stabilization and humidity resistance, particularly in tropical agricultural zones.
EPA container containment regulations shape product design requirements for pesticide-adjacent fertilizer applications in the United States, while REACH compliance in Europe restricts certain phthalate plasticizers in polyethylene formulations. India's BIS certification mandates tensile strength and seam integrity benchmarks for woven sacks distributed through the public distribution system. Stakeholders must monitor evolving extended producer responsibility frameworks and substrate-specific recycling mandates as these will determine material qualification and regional market access viability.
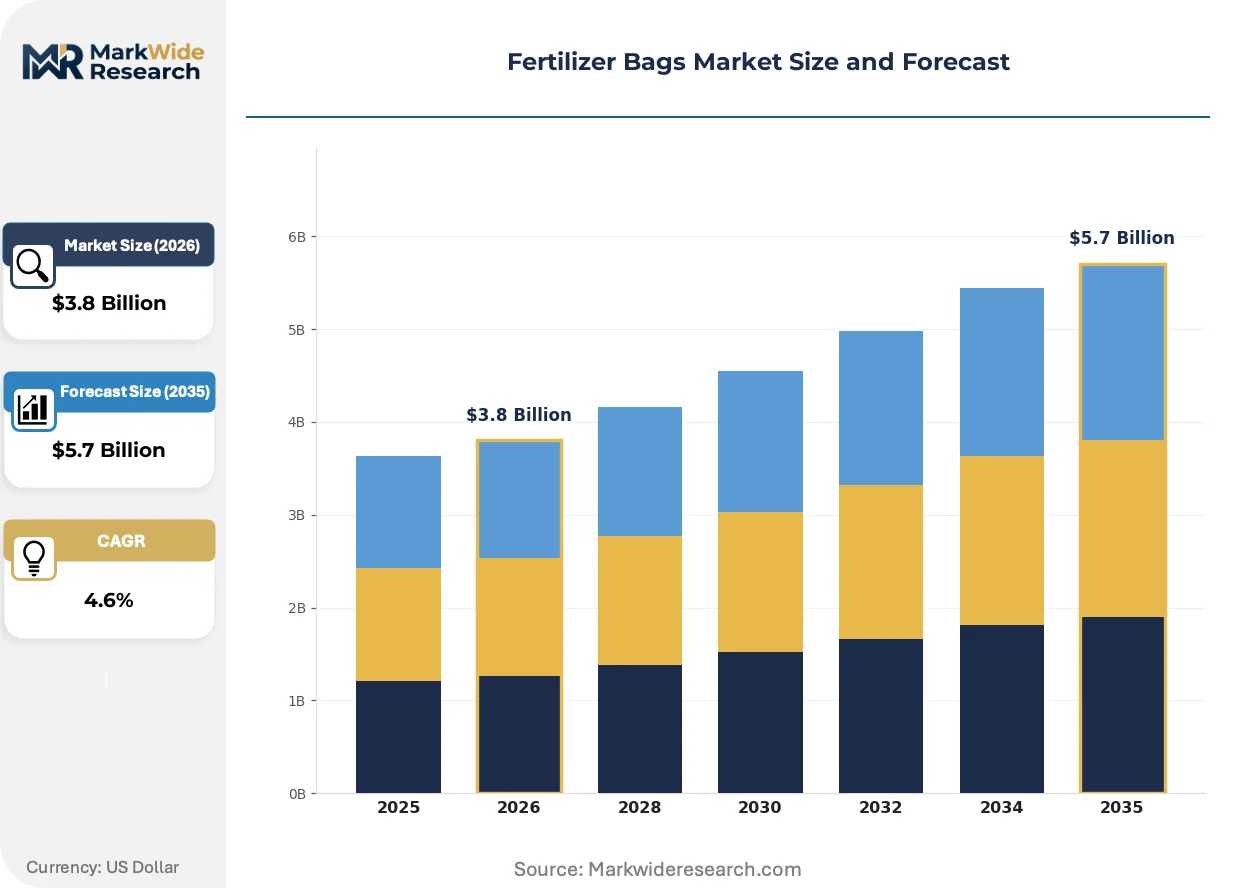
Market Dynamics
Aftermarket logistics services are compressing margins for commodity bag suppliers while rewarding integrated packaging-plus-inventory management providers across major agricultural corridors.
Growth Catalysts
- California's Department of Pesticide Regulation containment standards:Specialty crop producers in the Central Valley now mandate multi-layer laminated bags with enhanced spillage prevention, driving specification upgrades across nut and vine operations.
- Precision agriculture expansion:Collapsible intermediate bulk containers for liquid fertilizers are displacing rigid drums as fertigation systems proliferate in controlled-environment agriculture.
- India's cooperative procurement networks:Bulk tote formats dominate urea distribution through the public distribution system, favoring woven polypropylene suppliers with regional manufacturing scale.
Market Restraints
- Polypropylene resin price volatility:Crude oil-linked feedstock costs create margin compression for woven bag converters without long-term supply contracts.
- REACH compliance friction:ECHA restrictions on phthalate plasticizers in polyethylene formulations force reformulation cycles that delay European market entry.
- Extended outdoor storage limitations:Conventional single-layer kraft paper composites degrade within 90 days of tropical humidity exposure, ceding share to laminated alternatives.
Strategic Opportunities
- Brazil's soybean belt mechanization:Automated filling equipment at grain elevators creates demand for standardized bulk bag formats with integrated lifting loops.
- EU Green Deal packaging waste directives:Extended producer responsibility frameworks incentivize mono-material recyclable constructions that simplify end-of-life processing.
- RFID-enabled inventory tracking:Convergence of woven polypropylene with embedded sensor tags enables real-time traceability for high-value specialty fertilizer blends.
Industry Challenges
- BIS certification timelines:India's tensile strength and seam integrity testing protocols create 4-6 month approval delays for new woven sack designs entering the public distribution system.
- Legacy equipment retrofit costs:Converting filling lines from valve bags to open-mouth formats for bulk totes requires capital expenditure that mid-sized cooperatives defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fertilizer Bags Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Liquid, Powder, Soluble Material: Polyethylene, Paper, Jute, Multi-layer End Use: Agricultural, Horticultural, Landscaping, Gardening Packaging Type: Bag, Sack, Tote, Bulk |
| Companies Covered | Berry Global, Greif, Amcor plc, LC Packaging, NNZ Group, Sonoco Products Company, ProAmpac, CDF Corporation, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fertilizer Bags Market Shifts & Advancements
Material science advances and regulatory tightening are converging to redefine performance specifications across fertilizer packaging formats, with sustainability mandates accelerating substrate transitions.
Multi-layer polyethylene laminates with ultraviolet stabilization and humidity barriers measured in grams per square meter are collapsing the performance gap between premium outdoor storage solutions and economy-grade single-layer alternatives. Specialty crop producers in Mediterranean climates now specify these constructions for seasonal inventory holding, compressing the addressable market for conventional woven polypropylene with secondary tarpaulin coverage. The technology enables 18-month field storage without caking or nutrient degradation.
REACH restrictions on phthalate plasticizers are compelling polyethylene formulation changes across European horticultural supply chains. Compounders must certify alternative plasticizer systems through ECHA's substance evaluation process, extending product development cycles by 12-18 months. German and Dutch distributors are qualifying kraft paper-based barrier solutions from Mondi Group as interim substitutes while awaiting polymer reformulation approvals.
Turnkey inventory management contracts are displacing spot bag procurement among North American agricultural distributors. Greif anchors this shift through dedicated agricultural field teams that embed at customer facilities to manage container pooling, cleaning, and rotation. The model concentrates purchasing authority with fewer decision-makers, compressing supplier counts across the Corn Belt and Pacific Northwest specialty crop regions.
Fertilizer Bags Market Segmentation
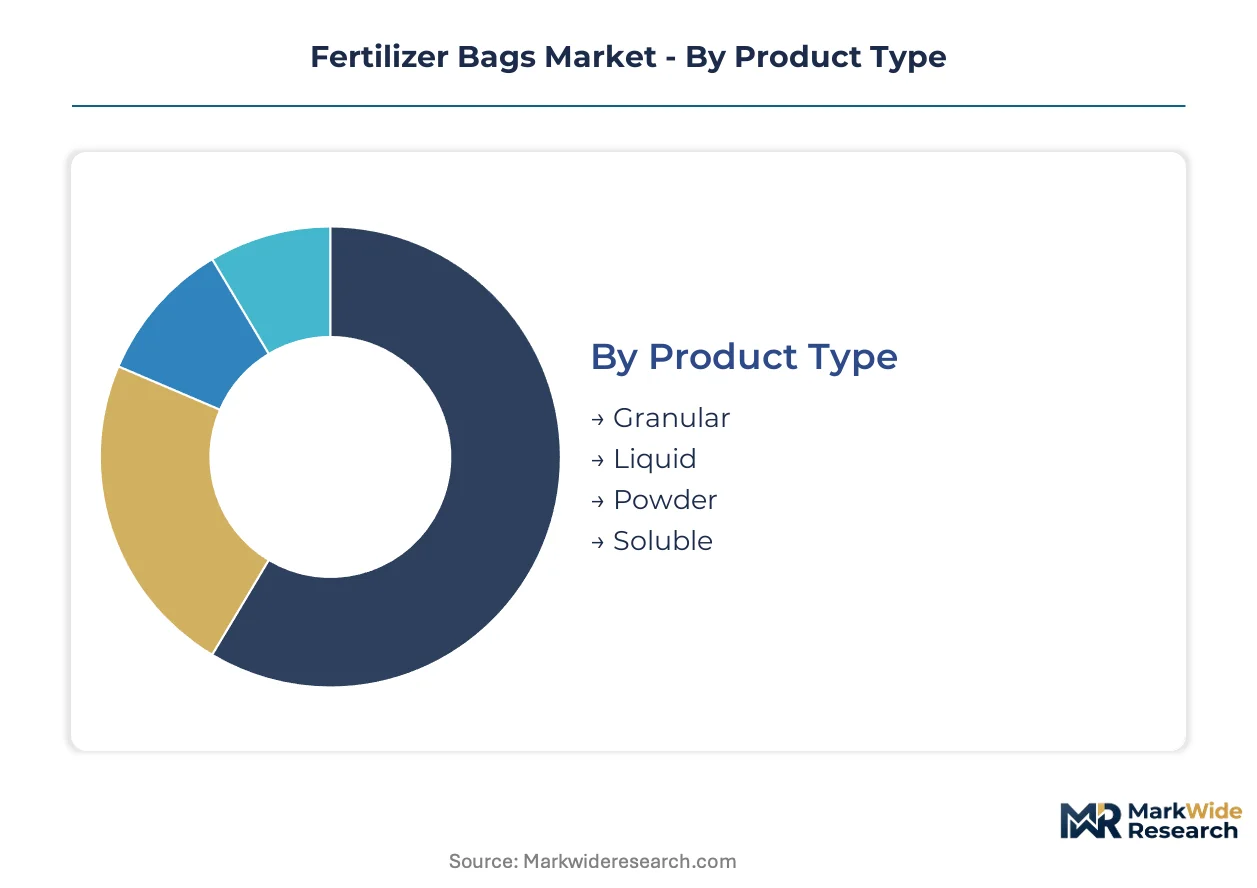
Packaging specification varies sharply across fertilizer formulations and distribution channels. Material selection and format sizing determine handling compatibility, shelf stability, and compliance with regional containment mandates.
Product Type:
Application chemistry and physical state dictate filling equipment requirements and barrier specifications across the value chain.
- Granular:Free-flowing crystalline or prilled formulations suit woven polypropylene valve bags with 25-50kg standard fill weights. Mechanized handling at grain elevators and cooperative procurement networks in India's wheat belt favor this format for urea and NPK blends.
- Liquid:Collapsible intermediate bulk containers with multi-layer polyethylene constructions enable precision agriculture fertigation systems. Controlled-environment agriculture in California's Central Valley and greenhouse clusters in the Netherlands drive specification upgrades for UV-stabilized, chemically resistant barrier films.
- Powder:Fine-particle formulations require anti-caking liners and moisture barriers measured in grams per square meter to prevent clumping during tropical storage.
- Soluble:Fully dissolvable concentrates for fertigation and foliar application demand water-soluble film overwraps or specialized laminate pouches.
Granular holds installed capacity. Liquid is rotating up the share rankings.
Material:
Substrate economics and regulatory compliance timelines shape converter sourcing decisions across agricultural corridors.
- Polyethylene:Multi-layer laminates with humidity barriers and UV stabilization enable 18-month outdoor storage without nutrient degradation. REACH restrictions on phthalate plasticizers force ECHA-compliant reformulation cycles that extend European product development timelines.
- Paper:Kraft-based barrier solutions from Nordic suppliers compete for horticultural clients seeking interim substitutes during polymer recertification. Conventional single-layer composites degrade within 90 days of tropical humidity exposure, limiting deployment to climate-controlled distribution.
- Jute:Natural fiber constructions serve heritage branding and biodegradability mandates in specialty organic fertilizer segments.
- Multi-layer:Laminated constructions combining woven polypropylene substrates with polyethylene film barriers command premium positioning where extended field storage and spillage prevention are mandated.
Polyethylene dominates volume throughput. Multi-layer is climbing the fastest as containment standards tighten.
End Use:
Customer operational scale and crop value intensity determine packaging performance tier and service integration requirements.
- Agricultural:Broadacre grain and oilseed operations favor bulk tote formats with integrated lifting loops for automated filling equipment at grain elevators. Brazil's soybean belt mechanization creates demand for standardized FIBC specifications.
- Horticultural:High-value nut and vine operations in California's Central Valley specify multi-layer laminated bags under Department of Pesticide Regulation containment standards. Mondi Group anchors European demand through kraft paper-based barrier solutions.
- Landscaping:Commercial turf and municipal maintenance programs favor mid-volume sack formats with weather-resistant outer treatments.
- Gardening:Retail consumer channels drive small-format polyethylene bags with printed branding and reseal features for home use.
Agricultural commands the volume base. Horticultural is expanding most quickly on specialty crop premiumization.
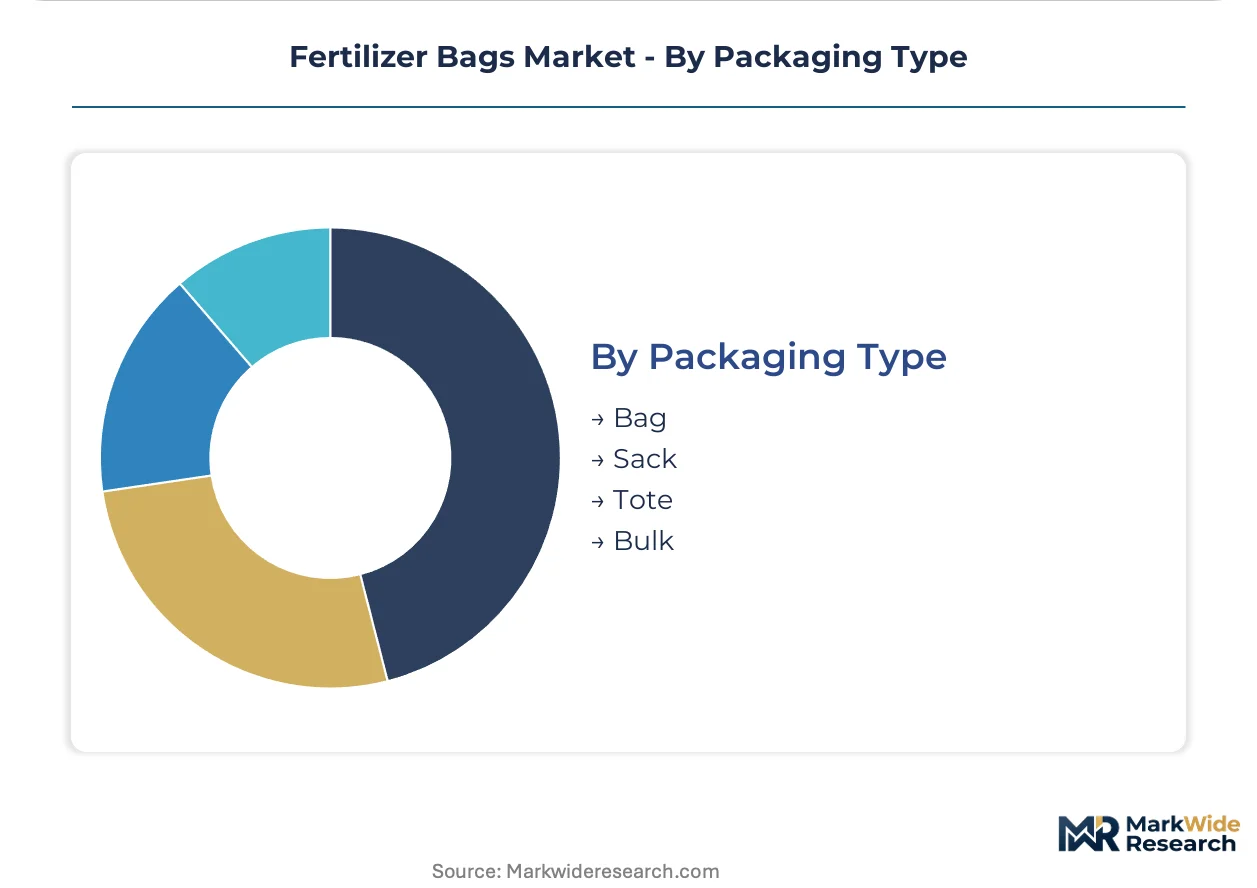
Packaging Type:
Unit load configuration aligns with mechanization levels and inventory turnover velocity across distribution networks.
- Bag:Standard 25-50kg woven polypropylene valve bags serve high-throughput urea distribution through India's public distribution system. BIS certification mandates tensile strength and seam integrity benchmarks that create 4-6 month approval delays for new designs.
- Sack:Open-mouth kraft paper formats suit protected storage environments and short-rotation inventory cycles in temperate climates.
- Tote:Flexible intermediate bulk containers with forklift pockets and discharge spouts enable bulk handling at cooperative procurement hubs. Legacy equipment retrofit costs from valve bag lines defer adoption among mid-sized cooperatives.
- Bulk:Rigid and collapsible intermediate bulk containers for liquid fertilizers displace steel drums as precision agriculture expands. Greif anchors North American demand through dedicated agricultural field teams managing container pooling and rotation.
Bag retains the volume anchor. Bulk is gaining share fastest on liquid formulation growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity clusters in China, India, and Germany, with regional specifications diverging sharply around containment mandates and mechanization levels. Regulatory friction in Europe and certification bottlenecks in India reshape competitive access patterns.
United States
California's Central Valley specialty crop producers drive multi-layer laminated bag specifications under EPA and state Department of Pesticide Regulation containment standards. The Corn Belt anchors bulk container demand through automated grain elevator networks. Greif positions dedicated agricultural field teams across these corridors to capture integrated packaging-plus-logistics contracts.
India
Cooperative procurement networks in Punjab and Haryana favor woven polypropylene bulk totes for urea distribution through the public distribution system. BIS certification mandates tensile strength and seam integrity benchmarks that create 4-6 month approval delays for new sack designs. Regional manufacturing scale concentrates in Gujarat and Maharashtra to serve wheat belt logistics hubs.
Germany
ECHA REACH restrictions on phthalate plasticizers force polyethylene reformulation cycles that extend product development timelines by 12-18 months. German distributors qualify kraft paper-based barrier solutions as interim substitutes. The Rhine-Ruhr industrial corridor hosts compounders certifying alternative plasticizer systems through substance evaluation protocols.
Brazil
Soybean belt mechanization in Mato Grosso and Paraná creates demand for standardized FIBC formats with integrated lifting loops at automated grain elevators. ANVISA alignment with international containment standards shapes import qualification for multinational packaging suppliers. Regional converter investments target export corridor access through Santos port infrastructure.
Netherlands
Greenhouse clusters in Westland and Aalsmeer drive specification upgrades for collapsible IBCs in liquid fertilizer fertigation systems. EU Green Deal packaging waste directives incentivize mono-material recyclable constructions that simplify end-of-life processing. Rotterdam logistics hubs anchor container pooling networks serving North European horticultural supply chains.
Fertilizer Bags Market Competitive Landscape
Integrated packaging-logistics providers and regional woven polypropylene specialists split the market along service intensity and manufacturing scale vectors. Consolidation concentrates purchasing authority with fewer agricultural distributors, compressing supplier counts across major corridors. Three archetypes dominate: multinational industrial packaging conglomerates with field service capabilities, regional woven fabric converters with BIS or FDA qualification depth, and specialty barrier film compounders serving horticultural premium segments. Competitive moves center on turnkey inventory management contract capture and ECHA-compliant material reformulation racing.
Within the multinational tier, Greif and Mondi Group exemplify divergent strategic positioning. Greif anchors North American bulk container demand through embedded agricultural field teams managing container pooling and rotation. Mondi Group occupies a position in European horticultural supply chains through kraft paper-based barrier solutions that serve as interim substitutes during polymer recertification cycles. LC Packaging represents the regional scale archetype, sustaining woven polypropylene positions through manufacturing footprint across multiple agricultural corridors.
| Leading Market Players |
|---|
| Berry Global |
| Greif |
| Amcor plc |
| LC Packaging |
| NNZ Group |
| Sonoco Products Company |
| ProAmpac |
| CDF Corporation |
| Mondi Group |
| Others |
Supply & Pricing Matrix
Polypropylene resin production clusters in Saudi Arabia and the US Gulf Coast anchor raw material cost structures for woven bag converters, concentrating margin capture with compounders holding long-term feedstock contracts rather than regional fabricators serving spot procurement networks.
Pricing Analysis
India's BIS certification mandates dictate the pricing tier structure across woven polypropylene sack procurement. Three-tier pricing structure across premium, standard, and economy levels separates multi-layer laminated constructions with seam integrity guarantees from single-layer commodity bags. Price differentiation rests on tensile strength certification grade and volume scale in cooperative procurement lots. Cost compression in standard-grade valve bags is intensifying because crude oil-linked resin volatility erodes converter margins without pass-through mechanisms. Smallholder cooperatives in Punjab and Haryana exhibit highest price sensitivity, while California specialty crop producers demonstrate lowest sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Greif, Mondi Group, and LC Packaging holding integrated film extrusion and conversion assets across North America, Europe, and South Asia. Geographic supply concentrates in China, India, and Germany for woven fabric production and barrier film compounding. Raw material dependencies draw from polypropylene resin, kraft pulp, and phthalate-free plasticizer formulations. Single-source vulnerability runs through Saudi Aramco and SABIC feedstock supply for Middle East resin exports. Distribution runs through cooperative procurement hubs in India's wheat belt and automated grain elevator networks in Brazil's Mato Grosso soybean belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regional certification regimes and substrate-specific regulatory timelines creates niche entry points for specialized converters, as precision agriculture and extended producer responsibility mandates splinter demand into format-specific segments.
For Market Incumbents: Pre-empt margin compression from integrated packaging-logistics providers by embedding field service teams at cooperative procurement hubs in India and grain elevator networks in Brazil. Backward integration into film extrusion assets in Gujarat and Maharashtra secures BIS certification continuity against 4-6 month approval delays for new sack designs.
For New Entrants and Emerging Players: Brazil's Mato Grosso soybean belt offers underpenetrated white-space for RFID-enabled FIBC formats serving automated grain elevator networks. European horticultural supply chains present secondary entry point through kraft paper-based barrier solutions as interim substitutes during REACH-compliant polymer recertification cycles. Qualify through ANVISA-aligned containment standards to access Santos port export corridors.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional woven polypropylene specialists holding BIS certification depth and cooperative procurement network relationships. Long-term viability across the analysis window favors converters with mono-material recyclable construction capabilities aligned to EU Green Deal packaging waste directives. Watch ECHA substance evaluation timelines for alternative plasticizer approvals as inflection indicator for polyethylene laminate demand recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | SABIC feedstock contracts in Saudi Arabia secure resin cost stability for multi-layer laminate production. |
| RFID-Enabled Inventory Tracking Integration | Embedded sensor tags in woven polypropylene enable real-time traceability for specialty fertilizer blends. |
| Mono-Material Recyclable Construction Transition | EU Green Deal directives in the Netherlands drive specification shifts toward simplified end-of-life processing. |
| Cooperative Procurement Hub Embedding | Dedicated agricultural field teams at India's PDS distribution points capture turnkey logistics contracts. |
| REACH-Compliant Plasticizer Reformulation | ECHA certification cycles in Germany extend product development timelines for polyethylene barrier films. |
Research Methodology
The analysis maps woven polypropylene valve bags, multi-layer polyethylene laminates, kraft paper barrier solutions, and collapsible IBC formats, each validated through converter plant managers, cooperative procurement officers at India's public distribution system, California Department of Pesticide Regulation compliance leads, and European horticultural distributor technical buyers. Primary fieldwork triangulates against customs and trade data for polypropylene resin flows, BIS certification registries, SEC 10-K filings from packaging conglomerates, and ECHA substance evaluation databases. Bottom-up volume estimates from regional manufacturing capacity and top-down demand aggregation from fertilizer formulation throughput cross-validate segment sizing.
Assumptions hold regulatory timelines for BIS certification and ECHA reformulation within observed historical ranges, with crude oil price corridors and agricultural commodity cycles varied across sensitivity scenarios. Segmentation dimensions modeled include fertilizer physical state, substrate material construction, end-use operational scale, and packaging unit load configuration. CAGRs derive from installed equipment base growth, mechanization penetration curves, and containment standard adoption rates across tropical and temperate agricultural zones.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese converters or accelerated REACH enforcement by ECHA would shift outcomes. Quarterly review of BIS approval queue lengths, ECHA substance evaluation publication schedules, and cooperative procurement tender awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
India Micronutrient Fertilizer Market
Fertilizers
EMEA Secondary Macronutrients Market
Fertilizers
Phosphoric Fertilizer Market
Fertilizers
Asia-Pacific Specialty Fertilizer Market
Fertilizers
Sulfur Fertilizer Market
Fertilizers
Ammonium Sulfate Fertilizer Market
Fertilizers
Asia-Pacific Fertilizers Market
Fertilizers
Nitro Compound Fertilizers Market
Fertilizers
Russia Specialty Fertilizer Market
Fertilizers
United States Fertilizers Market
Fertilizers
Malaysia NPK Fertilizer Market
Fertilizers
Vietnam Specialty Fertilizer Market
Fertilizers
North America Liquid Fertilizers Market
Fertilizers
Europe Micronutrient Fertilizer Market
Fertilizers
Soil Conditioners Market
Fertilizers
US Seaweed Fertilizers Market