
 India Urea Market | 2026-2036
India Urea Market Size, Share, and Industry Trends Forecast 2026-2036
India Urea Market Outlook
Buyer concentration among agricultural cooperatives is shifting as smaller farmer producer organizations fragment procurement across regional channels. Rashtriya Chemicals & Fertilizers Ltd leverages its coastal manufacturing complexes to dominate western India supply chains. Gujarat Narmada Valley Fertilizers & Chemicals Ltd anchors its position through backward integration into natural gas and petrochemical feedstocks. Indian Farmers Fertiliser Cooperative Limited extends its reach through one of the country's largest cooperative distribution networks.
Urea is a white crystalline solid with nitrogen content of 46% by weight, synthesized industrially via the Bosch-Haber process combining ammonia and carbon dioxide under high pressure to serve as the world's most concentrated nitrogen fertilizer. Granular urea leads volume throughput due to superior handling characteristics and blending compatibility with phosphatic fertilizers, while coated urea variants command margin premiums from controlled-release properties that reduce leaching losses. Prilled urea retains cost-sensitive share in bulk government tender programs, though its lower crush strength limits mechanical application adoption.
BIS fertilizer quality standards and the CEA's energy consumption norms for urea plants shape product specifications and plant economics, while the PLI scheme for alternative fertilizers creates competitive pressure on conventional urea margins. The nutrient-based subsidy framework administered by the Department of Fertilizers directly determines manufacturer offtake prices and import parity calculations. Stakeholders must monitor natural gas pricing reforms and the pace of nano-urea capacity scale-up to assess structural demand displacement risks.
Market Dynamics
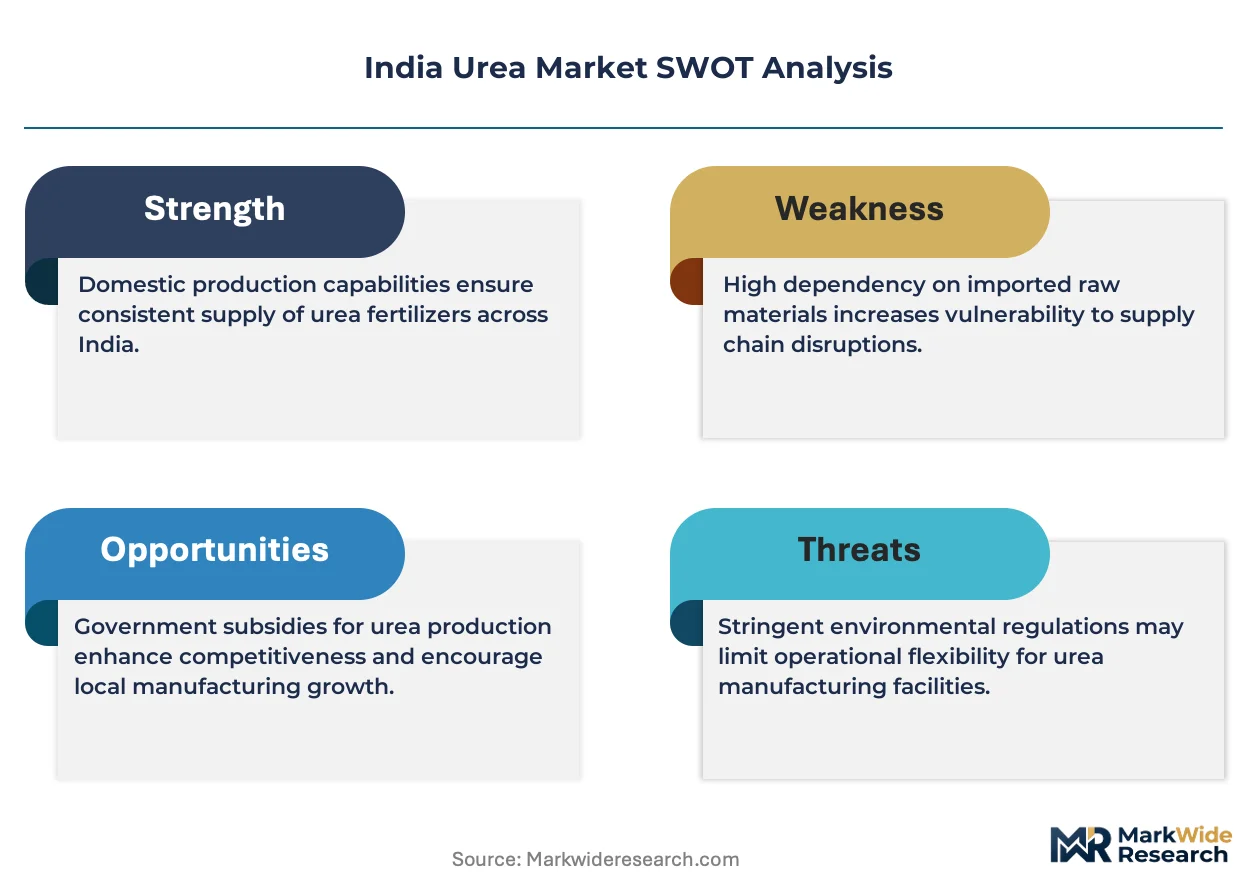
The nutrient-based subsidy framework administered by India's Department of Fertilizers is compressing manufacturer margins while redirecting procurement volumes toward agricultural cooperatives and farmer producer organizations. This policy recalibration is fragmenting traditional distribution channels and forcing feedstock integration decisions across the value chain.
Growth Catalysts
- Neem-coated urea mandate:The government's compulsory coating requirement for all domestically produced urea is stimulating demand for controlled-release variants that reduce nitrogen volatilization losses in rice-wheat cropping systems.
- Natural gas pooling mechanism:The uniform gas pricing policy is stabilizing input costs for naphtha-based plants in eastern India, preventing stranded capacity from exiting the market.
- Food security targets:India's wheat and paddy procurement commitments under the National Food Security Act are sustaining baseline urea offtake regardless of international price volatility.
Market Restraints
- Natural gas import dependency:Over 40% of feedstock requirements rely on LNG cargoes priced against volatile Henry Hub and JKM benchmarks, exposing margins to currency and commodity swings.
- Single-product plant economics:Standalone urea complexes without ammonia-derivative diversification face acute vulnerability during subsidy payment delays from the Department of Fertilizers.
- Nano-urea substitution threat:Indian Farmers Fertiliser Cooperative's liquid nano-urea formulation promises 50% nitrogen reduction per hectare, threatening volumetric demand displacement if scale-up accelerates.
Strategic Opportunities
- Coastal brownfield ammonia-urea complexes:Gujarat and Maharashtra port locations offer import-parity arbitrage for export-oriented producers targeting Bangladesh and Sri Lankan tender markets.
- Biomass-urea pilot integration:The PLI scheme for alternative fertilizers creates co-investment pathways for straw-gasification demonstrations in Punjab's rice-belt districts.
- Direct-to-farmer digital platforms:State agricultural departments in Madhya Pradesh and Rajasthan are piloting soil-health-card-integrated urea allocation systems that bypass mandi-level intermediaries.
Industry Challenges
- Retired plant workforce transition:Aging gas-based facilities in Uttar Pradesh and Bihar face skilled operator shortages as original technical staff reach pension thresholds without structured knowledge transfer protocols.
- CEA energy norm compliance:The Central Electricity Authority's specific consumption benchmarks for urea plants require capital-intensive compressor and reformer upgrades that strain cash flows during subsidy arrears cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Urea Market |
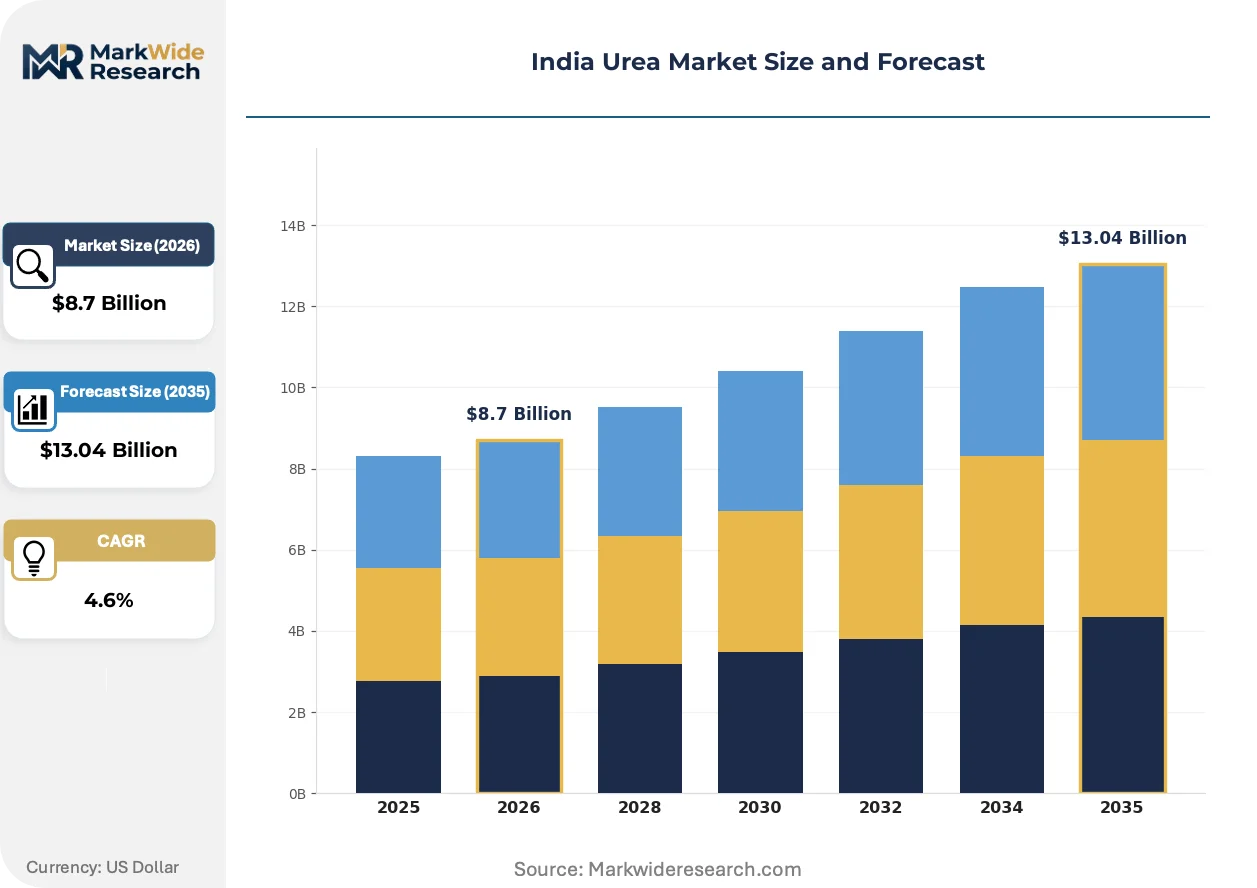
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular Urea, Prilled Urea, Coated Urea, Liquid Urea Application: Crop Fertilization, Soil Enrichment, Industrial Use, Gardening Distribution Channel: Retail, Wholesale, Online, Direct Sales Customer Type: Farmers, Agricultural Cooperatives, Commercial Growers, Distributors |
| Companies Covered | Rashtriya Chemicals & Fertilizers Ltd (RCF), Gujarat Narmada Valley Fertilizers & Chemicals Ltd (GNFC), Indian Farmers Fertiliser Cooperative Limited (IFFCO), Mangalore Chemicals & Fertilizers Ltd, Coromandel International Limited, National Fertilizers Limited (NFL), Krishak Bharati Cooperative Limited (KRIBHCO), Deepak Fertilisers and Petrochemicals Corporation Limited, Chambal Fertilisers and Chemicals Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Urea Market Strategic Shifts
Controlled-release coating technologies and precision application hardware are converging to reduce nitrogen-use inefficiency in India's cereal-dominated cropping systems. These innovations are compressing the gap between subsidized bulk urea and premium imported formulations.
Nano-urea manufacturing is modularizing production footprints across IFFCO's Kalol and Aonla complexes, enabling distributed 500-litre-per-day units that bypass centralized ammonia synthesis. State agricultural universities in Haryana and Tamil Nadu are field-testing these formulations against conventional prilled urea in split-application trials. The technology is modularizing capital deployment away from billion-dollar integrated complexes toward franchiseable micro-facilities.
The BIS fertilizer quality standards revision is tightening moisture content and biuret specifications for imported urea consignments. This regulatory tightening is elevating rejection risks for Middle Eastern and Chinese cargoes that previously cleared under older tolerances. Importers are responding by pre-shipment inspection contracts at load ports and dedicated storage conditioning at Hazira and Paradip terminals.
Cooperative procurement consolidation is accelerating among Punjab's agricultural service societies, which are aggregating demand for 50-tonne bulk tenders rather than individual farmer purchases. These societies are disintermediating traditional village-level retailers through warehouse-direct delivery commitments. The pattern is most visible in Ludhiana and Sangrur districts where soil-health-card penetration exceeds 80% and digitized allocation tracking has eliminated diversion to non-agricultural uses.
India Urea Market Segmentation
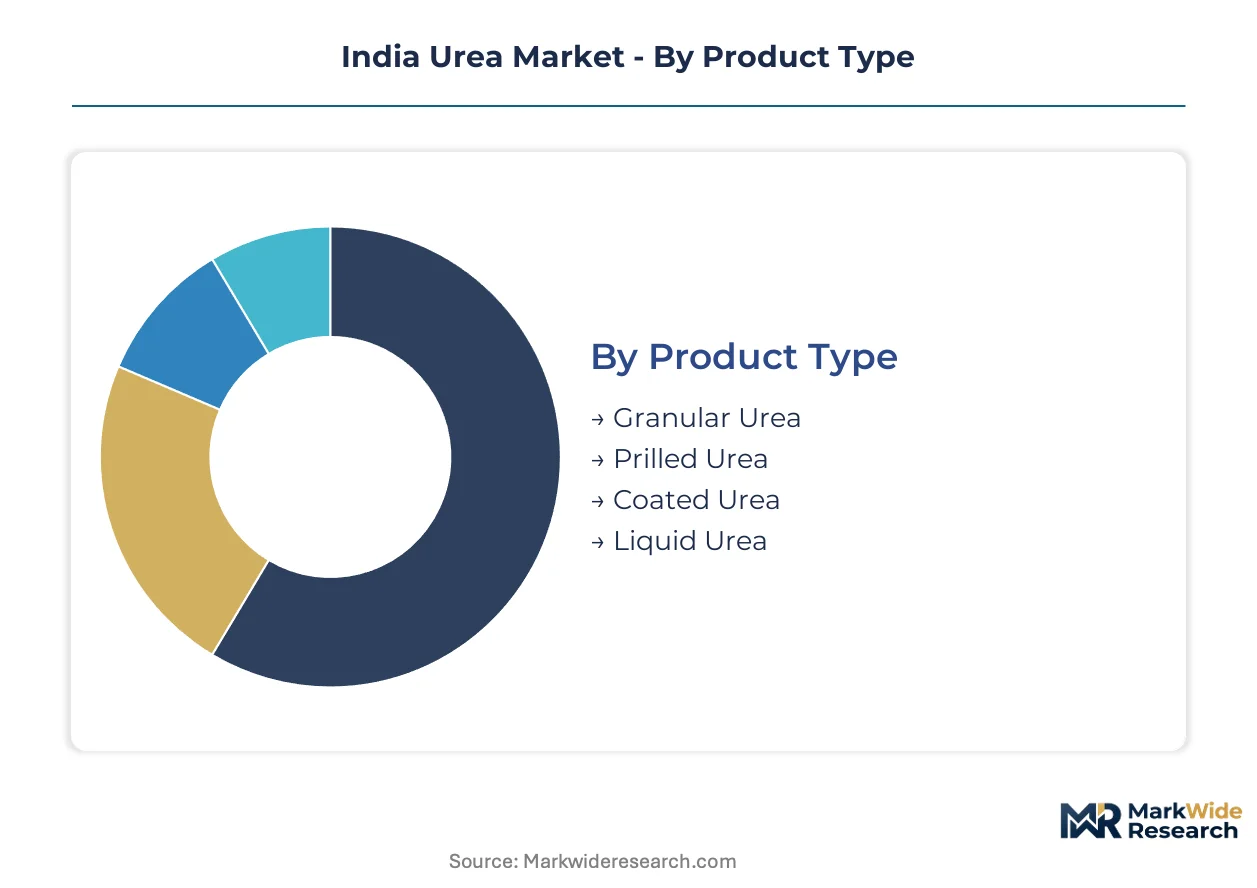
Segmentation in the India urea market reveals how subsidy mechanics, application technology, and procurement scale reshape competitive positioning across distinct buyer clusters. Understanding these divides exposes where margin pressure concentrates and where premium capture remains viable.
Product Type:
Buyers differentiate primarily by nitrogen-use efficiency requirements and mechanical handling capabilities across India's diverse agro-climatic zones.
- Granular Urea:Spherical particles with superior crush strength and blending compatibility enable mechanized broadcasting alongside phosphatic fertilizers. Demand concentrates in Punjab and Haryana's large-scale wheat-paddy operations where combine harvester integration and bulk handling infrastructure predominate.
- Coated Urea:Polymer or neem-based coatings deliver controlled nitrogen release that cuts volatilization losses in flooded rice systems. Adoption accelerates in Tamil Nadu's Cauvery delta districts where water-intensive cropping faces BIS-mandated efficiency targets and groundwater depletion pressures.
- Prilled Urea:Lower-density spheres produced via spray-drying serve cost-sensitive bulk procurement through government tender programs.
- Liquid Urea:Nano-urea formulations enable foliar application with reduced freight costs per unit nitrogen.
Volume sits with granular grades; growth tilts toward coated variants.
Application:
End-use concentration tracks India's crop procurement commitments and industrial diversification patterns.
- Crop Fertilization:Basal and top-dressing applications for cereals, pulses, and oilseeds absorb the majority of offtake under National Food Security Act procurement guarantees. Concentration peaks in Uttar Pradesh's Indo-Gangetic belt where wheat and paddy procurement infrastructure locks in predictable seasonal demand.
- Industrial Use:Urea-formaldehyde resins, melamine production, and diesel exhaust fluid (DEF) applications create non-subsidized pricing pockets. Demand clusters in Gujarat's chemical corridor where Dahej and Hazira complexes integrate urea into polymer and adhesive value chains.
- Soil Enrichment:Direct soil amendment for carbon sequestration and microbial activity enhancement.
- Gardening:Small-format retail packaging for horticultural and home garden applications.
Procurement scale favors crop fertilization; premium extraction shifts toward industrial contracts.
Distribution Channel:
Channel selection reflects buyer scale, subsidy eligibility verification, and logistics infrastructure maturity.
- Wholesale:Bulk procurement by agricultural cooperatives and state agricultural departments aggregates 50-tonne-plus shipments through warehouse-direct delivery. Concentration dominates in Madhya Pradesh and Rajasthan where soil-health-card digitization enables allocation tracking and diversion prevention.
- Direct Sales:Manufacturer-to-cooperative contracts bypass mandi intermediaries, capturing margin through volume commitments and payment security. Adoption accelerates in IFFCO and Kribhco's cooperative networks where member equity structures align procurement incentives.
- Retail:Village-level kiranas and agri-input shops serve fragmented smallholder demand.
- Online:E-commerce platforms and app-based ordering pilot in urban periphery markets.
Wholesale channels capture procurement volume; direct sales expand most quickly.
Customer Type:
Customer stratification follows landholding size, credit access, and collective bargaining power.
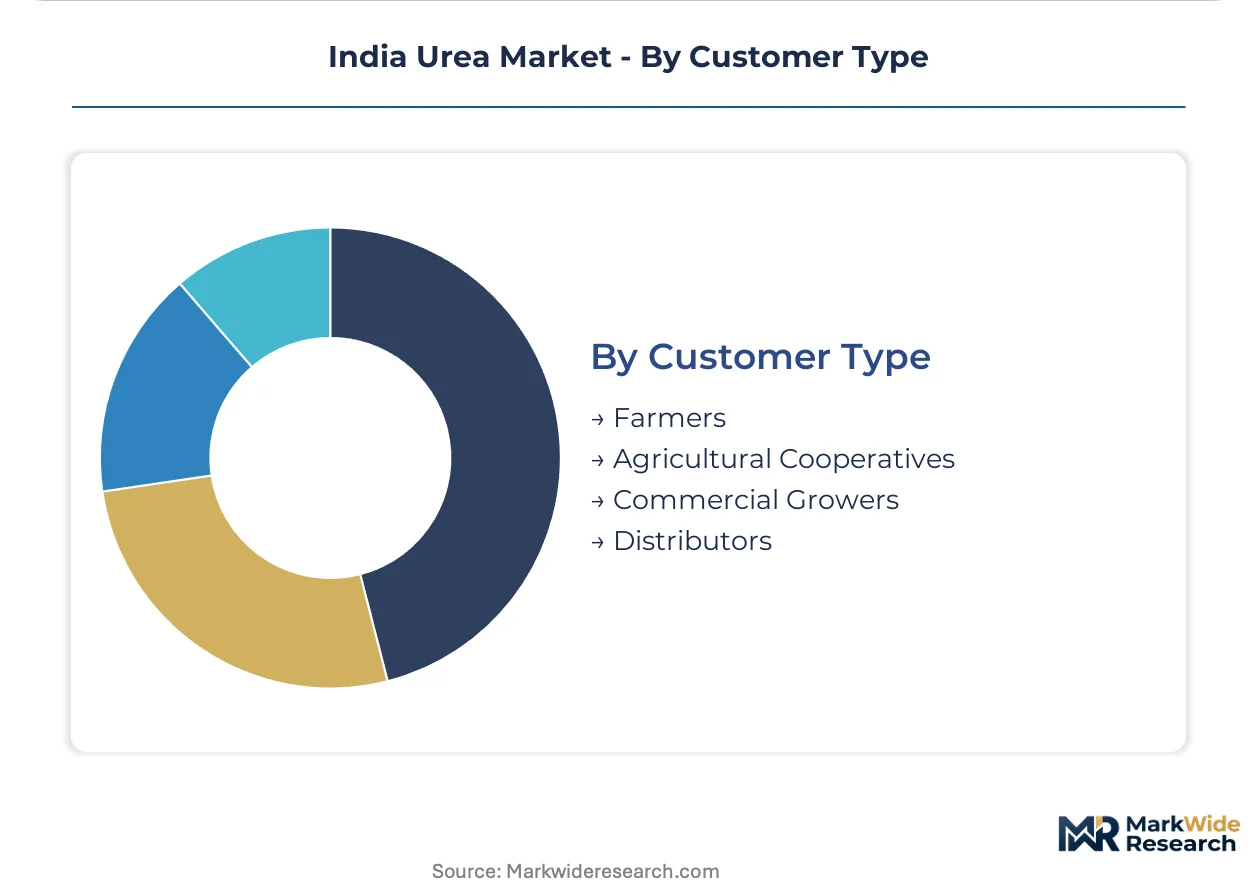
- Agricultural Cooperatives:Punjab's Primary Agricultural Credit Societies aggregate 500-plus member farmers into single tender volumes, extracting price concessions and priority delivery commitments. Fragmentation is reversing as smaller Farmer Producer Organizations consolidate procurement across Sangrur and Ludhiana districts.
- Commercial Growers:Contract farming operators and corporate agriculture ventures prioritize coated urea and precision application equipment. Concentration rises in Maharashtra's grape and pomegranate belts where export quality standards mandate nutrient management documentation.
- Farmers:Individual smallholders below two hectares dominate headcount but fragment purchasing power.
- Distributors:Regional stockists buffer inventory between manufacturers and retail endpoints.
Cooperative procurement anchors volume; commercial growers drive margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for urea in India clusters heavily in the northern cereal belt, where wheat and paddy procurement infrastructure locks in predictable seasonal offtake. Western coastal states leverage port access for import parity, while southern districts experiment with controlled-release formulations under water stress.
Punjab
Wheat-paddy rotation dominates procurement volumes across Ludhiana and Sangrur districts. The Department of Fertilizers' nutrient-based subsidy framework determines manufacturer offtake prices here. Agricultural cooperatives in this belt aggregate 500-plus member farmers into single tender volumes, extracting price concessions through warehouse-direct delivery.
Haryana
Soil-health-card penetration exceeds 80% in Karnal and Hisar, enabling digitized allocation tracking that eliminates diversion. The CEA's energy consumption norms for urea plants shape product specifications for facilities supplying this region. IFFCO's Kalol complex anchors supply through one of India's largest cooperative distribution networks.
Gujarat
Dahej and Hazira industrial corridors integrate urea into polymer and adhesive value chains for non-subsidized industrial demand. GNFC leverages backward integration into natural gas and petrochemical feedstocks. Coastal brownfield ammonia-urea complexes here offer import-parity arbitrage for export-oriented producers targeting Bangladesh.
Maharashtra
Contract farming operators in Nashik's grape and pomegranate belts prioritize coated urea and precision application equipment. The PLI scheme for alternative fertilizers creates co-investment pathways for pilot projects in this state. Port locations enable LNG feedstock access that stabilizes input costs for naphtha-based plants.
Uttar Pradesh
The Indo-Gangetic belt sustains baseline urea offtake under National Food Security Act procurement guarantees. Aging gas-based facilities in Gorakhpur and Barauni face skilled operator shortages as original technical staff reach pension thresholds. State agricultural departments pilot direct-to-farmer digital platforms that bypass mandi-level intermediaries.
India Urea Market Competitive Environment
Western India producers anchor one tier; northern and central specialists hold procurement scale through cooperative networks. The vendor base arranges into three tiers: coastal integrated complexes with feedstock control, inland gas-based plants dependent on pooled pricing, and cooperative manufacturers with member-equity distribution. Strategic moves concentrate on backward integration into natural gas and forward integration into specialty fertilizer formulations.
Within the coastal integrated tier, Gujarat Narmada Valley Fertilizers & Chemicals Ltd and Rashtriya Chemicals & Fertilizers Ltd exemplify feedstock-secured positioning. Indian Farmers Fertiliser Cooperative Limited occupies a distinct archetype as a member-owned cooperative with captive distribution. These three entities represent the dominant competitive configurations: petrochemical-integrated private, state-supported coastal, and farmer-owned cooperative.
| Leading Market Players |
|---|
| Rashtriya Chemicals & Fertilizers Ltd (RCF) |
| Gujarat Narmada Valley Fertilizers & Chemicals Ltd (GNFC) |
| Indian Farmers Fertiliser Cooperative Limited (IFFCO) |
| Mangalore Chemicals & Fertilizers Ltd |
| Coromandel International Limited |
| National Fertilizers Limited (NFL) |
| Krishak Bharati Cooperative Limited (KRIBHCO) |
| Deepak Fertilisers and Petrochemicals Corporation Limited |
| Chambal Fertilisers and Chemicals Limited |
| Others |
Value Chain & Pricing Dynamics
Henry Hub and JKM LNG benchmarks cascade through India's urea value chain, compressing margins at naphtha-dependent eastern plants while coastal gas-pooling beneficiaries maintain pricing flexibility across government tender and commercial offtake tiers.
Pricing Analysis
Volume concentrates in prilled urea through Department of Fertilizers bulk tenders, while margin capture shifts toward coated variants and industrial-grade formulations. Price differentiation hinges on nitrogen-use efficiency certification under BIS standards and volume scale in cooperative procurement aggregates. Pricing pressure intensifies in standard grades as nano-urea scale-up threatens volumetric displacement. Smallholder farmers in fragmented retail channels exhibit highest price sensitivity; commercial growers in Maharashtra's export-oriented belts accept premium positioning for documented nutrient management compliance.
Supply Chain Analysis
Skilled operator shortages in Uttar Pradesh and Bihar's aging gas-based facilities constrain output reliability as original technical cohorts exit without structured knowledge transfer protocols. Manufacturing gravity centers on Gujarat's coastal complexes, Maharashtra's port-adjacent brownfields, and Punjab-Haryana's cooperative-integrated inland plants. Feedstock draws from pooled domestic gas allocations, spot LNG cargoes, and naphtha streams for stranded eastern capacity. Single-product plant vulnerability to subsidy payment delays from the Department of Fertilizers constitutes the dominant structural risk. Distribution runs through agricultural cooperative warehouses with digitized soil-health-card tracking bypassing traditional mandi intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's urea sector navigates a technology-transition phase as liquid nano-urea formulations displace conventional prilled volumes in field trials across Haryana and Tamil Nadu state agricultural universities.
For Market Incumbents: Anchor feedstock security through natural gas pooling mechanism optimization and captive LNG terminal access at Dahej and Hazira coastal complexes. Deepen backward integration into ammonia synthesis to offset nano-urea substitution threats. Prioritize CEA energy norm compliance investments ahead of subsidy arrears cycles that strain compressor and reformer upgrade cash flows. For New Entrants and Emerging Players: Commercial growers in Maharashtra's grape and pomegranate export belts present the most penetrable buyer archetype for precision-coated urea and foliar application equipment bundles. Punjab's consolidating Farmer Producer Organizations offer white-space entry through warehouse-direct delivery contracts disintermediating village-level retailers. Pursue PLI scheme co-investment pathways for biomass-urea pilot demonstrations in rice-belt districts. For Investors and Strategic Acquirers: Distressed-cycle entries favor single-product gas-based plants in eastern India with stranded capacity exposure and pending subsidy receivables. Long-term viability centers on ammonia-derivative diversification and coastal relocation for LNG feedstock access. Monitor nano-urea manufacturing scale-up at IFFCO's Kalol and Aonla complexes as the critical inflection signal for volumetric demand displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Gas | Captive LNG terminal access at Hazira insulates margins from Henry Hub volatility. |
| Coated Urea Capacity Expansion | Neem-coating compliance captures government-mandated controlled-release premiums. |
| Nano-Urea Manufacturing Scale-Up | Modular 500-litre-per-day units bypass billion-dollar ammonia complex economics. |
| Direct-to-Farmer Digital Platform | Soil-health-card integration in Madhya Pradesh eliminates mandi diversion losses. |
| Coastal Brownfield Relocation | Gujarat port locations enable Bangladesh and Sri Lanka export-parity arbitrage. |
Study Parameters
Document review covered Department of Fertilizers subsidy disbursement records, CEA energy consumption norm filings, and BIS fertilizer quality standard revisions, complemented by interviews with plant operations managers at coastal and inland complexes, procurement leads at agricultural cooperatives in Punjab and Haryana, distribution channel partners in Madhya Pradesh and Rajasthan, and technical directors at state agricultural universities conducting nano-urea field trials. Secondary validation drew from customs import data, SEC filings of listed fertilizer manufacturers, and PLI scheme administrative disclosures. Bottom-up volume modeling triangulated against top-down subsidy allocation aggregates.
Cross-referencing historical offtake patterns against expert panel input on nano-urea adoption velocity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product grade tier, end-use application split between crop fertilization and industrial derivatives, distribution channel structure, and regional procurement cluster characteristics. CAGRs derived from elasticity-adjusted demand curves incorporating natural gas price scenarios and nutrient-based subsidy policy continuity assumptions. Forecast inputs included LNG import dependency ratios and cooperative consolidation trajectories in northern cereal belts.
Revisions become necessary when natural gas pricing reforms accelerate, nano-urea manufacturing scale-up exceeds field-trial validation rates, or Department of Fertilizers subsidy payment delays extend beyond historical arrears cycles. Forecasts reflect documented assumptions on policy continuity and feedstock cost trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Ammonium Thiosulfate Fertilizer Market
Fertilizers
Catalyst Fertilizers Market
Fertilizers
Africa Specialty Fertilizer Market
Fertilizers
Asia-Pacific Fertilizers Market
Fertilizers
Fertilizer Bags Market
Fertilizers
North America Fertilizers Market
Fertilizers
Brazil Organic Fertilizer Market
Fertilizers
Fertilizer Additives Market
Fertilizers
India Controlled Release Fertilizer Market
Fertilizers
Australia Fertilizer Market
Fertilizers
Europe Specialty Fertilizer Market
Fertilizers
Potash Market
Fertilizers
South America Micronutrient Fertilizer Market
Fertilizers
Global Controlled Release Fertilizer Market
Fertilizers
Russia Micronutrient Fertilizer Market
Fertilizers
Saudi Arabia Fertilizer Market