
 Global Phosphatic Fertilizers Market | 2026-2036
Global Phosphatic Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Phosphatic Fertilizers Market Foresight
A capital-intensity divergence between integrated phosphate rock miners and downstream blenders is bifurcating competitive returns in phosphatic fertilizers. OCP Group S.A. leverages captive phosphate rock reserves in Morocco to sustain margin structures that pure traders cannot replicate. The Mosaic Company anchors North American supply through its Florida and Peru mining network, while Nutrien Ltd. competes via retail distribution density and agronomic service bundling.
Phosphatic fertilizers are phosphate-bearing compounds—typically containing phosphorus pentoxide in water-soluble or citrate-soluble forms—manufactured through acidulation of phosphate rock with sulfuric or phosphoric acid to supply plant-available phosphorus for root development and energy transfer. Diammonium Phosphate dominates volume flows due to its nitrogen co-nutrient profile and established handling infrastructure across bulk supply chains. Monoammonium Phosphate occupies premium positioning in precision agriculture and greenhouse systems where solubility control and lower nitrogen ratios command higher unit economics. Granular formulations lead in emerging market adoption where mechanized spreading equipment penetration is rising fastest.
EPA nutrient management guidelines in the United States restrict phosphorus runoff near watersheds, compelling formulation shifts toward polymer-coated and stabilized products. REACH registration requirements in Europe mandate full supply chain toxicity documentation, raising compliance costs for importers of non-EU origin phosphate intermediates. China's MEE enforces phosphate mining quotas and tailings standards that constrain raw material availability for export-oriented producers. Stakeholders must monitor regulatory divergence between nutrient-use-efficiency mandates and food production targets to anticipate which product forms and geographic positions will absorb policy-driven demand migration.
Market Dynamics
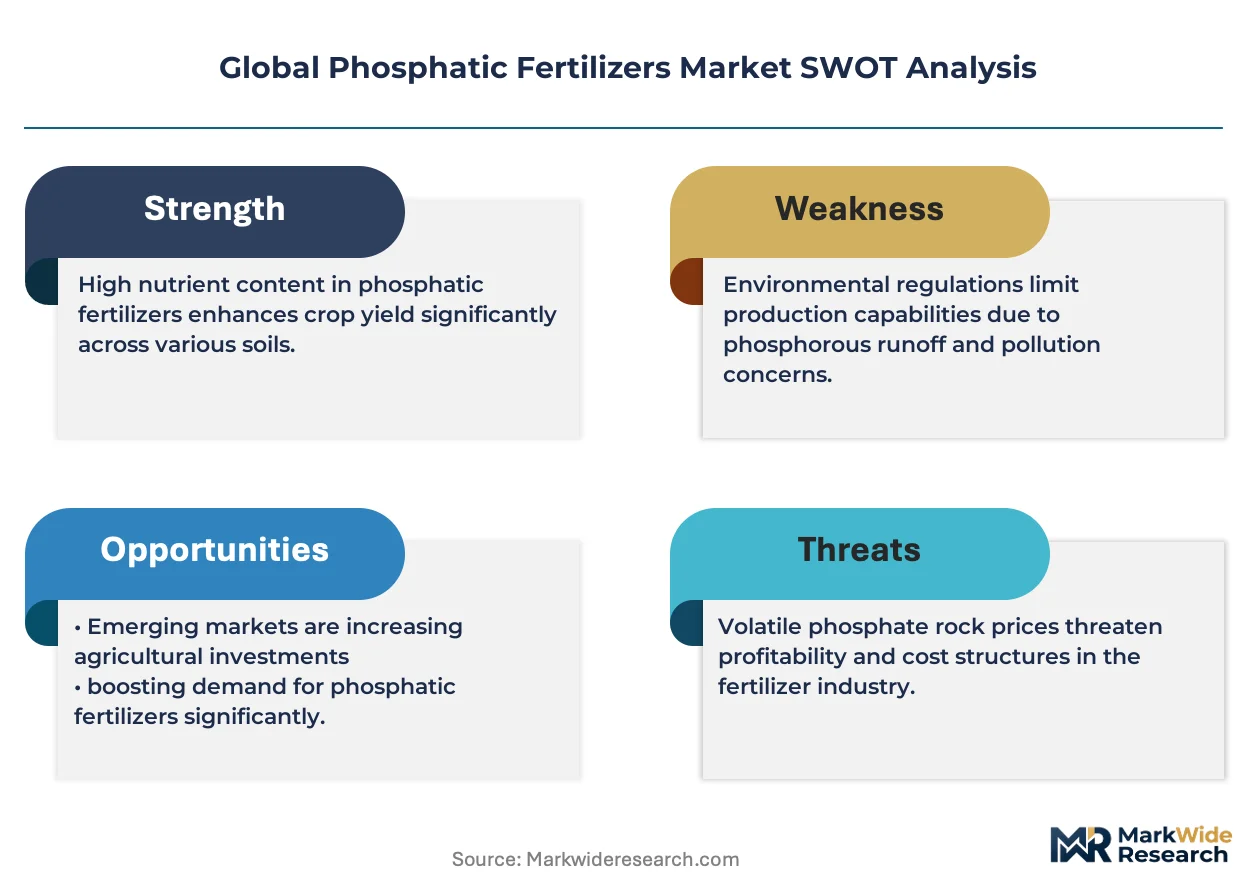
Integrated phosphate rock miners are capturing margin pools that downstream blenders cannot access, bifurcating competitive returns across the value chain as captive ore reserves become the decisive cost differentiator.
Growth Catalysts
- Farm to Fork Strategy:EFSA nutrient management standards under the EU Green Deal redirect formulation demand toward enhanced-efficiency phosphatic products with lower runoff profiles.
- Soybean yield gaps:Brazilian farmers are expanding phosphate applications on soybeans to close productivity differentials against global benchmarks.
- Food security programs:Sub-Saharan Africa smallholder access initiatives are concentrating demand growth faster than any other geography.
Market Restraints
- Sulfuric acid volatility:Input cost swings for the primary acidulation reagent compress blender margins unpredictably.
- Moroccan ore concentration:OCP Group's dominance of premium phosphate rock reserves creates supply security risk for non-integrated producers.
- REACH documentation burdens:ECHA registration requirements for non-EU phosphate intermediates raise compliance costs for importers.
Strategic Opportunities
- Polymer-coated formulations:EPA watershed runoff restrictions near US water bodies create premium positioning for stabilized phosphorus products.
- Greenhouse system penetration:Monoammonium phosphate solubility control commands higher unit economics in precision agriculture installations.
- Granular mechanization:Rising equipment penetration in India creates adoption pull for spreadable granular formats over bulk powders.
Industry Challenges
- Agronomic service bundling:Nutrien Ltd.'s retail density model forces competitors to replicate high-touch farm advisory capabilities without equivalent distribution footprint.
- Tailings compliance:China's MEE mining quotas and waste standards constrain raw material availability for export-oriented producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Phosphatic Fertilizers Market |
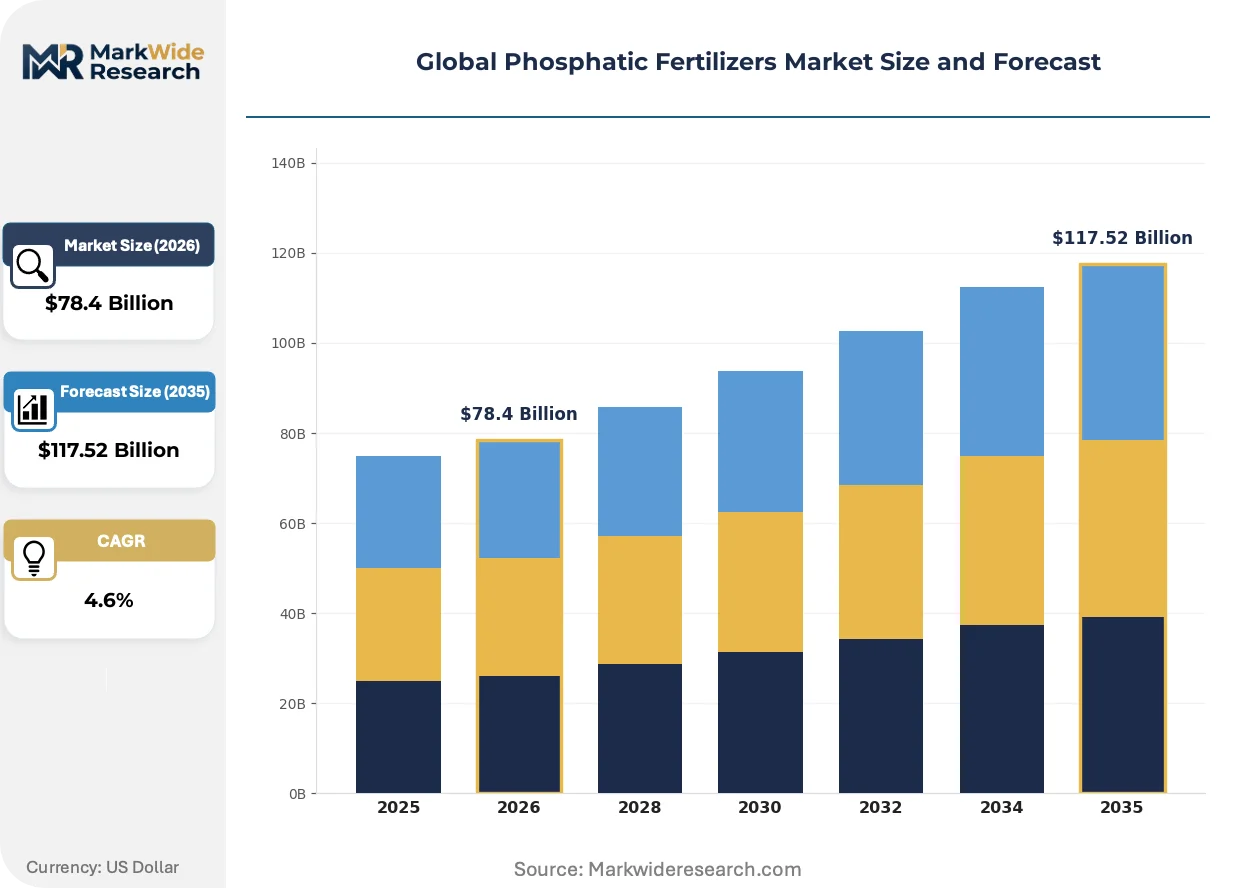
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $117.52 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Super Phosphate, Triple Super Phosphate, Diammonium Phosphate, Monoammonium Phosphate, Others Application: Cereals & Grains, Oilseeds & Pulses, Fruits & Vegetables, Plantation Crops, Fiber Crops, Others Form: Granular, Powder, Liquid, Pellets End User: Farmers, Agricultural Cooperatives, Agrochemical Companies, Government Agencies |
| Companies Covered | PhosAgro PJSC, Coromandel International Ltd., EuroChem Group, Nutrien Ltd., Indian Farmers Fertiliser Cooperative Limited, The Mosaic Company, OCP Group S.A., CF Industries Holdings Inc., Yara International ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Phosphatic Fertilizers Market Shifts & Advancements
Formulation chemistry and application precision are converging to reduce phosphorus loss rates while regulatory pressure on runoff intensifies across major agricultural economies.
Controlled-release polymer coatings are displacing conventional uncoated granules in watershed-proximate applications. Corn and soybean growers in Iowa and Illinois are adopting these formulations at accelerating rates to preempt EPA enforcement actions. The technology is displacing commodity diammonium phosphate in premium positions near sensitive water bodies.
REACH registration requirements now mandate full supply chain toxicity documentation for phosphate intermediates entering European formulation facilities. ECHA compliance timelines have extended import clearance periods by several months for non-EU origin materials. Blenders with pre-certified supply chains are capturing share from traders lacking documentation depth.
Precision agriculture platforms are unbundling traditional bulk procurement into variable-rate application contracts tied to soil testing data. Large corn operations in the US Midwest are shifting from seasonal volume purchases to subscription-based nutrient management programs. Brazil's expanding precision farming sector exhibits the fastest behavioral transition toward outcome-based phosphorus prescriptions.
Global Phosphatic Fertilizers Market Segmentation
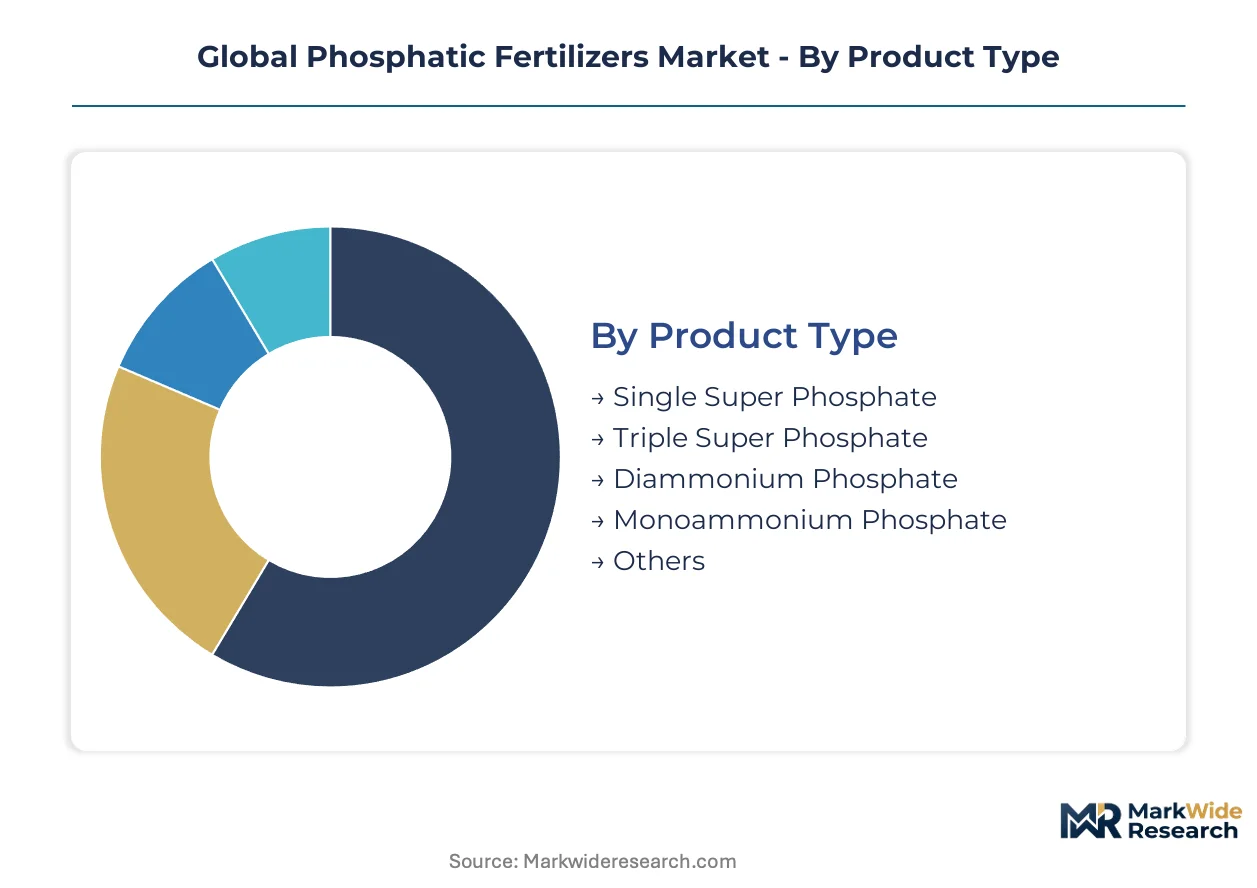
Phosphatic fertilizer segmentation reveals divergent margin structures across product chemistry, crop targeting, and customer procurement patterns. Each dimension carries distinct regulatory exposure and capital intensity profiles that reshape competitive positioning.
Product Type:
Domestic blending operations favor lower-analysis products with minimal import dependency, while export-led segments concentrate in regions with captive phosphate rock reserves.
- Diammonium Phosphate:Contains nitrogen and phosphorus pentoxide in water-soluble form, manufactured through phosphoric acid neutralization with ammonia. Brazilian soybean growers and Indian wheat farmers drive concentrated demand through established bulk handling infrastructure.
- Monoammonium Phosphate:Lower nitrogen-to-phosphorus ratio enables precise nutrient control in greenhouse and fertigation systems. Premium positioning accelerates in precision agriculture clusters across California and the Netherlands where solubility specifications command higher unit economics.
- Triple Super Phosphate:Higher phosphorus concentration per unit weight reduces freight costs for export-dependent supply chains serving Sub-Saharan Africa.
- Single Super Phosphate:Simpler acidulation process suits domestic producers lacking phosphoric acid capacity, prevalent in India and Pakistan.
- Others:Niche formulations including nitrophosphates and compound blends address specialty crop requirements in protected cultivation systems.
Diammonium Phosphate holds the largest share; momentum sits with Monoammonium Phosphate.
Application:
Cost-tier stratification separates commodity grain applications from premium horticultural and plantation segments with diverging price elasticity.
- Cereals & Grains:Wheat, rice, and corn dominate volume flows through seasonal procurement cycles tied to government support programs in India and procurement pools in the US Midwest.
- Oilseeds & Pulses:Soybean phosphate demand concentrates in Brazil's Cerrado and Argentina's Pampas as growers close yield gaps against US benchmarks.
- Fruits & Vegetables:High-value produce in Spain's Almería and China's Shandong Province drives soluble phosphate demand with strict residue compliance requirements.
- Plantation Crops:Palm oil and rubber operations in Indonesia and Malaysia favor slow-release formulations on acidic tropical soils.
- Fiber Crops:Cotton phosphate applications in Gujarat and Texas face water stress constraints requiring efficiency-focused product selection.
- Others:Turf, ornamental, and forage applications serve fragmented specialty markets with customized micronutrient packages.
Cereals & Grains commands the greatest volume; Oilseeds & Pulses exhibits the steepest expansion trajectory.
Form:
Equipment penetration rates determine form selection, with mechanization gradients creating geographic preference zones.
- Granular:Free-flowing particles suit mechanized spreaders and air seeders. Adoption accelerates across India's Punjab and Haryana as tractor-mounted equipment penetration rises.
- Powder:Finely ground material serves manual application in smallholder systems and as feedstock for compound fertilizer manufacturing.
- Liquid:Solution and suspension products enable fertigation integration in drip irrigation systems across Israel's Negev and Australia's Murray-Darling Basin.
- Pellets:Compressed forms reduce dust and improve handling characteristics for specialty applications in organic-compliant production systems.
Granular maintains dominant share; Liquid is climbing the fastest on irrigation modernization.
End User:
Procurement scale and technical sophistication separate institutional buyers from dispersed individual decision-makers.
- Farmers:Individual growers across 100+ countries make fragmented purchasing decisions influenced by extension service recommendations and credit availability.
- Agricultural Cooperatives:Aggregated buying power in Brazil's cooperativa system and US farmer-owned supply chains enables direct manufacturer negotiations and storage investment.
- Agrochemical Companies:Integrated crop nutrition providers bundle phosphatic products with crop protection and seed offerings through retail networks.
- Government Agencies:Subsidized distribution programs in India, Nigeria, and Ethiopia concentrate procurement through tender mechanisms with price caps and quality specifications.
Farmers represent the broadest base; Agricultural Cooperatives are gaining share fastest on consolidation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: Brazil and the United States favor high-analysis bulk formulations for mechanized row-crop systems, while India and Sub-Saharan Africa concentrate demand in subsidized, lower-analysis products distributed through government tender channels.
United States
Corn and soybean growers in Iowa and Illinois drive concentrated phosphate demand through precision agriculture platforms that unbundle traditional bulk procurement into variable-rate contracts. EPA watershed runoff restrictions near the Chesapeake Bay and Mississippi River basins compel formulation shifts toward polymer-coated products. The Midwest grain belt anchors North American volume flows through established bulk handling infrastructure.
Brazil
Soybean expansion across Mato Grosso and Goiás creates the steepest phosphate demand trajectory as farmers close yield gaps against US productivity benchmarks. ANVISA residue compliance requirements shape import specifications for phosphate intermediates entering formulation facilities. The Cerrado agricultural frontier exhibits the fastest behavioral transition toward outcome-based phosphorus prescriptions.
India
Wheat and rice procurement through government support programs concentrates seasonal demand spikes in Punjab and Haryana. FSSAI quality specifications and DGFT import licensing govern phosphate rock and acid intermediates entering domestic blending operations. Tractor-mounted equipment penetration across the Indo-Gangetic Plain accelerates adoption pull for granular formats over bulk powders.
China
Domestic phosphate consumption concentrates in Shandong Province's greenhouse vegetable clusters and Xinjiang's cotton belt where water stress constraints require efficiency-focused product selection. MEE mining quotas and tailings standards constrain raw material availability for export-oriented producers. The Yangtze River Delta houses the densest concentration of phosphoric acid capacity serving both domestic and international formulation demand.
Morocco
OCP Group's captive phosphate rock reserves in the Khouribga and Gantour basins sustain margin structures that pure traders cannot replicate. The country's national mining regulator enforces extraction quotas that shape global raw material availability. Jorf Lasfar anchors Atlantic export flows through integrated acidulation and granulation infrastructure serving European and Latin American markets.
Global Phosphatic Fertilizers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive phosphate rock reserves becoming the decisive cost differentiator across the value chain. OCP Group S.A. leverages Moroccan ore dominance to control upstream margin pools, while downstream blenders compete on distribution density and agronomic service bundling. Three archetypes define positioning: integrated miners with captive reserves, regional blenders with retail networks, and import-dependent traders exposed to raw material volatility. Capacity expansion and strategic partnerships represent the dominant competitive moves as players defend margin position against sulfuric acid cost swings.
Within the integrated mining tier, OCP Group S.A. and The Mosaic Company exemplify archetypes built on captive ore control and geographic mining diversification respectively. Among retail-intensive operators, Nutrien Ltd. occupies a position defined by distribution density and farm advisory bundling. These three companies anchor competitive dynamics across upstream supply security and downstream customer capture, with their structural positioning shaping how sulfuric acid volatility and regulatory compliance costs transmit through the value chain.
| Leading Market Players |
|---|
| PhosAgro PJSC |
| Coromandel International Ltd. |
| EuroChem Group |
| Nutrien Ltd. |
| Indian Farmers Fertiliser Cooperative Limited |
| The Mosaic Company |
| OCP Group S.A. |
| CF Industries Holdings Inc. |
| Yara International ASA |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Moroccan phosphate rock miners and Asian formulation facilities lock in both raw material access and price visibility across volatile sulfuric acid cycles. These agreements insulate integrated producers from spot market swings while exposing pure traders to margin compression when acidulation input costs spike unpredictably.
Pricing Analysis
After-sales agronomic service bundling drives lifetime value for retail-intensive operators like Nutrien Ltd. Three-tier pricing structure across premium polymer-coated, standard granular, and economy bulk powder levels segments buyers by runoff compliance requirements and equipment sophistication. Price differentiation hinges on solubility certification grade and geographic delivery distance from Jorf Lasfar or Florida mining hubs. Cost compression in standard-grade diammonium phosphate is intensifying because sulfuric acid volatility transmits directly to non-integrated blender margins. Government tender buyers in India and Nigeria exhibit highest price sensitivity; precision agriculture growers in California and the Netherlands show lowest elasticity due to outcome-based contracting.
Supply Chain Analysis
Inbound logistics costs from port congestion at Jorf Lasfar and container availability constraints on Atlantic-South America trade lanes periodically disrupt just-in-time formulation schedules. Geographic supply concentration centers on Morocco, the United States, and China as the three dominant phosphate rock jurisdictions. Raw material dependencies draw from sulfuric acid, ammonia, and phosphate rock feedstock with quality gradations. Single-source vulnerability to OCP Group's ore dominance creates structural supply security risk for non-integrated producers. Distribution runs through bulk vessel charters to deepwater ports, followed by rail and barge networks to inland blending facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phosphatic fertilizers sit in early-cycle expansion as Sub-Saharan Africa food security programs accelerate smallholder penetration faster than any prior adoption wave. This tailwind justifies capacity positioning ahead of demand concentration in the fastest-growing geography.
For Market Incumbents: Compound defensive moats by securing captive phosphate rock through backward integration into Moroccan or Peruvian mining assets, and expand polymer-coated formulation capacity near EPA-regulated US watersheds. Sulfuric acid cost volatility threatens blender margins; vertical integration into acid production or long-term supply agreements with smelter offgas providers reduces exposure. Certification investment in REACH-compliant supply chains captures European formulation share from documentation-deficient traders.
For New Entrants and Emerging Players: Lead with precision agriculture service bundling in Brazil's Cerrado, the most penetrable white-space where outcome-based phosphorus prescriptions outpace incumbent retail density. Target greenhouse system operators in Spain's Almería and China's Shandong Province with soluble monoammonium phosphate formulations. Go-to-market angle: variable-rate application contracts tied to soil testing data, unbundling seasonal bulk procurement.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated miners with captive ore reserves and long-term offtake contracts; these archetypes generate cash flow quality superior to trading-dependent blenders. Over the projection horizon, prioritize acquisition targets with pre-certified European supply chains and granular production capacity in Atlantic-adjacent geographies. Watch for inflection when China's MEE mining quotas tighten export-oriented raw material availability, shifting margin pools toward Moroccan and US reserve holders.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Rock Mining | Captive ore access insulates margin structures from OCP Group supply concentration. |
| Polymer-Coated Formulation Capacity Expansion | EPA watershed restrictions near Chesapeake Bay create premium positioning for stabilized products. |
| Long-term Sulfuric Acid Supply Agreement | Smelter offgas contracts reduce input cost volatility for acidulation-dependent blenders. |
| REACH-Compliant Supply Chain Certification | ECHA documentation requirements extend import clearance timelines for uncertified traders. |
| Precision Agriculture Platform Partnership | Variable-rate contracts with Brazil's cooperativa system displace seasonal bulk procurement. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with phosphate rock mining executives, formulation plant managers, agricultural cooperative procurement leads, and precision agriculture platform engineers. Secondary validation drew from OCP Group and Mosaic Company SEC filings, USGS mineral commodity summaries, ECHA REACH registration databases, and Brazil's ANVISA residue compliance records. Bottom-up volume modeling triangulated against top-down macroeconomic agricultural intensity indicators.
Across the analysis window, forecasts employed a segmented analytical framework spanning product chemistry tier, crop application intensity, equipment mechanization level, and regional regulatory cluster. CAGRs were derived from trend extrapolation of phosphate application rates per hectare against yield gap closure trajectories in Brazil and Sub-Saharan Africa. Industry-specific inputs included sulfuric acid price volatility indices and government subsidy program disbursement cycles in India and Nigeria.
The analysis sits within stated boundaries; outcomes outside sustained Farm to Fork Strategy enforcement, continued Chinese mining quota restrictions, or accelerated precision agriculture adoption would require recalibration. Forecasts reflect documented assumptions about sulfuric acid supply elasticity and smallholder credit access expansion. Specific risk factors that could revise projections include abrupt EPA enforcement tightening, Moroccan export license modifications, or substitution acceleration toward biological phosphorus sources. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Global Urea Market
Fertilizers
Ammonium Thiosulfate Fertilizer Market
Fertilizers
Nitrogen Nutrients Market
Fertilizers
Global Complex Fertilizers Market
Fertilizers
North America Micronutrient Fertilizers Market
Fertilizers
Sulfur Fertilizer Market
Fertilizers
Fertilizer Spreader Market
Fertilizers
Humate Fertilizer Market
Fertilizers
Biochar Fertilizer Market
Fertilizers
Ammonium Sulfate Fertilizer Market
Fertilizers
Global Controlled Release Fertilizer Market
Fertilizers
Asia-Pacific Specialty Fertilizer Market
Fertilizers
Vietnam Fertilizers Market
Fertilizers
Middle East and Africa Micronutrient Fertilizer Market
Fertilizers
Neem-Based Fertilizers Market
Fertilizers
Russia Specialty Fertilizer Market