
 Europe Fertilizers Market | 2026-2036
Europe Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fertilizers Market Analysis
Agronomic expertise is unwinding across Eastern Europe as veteran soil scientists retire faster than universities replace them. Yara International ASA leverages its digital farming platforms to capture precision application demand where local advisory capacity thins. EuroChem Group sustains phosphate cost advantages through captive mine-to-gate logistics. Grupa Azoty S.A. anchors nitrogen supply security for Polish cereal operations.
Fertilizers encompass industrially manufactured nutrient amendments—typically formulated with specified N-P-K ratios, secondary elements, or micronutrient coatings—designed to replenish soil fertility and optimize plant metabolic efficiency. Manufacturing routes span Haber-Bosch ammonia synthesis, phosphate rock acidulation, and potash solution mining, with formulation blending determining field-level nutrient release profiles. Nitrogenous products dominate volume flows across the region, though complex fertilizers command margin premiums where application precision reduces environmental compliance costs. Horticulture applications are expanding fastest within the application taxonomy, driven by protected cultivation expansion in the Netherlands and Italy. Agricultural cooperatives remain the dominant distribution channel in France and Germany, capturing farmer loyalty through collective purchasing power and seasonal credit extension.
The EU Green Deal and Farm to Fork Strategy mandate nutrient loss reductions, compelling reformulation toward stabilized and controlled-release products. REACH governs raw material registration and environmental fate disclosure, while national implementations of the Nitrates Directive cap application rates in designated vulnerable zones. ECHA reviews of cadmium limits in phosphate fertilizers are reshaping raw material sourcing economics for importers. Stakeholders must monitor evolving carbon border adjustment mechanisms and national fertilizer carbon intensity benchmarks to preserve market access.
Market Dynamics
The EU Green Deal's nutrient-loss mandates are compressing conventional fertilizer margins while accelerating stabilized and controlled-release formulation adoption across the region's agricultural belt.
Growth Catalysts
- Farm to Fork Strategy:The EU's binding 50% nutrient-loss reduction target by 2030 is compelling growers toward precision-applied specialty products that minimize environmental compliance penalties.
- Protected cultivation expansion:Netherlands greenhouse operators and Italian horticulture clusters are driving micronutrient demand for high-value vegetable and ornamental production.
- Digital farming platforms:Variable-rate application technologies are penetrating Eastern European cereal operations where agronomic advisory capacity has thinned.
Market Restraints
- Natural gas cost volatility:Ammonia synthesis economics swing with TTF hub pricing, compressing nitrogen producer margins during heating-demand spikes.
- Phosphate rock concentration:Moroccan and Russian mine-to-gate logistics dominate raw material supply, exposing European blenders to geopolitical transit disruptions.
- REACH registration burden:ECHA's extended environmental fate disclosure requirements are extending new product commercialization timelines for specialty coating technologies.
Strategic Opportunities
- Polish nitrogen security:Domestic ammonia capacity expansion offers captive supply integration for cereal belt cooperatives seeking price stability.
- Carbon intensity benchmarking:France's national low-carbon fertilizer certification scheme creates premium positioning for producers with verified supply chain emissions data.
- Biostimulant convergence:Microbial inoculant and seaweed extract technologies are merging with conventional N-P-K formulations to create next-generation efficiency products.
Industry Challenges
- Soil science talent depletion:Eastern European universities are graduating agronomists faster than veteran field advisors retire, eroding precision-application support infrastructure.
- Legacy equipment incompatibility:Controlled-release fertilizers require recalibrated spreader calibration protocols that many French and German farming cooperatives have deferred updating.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fertilizers Market |
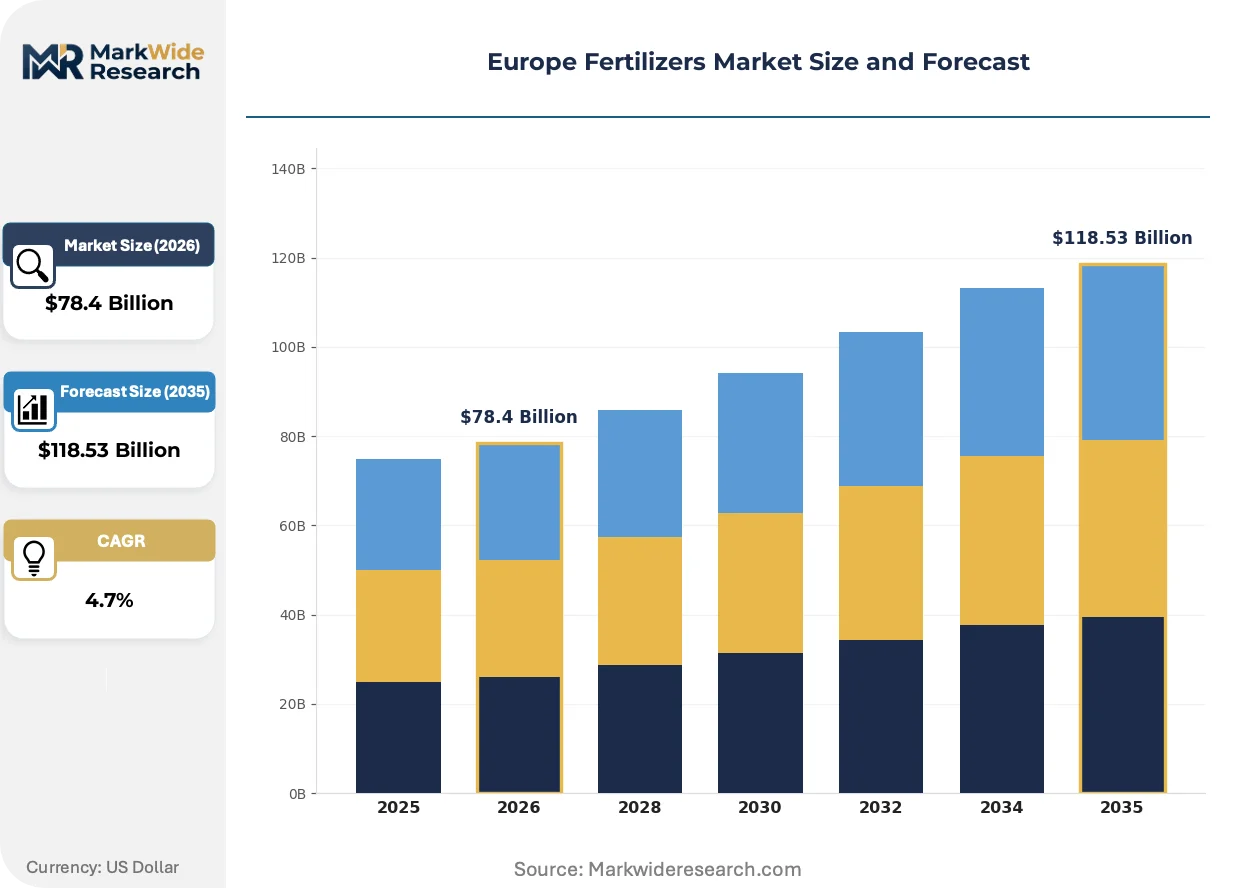
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $118.53 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitrogenous, Phosphatic, Potassic, Complex Application: Crop Nutrition, Horticulture, Turf Management, Soil Improvement Distribution Channel: Online Retail, Distributors, Agricultural Cooperatives, Direct Sales End User: Farmers, Agribusinesses, Garden Centers, Landscaping Companies |
| Companies Covered | Yara International ASA, EuroChem Group, ICL Group Ltd, Fertiberia, CF Industries Holdings, Inc., OCI Global N.V., Grupa Azoty S.A., K+S Aktiengesellschaft, The Mosaic Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fertilizers Market Emerging Trajectories
Formulation chemistry and application precision are converging as regulatory pressure tightens, with digital agronomy tools enabling site-specific nutrient management that was technically infeasible a decade prior.
Controlled-release polymer coatings are supplanting conventional urea in intensive cereal and horticulture systems across France and the Netherlands. Large-scale arable operations in the Paris Basin are adopting these products to maintain yield targets while staying within Nitrates Directive application caps. The technology is compressing commodity nitrogen margins while expanding specialty product premiums.
REACH's evolving cadmium limits for phosphate fertilizers are forcing importers to requalify rock sources or invest in beneficiation capacity. ECHA's 2023 review tightened thresholds for cadmium content, directly affecting Moroccan and Tunisian rock economics for European processors. Blend-dependent markets in Germany and Belgium are accelerating testing protocols to preserve market access.
Cooperative procurement consolidation is compressing distributor margins across the French cereal belt and German mixed-farming regions. Agricultural cooperatives in Normandy and Lower Saxony are pooling seasonal volumes to negotiate direct manufacturer contracts, bypassing traditional wholesale channels. This concentration is most visible in nitrogen product categories where price transparency through digital platforms has eroded information asymmetries.
Europe Fertilizers Market Segmentation
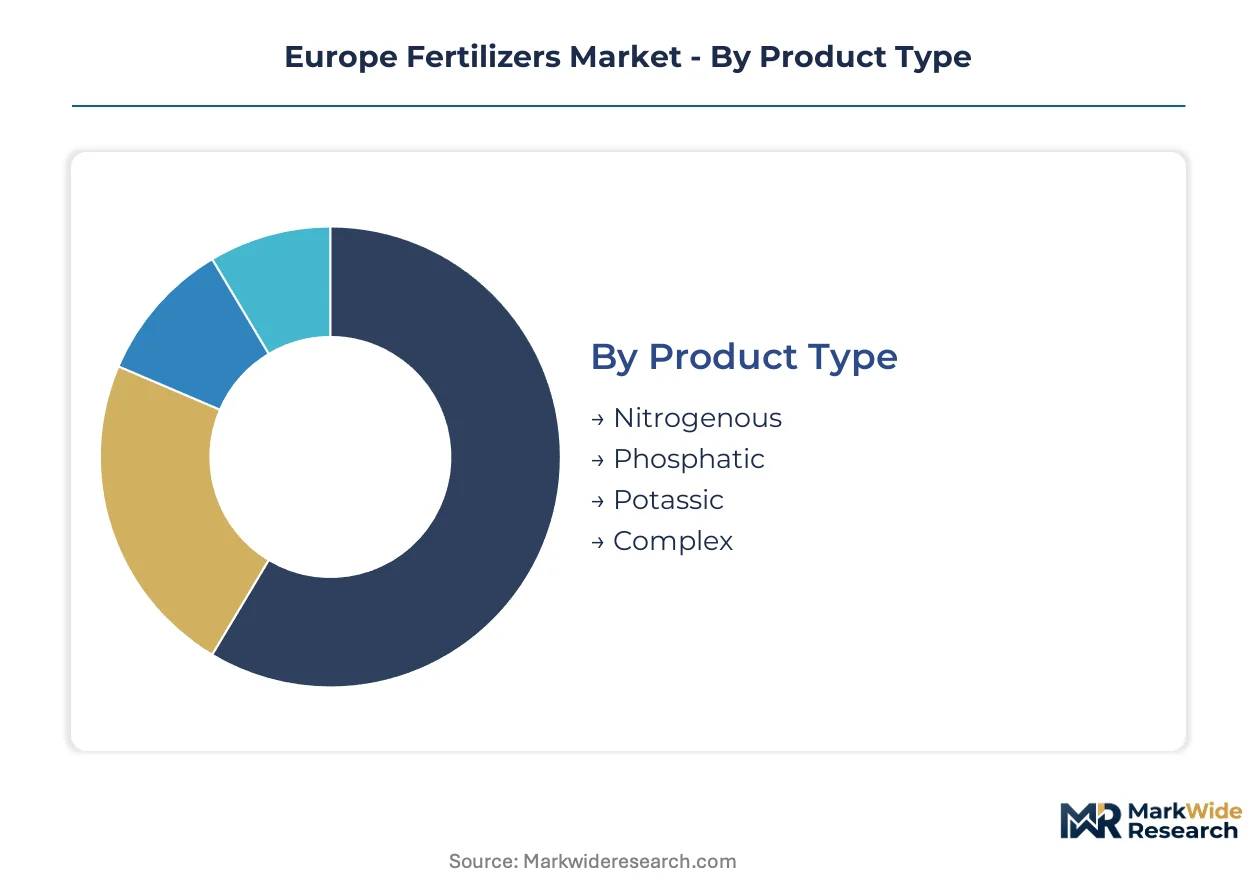
Segmentation reveals how regulatory pressure and channel economics reshape product flows across European agricultural systems. Channel concentration in cooperatives versus digital platforms determines which formulations reach which end-users.
Product Type:
Channel-mix dynamics vary sharply by product chemistry, with nitrogenous commodities flowing through cooperative bulk procurement while complex specialty products penetrate via distributor technical sales.
- Nitrogenous:Urea and ammonium nitrate formulations dominate volume flows through Haber-Bosch synthesis routes. French cereal belt cooperatives in Normandy and the Paris Basin concentrate procurement here, though TTF gas price spikes compress blender margins during winter heating peaks.
- Complex:Multi-nutrient formulations with tailored N-P-K ratios and micronutrient coatings command distributor technical support. Dutch greenhouse clusters and Italian horticulture operations in Emilia-Romagna drive adoption where precision application reduces Nitrates Directive compliance costs.
- Phosphatic:Single or triple superphosphate products depend on Moroccan and Tunisian rock imports facing ECHA cadmium threshold scrutiny.
- Potassic:Muriate and sulfate of potash sourced from Belarusian and Russian mines before transit disruptions redirected supply toward Canadian and Jordanian origins.
By volume, Nitrogenous leads. By growth pace, Complex is climbing the fastest.
Application:
Cost tier stratification separates commodity bulk applications from premium precision-managed systems where environmental compliance penalties reshape economics.
- Crop Nutrition:Broad-acre cereal and oilseed fertilization across France, Germany, and Poland generates baseline demand. Large arable operations in Lower Saxony and Brandenburg prioritize cost-per-hectare efficiency over formulation sophistication.
- Horticulture:Protected cultivation of vegetables, ornamentals, and fruits in Dutch Venlo greenhouses and Italian Po Valley tunnels demands micronutrient precision and controlled-release coatings. Water-soluble and foliar formulations penetrate here via distributor agronomist relationships.
- Soil Improvement:Organic amendment blending and pH correction products serve mixed-farming rotations in Bavaria and Austria where livestock integration sustains manure-chemical hybrid approaches.
- Turf Management:Golf courses, sports pitches, and municipal parks in the UK and Scandinavia specify slow-release nitrogen for aesthetic performance with runoff minimization.
By revenue concentration, Crop Nutrition dominates. By margin expansion, Horticulture is gaining share fastest.
Distribution Channel:
Customer-type concentration shapes channel viability, with farmer cooperatives demanding seasonal credit extension that online platforms cannot replicate.
- Agricultural Cooperatives:Member-owned purchasing bodies in France's cereal belt and Germany's mixed-farming regions aggregate seasonal volumes for direct manufacturer negotiation. Credit terms and collective bargaining power lock in farmer loyalty despite price transparency erosion from digital platforms.
- Distributors:Independent wholesalers with technical agronomy staff serve horticulture and specialty crop segments where application advice justifies margin retention. Belgian and Dutch distribution networks concentrate here due to dense greenhouse geography.
- Direct Sales:Large estate farms and agribusinesses in Eastern Poland and Romania bypass intermediaries for ammonia and UAN bulk delivery.
- Online Retail:E-commerce platforms capture garden center and smallholder demand for packaged specialty products, though bulk fertilizer logistics resist digital penetration.
By tonnage throughput, Agricultural Cooperatives lead. By digital penetration growth, Online Retail is expanding most quickly.
End User:
Volume scale versus application sophistication divides end-user economics, with agribusinesses driving procurement centralization while landscaping fragments across service providers.
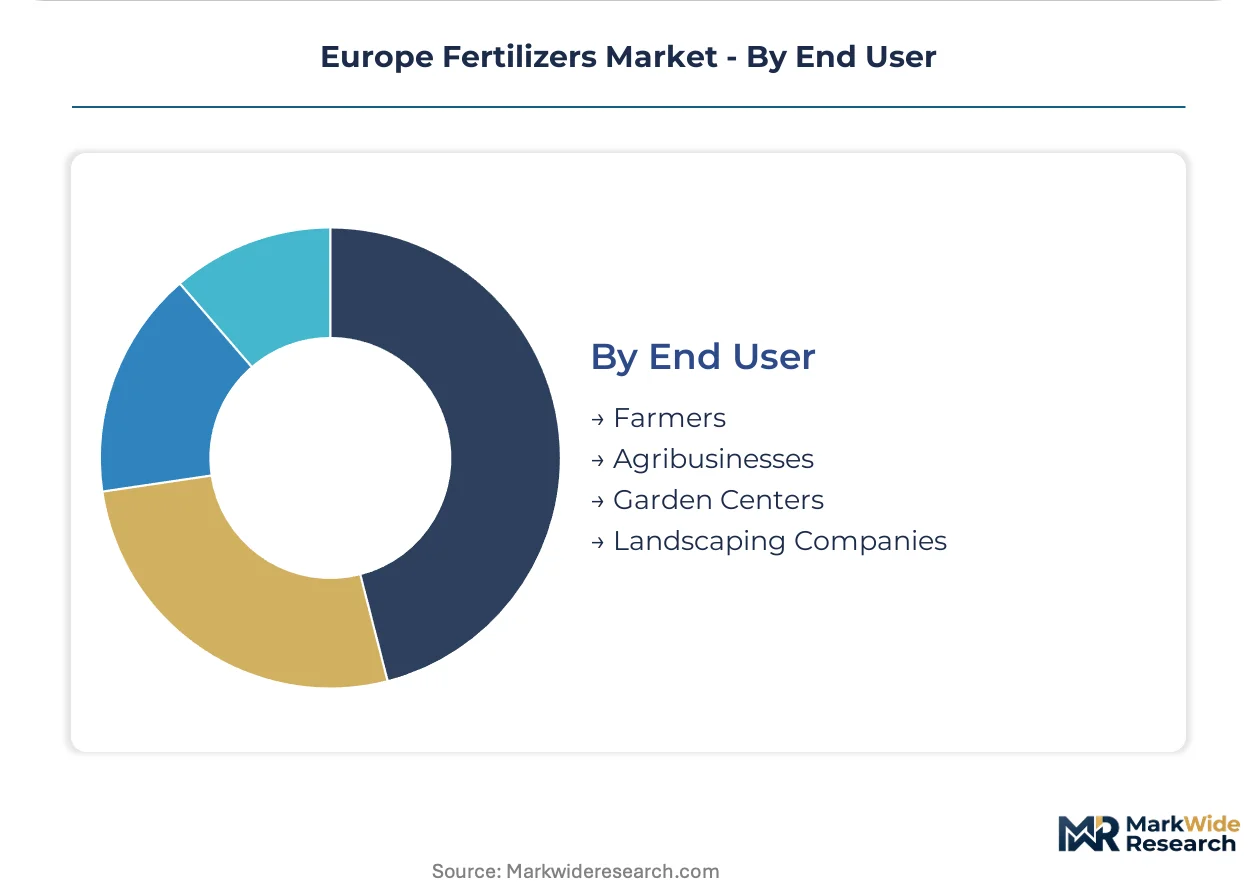
- Farmers:Individual and cooperative-member growers across Europe's agricultural belt make formulation decisions constrained by CAP subsidy compliance and national fertilizer reduction targets. French and German cereal producers dominate absolute consumption.
- Agribusinesses:Corporate farming operations and integrated food processors in Ukraine, Romania, and Poland centralize procurement for supply security. Vertical coordination from grain trading to input supply compresses independent distributor roles.
- Garden Centers:Retail outlets serving amateur growers and suburban households package specialty lawn and ornamental products with seasonal merchandising.
- Landscaping Companies:Commercial turf and grounds maintenance contractors in urban France and the UK specify professional-grade slow-release formulations for contract performance guarantees.
By absolute volume, Farmers lead. By procurement professionalization, Agribusinesses show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
French cooperatives command pricing leverage over German distributors in nitrogen procurement, while Dutch greenhouse operators extract premium terms for micronutrient formulations that Baltic blenders cannot match.
France
Cereal belt cooperatives in Normandy and the Paris Basin aggregate bulk urea volumes for direct manufacturer negotiation. The Nitrates Directive caps application rates in designated vulnerable zones, compressing commodity margins. Large arable operations around Chartres adopt controlled-release coatings to maintain yields within regulatory limits.
Germany
Mixed-farming regions in Lower Saxony and Bavaria sustain livestock-chemical hybrid fertilization approaches. REACH registration requirements extend commercialization timelines for specialty coating technologies. Industrial clusters along the Rhine corridor concentrate ammonia import terminals serving domestic blenders.
Netherlands
Venlo greenhouse operators and Westland horticulture clusters drive water-soluble and foliar formulation demand. The EU Green Deal's nutrient-loss mandates accelerate stabilized product adoption. Precision application equipment manufacturers around Eindhoven supply variable-rate technologies to protected cultivation facilities.
Poland
Domestic ammonia capacity expansion anchors nitrogen supply security for cereal belt cooperatives. Grupa Azoty facilities near Tarnów and Puławy integrate captive production for price stability. Eastern estate farms in Podlaskie bypass intermediaries for bulk UAN delivery.
Italy
Po Valley tunnels and Emilia-Romagna horticulture operations demand micronutrient precision for high-value vegetable production. Farm to Fork Strategy compliance costs reshape formulation preferences toward specialty products. Adriatic port infrastructure handles Moroccan phosphate rock facing ECHA cadmium threshold scrutiny.
Europe Fertilizers Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the European fertilizer landscape. The market structure consolidates around nitrogen specialists with captive ammonia capacity and diversified blenders with import-dependent phosphate economics. Three archetypes dominate: integrated producers with mine-to-gate phosphate control, regional nitrogen champions with domestic gas contracts, and specialty formulators with micronutrient coating expertise. Competitive moves concentrate on backward integration into ammonia production and portfolio diversification toward controlled-release formulations.
Among Nordic-integrated producers, Yara International ASA exemplifies the precision-application technology archetype through digital farming platform deployment. EuroChem Group occupies a position representing captive phosphate cost advantages through upstream mining integration. Grupa Azoty S.A. anchors the regional nitrogen security tier for Central European cereal operations.
| Leading Market Players |
|---|
| Yara International ASA |
| EuroChem Group |
| ICL Group Ltd |
| Fertiberia |
| CF Industries Holdings, Inc. |
| OCI Global N.V. |
| Grupa Azoty S.A. |
| K+S Aktiengesellschaft |
| The Mosaic Company |
| Others |
Supply Flow & Price Mechanics
REACH registration tiers gate both raw material qualification and price differentiation across European fertilizer markets, with ECHA's cadmium thresholds for phosphate rock forcing importers into costly beneficiation investments or premium sourcing premiums that reshape blender economics.
Pricing Analysis
Price spreads between TTF-indexed nitrogen products and stabilized specialty formulations widen during heating-demand spikes, with Dutch greenhouse operators paying premiums for micronutrient coatings that French cereal cooperatives reject. Three-tier pricing structure across premium controlled-release, standard complex, and economy bulk urea levels reflects certification grade and volume scale differentiation. Cost compression in commodity nitrogen is intensifying because Grupa Azoty's captive ammonia capacity anchors Polish supply security. Agricultural cooperatives exhibit highest price sensitivity through collective procurement leverage, while Dutch horticulture clusters show lowest sensitivity where compliance cost avoidance justifies formulation premiums.
Supply Chain Analysis
Morocco and Tunisia anchor phosphate rock supply for European acidulation plants, with Russian and Belarusian potash origins redirecting toward Canadian and Jordanian alternatives after transit disruptions. Ammonia synthesis draws from Norwegian and Algerian gas-linked capacity, while phosphate beneficiation rests on Moroccan mine-to-gate logistics. Single-source vulnerability concentrates in Moroccan rock dependence where ECHA cadmium reviews threaten qualification status. Distribution runs through agricultural cooperatives in France and Germany for bulk nitrogen, with independent distributors serving Dutch and Italian specialty segments via technical agronomist relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European fertilizer markets sit in early-cycle expansion as Farm to Fork Strategy nutrient-loss mandates accelerate precision formulation adoption ahead of regulatory deadlines.
For Market Incumbents: Shield nitrogen margin positions through backward integration into ammonia capacity near TTF-advantaged hubs, while accelerating controlled-release coating R&D to capture specialty premiums before REACH registration timelines extend further. Digital farming platform deployment captures advisory capacity gaps in Eastern Europe where veteran soil scientist retirements erode precision-application support. For New Entrants and Emerging Players: Anchor in Polish cereal belt cooperatives seeking price stability alternatives to Grupa Azoty dominance, and Italian horticulture clusters demanding micronutrient precision for high-value vegetable production. White-space penetration targets Baltic states where agronomic advisory infrastructure thins and cooperative procurement consolidation lags Western Europe. Go-to-market leverage rests on seasonal credit extension terms that match incumbent cooperative structures. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across controlled-release formulation capacity where polymer coating technology and REACH compliance infrastructure demand consolidated investment. Five-to-ten year viability favors blenders with captive ammonia supply or mine-to-gate phosphate control over import-dependent processors. Acquisition target archetype: regional nitrogen champions with domestic gas contracts and underutilized coating technology platforms. Signal to watch: ECHA cadmium threshold enforcement stringency as trigger for phosphate sourcing economics restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonia Capacity | Captive supply from TTF-linked hubs insulates nitrogen margins during heating-demand spikes. |
| Controlled-Release Coating Technology Investment | Polymer formulation expertise captures Farm to Fork compliance premiums in French cereal zones. |
| Digital Farming Platform Deployment | Yara-style precision tools fill advisory gaps where Eastern European soil scientists retire. |
| Phosphate Rock Source Requalification | ECHA cadmium compliance preserves market access for Moroccan and Tunisian import-dependent blenders. |
| Cooperative Procurement Consolidation | Normandy and Lower Saxony collective bargaining compresses distributor margins while locking farmer loyalty. |
Methodological Framework
Desk research of trade flow databases, ECHA regulatory filings, and national agricultural statistics preceded structured interviews with ammonia plant managers, cooperative procurement directors, Dutch greenhouse operators, and specialty distributor agronomists. Primary fieldwork with nitrogen producers and phosphate importers combined with secondary validation against customs records and Cefic industry reports. Bottom-up volume modeling and top-down value reconciliation triangulated segment outputs.
Variance decomposition across product chemistry, application intensity, and channel concentration shaped analytical framework development over the projection horizon. Segmentation dimensions modeled include nitrogenous versus complex versus phosphatic versus potassic product types, crop nutrition versus horticulture versus soil improvement applications, and cooperative versus distributor versus direct sales channels. CAGRs derived from historical volume elasticity analysis against TTF pricing and regulatory compliance cost trajectories, with Farm to Fork adoption curves and REACH registration timelines as industry-specific forecast inputs.
Material uncertainties — TTF hub volatility, ECHA cadmium enforcement calibration, and Eastern European agronomic advisory capacity erosion — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory timeline adherence and cooperative procurement consolidation velocity. Recalibration cycles align with material shifts in EU Green Deal implementation guidance and national fertilizer reduction target enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Global Fertilizers Market
Fertilizers
Nitrogen Nutrients Market
Fertilizers
Global Urea Market
Fertilizers
Polymer Coated Urea Market
Fertilizers
Multi-Nutrient Fertilizer Market
Fertilizers
Africa Potash Fertilizer Market
Fertilizers
Africa Fertilizers Market
Fertilizers
Sulfur Fertilizer Market
Fertilizers
Africa Specialty Fertilizer Market
Fertilizers
Italy Water Soluble Fertilizer Market
Fertilizers
China Micronutrient Fertilizer Market
Fertilizers
Phosphate Fertilizers Market
Fertilizers
Potash Market
Fertilizers
Global Phosphatic Fertilizers Market
Fertilizers
Europe Specialty Fertilizer Market
Fertilizers
Middle East and Africa Specialty Fertilizer Market