
 Veterinary Syringes Market | 2026-2036
Veterinary Syringes Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Syringes Market Analytics
A capital-intensity divergence between integrated glass converters and regional plastic molders is redrawing competitive boundaries in veterinary syringe supply. SCHOTT Group leverages its borosilicate glass expertise to anchor premium safety syringe lines for large-animal biologics. Henke-Sass Wolf sustains German manufacturing scale across reusable metal-and-glass systems for European livestock veterinarians. Becton Dickinson competes through disposable plastic volume and channel control in North American companion animal clinics.
Veterinary syringes are precision injection instruments engineered from borosilicate glass, medical-grade polypropylene, or stainless steel, with Luer-lock or slip-tip configurations calibrated for species-specific dosing accuracy in animal health applications. Disposable syringes dominate procurement volumes in veterinary clinics due to biosecurity protocols, while safety syringes capture expanding margin pools as occupational needlestick regulations tighten across jurisdictions. Automatic syringes serve high-throughput livestock operations where intramuscular delivery of multivalent vaccines requires speed and dose consistency.
The FDA's Center for Veterinary Medicine governs device biocompatibility for food-animal applications, while ISO 7886-1 sets dimensional and performance benchmarks for sterile hypodermic syringes used across species. The EU MDR's expanded scope for veterinary devices sold in human healthcare settings is forcing dual-certification strategies among exporters. Stakeholders must monitor how antimicrobial stewardship policies reshape vaccination protocols and, by extension, syringe specification requirements across production animal segments.
Market Dynamics
The veterinary syringes market is reconfiguring around biosecurity mandates that mandate single-use devices in commercial livestock operations, compressing demand toward disposable plastics while elevating safety-engineered alternatives in regulated jurisdictions.
Growth Catalysts
- Livestock Vaccination Scale-Up:Brazil's foot-and-mouth disease eradication campaigns in Mato Grosso and Pará states are driving mass immunization infrastructure procurement for high-capacity automatic syringe systems.
- EU MDR Dual-Certification Pull:Veterinary device exporters serving EU human healthcare settings must achieve MDR compliance, accelerating safety syringe upgrades across European distribution channels.
- Antimicrobial Stewardship Protocols:Veterinary biologics administration guidelines from the FDA's Center for Veterinary Medicine are expanding precision dosing requirements that favor calibrated Luer-lock configurations.
Market Restraints
- Medical-Grade Polypropylene Volatility:Petrochemical feedstock fluctuations are squeezing margins for disposable plastic syringe molders concentrated in East Asian manufacturing clusters.
- Borosilicate Glass Supply Concentration:SCHOTT Group's dominance in pharmaceutical-grade tubing creates bottleneck risk for premium glass syringe converters serving large-animal biologics.
- Reusable Metal System Substitution:German and Dutch livestock veterinarians retain stainless steel-and-glass reusable systems, limiting penetration of disposable alternatives in established European practices.
Strategic Opportunities
- Underpenetrated Indian Dairy Sector:India's National Dairy Development Board vaccination programs for brucellosis and mastitis control present volume openings for automatic syringe suppliers.
- Connected Device Convergence:Integration of RFID dose-tracking with safety syringe platforms addresses traceability mandates from the FDA's animal drug compounding regulations.
- Direct Veterinary Clinic Channels:Bypassing traditional distributor tiers through e-procurement platforms is capturing North American companion animal clinic demand for standardized SKU bundles.
Industry Challenges
- ISO 7886-1 Certification Timelines:Sterile hypodermic syringe dimensional and performance testing protocols are extending product launch cycles for regional molders seeking export qualification.
- Legacy Equipment Integration:Automated livestock vaccination lines in Australian feedlot operations require retrofit compatibility with existing pneumatic injection systems, complicating safety syringe adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Syringes Market |
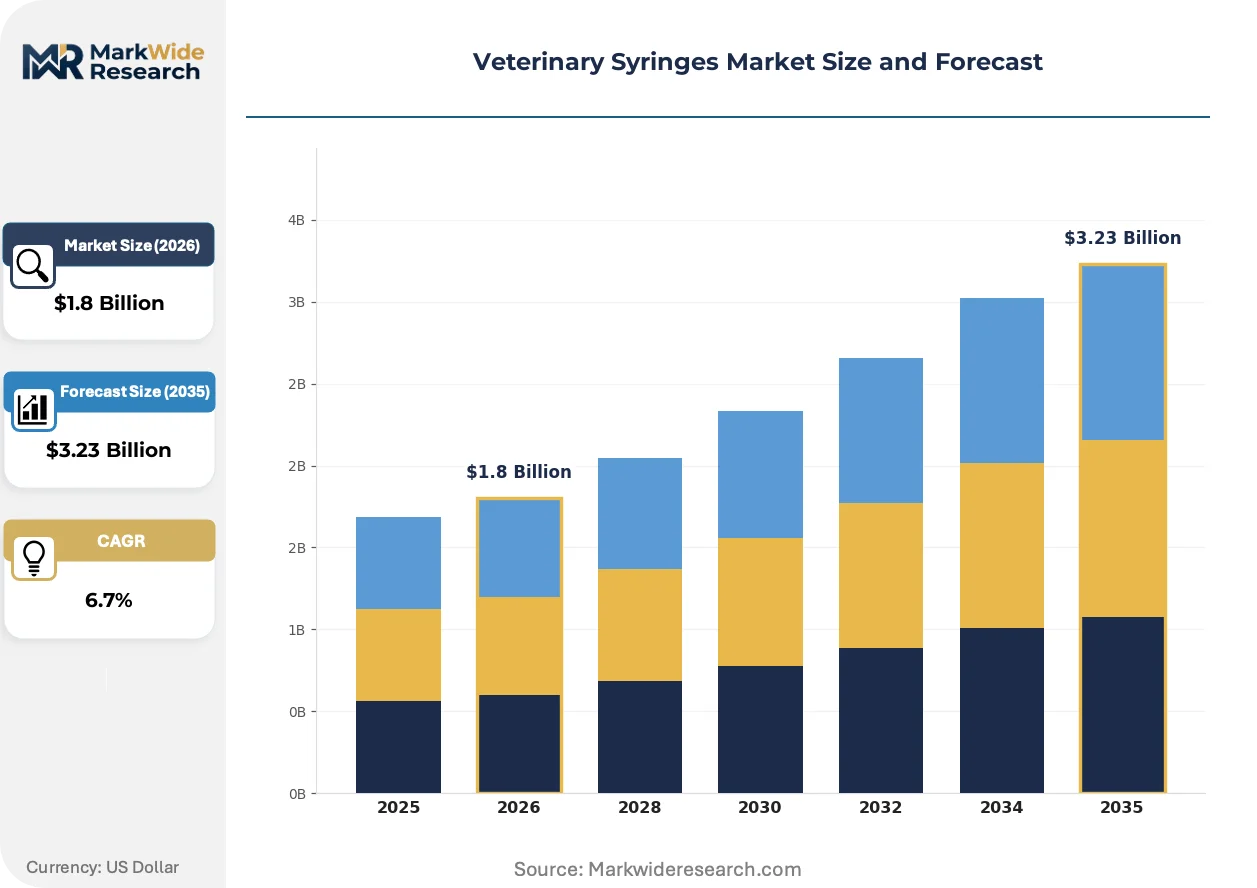
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Syringes, Reusable Syringes, Automatic Syringes, Safety Syringes Volume: 1ml, 5ml, 10ml, 20ml Delivery Mode: Intramuscular, Subcutaneous, Intravenous, Oral End User: Veterinary Clinics, Animal Hospitals, Research Laboratories, Home Care |
| Companies Covered | SCHOTT Group, Henke-Sass Wolf, Becton Dickinson, Zoetis, Retractable Technologies, Terumo Medical Corporation, Nipro Medical Corporation, Merck & Co., Inc., Gerresheimer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Syringes Market Evolving Landscape
Device architecture is splintering between premium safety-engineered platforms for regulated markets and cost-optimized disposable systems for volume livestock applications, with material science and connectivity features determining competitive position.
Needle retraction mechanisms in veterinary safety syringes are bifurcating the product landscape. Large-animal biologics manufacturers in the United States are specifying integrated sharps protection to satisfy OSHA needlestick prevention mandates, while Brazilian beef operations prioritize speed and dose consistency over safety features. This divergence is compressing mid-tier offerings and forcing suppliers to commit to either premium certification or economy scale.
REACH substance restrictions on phthalates and BPA in medical devices are accelerating material transitions across EU-bound veterinary syringe production. German converters are migrating to cyclic olefin polymers for barrel clarity and chemical resistance, with compliance costs filtering through to pricing in veterinary clinic channels. The shift is most pronounced in multi-dose vial adapters and pre-filled syringe systems for companion animal therapeutics.
Consolidated buying by corporate veterinary groups in the United States is unbundling after-sales service from device procurement. Banfield Pet Hospital and VCA Animal Hospitals are negotiating direct manufacturer contracts for standardized safety syringe SKUs, displacing independent distributor relationships that previously dominated clinic supply. This concentration is visible most acutely in metropolitan Texas and California markets where practice roll-ups have accelerated.
Veterinary Syringes Market Segmentation
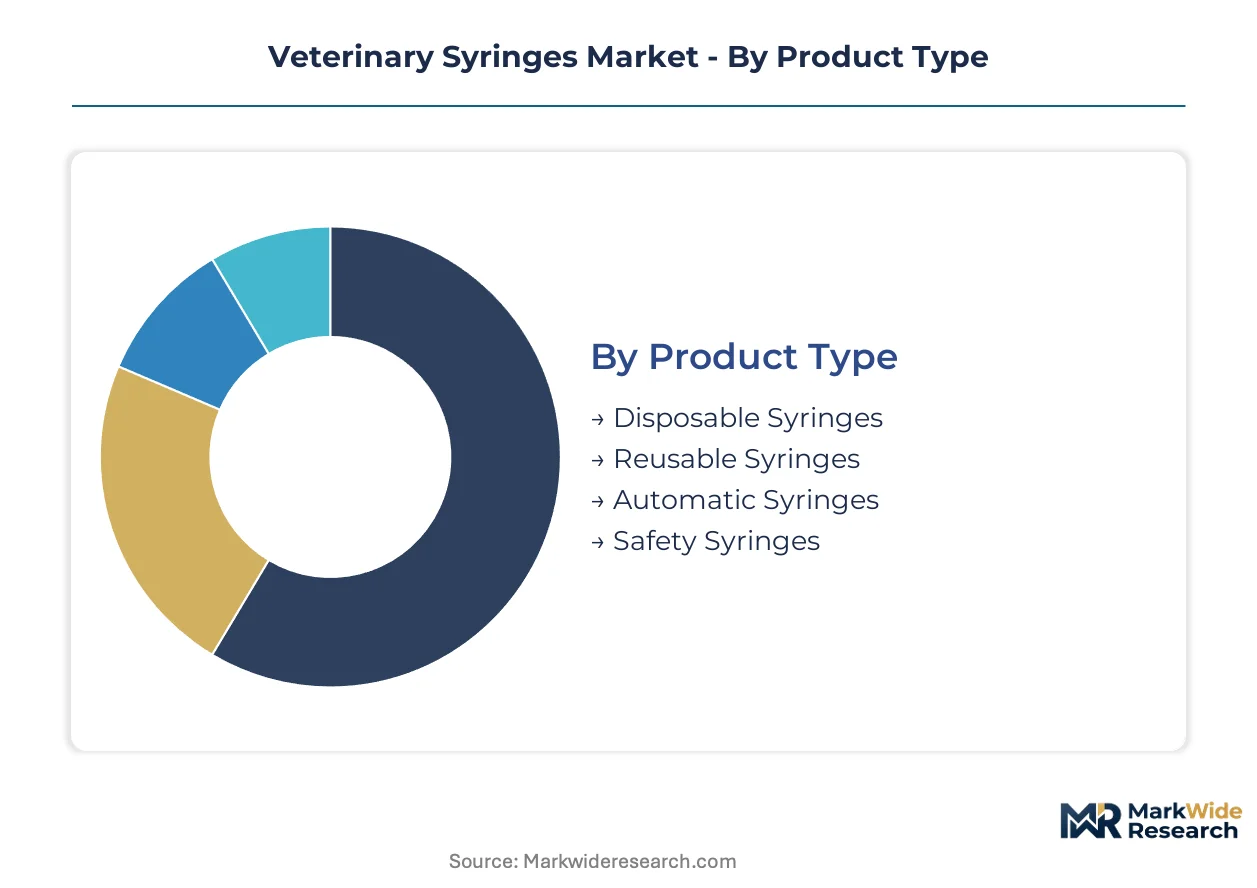
Veterinary syringe procurement splits sharply across biosecurity protocols, dosing precision requirements, and species-specific administration routes. Regulatory mandates from FDA's Center for Veterinary Medicine and EU MDR reshape specification priorities differently across each segment boundary.
Product Type:
FDA animal drug compounding regulations and OSHA needlestick mandates create divergent compliance burdens across disposable, reusable, and safety-engineered platforms.
- Disposable Syringes:Medical-grade polypropylene construction with Luer-lock or slip-tip configurations dominates clinic procurement due to biosecurity protocols. Brazilian foot-and-mouth disease eradication campaigns in Mato Grosso and Pará states are driving mass immunization infrastructure procurement for high-volume disposable systems.
- Safety Syringes:Integrated needle retraction mechanisms and sharps protection engineering satisfy OSHA prevention mandates in US large-animal biologics manufacturing. EU MDR dual-certification requirements for veterinary devices sold in human healthcare settings are accelerating safety syringe upgrades across European distribution channels.
- Reusable Syringes:Stainless steel-and-glass systems sustain German and Dutch livestock veterinary practices, limiting disposable penetration in established European markets.
- Automatic Syringes:Pneumatic and manual high-throughput systems deliver multivalent vaccines with speed and dose consistency in Australian feedlot operations.
Established volume favors disposable platforms; emerging adoption favors safety-engineered alternatives.
Volume:
Capacity selection tracks species body mass and biologic dosing protocols, with precision requirements tightening across companion animal applications.
- 1ml:Calibrated micro-dosing for companion animal therapeutics and feline/canine biologics administration in North American metropolitan clinic networks.
- 5ml:Mid-range capacity serving small ruminant and swine vaccination protocols with standardized Luer-lock precision.
- 10ml:Workhorse specification for bovine intramuscular delivery; Indian National Dairy Development Board brucellosis programs are expanding procurement of this capacity tier.
- 20ml:Large-volume reservoir for equine and cattle multivalent vaccines; Banfield Pet Hospital and VCA corporate contracts are standardizing 20ml safety SKU bundles in Texas and California markets.
Companion animal precision drives 1ml and 5ml specification; livestock scale concentrates 10ml and 20ml procurement.
Delivery Mode:
Route selection determines barrel design, needle gauge, and plunger force engineering, with intramuscular commanding the largest procurement volumes in production animal segments.
- Intramuscular:Deep tissue delivery of oil-adjuvanted vaccines and antibiotics in cattle and swine operations; Brazilian beef state vaccination infrastructure specifies high-capacity automatic systems for this route.
- Subcutaneous:Dermal layer administration for companion animal immunizations and certain poultry biologics; REACH phthalate restrictions are accelerating cyclic olefin polymer transitions in EU-bound subcutaneous devices.
- Intravenous:Direct bloodstream delivery for emergency therapeutics and anesthesia in equine and large animal hospitals.
- Oral:Drenching and paste administration systems for anthelmintics and nutritional supplements in small ruminant and companion animal applications.
Livestock biologics concentrate intramuscular procurement; companion animal channels split between subcutaneous immunization and oral supplementation.
End User:
Channel concentration and procurement authority reshape supplier relationships, with corporate veterinary groups displacing traditional distributor tiers in North American metropolitan markets.
- Veterinary Clinics:Primary care and preventive medicine settings; e-procurement platform adoption is capturing standardized safety syringe demand in independent and corporate-affiliated practices.
- Animal Hospitals:Emergency and specialty referral centers with higher-margin therapeutic administration; ISO 7886-1 certification timelines extend product qualification cycles for regional molders seeking hospital supply contracts.
- Research Laboratories:Preclinical and field trial applications with stringent traceability requirements; RFID dose-tracking integration addresses FDA animal drug compounding regulations for parenteral delivery devices.
- Home Care:Owner-administered chronic disease management and post-surgical care in companion animal segments; simplified Luer-lock configurations reduce administration error risk in non-clinical settings.
Institutional procurement concentrates in clinics and hospitals; home care represents the steepest expansion trajectory as chronic disease management shifts beyond clinical settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across veterinary syringe procurement channels, with Brazilian livestock operations prioritizing volume cost efficiency while German companion animal clinics absorb premium safety-engineered pricing. This divergence reshapes supplier strategies and certification investments by geography.
United States
Banfield Pet Hospital and VCA Animal Hospitals consolidate procurement through direct manufacturer contracts in Texas and California metropolitan markets. OSHA needlestick prevention mandates drive safety syringe specification in large-animal biologics manufacturing. Greater Boston's research corridor demands RFID-integrated dose-tracking devices for FDA animal drug compounding compliance.
Brazil
Foot-and-mouth disease eradication campaigns in Mato Grosso and Pará states generate mass immunization infrastructure demand for high-capacity automatic systems. ANVISA traceability requirements tighten parenteral delivery device documentation for commercial cattle operations. São Paulo state's veterinary distributor networks channel disposable plastic volume to beef-producing regions.
Germany
Livestock veterinarians in Lower Saxony retain stainless steel-and-glass reusable systems, limiting disposable penetration in established practices. EU MDR dual-certification requirements accelerate safety syringe upgrades across European distribution channels. Baden-Württemberg's precision engineering clusters supply calibrated Luer-lock configurations for companion animal therapeutics.
India
The National Dairy Development Board's brucellosis and mastitis vaccination programs create volume openings for automatic syringe suppliers in Gujarat and Maharashtra. CDSCO biocompatibility standards govern device qualification for food-animal applications. Karnataka's veterinary pharmaceutical corridor concentrates demand for 10ml capacity specifications in bovine intramuscular delivery.
Australia
Automated livestock vaccination lines in Queensland feedlot operations require retrofit compatibility with existing pneumatic injection systems. TGA alignment with ISO 7886-1 standards extends product qualification timelines for regional molders. New South Wales corporate veterinary groups standardize procurement through e-procurement platforms for companion animal clinic networks.
Veterinary Syringes Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in veterinary syringe supply, with capital intensity diverging sharply between glass converters and plastic molders. The upper tier commands premium positioning through material science expertise and regulatory certification depth. Mid-scale regional fabricators compete on disposable volume and channel proximity. Consolidated buying by corporate veterinary groups and livestock procurement cooperatives favors scale players with direct contract capabilities, while safety-engineered specifications reward certification investments.
Among glass-and-metal system specialists, SCHOTT Group and Henke-Sass Wolf exemplify the premium-tier archetype through borosilicate glass expertise and German manufacturing scale. Becton Dickinson occupies a position on the disposable plastic volume vector, channeling standardized SKU bundles through North American companion animal clinic networks. These three anchors illustrate how material specialization and geographic manufacturing concentration determine competitive boundaries.
| Leading Market Players |
|---|
| SCHOTT Group |
| Henke-Sass Wolf |
| Becton Dickinson |
| Zoetis |
| Retractable Technologies |
| Terumo Medical Corporation |
| Nipro Medical Corporation |
| Merck & Co., Inc. |
| Gerresheimer |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Brazilian livestock cooperatives and East Asian polypropylene molders lock in both supply access and price visibility for high-volume disposable syringe procurement. These arrangements insulate mass immunization programs from petrochemical feedstock volatility while compressing margins for spot-market participants.
Pricing Analysis
After-sales service contracts and calibration maintenance agreements drive lifetime value for reusable metal-and-glass system suppliers in German livestock veterinary practices. Three-tier pricing structure across premium safety-engineered, standard disposable, and economy bulk configurations stratifies by certification grade and volume scale. Cost compression in economy disposable tiers is intensifying because medical-grade polypropylene feedstock volatility squeezes East Asian molder margins. Brazilian beef operations exhibit the highest price sensitivity, while US corporate veterinary groups absorb premium safety-engineered pricing for OSHA compliance.
Supply Chain Analysis
Container availability constraints on Asia-Pacific to South America trade lanes elevate inbound logistics costs for polypropylene resin shipments destined for Brazilian syringe molders. Manufacturing concentrates in China, South Korea, and Germany, with borosilicate glass tubing sourcing anchored in SCHOTT's domestic production. Raw material dependencies span pharmaceutical-grade polypropylene, borosilicate glass tubing, and stainless steel alloys. Single-source vulnerability in glass tubing supply creates bottleneck exposure for premium veterinary syringe converters. Distribution runs through veterinary pharmaceutical distributors and direct e-procurement platforms to clinic and livestock operation endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of FDA Center for Veterinary Medicine certification expertise and EU MDR dual-certification capability concentrates competitive advantage among incumbent glass converters and multinational disposable manufacturers.
For Market Incumbents: Shield market position through captive supply of borosilicate glass tubing and accelerated ISO 7886-1 certification investments for safety-engineered product lines. Backward integration into pharmaceutical-grade polypropylene resin sourcing mitigates feedstock volatility exposure from petrochemical market swings. Channel control through direct contracting with corporate veterinary groups displaces independent distributor relationships in North American metropolitan markets. For New Entrants and Emerging Players: Differentiate on RFID-integrated dose-tracking platforms that satisfy FDA animal drug compounding traceability mandates for research laboratory and large-animal biologics segments. India's National Dairy Development Board vaccination programs present the most penetrable geography for automatic syringe suppliers seeking volume scale. A go-to-market angle anchored in e-procurement platform partnerships bypasses entrenched distributor tiers in underpenetrated clinic networks. For Investors and Strategic Acquirers: Regional plastic molders with ISO 7886-1 export qualification and established Brazilian livestock channel relationships represent the most attractive acquisition target archetype for portfolio expansion. Long-term viability hinges on dual-certification capability spanning FDA and EU MDR jurisdictions as regulatory scopes converge. The signal to watch is ANVISA traceability mandate expansion beyond commercial cattle operations into companion animal channels as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Dual-Certification Investment | Unlocks European distribution channels for veterinary devices sold in human healthcare settings. |
| RFID Dose-Tracking Integration | Addresses FDA animal drug compounding regulations for parenteral delivery device traceability. |
| Direct E-Procurement Platform Launch | Bypasses distributor tiers to capture North American corporate veterinary group procurement. |
| Cyclic Olefin Polymer Material Transition | Ensures REACH compliance for EU-bound subcutaneous veterinary syringe devices. |
| Automatic Syringe Capacity Expansion | Serves Brazilian foot-and-mouth disease eradication mass immunization infrastructure demand. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA Center for Veterinary Medicine guidance documents, ISO 7886-1 standards filings, and EU MDR technical documentation. Primary interviews engaged veterinary pharmaceutical procurement managers, livestock operation vaccination program directors, biomedical engineers at corporate veterinary groups, and regulatory affairs specialists at device manufacturers. Secondary validation drew from ANVISA traceability mandates, CDSCO biocompatibility standards, TGA alignment protocols, and customs trade data on polypropylene resin flows. Bottom-up segment sizing triangulates against top-down market boundary analysis.
Segmentation dimensions modeled include product type architecture, volume capacity tier, delivery mode specification, and end-user channel structure across the projection horizon. CAGRs derive from growth driver elasticity analysis against baseline penetration rates and regulatory mandate implementation timelines. Veterinary biologics administration protocol evolution and antimicrobial stewardship policy shifts feed into scenario-weighted forecast outputs.
Decision-makers should treat outputs as directional under assumptions of sustained livestock vaccination scale-up and stable regulatory certification timelines; material deviation would warrant model refresh. Antimicrobial stewardship acceleration or abrupt petrochemical feedstock disruption represent specific risk factors that could revise forecast trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Disposable Specimen Container Market
Medical Supplies
Compression Stockings Market
Medical Supplies
Global Post Surgery Bras Market
Medical Supplies
Casting and Splints Market
Medical Supplies
Crutch Pads Market
Medical Supplies
Single-Use Sterilization Wraps Market
Medical Supplies
Nucleic Acid Isolation and Purification Kits Market
Medical Supplies
Asia Pacific Industrial Gloves Market
Medical Supplies
Flexible Packaging for Healthcare Market
Medical Supplies
Global Contact Lens Solution Market
Medical Supplies
OTC Braces and Supports Market
Medical Supplies
Hospital Gowns Market
Medical Supplies
Disposable Bed Sheets Market
Medical Supplies
Healthcare Cleanroom Consumables Market
Medical Supplies
Hospital Consumables Market
Medical Supplies
Disposable Medical Gloves Market