
 Nucleic Acid Isolation and Purification Kits Market | 2026-2036
Nucleic Acid Isolation and Purification Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Nucleic Acid Isolation and Purification Kits Market Insights
A shortage of trained molecular biology technicians is reorganizing how laboratories evaluate kit procurement, pushing facilities toward pre-formulated, automation-compatible workflows. Thermo Fisher Scientific leverages its integrated instrument-reagent ecosystem to capture recurring consumable revenue from installed bases. QIAGEN N.V. sustains dominance in sample preparation through proprietary silica membrane chemistry and companion diagnostic partnerships. Promega Corporation specializes in flexible kit architectures that accommodate variable input volumes across research and applied markets.
Nucleic acid isolation and purification kits comprise buffered reagent systems designed to lyse cellular material, stabilize nucleic acids, and remove proteins and contaminants through phase separation or solid-phase binding. Magnetic bead-based technology leads the technology segment due to superior scalability and compatibility with robotic liquid handlers. RNA isolation kits represent the fastest-growing product type, driven by expanded transcriptomics research and mRNA vaccine quality control requirements. The genomic research application segment anchors volume demand, though clinical diagnostics commands premium pricing through regulatory-validated workflows.
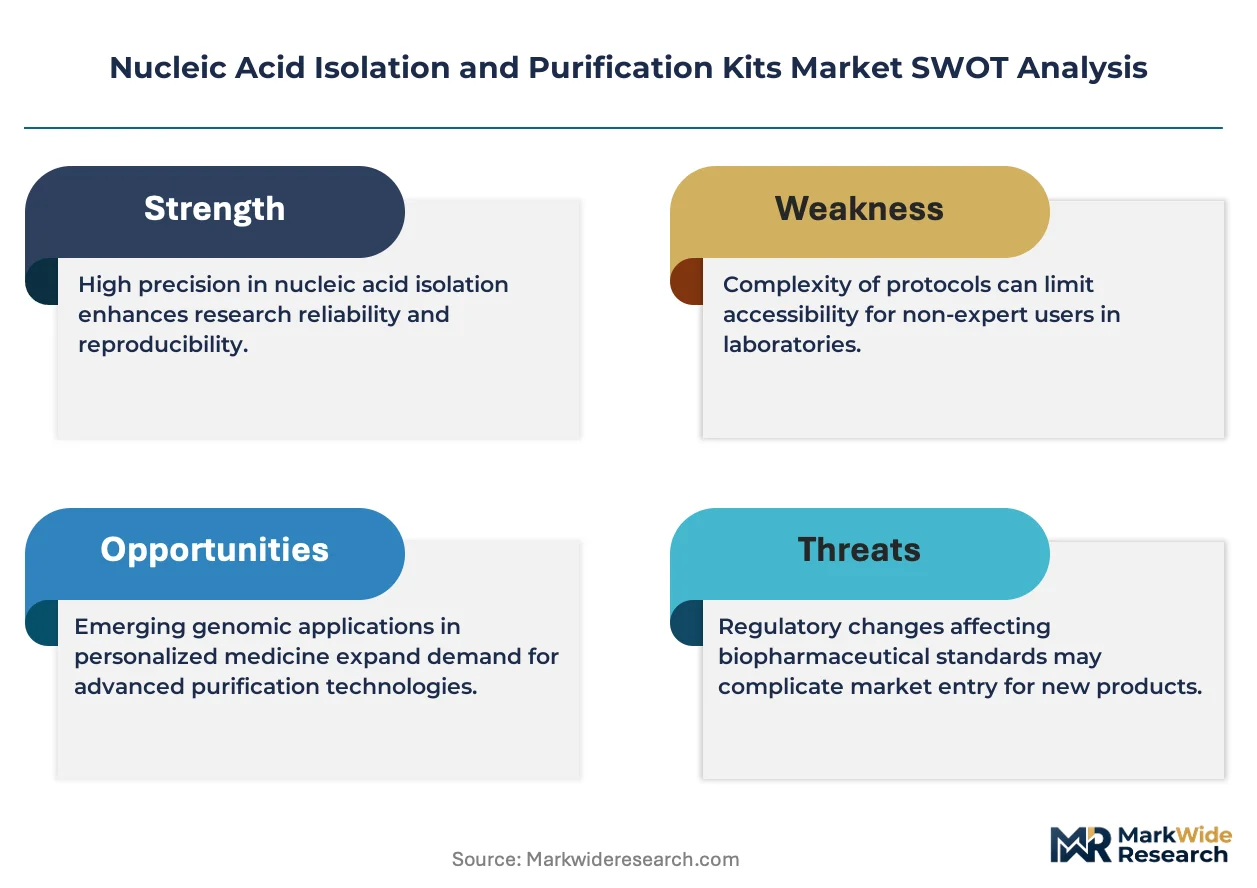
FDA oversight of laboratory-developed tests and companion diagnostics shapes kit validation requirements and manufacturing quality standards in the United States, while the EU In Vitro Diagnostic Regulation imposes stricter performance documentation and post-market surveillance obligations on kit suppliers serving European diagnostic laboratories. ISO 13485 quality management certification has become a baseline threshold for market access across major procurement channels. Stakeholders must monitor how evolving harmonization between FDA and EMA nucleic acid testing guidelines influences kit standardization and cross-border product registration strategies.
Market Dynamics
Magnetic bead-based extraction technology is compressing manual column workflows into automated platforms, forcing kit suppliers to restructure reagent formulations around robotic liquid handler compatibility rather than benchtop convenience.
Growth Catalysts
- EU In Vitro Diagnostic Regulation:Stricter performance documentation requirements are locking out unvalidated suppliers and consolidating procurement among ISO 13485-certified kit manufacturers serving European diagnostic laboratories.
- Transcriptomics research expansion:Academic and pharmaceutical RNA sequencing programs are driving volume demand for specialized RNA isolation kits with integrated DNase treatment protocols.
- China's infectious disease surveillance scaling:Provincial CDC networks are standardizing on automated nucleic acid extraction platforms for PCR-based pathogen detection workflows.
Market Restraints
- Reagent cost volatility:Magnetic bead raw material supply concentrates among specialty chemical suppliers in Germany and Japan, exposing kit margins to input price swings.
- Silica membrane technical ceiling:Column-based methods face hard throughput limits that prevent migration into clinical diagnostic high-volume settings regardless of price reduction.
- FDA laboratory-developed test oversight:Validation documentation burdens extend kit development timelines and raise capital requirements for US market entry.
Strategic Opportunities
- Point-of-care nucleic acid testing:Miniaturized extraction cartridges for decentralized infectious disease diagnostics represent underpenetrated white space outside centralized laboratory networks.
- mRNA vaccine quality control:Pharmaceutical manufacturers require specialized kits for residual DNA quantification and potency assay sample preparation.
- ISO 13485 certification arbitrage:Mid-tier suppliers can capture share from uncertified competitors by front-loading quality management investment ahead of EU MDR enforcement deadlines.
Industry Challenges
- Molecular biology technician scarcity:Pre-formulated, automation-compatible workflows must compensate for bench-level expertise gaps in clinical and research laboratories.
- Instrument-reagent ecosystem lock-in:Kit suppliers face integration complexity when attempting to displace entrenched platform vendors with standalone reagent offerings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nucleic Acid Isolation and Purification Kits Market |
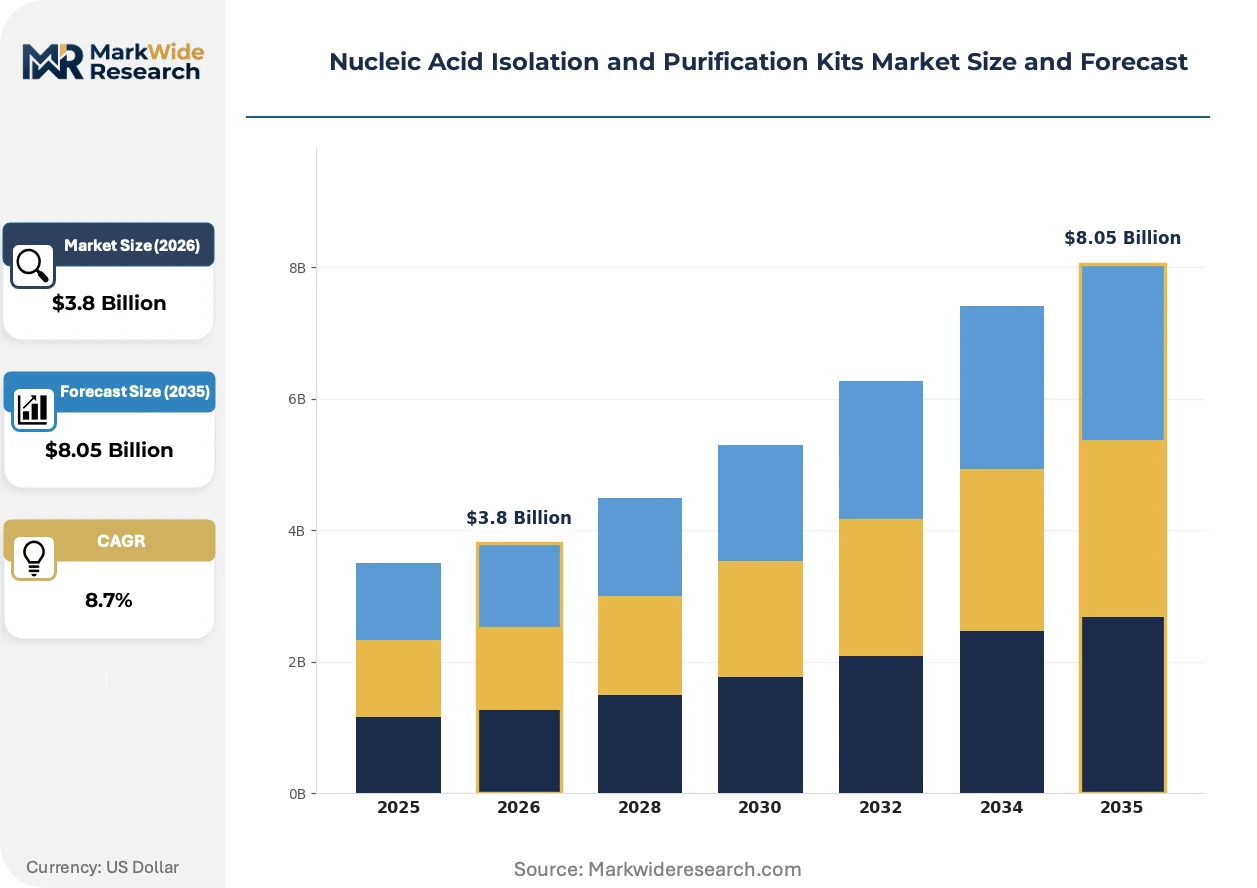
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Isolation Kits, RNA Isolation Kits, Plasmid Purification Kits, Nucleic Acid Extraction Kits Technology: Column-Based, Magnetic Bead-Based, Solid Phase Extraction, Liquid Phase Extraction End User: Research Laboratories, Academic Institutions, Diagnostic Laboratories, Pharmaceutical Companies Application: Genomic Research, Clinical Diagnostics, Drug Discovery, Forensic Analysis |
| Companies Covered | Thermo Fisher Scientific, Inc., QIAGEN N.V., Merck KGaA, Danaher Corporation, F. Hoffmann-La Roche Ltd, Agilent Technologies, Inc., Promega Corporation, Bio-Rad Laboratories, Inc., Takara Bio Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nucleic Acid Isolation and Purification Kits Market Trends and Innovations
Workflow integration pressures are compressing discrete extraction steps into unified instrument-reagent systems while regulatory documentation requirements reshape how kit suppliers structure validation data packages.
Microfluidic cartridge technology is miniaturizing nucleic acid extraction into single-use, closed-system devices. Point-of-care diagnostic manufacturers in the United States are adopting these platforms for decentralized infectious disease testing. This miniaturization is collapsing the boundary between sample collection and analytical preparation, enabling same-hour turnaround times previously restricted to centralized laboratories.
The EU In Vitro Diagnostic Regulation imposes stricter post-market surveillance obligations on kit suppliers serving European diagnostic laboratories. Manufacturers must maintain extended performance documentation and adverse event reporting systems that exceed prior CE-marking requirements. RNA isolation kits for companion diagnostic applications face the heaviest documentation burdens, pushing suppliers toward dedicated regulatory affairs staffing.
Consolidated procurement through group purchasing organizations is displacing direct kit sales to individual research laboratories. Academic medical centers in Germany and the United States are centralizing nucleic acid extraction reagent buying through integrated supply agreements. This channel compression favors kit suppliers with broad portfolio breadth and instrument platform partnerships over specialized niche providers.
Nucleic Acid Isolation and Purification Kits Market Segmentation
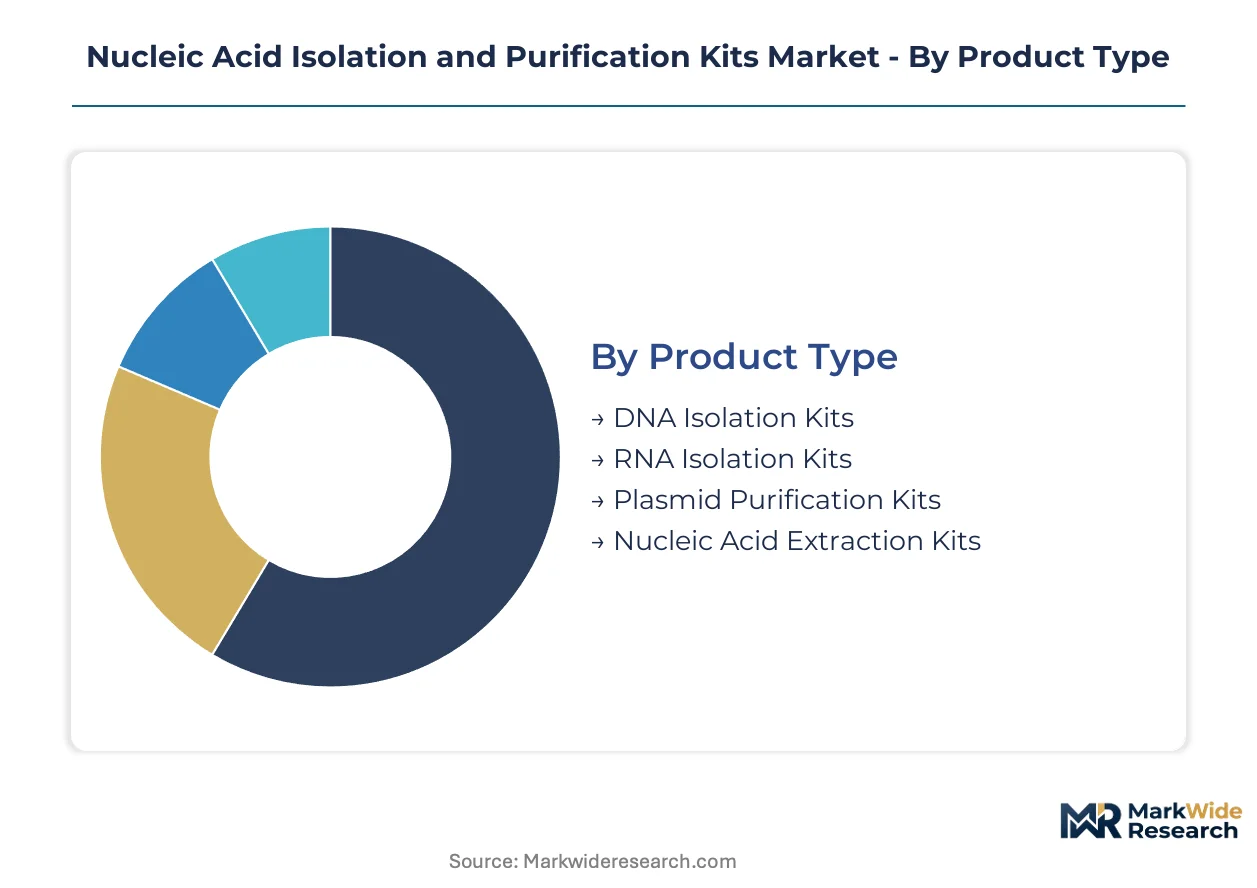
Kit procurement patterns diverge sharply across customer types, with research laboratories prioritizing flexibility while diagnostic facilities demand regulatory-validated workflows. Understanding these segment-specific channel dynamics enables suppliers to align formulation strategies with purchasing authority structures.
Product Type:
Channel mix varies by molecular target, with RNA isolation kits flowing predominantly through pharmaceutical direct accounts and DNA kits distributing heavily through academic supply aggregators.
- DNA Isolation Kits:Buffered reagent systems optimized for genomic DNA recovery from blood, tissue, and cell culture samples. Academic medical centers in Germany and the United States concentrate procurement through integrated supply agreements, driven by high-throughput sequencing infrastructure expansion.
- RNA Isolation Kits:Specialized formulations with integrated DNase protocols and stabilization chemistries for transcriptomics workflows. Pharmaceutical manufacturers in China and the United States drive demand through mRNA vaccine quality control requirements and companion diagnostic development programs.
- Plasmid Purification Kits:Endotoxin-free formulations for gene therapy vector production and molecular cloning applications.
- Nucleic Acid Extraction Kits:Universal chemistries accommodating variable input types for field-deployable and point-of-care settings.
DNA isolation kits dominate installed base across research infrastructure. RNA isolation kits are where expansion concentrates.
Technology:
Cost tier stratification separates premium automated platforms from economy manual workflows, with mid-tier hybrid systems capturing conversion demand.
- Magnetic Bead-Based:Paramagnetic particle chemistries enabling walk-away automation on robotic liquid handlers. High-throughput clinical diagnostic laboratories in the United States and China standardize procurement on these platforms, compelled by technician scarcity and throughput requirements.
- Column-Based:Silica membrane spin-column formats optimized for benchtop convenience and low sample throughput. Academic research laboratories in Germany retain significant installed base, constrained by capital budget limitations despite throughput ceilings.
- Solid Phase Extraction:Reversible binding matrices for specialized sample types including formalin-fixed tissue and environmental specimens.
- Liquid Phase Extraction:Traditional phenol-chloroform and trizol chemistries for cost-sensitive bulk processing applications.
Magnetic bead-based systems command premium positioning in clinical channels. Column-based formats retain economy-tier research penetration.
End User:
Application intensity varies by customer type, with pharmaceutical companies driving specialized kit customization and diagnostic laboratories prioritizing lot-to-lot consistency.
- Diagnostic Laboratories:ISO 13485-certified kit procurement for regulatory-validated PCR and sequencing workflows. FDA and EU MDR compliance documentation requirements shape vendor selection in the United States and European markets.
- Pharmaceutical Companies:GMP-grade kit specifications for bioprocess monitoring, cell line authentication, and release testing. mRNA vaccine manufacturers concentrate demand for residual DNA quantification protocols.
- Research Laboratories:Flexible format kits accommodating variable input volumes and sample types for exploratory genomics.
- Academic Institutions:Price-sensitive procurement through group purchasing organizations with emphasis on publication-grade reproducibility.
Diagnostic laboratories anchor premium pricing tiers. Pharmaceutical direct accounts are where specialized formulation growth concentrates.
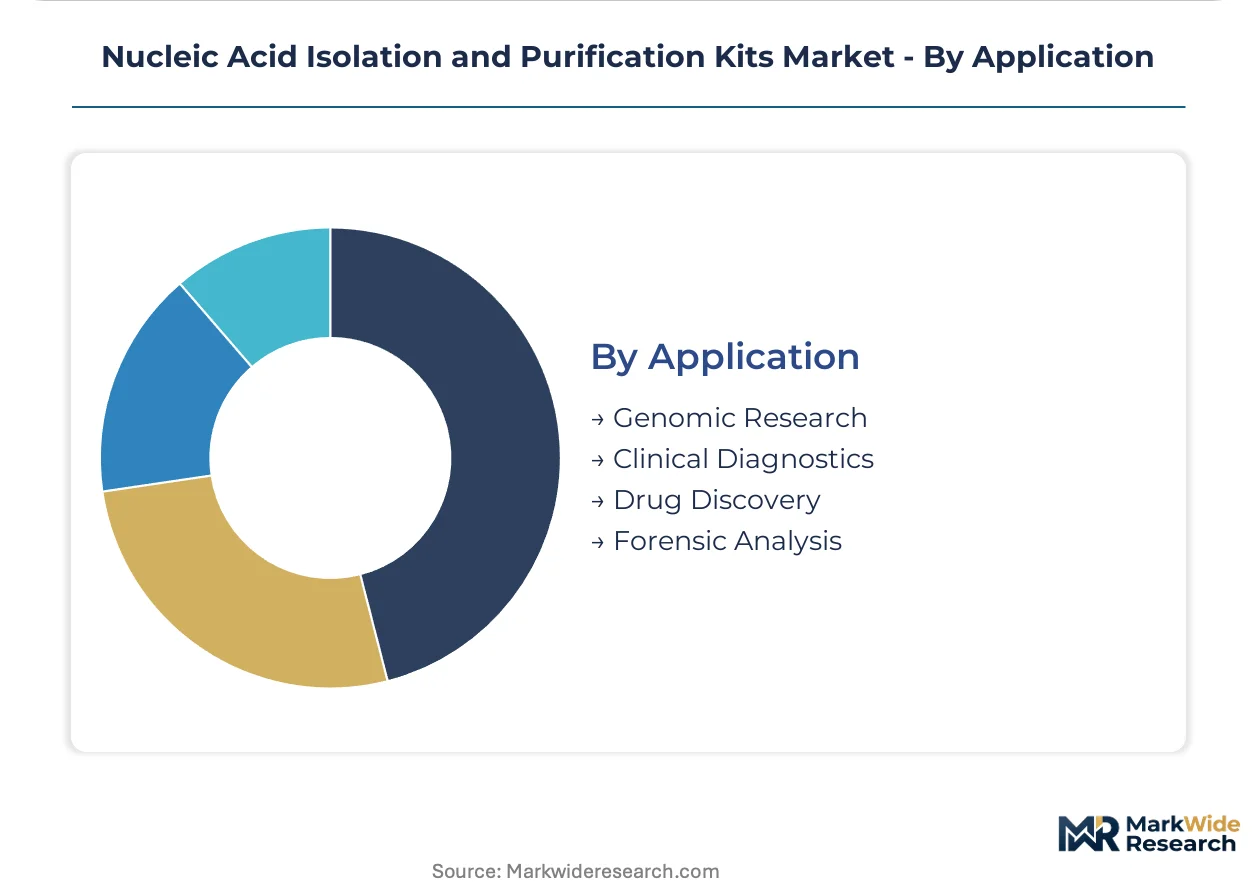
Application:
Volume-maturity segmentation separates established genomic research demand from emerging clinical diagnostic expansion trajectories.
- Clinical Diagnostics:Regulatory-validated extraction workflows for infectious disease surveillance, oncology profiling, and prenatal screening. China's provincial CDC networks and United States hospital systems scale automated platform deployment.
- Genomic Research:Discovery-phase nucleic acid preparation for population genomics, functional genomics, and epigenetic analysis. Academic consortia in Germany and the United States sustain baseline volume demand.
- Drug Discovery:High-complexity sample preparation for target validation, biomarker identification, and pharmacogenomic screening.
- Forensic Analysis:Specialized degradation-resistant chemistries for challenging sample types including bone, hair, and environmental DNA.
Genomic research commands volume leadership. Clinical diagnostics represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium kit pricing in the United States commands margins that German diagnostic laboratories resist through consolidated procurement, while Chinese provincial CDC networks scale automated platform deployment at intermediate price points.
United States
Hospital systems and reference laboratories drive automated magnetic bead-based platform adoption. FDA oversight of laboratory-developed tests and companion diagnostics shapes kit validation requirements and vendor selection criteria. The Greater Boston biotech cluster and San Francisco Bay Area anchor pharmaceutical direct account demand for specialized RNA isolation workflows.
Germany
Academic medical centers concentrate procurement through integrated supply agreements favoring broad portfolio suppliers. The EU In Vitro Diagnostic Regulation imposes stricter performance documentation and post-market surveillance obligations on kit manufacturers. The Munich and Heidelberg life science clusters sustain demand for high-throughput sequencing infrastructure and associated nucleic acid preparation reagents.
China
Provincial CDC networks standardize on automated extraction platforms for PCR-based pathogen detection workflows. NMPA regulatory pathways for in vitro diagnostic reagents influence kit registration timelines and clinical trial requirements. The Yangtze River Delta and Pearl River Delta manufacturing corridors concentrate domestic kit production capacity and pharmaceutical quality control demand.
Japan
Pharmaceutical manufacturers and academic consortia drive demand for GMP-grade and research-grade kit specifications. PMDA quality standards for diagnostic reagents shape import requirements and local partnership strategies. The Kanto region around Tokyo anchors centralized laboratory network procurement for infectious disease surveillance programs.
United Kingdom
Genomic research initiatives and NHS diagnostic transformation programs sustain dual-channel demand for research and clinical-grade kits. MHRA post-Brexit regulatory frameworks for in vitro diagnostics create parallel registration requirements alongside retained EU MDR alignment. The Cambridge and Oxford biotech corridor concentrates specialized kit demand for cell and gene therapy manufacturing.
Nucleic Acid Isolation and Purification Kits Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the nucleic acid isolation and purification kits market. Integrated instrument-reagent ecosystems dominate premium clinical diagnostic channels, while standalone reagent suppliers capture research laboratory flexibility requirements. Three archetypes define competitive positioning: platform-integrated conglomerates, specialized sample preparation pure-plays, and flexible-format research suppliers. M&A activity concentrates among mid-tier suppliers seeking ISO 13485 certification ahead of EU MDR enforcement, while strategic partnerships between kit manufacturers and robotic liquid handler vendors reshape channel access.
Within the platform-integrated tier, Thermo Fisher Scientific and QIAGEN N.V. represent archetypes of instrument-reagent ecosystem control, each anchoring distinct approaches to consumable revenue capture from installed bases. Promega Corporation exemplifies the flexible-format specialist archetype, occupying a position that accommodates variable input volumes across exploratory research and applied market segments without proprietary platform dependency.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc. |
| QIAGEN N.V. |
| Merck KGaA |
| Danaher Corporation |
| F. Hoffmann-La Roche Ltd |
| Agilent Technologies, Inc. |
| Promega Corporation |
| Bio-Rad Laboratories, Inc. |
| Takara Bio Inc. |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at German and Japanese specialty chemical suppliers directly shapes magnetic bead raw material availability and establishes price floors for kit manufacturers serving clinical diagnostic channels. Scale advantages in paramagnetic particle production concentrate pricing power among a narrow supplier base, while downstream kit vendors pass input volatility through to end users or absorb margin compression.
Pricing Analysis
The customization-premium spread separates GMP-grade pharmaceutical kits from standard research formulations. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification status and automation compatibility. Pricing pressure stems from consolidated procurement through group purchasing organizations in the United States and Germany. Academic institutions exhibit highest price sensitivity, while pharmaceutical quality control operations prioritize lot-to-lot consistency over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate research laboratory channels, whereas clinical diagnostic networks maintain strategic stockpiles of validated reagent lots. Magnetic bead raw material supply concentrates in Germany and Japan, with silica membrane substrates sourcing from United States and China. Single-source vulnerability in paramagnetic particle chemistry exposes kit margins to input disruption. Distribution runs through integrated supply agreements at academic medical centers and direct pharmaceutical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through group purchasing organization consolidation in the United States and Germany, fragmenting individual laboratory negotiating leverage while elevating volume-discount thresholds.
For Market Incumbents: Shield installed base revenue by deepening instrument-reagent ecosystem integration against standalone reagent competitors. Prioritize ISO 13485 certification maintenance ahead of EU MDR enforcement deadlines. Accelerate regulatory affairs staffing for RNA isolation kit documentation burdens in companion diagnostic applications. For New Entrants and Emerging Players: Differentiate on point-of-care miniaturization for decentralized infectious disease diagnostics outside centralized laboratory networks. Target pharmaceutical mRNA vaccine quality control segments with specialized residual DNA quantification protocols. Pursue robotic liquid handler vendor partnerships to bypass direct platform displacement challenges. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors mid-tier suppliers with front-loaded quality management investment and pending ISO 13485 certification. Long-term viability hinges on regulatory compliance infrastructure rather than formulation chemistry alone. Watch EU MDR harmonization progress with FDA nucleic acid testing guidelines as inflection indicator for cross-border registration scalability.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Acceleration | EU MDR enforcement locks out uncertified competitors from European diagnostic procurement channels. |
| Robotic Liquid Handler Partnership | Integration agreements with automation vendors secure recurring consumable revenue from installed bases. |
| Point-of-Care Cartridge Development | Miniaturized extraction platforms capture decentralized infectious disease testing outside hospital networks. |
| Companion Diagnostic Regulatory Staffing | Dedicated affairs teams manage RNA isolation kit documentation for oncology profiling applications. |
| Magnetic Bead Raw Material Hedging | Long-term supply agreements with German and Japanese specialty chemical suppliers stabilize input costs. |
Research Methodology
Initial hypotheses were tested against primary input from molecular biology laboratory directors, diagnostic procurement managers, pharmaceutical quality control leads, and regulatory affairs specialists at kit manufacturers and refined through secondary validation. Sources included FDA 510(k) filings, EU MDR technical documentation databases, hospital group purchasing organization contract disclosures, and SEC filings from publicly traded life science tools companies. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Variance decomposition across product type, technology platform, end-user category, and application intensity shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macro healthcare expenditure trends. Forecast inputs incorporated PCR-based pathogen detection workflow expansion rates and precision medicine program scaling trajectories in the United States, Germany, and China.
The analysis sits within stated boundaries; outcomes outside sustained infectious disease surveillance funding or automated platform adoption curves would require recalibration. Forecasts reflect documented assumptions regarding technician scarcity persistence and regulatory harmonization progress. Revision becomes warranted when EU MDR enforcement stringency or magnetic bead raw material supply disruption crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Healthcare Adhesive Tapes Market
Medical Supplies
Global Burn Ointment Market
Medical Supplies
Global Dried Blood Spot Collection Cards Market
Medical Supplies
Safety Needles Market
Medical Supplies
Disposable Bed Sheets Market
Medical Supplies
Combat Dressing Market
Medical Supplies
Unit Dose Tubes Market
Medical Supplies
Hemodialysis Consumables Market
Medical Supplies
Hemostasis Products Market
Medical Supplies
Sterile IV Containers Market
Medical Supplies
US Hospital Consumables Market
Medical Supplies
Continuous Ambulatory Peritoneal Dialysis Bags Market
Medical Supplies
Surgical Glue Market
Medical Supplies
Global Enema Based Products Market
Medical Supplies
Prepackaged Medical Kits and Trays Market
Medical Supplies
Latex Medical Disposables Market