
 Hospital Consumables Market | 2026-2036
Hospital Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Hospital Consumables Market Intelligence
EU MDR is shifting the cost-of-entry calculus for manufacturers seeking European market access, forcing recertification of legacy product lines under stricter clinical evidence requirements. Medtronic Plc leverages its vertically integrated manufacturing footprint to absorb these compliance costs without margin erosion. B Braun SE anchors its competitive position through specialized production of infusion and injection consumables with German-engineered precision standards. Cardinal Health competes aggressively on distribution density, controlling hospital supply chain logistics across North American metropolitan networks.
Hospital consumables encompass single-use and limited-use medical products manufactured from polymers, non-woven fabrics, latex or nitrile, and sterilized packaging materials, designed to prevent cross-contamination and streamline clinical workflows. These items undergo gamma irradiation or ethylene oxide sterilization and must meet biocompatibility standards under ISO 10993 to ensure patient safety during invasive or diagnostic procedures. Surgical supplies represent the most mature revenue pool with stable replacement demand, while diagnostic products capture accelerating growth from point-of-care testing expansion in outpatient settings. Disposable gloves face margin compression from raw material volatility, whereas infusion devices concentrate value through smart-pump connectivity and medication safety software integration.
FDA sterility assurance levels and EU MDR clinical evaluation requirements shape product development timelines and capital allocation for manufacturers serving Western markets. BIS certification in India and NMPA registration in China add parallel compliance layers for companies pursuing volume opportunities in Asia's fastest-expanding hospital networks. Procurement teams must weigh total cost of ownership against regulatory risk when qualifying second-source suppliers across geographically dispersed manufacturing footprints.
Market Dynamics
Single-use diagnostic kit demand in tertiary emergency departments is compressing sterilization validation timelines while FDA sterility assurance guidelines recalibrate cost structures for domestic manufacturers.
Growth Catalysts
- Aging surgical demographics:Elevated throughput of disposable medical supplies in United States hospitals sustains replacement demand across procedure categories.
- EU MDR recertification:Stricter clinical evidence requirements for legacy product lines create compliance-driven procurement windows for qualified suppliers.
- Point-of-care expansion:Outpatient diagnostic testing growth accelerates kit consumption in ambulatory surgical centers and urgent care networks.
Market Restraints
- Raw material volatility:Nitrile and latex price swings compress margin structures for disposable glove manufacturers without captive polymer supply.
- Supply concentration risk:Gamma irradiation and ethylene oxide sterilization capacity clusters in limited geographic zones, creating single-point failure exposure.
- Regulatory friction:Parallel BIS certification in India and NMPA registration in China extend product launch timelines for Western manufacturers.
Strategic Opportunities
- Smart-pump connectivity:Medication safety software integration in infusion devices captures premium pricing through error-reduction validation.
- Vertically integrated manufacturing:In-house production of sterilized packaging materials and polymer conversion insulates margin from input cost cycles.
- ISO 10993 biocompatibility specialization:Advanced testing capabilities open access to implantable and invasive procedure consumables with higher certification barriers.
Industry Challenges
- Sterilization validation backlog:Ethylene oxide residual testing and gamma dose mapping create bottlenecks in new product commercialization.
- Legacy ERP integration:Hospital supply chain systems resist real-time inventory tracking for serialized disposable devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospital Consumables Market |
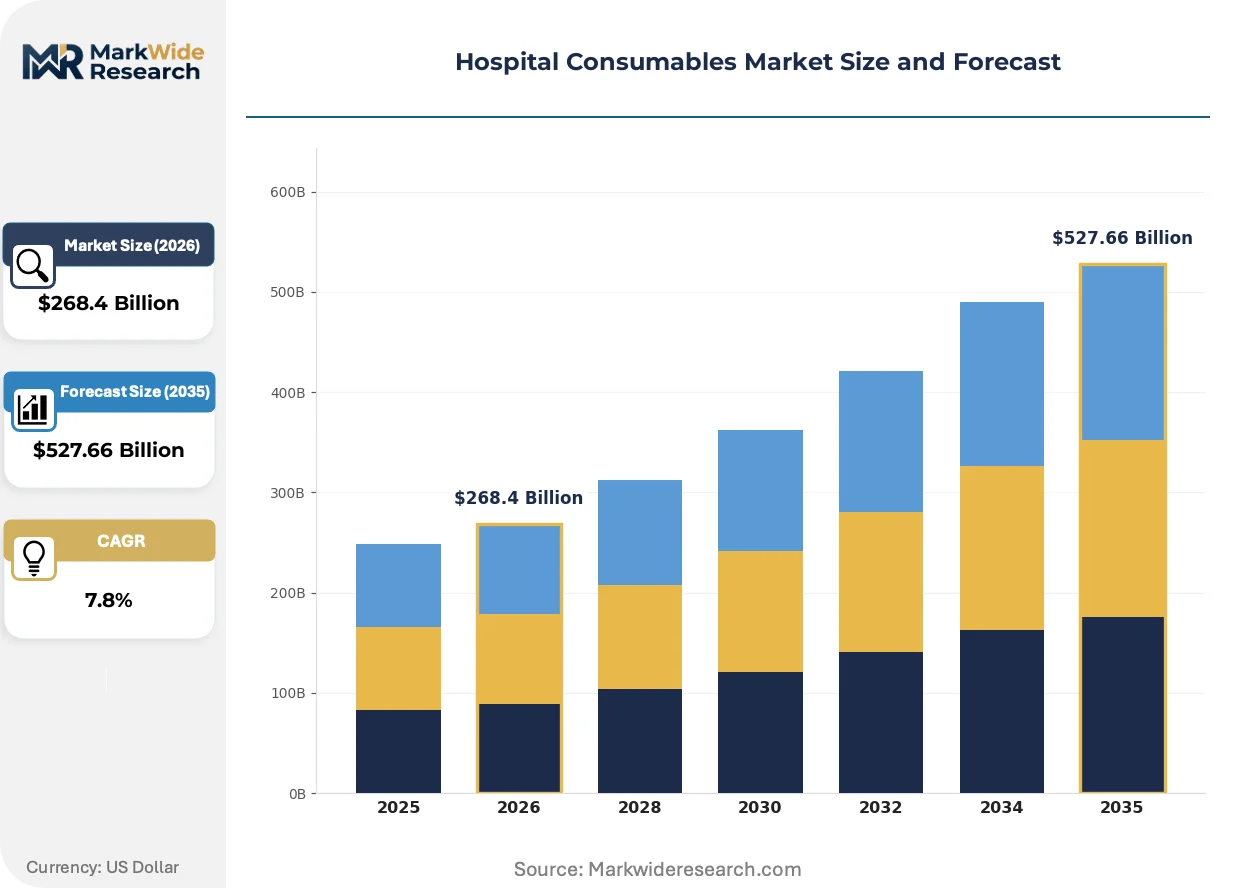
| Market Size in 2026 | $268.4 Billion |
| Market Size in 2035 | $527.66 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Supplies, Diagnostic Products, Disposable Gloves, Infusion Devices Application: Emergency Care, Surgical Procedures, Patient Monitoring, Rehabilitation End User: Hospitals, Clinics, Outpatient Facilities, Laboratories Delivery Mode: Bulk Supply, Individual Packs, On-Demand Service, Automated Dispensing |
| Companies Covered | Medtronic Plc, B Braun SE, Cardinal Health, 3M, Johnson & Johnson, Medline Industries, Baxter International, Becton Dickinson, Smith & Nephew, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospital Consumables Market Strategic Shifts & Innovations
Workflow compression in emergency and surgical settings is driving modularity in consumable design, with connectivity features and sterilization methods evolving in parallel.
Pre-sterilized procedure kits containing drapes, gowns, and instrument covers are modularizing operating room preparation protocols. Tertiary hospitals in high-throughput metropolitan markets are adopting these integrated bundles to reduce turnover time between cases. This consolidation is modularizing supplier relationships while compressing the vendor base for individual component categories.
EU MDR clinical evaluation requirements are extending technical documentation obligations for legacy consumable lines. Manufacturers must now generate clinical evidence or equivalence justifications for products previously cleared under simpler conformity paths. Surgical sutures and wound closure devices face the steepest compliance burden, with notified body capacity constraints stretching recertification timelines.
Hospital supply chain teams are consolidating purchase orders through distribution partners with metropolitan density. Cardinal Health and regional equivalents are capturing larger share-of-wallet by integrating logistics, consignment inventory, and usage analytics. This concentration is most visible in United States urban hospital networks where procurement departments prioritize total cost-of-ownership over unit pricing.
Hospital Consumables Market Segmentation
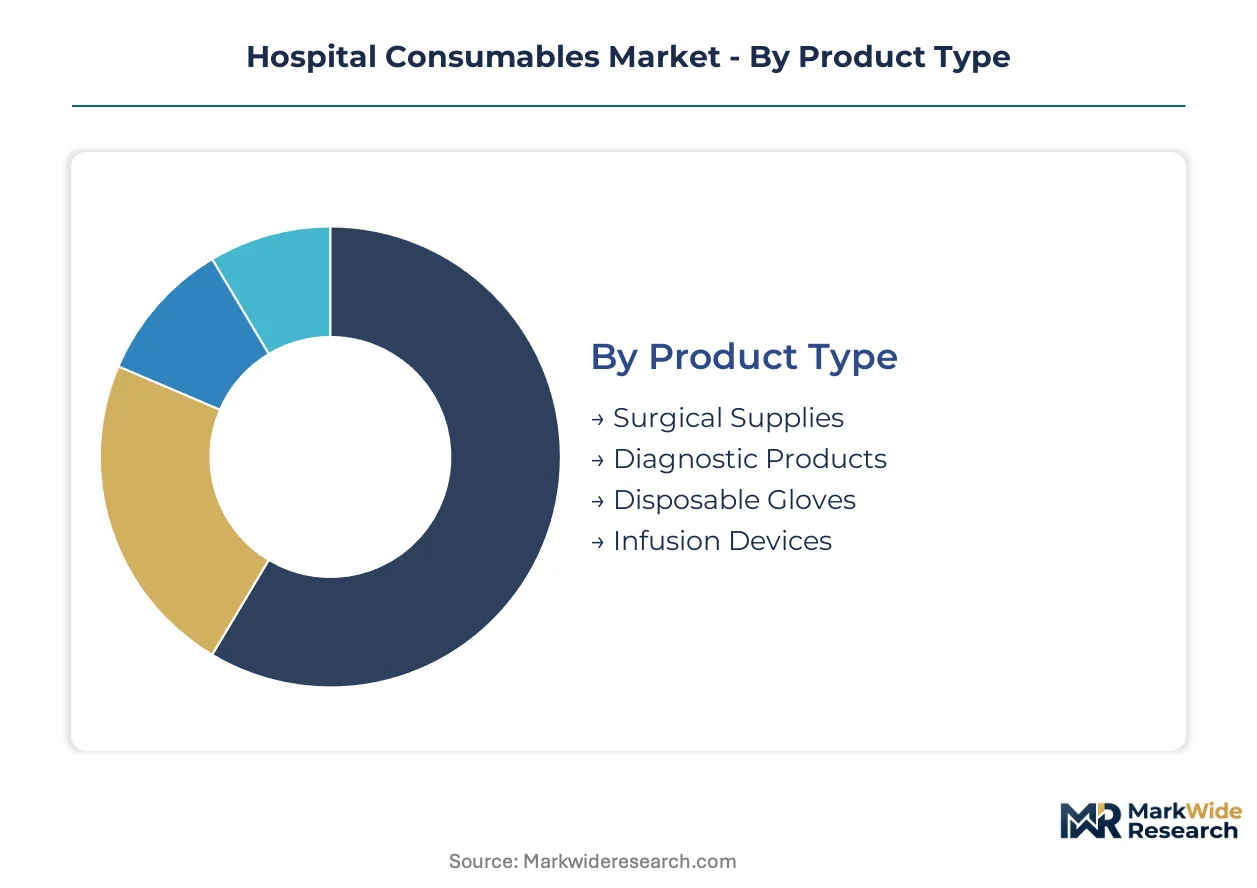
Hospital consumables segmentation reveals divergent capital requirements across product categories, with sterilization infrastructure and regulatory compliance creating tiered barriers to entry. Application-specific demand patterns reshape procurement priorities, while end-user concentration determines distribution economics and service models.
Product Type:
Surgical supplies and infusion devices demand the heaviest upfront investment in gamma irradiation chambers, ethylene oxide sterilization suites, and ISO 10993 biocompatibility testing laboratories.
- Surgical Supplies:Sutures, drapes, gowns, and wound closure devices manufactured from non-woven fabrics and polymer meshes undergo ethylene oxide or gamma sterilization. Tertiary hospitals in the United States sustain replacement demand through elevated procedural throughput across orthopedic and cardiovascular specialties.
- Diagnostic Products:Single-use test kits, specimen collection containers, and point-of-care consumables incorporate sterile packaging and reagent stabilization chemistries. Emergency departments in metropolitan hospital networks are compressing sterilization validation timelines while expanding kit procurement volumes.
- Disposable Gloves:Nitrile and latex examination gloves produced via dip-molding lines with chlorination or polymer coating treatments for donning ease.
- Infusion Devices:IV catheters, administration sets, and smart-pump disposables requiring precision extrusion and medication safety software integration.
Surgical supplies absorb the bulk of installed sterilization capacity; diagnostic products are expanding most quickly.
Application:
Emergency care and surgical procedures concentrate the highest-value consumable consumption, with patient monitoring and rehabilitation representing lower-unit-cost, higher-frequency replacement cycles.
- Emergency Care:Trauma kits, airway management consumables, and rapid diagnostic strips deployed in high-throughput tertiary emergency departments. United States urban hospital networks are driving demand for pre-sterilized procedure bundles that compress turnover protocols.
- Surgical Procedures:Sterile drapes, instrument covers, and wound closure systems organized into modular kits for operating room efficiency. EU MDR recertification requirements are extending compliance timelines for legacy suture lines across European hospital procurement cycles.
- Patient Monitoring:Electrode pads, pulse oximeter probes, and temperature sensors requiring biocompatible adhesives and signal reliability.
- Rehabilitation:Disposable resistance bands, therapeutic putty containers, and hygiene covers for continuous passive motion devices.
Surgical procedures command the highest procurement budgets; emergency care is climbing the fastest as point-of-care testing expands.
End User:
Hospitals and outpatient facilities present contrasting procurement profiles, with volume consolidation versus decentralized purchasing authority reshaping supplier relationships.
- Hospitals:Integrated delivery networks negotiating enterprise-wide contracts for sterilized consumables across inpatient and ambulatory settings. Cardinal Health and regional distributors are capturing metropolitan density through consignment inventory and usage analytics integration.
- Clinics:Physician-owned practices and specialty centers prioritizing unit cost over total cost of ownership in lower-throughput environments.
- Outpatient Facilities:Ambulatory surgical centers and urgent care networks demanding modular procedure kits with compressed sterilization validation documentation.
- Laboratories:Reference labs and hospital-based pathology units consuming specimen containers, pipette tips, and reagent vessels in high-throughput automated workflows.
Hospitals dominate absolute procurement volume; outpatient facilities are gaining share fastest as surgical migration accelerates.
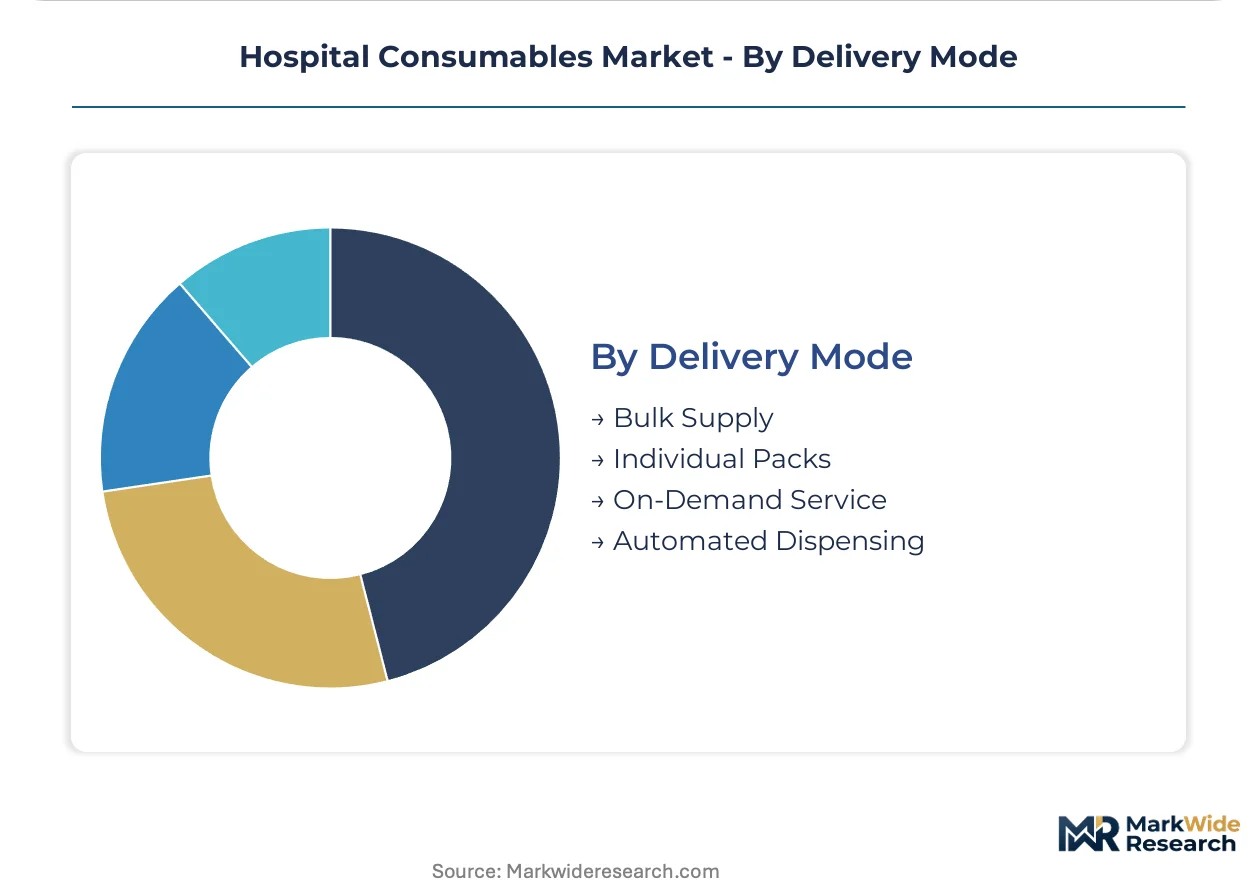
Delivery Mode:
Bulk supply and automated dispensing represent opposing capital strategies, with warehouse infrastructure versus cabinet hardware creating distinct competitive moats.
- Bulk Supply:Palletized shipments of non-sterile or terminally sterilized consumables to hospital central supply warehouses requiring climate-controlled storage and lot-tracking systems.
- Individual Packs:Unit-of-use packaging for point-of-care accessibility, common in emergency departments and operating rooms where workflow speed dominates.
- On-Demand Service:Direct-to-department restocking with usage-based billing, prevalent in cardiac catheterization labs and interventional radiology suites where consumption variability is high.
- Automated Dispensing:Pyxis and equivalent cabinet systems with RFID tracking and par-level replenishment algorithms, concentrated in United States academic medical centers pursuing inventory optimization.
Bulk supply retains the largest shipment volume; automated dispensing is expanding most quickly as health systems pursue working capital reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device special economic zones in Costa Rica and Malaysia concentrate sterilization services and polymer conversion for North American and European hospital networks. These tax-advantaged manufacturing clusters absorb compliance costs for FDA and EU MDR certification while serving as export hubs to major hospital procurement markets.
United States
Tertiary hospital networks in metropolitan markets sustain elevated surgical throughput across orthopedic and cardiovascular specialties. FDA sterility assurance guidelines elevate domestic manufacturing compliance costs while compressing validation timelines for single-use diagnostic kits. The Minneapolis medical technology corridor anchors precision extrusion capabilities for infusion device components.
Germany
EU MDR recertification requirements extend technical documentation obligations for legacy suture and wound closure product lines. B Braun SE maintains specialized production of infusion consumables with precision-engineered manufacturing standards. The Baden-Württemberg industrial cluster concentrates ethylene oxide sterilization capacity for European hospital supply chains.
China
NMPA registration timelines extend product commercialization cycles for Western manufacturers targeting domestic hospital procurement. Shanghai and Suzhou medical device parks concentrate gamma irradiation infrastructure for polymer-based consumable sterilization. The Yangtze River Delta absorbs nitrile and latex polymer conversion for examination glove production.
India
BIS certification requirements create parallel compliance layers for manufacturers accessing government hospital procurement programs. Maharashtra and Gujarat medical device manufacturing zones cluster dip-molding lines for disposable glove production. The Delhi-NCR corridor concentrates diagnostic kit assembly for South Asian hospital networks.
Japan
PMDA quality management system inspections enforce rigorous biocompatibility documentation for implantable consumables. The Kansai region around Osaka maintains specialized polymer processing for surgical suture and wound closure devices. Tokyo metropolitan hospitals drive demand for smart-pump connectivity in infusion therapy consumables.
Hospital Consumables Market Key Industry Players
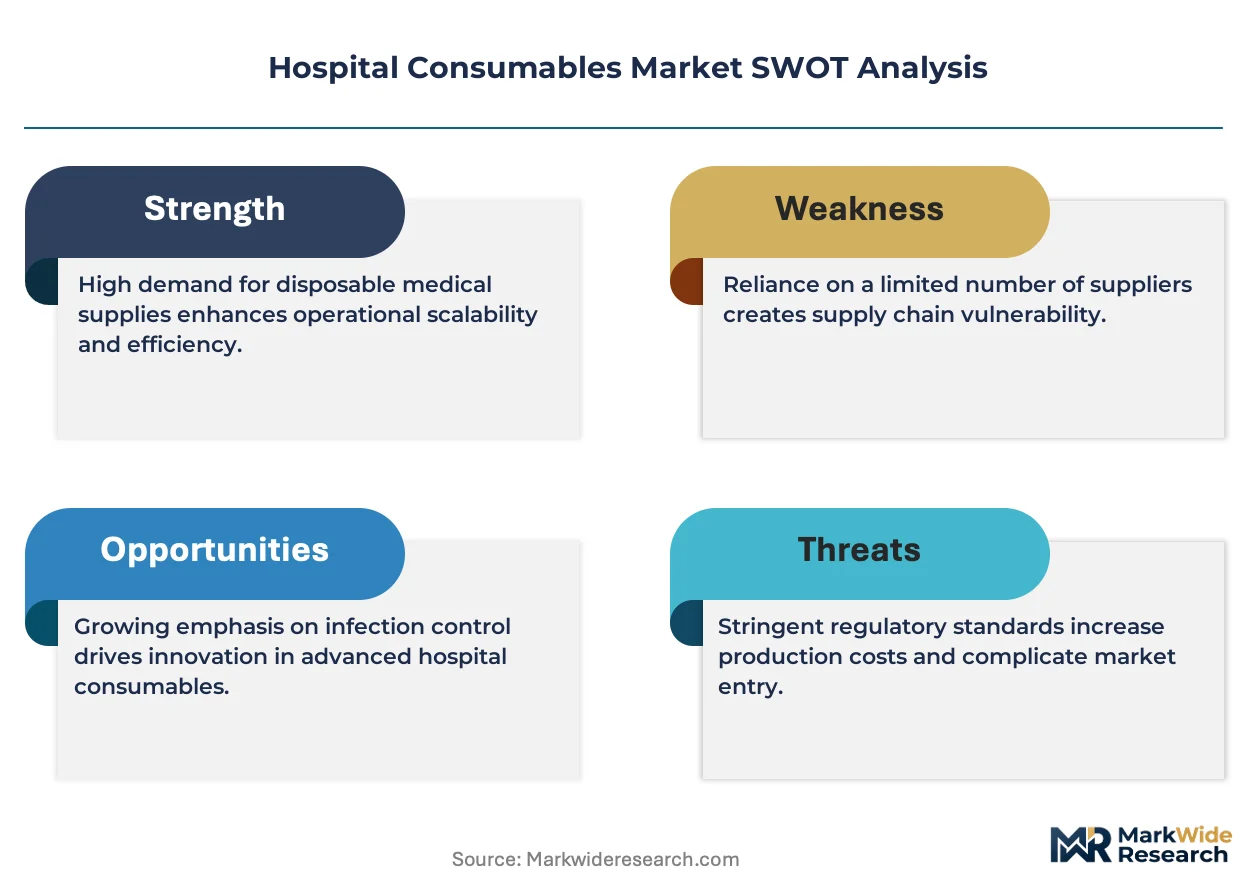
Diversified conglomerates compete with focused pure-play specialists across sterilized consumable categories, creating a tiered market structure with distinct capability requirements. Three archetypes dominate: vertically integrated manufacturers with captive polymer supply and sterilization infrastructure; distribution-heavy intermediaries controlling metropolitan hospital logistics networks; and specialized precision fabricators concentrating on ISO 10993-certified invasive procedure consumables. M&A activity concentrates sterilization capacity and polymer conversion assets, while strategic partnerships between distributors and manufacturers consolidate vendor relationships within integrated delivery networks.
Among diversified healthcare conglomerates, Medtronic Plc and Johnson & Johnson occupy positions spanning surgical supplies, diagnostic consumables, and infusion therapy devices. B Braun SE exemplifies the precision-specialist archetype with concentrated capabilities in infusion and injection consumables. Cardinal Health represents the distribution-anchored model, controlling hospital supply chain logistics across North American metropolitan networks through consignment inventory and usage analytics integration.
| Leading Market Players |
|---|
| Medtronic Plc |
| B Braun SE |
| Cardinal Health |
| 3M |
| Johnson & Johnson |
| Medline Industries |
| Baxter International |
| Becton Dickinson |
| Smith & Nephew |
| Others |
Cost & Logistics Intelligence
Gamma irradiation and ethylene oxide sterilization capacity concentration in Costa Rica and Malaysia medical device zones compresses cost economics while elevating pricing power for integrated manufacturers with captive sterilization infrastructure. FDA sterility assurance guideline updates simultaneously extend validation timelines and recalibrate procurement premiums for suppliers with redundant sterilization footprints.
Pricing Analysis
Short lead-time premiums for emergency department diagnostic kits command substantial markups over standard procurement cycles, while spot inventory liquidation creates discount windows for bulk purchasers with flexible demand timing. Contract-based long-term offtake agreements dominate hospital system procurement, with price differentiation driven by ISO 10993 certification tier and volume scale. Cost compression in disposable glove segments intensifies due to nitrile and latex raw material volatility. Clinics and physician-owned practices exhibit highest price sensitivity; tertiary hospitals with enterprise contracts prioritize total cost-of-ownership over unit pricing.
Supply Chain Analysis
Direct-to-hospital channels handle metropolitan integrated delivery network demand through consignment inventory models, while regional distributors serve decentralized outpatient facilities. Manufacturing concentrates in Costa Rica, Malaysia, and China medical device special economic zones. Supply chains draw from nitrile and latex polymer feedstocks, gamma irradiation chambers, and ethylene oxide sterilization suites. Single-source vulnerability in ethylene oxide residual testing capacity creates bottleneck exposure. Distribution runs through Cardinal Health and regional equivalents controlling North American metropolitan logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR recertification requirements are forcing consolidation among manufacturers lacking clinical evidence generation capabilities, eliminating marginal players from European hospital procurement cycles.
For Market Incumbents: Deploy backward integration into sterilized packaging materials to insulate margin from polymer cost cycles and absorb FDA compliance cost escalations without pricing erosion. Capture notified body capacity constraints as a defensive moat by accelerating legacy suture line recertification ahead of competitor submission backlogs. Threat: Emerging pure-play diagnostic kit specialists with modular manufacturing footprints and compressed validation timelines. For New Entrants and Emerging Players: The premium-to-economy pricing gap in smart-pump connectivity modules creates entry space for software-integrated infusion device specialists targeting ambulatory surgical center procurement. White-space concentrates in urgent care network diagnostic kit supply, where sterilization documentation compression meets elevated throughput demand. Go-to-market angle: ISO 10993 biocompatibility specialization for invasive procedure consumables with certification barriers that deter commodity competitors. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified healthcare conglomerates seeking sterilization capacity and polymer conversion assets. Long-term viability favors vertically integrated manufacturers with captive gamma irradiation infrastructure and metropolitan distribution density. Target archetype: Mid-cap specialists with EU MDR recertification progress and hospital system contract anchoring. Signal to watch: Notified body capacity expansion announcements as inflection indicator for recertification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Acceleration | Notified body queue positioning determines European hospital contract renewal timing for legacy suture lines. |
| Backward Integration into Sterilization | Captive ethylene oxide and gamma irradiation capacity insulates margin from third-party validation bottlenecks. |
| Smart-Pump Software Companion Development | Medication safety algorithm integration captures premium pricing through error-reduction validation in infusion therapy. |
| Hospital System Partnership Consolidation | Enterprise-wide GPO contracts with consignment inventory terms lock out secondary suppliers in metropolitan networks. |
| ISO 10993 Biocompatibility Certification Investment | Advanced testing capabilities open implantable and invasive procedure segments with elevated certification barriers. |
Research Approach
Multi-period observation of FDA 510(k) submission volumes, EU MDR notified body designation expansions, and hospital procurement database trends anchored the trend analysis, supplemented by interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, sterilization validation specialists, and polymer conversion plant managers. Secondary validation drew from FDA 510(k) filings, EUDAMED registration data, hospital supply chain procurement records, and SEC 10-K disclosures of listed medical device manufacturers. Bottom-up product-line revenue builds triangulated against top-down hospital expenditure estimates across the analysis window.
Input-output matrices mapped sterilization capacity utilization, polymer feedstock pricing, and regulatory compliance cost trajectories to segment-level revenue projections throughout the forecast period. Segmentation dimensions modeled encompass product type, application, end user, and delivery mode, with regional regulatory cluster as an additional cross-cutting variable. CAGRs were derived from trend extrapolation of historical throughput data and elasticity-adjusted demand response to pricing shifts. Industry-specific forecast inputs include surgical procedure volume trajectories by specialty and point-of-care testing expansion rates in outpatient settings.
Inputs from FDA submission databases and EU MDR notified body capacity reports were available through the study window; gaps in real-time hospital inventory consumption data introduce uncertainty bands around short-term demand volatility estimates. Forecasts reflect assumptions regarding sterilization validation timeline normalization and polymer supply chain stabilization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Blood Bags Market
Medical Supplies
Emergency Transfer Vacuum Mattress Market
Medical Supplies
Sterile Container Market
Medical Supplies
Dehydrated Culture Media Market
Medical Supplies
Antibacterial Haemostatic Gels Market
Medical Supplies
Latin America Incontinence Pads Market
Medical Supplies
Anesthesia Disposables Market
Medical Supplies
Retractable Needle Safety Syringes Market
Medical Supplies
Forensic Swabs Market
Medical Supplies
Pharmacy Accessory Bagging System (PABS) Market
Medical Supplies
Europe Sharps Containers Market
Medical Supplies
North America Insulin Syringe Market
Medical Supplies
GCC Intravenous Solutions Market
Medical Supplies
Single-Use Syringe Market
Medical Supplies
Casting and Splinting Market
Medical Supplies
Western Europe Sterile Gloves Market