
 Microdebrider Market | 2026-2036
Microdebrider Market Size, Share, and Industry Trends Forecast 2026-2036
Microdebrider Market Insights
Hospital procurement channels for microdebrider systems is fragmenting as ambulatory surgical centers gain direct purchasing autonomy and group purchasing organizations lose exclusive contracts. Medtronic leverages its integrated ENT navigation portfolio to sustain premium placement in academic medical centers. Smith & Nephew competes through specialized powered instrument kits tailored to office-based sinus procedures.
A microdebrider is a powered surgical instrument employing a rotating or oscillating blade within a suction cannula to precisely resect soft tissue and bone, typically operating at 5,000 to 12,000 RPM with integrated irrigation and aspiration ports. Electric technology dominates the installed base while pneumatic systems retain preference in cost-sensitive markets requiring lower capital outlay. Single-use microdebrider tips capture expanding margin pools as sterilization liability and FDA reprocessing validation costs erode reusable economics in high-volume settings.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and market access barriers for new entrants. ISO 13485 quality management systems and IEC 60601 electrical safety standards govern manufacturing compliance across all commercialized devices. Stakeholders must monitor reimbursement parity between inpatient and ambulatory settings as site-of-service shifts redefine volume allocation and pricing power.
Market Dynamics
The microdebrider market is restructuring around single-use platform economics as FDA sterilization validation requirements for reusable devices escalate compliance burdens beyond the break-even threshold for high-volume surgical centers.
Growth Catalysts
- Ambulatory Surgical Center Expansion:United States outpatient facility construction is accelerating sinus procedure volumes outside traditional hospital settings. These centers prioritize capital-efficient, disposable instrument platforms that minimize reprocessing infrastructure.
- EU MDR Technical Documentation:Stricter conformity assessment pathways for reusable powered instruments are compressing approval timelines for single-use alternatives. Manufacturers are redirecting R&D toward disposable tip architectures that bypass revalidation cycles.
- Navigation System Integration:Image-guided surgical platforms are hybridizing with powered instrumentation. ENT surgeons in academic medical centers are demanding microdebriders with embedded tracking capabilities for skull-base approaches.
Market Restraints
- Stainless Steel Supply Concentration:Precision-machined blade substrates depend on German and Japanese specialty metallurgy suppliers. Geopolitical friction and energy cost volatility in European manufacturing clusters are compressing margin structures for reusable instrument producers.
- Pneumatic System Lock-In:Cost-sensitive hospital systems in India and Brazil retain installed bases of compressed-air powered microdebriders. Capital replacement cycles for electric platforms extend beyond seven years in these markets.
- Manual Instrument Substitution:Low-complexity polypectomy and limited ethmoidectomy procedures in resource-constrained settings continue employing non-powered forceps and through-cutting instruments. These manual alternatives eliminate capital equipment requirements entirely.
Strategic Opportunities
- Office-Based Rhinology:United States otolaryngology practices are procuring compact, lower-RPM microdebriders for in-office balloon sinuplasty and polypectomy. These procedures bypass facility fees and capture margin directly from commercial payers.
- Japan's Aging ENT Specialist Pool:PMDA fast-track pathways for ergonomic, single-hand-operable instruments address workforce constraints. Lightweight disposable handpieces reduce procedural fatigue in extended skull-base cases.
- Battery-Powered Portability:Lithium-ion cell density improvements are enabling cordless microdebrider platforms. These systems penetrate military field hospitals and humanitarian surgical missions where compressed air and electrical infrastructure are unreliable.
Industry Challenges
- Biocompatibility Testing Bottlenecks:ISO 10993 cytotoxicity and sensitization studies for novel polymer handpiece materials extend validation timelines by 8-14 months. Contract research organization capacity constraints in North America and Europe are compressing product launch windows.
- OR Integration Complexity:Microdebrider suction and irrigation ports require standardized connections to existing surgical boom configurations. Legacy equipment from competing manufacturers employs proprietary coupling systems that fragment interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microdebrider Market |
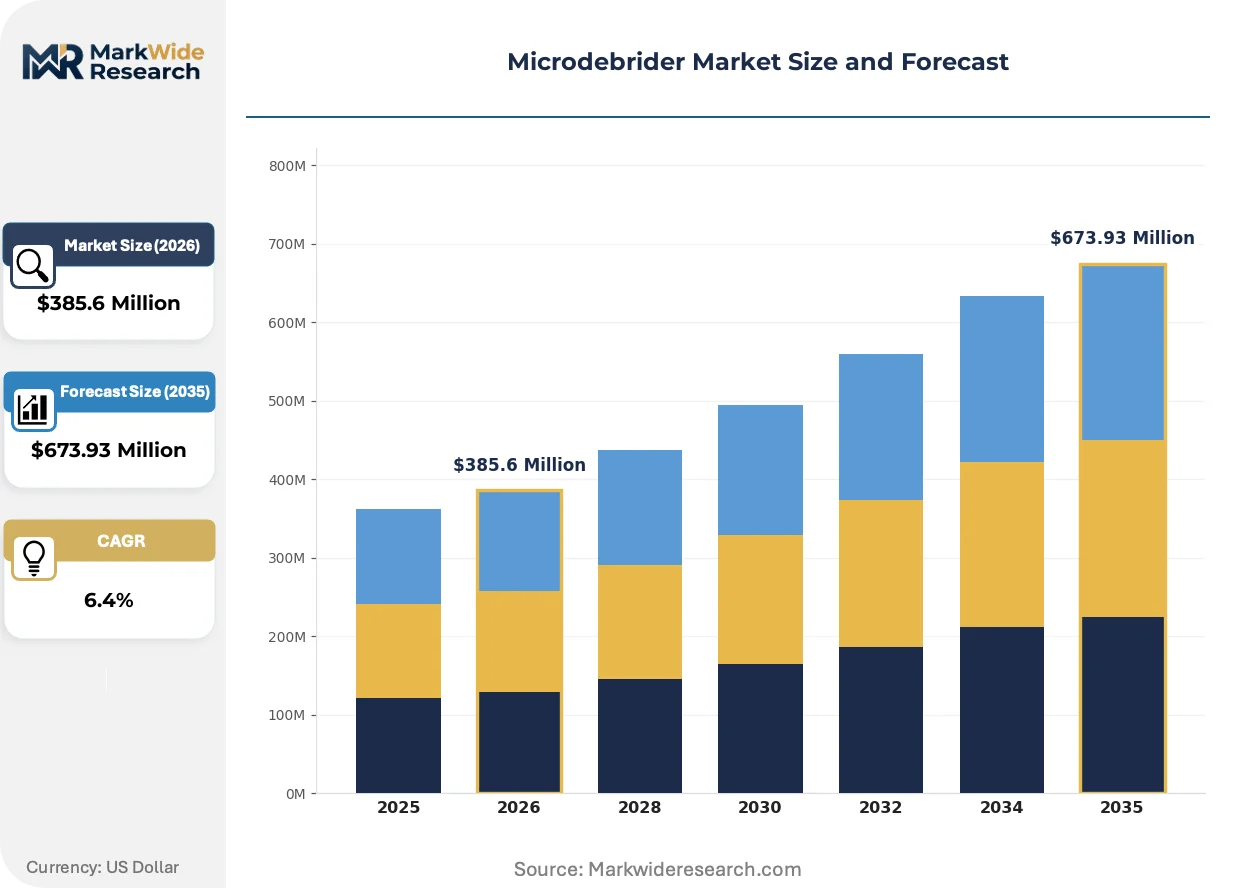
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-use, Reusable, Powered, Manual Technology: Electric, Pneumatic, Mechanical, Laser Application: Otolaryngology, Neurosurgery, Dental Surgery, Plastic Surgery End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Facilities |
| Companies Covered | KARL STORZ, CONMED Corporation, Medtronic, Richard Wolf GmbH, Arthrex, Stryker, Smith & Nephew, B. Braun, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microdebrider Market Trends and Innovations
Powered ENT instrumentation is converging with disposable platform economics and digital surgical navigation, compressing the traditional boundary between capital equipment and consumable supply chains.
Curved and angled microdebrider tips with integrated suction control are hybridizing across the installed base. These instruments enable access to the frontal sinus recess and sphenoid roof without supplementary manual instruments. Academic medical centers in Germany and the United States are standardizing on 70-degree and 90-degree configurations for endoscopic skull-base approaches. The technology is hybridizing procedure workflows by collapsing multi-instrument exchanges into single-device continuity.
FDA 510(k) substantial equivalence pathways are narrowing for reusable powered surgical instruments with modified reprocessing instructions. The agency's 2021 guidance on sterilization validation for complex device geometries has extended clearance timelines by requiring additional bioburden and endotoxin data. Single-use microdebrider tips with pre-validated sterile packaging are capturing preference among manufacturers seeking predictable regulatory trajectories.
Ambulatory surgical centers are consolidating purchasing authority through specialized GPOs focused on outpatient ENT procedures. These organizations negotiate bundled pricing for microdebrider handpieces, disposable tips, and suction tubing. The shift is most visible in United States metropolitan markets where independent ASCs outnumber hospital outpatient departments. Traditional distributor relationships with hospital supply chains are fragmenting as direct manufacturer contracts capture volume commitments.
Microdebrider Market Segmentation
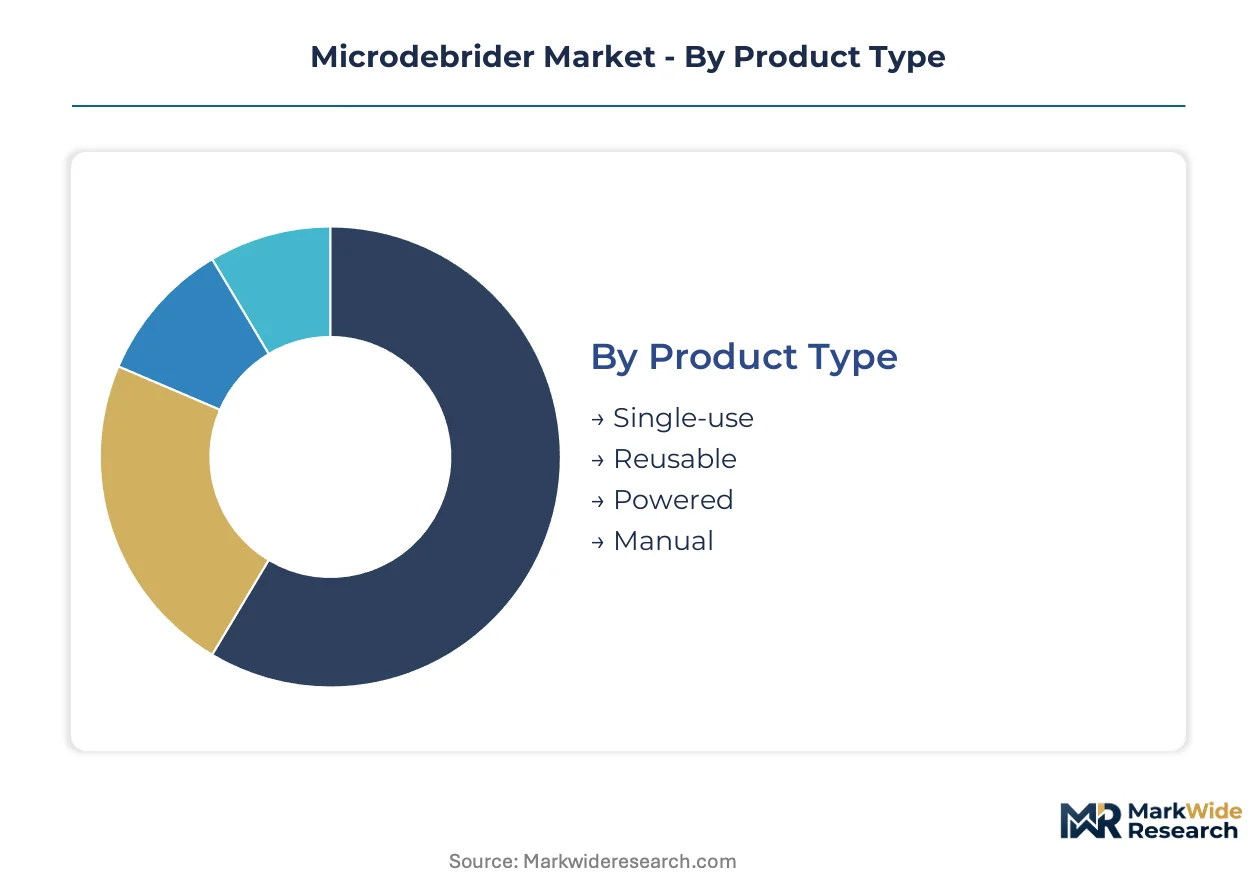
Microdebrider procurement patterns diverge sharply across facility types and procedural settings. Technology selection and tip architecture determine sterilization liability, capital intensity, and reimbursement capture for surgical stakeholders.
Product Type:
After-sales service intensity varies dramatically across product architectures. Single-use platforms eliminate sterilization validation burdens but require continuous tip replenishment. Reusable systems demand intensive field service for blade refurbishment and handpiece calibration.
- Single-use:Pre-sterilized polymer handpieces with integrated cutting blades eliminate FDA reprocessing validation costs. ASCs in Texas and Florida prioritize these platforms to bypass autoclave infrastructure investments. By volume, Single-use leads. By growth pace, Single-use is ahead.
- Reusable:Stainless steel handpieces with detachable autoclavable blades carry higher upfront capital costs but lower per-procedure consumable spend. German university hospitals retain these systems for skull-base volume. Precision-machined blade substrates from Solingen suppliers create service dependency on OEM refurbishment programs.
- Powered:Motor-driven handpieces operating at 5,000-12,000 RPM with integrated irrigation ports dominate functional endoscopic sinus surgery workflows.
- Manual:Non-powered through-cutting instruments persist in resource-constrained settings where capital equipment procurement is deferred entirely.
By volume, Single-use leads. By growth pace, Single-use is ahead.
Technology:
Cost tier separation defines technology adoption corridors. Electric systems command premium placement in academic medical centers. Pneumatic alternatives retain footholds where compressed air infrastructure is already institutionalized.
- Electric:Brushless DC motors with torque feedback control enable precise tissue resection at variable speeds. United States hospital systems standardize on these platforms for navigation-integrated procedures. The installed base concentrates in metropolitan markets with high sinus surgery density.
- Pneumatic:Compressed-air driven turbines operate without electrical isolation requirements, reducing capital outlay in Brazilian and Indian facilities. Extended replacement cycles beyond seven years lock in these systems where maintenance infrastructure is sparse.
- Mechanical:Hand-actuated cutting mechanisms without external power sources serve humanitarian surgical missions and field hospitals lacking reliable electricity.
- Laser:Er:YAG and CO2 laser ablation systems compete for select soft tissue applications but lack integrated suction functionality of rotary microdebriders.
Electric platforms dominate revenue contribution. Pneumatic systems expand most quickly in cost-sensitive emerging markets.
Application:
Procedure complexity dictates instrument specification requirements. Skull-base approaches demand navigation-compatible platforms with angled tip configurations. Office-based interventions drive compact, lower-RPM alternatives.
- Otolaryngology:Functional endoscopic sinus surgery, septoplasty, and turbinate reduction constitute the core volume. Academic medical centers in Heidelberg and Boston deploy 70-degree and 90-degree curved tips for frontal sinus recess access.
- Neurosurgery:Endoscopic skull-base tumor resection requires microdebriders with embedded electromagnetic tracking for navigation integration. These procedures command premium instrument pricing.
- Dental Surgery:Maxillofacial procedures including sinus lift augmentation employ modified handpieces with saline irrigation protocols.
- Plastic Surgery:Rhinoplasty and aesthetic septal procedures utilize lower-RPM platforms with finer blade geometries for cartilage sculpting.
Otolaryngology generates the highest procedure volume. Neurosurgery applications are climbing the fastest as navigation adoption accelerates.
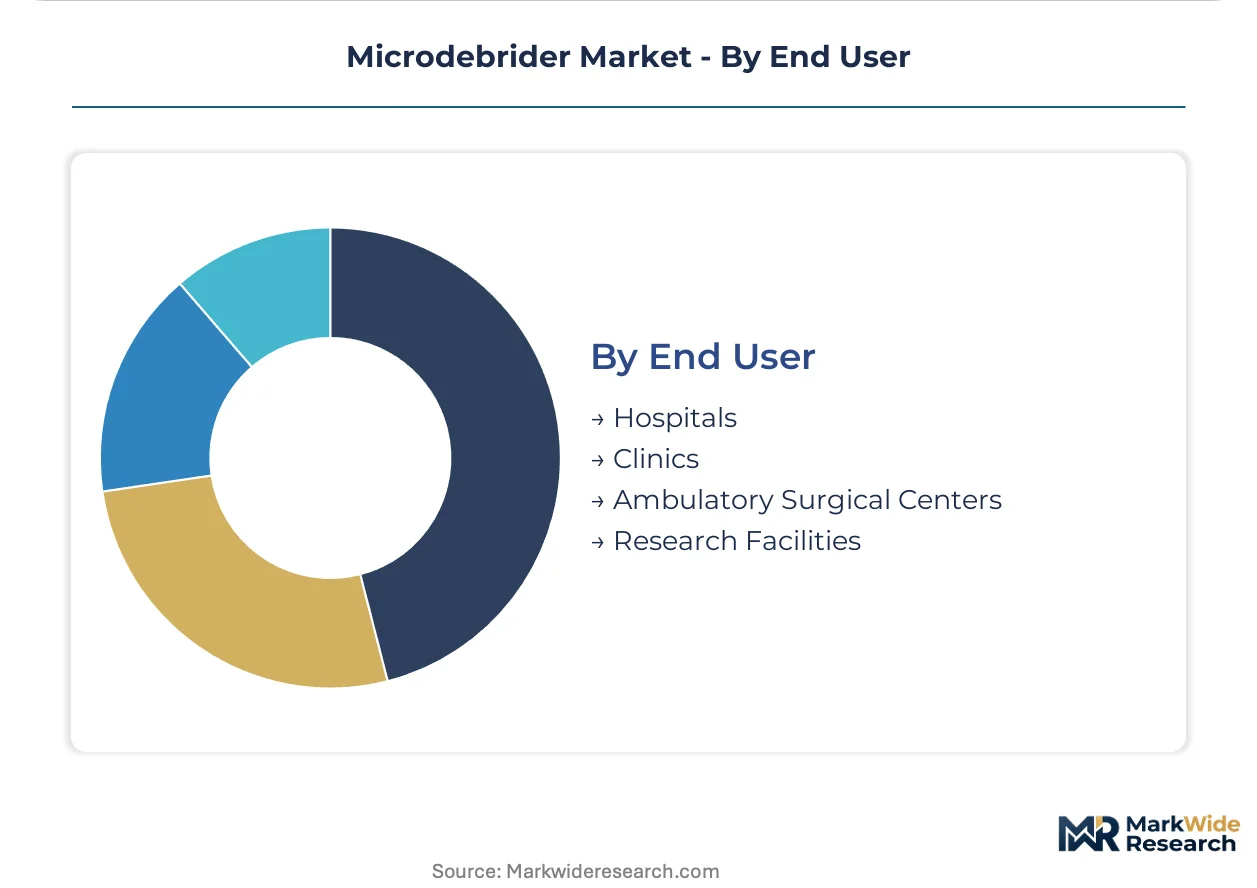
End User:
Customer type determines procurement channel and pricing leverage. Hospital systems negotiate bundled capital-consumable contracts. ASCs favor direct manufacturer relationships bypassing traditional distributors.
- Hospitals:Integrated delivery networks in Germany and Japan procure through specialized ENT GPOs with multi-year volume commitments. These facilities retain reusable platforms for high-complexity skull-base caseloads.
- Clinics:Office-based otolaryngology practices in United States metropolitan markets acquire compact microdebriders for in-office balloon sinuplasty. Commercial payer reimbursement for site-of-service migration drives this segment.
- Ambulatory Surgical Centers:Independent outpatient facilities prioritize single-use platforms to minimize reprocessing infrastructure and staffing costs. Direct purchasing autonomy fragments traditional supply chain relationships.
- Research Facilities:Cadaveric training laboratories and surgical simulation centers procure refurbished or obsolete-generation systems for educational purposes.
Hospitals retain the largest installed base. ASCs are gaining share fastest as site-of-service shifts accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty surgical instrument clusters concentrate near precision manufacturing infrastructure. The Solingen blade-making corridor in Germany and the Tuttlingen endoscopy cluster anchor European supply. Japanese medical device districts in Tokyo-Osaka corridor feed Asian demand.
United States
Ambulatory surgical center construction in Texas and Florida drives single-use microdebrider procurement. FDA 510(k) pathways for powered surgical instruments shape product launch timelines. The Minneapolis-St. Paul corridor hosts major ENT device engineering operations serving academic medical centers.
Germany
University hospitals in Heidelberg and Berlin maintain reusable platform installations for complex skull-base procedures. EU MDR technical documentation requirements compress approval cycles for disposable alternatives. The Solingen-Tuttlingen manufacturing belt supplies precision-machined blade substrates to global OEMs.
Japan
PMDA fast-track pathways for ergonomic instruments address aging ENT specialist workforce constraints. METI medical device reimbursement policies influence hospital capital procurement cycles. The Tokyo-Osaka corridor concentrates domestic microdebrider distribution and technical service infrastructure.
India
Compressed-air pneumatic systems retain installed base dominance in cost-sensitive hospital systems. CDSCO medical device registration requirements for imported powered instruments create market access timelines. Mumbai and Delhi medical device distribution hubs channel equipment to tier-2 city hospital expansions.
Brazil
Extended capital replacement cycles beyond seven years lock in pneumatic microdebrider platforms. ANVISA medical device conformity assessment pathways shape import registration for electric alternatives. São Paulo hospital procurement clusters concentrate ENT surgical volume in the Southeast region.
Microdebrider Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision-machined blades and polymer handpieces. The vendor base concentrates around integrated ENT navigation portfolios and disposable tip architectures. Three archetypes dominate: diversified surgical conglomerates with navigation integration capabilities; specialized powered instrument manufacturers focused on otolaryngology; and precision component fabricators supplying blade substrates and molded handpieces. Competitive moves center on single-use platform conversions and direct ASC contracting bypassing traditional distribution.
Among diversified surgical conglomerates, Medtronic and Stryker occupy positions exemplifying navigation-integrated system strategies. Smith & Nephew represents the specialized powered instrument archetype focused on ENT-specific disposable configurations. German-origin entities including KARL STORZ and Richard Wolf GmbH anchor the precision endoscopy and component fabrication tier, leveraging Tuttlingen-Solingen manufacturing proximity for blade substrate supply.
| Leading Market Players |
|---|
| KARL STORZ |
| CONMED Corporation |
| Medtronic |
| Richard Wolf GmbH |
| Arthrex |
| Stryker |
| Smith & Nephew |
| B. Braun |
| Olympus Corporation |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Solingen precision-blade fabrication is compressing margin structures for reusable microdebrider producers while simultaneously enabling aggressive pricing on single-use alternatives. German metallurgy suppliers are accepting longer payment terms to maintain utilization, a dynamic that transfers negotiating leverage downstream to disposable-tip manufacturers and ambulatory surgical center procurement committees.
Pricing Analysis
Volume-discount tiering structures separate academic medical center bundled contracts from independent ASC spot purchases. Three-tier pricing stratifies across navigation-integrated premium systems, standard electric platforms, and pneumatic economy configurations. Price differentiation rests on FDA 510(k) clearance tier and after-sales service bundling. Cost compression in the reusable segment is intensifying because EU MDR revalidation expenses erode lifecycle economics. Independent ASCs in Texas and Florida exhibit highest price sensitivity; university hospitals in Germany and Japan show lowest elasticity due to navigation integration requirements.
Supply Chain Analysis
Export-control regime scrutiny on precision-machined surgical steel from German and Japanese suppliers constrains blade substrate flows to third-country OEMs. Geographic supply concentration centers on Germany, Japan, and the United States for finished devices, with China and India emerging as molded polymer handpiece fabricators. Raw material dependencies include Solingen specialty stainless steel, Japanese high-torque miniature motors, and medical-grade polymer resins. Single-source vulnerability in German blade metallurgy creates chokepoint exposure. Distribution runs through specialized ENT GPOs in hospital systems and direct manufacturer contracts in ASC networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microdebrider market expansion sits in early-cycle penetration as site-of-service migration from inpatient to ambulatory settings accelerates disposable platform adoption. This tailwind compresses capital equipment replacement cycles and opens white-space procurement channels outside traditional hospital supply chains.
For Market Incumbents: Entrench navigation integration capabilities as the primary defensive moat against specialized powered-instrument challengers. Deepen backward integration into Solingen blade substrate supply through captive supplier agreements or equity stakes. Prioritize direct ASC contracting infrastructure to bypass fragmenting distributor relationships and capture volume commitments from independent outpatient facilities.
For New Entrants and Emerging Players: Build out office-based rhinology platforms targeting United States metropolitan otolaryngology practices seeking in-office procedure margin capture. Focus initial penetration on compact, lower-RPM devices for balloon sinuplasty and polypectomy bypassing facility fees. Leverage commercial payer reimbursement parity for site-of-service shifts as the primary go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across single-use microdebrider tip manufacturing as polymer molding scales displace precision machining. Long-term viability favors platform-integrated players with navigation system bundling capabilities over standalone powered instrument specialists. Acquisition target archetype: ergonomic handpiece designers with PMDA fast-track regulatory pathways. Signal to watch: CDSCO and ANVISA approval timelines for imported electric platforms as indicators of emerging market access inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Navigation System Integration | Embedded electromagnetic tracking in microdebriders commands premium placement in academic medical centers. |
| Single-Use Platform Conversion | Disposable tip architectures bypass FDA reprocessing validation burdens and capture ASC procurement preference. |
| Direct ASC Contracting | Manufacturer volume commitments with independent outpatient facilities fragment traditional GPO relationships. |
| Ergonomic Handpiece Development | PMDA fast-track pathways for lightweight single-hand-operable instruments address Japan's aging specialist workforce. |
| Reimbursement Strategy Alignment | Commercial payer site-of-service parity drives office-based rhinology platform demand in United States metropolitan markets. |
Research Methodology
Initial hypotheses were tested against primary input from ENT surgeons, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and ambulatory surgical center administrators and refined through secondary validation. Primary fieldwork combined structured interviews with procurement stakeholders and procedural observation in academic medical center and ASC settings. Secondary sources encompassed FDA 510(k) clearance databases, EU MDR technical documentation filings, hospital procurement contract disclosures, and CMS Medicare reimbursement schedules. Bottom-up procedure volume estimates and top-down equipment installed base calculations were triangulated to converge on market sizing.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, technology type, application complexity, and end-user facility category. CAGRs were derived from procedure volume growth rates, equipment replacement cycle compression, and disposable tip penetration curves. Industry-specific forecast inputs incorporated navigation system adoption trajectories and site-of-service migration elasticities by payer type.
Stress conditions across FDA reprocessing guidance stringency, EU MDR approval timeline variability, and German specialty steel supply disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding reimbursement parity maintenance and ASC construction permitting velocity. Material shifts in PMDA ergonomic instrument fast-track eligibility or CDSCO import registration requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Electromyography Devices Market
Medical Devices
Global Plastic Surgery Devices Market
Medical Devices
Subcutaneous Implantable Defibrillator System Market
Medical Devices
Artificial Spine Discs Market
Medical Devices
Global Image Guided Surgery Devices Market
Medical Devices
Global Breast Pumps Market
Medical Devices
Homecare Medical Devices Market
Medical Devices
Thyroid Ablation Devices Market
Medical Devices
3D Printed Medical Implants Market
Medical Devices
Asthma Inhaler Device Market
Medical Devices
Ultrasound Probe Market
Medical Devices
Urine Collection Devices Market
Medical Devices
EEG and EMG Equipment Market
Medical Devices
Flow Diverters Market
Medical Devices
Spinal Stenosis Implant Market
Medical Devices
Global Radiofrequency Ablation Devices Market