
 Orthopedic Consumables Market | 2026-2036
Orthopedic Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Orthopedic Consumables Market Analysis
Aftermarket service revenue from instrument tray refurbishment and sterilization logistics is reconfiguring margin pools away from pure device manufacturing. Stryker leverages its end-to-end surgical ecosystem to capture recurring service income alongside hardware placement. Zimmer Biomet anchors its competitiveness through deep specialization in knee and hip reconstruction portfolios. Smith & Nephew differentiates via advanced wound management integration with orthopedic procedural workflows.
Orthopedic consumables encompass single-use and limited-use devices including bone screws, plates, implants, and grafts manufactured from titanium alloys, medical-grade stainless steel, polymers, and bioceramics through precision machining, additive manufacturing, and sintering processes; these products stabilize skeletal structures, facilitate fusion, or replace damaged articulating surfaces during operative intervention. The trauma surgery application segment leads absolute volume due to emergency procedure frequency, while sports medicine represents the fastest-growing application as arthroscopic techniques expand to younger patient demographics. Joint replacement implants command premium pricing tiers driven by bearing surface innovation and patient-specific instrumentation, whereas bone graft substitutes face margin compression from synthetic material commoditization.
The FDA 510(k) program and EU Medical Device Regulation impose biocompatibility, sterility assurance, and post-market surveillance requirements that elevate compliance costs but also create barriers against lower-grade imports. ISO 5832 material standards and ASTM F136 specifications for implantable titanium alloys define minimum mechanical property thresholds that manufacturers must certify through validated testing protocols. Stakeholders must monitor evolving reimbursement policies for outpatient joint replacement and synthetic graft alternatives as site-of-care migration reshapes purchasing authority.
Market Dynamics
The migration of joint replacement procedures to ambulatory surgical centers is restructuring purchasing authority and kit standardization requirements across the orthopedic consumables value chain. This site-of-care shift compresses traditional hospital procurement cycles while elevating demand for sterile-packaged, procedure-specific disposable systems.
Growth Catalysts
- FDA 510(k) Pathway Modernization:Streamlined clearance timelines for titanium trauma implants accelerate manufacturer time-to-revenue and expand product pipelines.
- Additive Manufacturing Adoption:Patient-specific instrumentation and porous titanium structures produced through electron beam melting enable geometric complexity unattainable via conventional machining.
- Aging Demographics in Developed Economies:Revision surgery volumes in Germany, Japan, and the United States drive recurrent demand for knee and hip reconstruction components.
Market Restraints
- Titanium Alloy Input Concentration:Supply of ASTM F136-certified titanium sponge concentrates among limited primary smelters, exposing manufacturers to price volatility and allocation risk.
- EU Medical Device Regulation Compliance Burden:Enhanced clinical evidence requirements and notified body capacity constraints extend certification timelines and elevate fixed compliance costs.
- Synthetic Bone Graft Commoditization:Hydroxyapatite and beta-tricalcium phosphate substitutes face margin erosion as manufacturing processes standardize and supplier differentiation diminishes.
Strategic Opportunities
- Outpatient Joint Replacement Reimbursement Expansion:Medicare and commercial payer policy shifts toward same-day discharge create demand for compact, disposable instrument kits optimized for ambulatory workflows.
- Bioceramic-Polymer Composite Convergence:Integration of PEEK-OPTIMA with hydroxyapatite coatings merges radiolucency with osseointegration performance in spinal and trauma applications.
- India Orthopedic Infrastructure Buildout:Government hospital modernization and medical device manufacturing incentives under the PLI scheme attract component suppliers and kit assemblers.
Industry Challenges
- Electron Beam Welding Technician Scarcity:Precision joining of titanium implant components requires certified operators with aerospace-derived skill sets that orthopedic manufacturers compete to attract.
- Legacy Hospital ERP Integration:Ambulatory surgical center procurement platforms demand API-compatible inventory management that conflicts with established hospital supply chain architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthopedic Consumables Market |
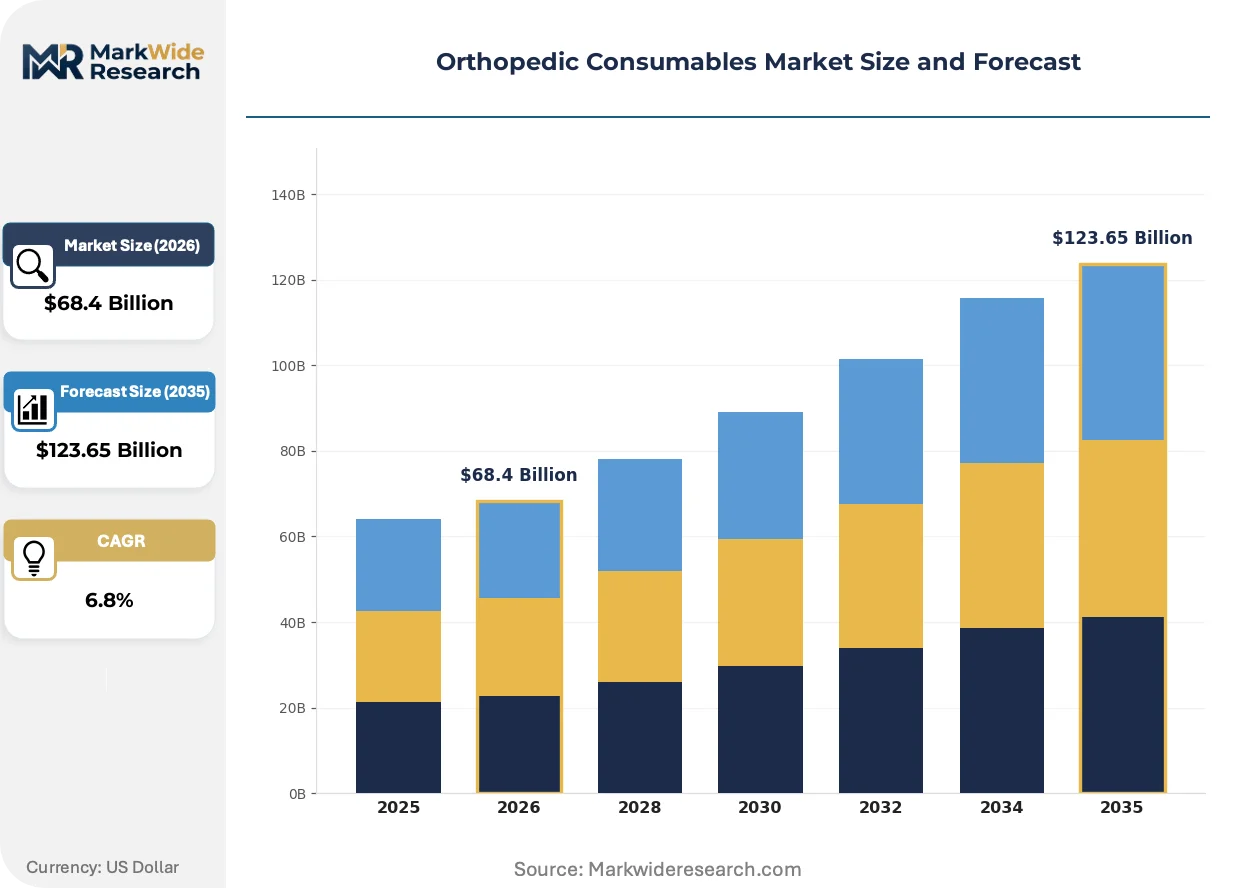
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone Screws, Plates, Implants, Grafts End User: Hospitals, Clinics, Rehabilitation Centers, Surgical Centers Material: Stainless Steel, Titanium, Polymers, Bioceramics Application: Trauma Surgery, Joint Replacement, Spine Surgery, Sports Medicine |
| Companies Covered | Smith & Nephew, Medtronic, Zimmer Biomet, ConMed, NuVasive, Stryker, Arthrex, B. Braun, DePuy Synthes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthopedic Consumables Market Emerging Trajectories
Orthopedic consumables innovation clusters around three vectors: manufacturing process transformation, regulatory pathway optimization, and procurement model reinvention. These forces collectively compress product lifecycles while elevating service-content expectations.
Additive manufacturing is collapsing the economic viability of conventional subtractive machining for complex implant geometries. Electron beam melting produces patient-matched acetabular cups with integrated porous surfaces that eliminate secondary coating steps. Ambulatory surgical centers in the United States are adopting these components at accelerating rates as instrumentation sets shrink and sterilization logistics simplify.
EU Medical Device Regulation post-market surveillance requirements are elevating clinical data obligations for implantable devices. Manufacturers must now maintain systematic literature review processes and periodic safety update reports across product portfolios. Knee and hip reconstruction segments face the steepest compliance cost increases as Class III device classification triggers enhanced scrutiny from notified bodies.
Hospital buying consortiums are consolidating orthopedic spend under single-source contracts with performance guarantees. This concentration transfers inventory risk to manufacturers while demanding real-time usage tracking and consignment replenishment. The United States exhibits the most pronounced consolidation, with regional health systems negotiating multi-year agreements that bundle implants with instrument tray management services.
Orthopedic Consumables Market Segmentation
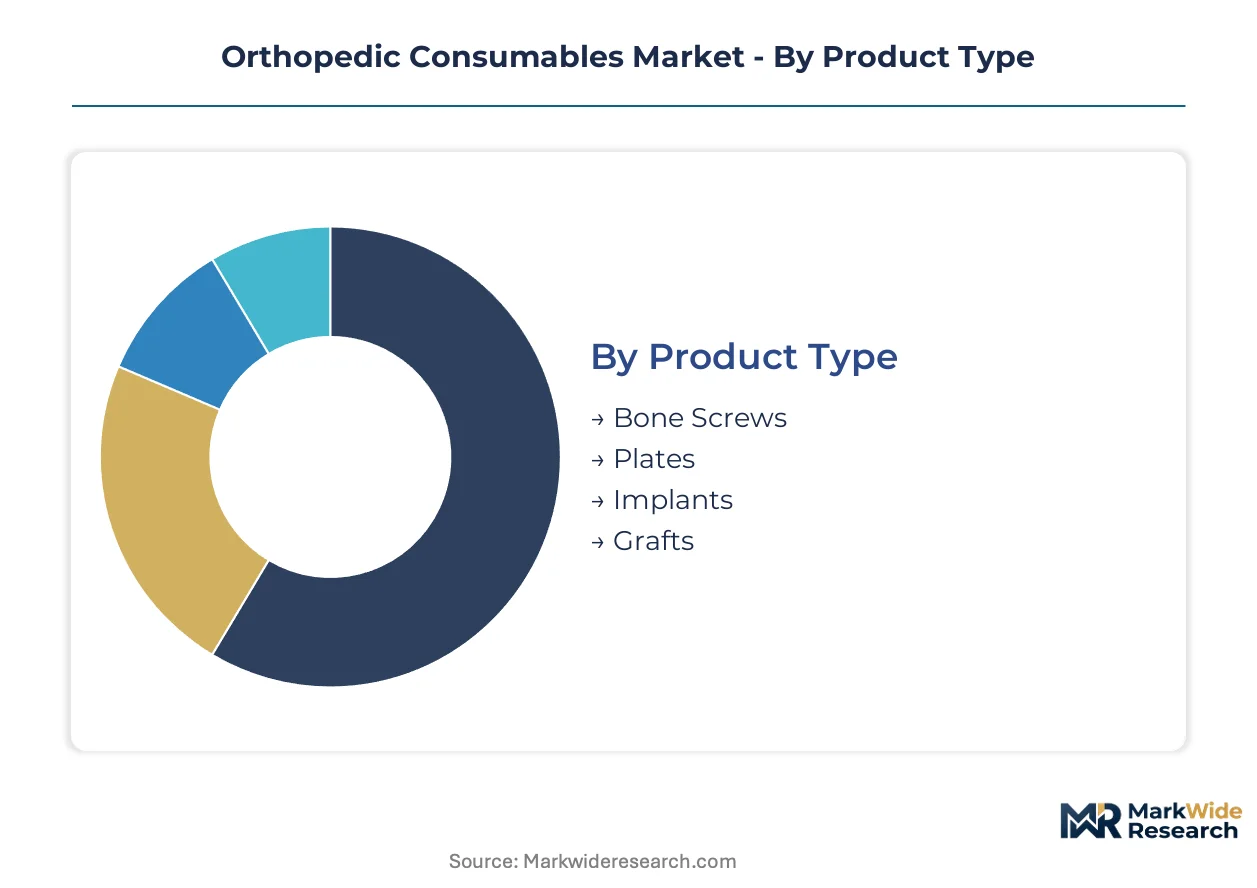
Orthopedic consumables segmentation reveals divergent margin profiles and procurement patterns across material grades and care settings. Product architecture, site-of-care economics, and bearing surface specifications collectively determine competitive positioning within each category.
Product Type:
Mature hardware categories dominate revenue concentration while emerging biologics reshape graft economics.
- Implants:Articulating surfaces and fixation devices manufactured from ASTM F136 titanium alloys or cobalt-chrome-molybdenum alloys command premium pricing tiers. Demand concentrates in the United States and Germany where aging populations drive revision knee and hip reconstruction volumes.
- Plates:Reconstruction and trauma plates with locking screw interfaces stabilize long-bone fractures through anatomically contoured designs. Ambulatory surgical centers in the United States are expanding adoption of sterile-packaged, procedure-specific plate systems as outpatient trauma migration accelerates.
- Bone Screws:Cortical and cancellous screw variants in titanium and stainless steel provide fragment fixation across trauma and spine applications.
- Grafts:Allograft, autograft, and synthetic bone substitutes facilitate osseous union in spinal fusion and trauma void filling.
Implants retain volume leadership; grafts hold the steepest expansion curve as synthetic hydroxyapatite manufacturing scales.
End User:
Site-of-care migration is redistributing purchasing authority from inpatient facilities to outpatient settings.
- Hospitals:Academic medical centers and community hospitals maintain dominance in complex revision arthroplasty and polytrauma procedures requiring extended postoperative monitoring. Germany's DRG-based reimbursement and Japan's universal coverage system sustain hospital-centric procurement for high-acuity cases.
- Surgical Centers:Ambulatory surgical centers in the United States are capturing primary joint replacement volume as Medicare reimbursement shifts toward same-day discharge. Compact disposable instrument kits and sterile-packaged implant systems align with limited storage and rapid turnover requirements.
- Clinics:Orthopedic and sports medicine clinics administer injectable biologics and minor soft-tissue procedures.
- Rehabilitation Centers:Post-acute facilities manage non-operative fracture care and joint mobilization protocols.
Hospitals retain volume leadership; surgical centers are gaining share fastest as outpatient arthroplasty authorization expands.
Material:
Performance requirements and cost structures stratify across metallic and non-metallic alternatives.
- Titanium:ASTM F136-certified implantable titanium alloys deliver superior strength-to-weight ratios and biocompatibility profiles for load-bearing applications. Supply concentrates among limited primary smelters, exposing manufacturers to price volatility and allocation risk for certified sponge feedstock.
- Stainless Steel:Medical-grade 316L and 22Cr-13Ni-5Mn alloys provide cost-effective fixation for temporary and semi-permanent implants. Demand persists in trauma applications across India and Brazil where procurement budgets constrain titanium adoption.
- Polymers:PEEK-OPTIMA and UHMWPE bearing surfaces enable radiolucent spinal cages and articulating joint liners.
- Bioceramics:Hydroxyapatite and beta-tricalcium phosphate coatings and granules promote osseointegration on implant surfaces.
Titanium retains volume leadership; bioceramics are climbing the fastest as coating technology penetrates spinal and trauma segments.
Application:
Procedure frequency and reimbursement intensity create divergent growth trajectories across surgical specialties.
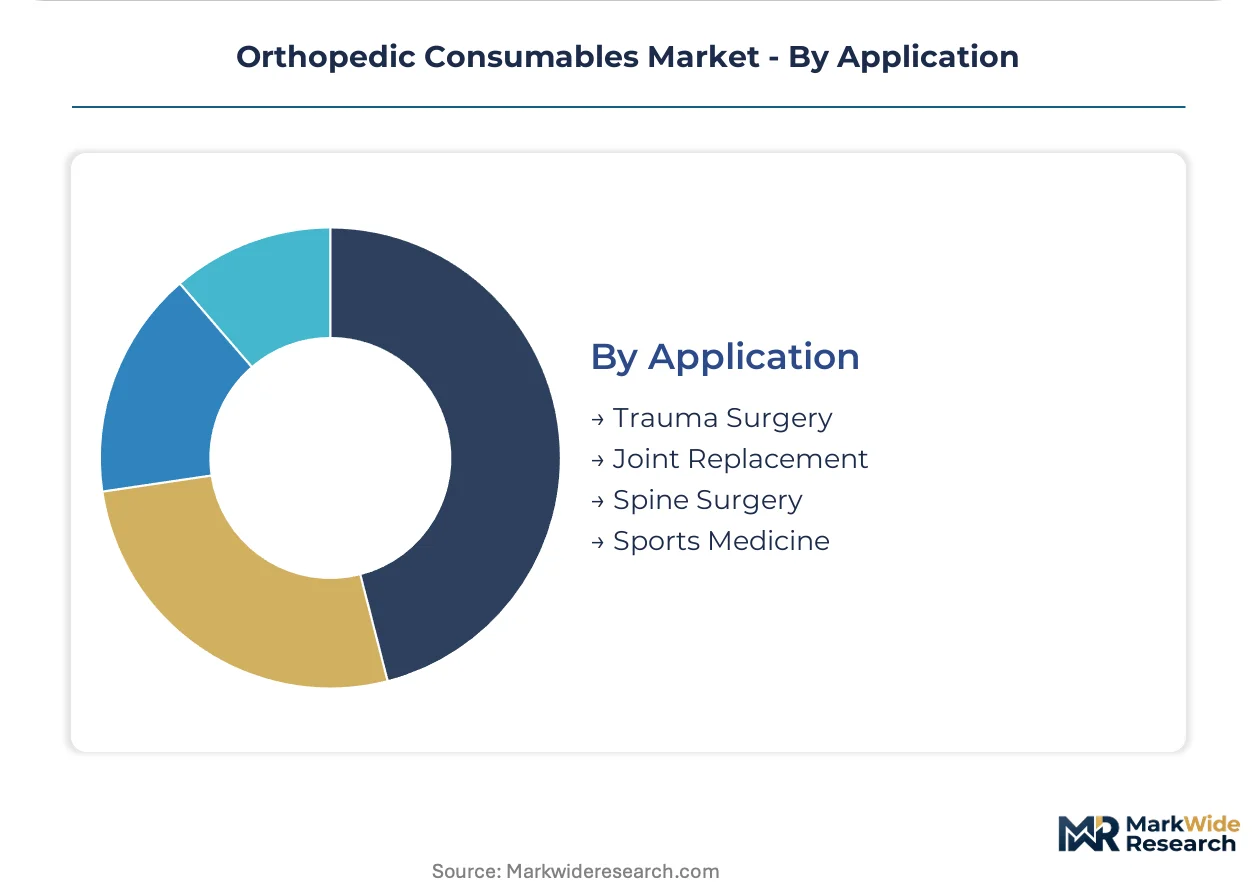
- Trauma Surgery:Emergency fracture fixation procedures generate the highest absolute volume across all orthopedic consumables categories. Japan's aging population and Germany's industrial accident rates sustain demand for titanium trauma implants and external fixation systems.
- Sports Medicine:Arthroscopic rotator cuff repair, ACL reconstruction, and meniscal procedures are expanding fastest among younger patient demographics. Ambulatory surgical centers in the United States prioritize disposable shavers, suture anchors, and all-inside repair systems for same-day discharge protocols.
- Joint Replacement:Primary and revision knee, hip, and shoulder arthroplasty commands premium implant pricing.
- Spine Surgery:Interbody fusion, deformity correction, and motion preservation procedures drive specialized implant demand.
Trauma surgery retains volume leadership; sports medicine represents the fastest-growing trajectory as arthroscopic technique penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ASTM F136-certified titanium sponge feedstock concentrates among primary smelters in the United States, Germany, and Japan, creating allocation bottlenecks that ripple through implant manufacturing networks worldwide.
United States
Medicare reimbursement shifts toward same-day joint replacement discharge are accelerating ambulatory surgical center procurement of sterile-packaged disposable kits. The FDA's modernized 510(k) pathway compresses titanium trauma implant clearance timelines. Warsaw, Indiana anchors domestic implant manufacturing, with Stryker and Zimmer Biomet maintaining precision machining operations there.
Germany
DRG-based hospital reimbursement and Europe's highest revision surgery rates sustain demand for knee and hip reconstruction components. EU Medical Device Regulation compliance costs elevate barriers for lower-grade imports. The Tuttlingen surgical instrument cluster concentrates tray fabrication and sterilization logistics expertise.
Japan
Aging demographics and industrial accident rates drive trauma implant and external fixation system consumption. PMDA post-market surveillance requirements align with EU MDR clinical data obligations. The Kobe-Osaka corridor hosts titanium alloy processing facilities serving domestic implant manufacturers.
India
Government hospital modernization and PLI scheme incentives for medical device manufacturing attract component suppliers and kit assemblers. CDSCO regulatory harmonization with ISO 5832 standards streamlines import substitution. Gujarat and Karnataka emerge as contract manufacturing hubs for stainless steel trauma fixation.
Switzerland
Swissmedic certification prestige supports premium positioning for precision-machined spinal and trauma implants. The country's metallurgical heritage translates into specialized titanium alloy finishing capabilities. The Jura Arc watchmaking region repurposes micron-level machining expertise toward orthopedic component production.
Orthopedic Consumables Market Vendor Landscape
Integrated surgical ecosystem providers and specialized reconstruction portfolio companies split the market between comprehensive service bundling and deep anatomical focus. The vendor base stratifies into three tiers: multinational conglomerates with end-to-end platform control, mid-cap specialists dominating single anatomical segments, and regional fabricators serving price-sensitive procurement. Dominant competitive moves include instrument tray management service integration and additive manufacturing capacity expansion for patient-specific instrumentation.
Within the integrated ecosystem tier, Stryker and Zimmer Biomet occupy positions that exemplify contrasting strategic anchors. Stryker leverages its end-to-end surgical platform to capture recurring service revenue alongside hardware placement. Zimmer Biomet represents deep specialization in knee and hip reconstruction portfolios. Among wound-integrated specialists, Smith & Nephew sits within a positioning that merges advanced wound management with orthopedic procedural workflows.
| Leading Market Players |
|---|
| Smith & Nephew |
| Medtronic |
| Zimmer Biomet |
| ConMed |
| NuVasive |
| Stryker |
| Arthrex |
| B. Braun |
| DePuy Synthes |
| Others |
Supply Flow & Price Mechanics
Warsaw, Indiana anchors global implant manufacturing capacity, with Stryker and Zimmer Biomet maintaining precision machining operations that translate titanium sponge feedstock into premium-priced trauma and joint replacement components. This geographic concentration of ASTM F136-certified finishing capability creates asymmetric pricing power for manufacturers serving ambulatory surgical centers demanding sterile-packaged disposable kits.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing structure across implantable orthopedic consumables. Three-tier pricing separates premium patient-matched instrumentation from standard catalog implants and economy-grade stainless steel trauma fixation. Price differentiation rests on ISO 5832 material certification grade and bearing surface innovation level. Margins are tightening in synthetic bone graft substitutes as hydroxyapatite manufacturing standardizes. Ambulatory surgical centers exhibit highest price sensitivity due to compressed reimbursement windows, while academic medical centers prioritize clinical performance over unit cost.
Supply Chain Analysis
Export control regimes on electron beam melting equipment limit additive manufacturing capacity expansion outside established aerospace-industrial corridors. Supply draws from United States, Germany, and Japan for ASTM F136-certified titanium sponge, with India and China supplying medical-grade stainless steel for cost-sensitive markets. Raw material dependencies center on titanium alloy feedstock, precision-machined instrument trays, and sterilization packaging materials. Single-source vulnerability concentrates in primary titanium smelters certified for implant-grade sponge. Distribution runs through hospital buying consortiums and GPO contracts that consolidate orthopedic spend under performance-guarantee agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The orthopedic consumables market functions as a regulatory-moat business where FDA 510(k) clearance timelines and EU MDR compliance costs erect barriers that protect incumbent returns. Switching costs for hospital systems locked into instrument tray ecosystems reinforce this defensive structure.
For Market Incumbents: Build switching-cost moats through instrument tray management service integration that embeds sterile logistics into hospital supply chain workflows. Deepen backward integration into titanium alloy finishing to secure ASTM F136-certified feedstock allocation. Additive manufacturing capacity expansion in Warsaw and Tuttlingen clusters defends against emerging entrants leveraging electron beam melting for patient-specific instrumentation. For New Entrants and Emerging Players: Establish a beachhead in India's contract manufacturing segment where PLI scheme incentives and CDSCO regulatory harmonization lower entry barriers for stainless steel trauma fixation. Target ambulatory surgical center procurement platforms with API-compatible inventory management systems that bypass legacy hospital ERP architectures. White-space exists in bioceramic-polymer composite spinal cages merging PEEK-OPTIMA radiolucency with hydroxyapatite osseointegration performance. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among instrument tray refurbishment and sterilization logistics providers that capture service income alongside hardware placement. Long-term viability favors manufacturers with captive titanium alloy processing and notified body relationships spanning FDA and EU MDR jurisdictions. Acquisition targets should demonstrate electron beam welding technician retention and additive manufacturing yield consistency. Watch for Medicare reimbursement expansion signals in outpatient joint replacement as inflection indicators for ambulatory surgical center kit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Modernized clearance timelines compress manufacturer time-to-revenue for titanium trauma implants. |
| Additive Manufacturing Capacity Expansion | Electron beam melting enables patient-specific acetabular cups with integrated porous surfaces. |
| Hospital System Partnership | Single-source contracts with performance guarantees transfer inventory risk to manufacturers. |
| Instrument Tray Management Service | Recurring service revenue from refurbishment and sterilization logistics reconfigures margin pools. |
| Reimbursement Strategy | Medicare same-day discharge authorization drives ambulatory surgical center kit standardization. |
Methodological Framework
A standing panel of orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation from FDA 510(k) filings, EU MDR notified body databases, CMS Medicare reimbursement schedules, and hospital procurement system records. Primary fieldwork combined structured interviews with sterile processing directors and ambulatory surgical center administrators with bottom-up shipment data triangulation against top-down implant registry analysis.
Scenario bracketing around reimbursement policy shifts and titanium alloy price volatility informed the analytical framework across the projection horizon. Segmentation dimensions modeled include material grade tier, site-of-care setting, application specialty, and bearing surface specification. CAGRs were derived from procedure volume trajectories and implant pricing elasticity patterns. Forecast inputs incorporated revision surgery demographics, outpatient migration authorization timelines, and additive manufacturing adoption curves.
Stress conditions across titanium sponge allocation disruptions, EU MDR notified body capacity constraints, and Medicare site-of-care reimbursement thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding procedure migration rates and material substitution patterns. Material shifts in FDA 510(k) pathway modernization or EU MDR post-market surveillance stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Orthopedic Braces and Supports Market
Orthopedic Devices
Global Patient Positioning Devices Market
Orthopedic Devices
Antibacterial Orthopedic Implant Market
Orthopedic Devices
Small Bone and Joint Orthopedic Devices Market
Orthopedic Devices
Hip Resurfacing Implants Market
Orthopedic Devices
Orthopedic Devices Market
Orthopedic Devices
Revision Knee Replacement Market
Orthopedic Devices
Orthopedic Insole Manufacturing Thermosealer Market
Orthopedic Devices
South Africa Spinal Surgery Devices Market
Orthopedic Devices
Global Personalized 3D Printed Orthopedic Implants Market
Orthopedic Devices
Pediatrics Orthotics Market
Orthopedic Devices
Global Orthopedic Implant Market
Orthopedic Devices
Global Orthopedic Digit Implants Market
Orthopedic Devices
Humeral Implant Market
Orthopedic Devices
Kyphoplasty Systems Market
Orthopedic Devices
Orthopedic Drill Bits Market