
 Knee Implants Market | 2026-2036
Knee Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Knee Implants Market Intelligence
Hospital procurement consortiums is reconfiguring how implant manufacturers secure volume contracts across integrated delivery networks. Stryker Corporation leverages its robotics ecosystem to anchor premium positioning within these consolidated buying structures. Zimmer Biomet Holdings, Inc. competes through broad portfolio breadth that sustains relevance across diverse contract tiers. DePuy Synthes Companies controls significant manufacturing scale that dominates cost-sensitive procurement channels.
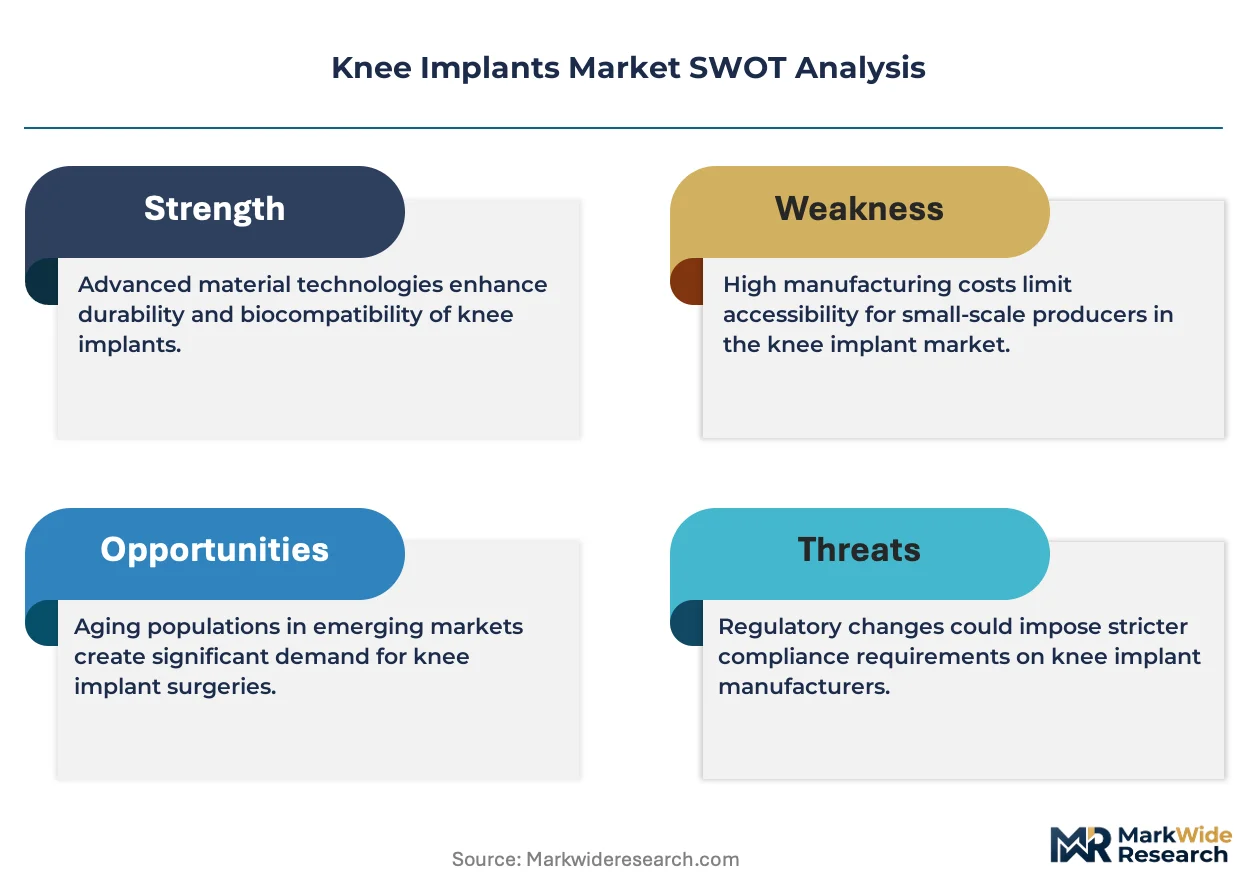
Knee implants are artificial joint prostheses, typically comprising cobalt-chromium-molybdenum alloys, ultra-high molecular weight polyethylene inserts, and titanium plasma-sprayed fixation surfaces, designed to restore biomechanical function after osteoarthritic or traumatic joint failure. Total knee replacement systems represent the mature revenue base where margin pools have compressed under bundled payment models, while robotic-assisted technology commands premium positioning as the fastest-expanding procedure category. Metal-on-polyethylene constructs still occupy the majority of implanted units, though ceramic and composite bearing surfaces are gaining traction in younger, higher-activity patient segments seeking improved wear characteristics.
The FDA's 510(k) premarket notification process and the EU Medical Device Regulation's clinical evidence requirements are elevating barriers to market entry, forcing manufacturers to expand post-market surveillance infrastructure. Japan's PMDA and its revised Pharmaceutical and Medical Device Act impose additional quality management system audits that extend approval timelines for foreign manufacturers. Stakeholders must monitor how evolving reimbursement thresholds for outpatient joint replacement in key markets reshape site-of-service economics and implant pricing power.
Market Dynamics
Hospital procurement consortiums are reconfiguring how implant manufacturers secure volume contracts across integrated delivery networks, compressing pricing power and forcing portfolio breadth as a defensive necessity.
Growth Catalysts
- EU Medical Device Regulation:The MDR's enhanced clinical evidence requirements are elevating barriers for marginal competitors, consolidating share among established manufacturers with robust post-market surveillance infrastructure.
- Robotic-assisted surgical platforms:Orthopedic centers are expanding adoption of computer-navigated implant positioning, driving premium system sales and recurring instrument revenue streams.
- Aging demographics in Japan:The world's oldest population is generating revision surgery volumes that outpace primary replacement growth, favoring manufacturers with specialized revision component portfolios.
Market Restraints
- Cobalt-chromium-molybdenum alloy supply:Concentration of specialty metal processing in limited foundry capacity creates input cost volatility and geographic supply risk.
- FDA 510(k) pathway friction:Heightened scrutiny of predicate device equivalency is extending clearance timelines and increasing regulatory compliance expenditure for new entrants.
- Polyethylene wear debris concerns:Long-term osteolysis risk from conventional bearing surfaces limits implant longevity claims and constrains marketing to younger patient segments.
Strategic Opportunities
- Outpatient joint replacement reimbursement:CMS and private payor expansion of ambulatory surgery center coverage is creating site-of-service economics that favor streamlined implant systems.
- Ceramic-on-ceramic bearing convergence:Advanced alumina matrix composite technology is opening high-activity patient segments previously unsuitable for standard metal-polyethylene constructs.
- India's PLI scheme for medical devices:Domestic manufacturing incentives are attracting component suppliers to establish regional production hubs serving South Asian markets.
Industry Challenges
- Robotics integration complexity:Surgical staff training requirements and capital equipment depreciation schedules are straining hospital operating budgets and implementation timelines.
- Post-market surveillance infrastructure:EU MDR mandates for implant registries and unique device identification are forcing manufacturers to rebuild quality management systems and data architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Knee Implants Market |
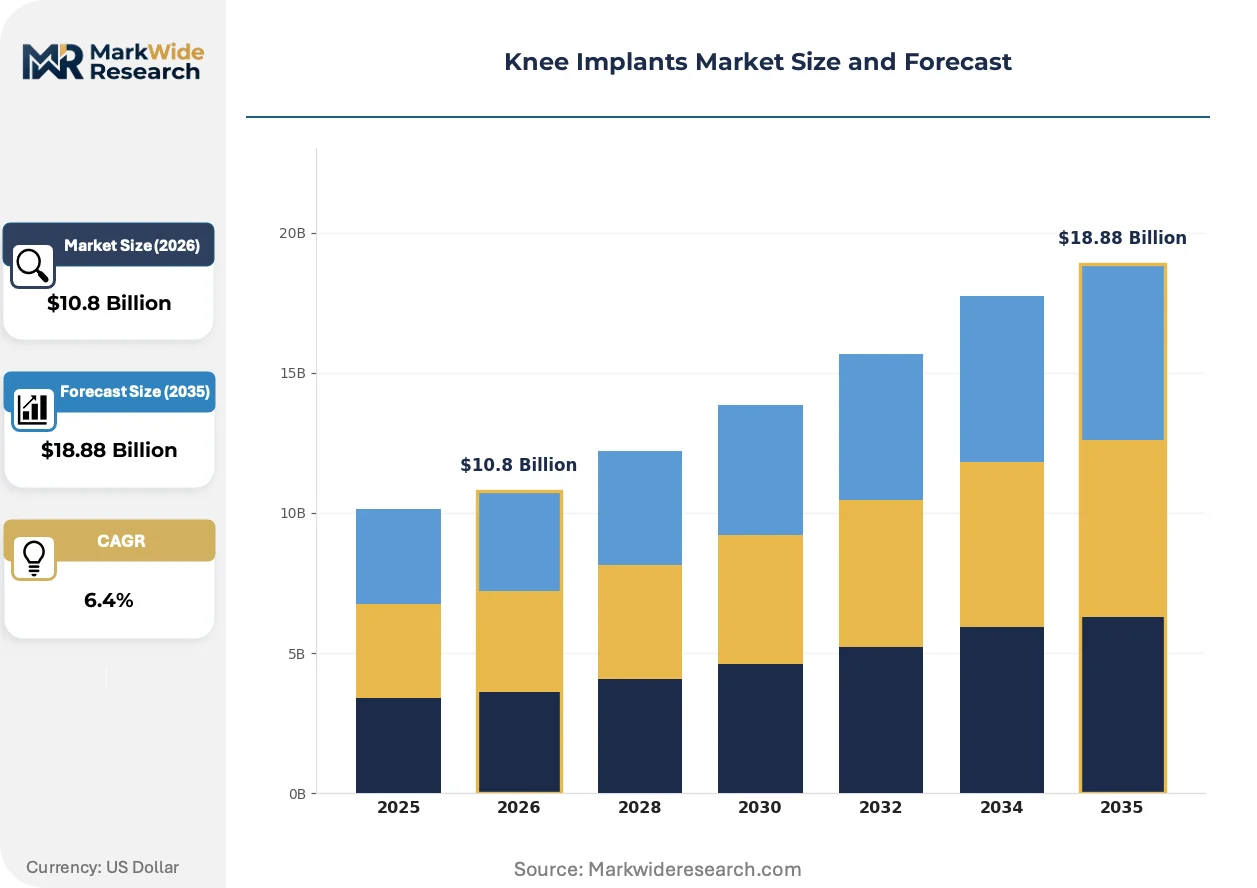
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $18.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Total Knee, Partial Knee, Revision Knee, Patellofemoral Material: Metal, Plastic, Ceramic, Composites End User: Hospitals, Clinics, Orthopedic Centers, Rehabilitation Facilities Technology: Traditional, Robotic-Assisted, Computer-Assisted, Biologic |
| Companies Covered | Stryker Corporation, Zimmer Biomet Holdings, Inc., DePuy Synthes Companies, Smith & Nephew plc, Medacta International SA, MicroPort Scientific Corporation, Exactech, Inc., Corin Group plc, B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Knee Implants Market Strategic Shifts & Innovations
Digital surgical planning and patient-specific instrumentation are compressing operative variability while regulatory evidence requirements are reshaping competitive moats around clinical data assets.
Patient-matched cutting guides derived from preoperative CT imaging are digitizing operative workflow standardization. High-volume orthopedic centers are adopting these systems to reduce instrument tray counts and operative time. The technology is digitizing how implant positioning accuracy is achieved, compressing the learning curve for less experienced surgeons.
Japan's PMDA revised Pharmaceutical and Medical Device Act imposes additional quality management system audits that extend approval timelines for foreign manufacturers. The regulation forces companies to establish local regulatory affairs capabilities or partner with domestic distributors possessing established QMS credentials. Revision knee systems face particular scrutiny given Japan's concentration of complex secondary procedures.
Integrated delivery networks are consolidating implant purchasing through centralized value analysis committees, displacing individual surgeon preference as the primary contract determinant. Ambulatory surgery centers are gaining negotiating leverage as outpatient joint replacement volumes migrate from inpatient settings. This concentration is most visible in United States markets where bundled payment models align site-of-service economics with procurement consolidation.
Knee Implants Market Segmentation
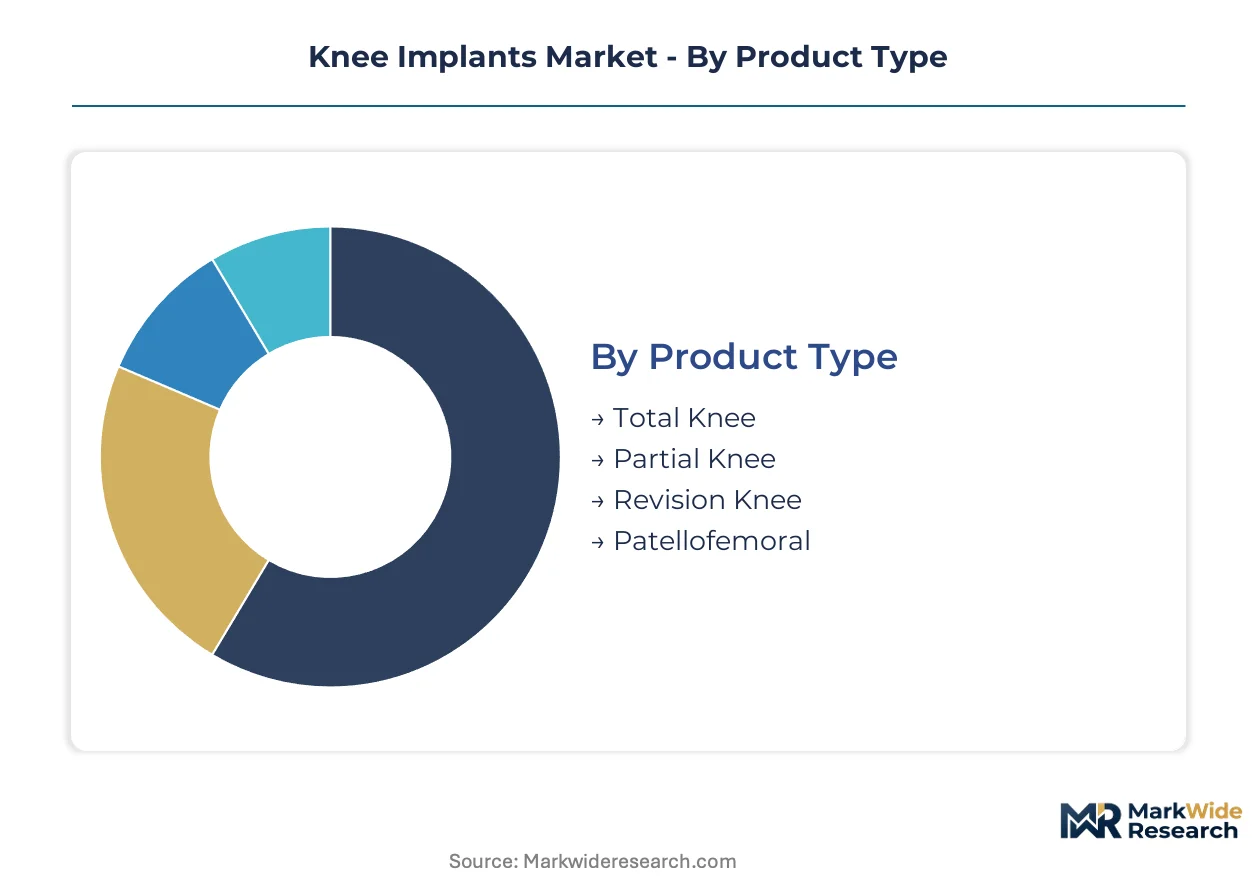
Segmentation in knee implants reveals how procedure complexity, material science, and site-of-service economics create distinct competitive battlegrounds. Manufacturers must align portfolio investments against these dimensions to capture volume in consolidated procurement environments.
Product Type:
Use-case spectrum spans primary intervention through complex secondary reconstruction, with each tier demanding differentiated component engineering and surgeon training infrastructure.
- Total Knee:Complete femoral and tibial component replacement with polyethylene insert, representing the procedural volume base where bundled payment compression has eroded margin pools. Demand concentrates in United States integrated delivery networks facing CMS mandatory bundled care models, with procurement committees prioritizing standardized implant systems that reduce instrument tray complexity.
- Revision Knee:Augmented stems, cones, and metaphyseal sleeves addressing bone loss and component loosening from prior failed arthroplasty. Japan's aging demographic generates the highest per-capita revision volumes globally, favoring manufacturers with specialized augments and porous metal augments approved under PMDA's stringent quality management audits.
- Partial Knee:Compartment-specific resurfacing preserving cruciate ligaments and bone stock.
- Patellofemoral:Isolated trochlear groove and patellar component replacement for isolated anterior knee pain.
The dominant share belongs to Total Knee, while Revision Knee is closing the gap fastest.
Material:
Cost tier stratification separates commodity constructs from premium bearing surfaces targeting younger, higher-activity patient profiles.
- Metal:Cobalt-chromium-molybdenum alloys dominate femoral component manufacturing, with foundry capacity concentration in Germany and United States creating input cost volatility. Procurement contracts in cost-sensitive channels favor established suppliers with captive forging operations.
- Plastic:Ultra-high molecular weight polyethylene inserts remain the bearing surface standard, though vitamin E stabilization and highly cross-linked variants command price premiums. Osteolysis concerns from wear debris constrain marketing to patients under 55, limiting expansion in high-activity segments.
- Ceramic:Alumina matrix composite femoral heads and inserts for reduced wear rates in younger patients.
- Composites:Carbon fiber-reinforced PEEK and polymer-ceramic hybrids for patient-specific applications.
Metal maintains volume leadership, though Ceramic is expanding most quickly in academic medical centers.
End User:
Customer type determines capital equipment requirements, surgeon training investment, and contracting sophistication.
- Hospitals:Inpatient surgical suites with comprehensive implant inventories and robotics capital budgets. United States health systems are consolidating purchasing through value analysis committees that displace individual surgeon preference, with Stryker and Zimmer Biomet anchoring multi-year system contracts.
- Orthopedic Centers:Specialized high-volume facilities where robotic-assisted platform adoption concentrates. Germany's outpatient clinic networks are expanding computer-navigated procedure volumes faster than hospital settings, driven by private payor reimbursement advantages.
- Clinics:Lower-acuity settings handling diagnostic workup and postoperative monitoring.
- Rehabilitation Facilities:Post-acute care sites managing functional recovery protocols.
Hospitals retain the largest procurement scale, yet Orthopedic Centers are gaining share fastest through site-of-service migration.
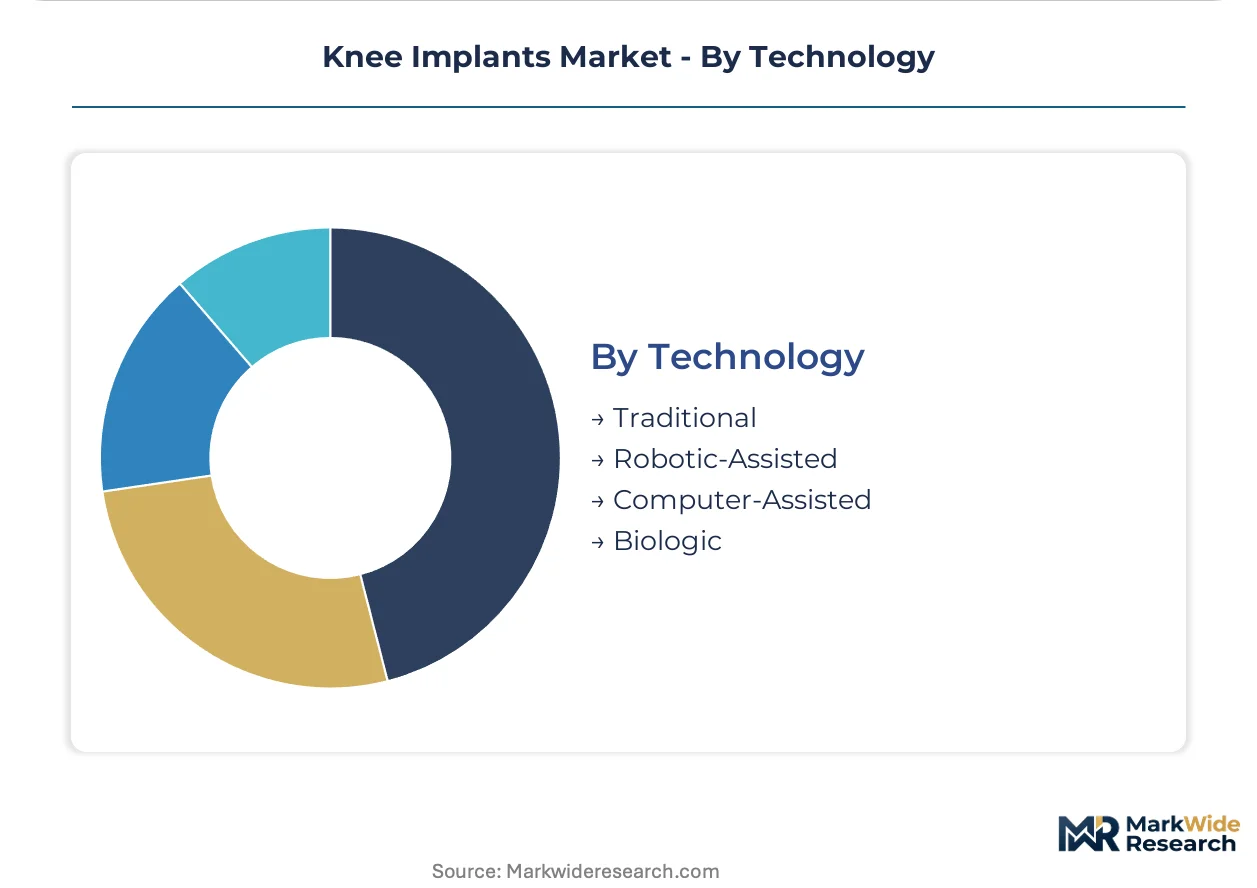
Technology:
Margin structure separates commoditized mechanical systems from premium digital platforms with recurring revenue streams.
- Robotic-Assisted:Computer-navigated implant positioning with preoperative CT planning and intraoperative haptic feedback. United States orthopedic centers are expanding adoption fastest, with Stryker's Mako platform and Zimmer Biomet's ROSA systems commanding premium pricing and disposable instrument attachments.
- Traditional:Mechanical alignment guides and manual instrumentation representing the mature revenue base. Cost pressure from bundled payments in United States and Germany is compressing pricing power, forcing manufacturers to defend position through volume rebates and instrument tray standardization.
- Computer-Assisted:Optical navigation without robotic arm intervention for intermediate positioning accuracy.
- Biologic:Growth factor coatings, porous titanium structures, and osteoconductive surfaces for enhanced fixation.
Traditional technology holds volume dominance, though Robotic-Assisted is climbing the fastest as capital depreciation cycles renew.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that in Germany by a substantial margin, reflecting divergent procurement consolidation timelines. Japan commands premium positioning for revision systems due to demographic concentration. India's domestic manufacturing incentives are reshaping supply geography for South Asian markets.
United States
Integrated delivery networks in Texas and Florida are consolidating implant purchasing through value analysis committees that displace individual surgeon preference. CMS mandatory bundled payment models for joint replacement compress margins but favor suppliers with robotics ecosystems. The Southeast surgical corridor from Atlanta to Tampa anchors outpatient migration volumes.
Germany
Outpatient clinic networks in Bavaria and North Rhine-Westphalia are expanding computer-navigated knee procedures faster than hospital settings. The country's statutory health insurance system imposes reference pricing that caps implant reimbursement premiums. The Berlin-Brandenburg medical technology cluster hosts specialized foundry capacity for cobalt-chromium-molybdenum alloy processing.
Japan
The world's oldest population generates per-capita revision surgery volumes that outpace primary replacement growth. PMDA's revised Pharmaceutical and Medical Device Act imposes quality management system audits extending approval timelines for foreign manufacturers. The Kansai region around Osaka concentrates specialized orthopedic centers handling complex secondary procedures.
India
Rising osteoarthritis prevalence among urban populations is expanding addressable patient pools beyond prior penetration limits. The PLI scheme for medical devices is attracting component suppliers to establish regional production hubs serving South Asian markets. Maharashtra's Mumbai-Pune corridor is emerging as the primary cluster for domestic implant manufacturing scale-up.
United Kingdom
NHS England's Getting It Right First Time program is standardizing implant selection across hospital trusts to reduce unwarranted procedural variation. The Medicines and Healthcare products Regulatory Agency post-Brexit framework maintains alignment with EU MDR clinical evidence requirements. The Midlands surgical hub network is consolidating high-volume knee replacement capacity away from dispersed district general hospitals.
Knee Implants Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying bearing surfaces and fixation coatings to multiple OEMs. The vendor base organizes into three strata: diversified conglomerates with robotics ecosystems, mid-scale orthopedic pure-plays with broad portfolio breadth, and specialized revision component manufacturers. Consolidation pressure favors players with captive manufacturing of cobalt-chromium-molybdenum alloys. Defensive moves center on instrument tray standardization contracts and ambulatory surgery center partnership networks.
Among diversified platform operators, Stryker Corporation and Zimmer Biomet Holdings, Inc. exemplify the integrated robotics-and-implant model that anchors premium positioning within consolidated procurement structures. DePuy Synthes Companies represents the scale-driven manufacturing archetype dominating cost-sensitive hospital procurement channels. These three entities collectively illustrate how competitive position depends on alignment with diverging site-of-service economics.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet Holdings, Inc. |
| DePuy Synthes Companies |
| Smith & Nephew plc |
| Medacta International SA |
| MicroPort Scientific Corporation |
| Exactech, Inc. |
| Corin Group plc |
| B. Braun Melsungen AG |
| Others |
Cost & Logistics Intelligence
German cobalt-chromium-molybdenum foundry concentration anchors input cost volatility that cascades into tiered margin structures downstream. Procurement committees at United States integrated delivery networks exploit this supplier geography to extract volume rebates from manufacturers lacking captive forging operations.
Pricing Analysis
The customization-premium spread separates robotic-assisted system pricing from standard mechanical construct contracts. Three-tier pricing structure across premium, standard, and economy levels reflects FDA clearance tier, volume commitment scale, and after-sales instrument service bundling. Cost compression in standard total knee systems intensifies because bundled payment models cap reimbursement ceilings. Ambulatory surgery centers exhibit highest price sensitivity; academic medical centers with robotics capital budgets show least.
Supply Chain Analysis
Export-control regimes limiting flows of precision machining equipment constrain foundry capacity expansion in Germany and United States. Supply draws from German specialty metal processors, United States forging operations, and Japanese plasma-spray coating facilities. Cobalt-chromium-molybdenum alloy, ultra-high molecular weight polyethylene resin, and titanium fixation substrates constitute critical input dependencies. Single-source vulnerability concentrates in European foundry capacity for femoral component blanks. Distribution runs through hospital procurement consortiums and orthopedic center group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Robotic-assisted platform penetration sits at early-cycle expansion, with outpatient joint replacement reimbursement tailwinds accelerating site-of-service migration faster than historical replacement procedure growth curves.
For Market Incumbents: Harden post-market surveillance infrastructure against EU MDR registry mandates and PMDA quality management audit requirements. Deepen backward integration into cobalt-chromium-molybdenum forging capacity to defend margin position against German foundry supply risk. Consolidate instrument tray standardization contracts before ambulatory surgery center purchasing committees mature. For New Entrants and Emerging Players: India's PLI scheme manufacturing incentives represent the most penetrable entry point for component suppliers seeking regional production scale without German or United States foundry dependence. Ceramic-on-ceramic bearing surfaces for high-activity patient segments offer white-space positioning outside commoditized metal-polyethylene constructs. Pursue hospital system partnership models bundling disposable instruments with implant contracts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed orthopedic pure-plays possessing revision component portfolios but lacking robotics ecosystem integration. Long-term viability centers on manufacturers with FDA 510(k) predicate libraries and EU MDR technical documentation assets. Watch CMS outpatient procedure reimbursement expansion rates as inflection signal for ambulatory surgery center volume migration.| Strategic Initiative | Industry Significance |
|---|---|
| Robotics Ecosystem Integration | Stryker's Mako platform anchors premium positioning within consolidated United States procurement structures. |
| EU MDR Technical Documentation Buildout | Post-market surveillance infrastructure investment separates compliant manufacturers from clearance-denied competitors. |
| Ceramic Bearing Surface Development | Alumina matrix composite technology opens high-activity patient segments previously unsuitable for standard constructs. |
| Ambulatory Surgery Center Partnership Networks | Site-of-service migration favors streamlined implant systems with reduced instrument tray complexity. |
| Captive Cobalt-Chromium-Molybdenum Forging | In-house alloy processing insulates margin pools from German foundry capacity constraints and price volatility. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) premarket notification databases, EU MDR technical documentation filings, and hospital procurement contract registries. Orthopedic surgeons, biomedical engineers, GPO contracts managers, and regulatory affairs specialists provided structured input. Bottom-up implant volume modeling triangulates against top-down procedure frequency estimates from CMS Medicare claims data and Japan's PMDA device registration statistics.
Forecast inputs include procedure volume trajectories, site-of-service migration rates, and robotics adoption curves across the analysis window. Segmentation dimensions span product type complexity tiers, material science grades, end-user facility categories, and technology platform architectures. CAGRs derive from regression analysis against demographic aging indicators and reimbursement policy shifts. EU MDR implementation timelines and CMS outpatient coverage expansion feed directly into scenario-weighted projections.
Macroeconomic conditions sit as an overlay; deviation in elective procedure deferral rates, specialty metal commodity pricing, or reimbursement threshold adjustments would shift the trajectory. Forecasts reflect assumptions about regulatory clearance continuity and supply chain geographic stability. Material shifts in FDA 510(k) predicate scrutiny intensity or German foundry capacity constraints would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Spine Devices Market
Orthopedic Devices
Orthopedic Prosthetic Devices Market
Orthopedic Devices
Orthopaedic Cushions Market
Orthopedic Devices
Physiotherapy Devices Market
Orthopedic Devices
Polyethylene Orthopaedic Insert Market
Orthopedic Devices
Orthobiologics Market
Orthopedic Devices
South Korea Spinal Surgery Devices Market
Orthopedic Devices
Middle East and Africa Knee Cartilage Repair Market
Orthopedic Devices
Spinal Surgery Devices Market
Orthopedic Devices
Patient Lifts Market
Orthopedic Devices
Vertebroplasty Needles Market
Orthopedic Devices
Podiatry Laser Market
Orthopedic Devices
Dental Orthotic Devices Market
Orthopedic Devices
Personalized Orthopaedic Implant Market
Orthopedic Devices
Global Orthopedic Implant Market
Orthopedic Devices
Orthopedic Bone Cement and Casting Materials Market