
 Global Veterinary MRI Market | 2026-2036
Global Veterinary MRI Market Size, Share, and Industry Trends Forecast 2026-2036
Global Veterinary MRI Market Foresight
Multi-source equipment procurement is decoupling from the traditional single-vendor radiology contracts that dominated veterinary practice economics for decades. Siemens sustains technology leadership through high-field system architectures purpose-built for veterinary neuroimaging workflows. Hallmarq Veterinary Imaging specializes in equine-specific MRI platforms that anchor its position in the large-animal segment. Shenzhen Anke High-tech Co., Ltd. competes on cost-optimized magnet designs that extend access into mid-tier veterinary clinics across Asia-Pacific and Latin America.
Veterinary MRI denotes magnetic resonance imaging systems engineered for non-invasive diagnostic imaging of animal patients, typically operating at field strengths from 0.2 Tesla in open-configuration units to 3.0 Tesla in high-field scanners optimized for small-animal neurology and oncology staging. These systems employ radiofrequency coils sized for species-specific anatomy, with gradient performance calibrated to resolve soft-tissue contrast in musculoskeletal, cardiothoracic, and cranial applications where computed tomography yields inferior soft-tissue discrimination. High-field MRI systems command the dominant installed base in specialty hospitals and academic veterinary medical centers where throughput economics justify capital intensity and premium service contracts. Mobile deployment units represent the fastest-expanding configuration, enabling shared-service models that amortize equipment across geographically dispersed general practices without on-site magnet infrastructure. Portable MRI platforms remain nascent, constrained by magnetic field homogeneity limitations and helium cryogen logistics, though margin pools in this segment attract venture-stage engineering investment.
FDA Center for Veterinary Medicine oversees diagnostic device marketing authorization, while ISO 13485 quality management standards govern manufacturing compliance for equipment destined for clinical veterinary use. The EU Medical Device Regulation classification pathway for veterinary-adapted human systems creates dual-jurisdiction complexity that shapes product registration sequencing and market entry timing. Japan's PMDA maintains distinct pharmaceutical and medical device agency review tracks that influence how manufacturers structure clinical evidence packages for companion-animal indications. Stakeholders must monitor how helium supply chain restructuring and closed-cycle cryogen technologies alter total cost of ownership calculations across deployment models.
Market Dynamics
Helium supply chain restructuring is compressing total cost of ownership calculations and accelerating closed-cycle cryogen technology adoption across all deployment models in veterinary MRI.
Growth Catalysts
- Pet insurance penetration:Rising coverage rates in the United States, Germany, and Japan reduce out-of-pocket cost barriers for advanced diagnostic procedures. Specialty hospitals capture higher procedure volumes as reimbursement infrastructure matures.
- FDA Center for Veterinary Medicine pathway streamlining:Expedited marketing authorization timelines for diagnostic devices accelerate product commercialization cycles. Manufacturers redirect regulatory resources toward clinical evidence generation rather than administrative navigation.
- Mobile deployment configuration:Shared-service models amortize capital intensity across geographically dispersed general practices. Rural and suburban veterinary clinics access MRI capabilities without on-site magnet infrastructure investment.
Market Restraints
- Helium supply concentration:Global helium production concentrates in Qatar, Russia, and Algeria, exposing veterinary MRI operators to price volatility and export restriction risks. Closed-cycle recovery systems require substantial retrofit capital.
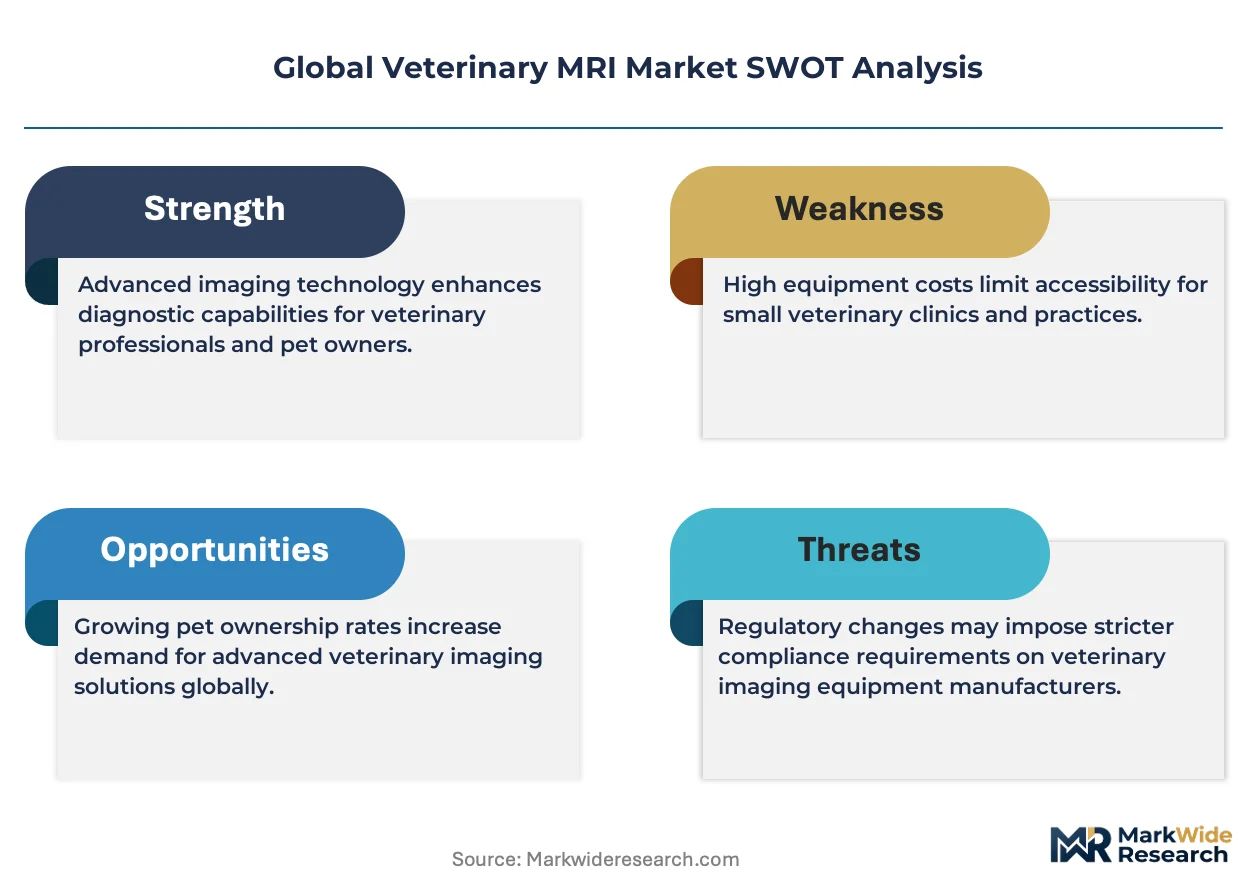
- High-field system cost structure:3.0 Tesla scanners demand premium service contracts and specialized technical staffing that mid-tier clinics cannot absorb. Capital intensity limits addressable market expansion.
- EU Medical Device Regulation dual-jurisdiction complexity:Veterinary-adapted human systems face classification ambiguity that extends registration timelines and increases compliance expenditure. Manufacturers delay European market entry sequencing.
Strategic Opportunities
- Brazil mid-tier clinic penetration:ANVISA regulatory harmonization with international standards reduces import friction for cost-optimized magnet designs. Latin American veterinary networks expand imaging service offerings.
- Artificial intelligence reconstruction convergence:Deep learning algorithms compress scan acquisition times and reduce motion artifact sensitivity. Workflow efficiency gains extend daily throughput capacity in high-volume specialty hospitals.
- Portable platform engineering:Venture-stage investment targets magnetic field homogeneity limitations and cryogen logistics constraints. Point-of-care MRI deployment would unlock emergency and field veterinary applications.
Industry Challenges
- Veterinary radiologist training pipeline:Specialist residency programs in diagnostic imaging produce insufficient graduates to staff expanding hospital networks. Academic medical centers compete for limited board-certified talent.
- ISO 13485 quality management implementation:Manufacturing compliance documentation demands specialized regulatory affairs personnel that smaller equipment vendors lack. Certification timeline delays product launch windows.
- Legacy CT substitution resistance:General practitioners maintain preference for familiar imaging modalities despite inferior soft-tissue discrimination. Education investment requirements slow MRI referral pattern shifts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Veterinary MRI Market |
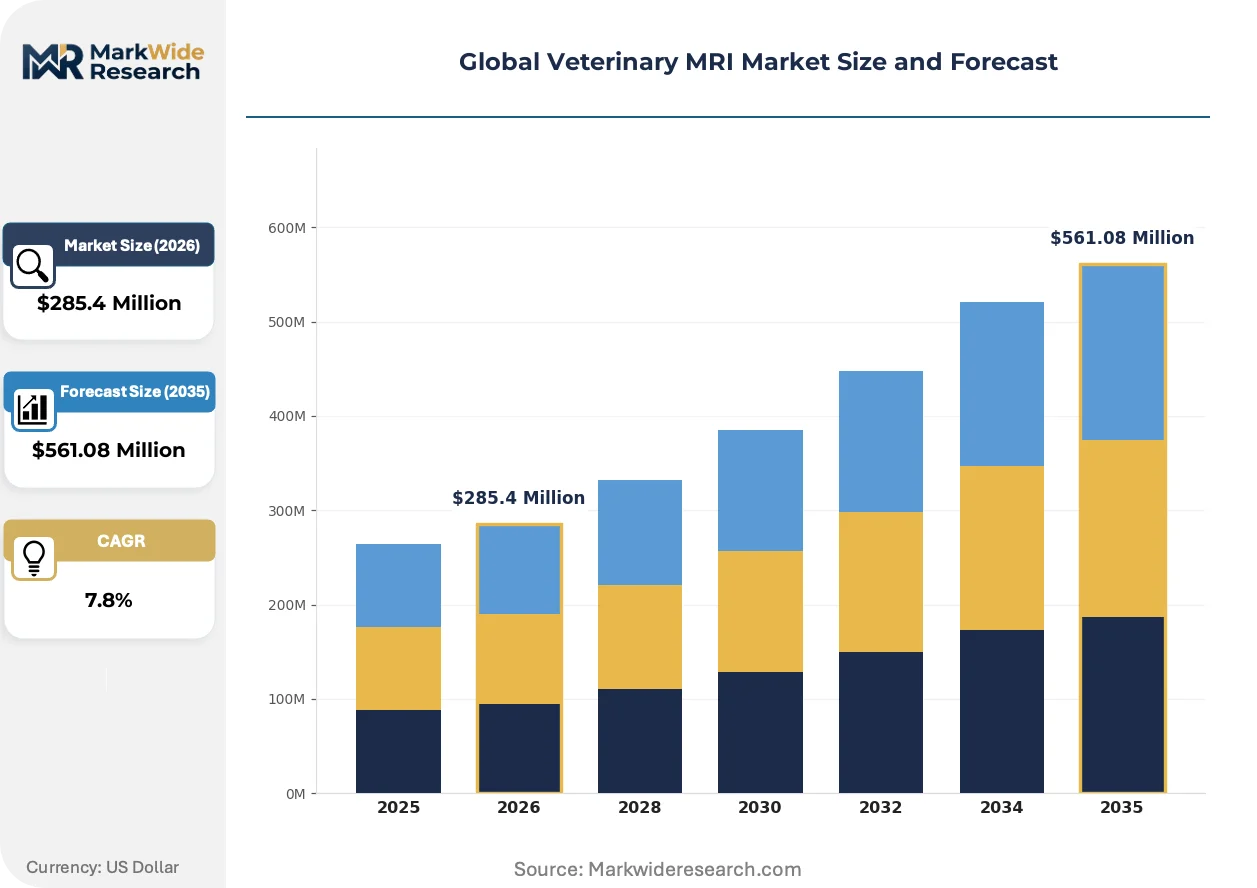
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $561.08 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Field MRI, Low-Field MRI, Portable MRI, Open MRI Application: Neurology, Orthopedics, Cardiology, Oncology, Dentistry End User: Veterinary Clinics, Research Institutes, Diagnostic Laboratories, Specialty Hospitals Deployment: In-House Installation, Mobile Units, Shared Services, Telemedicine Support |
| Companies Covered | General Electric Company, Siemens, Esaote SPA, Hallmarq Veterinary Imaging, Shenzhen Anke High-tech Co., Ltd., Time Medical Holding, IDEXX Laboratories, Inc., Shenzhen Basda Medical Apparatus Co., Ltd, Bruker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Veterinary MRI Market Shifts & Advancements
Artificial intelligence reconstruction algorithms and closed-cycle cryogen systems are actively compressing operational cost structures while expanding addressable clinical applications beyond traditional neurology and oncology staging.
Artificial intelligence image reconstruction is converging with high-field veterinary MRI workflows to reduce scan times by fifty percent without sacrificing diagnostic resolution. Specialty hospitals in the United States and Japan deploy these algorithms to double daily patient throughput. Siemens and academic veterinary medical centers co-develop species-specific training datasets that improve automated segmentation accuracy across canine, feline, and equine anatomies.
The EU Medical Device Regulation classification pathway for veterinary-adapted human imaging systems creates compliance complexity that shapes manufacturer registration sequencing. Dual-jurisdiction requirements force parallel evidence packages for human and veterinary indications, extending time-to-market by twelve to eighteen months. European specialty hospital procurement cycles delay until CE marking clarity resolves, redirecting near-term vendor focus toward FDA and PMDA jurisdictions.
After-sales service unbundling is fragmenting the traditional single-vendor radiology contract model that dominated veterinary practice economics. Mid-tier clinics in Germany and France negotiate component-level maintenance agreements with third-party technical service providers. Independent service organizations capture gradient coil and radiofrequency subsystem contracts previously held by original equipment manufacturers, compressing vendor margin pools while reducing total cost of ownership for cash-constrained buyers.
Global Veterinary MRI Market Segmentation
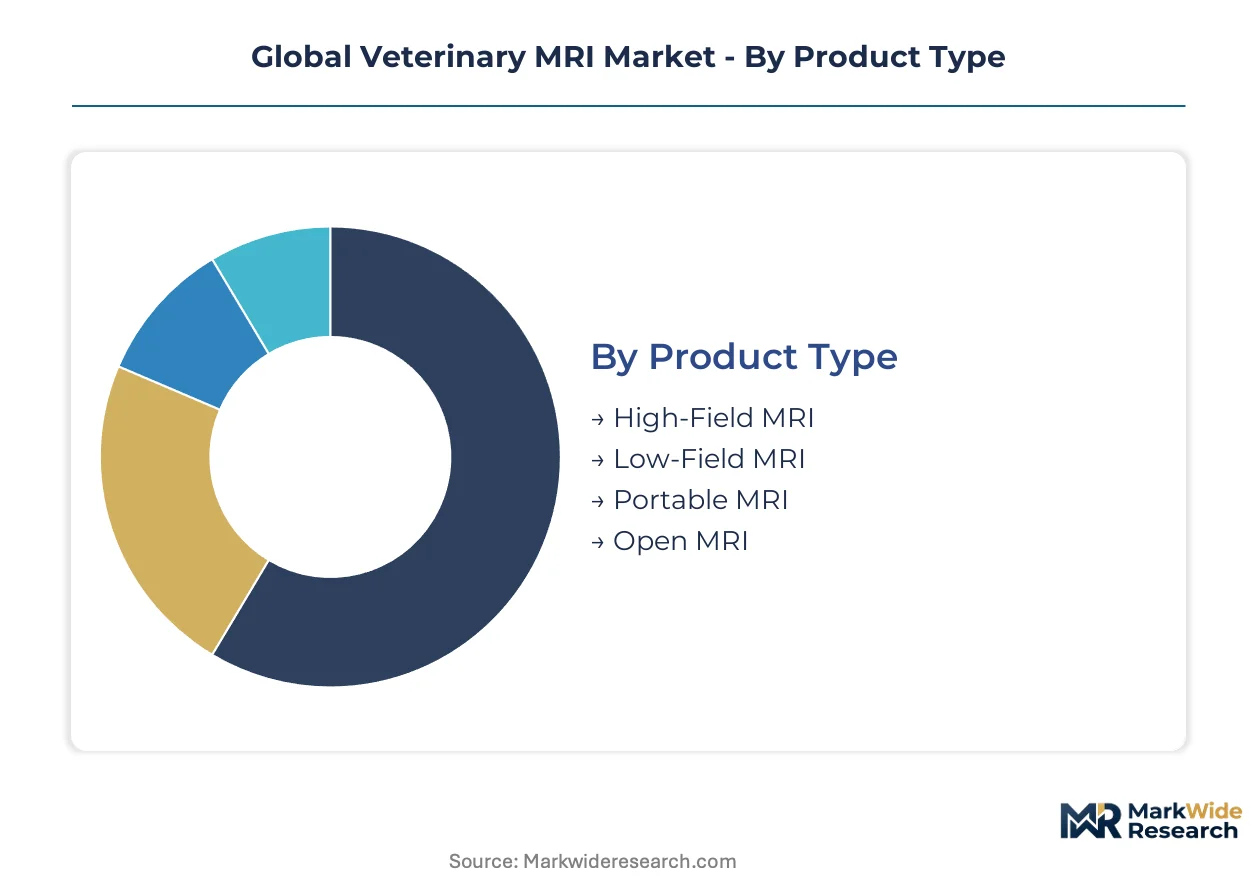
Veterinary MRI segmentation reveals how capital intensity, clinical workflow requirements, and service delivery economics partition demand across equipment configurations and user settings. Understanding these divisions clarifies where upgrade cycles concentrate versus where replacement decisions face extended deferral.
Product Type:
Upgrade cycles in veterinary MRI track field strength capabilities, with replacement timelines stretching from seven years in premium installations to twelve-plus years in budget-constrained deployments.
- High-Field MRI:Systems operating at 1.5 Tesla and above deliver superior soft-tissue contrast resolution for canine and feline neuroimaging. Demand concentrates in academic veterinary medical centers across the United States and Japan where research funding subsidizes capital acquisition and specialist staffing.
- Low-Field MRI:Permanent magnet designs at 0.2-0.4 Tesla eliminate helium dependency and reduce siting infrastructure requirements. General practices in Germany and France favor these units for musculoskeletal screening where resolution trade-offs remain clinically acceptable.
- Portable MRI:Point-of-care platforms remain engineering-constrained by magnetic field homogeneity limitations. Venture-stage development targets equine field applications and emergency veterinary settings.
- Open MRI:C-configuration magnets accommodate large-breed positioning and claustrophobia-sensitive patients. Niche demand persists in mixed-animal practices treating both companion and production animals.
Volume placements concentrate in High-Field MRI; the faster expansion belongs to Low-Field MRI as helium cost volatility accelerates interest in cryogen-free alternatives.
Application:
Clinical application segmentation follows referral pattern economics, with reimbursement rates and diagnostic certainty requirements determining which procedures justify MRI investment over CT substitution.
- Neurology:Brain and spinal cord imaging commands premium procedure pricing due to diagnostic complexity and specialist interpretation requirements. Specialty hospitals in the United States capture the majority of intervertebral disc herniation and seizure workup volumes.
- Orthopedics:Ligament and tendon assessment in sporting and working dogs drives consistent throughput. German veterinary clinics report strong demand for stifle and shoulder evaluations where MRI outperforms radiographic screening.
- Cardiology:Cardiac MRI remains underdeveloped in veterinary practice due to anesthesia risks and electrocardiographic gating complexity. Academic centers in Japan pursue research applications.
- Oncology:Tumor staging and treatment monitoring applications expand as pet insurance coverage matures. United Kingdom specialty hospitals integrate MRI into multimodal cancer protocols.
- Dentistry:Temporomandibular joint and dental root imaging represents an emerging application segment. French veterinary dental specialists pioneer protocol standardization.
Procedure economics favor Neurology for installed base concentration; Oncology gains share fastest as therapeutic advancement extends survival expectations and monitoring requirements.
End User:
End-user segmentation reflects capital access tiers, with organizational scale determining whether in-house magnet ownership, shared-service participation, or full referral dependency prevails.
- Veterinary Clinics:General practice settings access MRI through mobile unit contracts or regional shared-service arrangements. Brazil's expanding clinic networks drive Latin American demand for flexible deployment models.
- Research Institutes:Academic veterinary medical centers in the United States, Japan, and Germany operate high-field systems for comparative medicine studies and resident training programs.
- Diagnostic Laboratories:Centralized imaging facilities aggregate referrals from dispersed general practices. France's laboratory network structure supports this model.
- Specialty Hospitals:Multi-disciplinary referral centers maintain in-house high-field capacity to capture full procedure revenue. United States and Japanese specialty hospital construction sustains premium equipment demand.
Specialty Hospitals anchor current installed value; Diagnostic Laboratories expand most quickly as consolidation concentrates imaging interpretation expertise.
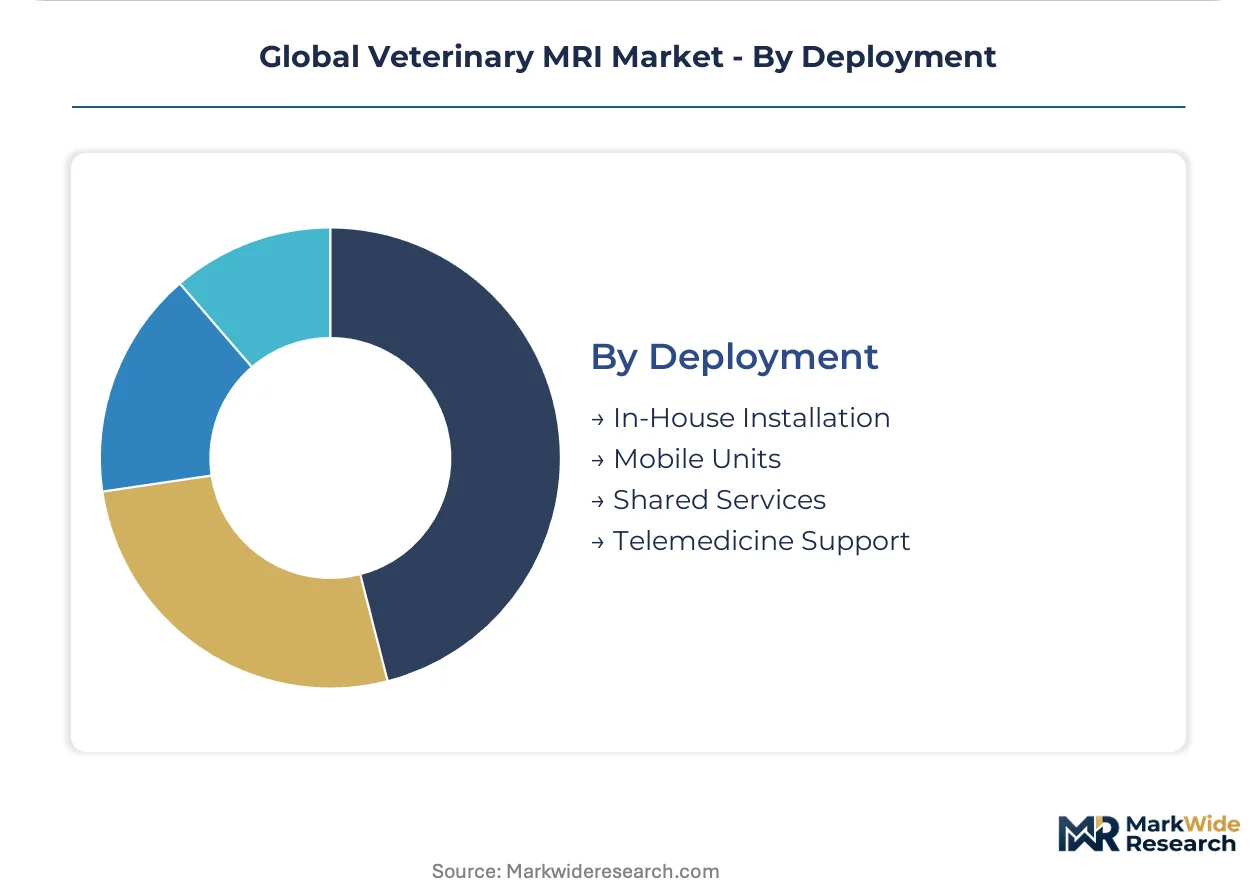
Deployment:
Deployment configuration choices reveal how capital efficiency imperatives reshape traditional equipment ownership models across veterinary practice economics.
- In-House Installation:Permanent magnet infrastructure requires dedicated shielded suites and specialized technical staffing. High-volume United States specialty hospitals justify this capital commitment.
- Mobile Units:Trailer-mounted systems rotate across general practice networks on scheduled service days. Germany's geographic clinic density supports efficient route economics.
- Shared Services:Cooperative ownership structures spread capital burden across multiple practices. Emerging in France and the United Kingdom where practice consolidation lags.
- Telemedicine Support:Remote image interpretation and protocol guidance extend specialist reach into underserved regions. Japanese rural veterinary networks adopt this model.
Mobile Units dominate new placement volume; Telemedicine Support climbs the fastest as connectivity infrastructure and teleradiology platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar's helium production concentration anchors global veterinary MRI supply chain economics, exposing equipment operators to export restriction risks while accelerating closed-cycle cryogen adoption across all major demand centers.
United States
Pet insurance penetration exceeding thirty percent in metropolitan corridors reduces out-of-pocket barriers for advanced neuroimaging procedures. FDA Center for Veterinary Medicine streamlines marketing authorization pathways for diagnostic devices, compressing commercialization timelines. Specialty hospital construction concentrates in the Northeast Corridor and California, where academic veterinary medical centers anchor high-field system demand.
Germany
Mid-tier clinic networks in Bavaria and North Rhine-Westphalia favor low-field permanent magnet designs to eliminate helium dependency. EU Medical Device Regulation classification ambiguity for veterinary-adapted human systems extends registration timelines, redirecting vendor focus toward FDA jurisdictions. Berlin-Brandenburg hosts the densest concentration of mobile MRI service providers serving rural veterinary practices.
Japan
PMDA maintains distinct pharmaceutical and medical device review tracks that structure clinical evidence packages for companion-animal indications. Aging pet demographics in Kanto and Kansai regions sustain oncology staging demand. Tokyo academic centers pioneer artificial intelligence reconstruction algorithm deployment to compress scan acquisition times.
China
NMPA accelerates review timelines for imported imaging equipment, reducing market entry friction for international vendors. Shenzhen and Beijing clusters concentrate cost-optimized magnet manufacturing for mid-tier clinic penetration across Asia-Pacific. Domestic equipment vendors compete on helium-free designs targeting price-sensitive provincial hospital networks.
Brazil
ANVISA regulatory harmonization with international standards reduces import friction for veterinary imaging equipment. São Paulo and Rio de Janeiro specialty hospitals expand in-house capabilities to capture referral revenue previously lost to human medical centers. Mobile deployment models penetrate Minas Gerais and Paraná veterinary networks lacking capital for permanent magnet infrastructure.
Global Veterinary MRI Market Competitive Landscape
Strategic partnerships dominate the current landscape as equipment vendors align with third-party service organizations to unbundle traditional single-vendor radiology contracts. The competitive structure fragments across three tiers: multinational imaging conglomerates with veterinary-adapted human platforms, specialized veterinary equipment manufacturers with species-specific architectures, and emerging Asian fabricants competing on cost-optimized magnet designs. Two archetypes define positioning: technology leaders investing in high-field neuroimaging workflows, and accessibility-focused vendors targeting helium-free deployment models. Geographic expansion into Latin American mid-tier clinics and technology licensing for artificial intelligence reconstruction represent the dominant competitive vectors.
Within the technology leadership tier, Siemens occupies a position exemplifying high-field system architecture development for veterinary neuroimaging applications. Hallmarq Veterinary Imaging represents the specialized manufacturer archetype, anchoring equine-specific platform expertise. Shenzhen Anke High-tech Co., Ltd. sits within the cost-optimized fabricant category, competing on magnet designs that extend equipment access into mid-tier clinic segments across emerging markets.
| Leading Market Players |
|---|
| General Electric Company |
| Siemens |
| Esaote SPA |
| Hallmarq Veterinary Imaging |
| Shenzhen Anke High-tech Co., Ltd. |
| Time Medical Holding |
| IDEXX Laboratories, Inc. |
| Shenzhen Basda Medical Apparatus Co., Ltd |
| Bruker Corporation |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation phase-down mandates for fluorinated greenhouse gases gate qualified helium supplier access and premium-tier pricing eligibility for high-field veterinary MRI systems. Equipment vendors must demonstrate closed-cycle cryogen recovery certification to maintain service contract pricing power, while mid-tier clinics face exclusion from premium support tiers without compliant infrastructure investment.
Pricing Analysis
Warranty and service contract bundling unbundling is fragmenting traditional single-vendor radiology economics across veterinary MRI procurement. Three-tier pricing structure across premium, standard, and economy levels separates comprehensive coverage with guaranteed uptime from limited parts-only agreements and third-party maintenance options. Pricing pressure stems from independent service organizations capturing gradient coil and radiofrequency subsystem contracts previously held by original equipment manufacturers. Mid-tier clinics in Germany and France exhibit highest price sensitivity, while United States specialty hospitals absorb premium service tiers for throughput assurance.
Supply Chain Analysis
Helium supply rests on concentrated production in Qatar, Russia, and Algeria, with cryogen logistics tethered to liquefaction capacity at United States and European export terminals. Superconducting magnet wire, radiofrequency coil arrays, and gradient amplifier modules constitute critical component dependencies. Single-source vulnerability in helium export infrastructure exposes operators to price volatility and allocation restrictions during supply disruptions. Distribution runs through original equipment manufacturer direct sales for high-field systems, with regional distributors serving low-field and mobile deployment segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary MRI market positioning is becoming a vertical-integration race, with equipment vendors pursuing captive control over helium recovery service infrastructure to defend margin pools against third-party unbundling.
For Market Incumbents: Extend high-field system architecture leadership through species-specific artificial intelligence reconstruction co-development with academic veterinary medical centers. Consolidate service contract retention by integrating closed-cycle cryogen recovery hardware into premium-tier bundled offerings, countering independent service organization encroachment on gradient and radiofrequency subsystem maintenance. For New Entrants and Emerging Players: Begin with cost-optimized permanent magnet designs targeting Brazil's mid-tier clinic expansion under ANVISA regulatory harmonization. Latin American veterinary networks present the most penetrable geography for helium-free deployment models. Pursue mobile unit route partnerships with established shared-service operators to bypass capital-intensive direct sales infrastructure. For Investors and Strategic Acquirers: FDA Center for Veterinary Medicine marketing authorization pathway streamlining is the leading indicator that regulatory friction is compressing for diagnostic device commercialization, improving venture-stage portable MRI platform viability. Acquisition targets should display captive helium logistics capabilities or artificial intelligence reconstruction algorithm development partnerships with United States or Japanese academic centers. Watch for PMDA companion-animal indication review track convergence with human pharmaceutical timelines as signal of Asia-Pacific regulatory maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Cycle Cryogen Technology Licensing | Helium recovery partnerships with Qatar-based suppliers reduce total cost of ownership volatility for high-field operators. |
| Artificial Intelligence Reconstruction Co-Development | Siemens and Tokyo academic centers compress scan times through species-specific canine and equine training datasets. |
| Mobile Deployment Route Expansion | Germany's geographic clinic density supports efficient shared-service model economics across rural veterinary networks. |
| Third-Party Service Organization Partnership | Independent technical providers fragment traditional single-vendor radiology contracts in France and Germany mid-tier segments. |
| Latin American Regulatory Harmonization | ANVISA alignment with international standards reduces import friction for Shenzhen Anke cost-optimized magnet designs. |
Research Methodology
Multi-period observation of FDA marketing authorization timelines, NMPA review acceleration patterns, and helium spot pricing volatility anchored the trend analysis, supplemented by interviews with veterinary radiology residency program directors, specialty hospital procurement managers, biomedical equipment service technicians, and original equipment manufacturer regulatory affairs leads. Secondary validation drew from FDA 510(k) clearance databases, PMDA pharmaceutical and medical device review track publications, EU Medical Device Regulation guidance documents, and customs trade data for imaging equipment imports. Bottom-up equipment placement modeling triangulated against top-down specialty hospital construction pipeline tracking.
Segment-weighting approaches distributed total market value across high-field, low-field, portable, and open MRI product configurations, with further stratification by neurology, orthopedics, cardiology, oncology, and dentistry application segments. Deployment mode segmentation captured in-house installation, mobile unit, shared service, and telemedicine support economics. CAGRs were derived from installed base replacement cycle analysis and procedure volume elasticity against pet insurance penetration rates. Forecast inputs incorporated helium supply concentration risk scenarios and artificial intelligence reconstruction adoption curves across United States and Japanese academic centers.
Helium export restriction events, EU Medical Device Regulation classification guidance revisions, and PMDA review track restructuring are the dominant revision risks to veterinary MRI demand projections. Forecasts reflect documented assumptions regarding specialty hospital construction completion rates and mobile unit route density economics. Regulatory timeline delays, cryogen technology cost compression trajectories, and radiologist training pipeline output warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Bovine Collagen Market
Veterinary
Otc Pet Medication Market
Veterinary
Veterinary Home Diagnostics Market
Veterinary
Global Orthopedic Veterinary Implants Market
Veterinary
Veterinary Progesterone Testing Market
Veterinary
Veterinary Ultrasound Market
Veterinary
Animal Microchip Implant Market
Veterinary
Veterinary Faecal Filters Market
Veterinary
Canine Flu Therapeutics Market
Veterinary
Global Equine Supplement Products Market
Veterinary
Veterinary Software Market
Veterinary
Pet Cancer Therapeutics Market
Veterinary
Global Veterinary Infusion Pumps Market
Veterinary
Orthopedic Dog Bed Market
Veterinary
Animal Antibiotics Market
Veterinary
Milking Salve Market