
 Global Cattle Vaccines Market | 2026-2036
Global Cattle Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cattle Vaccines Market Foresight
Dairy farm procurement is rebalancing toward preventive health programs as operators shift from curative antibiotics to scheduled vaccination protocols. Zoetis leverages its recombinant platform to anchor North American dairy supply chains with clostridial and respiratory combination products. Boehringer Ingelheim International GmbH sustains manufacturing scale across European bovine health networks. Merck & Co., Inc. competes through R&D intensity in modified-live viral vector development for emerging respiratory pathogens.
Cattle vaccines are biological preparations containing attenuated or inactivated pathogens, recombinant proteins, or nucleic acid constructs formulated to induce adaptive immunity in Bos taurus and Bos indicus species, typically requiring cold-chain storage at two to eight degrees Celsius and adjuvant stabilization for field efficacy. Their primary purpose is to reduce morbidity, mortality, and production losses across commercial beef and dairy operations while supporting herd-level disease eradication goals. Live attenuated products dominate current volume due to established cold-chain infrastructure and cost efficiency in mass administration programs, though mRNA technology segments are attracting development capital for rapid strain-matching against antigenically variable pathogens. Subunit formulations occupy premium positioning where DIVA-compliant differentiation of infected from vaccinated animals unlocks export market access for national herd health programs.
USDA licensing requirements under the Virus-Serum-Toxin Act shape product approval timelines and field efficacy standards for manufacturers seeking US market entry, while OIE Terrestrial Animal Health Code provisions influence cross-border trade eligibility for vaccinated herds. EMA veterinary medicine regulations and REACH adjuvant safety assessments constrain formulation choices within European commercialization pathways. Stakeholders must monitor mRNA platform regulatory precedents as FDA Center for Veterinary Medicine and Brazil's national agricultural regulator develop novel biologic assessment frameworks that will determine speed-to-market for next-generation candidates.
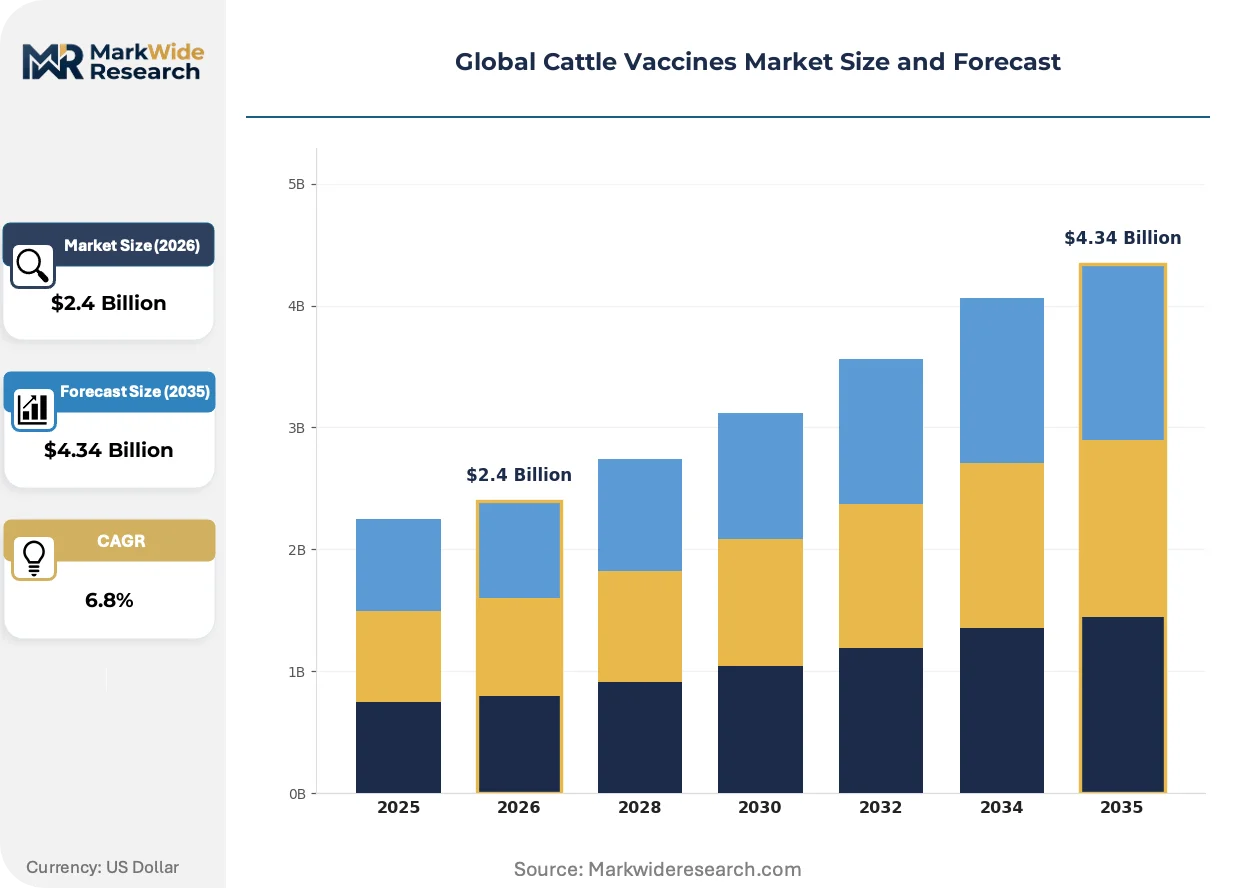
Market Dynamics
Foot-and-mouth disease eradication mandates under USDA and OIE guidelines are compressing procurement cycles toward preventive health programs, forcing feedlot operators to consolidate veterinary supply contracts around scheduled vaccination protocols rather than curative interventions.
Growth Catalysts
- OIE Terrestrial Animal Health Code alignment:National herd health programs in Brazil and Argentina are unlocking export market access through DIVA-compliant subunit formulations, accelerating replacement of conventional vaccines.
- Feedlot consolidation in Mato Grosso:Large-scale Brazilian operators are bundling preventive health spend into multi-year veterinary supply contracts, concentrating demand for combination respiratory-clostridial products.
- mRNA platform maturation:Rapid strain-matching capabilities against antigenically variable pathogens are attracting development capital from institutional investors targeting emerging disease variants.
Market Restraints
- Adjuvant input cost volatility:REACH safety assessments constrain formulation choices for aluminum-based and oil-in-water adjuvants, compressing margin structures for European manufacturers.
- Cold-chain infrastructure gaps:Last-mile refrigeration failures in tropical ranching zones degrade live attenuated product efficacy, limiting penetration in Indonesian and Nigerian cattle corridors.
- Regulatory timeline friction:FDA Center for Veterinary Medicine licensing under the Virus-Serum-Toxin Act extends approval windows for novel biologics, delaying commercialization of nucleic acid constructs.
Strategic Opportunities
- Underpenetrated Indonesian smallholder segment:Fragmented dairy cooperatives in East Java lack access to bulk purchasing programs, creating white space for mobile vaccination units and subscription-based herd health services.
- Technology convergence of mRNA and DIVA diagnostics:Paired platforms enabling simultaneous vaccination and serological differentiation are opening premium positioning for export-certified operations in Uruguay and New Zealand.
- Channel innovation through veterinary telemedicine:Remote prescribing platforms in Australian outback stations are bypassing traditional distributor networks, shortening reorder cycles for respiratory combination products.
Industry Challenges
- Specialized cold-chain logistics talent scarcity:Qualified technicians for two-to-eight-degree Celsius handling are concentrated in urban veterinary hubs, complicating rural deployment in the Brazilian Pantanal and Australian Northern Territory.
- Legacy system integration complexity:Digital herd management platforms require API compatibility with existing RFID ear-tag databases, slowing adoption among Argentine estancias with decades-old record-keeping infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cattle Vaccines Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Attenuated, Inactivated, Subunit, DNA Administration Route: Intramuscular, Subcutaneous, Oral, Intranasal End User: Dairy Farms, Beef Farms, Veterinary Clinics, Research Institutions Technology: Recombinant, MRNA, Viral Vector, Protein-Based |
| Companies Covered | Zoetis, Boehringer Ingelheim International GmbH, Merck & Co., Inc., Elanco Animal Health, Ceva Santé Animale, Virbac, Phibro Animal Health Corporation, Biogénesis Bagó S.A., Hipra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cattle Vaccines Market Shifts & Advancements
Biologic platform diversification is fragmenting competitive positioning across the cattle vaccines value chain, with recombinant and nucleic acid technologies compressing the dominance of live attenuated formulations while regulatory frameworks scramble to keep pace with validation protocols.
Recombinant subunit vaccines are modularizing disease coverage for clostridial and respiratory pathogens, enabling antigen-specific formulation without live virus handling. Large-scale dairy operations in Wisconsin and California are adopting these platforms to simplify cold-chain requirements and reduce biosafety containment costs. This modularization is compressing the traditional trade-off between efficacy and operational flexibility, allowing customized combination products for regional pathogen profiles.
EMA veterinary medicine regulations are tightening adjuvant safety documentation under REACH-aligned hazard assessments, forcing reformulation of legacy mineral oil emulsions. Manufacturers serving European bovine health networks are accelerating transitions to saponin and liposome-based alternatives. Subunit and inactivated product categories face the steepest compliance burdens, with German and Dutch formulation specialists investing in toxicology dossiers to maintain market access.
Consolidated procurement through integrated beef processors is displacing independent veterinary distributor relationships in North American feedlot networks. Cargill and JBS are negotiating direct supply agreements with manufacturers for respiratory combination products, compressing margins for regional distributors in Kansas and Texas. This concentration is most visible in the US High Plains feedlot belt, where thousand-head operations now specify vaccine protocols in processor-aligned husbandry contracts.
Global Cattle Vaccines Market Segmentation
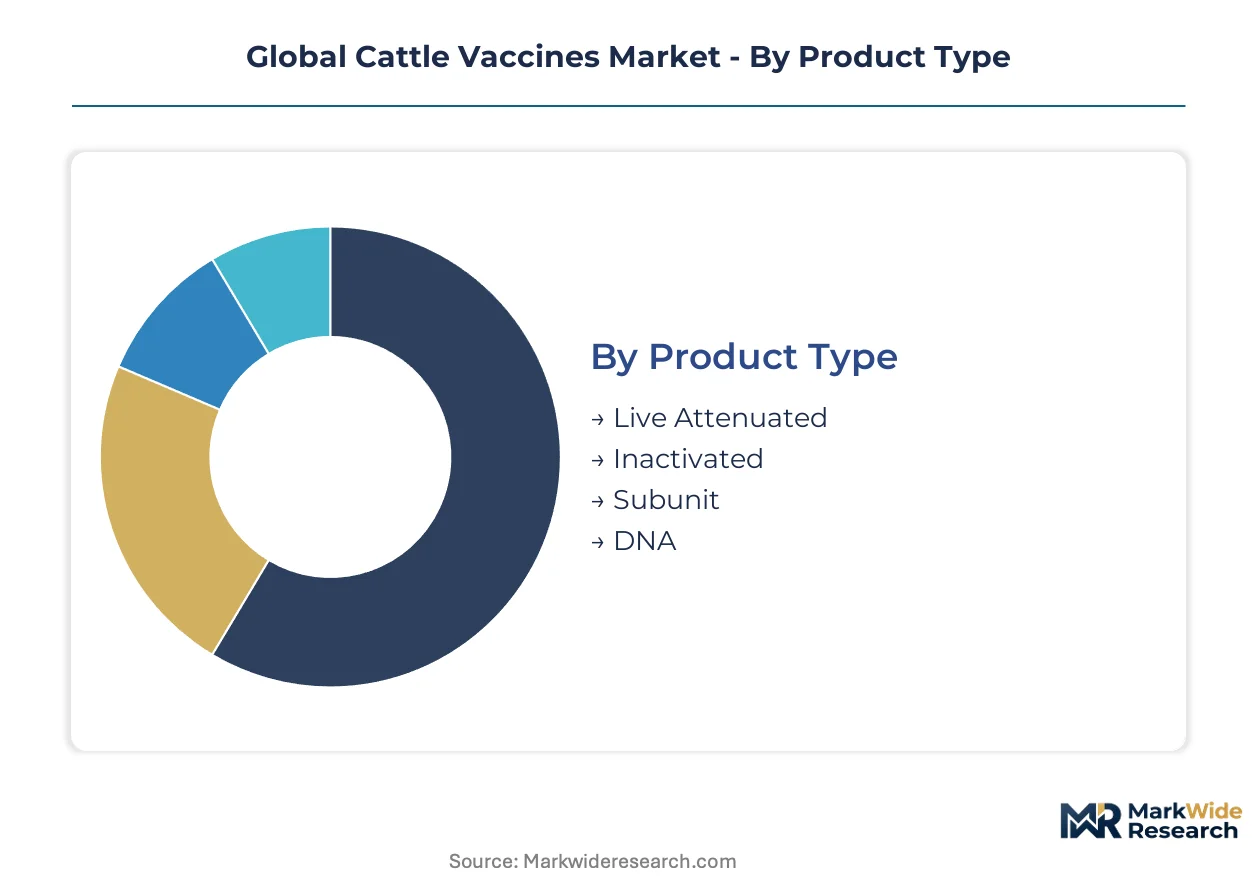
Cattle vaccine procurement splits across four critical dimensions: biologic platform sophistication, delivery method logistics, customer operational scale, and manufacturing technology maturity. Each axis captures distinct margin structures, cold-chain requirements, and regulatory approval pathways that shape vendor competitive positioning.
Product Type:
Buyers prioritize efficacy-to-cost ratios and cold-chain feasibility when selecting biologic platforms for herd-scale deployment.
- Live Attenuated:Formulations containing weakened pathogenic organisms stimulate robust cellular immunity with single-dose protocols. Demand clusters in Brazil's Mato Grosso feedlot belt where thousand-head operations require cost-efficient mass administration without booster schedules. Cold-chain infrastructure investments by JBS and Minerva Foods anchor procurement concentration.
- Inactivated:Killed-pathogen preparations with mineral oil or aluminum hydroxide adjuvants deliver stable shelf-life profiles suited to fragmented distribution networks. Nigerian and Indonesian smallholder cooperatives favor these products where refrigeration continuity cannot be guaranteed across tropical ranching corridors.
- Subunit:Purified antigen formulations enable DIVA-compliant serological differentiation for export-certified herds in Uruguay and New Zealand.
- DNA:Nucleic acid constructs encoding pathogen-specific antigens remain developmental-stage candidates with regulatory pathways under FDA Center for Veterinary Medicine review.
Volume sits with Live Attenuated; growth tilts toward Subunit as OIE Terrestrial Animal Health Code alignment accelerates.
Administration Route:
Logistics costs and labor availability at the ranch level determine delivery method selection across climatic and operational contexts.
- Intramuscular:Deep tissue injection of oil-adjuvanted formulations ensures prolonged antigen release and durable antibody titers. Large-scale dairy operations in Wisconsin and California specify this route for clostridial combination products in automated chute systems.
- Subcutaneous:Loose connective tissue deposition reduces carcass blemish risk and enables less-skilled technician administration. Australian outback stations deploy this method where qualified veterinary labor is scarce across the Northern Territory.
- Oral:Feed-additive or bolus delivery bypasses handling stress in extensive grazing systems across the Brazilian Pantanal.
- Intranasal:Mucosal application targets respiratory pathogen entry points with rapid local immunity induction in preconditioned feedlot arrivals.
Intramuscular commands current throughput; Intranasal is climbing the fastest as respiratory disease pressure intensifies in receiving protocols.
End User:
Customer scale and regulatory exposure create divergent purchasing patterns across the value chain.
- Dairy Farms:High-frequency milking operations with intensive housing density demand scheduled respiratory and clostridial protocols. Preventive health rebalancing in North American supply chains concentrates procurement through direct manufacturer relationships with Zoetis and Boehringer Ingelheim.
- Beef Farms:Extensive grazing and feedlot finishing operations prioritize combination products with broad pathogen coverage. Consolidated processor contracts through Cargill Protein Group and JBS USA are displacing independent distributor relationships in Kansas and Texas.
- Veterinary Clinics:Mixed-animal practices serve as technical advisors and procurement intermediaries for smaller operations.
- Research Institutions:Academic and government laboratories drive field trial validation for novel platform candidates.
Beef Farms generate largest absolute volume; Dairy Farms show steepest expansion trajectory as antibiotic curtailment mandates tighten.
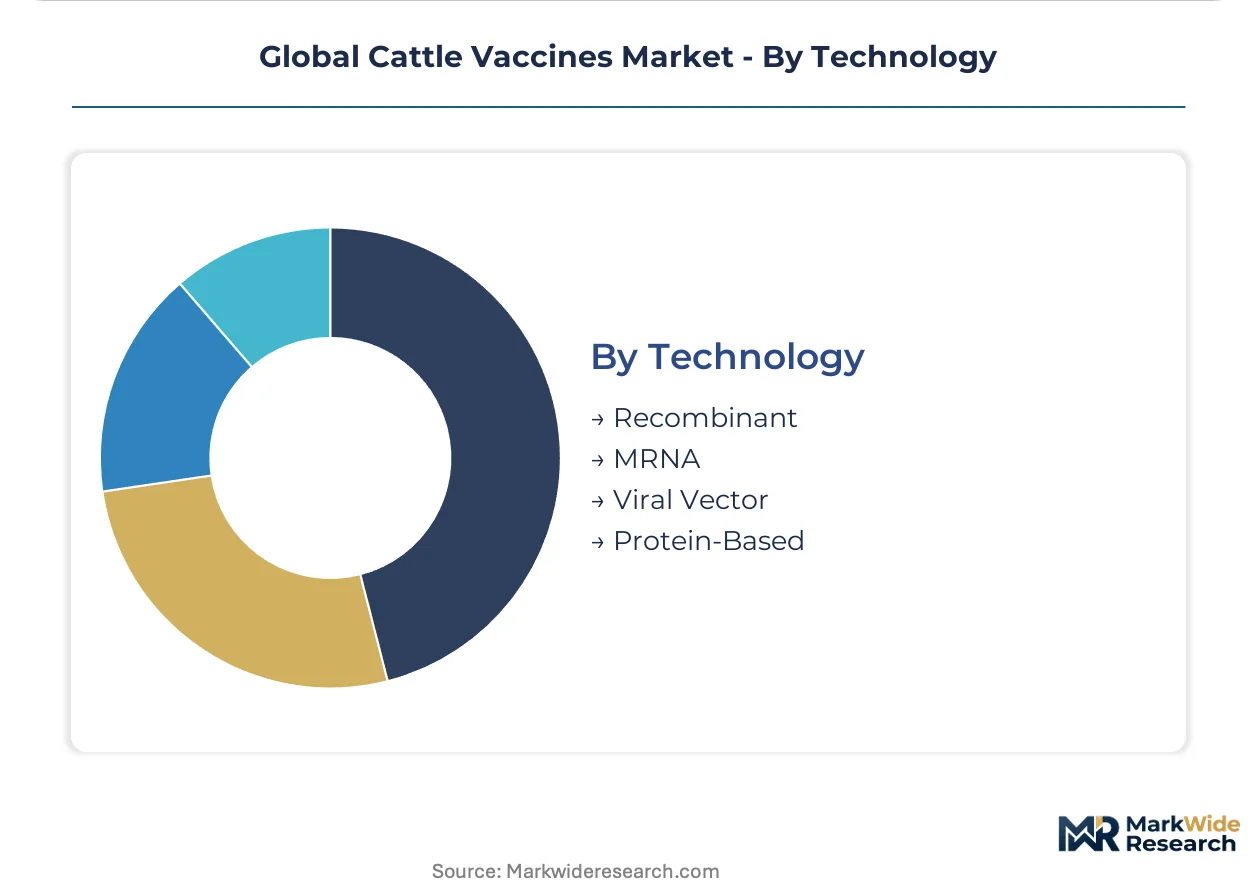
Technology:
Platform selection reflects R&D capital availability, regulatory risk tolerance, and speed-to-market requirements for emerging strain variants.
- Recombinant:Genetically engineered antigen expression systems enable modular combination products without live virus biosafety containment. European manufacturers under EMA veterinary medicine regulations accelerate transitions to saponin-adjuvanted recombinant formulations as REACH assessments constrain legacy mineral oil emulsions.
- MRNA:Synthetic nucleic acid platforms promise rapid strain-matching against antigenically variable pathogens with simplified cold-chain requirements compared to live attenuated alternatives. Development capital from institutional investors targets this segment for foot-and-mouth disease and lumpy skin disease variants.
- Viral Vector:Replication-deficient delivery vehicles harness potent immunogenicity with established manufacturing scale.
- Protein-Based:Purified native or recombinant protein formulations occupy stable positions in validated combination products.
Recombinant anchors current revenue; mRNA is gaining share fastest as regulatory precedents crystallize under FDA and Brazil's national agricultural regulator frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Matto Grosso do Sul's free-trade zone incentives concentrate veterinary manufacturing investment, while Argentina's Santa Fe biotechnology corridor attracts cold-chain logistics operators serving export-certified herds.
United States
Wisconsin and California dairy cooperatives drive demand for clostridial combination products. USDA licensing under the Virus-Serum-Toxin Act shapes approval timelines for novel biologics. Kansas feedlot operators in the High Plains specify respiratory vaccines through processor-aligned contracts with Cargill Protein Group.
Brazil
Mato Grosso ranching belt consolidates procurement through thousand-head feedlot operators bundling preventive health spend. ANVISA develops novel biologic assessment frameworks for mRNA platform candidates. JBS and Minerva Foods anchor cold-chain infrastructure investments across the Pantanal grazing zones.
Germany
EMA veterinary medicine regulations and REACH-aligned adjuvant safety assessments constrain formulation choices for European manufacturers. Lower Saxony formulation specialists invest in toxicology dossiers for saponin-based alternatives. Bavarian dairy networks transition from mineral oil emulsions to liposome-stabilized products.
Australia
Northern Territory outback stations deploy subcutaneous delivery methods where qualified veterinary labor remains scarce. TGA guidelines influence regional validation protocols for DIVA-compliant serological differentiation. New South Wales and Victoria dairy operations adopt recombinant platforms to simplify biosafety containment costs.
Argentina
Santa Fe province biotechnology clusters attract cold-chain logistics investment for export market access. OIE Terrestrial Animal Health Code alignment accelerates replacement of conventional vaccines with subunit formulations. Buenos Aires province estancias face legacy system integration complexity with digital herd management platforms.
Global Cattle Vaccines Market Competitive Landscape
Top-tier vendors anchor recombinant and modified-live viral platforms, while mid-scale specialists occupy regional adjuvant formulation niches. The vendor base stratifies across three tiers: multinational biopharmaceutical conglomerates with USDA and EMA dual-approval capabilities, regional manufacturers serving tropical cold-chain corridors, and emerging nucleic acid platform developers awaiting regulatory precedent. Dominant competitive moves include backward integration into adjuvant raw material supply and strategic partnerships with integrated beef processors for direct procurement contracts.
Within the multinational tier, Zoetis and Boehringer Ingelheim International GmbH represent established regulatory navigation capabilities across North American and European approval pathways. Merck & Co., Inc. occupies a position emphasizing R&D intensity in viral vector development. These three entities exemplify divergent platform strategies: recombinant antigen expression systems, European manufacturing scale networks, and modified-live vector innovation respectively.
| Leading Market Players |
|---|
| Zoetis |
| Boehringer Ingelheim International GmbH |
| Merck & Co., Inc. |
| Elanco Animal Health |
| Ceva Santé Animale |
| Virbac |
| Phibro Animal Health Corporation |
| Biogénesis Bagó S.A. |
| Hipra |
| Others |
Supply & Pricing Matrix
Aluminum hydroxide and saponin adjuvant costs flow from German and Dutch specialty chemical producers through formulation specialists to three-tier pricing structures across premium recombinant, standard inactivated, and economy live attenuated tiers, with cold-chain logistics premiums layering onto final delivered prices for Brazilian Pantanal and Australian Northern Territory ranching corridors.
Pricing Analysis
Short lead-time premiums apply to DIVA-compliant subunit formulations required by Uruguay and New Zealand export-certified herds, while spot inventory discounts emerge for legacy mineral oil emulsions facing REACH-mandated reformulation. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with cost compression in European manufacturing intensifying due to toxicology dossier investments for saponin alternatives. Large-scale Mato Grosso feedlot operators exhibit lowest price sensitivity through multi-year bundled contracts, whereas Indonesian smallholder cooperatives in East Java demonstrate highest sensitivity to per-dose delivered costs.
Supply Chain Analysis
Adjuvant raw material supply rests on German specialty chemical producers for aluminum-based formulations and Brazilian botanical suppliers for Quillaja saponin extracts. Live attenuated viral seed stock concentrates in USDA-licensed facilities across the United States, with fill-finish capacity clustering in Germany and Brazil. Single-source vulnerability exists for qualified cold-chain technicians capable of two-to-eight-degree Celsius handling. Distribution runs through integrated beef processor direct contracts in North America and veterinary distributor networks in fragmented Asian and African markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
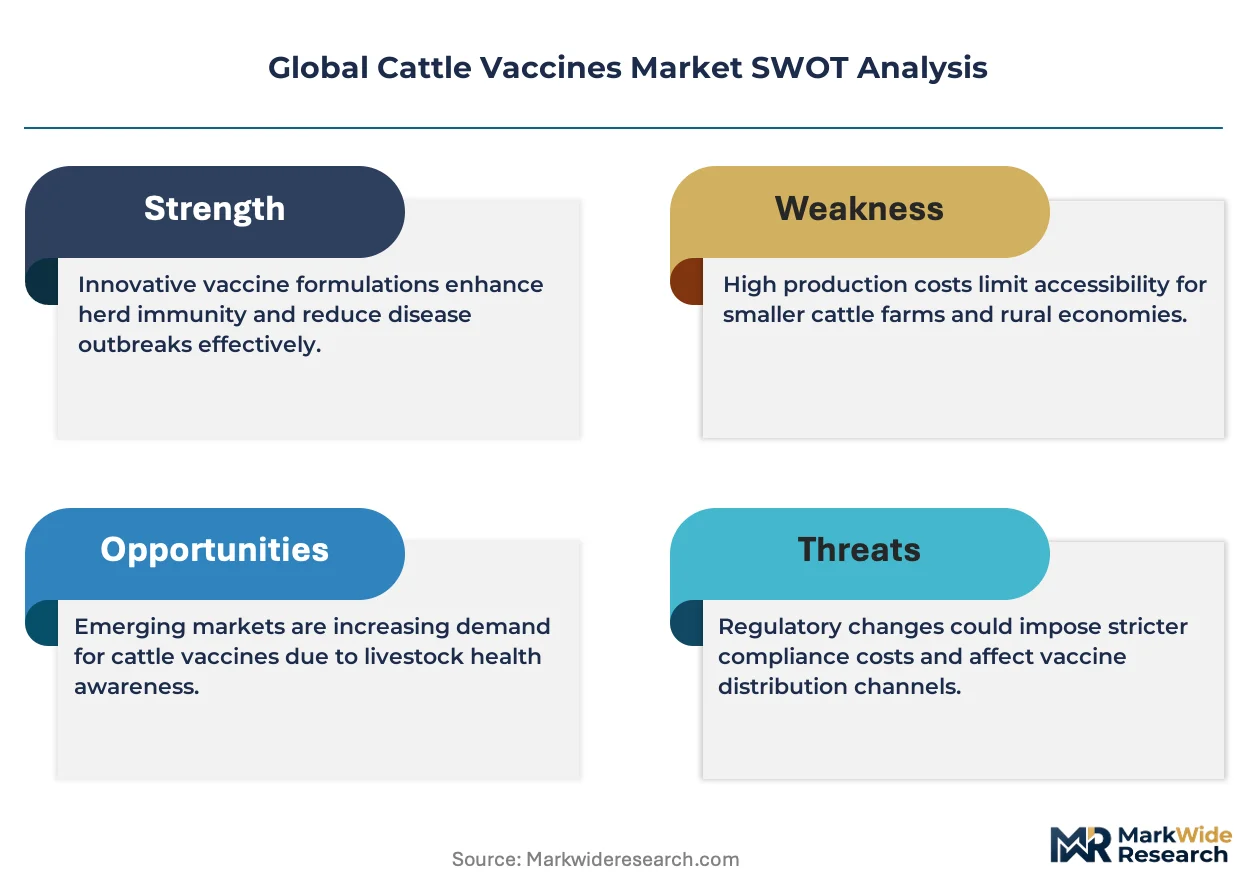
Regulatory timeline friction under FDA and Brazil's national agricultural regulator frameworks is compressing weaker players lacking dual-approval capabilities, positioning the market as a consolidation play where capital reserves determine survival.
For Market Incumbents: Lock in backward integration into adjuvant raw material supply to defend against REACH-mandated reformulation cost spikes, while securing direct procurement contracts with JBS and Cargill to preempt distributor displacement in North American feedlot networks. Priority investment in mRNA platform validation under FDA Center for Veterinary Medicine precedents will anchor future positioning. For New Entrants and Emerging Players: Launch via mobile vaccination unit subscription models targeting Indonesian East Java dairy cooperatives lacking bulk purchasing access, and pursue veterinary telemedicine remote prescribing platforms for Australian outback stations bypassing traditional distributor networks. The most penetrable segment remains fragmented smallholder operations in tropical cold-chain corridors. For Investors and Strategic Acquirers: Brazil's ANVISA publication of novel biologic assessment frameworks for mRNA platforms is the leading indicator that regulatory precedents are crystallizing, signaling accelerated speed-to-market windows. Acquisition targets should include mid-scale recombinant formulation specialists with existing EMA dossiers and cold-chain logistics operators in Argentina's Santa Fe biotechnology corridor. Long-term viability over the next decade hinges on platform diversification beyond live attenuated dominance.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adjuvant Supply | Captive supply of saponin and aluminum hydroxide insulates margin compression from REACH reformulation mandates. |
| mRNA Platform Regulatory Submission | FDA Center for Veterinary Medicine precedents for nucleic acid constructs will determine category entry timing. |
| Direct Processor Contract Negotiation | Cargill and JBS alignment secures volume commitments bypassing regional distributor margin extraction. |
| Mobile Vaccination Unit Deployment | Subscription-based herd health services unlock Indonesian smallholder segments lacking cold-chain infrastructure. |
| DIVA Diagnostic Platform Pairing | Simultaneous vaccination and serological differentiation opens premium positioning for Uruguay export certification. |
Research Methodology
Independent corroboration across regulatory filing databases, customs trade records, and veterinary procurement contract registries underwrites the qualitative findings, combining primary interviews with cattle vaccine development executives, regulatory affairs leads at USDA and ANVISA, feedlot procurement managers in Mato Grosso, and veterinary distributor principals in Southeast Asia with secondary validation from OIE Terrestrial Animal Health Code provisions, EMA veterinary medicine regulations, and cold-chain logistics operator disclosures. Bottom-up demand modeling across biologic platform segments and top-down supply capacity assessments triangulate volume estimates.
Rate-of-change decomposition across the projection horizon isolates volume drivers by biologic platform sophistication, administration route logistics, customer operational scale, and manufacturing technology maturity. CAGRs derive from segment-level growth rate blending weighted by current revenue contribution, incorporating foot-and-mouth disease eradication mandate timelines, feedlot consolidation trajectories in Brazil, and mRNA platform maturation curves as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for mRNA platform regulatory acceptance under FDA and Brazil's national agricultural regulator frameworks would alter the outlook, as would accelerated cold-chain infrastructure deployment in Indonesian and Nigerian corridors. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Global Animal Vaccine Market
Veterinary
Veterinary Endotracheal Tubes Market
Veterinary
Veterinary Ophthalmic Equipment Market
Veterinary
Pet Veterinary Diet Market
Veterinary
Europe Veterinary Healthcare Market
Veterinary
Canine Parvovirus Market
Veterinary
Global Pet Obesity Management Market
Veterinary
Orthopedic Dog Bed Market
Veterinary
Veterinary Vaccine Adjuvants Market
Veterinary
Veterinary Respiratory Disease Treatment Market
Veterinary
Global Canine Influenza Vaccine Market
Veterinary
Spain Veterinary Healthcare Market
Veterinary
Veterinary Equipment and Supplies Market
Veterinary
Veterinary Healthcare Market
Veterinary
Veterinary Scales Market
Veterinary
Pet Light Therapy Devices Market