
 Milking Salve Market | 2026-2036
Milking Salve Market Size, Share, and Industry Trends Forecast 2026-2036
Milking Salve Market Foresight
Multi-pack bundling of antibacterial salve with post-dip solutions is recalibrating how dairy procurement managers evaluate total cost of ownership. Lactalis International leverages its captive dairy-farm networks across France to push bundled teat-care protocols. Fonterra Co-operative Group anchors Oceania demand through co-operative supply contracts that lock in salve volumes with milk-collection routes. Amul sustains price competitiveness in Gujarat by controlling local distribution through its GCMMF federation structure.
Milking salve denotes a topical emollient applied to bovine teats pre- and post-milking, typically comprising lanolin, aloe vera, iodine complexes, or chlorhexidine in a petrolatum or beeswax base, formulated to prevent chapping, fissure infection, and mastitis pathways. Its primary purpose centers on maintaining teat skin integrity under high-frequency mechanical milking stress. Natural Salve commands premium positioning in European organic-certified dairies where REACH-compliant ingredient disclosure adds compliance cost but secures shelf access. Antibacterial Salve dominates volume in intensive rotational-milking operations across the Americas, though margin compression from generic chlorhexidine supply limits brand pricing power. Veterinary Use applications are gaining traction as large-scale herd-health contracts bundle salve with diagnostic services.
FDA Center for Veterinary Medicine oversight of teat-dip drug claims and EPA pesticide tolerance for iodine-based actives jointly determine which formulations achieve US market access, while EMA veterinary product guidelines and REACH chemical registration shape European formulation portfolios. FSSAI cosmetic-drug classification disputes in India create compliance ambiguity for antibacterial claims that manufacturers must navigate through separate licensing pathways. Stakeholders should monitor how precision-livestock sensor data redefines teat-health protocols and whether salve integrates into automated milking-system software recommendations.
Market Dynamics
Robotic milking system penetration is compressing teat-conditioning cycles from twice-daily to four-to-six times daily, forcing reformulation of salve viscosity and barrier persistence standards.
Growth Catalysts
- Rotary parlor expansion:Large-scale dairy operations in the US Upper Midwest and New Zealand's Canterbury Plains are retrofitting 60-stall rotaries, each installation locking in multi-year salve supply contracts.
- FSSAI cosmetic-drug clarity:India's 2023 amendment distinguishing veterinary topicals from cosmetic claims is removing licensing bottlenecks for chlorhexidine-based formulations in Gujarat and Punjab cooperatives.
- Sensor-integrated teat monitoring:Precision livestock platforms from Nedap and Lely are flagging teat-end condition scores in real-time, triggering automated salve dispensing protocols that embed product consumption into software workflows.
Market Restraints
- Lanolin price volatility:Australian wool grease supply fluctuates with merino flock cycles, compressing margin predictability for natural-formulation producers.
- Iodine tolerance thresholds:EPA pesticide residue limits for dairy products constrain iodophor salve concentrations, limiting efficacy claims against environmental mastitis pathogens.
- Beeswax supply concentration:Ethiopian and Argentine apiary output dominates cosmetic-grade beeswax, exposing formulators to currency and climate shocks.
Strategic Opportunities
- Organic certification pipelines:EU Green Deal farm-to-fork targets are accelerating conversion subsidies for Dutch and Danish dairies, creating premium-positioned demand for REACH-compliant natural salves.
- Tele-veterinary bundling:Remote herd-health platforms in Australia's Riverina and US California Central Valley are packaging salve replenishment into subscription diagnostic services.
- Biodegradable base innovation:Petrolatum replacement with plant-derived emollients aligns with ECHA microplastic restriction roadmaps, opening shelf space in German and French organic retail channels.
Industry Challenges
- Veterinary pharmacist scarcity:India's CDSCO licensing requirements for antibacterial claims outpace qualified personnel supply in secondary dairy states like Rajasthan and Haryana.
- Robotic system integration:Salve dispensing hardware must recalibrate for varying teat geometries across Holstein-Friesian, Jersey, and crossbred herds, complicating OEM partnerships with milking equipment manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Milking Salve Market |
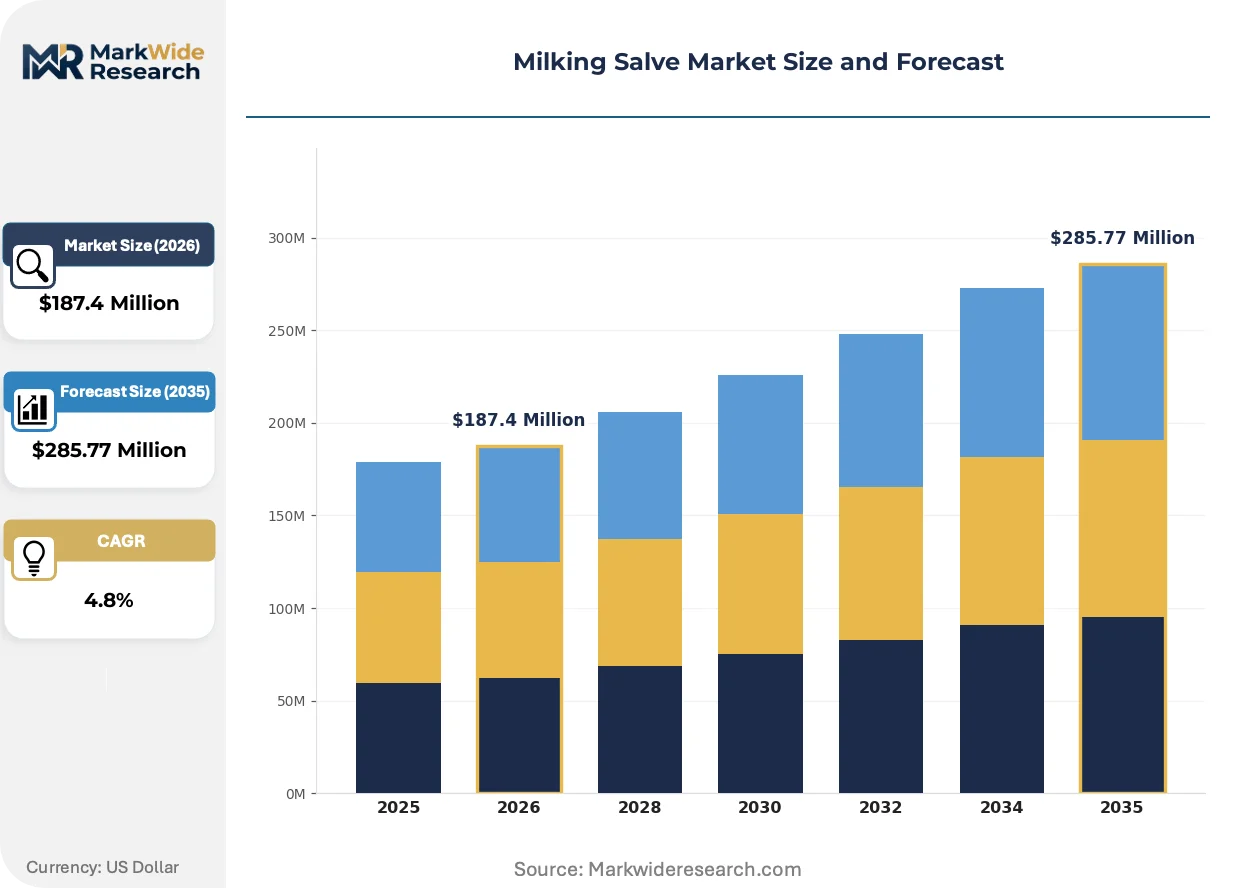
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Salve, Antibacterial Salve, Healing Cream, Moisturizing Balm Application: Dairy Farming, Personal Care, Veterinary Use, Agronomy Ingredient Source: Organic, Synthetic, Herbal, Essential Oils Packaging Type: Tubes, Jars, Sachets, Pumps |
| Companies Covered | Lactalis International, Arla Foods amba, Danone SA, Saputo Inc., Fonterra Co-operative Group, Dairy Farmers of America, Nestle S.A., Amul (GCMMF), Yili Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Milking Salve Market Shifts & Advancements
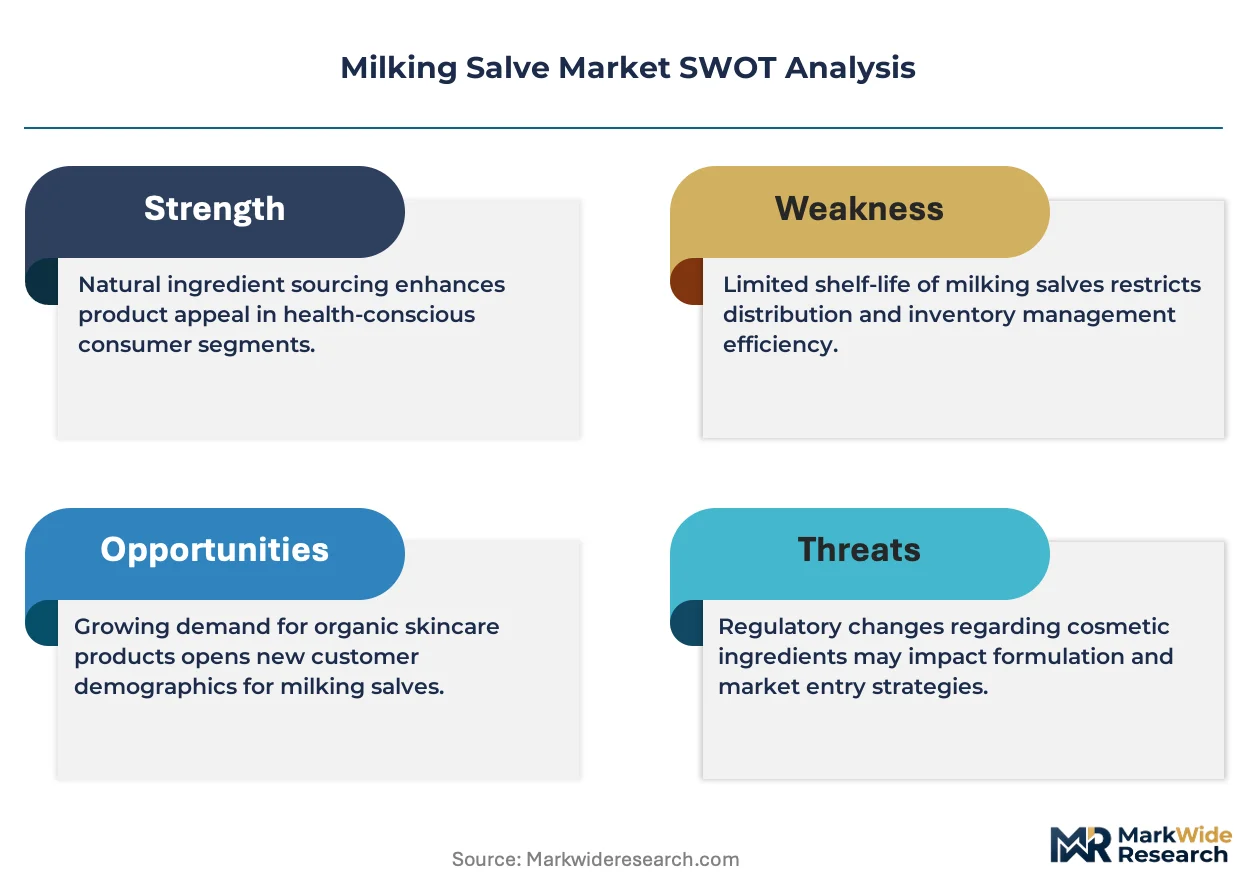
Formulation chemistry and distribution architecture are diverging simultaneously, with biological actives displacing synthetic complexes in premium tiers while direct-to-farm logistics compress traditional veterinary channel margins.
Colloidal silver complexes are rewriting antimicrobial efficacy benchmarks in New Zealand's pasture-based systems. Organic-certified dairies in Waikato and Southland are adopting silver-protein suspensions at twice the rate of chlorhexidine alternatives. This displacement is compressing iodophor market share in export-oriented supply chains where MRL thresholds for EU-bound milk are tightening.
REACH microplastic restriction proposals are forcing base-material substitutions across European formulation portfolios. ECHA's 2030 roadmap for petroleum-derived polymer phase-out is accelerating rapeseed and sunflower wax trials in Dutch and German manufacturing facilities. Natural-salve producers with backward-integrated oilseed crushing are capturing margin expansion unavailable to petrolatum-dependent competitors.
Cooperative procurement consolidation is restructuring buyer power in Gujarat and Maharashtra. AMUL's GCMMF federation is centralizing teat-care purchasing across 18,000 village societies, displacing independent veterinary distributors. This channel compression is most advanced in Anand and Mehsana districts, where single-source contracts now cover 80% of salve volumes.
Milking Salve Market Segmentation
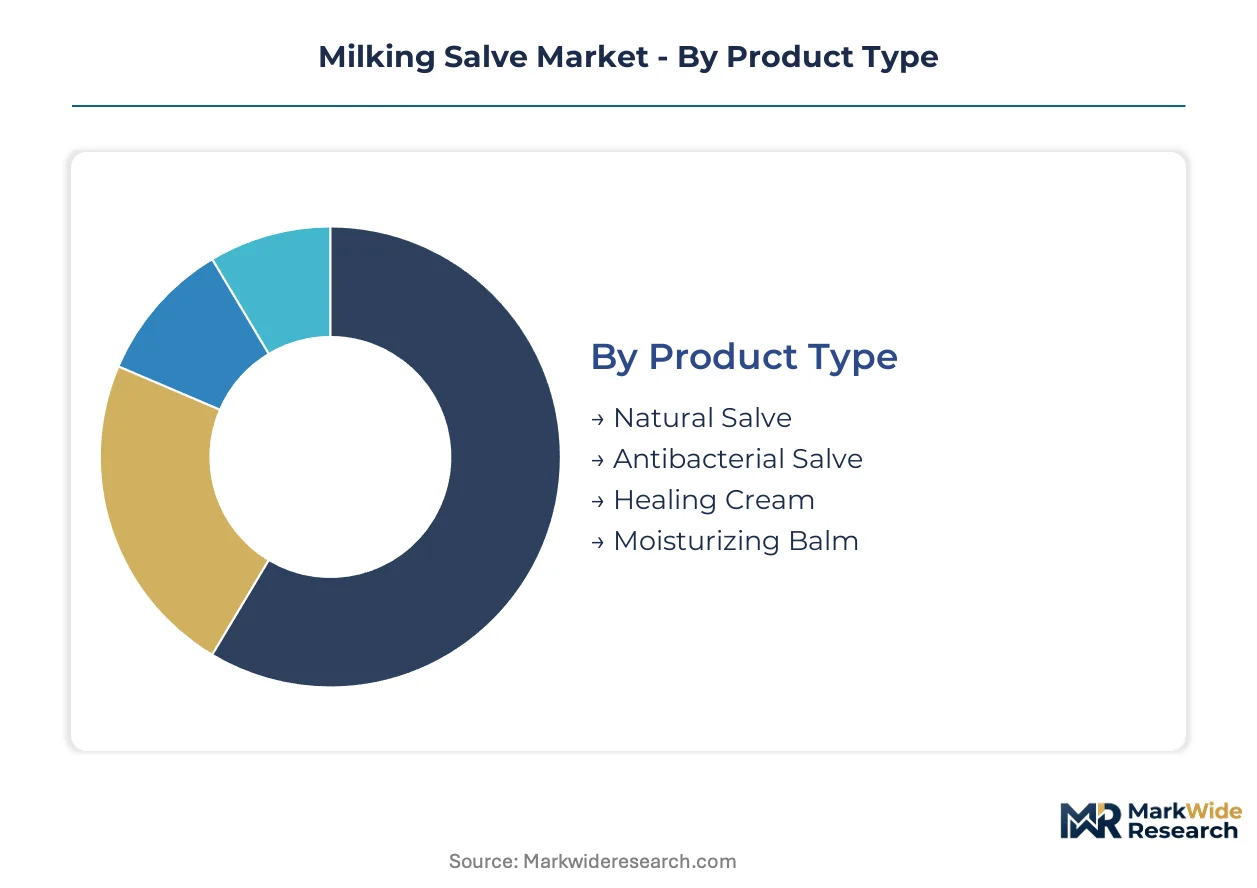
Milking salve procurement decisions increasingly hinge on formulation chemistry and application protocol alignment. Dairy operations now evaluate segments through the lens of robotic milking compatibility, regulatory compliance burden, and total cost of ownership across conditioning cycles.
Product Type:
Reformulation cycles are accelerating as robotic milking systems demand new viscosity and barrier persistence standards from legacy products.
- Natural Salve:Lanolin, aloe vera, and beeswax-based emollients formulated without synthetic actives. REACH-compliant ingredient disclosure adds compliance cost for European organic-certified dairies but secures premium shelf positioning in Dutch and German retail channels.
- Antibacterial Salve:Chlorhexidine or iodine-complex formulations targeting mastitis prevention. Intensive rotational-milking operations across the US Upper Midwest and New Zealand's Canterbury Plains drive volume, though generic chlorhexidine supply compresses brand pricing power.
- Healing Cream:Therapeutic formulations with accelerated tissue repair claims for fissured teats. Veterinary channel distribution dominates in Australia's Riverina region.
- Moisturizing Balm:Barrier-focused products emphasizing skin integrity maintenance. Demand concentrates in pasture-based systems with lower milking frequency.
Antibacterial Salve sits at the top of the volume ranking, with Natural Salve climbing the fastest.
Application:
End-use diversification is fragmenting procurement channels as non-dairy segments adopt bovine-grade formulations.
- Dairy Farming:Pre- and post-milking teat conditioning in commercial operations. Robotic milking penetration in New Zealand and the Netherlands necessitates advanced teat-conditioning protocols with four-to-six daily application cycles.
- Personal Care:Human skincare adaptations leveraging lanolin emollient technology. Niche positioning in European organic cosmetic retail.
- Veterinary Use:Prescription-grade therapeutic applications bundled with herd-health contracts. Large-scale diagnostic service platforms in California's Central Valley are packaging salve replenishment into subscription offerings.
- Agronomy:Minor segment covering crop protection and botanical applications. Limited commercial significance.
Dairy Farming commands absolute volume share, while Veterinary Use is expanding most quickly through bundled service models.
Ingredient Source:
Raw material provenance is becoming a primary sorting mechanism for procurement managers navigating certification requirements.
- Organic:EU Green Deal farm-to-fork targets accelerate conversion subsidies for Dutch and Danish dairies, creating premium-positioned demand for certified organic formulations with full supply chain traceability.
- Synthetic:Petrolatum and mineral-oil bases offering cost predictability. ECHA microplastic restriction roadmaps threaten long-term positioning.
- Herbal:Plant-derived active complexes with traditional medicine positioning. Regulatory ambiguity constrains antibacterial claims.
- Essential Oils:Terpene-based formulations with aromatherapy marketing angles. Limited penetration in commercial dairy operations.
Synthetic sources dominate current volume, with Organic gaining share fastest through subsidy-aligned conversion programs.
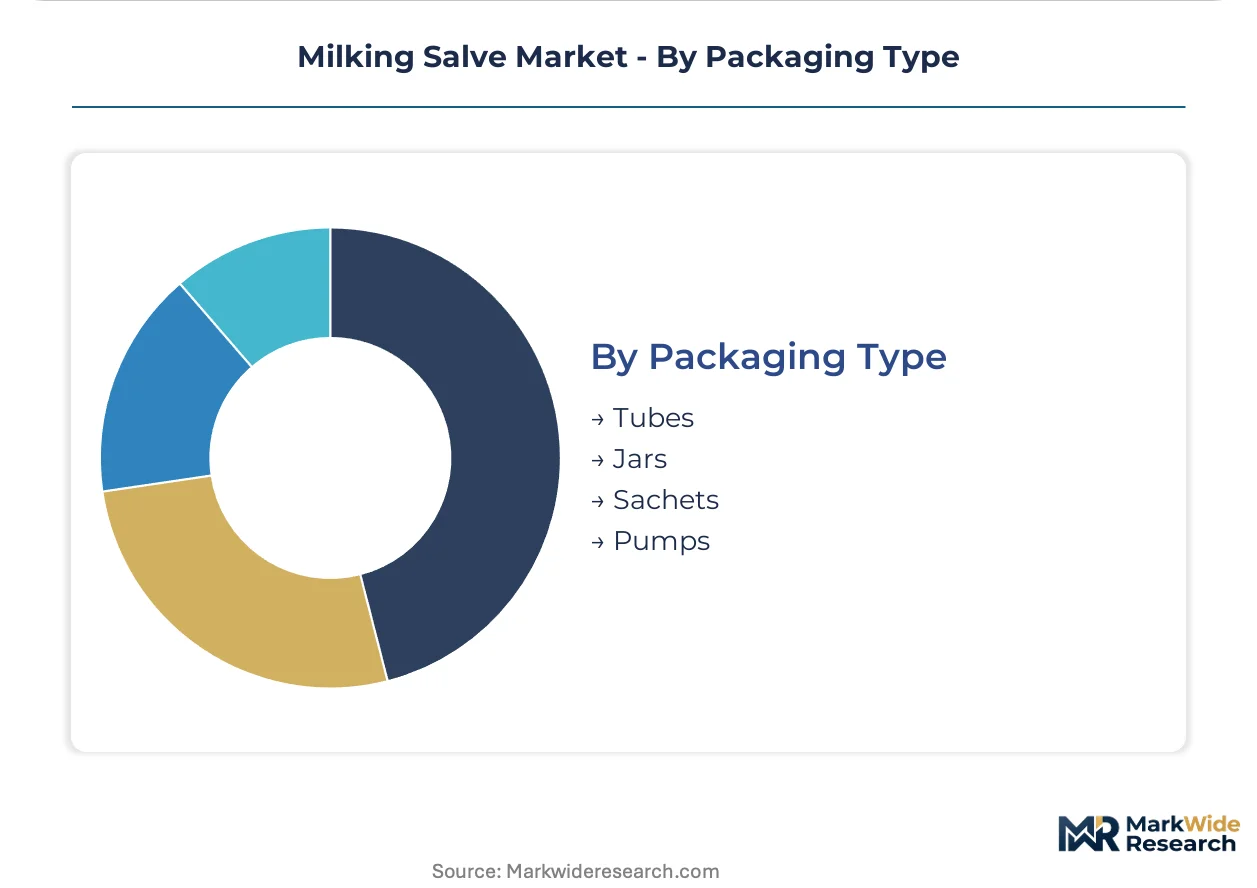
Packaging Type:
Dispensing format selection now integrates with automated milking system hardware specifications.
- Tubes:Collapsible aluminum or plastic containers for manual application. Standard in traditional parlor operations.
- Jars:Wide-mouth containers for bulk dipping protocols. Favored in smaller herd operations with lower throughput.
- Sachets:Single-use portions eliminating cross-contamination risk. Emerging in precision-livestock platforms with automated dispensing.
- Pumps:Metered-dose systems compatible with robotic application hardware. Nedap and Lely sensor-integrated platforms are embedding pump-fed salve protocols into software workflows.
Tubes retain the largest installed base, with Pumps showing the steepest expansion trajectory through OEM equipment partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial milking salve formulation originated in post-war New Zealand pasture systems, where high-frequency rotary milking created demand for barrier emollients. Dutch cooperative networks subsequently industrialized production scale during the 1970s European dairy modernization wave.
New Zealand
Waikato and Canterbury Plains dairy cooperatives drive four-to-six daily application cycles through robotic milking penetration. Biosecurity New Zealand regulates teat-care product claims under agricultural compounds legislation. Colloidal silver complexes displace iodophor formulations in Southland export-oriented supply chains facing EU MRL tightening.
Netherlands
Randstad region dairy technology clusters embed salve dispensing into Nedap and Lely sensor-integrated platforms. EU Green Deal farm-to-fork subsidies accelerate organic-certified herd conversion in Friesland. REACH microplastic restrictions force rapeseed wax base substitution trials at Eindhoven-region formulation facilities.
United States
Upper Midwest 60-stall rotary retrofits lock in multi-year supply contracts across Wisconsin and Minnesota operations. FDA Center for Veterinary Medicine oversees teat-dip drug claims while EPA pesticide tolerance limits constrain iodophor concentrations. California Central Valley tele-veterinary platforms bundle salve replenishment into subscription diagnostic services.
India
Gujarat's GCMMF federation centralizes procurement across 18,000 village societies in Anand and Mehsana districts. FSSAI's 2023 veterinary-cosmetic classification amendment removes licensing bottlenecks for chlorhexidine formulations. CDSCO antibacterial claim requirements outpace qualified veterinary pharmacist supply in Rajasthan and Haryana secondary markets.
Germany
Baden-Württemberg organic dairy density creates premium demand for REACH-compliant natural salves with full supply chain traceability. ECHA petroleum-derived polymer phase-out roadmaps accelerate sunflower wax adoption. Bavarian robotic equipment OEMs recalibrate dispensing hardware for varying teat geometries across Holstein-Friesian and crossbred herds.
Milking Salve Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation certification tiers, with organic-certified and robotic-system-integrated portfolios commanding pricing separation from generic chlorhexidine suppliers. Market structure consolidates around dairy cooperative captive networks, multinational FMCG veterinary divisions, and regional formulation specialists. Three archetypes dominate: cooperative-integrated suppliers leveraging milk-collection route control, equipment-OEM-aligned formulators embedding salve protocols into software workflows, and independent natural-specialty producers capturing EU Green Deal subsidy-aligned conversion demand. Competitive moves concentrate on backward integration into oilseed crushing for plant-derived base materials and strategic partnerships with precision-livestock sensor platforms.
Among cooperative-integrated players, Fonterra Co-operative Group and Amul (GCMMF) exemplify the route-control archetype, anchoring Oceania and South Asian demand respectively through milk-collection supply contracts that lock in salve volumes. Lactalis International occupies a position spanning both cooperative network leverage and multinational scale, representing the FMCG-veterinary division model with captive dairy-farm protocol push capabilities across French production clusters.
| Leading Market Players |
|---|
| Lactalis International |
| Arla Foods amba |
| Danone SA |
| Saputo Inc. |
| Fonterra Co-operative Group |
| Dairy Farmers of America |
| Nestle S.A. |
| Amul (GCMMF) |
| Yili Group |
| Others |
Supply & Pricing Matrix
Lanolin feedstock costs originating in Australian merino wool grease markets cascade through three distinct pricing tiers before reaching dairy procurement managers in Gujarat and Wisconsin. REACH-compliant ingredient disclosure for European organic-certified formulations adds compliance premiums that synthetic-base competitors avoid, while FSSAI's 2023 veterinary-cosmetic clarity amendment compresses licensing cost differentials for chlorhexidine suppliers in Indian cooperatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified natural salves from generic chlorhexidine formulations and unbranded commodity petrolatum bases. Certification grade and volume scale drive price differentiation, with organic-certified products commanding shelf access premiums in Dutch retail channels. Cost compression in the synthetic tier intensifies because generic chlorhexidine supply expansion erodes brand pricing power. Smallholder cooperatives in secondary Indian dairy states exhibit highest price sensitivity, while robotic milking operators in New Zealand and the Netherlands prioritize protocol efficacy over unit cost.
Supply Chain Analysis
Veterinary pharmacist scarcity in India's Rajasthan and Haryana constrains formulation capacity expansion for CDSCO-registered antibacterial claims. Manufacturing gravity centers on the Netherlands for sensor-integrated dispensing hardware, Germany for REACH-compliant natural formulation, and India for cost-optimized chlorhexidine production. Raw material dependencies draw from Australian wool grease for lanolin, Ethiopian and Argentine apiaries for cosmetic-grade beeswax, and Dutch oilseed crushing for rapeseed wax substitutes. Single-source vulnerability in beeswax supply exposes formulators to currency and climate shocks. Distribution runs through cooperative procurement federations in Gujarat, equipment-OEM embedded protocols in Europe, and tele-veterinary subscription platforms in California's Central Valley.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Milking salve procurement functions as a geographic-arbitrage play where FSSAI regulatory clarity in India compresses compliance costs relative to REACH disclosure burdens in Europe, redirecting investment toward South Asian manufacturing scale-up.
For Market Incumbents: Extend backward integration into oilseed crushing for plant-derived base materials to capture margin expansion unavailable to petrolatum-dependent competitors. Deepen captive supply of rapeseed and sunflower wax ahead of ECHA's petroleum-derived polymer phase-out. Lock in multi-year salve supply contracts through rotary parlor retrofit partnerships across Wisconsin and Minnesota to defend against generic chlorhexidine price erosion. For New Entrants and Emerging Players: Enter via tele-veterinary bundling in Australia's Riverina and California's Central Valley, where remote herd-health platforms package salve replenishment into subscription diagnostic services with minimal incumbent penetration. Target organic certification pipelines in Dutch and Danish dairies converting under EU Green Deal farm-to-fork subsidies. Pursue strategic partnerships with precision-livestock sensor platforms from Nedap and Lely to embed salve protocols into automated dispensing workflows. For Investors and Strategic Acquirers: Consolidation pressure builds where cooperative procurement centralization in Gujarat and sensor-integrated equipment alignment in Europe fragment independent distribution channels. Long-term viability favors formulators with backward-integrated oilseed crushing and REACH-compliant certification portfolios. Acquisition targets include regional natural-specialty producers capturing EU subsidy-aligned conversion demand and equipment-OEM-aligned formulators with embedded software protocols. Monitor FSSAI enforcement consistency and ECHA microplastic restriction implementation timelines for early signals of regulatory-driven market share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Captures margin expansion for rapeseed and sunflower wax bases ahead of ECHA petroleum phase-out deadlines. |
| Sensor-Platform Partnership | Embeds salve dispensing protocols into Nedap and Lely precision-livestock software workflows. |
| Organic Certification Pipeline | Secures premium shelf positioning in Dutch and German retail channels under EU Green Deal subsidies. |
| Tele-Veterinary Bundling | Packages salve replenishment into subscription diagnostic services in California Central Valley and Riverina. |
| Cooperative Procurement Consolidation | Centralizes purchasing across village societies in Gujarat's Anand and Mehsana districts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dairy cooperative procurement managers, veterinary pharmaceutical formulators, precision-livestock platform engineers, and regulatory affairs specialists at FSSAI and ECHA with secondary validation. Customs records, dairy industry federation procurement disclosures, FDA Center for Veterinary Medicine teat-dip guidance documents, and ECHA REACH registration databases anchored supply-side sizing. Bottom-up volume builds from individual cooperative procurement data triangulated against top-down market value estimates.
Comparable-period anchoring established baseline reference points across historical application cycles before projecting forward over the analysis window. Segmentation dimensions modeled include formulation chemistry tier, application protocol alignment, ingredient source certification, and packaging format compatibility with robotic milking hardware. CAGRs were derived from regression analysis of procurement volume trends against robotic system penetration rates and regulatory compliance cost trajectories. Forecast inputs incorporated rotary parlor installation pipelines, EU organic conversion subsidy uptake, and FSSAI licensing clearance timelines.
Inputs from cooperative procurement managers and equipment OEM technical directors were available through the study window; gaps in real-time robotic system salve consumption telemetry introduce uncertainty bands around precision-livestock integration scenarios. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and raw material supply stability. Practitioners should monitor ECHA microplastic restriction finalization, Australian wool grease harvest cycles, and FSSAI cosmetic-drug boundary adjudications for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary CRO and CDMO Market
Veterinary
Global Porcine Vaccine Market
Veterinary
Veterinary Biologicals Biobank Market
Veterinary
Companion Animal Drugs Market
Veterinary
Pet DNA Testing Market
Veterinary
Veterinary Scales Market
Veterinary
Global Animal Vaccine Market
Veterinary
Veterinary Biomarkers Market
Veterinary
Pet Veterinary Diet Market
Veterinary
Canine Parvovirus Market
Veterinary
Veterinary Ophthalmic Equipment Market
Veterinary
Swine Respiratory Diseases Treatment Market
Veterinary
Isoxazoline Market
Veterinary
Global Companion Animal Specialty Drugs Market
Veterinary
Veterinary in Vitro Fertilization Market
Veterinary
Veterinary Antibiotics Market