
 Veterinary Parasiticides Market | 2026-2036
Veterinary Parasiticides Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Parasiticides Market Analytics
Multi-source API procurement is rebalancing toward captive manufacturing among top veterinary pharmaceutical groups. Zoetis Services LLC anchors its parasiticide portfolio through backward integration into fermentation-based avermectin production. Boehringer Ingelheim International GmbH competes via sustained investment in recombinant vaccine-parasiticide combination platforms. Merck & Co., Inc. leverages its legacy anthelmintic research infrastructure to dominate channel access with livestock veterinarians.
Veterinary parasiticides comprise biocidal and pharmaceutical agents formulated to prevent, treat, or control ectoparasite and endoparasite infestations in animals, typically delivered as pour-on solutions, oral pastes, or injectable formulations containing active compounds such as milbemycin oxime or fluralaner. These products serve commercial livestock operations, companion animal practices, and aquaculture facilities by protecting animal health, ensuring food safety compliance, and maintaining productivity metrics. Anthelmintics and endectocides occupy the largest share of the product type landscape, reflecting entrenched demand for broad-spectrum nematode and arthropod control in cattle and small ruminant herds. The companion animal application segment generates premium margin pools, particularly for topical spot-on formulations targeting fleas and ticks in canine and feline patients. Oral administration routes are gaining formulation innovation attention as palatability-enhanced chewables improve owner compliance and extend dosing intervals.
The FDA's Center for Veterinary Medicine enforces stringent new animal drug approval pathways and residue tolerance limits that shape product development timelines and label claims for food animal parasiticides. The European Medicines Agency's Committee for Medicinal Products for Veterinary Use applies benefit-risk assessments under the EU Veterinary Medicines Regulation, accelerating novel active substance approvals while restricting environmental persistence profiles. Stakeholders must monitor evolving regulatory divergence between major jurisdictions to optimize portfolio registration sequencing and manufacturing site qualification.
Market Dynamics
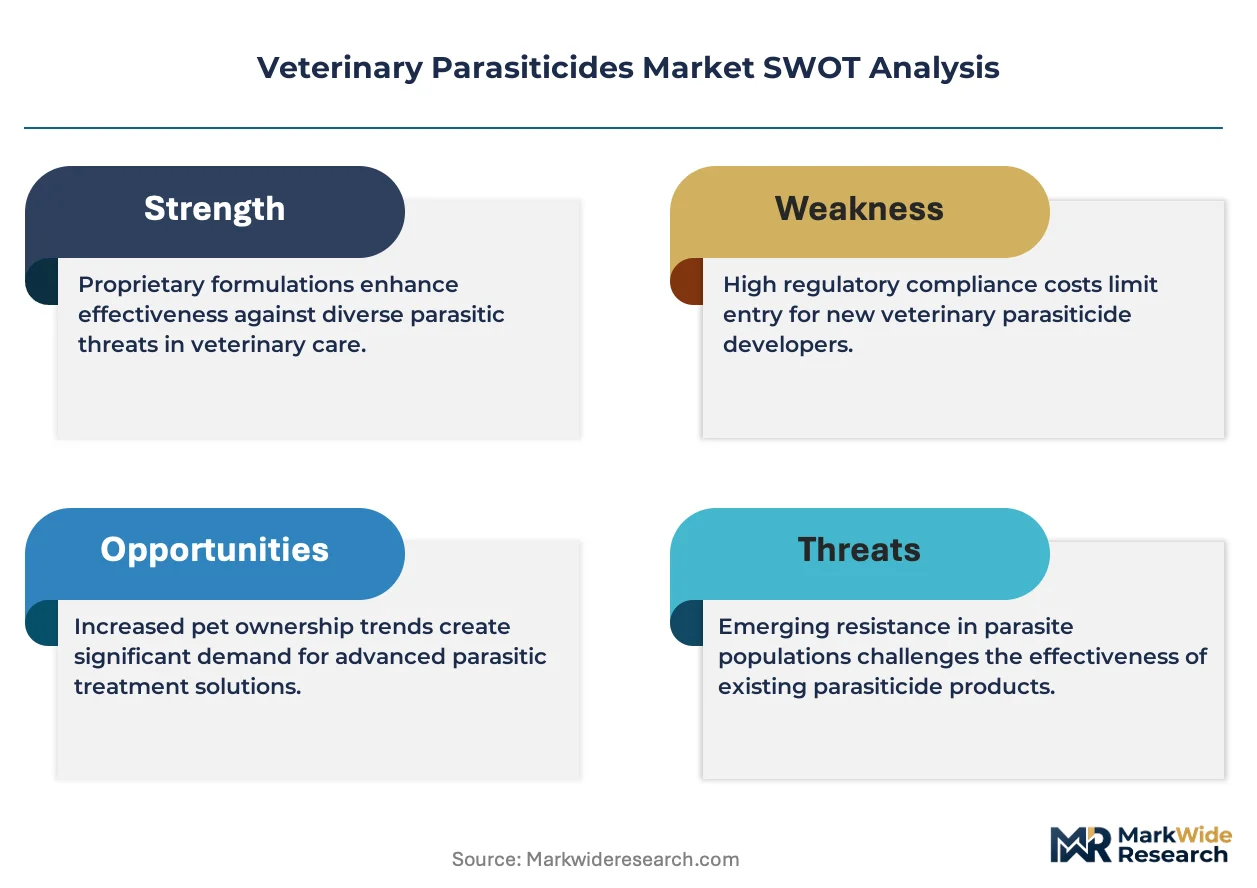
Companion animal clinics are extending prophylactic deworming protocols while livestock operations face tightened residue monitoring, creating divergent demand patterns that split R&D investment between premium small-animal formulations and compliance-driven food animal products.
Growth Catalysts
- FDA residue tolerance enforcement:Heightened surveillance of food animal tissues accelerates adoption of shorter-withdrawal anthelmintics among cattle feedlot operators seeking supply chain continuity.
- Palatability-enhanced chewables:Extended-release oral formulations for companion animals improve owner compliance and extend dosing intervals, deepening product penetration in canine and feline practices.
- Brazilian livestock intensification:Large-scale beef and dairy operations in Mato Grosso and São Paulo states generate concentrated demand for pour-on endectocides and injectable anthelmintics.
Market Restraints
- Fermentation capacity concentration:Captive avermectin production anchors supply among top three veterinary pharmaceutical groups, limiting API access for mid-tier formulators.
- EU organophosphate phase-out:The European Commission's restriction of certain ectoparasiticides forces reformulation investments without guaranteed label renewal timelines.
- Anthelmintic resistance proliferation:Nematode populations in sheep and goat herds demonstrate reduced efficacy to benzimidazole and macrocyclic lactone classes, compressing product lifecycles.
Strategic Opportunities
- Aquaculture parasiticide underpenetration:Sea lice management in Norwegian salmon farming represents an underserved application with limited approved actives relative to terrestrial livestock.
- Vaccine-parasiticide combination platforms:Recombinant delivery systems integrating immunization and endoparasite control address multi-pathogen protocols in swine and poultry operations.
- Direct-to-veterinarian digital channels:Specialized distribution platforms bypass traditional wholesale tiers, capturing margin and enabling real-time inventory management for companion animal practices.
Industry Challenges
- Veterinary parasitology expertise scarcity:Diagnostic proficiency in fecal egg count reduction testing and resistance monitoring lags behind product innovation pipelines.
- Environmental persistence compliance:Avermectin metabolite runoff assessments for soil and aquatic ecosystems extend registration timelines and expand toxicology data requirements.
- Multi-jurisdiction label harmonization:Divergent withdrawal period standards between FDA and EMA create manufacturing complexity for global livestock pharmaceutical portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Parasiticides Market |
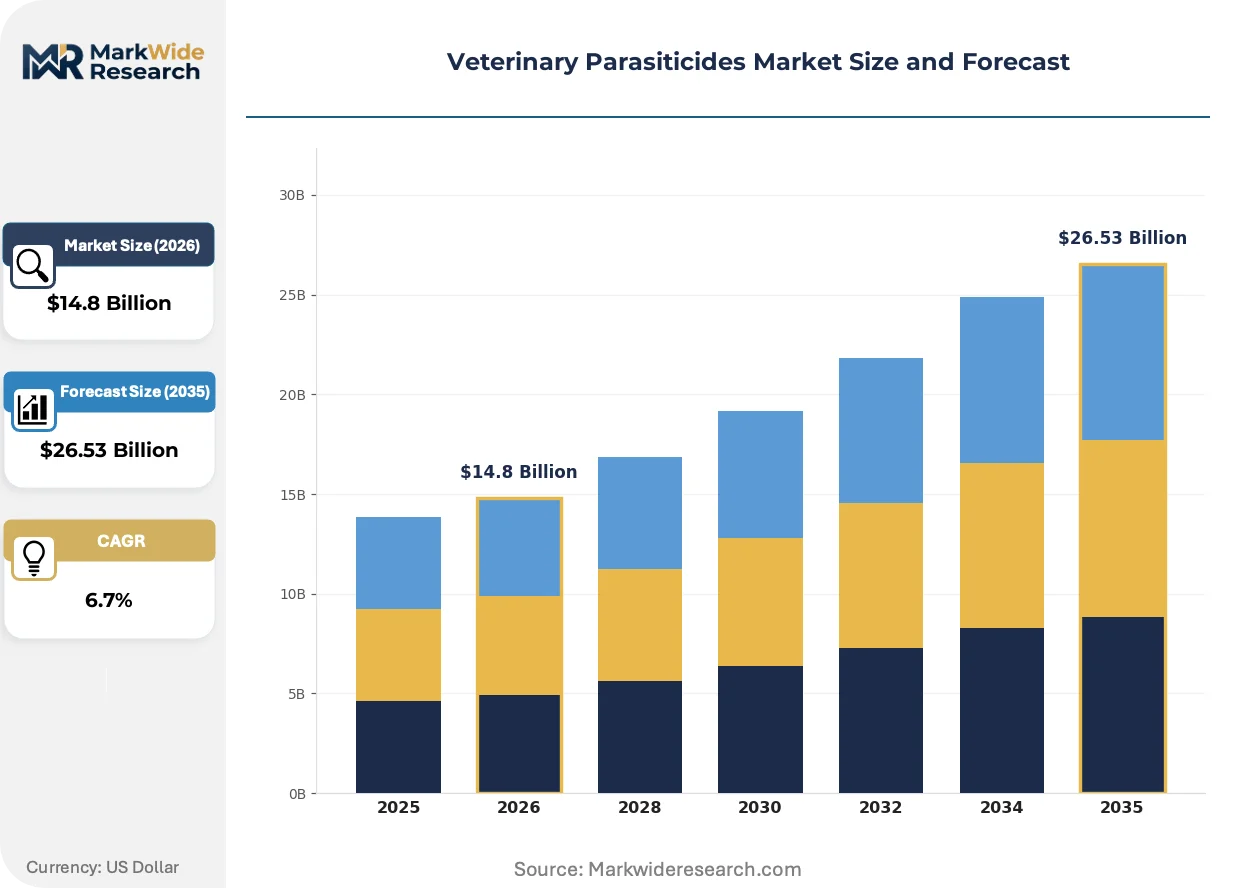
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endectocides, Acaricides, Anthelmintics, Insect Growth Regulators Application: Companion Animals, Livestock, Aquaculture, Equine Administration Route: Oral, Topical, Injection, Inhalation Formulation Type: Liquid, Powder, Granules, Spray |
| Companies Covered | Zoetis Services LLC, Merck & Co., Inc., Elanco, Boehringer Ingelheim International GmbH, Virbac, Ceva, Vetoquinol, Dechra Pharmaceuticals, Phibro Animal Health Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Parasiticides Market Evolving Landscape
Formulation chemistry and delivery mechanisms are converging with digital compliance tools, reshaping how parasiticides achieve efficacy, safety, and regulatory alignment across species and geographies.
Long-acting injectable formulations containing moxidectin or doramectin are rewriting treatment protocols for grazing cattle by enabling season-long parasite suppression from single administrations. Ranchers in Australia and New Zealand have accelerated uptake of these extended-duration products, compressing the labor and animal-handling costs associated with repeated pour-on or oral applications. The technology is rewriting competitive positioning by favoring manufacturers with sophisticated controlled-release polymer expertise over traditional formulation houses.
REACH environmental persistence assessments are tightening acceptable degradation profiles for veterinary medicinal products entering European water systems. ECHA classification of certain parasiticide metabolites as substances of very high concern is forcing reformulation toward biodegradable actives or closed-system administration. Aquaculture applications in Norway and Scotland face the steepest compliance gradients, driving investment in sea lice management alternatives with reduced marine ecotoxicity.
Diagnostic-guided selective treatment protocols are displacing calendar-based mass medication in sheep and cattle enterprises. Veterinary practitioners and livestock consultants in the United Kingdom and Ireland are deploying fecal egg count testing to identify high-burden individuals, reducing anthelmintic use by half in monitored flocks. This behavioral shift concentrates demand for precision diagnostic services and challenges volume-dependent pricing models that rewarded blanket herd treatments.
Veterinary Parasiticides Market Segmentation
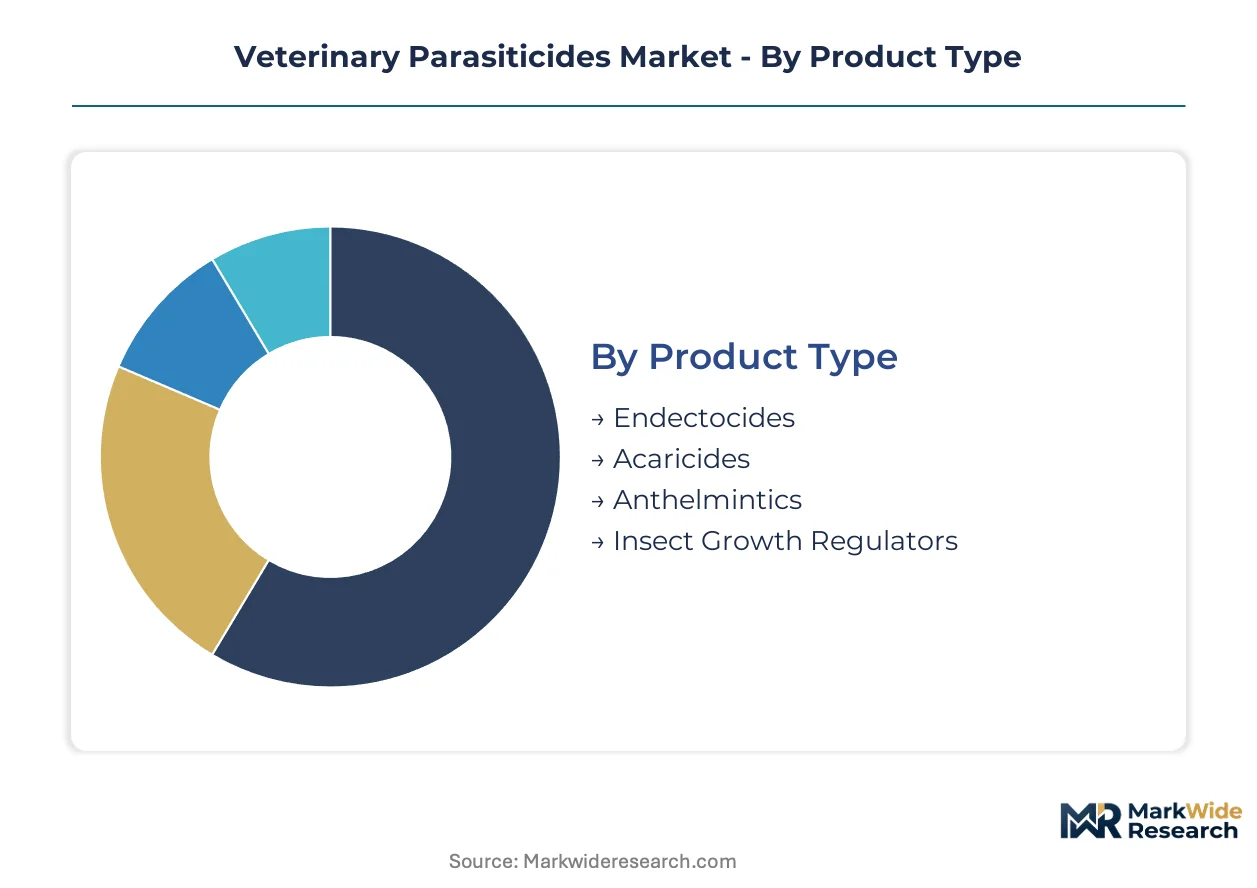
Veterinary parasiticide segmentation reflects divergent efficacy requirements across species, with formulation chemistry and delivery mechanisms determining compliance economics in food animal operations versus companion animal convenience. Each axis carries distinct margin profiles and regulatory complexity that reshape competitive positioning.
Product Type:
Active compound class defines spectrum breadth, residue profile, and resistance management protocols across veterinary applications.
- Endectocides:Macrocyclic lactone formulations including ivermectin and moxidectin deliver simultaneous nematode and arthropod control through glutamate-gated chloride channel modulation. Cattle feedlots in the United States favor pour-on endectocides for their single-dose convenience and shortened meat withdrawal periods under FDA residue monitoring.
- Anthelmintics:Benzimidazole, imidazothiazole, and amino-acetonitrile derivative classes target gastrointestinal nematodes via tubulin binding or nicotinic acetylcholine receptor agonism. Sheep and goat enterprises in the United Kingdom deploy fecal egg count reduction testing to guide selective anthelmintic use, compressing volume-dependent pricing models.
- Acaricides:Amitraz and pyrethroid-based formulations interrupt tick and mite nervous system function for companion animal and livestock ectoparasite management.
- Insect Growth Regulators:Juvenile hormone analogs and chitin synthesis inhibitors disrupt flea and fly development cycles without acute neurotoxicity.
Mature deployment sits with anthelmintics in ruminant herds. Newer deployment is concentrated in endectocides for extended-release cattle formulations.
Application:
Species-specific physiology and economic value per animal dictate formulation premium tolerance and regulatory scrutiny intensity.
- Companion Animals:Canine and feline parasiticide demand centers on monthly topical spot-ons and palatable oral chewables with extended flea, tick, and heartworm protection. Premium pricing tolerances in United States and German veterinary practices drive innovation in isoxazoline-class actives and combination products.
- Livestock:Cattle, swine, and small ruminant operations prioritize cost-efficient mass medication with pour-on, injectable, or feed-additive delivery. Brazilian intensified beef operations in Mato Grosso generate concentrated demand for endectocide pour-ons that reduce labor costs in large-scale pasture systems.
- Aquaculture:Sea lice management in Norwegian salmon farming employs limited approved actives including emamectin benzoate and hydrogen peroxide baths.
- Equine:Anthelmintic resistance in cyathostomin populations drives rotation strategies and fecal egg count monitoring in racing and pleasure horse establishments.
Revenue concentration favors companion animals for margin depth. Volume expansion is climbing the fastest in Brazilian and Australian livestock intensification.
Administration Route:
Delivery mechanism determines labor economics, bioavailability, and tissue residue distribution for regulatory compliance.
- Oral:Pastes, gels, and chewable tablets achieve systemic distribution for endoparasite control with owner-administered convenience in companion animals.
- Topical:Spot-on pipettes and pour-on solutions provide transdermal absorption with minimal handling stress; transdermal macrocyclic lactones dominate cattle parasite control in Australia and New Zealand grazing systems.
- Injection:Subcutaneous and intramuscular formulations including long-acting moxidectin implants enable season-long protection with single handling events.
- Inhalation:Limited deployment for respiratory nematode control in specific sheep and goat management protocols.
Established protocols rely on topical delivery in cattle. Injectable long-acting formulations are gaining share fastest in extensive grazing operations.
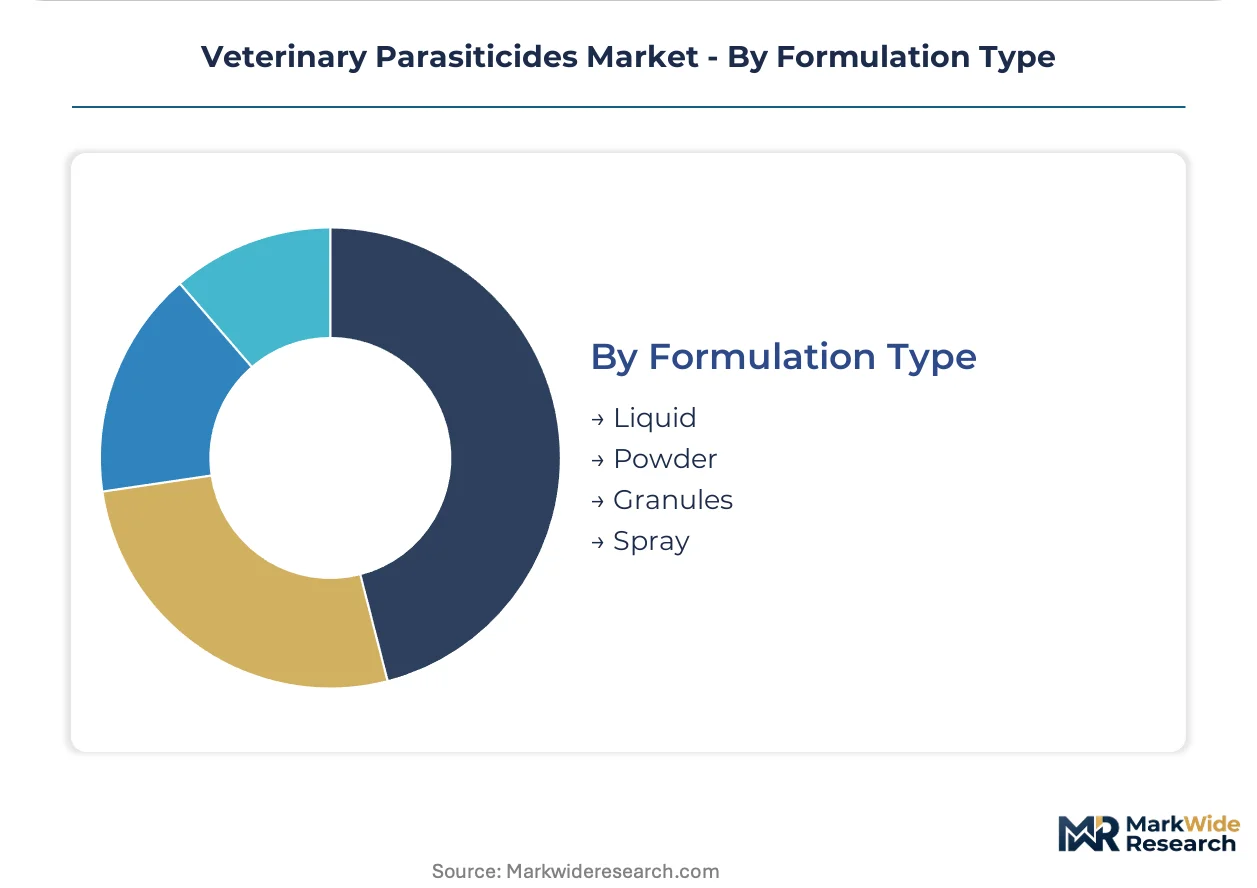
Formulation Type:
Physical presentation shapes storage stability, dosing precision, and environmental persistence profiles under ECHA and EPA assessments.
- Liquid:Emulsifiable concentrates and suspension concentrates dominate pour-on and spray applications with flexible dilution for varying infestation pressure.
- Powder:Feed premixes enable mass medication integration for swine and poultry anthelmintic programs.
- Granules:Palatable oral formulations improve compliance in companion animals with taste-masking excipients.
- Spray:Aqueous and oil-based sprays deliver targeted ectoparasite control for premises and animal application in equine and livestock housing.
Liquid formulations anchor livestock parasiticide supply. Granule formats are expanding most quickly in premium companion animal segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation-based avermectin production clusters in the United States, Germany, and Brazil anchor supply-side capacity for veterinary parasiticide manufacturing. These three countries concentrate backward-integrated API production, formulation expertise, and regulatory infrastructure that shapes product registration sequencing across the analysis window.
United States
Large-scale cattle feedlot operations in Texas and Kansas generate concentrated demand for pour-on endectocides with shortened meat withdrawal periods. The FDA's Center for Veterinary Medicine enforces stringent residue tolerance limits that accelerate adoption of compliance-driven anthelmintic formulations. Zoetis Services LLC maintains captive fermentation capacity in the Midwest, securing supply chain continuity for macrocyclic lactone production.
Germany
Premium companion animal practices in Bavaria and North Rhine-Westphalia drive demand for palatable oral chewables and topical spot-on formulations. The European Medicines Agency's Committee for Medicinal Products for Veterinary Use applies REACH-aligned environmental persistence assessments that redirect R&D toward biodegradable actives. Boehringer Ingelheim International GmbH anchors its European operations through sustained investment in recombinant vaccine-parasiticide combination platforms.
Brazil
Intensified beef and dairy operations in Mato Grosso and São Paulo states generate volume demand for pour-on endectocides and injectable anthelmintics. ANVISA registration pathways for veterinary medicinal products shape product development timelines for food animal applications. Regional formulators compete through cost-efficient mass medication protocols tailored to large-scale pasture systems with compressed labor budgets.
United Kingdom
Sheep and goat enterprises in Wales and the Scottish Highlands deploy fecal egg count reduction testing to guide selective anthelmintic use. The Veterinary Medicines Directorate enforces withdrawal period standards that diverge from FDA benchmarks, creating manufacturing complexity for global portfolios. Diagnostic-guided treatment protocols in monitored flocks compress volume-dependent pricing models that previously rewarded blanket herd medication.
Australia
Extensive grazing operations in Queensland and New South Wales accelerate uptake of long-acting injectable moxidectin formulations for season-long parasite suppression. The Therapeutic Goods Administration coordinates with APVMA on environmental persistence assessments for macrocyclic lactone metabolites entering aquatic ecosystems. Ranchers favor controlled-release polymer expertise that eliminates repeated handling costs in remote pastoral zones.
Veterinary Parasiticides Market Competitive Landscape
Global majors compete with regional champions across formulation sophistication and captive API access. The market structure consolidates around three veterinary pharmaceutical groups with backward-integrated fermentation capacity, while mid-tier formulators face API procurement constraints. Strategic archetypes include: vertically integrated innovators with captive avermectin production; recombinant platform specialists pursuing vaccine-parasiticide combinations; and regional generics manufacturers serving price-sensitive livestock markets. Dominant competitive moves center on captive manufacturing investments and regulatory-driven portfolio diversification.
Within the integrated innovator tier, Zoetis Services LLC and Merck & Co., Inc. exemplify archetypes defined by fermentation-based supply control and legacy anthelmintic research infrastructure. Boehringer Ingelheim International GmbH occupies a position representing recombinant platform investment. These three entities anchor competitive dynamics through differential access to macrocyclic lactone APIs and channel relationships with livestock veterinarians versus companion animal practices.
| Leading Market Players |
|---|
| Zoetis Services LLC |
| Merck & Co., Inc. |
| Elanco |
| Boehringer Ingelheim International GmbH |
| Virbac |
| Ceva |
| Vetoquinol |
| Dechra Pharmaceuticals |
| Phibro Animal Health Corporation |
| Others |
Value Network & Pricing Analysis
FDA residue tolerance enforcement and EMA environmental persistence assessments are forcing formulators toward shorter-withdrawal anthelmintics and biodegradable actives, compelling API suppliers to revalidate manufacturing sites and absorb compliance costs that compress margins across mid-tier producers.
Pricing Analysis
Diagnostic service bundling with parasiticide products separates premium veterinary practices from economy-focused livestock operations. Three-tier pricing structure across premium, standard, and economy levels reflects formulation complexity, captive API access, and after-sales technical support depth. Cost compression in generic endectocides is intensifying because Brazilian and Indian formulators are expanding volume-based contract terms. Livestock feedlot operators exhibit highest price sensitivity due to thin operating margins, while companion animal clinics in Germany and the United States tolerate premium pricing for palatability-enhanced chewables.
Supply Chain Analysis
Reverse logistics for expired or recalled veterinary medicinal products flow through specialized hazardous waste handlers to incineration facilities compliant with EPA and ECHA destruction standards. Fermentation-based avermectin production concentrates in the United States, Germany, and China, with downstream formulation clustering in Brazil and India. Supply chains draw from streptomyces fermentation feedstocks, controlled-release polymer excipients, and glass primary packaging. Single-source vulnerability sits with captive macrocyclic lactone API production among top three veterinary pharmaceutical groups. Distribution runs through veterinary wholesale distributors and direct-to-clinic digital platforms serving companion animal practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The veterinary parasiticides market functions as a vertical-integration race where control over fermentation-based API production and recombinant platform development determines margin capture and regulatory agility across jurisdictions.
For Market Incumbents: To counter anthelmintic resistance proliferation in sheep and goat herds, deepen captive manufacturing investments in novel macrocyclic lactone fermentation capacity and accelerate recombinant vaccine-parasiticide combination platform development. Secure channel control through direct-to-veterinarian digital inventory management systems that bypass traditional wholesale markups. For New Entrants and Emerging Players: Precision diagnostic-guided selective treatment protocols offer technology-first entry points into underserved veterinary parasitology service markets. Target aquaculture sea lice management in Norwegian salmon farming with reduced marine ecotoxicity formulations. Pursue white-label manufacturing partnerships with regional Brazilian formulators serving intensified beef operations in Mato Grosso. For Investors and Strategic Acquirers: The window for entry favors mid-tier formulators with validated ANVISA or FDA manufacturing site qualifications and established veterinary distribution relationships. Long-term viability hinges on consolidation plays that aggregate regional generics manufacturers and retrofit their facilities for environmental compliance. Monitor ECHA substance-of-very-high-concern designations for parasiticide metabolites as inflection indicators for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Fermentation Capacity Expansion | Zoetis and Merck anchor supply chain continuity through backward-integrated avermectin production in Midwestern US facilities. |
| Recombinant Platform Development | Boehringer Ingelheim pursues vaccine-parasiticide combinations addressing multi-pathogen protocols in swine operations. |
| Direct-to-Veterinarian Digital Channels | Specialized distribution platforms capture margin and enable real-time inventory management for companion animal practices. |
| Environmental Compliance Reformulation | EMA REACH assessments force biodegradable active development for reduced aquatic ecosystem persistence. |
| Diagnostic Service Integration | Fecal egg count testing deployment in UK and Irish flocks halves anthelmintic use and challenges volume-dependent pricing. |
Research Methodology
Regulatory filings with FDA's Center for Veterinary Medicine, EMA's Committee for Medicinal Products for Veterinary Use, and ANVISA veterinary product registrations formed the secondary backbone for market sizing and approval pathway mapping. Primary interviews with veterinary pharmaceutical R&D directors, livestock feedlot procurement managers, companion animal practice owners, and distribution channel partners validated demand assumptions and pricing dynamics. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators produced volume and value estimates.
Historical trendline analysis of anthelmintic and endectocide sales trajectories informed baseline growth assumptions across the projection horizon. The analytical framework segmented by active compound class, species application, administration route, and regional regulatory cluster. CAGRs derived from fitted growth curves adjusted for patent expiry cycles, resistance-driven product obsolescence, and environmental compliance cost pass-through. Forecast inputs incorporated veterinary practitioner density trends, livestock herd intensification rates, and companion animal premiumization indices.
Several conditions sit outside the modeled scope, including unforeseen anthelmintic resistance mutations, abrupt regulatory bans on macrocyclic lactone classes, and trade disruption affecting fermentation feedstock supply. Forecasts reflect assumptions about continued veterinary pharmaceutical consolidation and stable residue monitoring enforcement intensity. Practitioners should monitor ECHA substance-of-very-high-concern designations, FDA abbreviated new animal drug approval pathway modifications, and Brazilian real currency volatility for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Asia-Pacific Veterinary Healthcare Market
Veterinary
Veterinary Intravenous (IV) Solutions Market
Veterinary
United Kingdom Veterinary Healthcare Market
Veterinary
Global Porcine Vaccine Market
Veterinary
Veterinary Thermography Market
Veterinary
Veterinary Clostridium Vaccine Market
Veterinary
Veterinary Vaccines Market
Veterinary
Global Canine Influenza Vaccine Market
Veterinary
Global Animal Parasiticides Market
Veterinary
Veterinary Biomarkers Market
Veterinary
Global Veterinary MRI Market
Veterinary
Veterinary Immunodiagnostics Market
Veterinary
Canine Separation Anxiety Treatment Market
Veterinary
Bovine Mastitis Treatment System Market
Veterinary
Global Animal Model Market
Veterinary
Pet Light Therapy Devices Market