
 Single-Use Centrifuge System Market | 2026-2036
Single-Use Centrifuge System Market Size, Share, and Industry Trends Forecast 2026-2036
Single-Use Centrifuge System Market Outlook
Aftermarket service revenue is narrowing as equipment OEMs bundle predictive maintenance into platform licensing agreements. Danaher Corporation leverages its life sciences instrumentation portfolio to anchor recurring consumable sales alongside hardware placements. Sartorius AG sustains R&D intensity in polymer formulation science to differentiate its bioprocessing membrane technologies. Thermo Fisher Scientific controls distribution scale across North American and European biopharma corridors.
A single-use centrifuge system employs gamma-sterilized polymeric rotors, sealed drive assemblies, and disposable fluid contact surfaces to execute density-based separation without steam-in-place cleaning validation. These systems process cell cultures, blood derivatives, and recombinant protein suspensions at rotational speeds typically spanning 500 to 15,000 RPM while eliminating equipment turnaround downtime between batches. Batch Systems occupy the dominant installed base among contract manufacturing organizations running campaign-style production, whereas Continuous Flow Systems represent the fastest-expanding product category as perfusion bioprocessing gains adoption in monoclonal antibody facilities. Automated Systems command premium positioning through integrated in-process analytics that reduce manual sampling interventions.
FDA process validation guidance and EMA Annex 15 requirements jointly shape equipment qualification protocols for single-use technologies in GMP environments. ISO 13485 quality management standards and USP Class VI biocompatibility testing further constrain material selection for fluid-contact polymers. BIS certification requirements in India and NMPA registration pathways in China add country-specific compliance layers for multinational suppliers. Stakeholders must monitor evolving extractables and leachables testing standards as regulatory agencies tighten scrutiny on polymer additive migration into parenteral drug products.
Market Dynamics
Perfusion bioprocessing adoption is compressing batch cycle times and forcing equipment suppliers to engineer continuous-flow single-use centrifuge architectures that eliminate steam-in-place validation bottlenecks entirely.
Growth Catalysts
- EMA Annex 15 process validation requirements:European biopharmaceutical manufacturers face mandatory equipment qualification protocols that favor single-use technologies with pre-validated disposable fluid paths over stainless-steel alternatives requiring extensive cleaning validation documentation.
- Cell and gene therapy manufacturing expansion:Viral vector production facilities in Massachusetts and California deploy single-use centrifuge systems to prevent cross-contamination between patient-specific batches in multi-product cleanroom environments.
- Gamma-sterilized polymer rotors:Advances in high-performance thermoplastic formulations enable rotational speeds exceeding 10,000 RPM while maintaining USP Class VI biocompatibility certification for parenteral drug contact surfaces.
Market Restraints
- Specialized polymer supply concentration:Medical-grade polycarbonate and polysulfone resin production concentrates among German and US chemical suppliers, exposing equipment OEMs to input cost volatility and allocation constraints during capacity tightness.
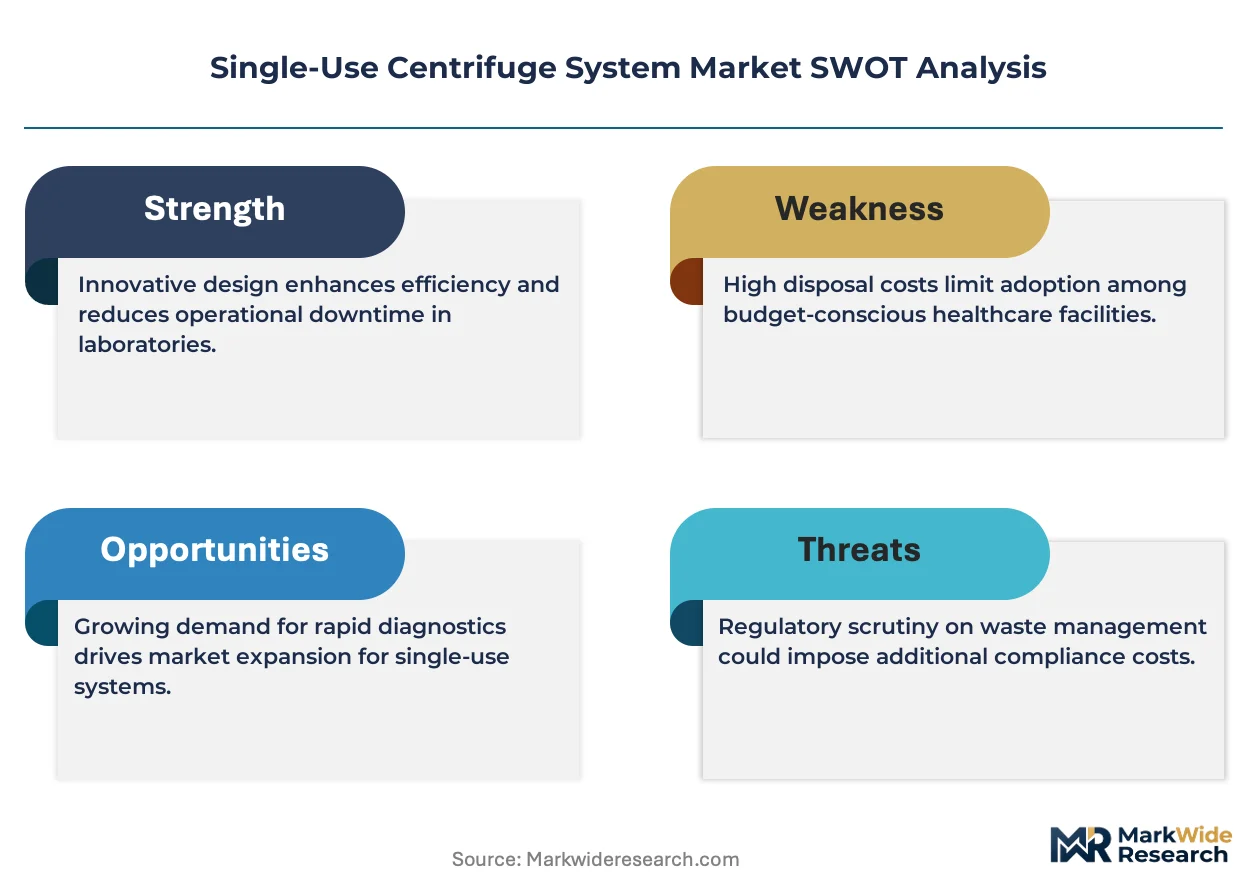
- Extractables and leachables testing burden:FDA guidance on polymer additive migration into biologic drug products imposes extended qualification timelines and analytical chemistry costs that delay new material introductions.
- Stainless-steel equipment residual value:Established biopharmaceutical facilities with depreciated capital infrastructure face switching cost barriers when evaluating full platform replacement versus hybrid single-use integration.
Strategic Opportunities
- Indian CDMO capacity expansion:BIS certification requirements and CDSCO manufacturing facility approvals create first-mover advantage for suppliers establishing localized technical service and polymer formulation partnerships in Hyderabad and Bengaluru clusters.
- Integrated in-process analytics convergence:Automated single-use centrifuge platforms combining turbidity sensors and conductivity probes enable real-time cell density monitoring that reduces manual sampling interventions in perfusion bioreactor trains.
- Japan PMDA regenerative medicine pathway:Accelerated approval frameworks for cell therapy products drive demand for closed-system processing equipment that eliminates open manipulation steps in induced pluripotent stem cell manufacturing.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists with expertise in gamma-irradiation stability and biocompatibility testing command premium compensation, constraining R&D expansion at mid-scale equipment suppliers.
- Legacy SCADA integration complexity:Brownfield biologics facilities require custom communication protocol bridges to connect single-use centrifuge controllers with established distributed control systems, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single-Use Centrifuge System Market |
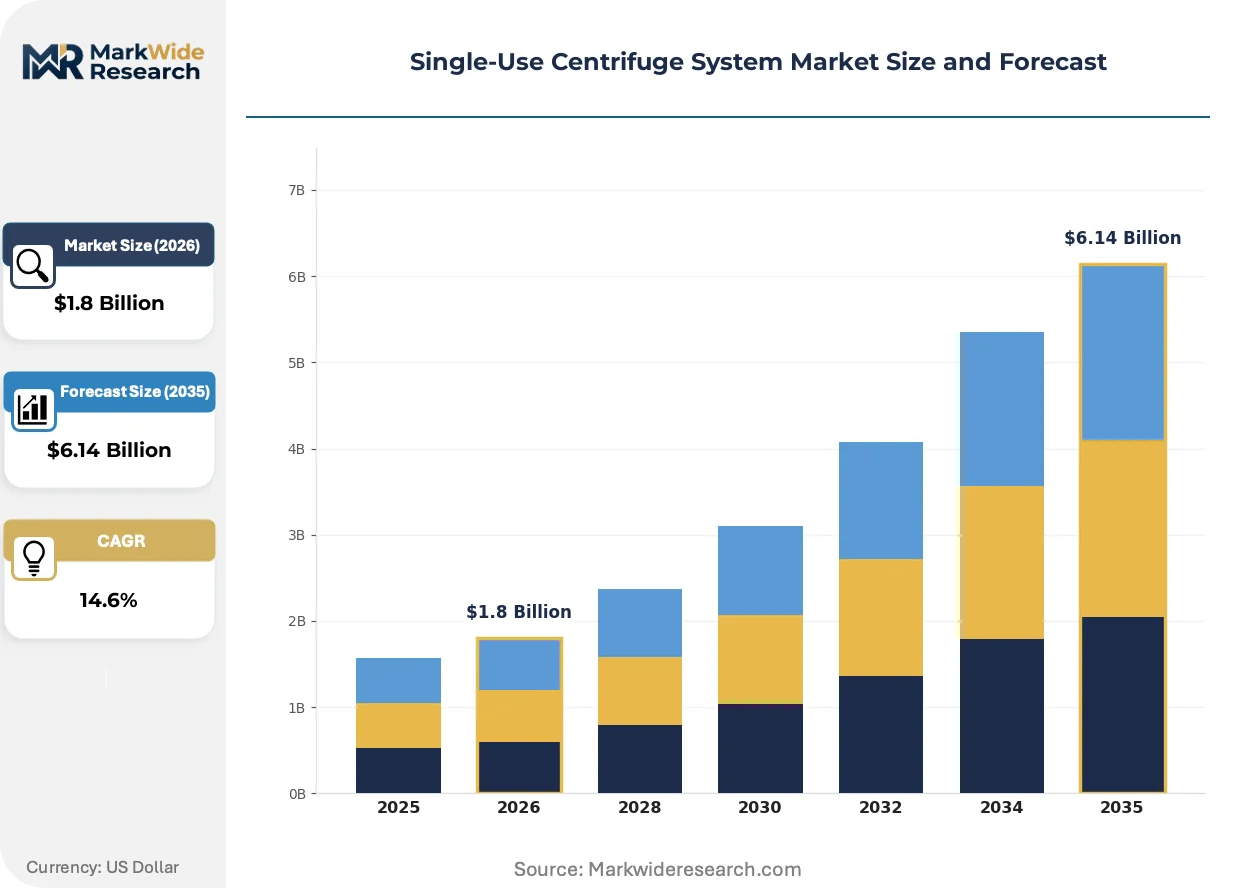
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Systems, Continuous Flow Systems, Integrated Systems, Automated Systems End User: Pharmaceutical Companies, Biotech Firms, Contract Manufacturing Organizations, Research Institutions Application: Cell Separation, Plasma Processing, Particle Removal, Protein Purification Technology: Filtration, Sedimentation, Self-Contained Systems, Hybrid Systems |
| Companies Covered | Sartorius AG, Thermo Fisher Scientific, Danaher Corporation, Merck KGaA, Alfa Laval, GEA Group, Becton Dickinson and Company, Eppendorf AG, Fresenius Kabi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single-Use Centrifuge System Market Strategic Shifts
Equipment architectures are converging around closed-system processing principles that eliminate open manipulation steps, while regulatory pressure on extractables documentation accelerates material science investment.
Continuous flow centrifuge technology is migrating from niche perfusion applications toward mainstream monoclonal antibody production. Contract manufacturing organizations in North Carolina and Belgium adopt these systems to achieve 30-day campaign durations without equipment turnaround downtime. The shift compresses capital deployment cycles and reduces cleanroom footprint requirements by eliminating dedicated cleaning infrastructure.
REACH restrictions on phthalate plasticizers and ECHA scrutiny of bisphenol-A derivatives constrain polymer additive selection for fluid-contact components. Equipment suppliers reformulate rotor housings and seal materials to maintain mechanical performance under gamma sterilization while meeting evolving substance restriction thresholds. European biopharmaceutical manufacturers now prioritize suppliers with full material disclosure documentation ahead of hardware performance specifications.
Service contract unbundling is fragmenting traditional aftermarket revenue streams. Large biopharma procurement functions negotiate predictive maintenance algorithms as standalone software licenses rather than bundled hardware-service packages. This behavioral shift concentrates in Massachusetts and California metropolitan clusters where sophisticated buyer organizations maintain internal metrology and calibration capabilities. Equipment OEMs respond by developing consumption-based pricing tied to processed batch volumes rather than fixed service agreements.
Single-Use Centrifuge System Market Segmentation
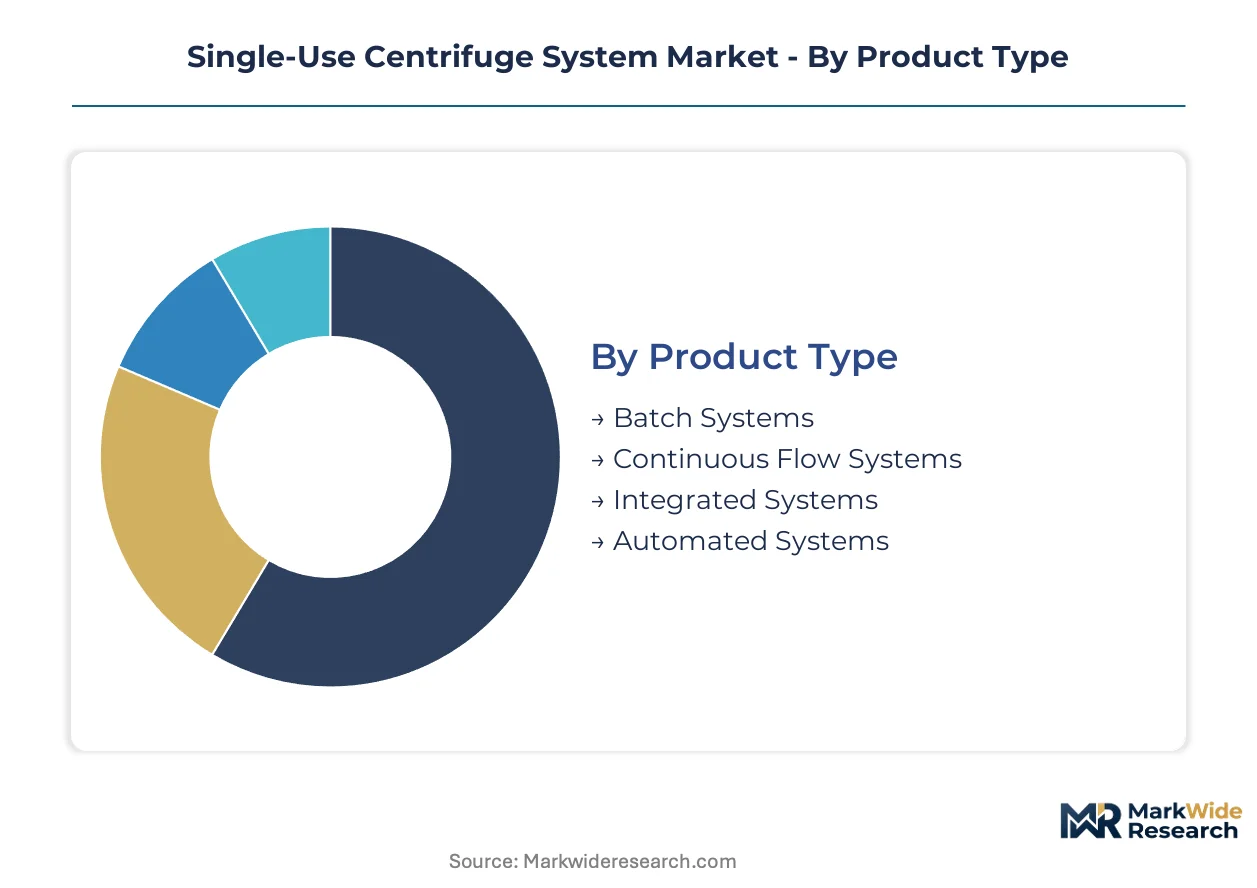
Segmentation in single-use centrifuge systems reveals distinct equipment turnover patterns driven by campaign duration, regulatory validation cycles, and facility infrastructure age. Understanding these velocity differentials enables suppliers to align polymer formulation roadmaps with segment-specific replacement frequencies.
Product Type:
Cycle times vary dramatically across architectures, with continuous-flow platforms turning over in months versus batch systems persisting for years in depreciated installed bases.
- Batch Systems:These platforms process discrete volumes through gamma-sterilized polymeric rotors with sealed drive assemblies, requiring full equipment qualification between campaigns. Contract manufacturing organizations in Massachusetts and North Carolina deploy these for multi-product biologics manufacturing where steam-in-place validation bottlenecks mandate disposable fluid paths.
- Continuous Flow Systems:Architectures engineered for perfusion bioprocessing eliminate batch turnover downtime entirely by maintaining steady-state operation across 30-day campaign durations. Belgian and California monoclonal antibody facilities adopt these systems to compress capital deployment cycles and reduce cleanroom footprint requirements.
- Integrated Systems:Pre-assembled skid-mounted configurations reduce field commissioning timelines through factory acceptance testing protocols.
- Automated Systems:Platforms combining turbidity sensors and conductivity probes command premium positioning through real-time cell density monitoring capabilities.
Batch Systems dominate installed base. Continuous Flow Systems is where expansion concentrates.
End User:
Cost tier stratification separates capital-intensive biopharma manufacturers from research-scale buyers with constrained procurement budgets.
- Pharmaceutical Companies:Large-scale biologics manufacturers in Boston and San Francisco metropolitan areas purchase automated platforms with integrated in-process analytics. These buyers negotiate predictive maintenance algorithms as standalone software licenses rather than bundled hardware-service packages.
- Contract Manufacturing Organizations:CDMOs running campaign-style production prioritize batch systems with rapid polymer rotor replacement capabilities to prevent cross-contamination between client programs. Hyderabad and Bengaluru clusters in India represent emerging demand centers as BIS certification requirements create localized technical service needs.
- Biotech Firms:Venture-funded developers favor flexible leasing arrangements over capital purchases during clinical-stage manufacturing.
- Research Institutions:Academic buyers concentrate demand for lower-throughput systems with simplified qualification documentation requirements.
Contract Manufacturing Organizations anchor current revenue concentration. Biotech Firms represent the steepest expansion trajectory as cell and gene therapy pipelines mature.
Application:
Volume throughput requirements differentiate high-frequency plasma processing from specialized cell separation protocols with extended cycle times.
- Cell Separation:Density-based isolation of mammalian cell cultures and induced pluripotent stem cells demands closed-system processing to eliminate open manipulation steps. Japan PMDA regenerative medicine pathway requirements drive specifications for patient-specific batch traceability in cell therapy manufacturing.
- Protein Purification:Recombinant protein suspension processing at rotational speeds exceeding 10,000 RPM requires USP Class VI biocompatibility certification for parenteral drug contact surfaces. FDA extractables and leachables guidance imposes extended qualification timelines on polymer additive selection for these applications.
- Plasma Processing:Blood derivative fractionation relies on gamma-sterilized fluid contact surfaces with validated viral clearance capabilities.
- Particle Removal:Clarification steps in upstream bioprocessing employ lower-speed centrifugation to protect shear-sensitive cell cultures.
Protein Purification commands premium pricing tiers. Cell Separation is climbing the fastest as regenerative medicine manufacturing scales.
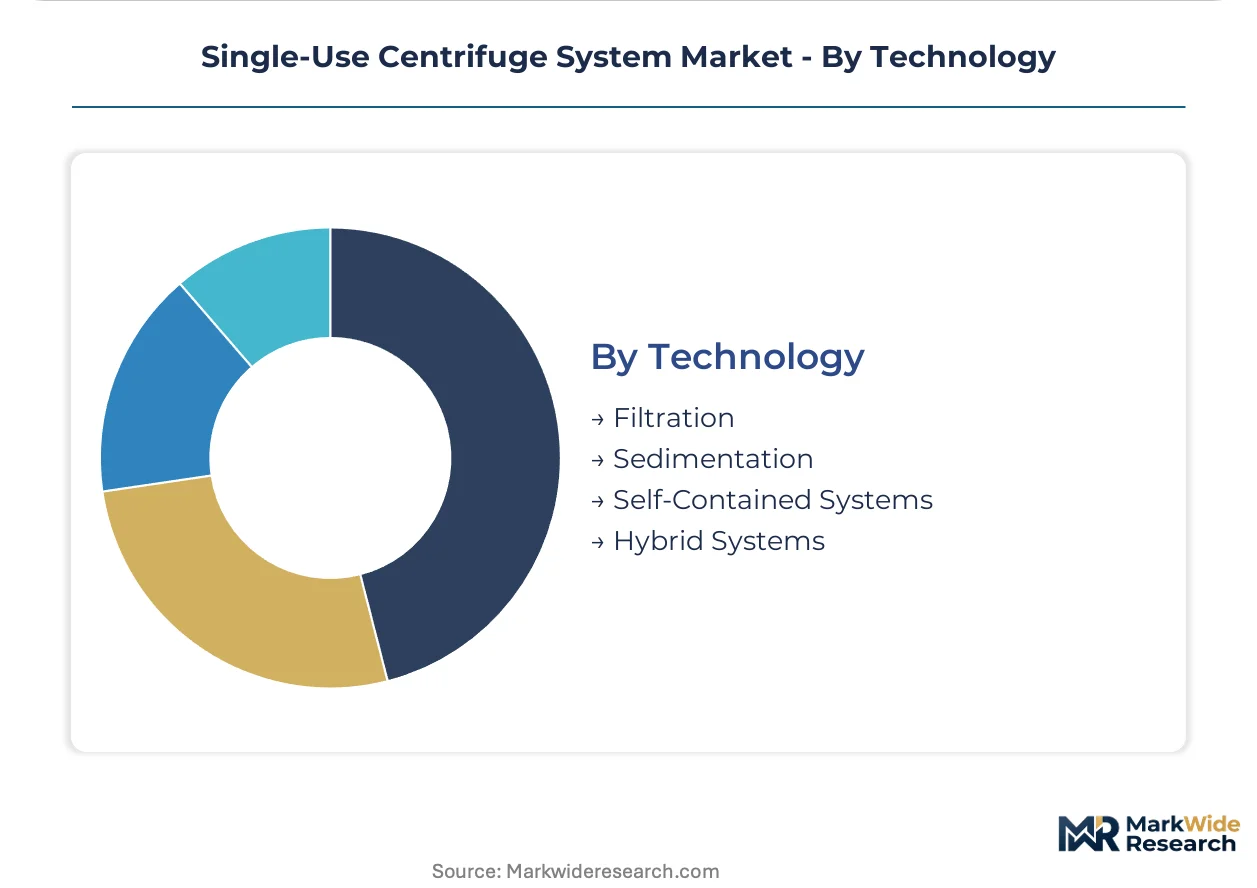
Technology:
Supply concentration in polymer formulation science constrains technology migration paths, with sedimentation expertise residing among German chemical suppliers.
- Self-Contained Systems:Fully enclosed architectures with disposable fluid paths eliminate equipment turnaround downtime between batches. EMA Annex 15 process validation requirements favor these platforms over stainless-steel alternatives requiring extensive cleaning validation documentation.
- Hybrid Systems:Configurations combining centrifugal separation with tangential flow filtration modules address complex cell culture broth clarification challenges. These platforms gain traction in perfusion bioreactor trains where real-time cell density monitoring reduces manual sampling interventions.
- Sedimentation:Density-gradient separation protocols rely on precisely controlled acceleration profiles for blood derivative processing.
- Filtration:Membrane-based clarification alternatives compete with centrifugal methods for low-cell-density applications.
Self-Contained Systems anchor qualification-driven procurement decisions. Hybrid Systems is gaining share fastest as integrated process intensification advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States biopharmaceutical buyers exhibit the lowest price elasticity, absorbing premium automated platforms with integrated analytics, while Indian contract manufacturers face acute cost sensitivity that favors batch systems with rapid rotor replacement cycles.
United States
FDA process validation guidance and cell therapy manufacturing expansion in Massachusetts and California drive specification requirements. Boston metropolitan biologics clusters deploy automated single-use centrifuge platforms with predictive maintenance algorithms as standalone software licenses. San Francisco Bay Area viral vector facilities prioritize closed-system processing to prevent cross-contamination between patient-specific batches.
Germany
EMA Annex 15 equipment qualification protocols and REACH restrictions on phthalate plasticizers reshape polymer formulation roadmaps. Medical-grade polycarbonate and polysulfone resin production concentrates among specialized chemical suppliers near Frankfurt and Leverkusen. Equipment OEMs in Baden-Württemberg reformulate rotor housings to maintain gamma-irradiation stability while meeting evolving substance restriction thresholds.
Japan
PMDA accelerated approval frameworks for regenerative medicine products and induced pluripotent stem cell manufacturing expansion create specifications for patient-specific batch traceability. Kanto region cell therapy facilities demand closed-system processing equipment that eliminates open manipulation steps. Osaka-based biologics manufacturers integrate real-time cell density monitoring to reduce manual sampling interventions.
India
BIS certification requirements and CDSCO manufacturing facility approvals concentrate demand among Hyderabad and Bengaluru contract manufacturing clusters. Domestic CDMOs running campaign-style production prioritize batch systems with rapid polymer rotor replacement to prevent cross-contamination between client programs. Localized technical service partnerships emerge as first-mover advantages for multinational suppliers establishing regional presence.
Belgium
Continuous flow centrifuge adoption in monoclonal antibody facilities and perfusion bioprocessing integration compress capital deployment cycles. Flemish biologics manufacturers achieve 30-day campaign durations without equipment turnaround downtime. Wallonia-based facilities reduce cleanroom footprint requirements by eliminating dedicated steam-in-place cleaning infrastructure.
Single-Use Centrifuge System Market Competitive Environment
Integrated life sciences conglomerates and specialized bioprocessing equipment fabricators split the market along capability depth versus portfolio breadth lines. Tier-one suppliers anchor recurring consumable revenue through hardware placements, while mid-scale specialists concentrate polymer formulation science differentiation. Three strategic archetypes dominate: instrumentation conglomerates leveraging distribution scale, membrane technology specialists sustaining R&D intensity, and precision engineering houses controlling gamma-sterilization protocols. Competitive dynamics center on predictive maintenance algorithm licensing and regional technical service expansion.
Within the instrumentation conglomerate tier, Danaher Corporation and Thermo Fisher Scientific exemplify platform licensing strategies that bundle consumable sales with hardware placements. Sartorius AG occupies a position among membrane technology specialists, anchoring differentiation through sustained investment in polymer formulation science. These three entities represent the dominant competitive anchors, with geographic coverage concentrating in North American and European biopharma corridors where sophisticated procurement functions negotiate unbundled service contracts.
| Leading Market Players |
|---|
| Sartorius AG |
| Thermo Fisher Scientific |
| Danaher Corporation |
| Merck KGaA |
| Alfa Laval |
| GEA Group |
| Becton Dickinson and Company |
| Eppendorf AG |
| Fresenius Kabi |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in German medical-grade polymer resin production is compressing input costs for rotor housing manufacturers while simultaneously eroding pricing power among mid-scale equipment suppliers competing on material specifications rather than platform integration.
Pricing Analysis
Aftermarket service contracts anchored through predictive maintenance algorithm licensing now generate lifetime value exceeding hardware margins for tier-one suppliers. Three-tier pricing structure across premium automated platforms, standard batch systems, and economy research-grade configurations stratifies the market, with certification grade and integrated analytics capabilities driving differentiation. Pricing pressure stems from biopharma procurement functions negotiating unbundled software licenses rather than bundled hardware-service packages. Contract manufacturing organizations in India exhibit acute price sensitivity, while Massachusetts biologics clusters absorb premium positioning for closed-system processing equipment.
Supply Chain Analysis
Tariff exposure between United States and Chinese chemical suppliers dominates risk planning for polycarbonate and polysulfone resin procurement. Medical-grade polymer formulation concentrates in Germany, the United States, and Japan, with equipment OEMs drawing from specialized chemical suppliers near Frankfurt and Leverkusen. Single-source vulnerability in gamma-irradiation sterilization capacity creates bottlenecks for rotor assembly qualification. Distribution runs through direct technical service partnerships in biopharma manufacturing clusters, with regional stocking locations in Boston, San Francisco, and Hyderabad supporting campaign-style production timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Perfusion bioprocessing adoption represents a technological inflection forcing equipment architecture redesign, while EMA Annex 15 validation requirements create regulatory tailwinds for disposable fluid path technologies.
For Market Incumbents: Build predictive maintenance algorithm moats through integrated in-process analytics that reduce manual sampling interventions. Secure polymer formulation partnerships with German chemical suppliers to defend rotor housing specifications against REACH substance restrictions. Expand technical service density in Hyderabad and Bengaluru clusters before BIS certification requirements solidify competitive positions.
For New Entrants and Emerging Players: Indian CDMO capacity expansion offers the most penetrable geographic entry point for batch systems with rapid rotor replacement capabilities. Target cell and gene therapy viral vector facilities in California with closed-system processing equipment that eliminates cross-contamination risks. Pursue flexible leasing arrangements for venture-funded biotech firms during clinical-stage manufacturing to bypass capital purchase barriers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automated platform suppliers with standalone software licensing capabilities. Long-term viability favors membrane technology specialists sustaining R&D intensity in gamma-irradiation stability science. Monitor extractables and leachables testing standard evolution as the signal for polymer additive migration scrutiny tightening.
| Strategic Initiative | Industry Significance |
|---|---|
| Polymer Formulation Partnership | Secures gamma-irradiation stable rotor housings meeting REACH phthalate restrictions for EMA compliance. |
| Predictive Maintenance Algorithm Licensing | Converts hardware placements into recurring software revenue streams unbundled from service contracts. |
| Regional Technical Service Expansion | Establishes BIS certification support capabilities in Hyderabad clusters ahead of CDMO capacity buildout. |
| Continuous Flow Architecture Development | Eliminates steam-in-place validation bottlenecks for perfusion bioprocessing in monoclonal antibody facilities. |
| Closed-System Processing Integration | Prevents cross-contamination between patient-specific batches in Massachusetts cell therapy manufacturing. |
Study Parameters
Operator-level perspectives from bioprocess engineers, regulatory affairs specialists, CDMO procurement managers, and polymer formulation scientists anchored the qualitative base. Primary interviews with equipment OEM technical service heads and gamma-sterilization facility operators combined with secondary validation from FDA guidance documents, EMA Annex 15 requirements, and ISO 13485 certification databases. Bottom-up segment sizing across batch, continuous flow, and automated system architectures triangulated against top-down industry spend estimates from biopharma capital expenditure disclosures.
Scenario-bracketing around perfusion bioprocessing adoption rates and REACH substance restriction timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, end-user scale tier, application protocol, and regional regulatory cluster. CAGRs derived from equipment replacement velocity differentials and polymer consumable attach rates. Industry-specific forecast inputs incorporated viral vector manufacturing capacity buildout and induced pluripotent stem cell facility commissioning timelines.
Practitioners should monitor extractables testing standard evolution and polymer resin allocation constraints for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
India Hemostats Market
Medical Devices
Global Cardiac Resuscitation Device Market
Medical Devices
Low Flux Single-Use Dialyzers Market
Medical Devices
Indwelling Catheter Market
Medical Devices
Guide Extension Catheter Market
Medical Devices
3D-Printed Prosthetic Implants Market
Medical Devices
Pathology Devices Market
Medical Devices
High Pressure Contrast Media Injectors Market
Medical Devices
US External Counterpulsation Devices Market
Medical Devices
Powered Mattress System Market
Medical Devices
Transcatheter Mitral Valve Market
Medical Devices
Pleural Cavity Drainage Market
Medical Devices
Australia Contraceptive Devices Market
Medical Devices
Stethoscope Hygiene Devices Market
Medical Devices
Disposable Contact Lenses Market
Medical Devices
North America and Europe Group 2 Powered Mobility Devices Market