
 Global Veterinary Endoscopy Market | 2026-2036
Global Veterinary Endoscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Veterinary Endoscopy Market Foresight
Buyer concentration among multi-site veterinary hospital groups is decoupling from traditional single-practice procurement patterns. KARL STORZ leverages its rigid endoscope manufacturing depth to anchor supply relationships with European university teaching hospitals. Olympus Corporation competes through video system integration across flexible and rigid platforms for large companion animal applications. Fujifilm Holdings Corporation differentiates via image processing architectures adapted from human healthcare portfolios.
Veterinary endoscopy encompasses minimally invasive visualization systems employing fiber-optic or digital image sensors with working channels typically ranging from 1.0 to 2.8 millimeters for diagnostic and interventional procedures in companion and production animals. Flexible endoscopes dominate procedural volume in gastrointestinal and respiratory examinations due to anatomical navigability, while rigid endoscopes capture margin concentration in arthroscopic and laparoscopic surgical applications. Video endoscopes are displacing fiber-optic systems in premium-tier installations as high-definition and 4K modalities transfer from human medical platforms.
FDA Center for Veterinary Medicine maintains device classification oversight, while EU MDR and ISO 13485 quality management standards govern market access pathways for manufacturers serving both jurisdictions. Japan's PMDA and METI coordinate standards alignment that conditions import eligibility for non-domestic suppliers. Stakeholders must monitor regulatory divergence between US and EU quality system requirements as veterinary-specific guidance documents remain underdeveloped relative to human medical device frameworks.
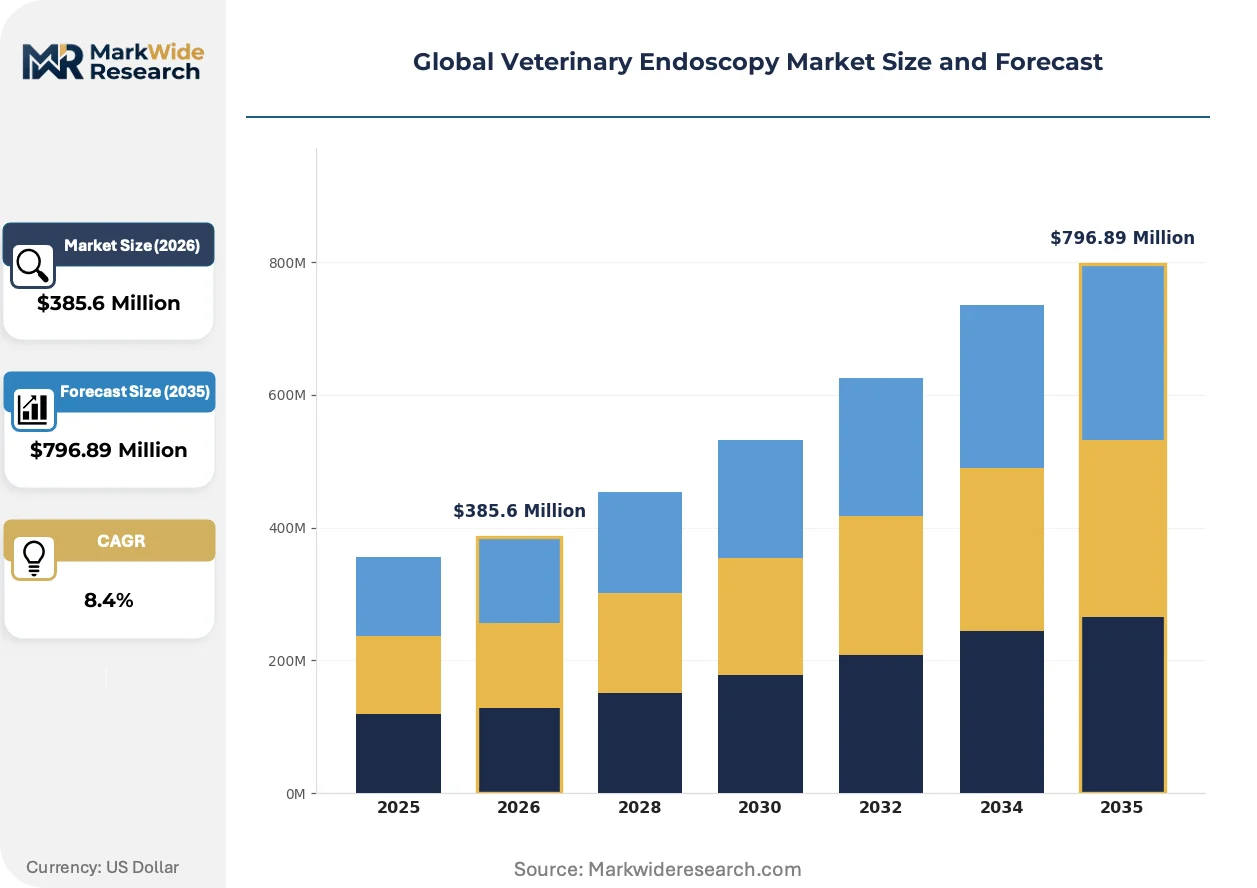
Market Dynamics
Video endoscopes are compressing fiber-optic system margins as specialty veterinary clinics in the United States, Germany, and Japan accelerate capital refresh cycles toward high-definition and 4K modalities transferred from human healthcare platforms.
Growth Catalysts
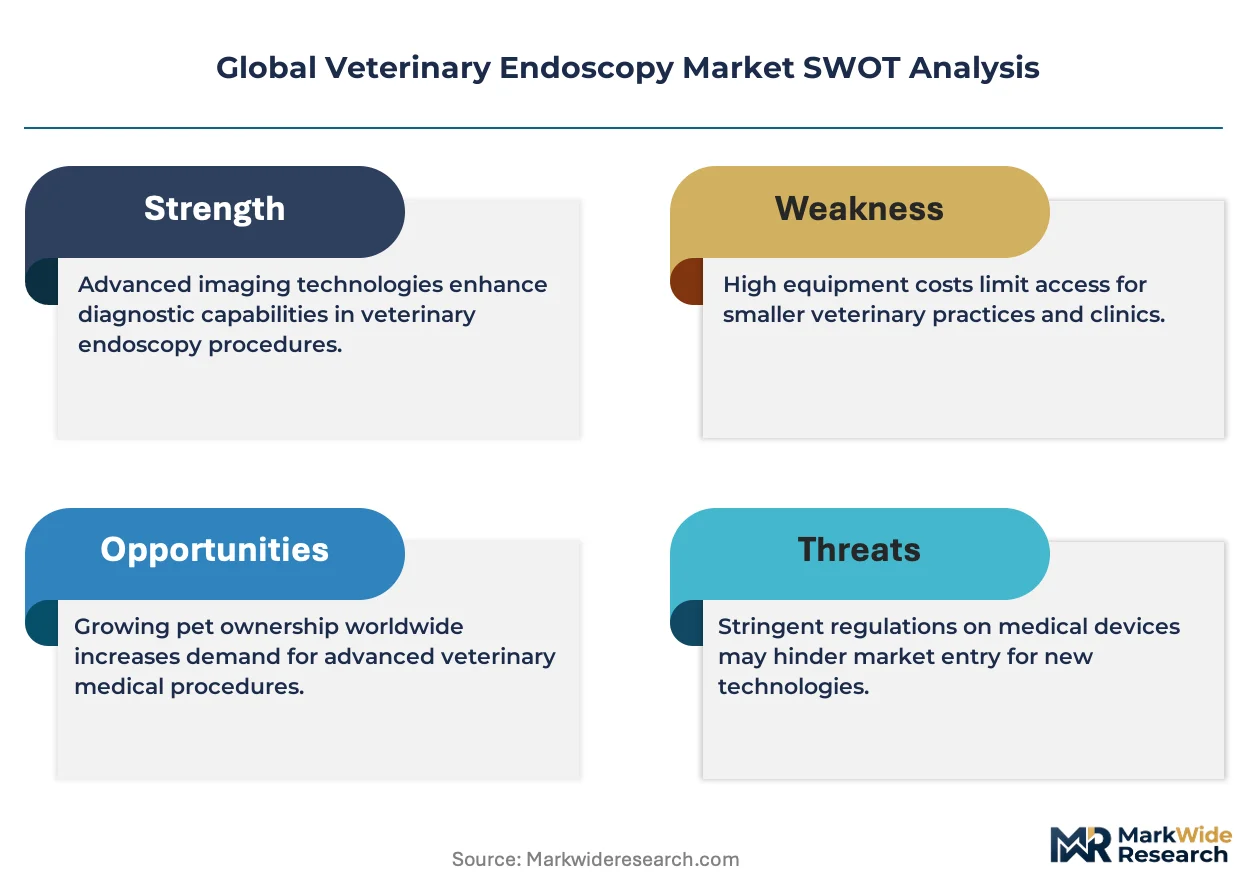
- EU Medical Device Regulation:Elevated compliance requirements are filtering marginal manufacturers from the European supply base, consolidating procurement relationships with quality-certified vendors capable of ISO 13485-aligned production.
- Pet insurance penetration:Referral-level specialty practice density in the United States and Japan supports capital investment in advanced visualization platforms previously restricted to human medical budgets.
- Minimally invasive surgical protocols:University teaching hospitals in Germany and the Netherlands are standardizing arthroscopic and laparoscopic curricula, embedding rigid endoscopy competency into veterinary specialist training pipelines.
Market Restraints
- Optical component supply concentration:Image sensor and fiber-bundle manufacturing concentrates in East Asian foundries, exposing European and North American assemblers to input cost volatility and logistics disruption.
- FDA Center for Veterinary Medicine oversight gaps:Absence of veterinary-specific premarket guidance creates regulatory friction, forcing manufacturers to navigate human-device classification analogies that delay market entry timelines.
- Capital intensity threshold:Flexible endoscopy platforms require dedicated sterilization infrastructure and technician training that excludes single-practice operators from the installed base expansion.
Strategic Opportunities
- Production animal applications:Bovine and equine reproductive endoscopy remains underpenetrated relative to companion animal segments, offering volume expansion for manufacturers with durable instrument designs.
- Japan PMDA-METI standards alignment:Coordinated import eligibility frameworks condition market access for non-domestic suppliers meeting JIS quality benchmarks, creating regulatory tailwinds for compliant entrants.
- Telemedicine integration:Remote image transmission capabilities are converging with cloud-based diagnostic support, enabling hub-and-spoke service models that extend specialist reach into rural veterinary networks.
Industry Challenges
- Veterinary endoscopy technician certification:Absence of standardized credentialing programs across the United States and European Union creates skill variability that complicates equipment utilization rates and warranty claim resolution.
- Legacy fiber-optic system obsolescence:Discontinued component support for first-generation platforms forces premature capital write-downs among budget-constrained independent practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Veterinary Endoscopy Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $796.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Endoscopes, Rigid Endoscopes, Video Endoscopes, Capsule Endoscopes, Accessories Application: Diagnostic Procedures, Surgical Procedures, Therapeutic Procedures, Preventive Care, Research End User: Veterinary Clinics, Animal Hospitals, Diagnostic Laboratories, Research Institutions Distribution Channel: Direct Sales, Online Platforms, Distributors, Veterinary Equipment Retailers |
| Companies Covered | KARL STORZ, Olympus Corporation, Steris, Biovision Veterinary Endoscopy, Dr. Fritz Endoscopes, Eickemeyer, Fujifilm Holdings Corporation, Endoscopy Support Services, Welch Allyn, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Veterinary Endoscopy Market Shifts & Advancements
Digital image processing architectures are compressing the capability gap between veterinary and human medical visualization systems, reshaping procurement criteria and supplier competitive positioning across multiple geographies.
Single-use endoscope sheaths are decentralizing sterilization workflows by eliminating high-level disinfection cycles between procedures. Multi-site hospital groups in the United States are adopting these disposable barriers to maximize equipment utilization rates. This technology is decentralizing capital planning away from centralized reprocessing infrastructure toward per-procedure consumable budgeting.
EU MDR technical documentation requirements are elevating clinical evidence thresholds for veterinary device registrations previously grandfathered under withdrawn directives. Manufacturers serving both human and veterinary markets face portfolio prioritization pressures as notified body capacity constrains. Flexible endoscope suppliers with existing human-device conformity assessments are leveraging technical file cross-referencing to accelerate veterinary pathway completion.
Specialty practice consolidation is compressing vendor negotiation leverage as purchasing committees standardize equipment specifications across affiliated clinics. Independent distributors in Germany and France are losing direct access to decision-makers as hospital group procurement offices centralize supplier qualification. This concentration is most visible in the United States, where corporate veterinary platforms now control a substantial share of flexible endoscope procurement volume.
Global Veterinary Endoscopy Market Segmentation
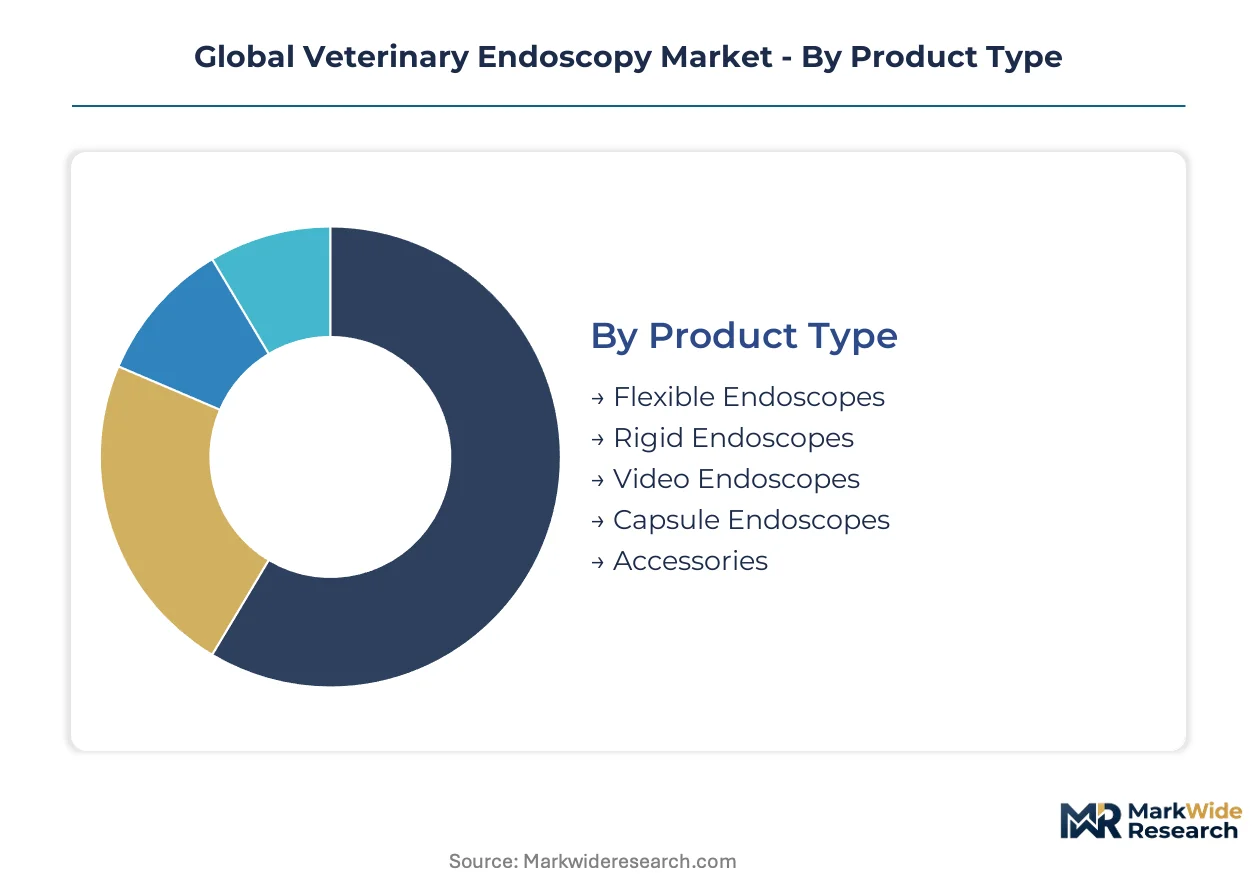
Veterinary endoscopy procurement varies sharply by clinical setting and procedure type, with certification requirements, sterilization infrastructure, and capital intensity creating distinct addressable markets for each segment configuration.
Product Type:
EU MDR and FDA Center for Veterinary Medicine oversight apply differentially across these segments, with video endoscopes facing the steepest clinical evidence requirements and capsule systems navigating novel device classification ambiguity.
- Flexible Endoscopes:Fiber-optic or digital platforms with working channels of 1.0–2.8 millimeters enable gastrointestinal and respiratory navigation in companion animals. Demand concentrates in United States specialty clinics where pet insurance reimbursement supports capital refresh cycles toward high-definition modalities.
- Video Endoscopes:Digital image sensor architectures with 4K resolution capabilities transferred from human medical platforms are displacing fiber-optic systems in premium-tier installations. German university teaching hospitals anchor European procurement volume as arthroscopic and laparoscopic curricula standardize.
- Rigid Endoscopes:Stainless steel sheath designs with rod-lens optical systems dominate surgical applications requiring instrument stability.
- Capsule Endoscopes:Ingestible wireless imaging platforms face regulatory friction due to veterinary-specific premarket guidance gaps.
- Accessories:Biopsy forceps, retrieval baskets, and irrigation pumps complete procedural workflows.
Leading the category by volume: Flexible Endoscopes. Expanding most quickly: Video Endoscopes.
Application:
Procedure reimbursement economics and technician certification requirements segment demand, with surgical applications commanding capital premiums and diagnostic workhorses driving installed base expansion.
- Diagnostic Procedures:Gastrointestinal examination and respiratory assessment constitute the procedural volume foundation, with flexible platforms enabling visualization without general anesthesia in select cases. United States multi-site hospital groups prioritize diagnostic throughput metrics in procurement specifications.
- Surgical Procedures:Arthroscopy, laparoscopy, and thoracoscopy require rigid platforms with integrated video systems and specialized instrument portals. Japanese specialty practices lead Asia-Pacific adoption as PMDA-METI standards alignment clarifies import pathways.
- Therapeutic Procedures:Foreign body retrieval and polypectomy bridge diagnostic and surgical categories.
- Preventive Care:Screening protocols in high-value production animals remain underdeveloped relative to companion segments.
- Research:Preclinical imaging demands drive specialized configurations for pharmaceutical and academic institutions.
Dominant by procedure count: Diagnostic Procedures. Steepest expansion trajectory: Surgical Procedures.
End User:
Capital intensity thresholds and sterilization infrastructure availability fragment the customer base, with consolidation trends favoring vendors capable of enterprise-scale service contracts.
- Veterinary Clinics:Single-practice and small-group operators face exclusion from flexible endoscopy markets due to reprocessing infrastructure costs and technician training requirements. Independent German and French distributors retain residual access here.
- Animal Hospitals:Multi-site corporate platforms in the United States centralize procurement through dedicated purchasing committees, compressing vendor negotiation leverage and standardizing specifications across affiliated clinics.
- Diagnostic Laboratories:Reference laboratory networks leverage remote image transmission capabilities for hub-and-spoke service models.
- Research Institutions:University teaching hospitals in the Netherlands and Germany embed rigid endoscopy competency into specialist training pipelines.
Volume leader: Animal Hospitals. Gaining share fastest: Diagnostic Laboratories.
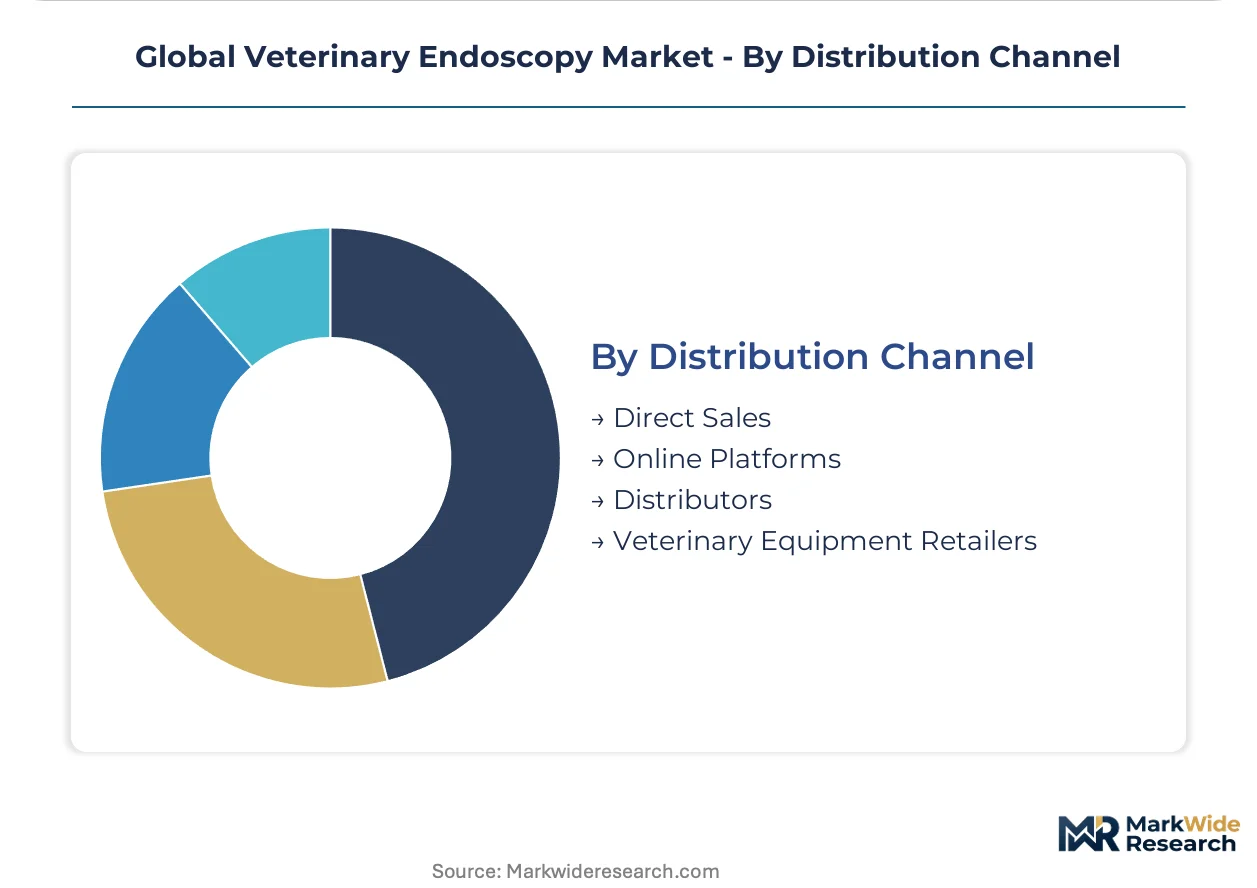
Distribution Channel:
Channel selection correlates with customer scale and geographic market maturity, with direct relationships dominating consolidated accounts and intermediaries serving fragmented demand.
- Direct Sales:Manufacturer field organizations manage enterprise accounts for multi-site hospital groups and university teaching hospitals, providing installation, training, and service integration. KARL STORZ and Olympus Corporation anchor European supply relationships through this channel.
- Distributors:Regional intermediaries retain relevance in fragmented markets where localized technical support and financing flexibility matter. French and German independent distributors face pressure as hospital group procurement offices centralize supplier qualification.
- Online Platforms:E-commerce penetration concentrates in accessories and consumables rather than capital equipment.
- Veterinary Equipment Retailers:Brick-and-mortar presence serves rural and independent practice segments with limited digital procurement capability.
Primary channel by value: Direct Sales. Climbing the fastest: Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, Germany, and Japan where pet insurance penetration and specialty practice density support capital investment in advanced visualization platforms. Veterinary endoscopy procurement patterns diverge sharply between mature markets with consolidated hospital groups and emerging markets where independent practices dominate.
United States
Multi-site veterinary hospital groups centralize procurement through dedicated purchasing committees, compressing vendor negotiation leverage across affiliated clinics. FDA Center for Veterinary Medicine maintains device classification oversight, though absence of veterinary-specific premarket guidance creates regulatory friction. Corporate veterinary platforms in California and Texas now control substantial shares of flexible endoscope procurement volume.
Germany
University teaching hospitals in Bavaria and North Rhine-Westphalia embed rigid endoscopy competency into veterinary specialist training pipelines. EU Medical Device Regulation elevates compliance requirements, filtering marginal manufacturers from the European supply base. KARL STORZ leverages its manufacturing depth to anchor supply relationships with European university teaching hospitals concentrated in Baden-Württemberg.
Japan
PMDA and METI coordinate standards alignment that conditions import eligibility for non-domestic suppliers meeting JIS quality benchmarks. Specialty practices in Tokyo and Osaka lead Asia-Pacific adoption of surgical endoscopy platforms. Japanese distributors face pressure as hospital group procurement offices centralize supplier qualification and standardize equipment specifications.
United Kingdom
Referral-level specialty practice density in London and Southeast England supports investment in high-definition and 4K modalities transferred from human healthcare platforms. MHRA post-Brexit regulatory divergence from EU MDR creates dual compliance burdens for manufacturers serving both jurisdictions. Independent distributors retain residual access in fragmented rural markets beyond the M25 corridor.
Netherlands
Veterinary universities in Utrecht standardize arthroscopic and laparoscopic curricula, embedding rigid endoscopy competency into specialist training pipelines. EU MDR technical documentation requirements elevate clinical evidence thresholds for device registrations. Diagnostic laboratory networks in Randstad leverage remote image transmission capabilities for hub-and-spoke service models extending into rural networks.
Global Veterinary Endoscopy Market Competitive Landscape
German producers anchor the premium-tier supply relationships with European university teaching hospitals; Japanese specialists hold integrated video system positions across flexible and rigid platforms. The vendor base organizes around three strategic archetypes: diversified medical technology conglomerates with veterinary divisions, pure-play veterinary endoscopy specialists, and human-device manufacturers cross-applying platforms. Dominant competitive moves include portfolio diversification into single-use consumables and strategic partnerships with multi-site hospital groups for enterprise service contracts.
Among diversified medical technology conglomerates, Olympus Corporation and Fujifilm Holdings Corporation exemplify the video system integration archetype across flexible and rigid platforms. KARL STORZ occupies a position representing European manufacturing depth in rigid endoscope supply relationships. These three anchors illustrate how human healthcare technology transfer and veterinary-specific manufacturing heritage represent distinct competitive vectors in procurement decisions by specialty clinics and teaching hospitals.
| Leading Market Players |
|---|
| KARL STORZ |
| Olympus Corporation |
| Steris |
| Biovision Veterinary Endoscopy |
| Dr. Fritz Endoscopes |
| Eickemeyer |
| Fujifilm Holdings Corporation |
| Endoscopy Support Services |
| Welch Allyn |
| Others |
Supply & Pricing Matrix
Captive in-house production of optical assemblies by KARL STORZ and Olympus Corporation anchors supply security for premium-tier veterinary endoscope manufacturers while compressing procurement leverage for European and North American assemblers dependent on East Asian component sourcing. This vertical integration choice secures margin control at the high end of the market but leaves mid-tier competitors exposed to input cost volatility from concentrated image sensor foundries.
Pricing Analysis
Volume concentrates in flexible diagnostic platforms while margins accrue to video endoscope systems with 4K resolution capabilities. Three-tier pricing structure across premium, standard, and economy levels separates university teaching hospital specifications from independent clinic procurement, with ISO 13485 certification tier and after-sales service bundling as primary price differentiation drivers. Cost compression in fiber-optic tiers is intensifying because video endoscopes are displacing legacy systems in capital refresh cycles. Single-practice operators exhibit highest price sensitivity while multi-site hospital groups prioritize total cost-of-ownership metrics over unit acquisition cost.
Supply Chain Analysis
Freight cost volatility from East Asian logistics corridors compounds margin pressure for European and North American veterinary endoscope assemblers sourcing CMOS image sensors and fiber-optic bundles. Manufacturing concentrates in Japan, Germany, and China, with raw material dependencies spanning rare-earth optical glass, precision-machined stainless steel sheaths, and specialized polymer coatings for flexible insertion tubes. Single-source vulnerability in CMOS sensor supply creates structural risk for non-integrated manufacturers. Distribution runs through direct manufacturer field organizations for enterprise accounts and regional distributors for fragmented independent practice demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR compliance costs function as a barrier-to-entry moat, filtering marginal manufacturers from the European supply base and consolidating procurement relationships with quality-certified vendors capable of sustained regulatory investment. This cost-of-compliance dynamic rewards incumbents with existing notified body relationships while elevating capital requirements for market entry.
For Market Incumbents: Anchor supply relationships with European university teaching hospitals through ISO 13485-aligned production certification and dedicated service contracts covering installation, training, and preventive maintenance. Defend against single-use endoscope sheath substitution by bundling reprocessing infrastructure financing with capital equipment leases. Prioritize R&D investment in 4K video system integration to maintain margin separation from fiber-optic commodity tiers. For New Entrants and Emerging Players: Disposable single-use sheath technology offers a technology-first wedge into multi-site hospital group procurement specifications seeking to decentralize sterilization workflows and maximize equipment utilization rates. Target bovine and equine reproductive endoscopy applications in North America as the most penetrable segment, with durable instrument designs addressing unmet production animal demand. Pursue direct-to-laboratory distribution partnerships with diagnostic laboratory networks implementing hub-and-spoke service models. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified medical technology conglomerates seeking veterinary division expansion. Long-term viability hinges on regulatory compliance infrastructure rather than product innovation velocity alone. Monitor PMDA-METI standards alignment progress as the signal indicating import pathway clarity for non-domestic suppliers entering Japanese specialty practice markets.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical File Completion | Notified body capacity constraints prioritize vendors with existing human-device conformity assessments. |
| Single-Use Consumable Portfolio Expansion | Disposable sheaths shift capital planning toward per-procedure budgeting for hospital groups. |
| University Teaching Hospital Partnership | Curriculum embedding creates rigid endoscopy competency pipelines and installed base lock-in. |
| Telemedicine Platform Integration | Remote image transmission enables hub-and-spoke service models extending specialist reach. |
| Production Animal Application Development | Bovine and equine reproductive endoscopy remains underpenetrated relative to companion animal segments. |
Research Methodology
Regulatory filings from FDA Center for Veterinary Medicine, EU MDR notified body databases, and PMDA submission records formed the secondary backbone for compliance pathway mapping. Primary interviews with veterinary clinic procurement managers, biomedical engineers at university teaching hospitals, GPO contracts specialists, and aftermarket service technicians combined with secondary validation from hospital procurement databases and GPO contract repositories. Bottom-up segmentation modeling and top-down macroeconomic adjustment provided cross-verification for volume and value estimates across the analysis window.
Historical trendline analysis of capital equipment refresh cycles and pet insurance reimbursement expansion patterns informed the projection framework. Segmentation dimensions spanned product type, application, end user, and distribution channel with regional regulatory cluster overlays. CAGRs were derived from fitted growth curves adjusted for compliance cost trajectories and consolidation velocity in multi-site hospital group procurement. Industry-specific forecast inputs incorporated technician certification program development timelines and sterilization infrastructure penetration rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of extended notified body approval delays or acute optical component supply disruption. Decision-makers should treat outputs as directional within the stated assumption set, recognizing that veterinary-specific premarket guidance gaps create regulatory friction that may accelerate or delay market entry timelines beyond modeled parameters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
ENT Endoscopy Market
Endoscopy
Chile Endoscopy Devices Market
Endoscopy
Netherlands Endoscopy Devices Market
Endoscopy
Global Endoscopes Market
Endoscopy
Endoscopic Retrograde Cholangiopancreatography (ERCP) Devices Market
Endoscopy
Chip-On-The-Tip Endoscopes Market
Endoscopy
Polyp Biopsy Market
Endoscopy
Argentina Endoscopy Devices Market
Endoscopy
Global Endoscopic Stricture Management Device Market
Endoscopy
Hysteroscopic Endometrial Resection Procedures Market
Endoscopy
Endoscopy Device Market
Endoscopy
Dermatology Endoscopy Devices Market
Endoscopy
Mexico Endoscopy Devices Market
Endoscopy
Rigid Endoscopes Market
Endoscopy
Global Mobile Endoscopic Workstations Market
Endoscopy
Duodenoscope Market