
 Hemodynamic Monitoring Devices Market | 2026-2036
Hemodynamic Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Hemodynamic Monitoring Devices Market Outlook
Leasing and pay-per-use financing is fragmenting the competitive landscape for high-acuity monitoring systems. Edwards Lifesciences Corporation leverages its catheter-based heritage to anchor premium positioning in invasive hemodynamic measurement. Koninklijke Philips N.V. sustains a broad technology portfolio spanning ultrasound and electrical impedance modalities across hospital networks. Getinge AB competes through integrated critical care ecosystems that bundle monitoring with ventilator and therapeutic platforms.
Hemodynamic monitoring devices measure cardiovascular performance parameters including cardiac output, blood pressure, and oxygen delivery through invasive catheter insertion or external sensor application. These systems employ thermodilution, electrical impedance, or miniaturized sensor arrays to generate real-time physiological data that guides fluid management and vasopressor therapy in surgical and critical care settings. Non-invasive monitors are capturing expanded share in emergency rooms and outpatient clinics where procedure volume rises and infection risk tolerance falls. Pulmonary artery catheters retain dominance in cardiac surgery applications despite gradual displacement by less invasive alternatives in trauma and preoperative assessment workflows.
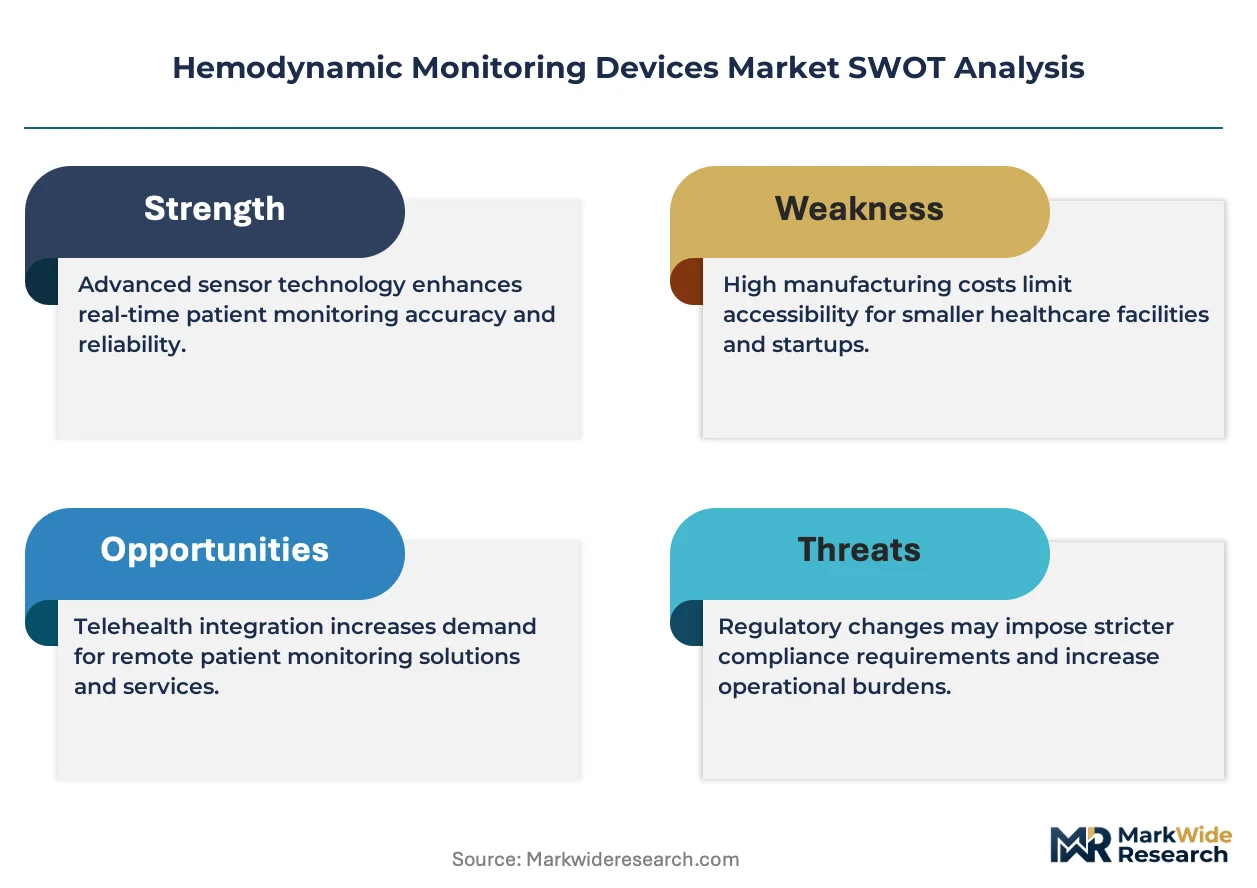
FDA premarket notification requirements and the EU MDR conformity assessment process shape product development timelines and clinical evidence burdens for manufacturers seeking transatlantic market access. The EPA regulates device material disposal and lithium battery handling, while ISO 13485 quality management certification remains a baseline procurement filter for hospital systems. Stakeholders must weigh the pace of miniaturized sensor maturation against reimbursement inertia for non-invasive monitoring codes when allocating R&D and commercial resources.
Market Dynamics
The transition from invasive catheter-based measurement to non-invasive sensor platforms is restructuring competitive advantage around signal processing algorithms and disposable sensor economics rather than surgical precision engineering.
Growth Catalysts
- Aging demographics in developed economies:Cardiac surgery volumes in Germany, Japan, and the United States sustain utilization of pulmonary artery catheters and drive replacement cycles for monitoring infrastructure in tertiary hospitals.
- FDA premarket notification pathways:Streamlined 510(k) clearance for predicate-based non-invasive monitors accelerates commercial timelines and reduces clinical evidence burdens relative to de novo pathways.
- Electrical impedance tomography maturation:Miniaturized electrode arrays and improved reconstruction algorithms enable real-time thoracic perfusion imaging without arterial cannulation in emergency departments.
Market Restraints
- Reimbursement code inertia:CMS and private payers maintain limited coverage for non-invasive hemodynamic monitoring outside anesthesia billing, compressing hospital budget justification for capital conversion.
- Lithium battery supply concentration:Portable monitor manufacturers depend on cell production concentrated in East Asian supply chains, exposing procurement to export control and shipping disruption risks.
- Signal artifact vulnerability:Electrical impedance and pulse contour methods exhibit measurement drift during patient movement, limiting deployment in ambulatory and transport settings where motion is unavoidable.
Strategic Opportunities
- Ambulatory surgery center expansion:United States outpatient procedural volume growth creates demand for compact, battery-operated monitors that bridge intraoperative and recovery room monitoring without capital-intensive installation.
- EU Medical Device Regulation harmonization:MDR conformity assessment alignment across notified bodies enables single technical documentation packages to access multiple European national markets through mutual recognition.
- Machine learning and photoplethysmography convergence:Algorithmic compensation for peripheral perfusion variation enables continuous blood pressure estimation from fingertip optical sensors, opening prehospital and home monitoring applications.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized expertise in physiological signal processing and regulatory clinical affairs concentrates in established medical device hubs, constraining startup scaling and geographic diversification.
- ISO 13485 certification timeline:Quality management system implementation and notified body audit scheduling extends 12-18 months, delaying market entry for novel sensor platforms even after technical validation completion.
- Interoperability with legacy EMR infrastructure:HL7 FHIR adoption varies across hospital networks, forcing middleware development or manual data entry for monitors that lack native integration with dominant electronic health record vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemodynamic Monitoring Devices Market |
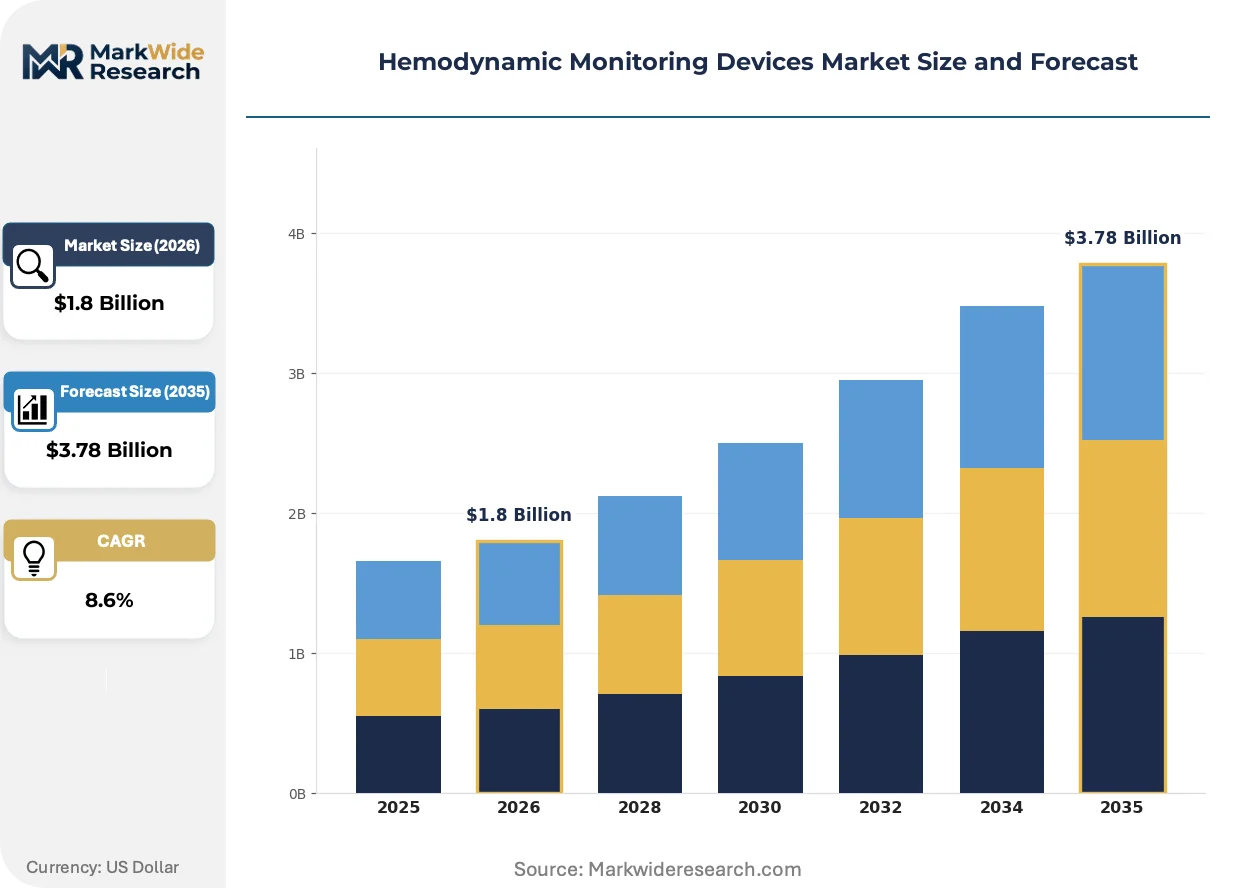
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Invasive Pressure Monitors, Non-Invasive Monitors, Pulmonary Artery Catheters, Cardiac Output Monitors Technology: Ultrasound, Electrical Impedance, Thermodilution, Miniaturized Sensors End User: Hospitals, Intensive Care Units, Emergency Rooms, Outpatient Clinics Application: Cardiac Surgery, Trauma Cases, Critical Care, Preoperative Assessment |
| Companies Covered | Edwards Lifesciences Corporation, Koninklijke Philips N.V., Getinge AB, Baxter International, GE HealthCare Technologies, ICU Medical, Abbott Laboratories, Siemens Healthineers, BD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemodynamic Monitoring Devices Market Strategic Shifts
Sensor miniaturization and wireless connectivity are compressing the physical footprint of hemodynamic monitoring while expanding data capture beyond traditional critical care boundaries into procedural and transitional care environments.
Photoplethysmography-based continuous blood pressure monitors employ multi-wavelength LED arrays and machine learning calibration to estimate arterial pressure from peripheral pulse wave morphology. Emergency medicine departments in the United States and Western Europe are piloting these devices for triage and early shock detection. This technology is digitizing hemodynamic surveillance by converting intermittent manual measurements into automated, timestamped data streams that integrate directly with clinical decision support systems.
The EU Medical Device Regulation's enhanced clinical evidence requirements for Class IIa and above devices mandate post-market surveillance systems and periodic safety update reports throughout product lifecycles. Manufacturers must maintain technical documentation and quality management systems under stricter notified body oversight than under the previous Medical Device Directive. Cardiac output monitoring systems with novel measurement principles face extended conformity assessment timelines, pushing developers toward predicate-based 510(k) strategies in the United States as a faster initial market entry path.
Hospital procurement committees are unbundling device acquisition from long-term service contracts, negotiating separate pricing for hardware, software licenses, and preventive maintenance. This disaggregation pressures original equipment manufacturers to defend recurring revenue through consumable sensor sales rather than captive service agreements. The shift is most pronounced in German and Dutch hospital networks, where centralized purchasing cooperatives standardize equipment across multiple facilities and demand interoperable platforms that reduce vendor lock-in.
Hemodynamic Monitoring Devices Market Segmentation
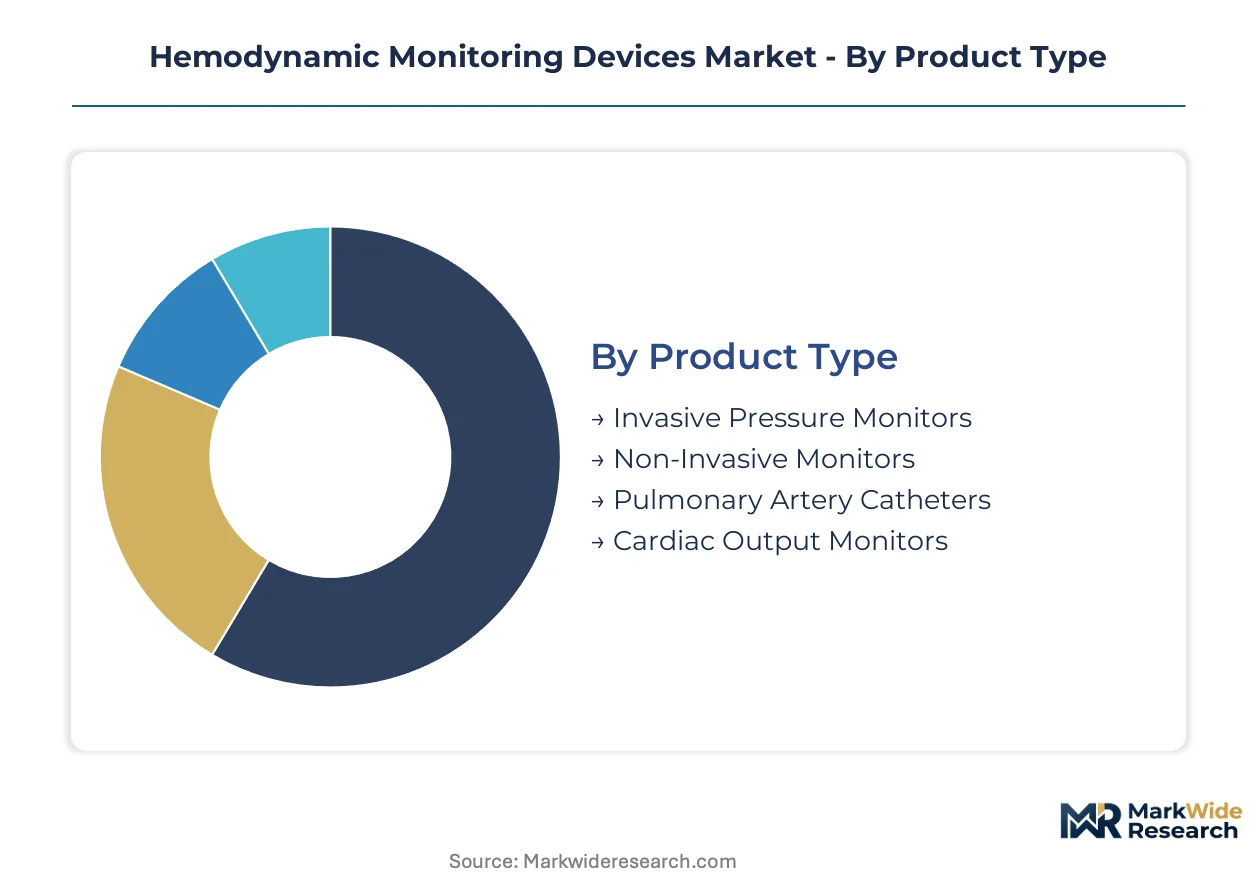
Segmentation in hemodynamic monitoring reveals how technology maturity, clinical setting economics, and procedural volume interact to shape procurement patterns. Manufacturers must align sensor platform design with specific reimbursement codes and infrastructure requirements that vary across acute care environments.
Product Type:
Cost tier stratification separates capital-intensive installed systems from disposable-heavy portable platforms, with procurement committees weighing total cost of ownership against clinical acuity requirements.
- Invasive Pressure Monitors:These systems integrate fluid-filled transducer assemblies with pressure tubing sets for continuous arterial, central venous, and pulmonary artery pressure measurement. Demand concentrates in cardiac surgery suites across the United States and Germany where hemodynamic instability during cardiopulmonary bypass demands beat-to-beat precision that non-invasive alternatives cannot replicate.
- Non-Invasive Monitors:External sensor arrays employing electrical impedance or photoplethysmography eliminate catheter-related infection risk while reducing nursing workload for line maintenance. Emergency departments in Japan and the Netherlands are expanding procurement of these platforms for triage and early shock detection where speed of deployment outweighs absolute measurement accuracy.
- Pulmonary Artery Catheters:Balloon-tipped flow-directed catheters with thermistor sensors enable simultaneous pressure monitoring and thermodilution cardiac output calculation in high-acuity settings.
- Cardiac Output Monitors:Dedicated systems for stroke volume and systemic vascular resistance measurement support goal-directed fluid therapy protocols in perioperative management.
Pulmonary artery catheters command the established base. The steepest expansion runs through non-invasive monitors.
Technology:
Application requirements determine signal fidelity thresholds, with surgical precision workflows demanding validated measurement principles while screening applications prioritize speed and patient tolerance.
- Ultrasound:Doppler-based and transthoracic echocardiography methods provide intermittent cardiac output validation without catheter placement, though operator dependency limits continuous monitoring utility. Intensive care units in France and Switzerland deploy ultrasound as a confirmatory modality when invasive measurements show unexpected drift or when catheter placement is contraindicated by coagulopathy.
- Electrical Impedance:Thoracic bioimpedance and electrical impedance tomography reconstruct cardiac output and regional perfusion from surface electrode arrays, enabling completely external monitoring. Emergency medicine departments in the United Kingdom and Australia are piloting these systems for trauma resuscitation where rapid assessment of fluid responsiveness determines survival outcomes.
- Thermodilution:The established reference standard for cardiac output measurement using cold saline injectate or thermal filament heating through pulmonary artery catheters.
- Miniaturized Sensors:MEMS-based pressure and flow sensors embedded in arterial lines or attached to skin surfaces reduce form factor while maintaining measurement frequency.
Thermodilution anchors regulatory validation for new device approvals. Electrical impedance is climbing the fastest as reconstruction algorithms improve and electrode costs fall.
End User:
Customer type determines capital budget availability, with consolidated health systems negotiating enterprise pricing while independent facilities prioritize leasing flexibility and rapid depreciation.
- Hospitals:Tertiary medical centers maintain hybrid monitoring infrastructures that match technology to acuity, deploying invasive platforms in cardiac surgery and non-invasive alternatives in general wards. German university hospitals are unbundling device procurement from service contracts, forcing manufacturers to defend recurring revenue through disposable sensor sales rather than captive maintenance agreements.
- Intensive Care Units:These environments generate the highest per-bed monitoring expenditure due to continuous multi-parameter surveillance requirements and integration with mechanical ventilation and renal replacement platforms. United States academic medical centers are consolidating vendor relationships to reduce interoperability costs and simplify biomedical engineering training.
- Emergency Rooms:High patient throughput and unpredictable acuity create demand for rapid-deployment monitors with minimal calibration requirements.
- Outpatient Clinics:Ambulatory surgical and procedural settings prioritize compact, battery-operated platforms that bridge intraoperative and recovery monitoring without fixed infrastructure installation.
Intensive care units absorb the premium installed base. Outpatient clinics are expanding most quickly as procedural volume shifts from inpatient to ambulatory settings.
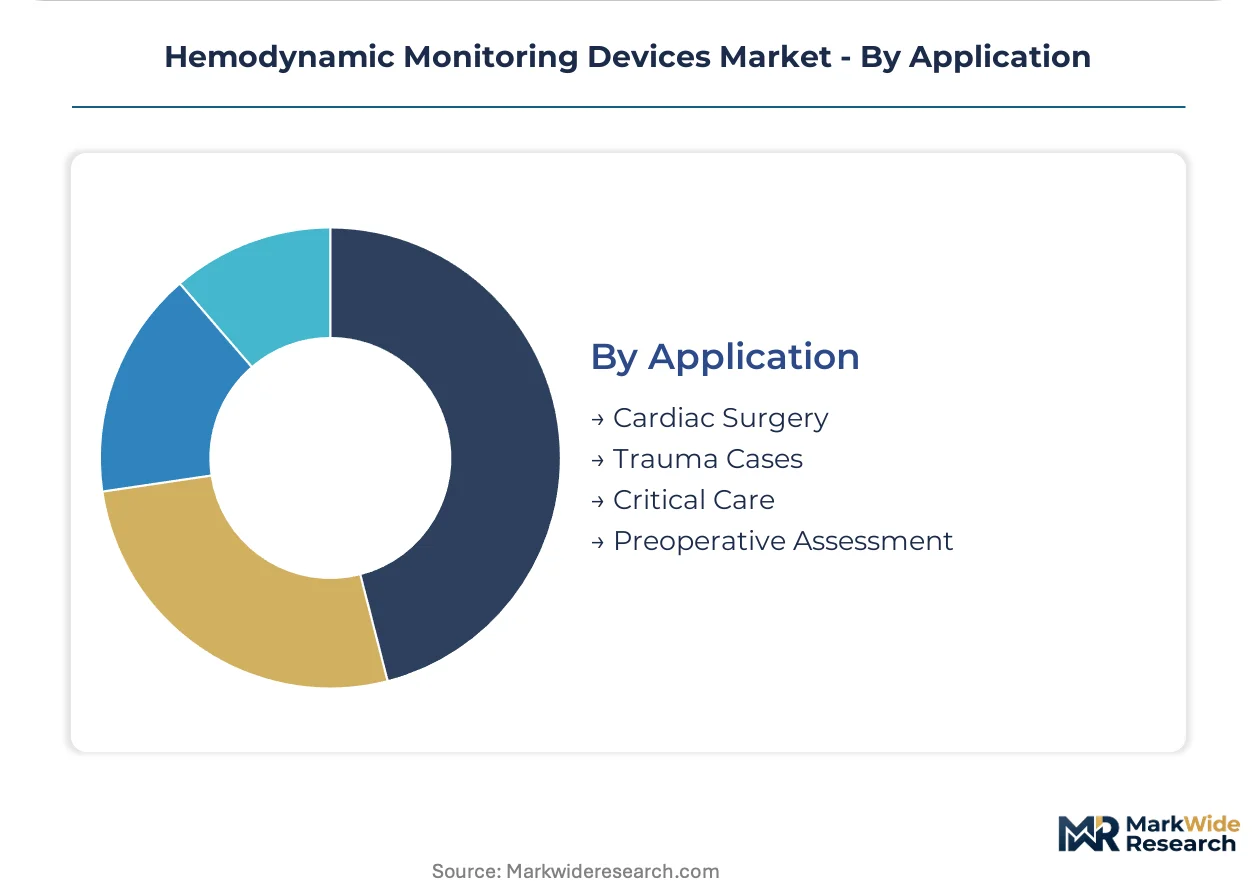
Application:
Volume concentration in cardiac surgery sustains demand for measurement precision, while trauma and critical care applications drive adoption of faster-deploying alternatives that sacrifice some accuracy for speed.
- Cardiac Surgery:Cardiopulmonary bypass and valve replacement procedures require pulmonary artery catheter monitoring for mixed venous oxygen saturation and continuous cardiac output measurement. Japanese and United States cardiac centers maintain the highest catheter utilization rates globally, with replacement cycles driven by surgical volume rather than device obsolescence.
- Trauma Cases:Hemorrhagic shock resuscitation demands rapid assessment of preload responsiveness and cardiac function without the time or vascular access conditions for catheter insertion. Level I trauma centers in Texas, California, and Illinois are standardizing non-invasive platforms for initial assessment while reserving invasive monitoring for confirmed surgical candidates.
- Critical Care:Sepsis and acute respiratory distress syndrome management employs hemodynamic monitoring to guide fluid administration and vasopressor titration.
- Preoperative Assessment:Risk stratification for non-cardiac surgery in elderly patients uses non-invasive cardiac output estimation to identify occult cardiac dysfunction.
Cardiac surgery retains the highest per-procedure monitoring intensity. Preoperative assessment is gaining share fastest as enhanced recovery protocols expand screening requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket notification pathways and the EU MDR conformity assessment process are accelerating compliance investments among manufacturers seeking transatlantic market access. Procurement concentrates in the United States, Germany, and Japan where aging populations and cardiac surgery volumes sustain device utilization.
United States
Cardiac surgery volumes in tertiary hospitals sustain demand for pulmonary artery catheters and drive replacement cycles for monitoring infrastructure. FDA 510(k) clearance pathways streamline commercial timelines for predicate-based non-invasive monitors. Academic medical centers in Boston and Houston are consolidating vendor relationships to reduce interoperability costs.
Germany
German university hospitals are unbundling device procurement from service contracts, forcing manufacturers to defend recurring revenue through disposable sensor sales. The EU MDR conformity assessment process shapes product development timelines for transatlantic market access. Industrial clusters in Bavaria and Baden-Württemberg host critical care ecosystem integrators.
Japan
Japanese cardiac centers maintain the highest pulmonary artery catheter utilization rates globally, with replacement cycles driven by surgical volume. PMDA regulatory frameworks align with international standards while maintaining distinct clinical evidence requirements. Tokyo and Osaka metropolitan areas concentrate procurement decision-making for national hospital networks.
United Kingdom
Emergency medicine departments in the United Kingdom are piloting electrical impedance systems for trauma resuscitation where rapid assessment determines survival outcomes. NHS procurement frameworks standardize equipment specifications across regional trusts. London and Manchester hospital networks drive adoption of compact, battery-operated monitors.
Australia
Level I trauma centers in New South Wales and Victoria are standardizing non-invasive platforms for initial assessment while reserving invasive monitoring for confirmed surgical candidates. TGA regulatory pathways provide streamlined market entry for predicate-based devices. Sydney and Melbourne medical device distributors anchor Asia-Pacific supply chain coordination.
Hemodynamic Monitoring Devices Market Competitive Environment
Channel-controlling players compete with product-specialist players across leasing and pay-per-use financing arrangements that fragment the competitive landscape for high-acuity monitoring systems. The market exhibits tiered consolidation with catheter-based heritage manufacturers, diversified health technology conglomerates, and integrated critical care ecosystem providers. Three archetypes dominate: precision-engineering specialists leveraging surgical instrument heritage, platform-scale operators spanning multiple monitoring modalities, and bundled-solution integrators combining monitoring with therapeutic platforms. Competitive moves center on unbundling hardware from service contracts and defending recurring revenue through consumable sensor economics.
Within the precision-engineering tier, Edwards Lifesciences Corporation exemplifies catheter-based heritage positioning, while Koninklijke Philips N.V. represents diversified platform-scale operations across ultrasound and electrical impedance modalities. Getinge AB occupies a position among integrated critical care ecosystem providers that bundle monitoring with ventilator and therapeutic platforms.
| Leading Market Players |
|---|
| Edwards Lifesciences Corporation |
| Koninklijke Philips N.V. |
| Getinge AB |
| Baxter International |
| GE HealthCare Technologies |
| ICU Medical |
| Abbott Laboratories |
| Siemens Healthineers |
| BD |
| Others |
Value Chain & Pricing Dynamics
Shenzhen's lithium-ion cell manufacturing clusters anchor portable monitor production capacity, with electrode material throughput directly translating into downstream pricing leverage for battery-dependent device tiers. This geographic concentration in East Asian supply nodes compresses margins for manufacturers lacking long-term offtake agreements or captive cathode sourcing.
Pricing Analysis
Certification level creates the primary spread between premium FDA-cleared platforms and economy-tier CE-marked alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 audit depth and predicate-device validation burden. Cost compression in the standard tier is intensifying because German hospital purchasing cooperatives demand unbundled hardware-software pricing. Ambulatory surgery centers exhibit highest price sensitivity; cardiac surgery suites demonstrate lowest.
Supply Chain Analysis
Export control regimes restricting semiconductor lithography equipment to Chinese fabs constrain MEMS sensor foundry expansion. Component sourcing draws from Japanese precision sensor houses, Taiwanese semiconductor foundries, and German transducer specialists. Single-source vulnerability concentrates in lithium hexafluorophosphate electrolyte production. Distribution runs through regional medical device distributors holding ISO 13485 certification and hospital GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in physiological signal processing and regulatory clinical affairs concentrates in established medical device hubs, constraining scaling velocity for innovators outside Boston, Stuttgart, and Tokyo corridors.
For Market Incumbents: Harden predicate-device portfolios against algorithmic non-invasive substitutes by accelerating electrical impedance tomography R&D. Deepen backward integration into MEMS pressure sensor fabrication to reduce foundry queue dependency. Secure exclusive sensor supply agreements with trauma center networks before emerging players achieve ISO 13485 certification. For New Entrants and Emerging Players: Pursue preoperative assessment applications in United States ambulatory surgery centers where reimbursement code gaps have stalled incumbent conversion. Exploit the fastest-penetrable segment: compact battery-operated monitors bridging intraoperative and recovery workflows. Lead with pay-per-use financing to bypass capital committee approval cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform-scale operators with existing FDA 510(k) predicate libraries over de novo pathway startups facing extended clinical evidence timelines. Long-term viability hinges on recurring consumable sensor economics rather than hardware depreciation models. Monitor EU MDR notified body audit queue lengths as inflection indicator for European market entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Predicate-based clearance accelerates commercial timelines relative to de novo pathways. |
| CE Marking Pathway | MDR conformity assessment alignment enables mutual recognition across European national markets. |
| Hospital System Partnership | Enterprise pricing agreements with academic medical centers reduce interoperability integration costs. |
| Software Companion Development | HL7 FHIR-native integration addresses legacy EMR infrastructure variation across networks. |
| Reimbursement Strategy | CPT code expansion for non-invasive monitoring unlocks outpatient clinic budget justification. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cardiac anesthesiologists, biomedical engineering directors, hospital purchasing committee members, and GPO contracts managers. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR technical documentation filings, CMS Medicare reimbursement schedules, and hospital procurement contract registries. Bottom-up sensor unit shipment estimates triangulated against top-down cardiac surgery volume projections.
Calibration against historical replacement cycles and regulatory approval timelines anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type, technology modality, end-user facility tier, and application acuity level. CAGRs were derived from fitted growth curves applied to procedural volume forecasts and technology substitution rates. Forecast inputs incorporated PMDA regulatory lag effects and electrical impedance algorithm maturation curves.
Macroeconomic conditions sit as an overlay; deviation in lithium carbonate pricing and East Asian shipping rates would shift the trajectory. Forecasts reflect documented assumptions regarding reimbursement code expansion velocity and notified body audit capacity. Material shifts in FDA de novo pathway stringency or EU MDR clinical evidence requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Resuscitation Devices Market
Cardiovascular Devices
Pressure Infusion Bags Market
Cardiovascular Devices
Germany Cardiovascular Devices Market
Cardiovascular Devices
China Vascular Grafts Market
Cardiovascular Devices
Global Percutaneous Coronary Intervention (PCI) Devices Market
Cardiovascular Devices
Cardiogenic Shock Treatment Market
Cardiovascular Devices
Europe Heart Valve Repair and Replacement Market
Cardiovascular Devices
Cardiovascular and Soft Tissue Repair Patches Market
Cardiovascular Devices
Implantable Drug Infusion Pumps Market
Cardiovascular Devices
Cardiac Mapping Systems Market
Cardiovascular Devices
Bioresorbable Coronary Stents Market
Cardiovascular Devices
Sweden Cardiovascular Devices Market
Cardiovascular Devices
Australia Cardiovascular Devices Market
Cardiovascular Devices
Vital Signs Monitoring Devices Market
Cardiovascular Devices
Global Cardiac Arrest Treatment Market
Cardiovascular Devices
Intravenous Catheters Market